
 Intimate Lingerie Market | 2026-2036
Intimate Lingerie Market Size, Share, and Industry Trends Forecast 2026-2036
Intimate Lingerie Market Analytics
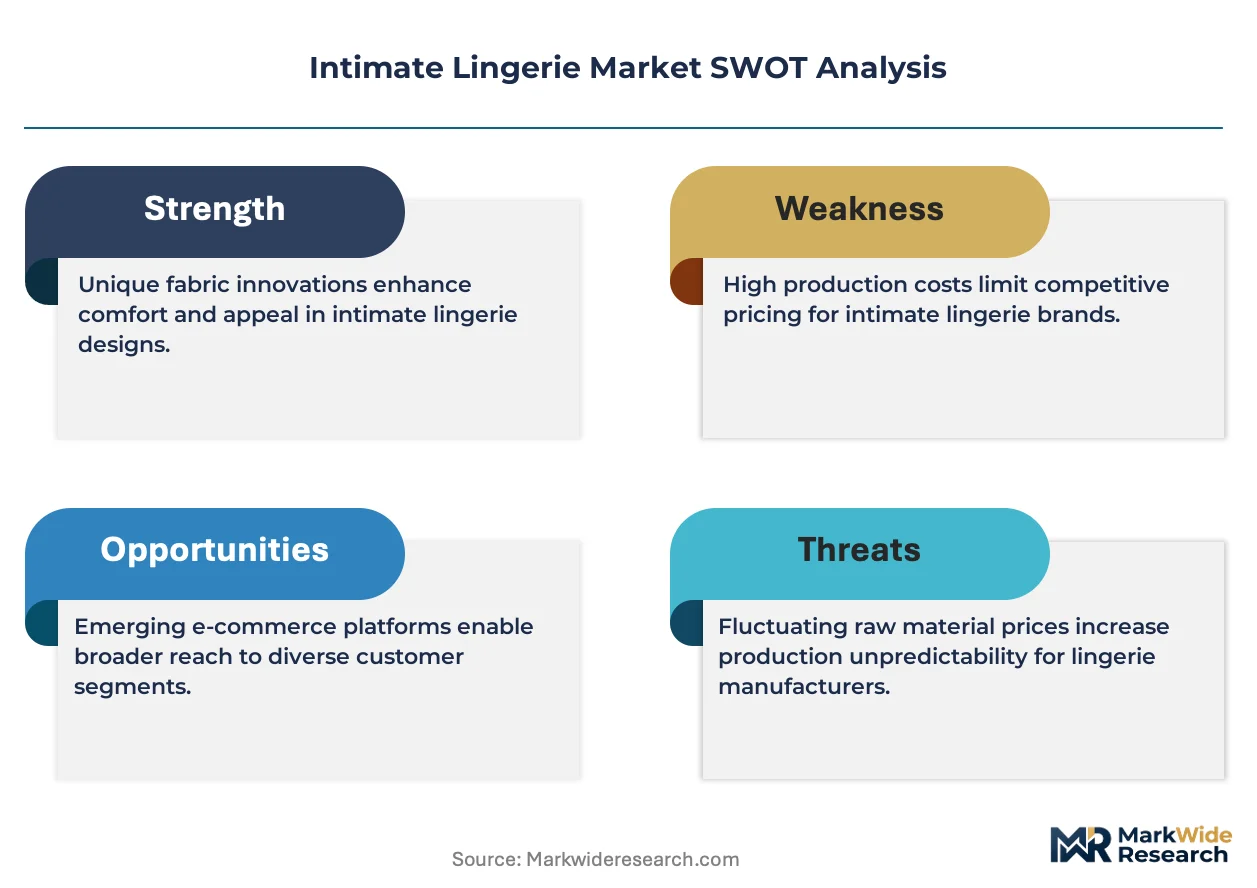
Subscription-based replenishment and digital fit-technology services is hardening as a permanent revenue layer in intimate apparel. Wacoal leverages its legacy engineering database to sustain precision-fit leadership across Asian and North American channels. Agent Provocateur differentiates through editorial curation and limited-release collections that occupy the ultra-premium occasion-wear niche.
Intimate lingerie comprises structured and unstructured undergarments engineered with specific compression, support, and moisture-management parameters; bras integrate underwire, molded foam, or wireless construction with band-size gradations typically spanning 28–44 inches and cup volumes from A to K. Cotton and lace material segments anchor volume production, while microfiber commands technical-performance margins in shapewear-adjacent applications. Plus-size sizing represents the fastest-expanding dimensional category as fit-technology investment redirects toward inclusive grading standards.
FDA textile labeling requirements, REACH chemical restrictions administered by ECHA, and California's Proposition 65 disclosure mandates collectively elevate compliance costs for cross-border suppliers. These frameworks shape demand by disqualifying non-compliant dye processes and mandating phased elimination of certain phthalate-based fabric treatments. Stakeholders must monitor evolving extended-producer-responsibility proposals in the European Union and state-level chemical disclosure expansions in the United States to anticipate sourcing reallocations.
Market Dynamics
REACH chemical restrictions administered by ECHA are forcing wholesale reformulation of dye processes and fabric treatments across intimate apparel supply chains, with compliance costs now dictating supplier selection criteria and geographic sourcing decisions.
Growth Catalysts
- Subscription replenishment models:Direct-to-consumer services lock in recurring revenue from bridal and occasion-wear buyers, reducing customer acquisition costs and smoothing seasonal demand volatility.
- REACH compliance investments:European chemical disclosure mandates are accelerating adoption of phthalate-free fabric treatments, creating first-mover advantages for compliant suppliers.
- Inclusive-size grading expansion:Technical investment in extended band and cup sizing is unlocking underserved consumer segments and expanding addressable market boundaries.
Market Restraints
- Raw material concentration:Lace and specialty elastic production clusters in specific Asian manufacturing zones, creating single-source vulnerability for premium collections.
- Technical limitation in seamless construction:Current knitting technology cannot achieve targeted compression gradients without visible seam lines, constraining shapewear-adjacent product development.
- California Proposition 65 friction:State-level chemical disclosure requirements add compliance layers that disproportionately burden small cross-border suppliers lacking legal infrastructure.
Strategic Opportunities
- Digital fit-technology convergence:Integration of 3D body scanning with AI sizing recommendation engines is reducing return rates and enabling made-to-measure scalability.
- Extended-producer-responsibility tailwind:EU circular economy proposals will mandate take-back programs, rewarding brands with pre-built recycling infrastructure.
- Microfiber performance positioning:Technical moisture-management applications in athletic-intimate crossover products command premium positioning in German and US specialty retail channels.
Industry Challenges
- Specialized pattern engineering talent scarcity:Grading expertise for inclusive sizing requires skills distinct from traditional intimate apparel pattern-making, with limited training pipeline capacity.
- Legacy ERP integration friction:Real-time inventory synchronization between subscription platforms and manufacturing execution systems demands costly middleware development for established brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intimate Lingerie Market |
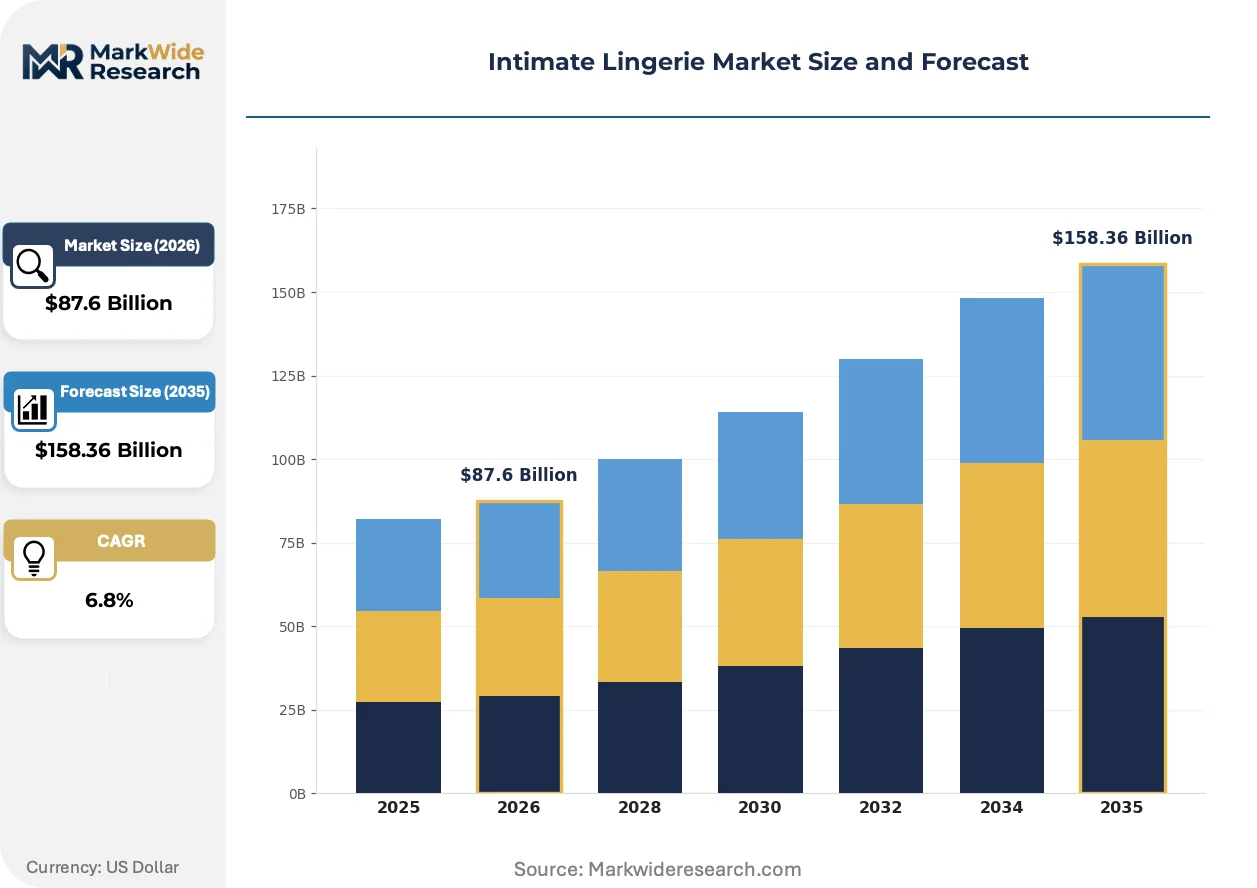
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bras, Panties, Loungewear, Sleepwear Material: Cotton, Lace, Satin, Microfiber Size: Small, Medium, Large, Plus Size Customer Type: Women, Brides, Plus-Size Customers, Fashion-Conscious Shoppers |
| Companies Covered | Coco De Mer, Agent Provocateur, Wacoal, Intimissimi, La Perla, Empreinte, Bordelle, Juliemay, Fleur of England, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intimate Lingerie Market Evolving Landscape
Three intersecting forces are compressing traditional product development cycles and redistributing value capture toward data-enabled fit solutions and compliant material sourcing.
AI-driven grading algorithms are automating size curve generation across extended dimensional ranges, compressing pattern development from weeks to days. Premium brands in the United States and Germany are adopting these tools fastest, using them to accelerate inclusive-size collection launches. This compression is automating away traditional manual pattern-making roles while concentrating value in data-science and fit-engineering functions.
ECHA's phased elimination of certain azo dyes under REACH Annex XVII is redirecting R&D investment toward bio-based colorants and waterless dyeing technologies. Suppliers serving European retail channels must now certify dye lot compliance through third-party testing, adding documentation burdens but creating differentiation for certified producers. The lace and embroidery segments face the steepest reformulation costs given their reliance on synthetic dye vibrancy.
Bridal and occasion-wear buyers are consolidating purchase decisions around curated subscription boxes that bundle lingerie with styling consultation and occasion-specific coordination. This unbundling of traditional retail discovery is displacing department store intimate apparel floors in urban China and coastal US markets. The shift is most visible among millennial and Gen-Z demographics prioritizing convenience and personalized curation over in-store fitting room experiences.
Intimate Lingerie Market Segmentation
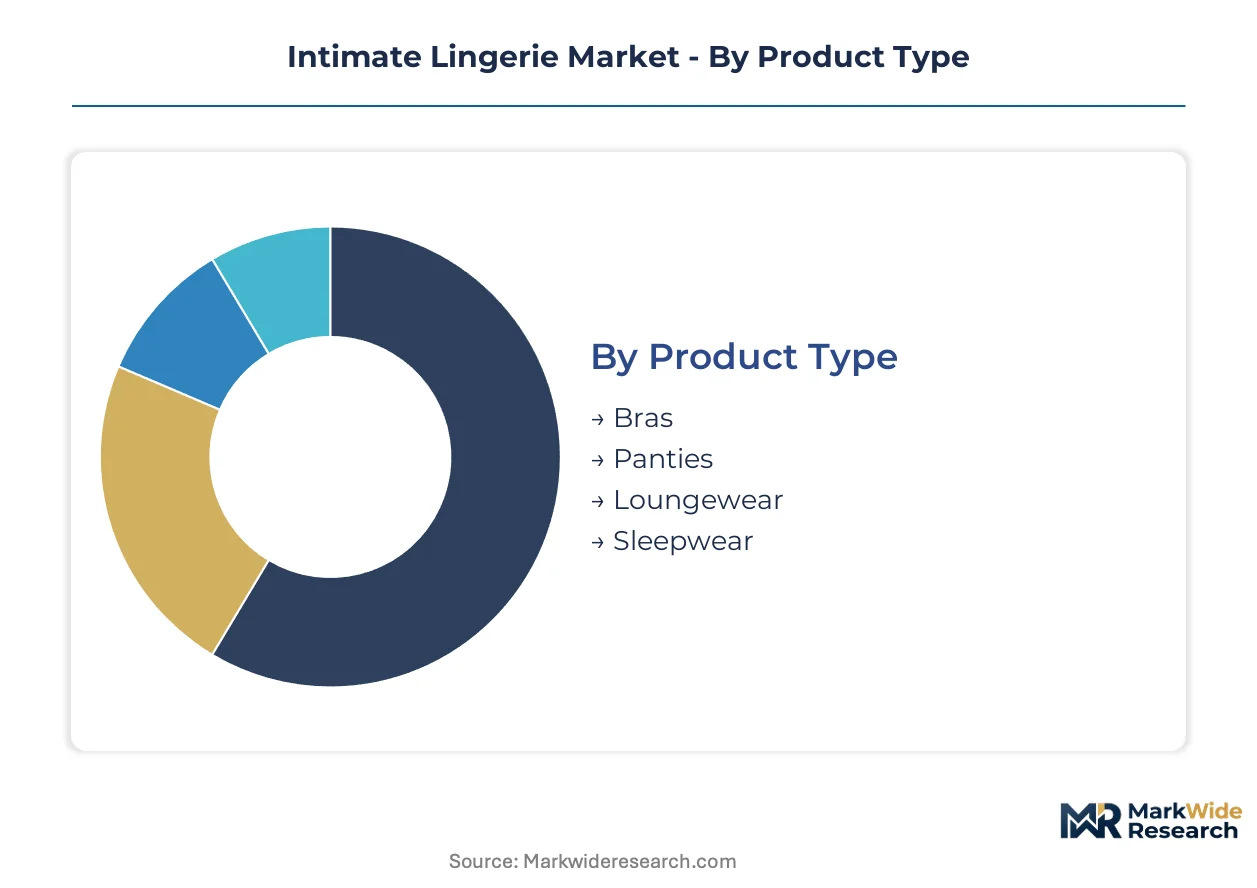
Segmentation in intimate apparel reveals divergent margin profiles and capital requirements across product architectures. Material sourcing decisions and sizing complexity dictate which manufacturers capture premium positioning versus commodity volume.
Product Type:
Capital intensity peaks with engineered support structures requiring precision molding and metalwork integration.
- Bras:Underwire, molded foam, and wireless constructions demand graded band systems spanning 28–44 inches with cup volumes from A to K. Technical investment concentrates in the United States and Germany as fit-technology vendors automate pattern generation for extended sizing.
- Panties:Seamless knitting and compression-grade elastic integration require specialized circular machines. Volume production clusters in Asian manufacturing zones serving mass-market replenishment channels.
- Loungewear:Relaxed silhouettes with minimal structural engineering permit faster inventory turns and lower SKU complexity.
- Sleepwear:Breathable natural fibers dominate; technical performance requirements are minimal compared to shapewear-adjacent categories.
Most installed capacity flows through Bras. Expansion is steepest in Loungewear as work-from-home permanence reshapes daily wardrobe composition.
Material:
Raw material selection determines regulatory exposure and end-market access, particularly for European REACH compliance.
- Cotton:Natural fiber anchor for volume production with established organic certification pathways. Sourcing concentrates in India and Egypt as brands preempt ECHA chemical restrictions through third-party tested dye lots.
- Microfiber:Technical moisture-management properties command performance premiums in athletic-intimate crossover applications. German specialty retail channels show strongest adoption for sweat-wicking base layers.
- Lace:Synthetic dye vibrancy requirements face steepest reformulation costs under phased azo dye elimination.
- Satin:Silk and polyester variants occupy occasion-wear and bridal positioning with seasonal demand concentration.
Procurement volume concentrates in Cotton. Microfiber is climbing the fastest as performance positioning penetrates premium channels.
Size:
Grading complexity escalates nonlinearly with dimensional range, requiring specialized pattern engineering talent.
- Plus Size:Extended band and cup sizing unlocks underserved consumer segments. Technical investment redirects toward inclusive grading standards with AI-driven automation compressing development cycles from weeks to days.
- Medium:Core volume tier with established pattern libraries and lowest marginal production cost.
- Large:Intermediate complexity tier with moderate grading adjustments from base blocks.
- Small:Niche positioning with limited dedicated collection development.
Pattern development capacity concentrates in Medium. Plus Size shows the steepest expansion trajectory as brands compete for inclusive-size market share.
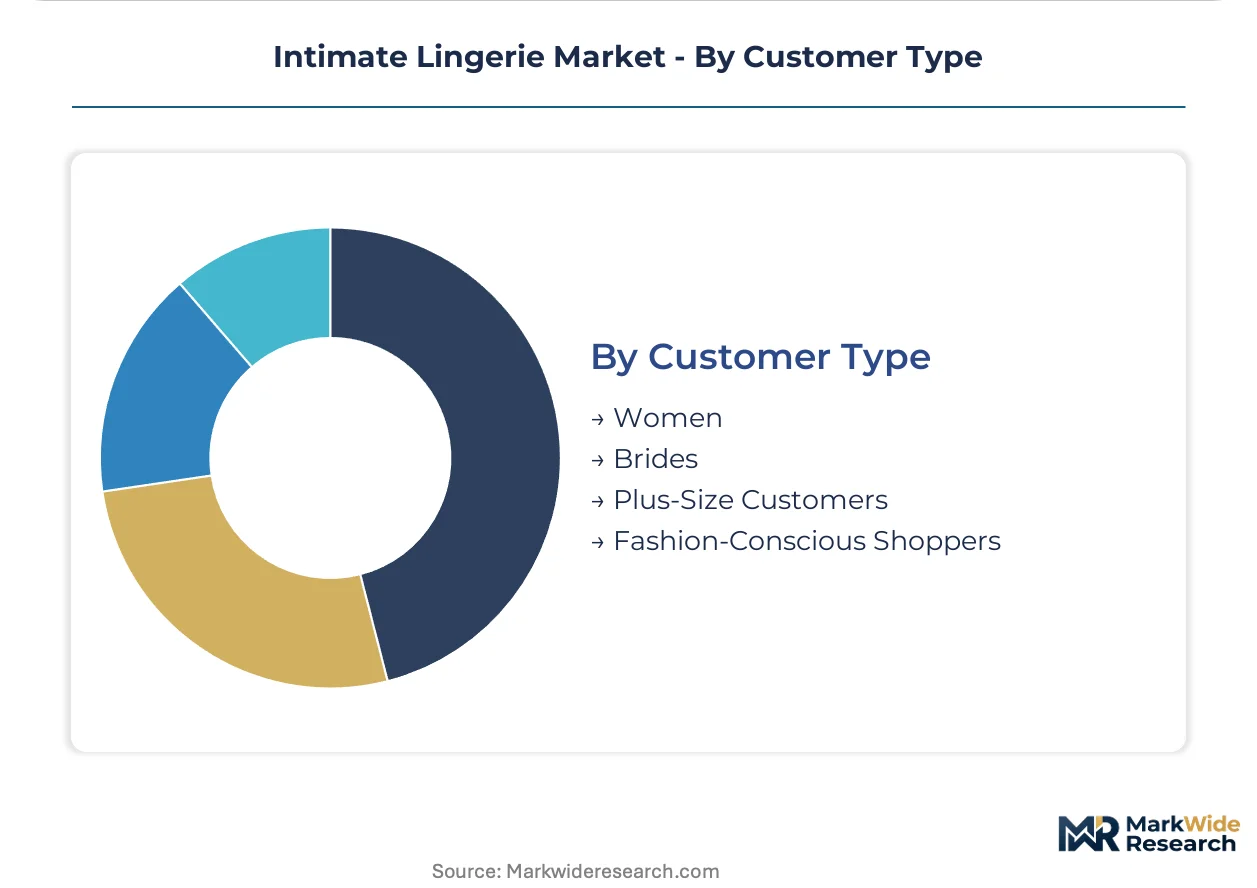
Customer Type:
Customer archetypes dictate channel strategy and subscription service viability.
- Brides:Curated subscription boxes bundle lingerie with styling consultation and occasion-specific coordination. Direct-to-consumer services lock in recurring revenue and reduce customer acquisition costs.
- Fashion-Conscious Shoppers:Limited-release collections and editorial curation drive purchase frequency. Urban China and coastal US markets show strongest responsiveness to digital discovery.
- Women:Broad category encompassing replenishment-driven purchasing with price sensitivity varying by life stage.
- Plus-Size Customers:Distinct service expectations around fit accuracy and representation; loyalty concentrates with brands demonstrating sustained inclusive-size commitment.
Subscription infrastructure concentrates on Brides. Fashion-Conscious Shoppers are gaining share fastest as social commerce reshapes discovery patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns in intimate apparel track regulatory arbitrage opportunities, with REACH compliance costs in Europe pushing dye-house capacity toward Asian manufacturing zones while premium finishing clusters consolidate in Germany and the United States.
United States
Subscription replenishment services and digital fit-technology adoption concentrate in coastal metropolitan markets, with Los Angeles and New York anchoring design and brand headquarters. FDA textile labeling requirements and California Proposition 65 disclosure mandates elevate compliance infrastructure costs for cross-border suppliers. Technical pattern-engineering talent pools in the Northeast corridor support AI-driven grading automation for inclusive-size collections.
China
Volume manufacturing of cotton basics and seamless panty constructions clusters in Guangdong and Zhejiang provinces serving mass-market replenishment channels. The country's national chemical regulator enforces phased alignment with international standards on azo dye restrictions. Suzhou and Hangzhou retain specialized lace and embroidery finishing capacity despite rising labor costs.
Germany
Performance microfiber applications in athletic-intimate crossover products command premium positioning through Munich and Hamburg specialty retail channels. ECHA REACH Annex XVII enforcement drives wholesale reformulation of fabric treatments among suppliers serving European retail networks. The Rhine-Ruhr industrial corridor hosts technical textile R&D facilities developing bio-based colorant alternatives.
India
Organic cotton sourcing concentrates in Maharashtra and Gujarat as brands preempt ECHA chemical restrictions through third-party certified dye lots. The Bureau of Indian Standards maintains fiber content labeling mandates that align with export market requirements. Tirupur and Surat industrial clusters expand circular knitting capacity for seamless construction serving European and North American private-label programs.
United Kingdom
Editorial curation and limited-release collection strategies concentrate in London's luxury retail corridor targeting bridal and occasion-wear segments. The UK's national chemical regulator enforces REACH-equivalent restrictions through retained EU law frameworks. Manchester retains legacy textile engineering expertise supporting technical shapewear development for premium export markets.
Intimate Lingerie Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium design houses capturing margin through editorial positioning while Asian OEMs dominate volume replenishment. The vendor base organizes into three functional tiers: heritage European luxury marques, Japanese precision-fit engineering specialists, and agile direct-to-consumer challengers. Competitive moves concentrate on AI-driven fit-technology licensing and backward integration into certified dye-house capacity.
Within the heritage European luxury tier, Agent Provocateur and La Perla occupy positions defined by limited-release curation and occasion-wear positioning. Wacoal anchors the precision-fit engineering archetype through its legacy grading database spanning Asian and North American channels. Among direct-to-consumer challengers, Intimissimi exemplifies the subscription-replenishment model locking in recurring revenue from bridal and fashion-conscious demographics.
| Leading Market Players |
|---|
| Coco De Mer |
| Agent Provocateur |
| Wacoal |
| Intimissimi |
| La Perla |
| Empreinte |
| Bordelle |
| Juliemay |
| Fleur of England |
| Others |
Value Network & Pricing Analysis
Premium-curated bridal collections and mass-market replenishment basics diverge sharply in margin architecture, with the former capturing value through styling consultation bundling while the latter competes on raw material efficiency and Asian manufacturing scale. This bifurcation channels investment toward certified dye-house backward integration for REACH compliance on one tier, and circular knitting automation for seamless construction on the other.
Pricing Analysis
Retailer markup layers dominate downstream pricing, with specialty boutiques commanding 2.5-3.5x landed cost multiples against mass-market replenishment channels operating on thinner turns. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and geographic delivery cost, with ECHA-tested dye lots and California Proposition 65 documentation adding compliance premiums. Cost compression in mass-market cotton basics intensifies because of Asian manufacturing overcapacity and raw material price volatility. Price-sensitive volume buyers in replenishment channels prioritize unit economics over fit-technology features, while bridal and occasion-wear segments show minimal elasticity for editorial curation and limited-release positioning.
Supply Chain Analysis
Domestic-content mandates in India and evolving EU circular economy proposals are reshaping sourcing footprints, pressuring brands to certify local finishing capacity and pre-build recycling infrastructure. Lace and specialty elastic production clusters in China, India, and Sri Lanka, with Guangdong and Zhejiang provinces anchoring volume manufacturing of cotton basics and seamless panty constructions. Raw material supply draws from Egyptian long-staple cotton, German synthetic microfiber R&D, and Italian embroidery finishing. Single-source vulnerability concentrates in azo-dye-dependent lace segments facing phased REACH elimination. Distribution runs through direct-to-consumer subscription platforms, specialty retail boutiques in Munich and Los Angeles, and mass-market replenishment channels serving urban China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intimate lingerie functions as a stable compounder anchored by subscription replenishment models that lock in recurring revenue and smooth seasonal volatility across bridal and occasion-wear cohorts.
For Market Incumbents: Anchor precision-fit leadership through AI-driven grading automation and legacy pattern database monetization, while accelerating backward integration into REACH-certified dye-house capacity to defend margin position against compliance-cost inflation. Wacoal's engineering database and Agent Provocateur's editorial curation demonstrate defensible moats that emerging players struggle to replicate without multi-decade investment horizons. For New Entrants and Emerging Players: Enter via underserved plus-size grading segments where technical talent scarcity limits incumbent response speed, targeting direct-to-consumer channels with digital fit-technology integration that reduces return rates and enables made-to-measure scalability. White-space concentration in inclusive-size bridal subscription boxes offers the most penetrable entry vector, with AI sizing recommendation engines providing the critical go-to-market differentiation against established pattern libraries. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs disproportionately burden small cross-border suppliers lacking legal infrastructure and certified dye-lot documentation. Long-term viability favors brands with pre-built recycling infrastructure and extended-producer-responsibility readiness across the European footprint. Acquisition targets should display captive fit-technology development or exclusive bridal subscription subscriber bases. The signal to watch is ECHA enforcement intensity on azo dye elimination timelines, which would accelerate supplier distress and create distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Certified Dye-House Backward Integration | ECHA Annex XVII compliance creates first-mover supply security for European retail channels. |
| AI-Driven Grading Automation Deployment | Pattern development compression from weeks to days unlocks inclusive-size collection velocity. |
| Bridal Subscription Box Curation Launch | Direct-to-consumer bundling with styling consultation displaces department store discovery. |
| Extended-Producer-Responsibility Infrastructure Build | Pre-built recycling programs capture EU circular economy proposal mandates ahead of compliance deadlines. |
| Microfiber Performance Positioning | Athletic-intimate crossover applications command premium placement in German specialty retail. |
Research Methodology
Coverage spans the United States, China, Germany, India, and the United Kingdom, with primary inputs from each market combining structured interviews with brand managers, category buyers at specialty retailers, supply planners at contract manufacturers, and technical textile R&D directors. Secondary validation draws from ECHA REACH compliance databases, FDA textile labeling filings, California Proposition 65 enforcement records, and customs trade data tracking lace and elastic import flows. Bottom-up SKU-level volume builds triangulate against top-down macroeconomic consumption models.
Granularity-level modeling operates at product-type, material-grade, size-tier, and customer-archetype dimensions, with separate treatment of bridal occasion-wear versus replenishment-driven purchasing patterns across the projection horizon. CAGRs derive from segment-level growth rate synthesis anchored by subscription service penetration curves and inclusive-size grading investment trajectories. Forecast inputs incorporate REACH enforcement phase-in schedules, AI fit-technology adoption rates in coastal US and German markets, and organic cotton certification expansion in Maharashtra and Gujarat.
The model holds under stable regulatory enforcement timelines and continued direct-to-consumer channel growth; deviation in ECHA acceleration of azo dye elimination or collapse of bridal subscription retention economics would shift volume and value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Maternity Apparels Market
Apparel & Footwear
North America Denim Jeans Market
Apparel & Footwear
Outdoor Jacket Market
Apparel & Footwear
Touchscreen Gloves Market
Apparel & Footwear
Premium Denim Jeans Market
Apparel & Footwear
Seamless Underwear for Men Market
Apparel & Footwear
Shapewear Market
Apparel & Footwear
New Smart Wardrobe Market
Apparel & Footwear
Gymnastic Leotards Market
Apparel & Footwear
Denim Jeans Market
Apparel & Footwear
Compression and Shapewear Market
Apparel & Footwear
Women's T-Shirts Market
Apparel & Footwear
Women's Trousers Market
Apparel & Footwear
South Korea Denim Jeans Market
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
Global Apparel Market