
 Compression Wear and Shapewear Market | 2026-2036
Compression Wear and Shapewear Market Size, Share, and Industry Trends Forecast 2026-2036
Compression Wear and Shapewear Market Intelligence
Spandex blends are pivoting toward bio-based elastane alternatives as raw material volatility reshapes cost structures across the value chain. Spanx LLC leverages direct-to-consumer channel control to sustain premium positioning in the shapewear bodysuit category. Nike Inc. anchors its compression tights line through athletic performance credibility and team sports procurement relationships. Adidas AG competes on technical fabric innovation, particularly moisture-wicking knitted constructions for endurance athletes.
Compression wear and shapewear encompasses engineered garments delivering graduated mechanical pressure to specific body zones, typically constructed with 15-40% elastomeric fiber content in circular knit or warp-knit structures to achieve controlled stretch and recovery properties. These products serve medical rehabilitation, athletic performance optimization, and body contouring objectives across consumer and clinical settings. Shapewear bodysuits represent the largest margin pool as premium positioning sustains price premiums despite fabric commoditization. Compression tights are recording the fastest volume trajectory among fitness enthusiasts and amateur athletes seeking recovery benefits. Support stockings remain a mature segment concentrated in pharmacy and medical supply channels with reimbursement-dependent demand patterns.
The FDA regulates medical-grade compression garments under 510(k) clearance pathways, while the FTC monitors advertising claims related to performance and therapeutic benefits in the United States. ASTM International and ISO 13485 standards govern pressure gradient calibration and quality management for clinical applications, creating compliance barriers for unqualified entrants. Stakeholders must monitor evolving textile sustainability regulations and biocompatibility testing requirements that will reshape material sourcing decisions and manufacturing location strategies.
Market Dynamics
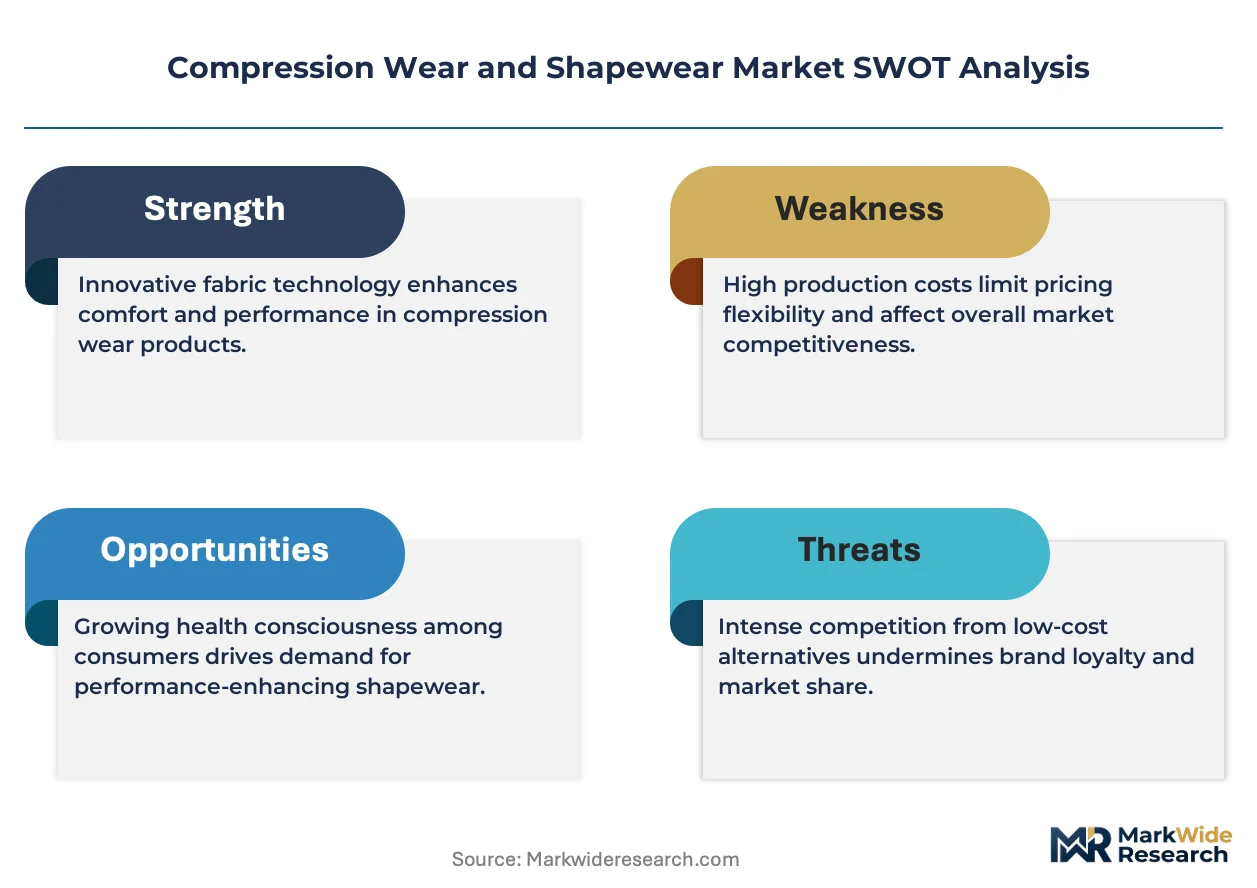
FDA's updated textile biocompatibility guidelines are compressing material certification timelines while forcing manufacturers toward medical-grade fabric investments that reshape competitive cost structures.
Growth Catalysts
- Post-surgical recovery demand:Physician endorsement of medical-grade compression garments for lymphedema management and cosmetic procedure recovery is expanding hospital and clinic procurement channels.
- REACH compliance migration:European manufacturers accelerating bio-based elastane adoption ahead of chemical substance restrictions are capturing sustainability premiums in premium retail segments.
- Athletic recovery convergence:Amateur marathon runners and CrossFit participants purchasing compression tights for DOMS reduction are blurring medical and consumer category boundaries.
Market Restraints
- Petrochemical feedstock volatility:Spandex production costs fluctuate with propylene oxide and polytetramethylene ether glycol pricing, squeezing margin predictability for circular knit manufacturers.
- ISO 13485 certification bottlenecks:Clinical-grade garment producers face 12-18 month quality management system audits that delay market entry for new medical device entrants.
- Seamless knitting equipment concentration:Santoni and Lonati machinery dominance in Italy creates supply risk for warp-knit capacity expansion outside established manufacturing clusters.
Strategic Opportunities
- Geriatric support stocking underpenetration:India's aging population and rising diabetes prevalence create pharmacy channel expansion potential for graduated compression hosiery with domestic BIS certification.
- Smart textile convergence:Integration of conductive yarn sensors with compression fabrics enables remote patient monitoring for chronic venous insufficiency management.
- Direct-to-consumer channel maturation:Virtual fitting algorithms and subscription replenishment models for medical compression stockings bypass traditional durable medical equipment distributor markups.
Industry Challenges
- Pressure gradient calibration expertise scarcity:Textile engineers capable of programming circular knitting machines for precise mmHg graduation commands compensation premiums that inflate R&D overhead.
- Legacy ERP integration friction:Small-batch medical garment manufacturers migrating from manual production tracking to automated lot traceability systems face workflow disruption during ISO compliance audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compression Wear and Shapewear Market |
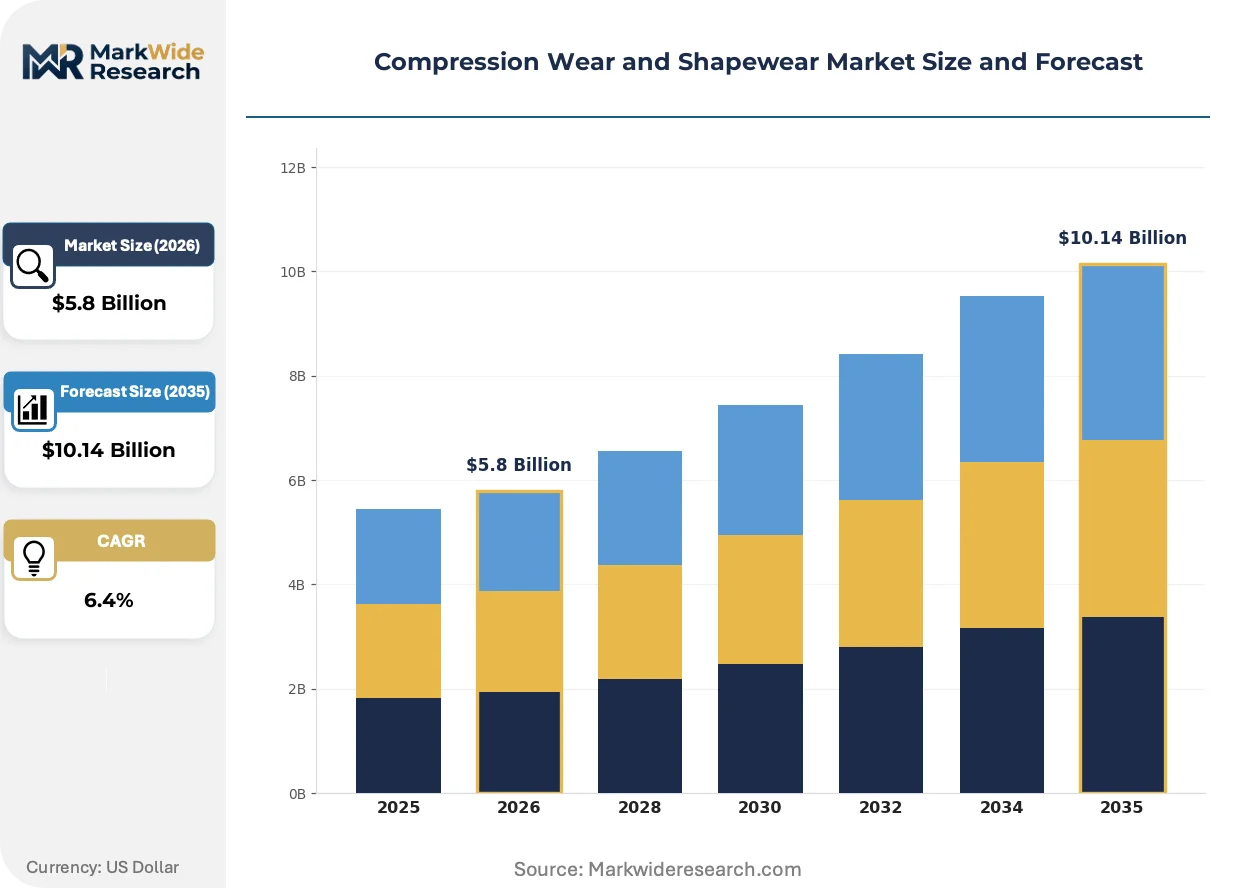
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Tops, Compression Tights, Shapewear Bodysuits, Support Stockings Fabric Type: Spandex, Nylon, Polyester, Cotton End User: Fitness Enthusiasts, Athletes, Patients, Everyday Consumers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Honeylove Sculptwear Inc., Ann Chery, Spanx LLC, Nike Inc., Adidas AG, Skims Body Inc., Anita Dr. Helbig GmbH, Wacoal Holdings Corp., Hanesbrands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compression Wear and Shapewear Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory harmonization efforts are compressing development cycles while expanding the addressable boundary between clinical rehabilitation and athletic performance applications.
Bio-based elastane derived from renewable feedstocks is expanding into premium shapewear and medical compression lines as brands respond to Scope 3 emissions disclosure requirements. Lycra's bio-derived spandex variants and Fulgar's EVO nylon are capturing placement with sustainability-positioned retailers seeking differentiated fiber stories. This material transition is expanding into cost-sensitive segments faster than petroleum-based alternatives anticipated, compressing the premiumization timeline for sustainable positioning.
The FDA's 510(k) clearance pathway for medical-grade compression garments is tightening evidentiary standards for pressure gradient claims, forcing manufacturers toward clinical trial investments previously reserved for Class II devices. ASTM D6193 calibration protocols are becoming de facto requirements for reimbursement eligibility with Medicare Advantage plans. Post-mastectomy compression bras and lymphedema sleeves face the steepest compliance cost escalation as payers demand documented therapeutic efficacy.
Subscription replenishment models for medical compression stockings are displacing pharmacy counter purchases among chronic venous insufficiency patients managing long-term therapy. Hinge Health and Omada Health are incorporating compression garment fulfillment into virtual physical therapy programs, capturing patient adherence data that informs insurer contract negotiations. This channel shift concentrates most rapidly in United States markets where remote patient monitoring CPT codes subsidize digital health integration.
Compression Wear and Shapewear Market Segmentation
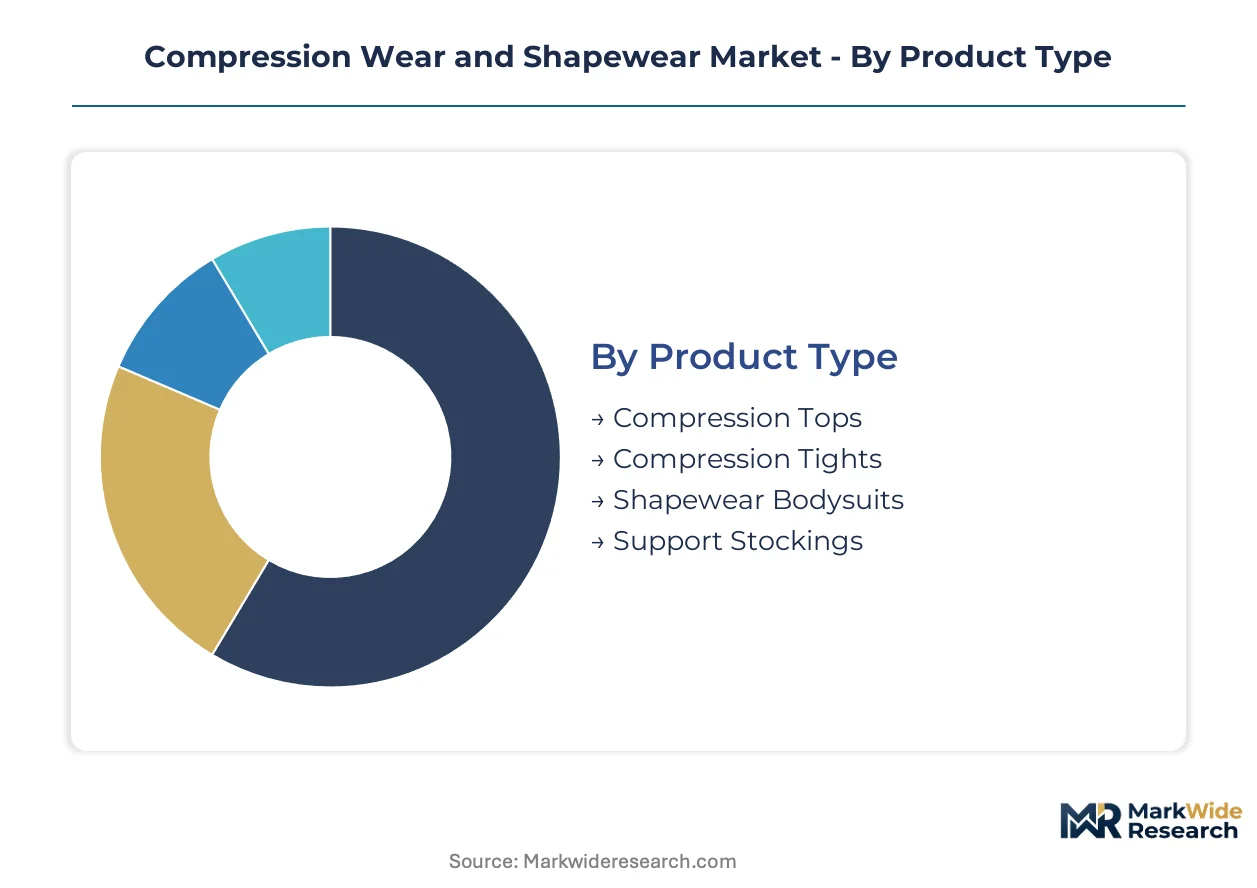
Segmentation in compression wear and shapewear determines margin capture, as medical-grade certification requirements and channel control create divergent profitability profiles across product categories. Manufacturers must align technical capabilities with specific end-user demands, from FDA-cleared hospital procurement to direct-to-consumer athletic recovery.
Product Type:
Supply concentration in circular knitting machinery creates asymmetric capacity allocation, favoring segments that command premium pricing for technical precision.
- Shapewear Bodysuits:Engineered with 20-35% elastomeric fiber content in warp-knit constructions for targeted abdominal and torso compression. Demand concentrates among United States consumers seeking aesthetic contouring under formal attire, sustained by Spanx LLC's direct-to-consumer channel dominance and subscription replenishment models. Premium positioning resists fabric commoditization through brand equity and fit algorithm differentiation.
- Compression Tights:Graduated pressure garments constructed with moisture-wicking knitted constructions for lower extremity circulation management. Amateur marathon runners and CrossFit participants in the United States drive volume expansion, blurring medical and athletic category boundaries as Nike Inc. and Adidas AG compete on technical fabric innovation. Recovery benefits marketing accelerates adoption beyond professional athlete penetration.
- Compression Tops:Upper body garments delivering postural support and muscle stabilization for weightlifting and contact sports applications.
- Support Stockings:Mature segment concentrated in pharmacy and medical supply channels with reimbursement-dependent demand patterns for chronic venous insufficiency management.
Today's leader: Shapewear Bodysuits. Tomorrow's challenger: Compression Tights.
Fabric Type:
Raw material cost tiering separates certified medical-grade suppliers from commodity apparel producers, with bio-based alternatives capturing sustainability premiums.
- Spandex:Elastomeric polyurethane fiber delivering 15-40% stretch content for controlled compression profiles. REACH compliance migration in Europe accelerates bio-based elastane adoption ahead of chemical substance restrictions, with Lycra's bio-derived variants capturing placement with sustainability-positioned retailers.
- Nylon:Polyamide fiber providing durability and shape retention in high-wear compression applications. Fulgar's EVO nylon from renewable feedstocks expands into premium medical compression lines as brands respond to Scope 3 emissions disclosure requirements.
- Polyester:Petroleum-derived fiber offering cost efficiency and moisture management in mass-market athletic compression.
- Cotton:Natural fiber limited to low-compression everyday shapewear where breathability outweighs elastic recovery requirements.
Spandex commands current margin pools. Nylon bio-derivatives are climbing the fastest.
End User:
Customer type fragmentation creates channel complexity, as clinical procurement and consumer retail require incompatible quality management systems.
- Patients:Chronic venous insufficiency and lymphedema sufferers requiring graduated compression with documented therapeutic efficacy. Medicare Advantage reimbursement eligibility demands ASTM D6193 calibration protocols, concentrating demand among ISO 13485-certified manufacturers with clinical trial investments.
- Fitness Enthusiasts:Amateur athletes purchasing compression tights for delayed onset muscle soreness reduction and perceived recovery acceleration. United States CrossFit box retail and marathon expo channels drive volume with lower certification barriers than medical segments.
- Athletes:Professional and collegiate competitors accessing compression through team sports procurement relationships with performance credibility requirements.
- Everyday Consumers:Aesthetic shaping demand from office workers and social event attendees prioritizing discretion and comfort over medical-grade pressure precision.
Patients generate the steepest expansion trajectory through reimbursement expansion. Fitness enthusiasts offer volume scale with simpler compliance.
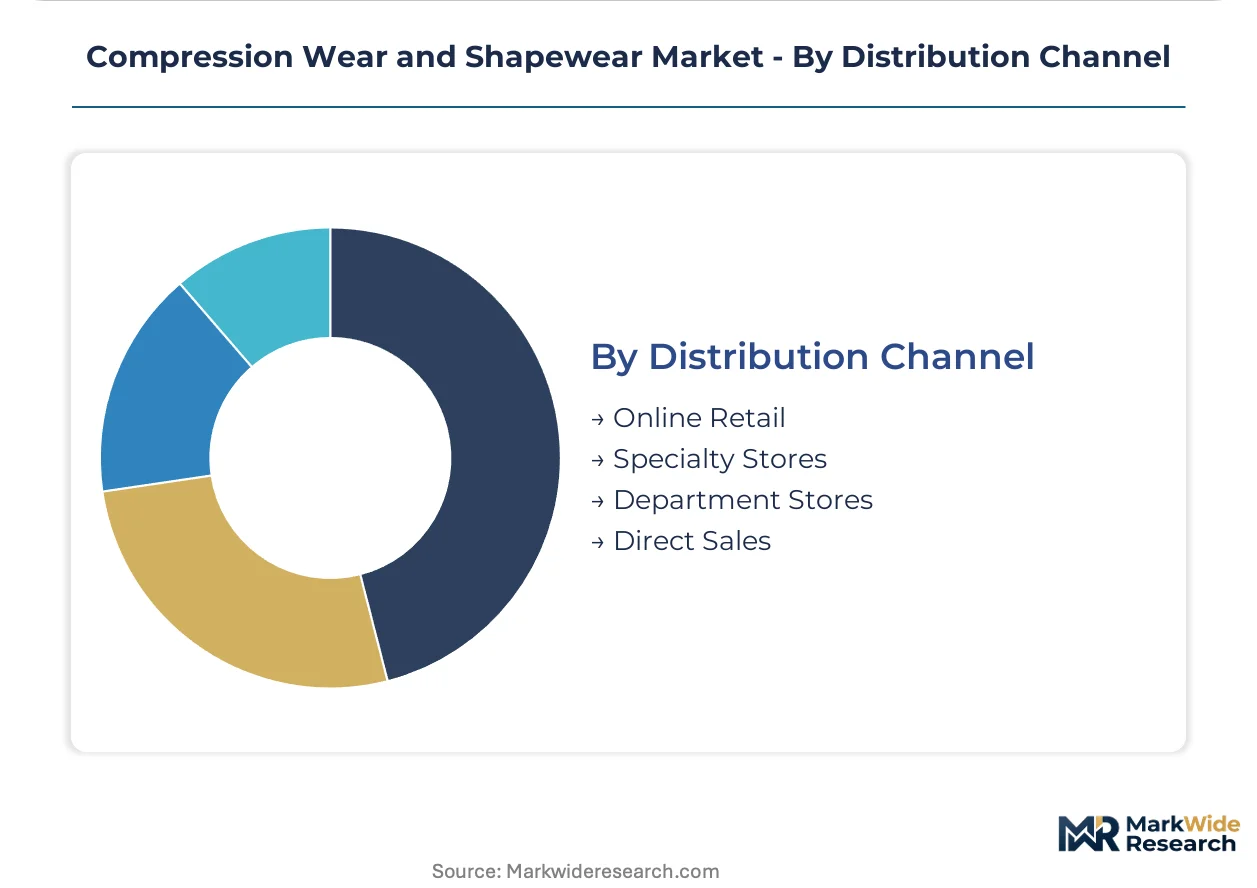
Distribution Channel:
Channel maturation determines margin retention, as intermediary markups compress profitability in traditional retail while direct relationships sustain premium positioning.
- Direct Sales:Manufacturer-controlled channels including brand-owned e-commerce and virtual fitting algorithms. Virtual physical therapy programs from Hinge Health and Omada Health incorporate compression garment fulfillment, capturing patient adherence data that informs insurer contract negotiations in United States markets.
- Online Retail:Third-party marketplace and specialty e-commerce platforms aggregating comparison shoppers. Amazon and dedicated athletic apparel sites concentrate price-transparent competition for standardized compression tights.
- Specialty Stores:Running shops, medical supply outlets, and lingerie boutiques offering fit expertise and personalized consultation.
- Department Stores:Mass retail placement for shapewear bodysuits with lower service intensity and higher return rates.
Direct sales capture margin expansion. Online retail faces price compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Santoni and Lonati machinery clusters anchor global warp-knit capacity for compression wear manufacturing. FDA textile biocompatibility guidelines in the United States and REACH chemical restrictions in Europe are reshaping material certification requirements across major production hubs.
United States
Post-surgical recovery demand and athletic recovery convergence drive compression tights and shapewear bodysuit consumption. FDA 510(k) clearance pathways for medical-grade garments tighten evidentiary standards for pressure gradient claims. New York and Los Angeles host direct-to-consumer brand headquarters where virtual fitting algorithms bypass traditional retail markups.
Germany
Chronic venous insufficiency patient populations sustain pharmacy channel demand for graduated compression hosiery. REACH compliance migration accelerates bio-based elastane adoption ahead of chemical substance restrictions. Bavaria's textile engineering centers develop pressure gradient calibration expertise for circular knitting machine programming.
China
Domestic manufacturing scale supports cost-efficient polyester and nylon fiber production for mass-market athletic compression. NMPA medical device regulations create parallel certification tracks for export-oriented medical-grade garment producers. Zhejiang and Jiangsu provinces concentrate circular knit capacity serving global brand OEM contracts.
India
Rising diabetes prevalence and aging demographics expand geriatric support stocking demand through pharmacy channels. BIS certification requirements for medical compression hosiery create compliance barriers for imported products. Tamil Nadu's knitwear industrial clusters develop domestic warp-knit capacity for graduated pressure garments.
Japan
Precision textile engineering traditions support high-compression medical garment production for domestic and export markets. METI sustainability guidelines push manufacturers toward bio-derived fiber sourcing for Scope 3 emissions reduction. Osaka's technical textile sector advances moisture-wicking knitted constructions for endurance athlete applications.
Compression Wear and Shapewear Market Key Industry Players
Direct-to-consumer channel control dominates the current landscape as brands bypass traditional retail intermediaries. The vendor base stratifies across three tiers: premium positioning specialists, mass-market athletic apparel conglomerates, and certified medical device manufacturers. Strategic archetypes include vertical integration into raw material sourcing, subscription replenishment model deployment, and ISO 13485 quality management certification for clinical procurement access. M&A activity concentrates on direct-to-consumer brand acquisitions and bio-based elastane technology licensing.
Within the premium positioning tier, Spanx LLC exemplifies direct-to-consumer channel mastery in shapewear bodysuits, while Nike Inc. anchors athletic compression credibility through team sports procurement relationships. Among European medical device specialists, Anita Dr. Helbig GmbH occupies a certified clinical-grade position serving post-surgical recovery segments with ISO 13485-compliant manufacturing.
| Leading Market Players |
|---|
| Honeylove Sculptwear Inc. |
| Ann Chery |
| Spanx LLC |
| Nike Inc. |
| Adidas AG |
| Skims Body Inc. |
| Anita Dr. Helbig GmbH |
| Wacoal Holdings Corp. |
| Hanesbrands Inc. |
| Others |
Cost & Logistics Intelligence
Propylene oxide spot pricing volatility cascades through spandex production costs into three distinct garment tiers, compressing margins for circular knit manufacturers while concentrating pricing power with ISO 13485-certified medical-grade suppliers in Germany and the United States.
Pricing Analysis
Input-cost pass-through from petroleum-derived elastane feeds a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates FDA-cleared medical garments from athletic compression tights and mass-market shapewear bodysuits. Pricing pressure stems from bio-based elastane adoption costs ahead of REACH compliance deadlines. Chronic venous insufficiency patients demonstrate lowest price sensitivity due to Medicare Advantage reimbursement, while amateur fitness enthusiasts drive volume at compressed margins.
Supply Chain Analysis
Single-source vulnerability sits with Santoni and Lonati circular knitting equipment dominance in Italy, creating capacity bottlenecks for warp-knit compression garment expansion. Geographic supply concentration centers on Italy for machinery, China for polyester and nylon fiber production, and Germany for medical-grade fabric finishing. Raw material dependencies draw from propylene oxide, polytetramethylene ether glycol, and bio-derived feedstocks. Tariff exposure on elastomeric imports from Asia threatens cost structures. Distribution runs through direct-to-consumer brand channels, pharmacy counters, and hospital procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States-Germany regulatory arbitrage on FDA 510(k) versus CE marking timelines creates manufacturing location advantages for firms positioning across both approval pathways.
For Market Incumbents: Anticipate bio-based elastane cost escalation by securing multi-year renewable feedstock contracts before REACH restrictions tighten. Defend channel position through backward integration into circular knitting capacity in Bavaria's textile engineering clusters. Prioritize ISO 13485 certification maintenance as Medicare Advantage plans tighten ASTM D6193 calibration requirements for reimbursement eligibility. For New Entrants and Emerging Players: Direct-to-consumer virtual fitting algorithms offer the most penetrable route into shapewear bodysuits, bypassing department store markups that compress margins for traditional retail entrants. Target India's geriatric support stocking segment where BIS certification creates import barriers and domestic warp-knit capacity remains underdeveloped. Deploy subscription replenishment models for chronic venous insufficiency patients through partnerships with virtual physical therapy platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap medical garment specialists possessing ISO 13485 quality management systems and established hospital procurement relationships. Long-term viability hinges on clinical trial investments for pressure gradient efficacy documentation that secures payer contracts. Watch FDA evidentiary standard tightening for post-mastectomy compression bras as the inflection signal for medical-grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Elastane Sourcing Transition | Lycra's renewable feedstock variants capture sustainability premiums ahead of REACH chemical restrictions. |
| ISO 13485 Certification Investment | Quality management system audits unlock Medicare Advantage reimbursement channels for medical-grade garments. |
| Direct-to-Consumer Channel Buildout | Virtual fitting algorithms bypass traditional durable medical equipment distributor markups in United States markets. |
| Smart Textile Sensor Integration | Conductive yarn convergence enables remote patient monitoring CPT code capture with insurer contracts. |
| India Domestic Manufacturing Footprint | Tamil Nadu warp-knit capacity addresses geriatric support stocking demand under BIS certification requirements. |
Research Approach
Direct dialogue with textile engineers, hospital procurement managers, circular knitting machine operators, and compression garment brand executives grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) clearance databases, ASTM International calibration protocol publications, REACH substance restriction filings, and Medicare Advantage reimbursement policy updates. Bottom-up manufacturing cost modeling triangulated against top-down retail channel revenue estimates across product categories.
Segment-level volume and value trajectories emerged from elasticity modeling across fabric type, end-user archetype, and distribution channel dimensions throughout the forecast period. CAGRs derived from historical shipment data reconciliation with forward-looking capacity expansion announcements and regulatory compliance timelines. Industry-specific inputs incorporated bio-based elastane adoption curves, ISO 13485 certification queue lengths, and virtual physical therapy platform partnership velocities.
Petrochemical feedstock price shocks, FDA evidentiary requirement escalations, and REACH chemical restriction accelerations are the dominant revision risks that could compress or expand addressable market boundaries. Forecasts reflect documented assumptions on material substitution elasticities and reimbursement policy stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Women's Shirts and Blouses Market
Apparel & Footwear
Europe Headwear Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
South Korea Denim Jeans Market
Apparel & Footwear
Touchscreen Gloves Market
Apparel & Footwear
Football Kits Market
Apparel & Footwear
Sleepwear Market
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
Premium Denim Jeans Market
Apparel & Footwear
Hats Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Women's Tights and Leggings Market
Apparel & Footwear
Australia Denim Jeans Market
Apparel & Footwear
Asia-Pacific Jeans Market
Apparel & Footwear
Multiple Toe Socks Market
Apparel & Footwear
North America Jeans Market