
 Global Apparel and Footwear Market | 2026-2036
Global Apparel and Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Apparel and Footwear Market Analysis
Subscription-based wardrobe services and membership-driven replenishment models are shifting how apparel and footwear firms monetize customer relationships beyond transactional purchases. Nike leverages its direct-to-consumer ecosystem to control pricing and data capture across digital channels. Adidas sustains R&D intensity in bio-based materials and automated manufacturing. Anta Sports anchors its expansion through vertical integration in performance footwear and Greater China distribution dominance.
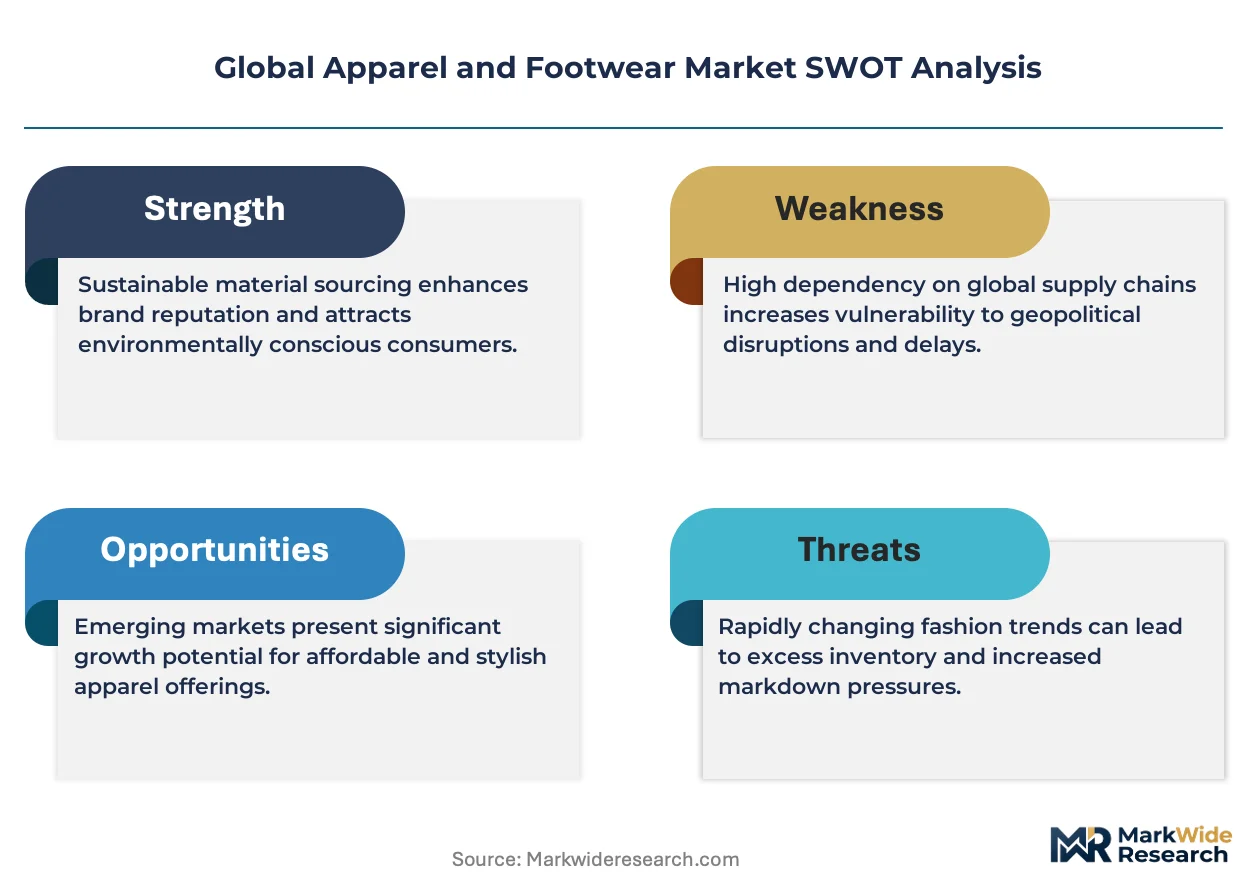
Apparel and footwear encompasses garments and protective coverings for the human body manufactured through cut-and-sew assembly, knitting, weaving, or injection-molded sole construction, with specifications spanning GSM weight, stitch density, and abrasion resistance ratings for commercial durability. The primary purpose is functional body protection, aesthetic expression, and athletic performance enhancement across consumer and professional contexts. Footwear commands disproportionate margin pools relative to tops and bottoms due to material complexity and brand premiumization. Polyester and cotton splits in material segmentation reflect diverging sustainability pressures against cost efficiency. Online retail channels are displacing department stores as the primary volume pathway for younger demographics.
The EU Green Deal, REACH chemical frameworks, and California's SB 657 transparency mandates collectively shape fiber sourcing, dyeing processes, and labor disclosure requirements across multinational supply chains. China's GB standards and dual carbon goals impose additional emissions constraints on textile-producing regions serving export markets. Stakeholders must monitor evolving extended producer responsibility legislation and digital traceability infrastructure investments to secure market access and avoid stranded inventory positions.
Market Dynamics
Digital product passport mandates and material traceability requirements are compressing lead times and forcing upstream visibility investments across polyester and cotton supply chains.
Growth Catalysts
- EU Green Deal compliance requirements:Digital product passport mandates are accelerating fiber sourcing transparency investments across European import channels.
- Bio-based material R&D intensity:Automated manufacturing lines for mycelium leather and algae-based dyes are reducing petroleum dependency in performance footwear.
- Southeast Asian manufacturing clusters:Vietnam and Bangladesh are capturing cut-and-sew volume shifts as Chinese producers pivot toward domestic premium consumption.
Market Restraints
- Cotton price volatility:Climate-induced yield compression in Texas and Punjab is destabilizing raw material cost structures for denim and knitwear producers.
- REACH chemical framework friction:ECHA restrictions on per- and polyfluoroalkyl substances are forcing reformulation of water-repellent outdoor apparel.
- Synthetic fiber substitution threat:Mechanical recycling of polyethylene terephthalate is displacing virgin polyester demand in fast-fashion supply chains.
Strategic Opportunities
- India domestic consumption corridors:Tier-2 and Tier-3 cities are driving branded apparel penetration as disposable incomes expand beyond metropolitan centers.
- Resale platform infrastructure:Authentication technology and reverse logistics networks are enabling circular economy monetization for luxury and streetwear segments.
- Extended producer responsibility tailwinds:France's AGEC law and similar frameworks are creating compliance-service revenue pools for traceability software providers.
Industry Challenges
- Automated pattern-making skill scarcity:CAD-to-cut workflows require retraining legacy garment technicians in computational design tools.
- Multi-tier supplier audit complexity:SB 657 and Modern Slavery Act disclosures demand documentation across subcontracting networks beyond tier-2 visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Apparel and Footwear Market |
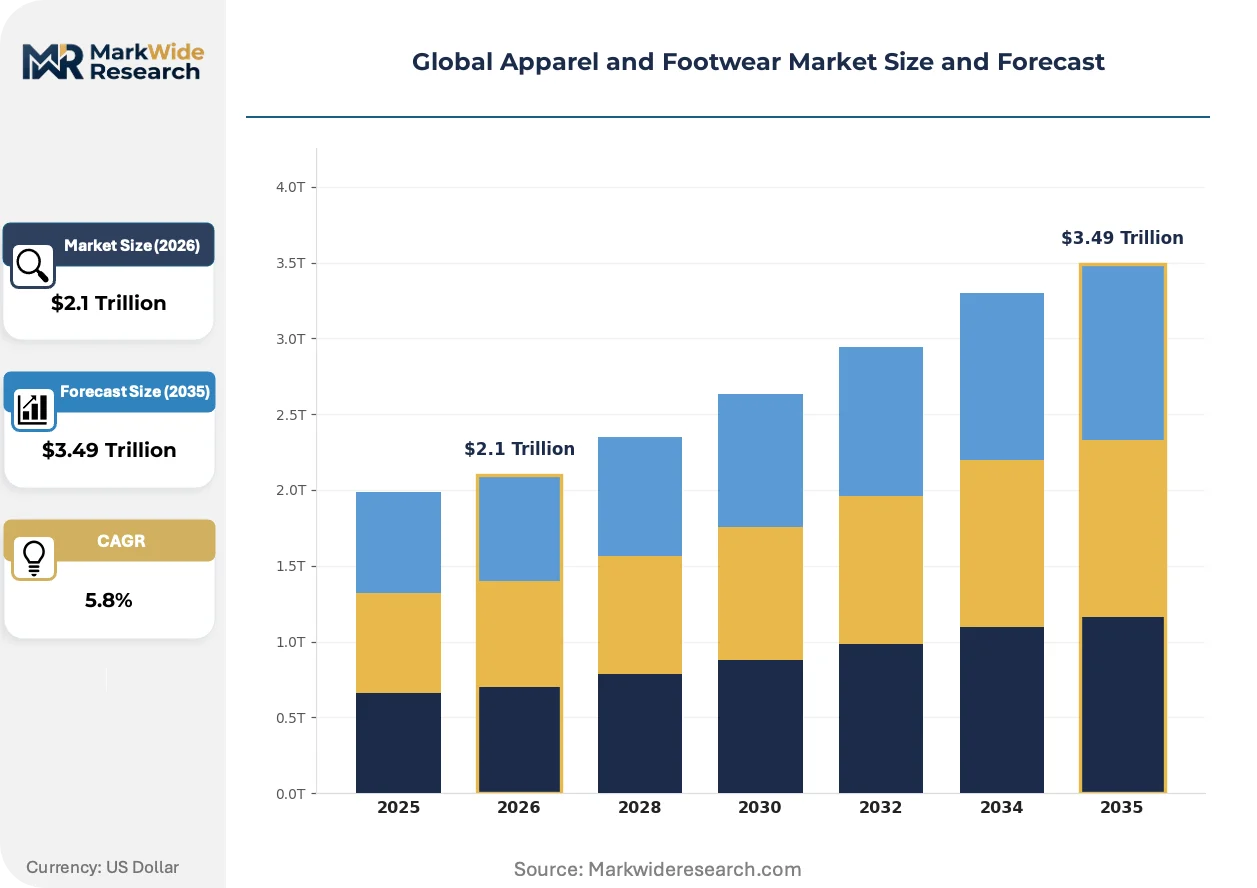
| Market Size in 2026 | $2.1 Trillion |
| Market Size in 2035 | $3.49 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tops, Bottoms, Footwear, Outerwear Material: Cotton, Polyester, Leather, Nylon End User: Men, Women, Children, Infants Distribution Channel: Online Retail, Specialty Stores, Department Stores, Discount Stores |
| Companies Covered | Anta Sports, New Balance, Nike, Li Ning Company, VF Corporation, Adidas, Lululemon Athletica, PUMA, ASICS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Apparel and Footwear Market Emerging Trajectories
Material science breakthroughs and regulatory disclosure requirements are compressing traditional design-to-retail cycles while fragmenting channel control across direct-to-consumer and resale ecosystems.
Blockchain-enabled fiber provenance tracking is converging with near-infrared spectroscopy for automated textile composition verification. Luxury houses and outdoor brands are deploying these systems to satisfy EU Green Deal documentation requirements. The structural consequence is converging with quality control and customs clearance processes, collapsing authentication timelines from weeks to hours.
REACH chemical restrictions on per- and polyfluoroalkyl substances are eliminating durable water-repellent treatments from European-bound outdoor and performance apparel. Manufacturers are reformulating with silicone-based or bio-derived alternatives at elevated unit costs. Alpine and Nordic markets are responding fastest, with brands accelerating 2025 collection redesigns to maintain import eligibility.
Rental and subscription wardrobe services are capturing Gen Z and millennial spend previously allocated to seasonal purchasing. Department store foot traffic is collapsing as these models displace ownership norms in urban professional segments. This behavioral pivot is most visible in London, New York, and Tokyo, where logistics density supports reverse collection economics.
Global Apparel and Footwear Market Segmentation
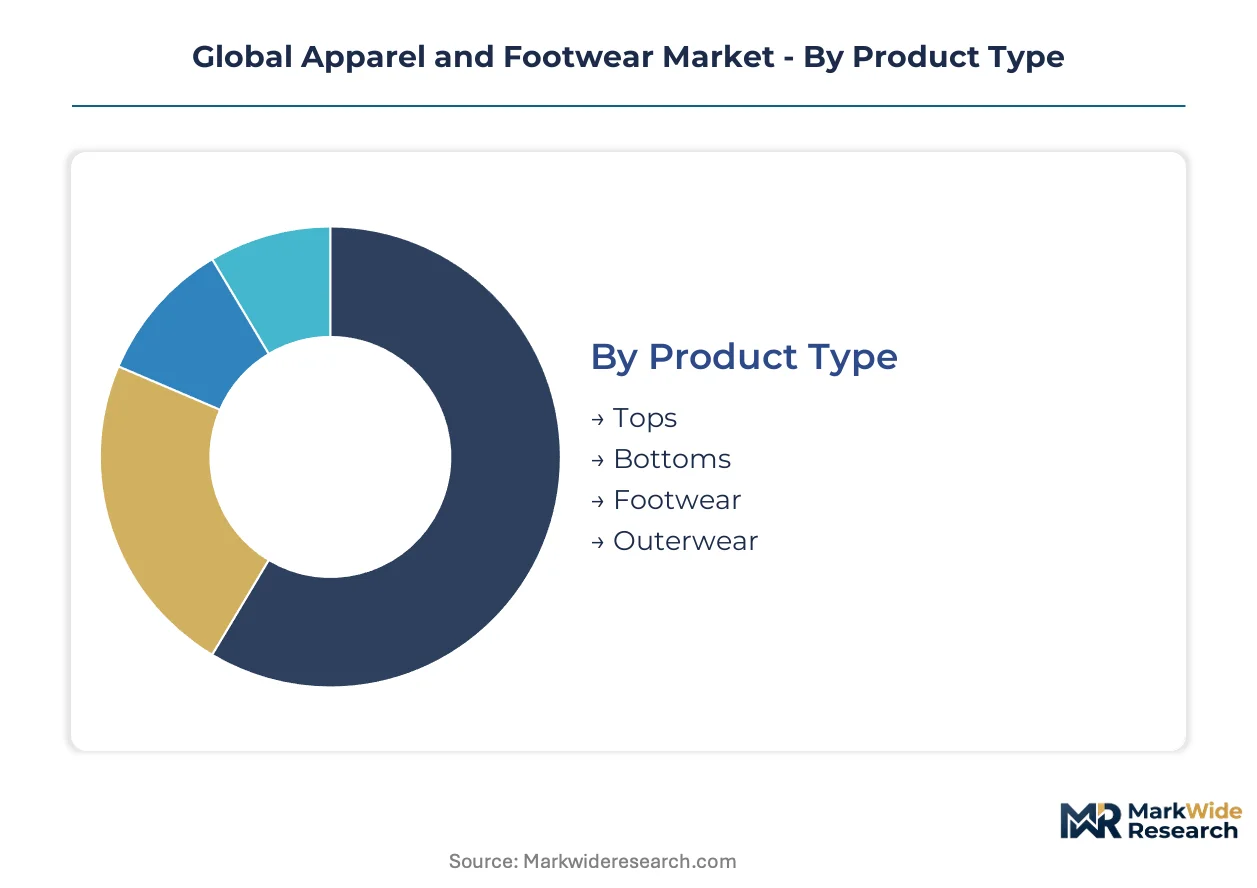
Segmentation in apparel and footwear reveals how margin pools, supply chain complexity, and channel economics diverge across product categories. Understanding these splits enables targeted capacity allocation and pricing architecture design.
Product Type:
Supply concentration in cut-and-sew and injection-molded manufacturing creates divergent margin profiles across garment versus footwear production.
- Footwear:Injection-molded sole construction and multi-material upper assembly command premium pricing due to technical complexity. Vietnam and China dominate volume for performance and fashion segments, with Italian producers anchoring luxury leather goods.
- Tops:Cut-and-sew assembly of shirts, blouses, and knitwear operates at higher velocity but compressed margins. Bangladesh and India absorb the bulk of woven shirt capacity as buyers seek cost efficiency against sustainability compliance burdens.
- Bottoms:Denim and trouser production clusters in Turkey, Mexico, and Pakistan, with finishing capabilities determining access to EU and US import channels.
- Outerwear:Technical fabric lamination and seam-sealing equipment requirements limit supplier pools. Alpine and Nordic brands source heavily from Romania and Portugal for proximity to European outdoor markets.
Footwear absorbs the bulk of installed capacity investment in automated lasting and 3D knitting equipment; outerwear is expanding most quickly as climate-adaptive technical specifications proliferate.
Material:
Cost tier stratification separates commodity fibers from performance and certified alternatives with divergent traceability burdens.
- Polyester:Virgin and recycled polyethylene terephthalate variants dominate fast-fashion volume. Mechanical recycling infrastructure in Southeast Asia is displacing virgin feedstock demand as brand sustainability commitments harden.
- Cotton:Staple fiber length and organic certification grades determine pricing spreads. Texas High Plains and Punjab supply volatility is forcing long-term contracting by denim and knitwear producers.
- Leather:Full-grain hides for luxury goods concentrate in Italian and Spanish tanneries; chrome-free tanning investments respond to REACH chemical restrictions.
- Nylon:Polyamide 6 and 6,6 polymers serve performance outerwear and activewear. Bio-based feedstocks from castor oil are penetrating premium segments at elevated unit economics.
Polyester commands the greatest volume share; nylon is climbing the fastest on technical apparel substitution trends.
End User:
Customer type segmentation aligns design cycles, sizing complexity, and channel strategy with life-stage purchasing patterns.
- Women:Higher SKU breadth and seasonal velocity drive demand for responsive supply chains. Size inclusivity investments are expanding pattern-making and grading capabilities.
- Men:Longer replacement cycles and standardized fits favor efficiency-focused production. Tailoring and formalwear segments retain higher margin profiles in developed markets.
- Children:Rapid size turnover creates inventory risk managed through subscription and rental models. Safety certification requirements for flammability and choking hazards constrain supplier pools.
- Infants:Ultra-soft fabric specifications and chemical-free processing command premium positioning. Organic cotton and bamboo fiber penetration is highest in this segment.
Women's segments absorb the bulk of design and sampling capacity; children's is gaining share fastest via direct-to-consumer subscription infrastructure.
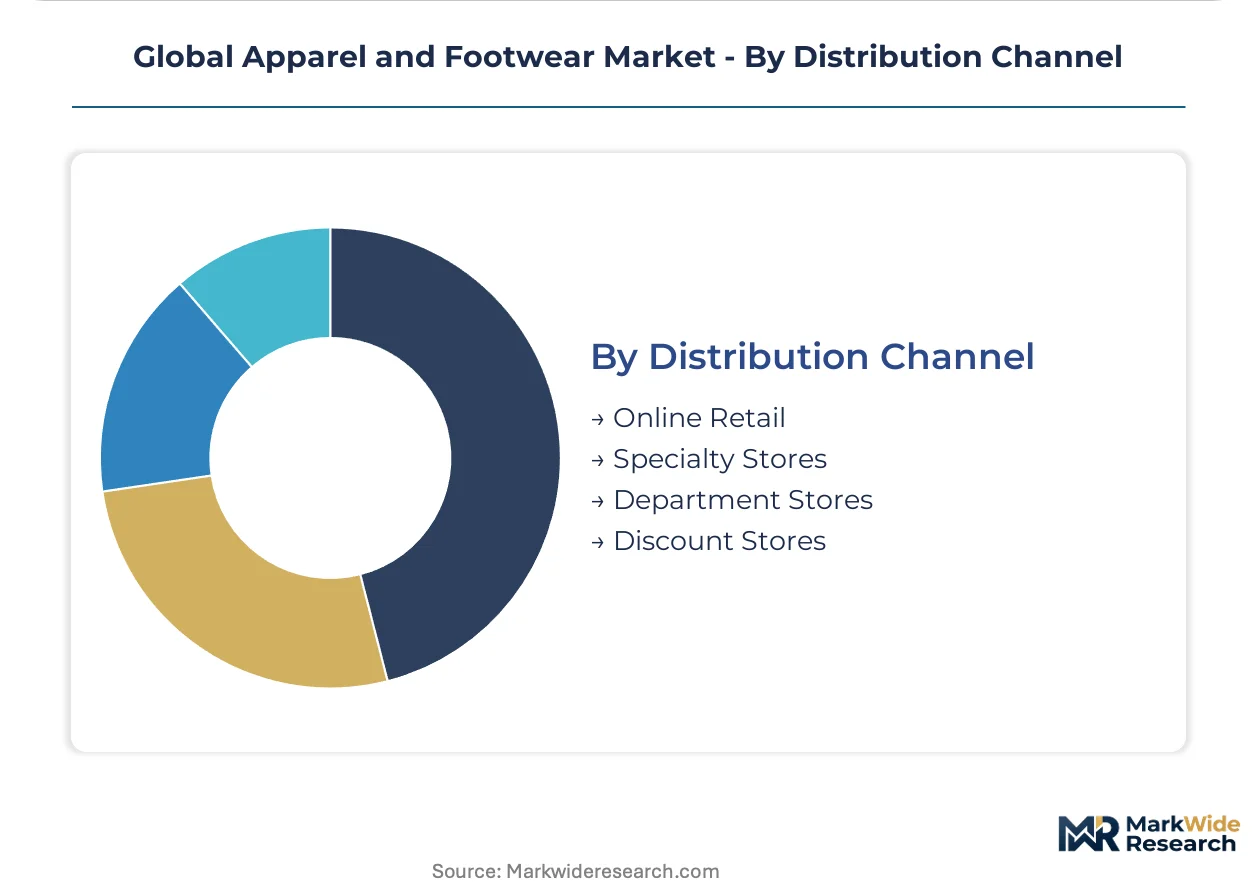
Distribution Channel:
Channel economics determine working capital intensity, return rates, and customer data capture capabilities across the value chain.
- Online Retail:Direct-to-consumer platforms enable dynamic pricing and inventory optimization. Reverse logistics networks for sizing returns are becoming competitive differentiators.
- Specialty Stores:Curated assortments and trained staff support premium and technical product categories. Running, outdoor, and luxury segments rely on this channel for brand experience delivery.
- Department Stores:Consolidating foot traffic and inventory risk is compressing order volumes. Remaining players are shifting to concession and marketplace models.
- Discount Stores:Off-price and value channels absorb excess inventory and secondary lines. Real-time inventory visibility systems are enabling more precise allocation.
Online retail captures the bulk of capital investment in fulfillment infrastructure; specialty stores are expanding most quickly in experience-driven premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing gravity concentrates in Southeast Asian export zones while consumption corridors expand across Chinese domestic markets and Indian tier-2 urban centers. This divergence between production and purchasing geography is reshaping logistics networks and regulatory compliance architectures.
China
Domestic premium consumption corridors in Shanghai, Beijing, and Shenzhen are absorbing capacity previously dedicated to export manufacturing. The country's dual carbon goals and GB standards are tightening emissions constraints on textile-producing regions. The Yangtze River Delta cluster is pivoting toward high-value technical fabrics and automated cut-and-sew lines.
Vietnam
Footwear and apparel export volume is accelerating as brands diversify sourcing beyond Chinese borders. The government's industrial zone incentives and EU-Vietnam Free Trade Agreement tariff advantages are attracting cut-and-sew investment. Ho Chi Minh City and surrounding provinces are absorbing the bulk of Korean and Taiwanese capital deployment in injection-molded sole facilities.
United States
Direct-to-consumer platform density and resale infrastructure investment are concentrating in Los Angeles, New York, and Chicago metropolitan areas. California's SB 657 transparency mandates and emerging extended producer responsibility frameworks are forcing supply chain documentation upgrades. The Southeast region is gaining apparel distribution center investment to compress last-mile delivery timelines.
India
Tier-2 and tier-3 cities including Surat, Ludhiana, and Tiruppur are driving branded penetration as disposable incomes expand beyond Delhi-Mumbai corridors. The Bureau of Indian Standards textile labeling requirements and PLI scheme incentives for man-made fiber production are restructuring domestic sourcing patterns. The Tamil Nadu knitwear cluster is upgrading from commodity exports to technical sportswear manufacturing.
Germany
Technical outdoor and performance segments command premium positioning through Munich and Hamburg design centers. REACH chemical restrictions administered by ECHA are eliminating perfluorinated treatments from European-bound apparel, forcing reformulation investments. The Baden-Württemberg region anchors automated manufacturing R&D for bio-based material processing.
Global Apparel and Footwear Market Vendor Landscape
Top-tier vendors anchor premium performance and luxury segments, while mid-scale specialists and private-label aggregators occupy volume-driven tiers. The vendor base stratifies across three archetypes: vertically integrated sportswear houses with captive R&D ecosystems, asset-light brand licensors outsourcing manufacturing to Southeast Asian contract producers, and direct-to-consumer challengers built on resale and subscription infrastructure. Competitive moves center on backward integration into bio-based material supply and geographic diversification of cut-and-sew capacity beyond single-country dependence.
Within the integrated sportswear tier, Nike and Adidas exemplify divergent strategic postures—Nike through direct-to-consumer channel control and Adidas through bio-material R&D intensity—while Anta Sports occupies a position representing Greater China distribution dominance and vertical manufacturing consolidation. These three anchors illustrate how regional market access, material innovation pipelines, and channel architecture differentiate competitive positioning without requiring uniform global scale.
| Leading Market Players |
|---|
| Anta Sports |
| New Balance |
| Nike |
| Li Ning Company |
| VF Corporation |
| Adidas |
| Lululemon Athletica |
| PUMA |
| ASICS Corporation |
| Others |
Supply Flow & Price Mechanics
Fast-fashion volume buyers concentrate procurement decisions in Bangladesh and Vietnam, locking in contract-based long-term offtake pricing that rewards scale and compliance certification over spot-market flexibility. This buyer-archetype concentration forces suppliers to absorb cotton price volatility and REACH reformulation costs within fixed-margin structures.
Pricing Analysis
Margin tightening in cut-and-sew segments reflects cotton price volatility from Texas High Plains and Punjab yield compression. Three-tier pricing structure across premium, standard, and economy levels separates certified organic cotton goods from conventional fiber and recycled polyester alternatives. Price differentiation hinges on GOTS certification grade and brand premium capture in direct-to-consumer channels. Mass-market retailers exhibit highest price sensitivity; luxury houses maintain pricing power through scarcity and authentication technology.
Supply Chain Analysis
EU Green Deal digital passport certification gates access to European import channels, forcing upstream visibility investments. Manufacturing concentrates in Bangladesh, Vietnam, and China, with raw material dependencies on Texas and Punjab cotton, Saudi petrochemical feedstocks, and Italian tannery outputs. Single-source vulnerability in dyeing chemicals from ECHA-restricted PFAS suppliers creates reformulation bottlenecks. Distribution runs through direct-to-consumer platforms and specialty retail in urban consumption corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's extended producer responsibility mandates erect a compliance moat that favors incumbent players with capital to fund traceability infrastructure and digital passport systems.
For Market Incumbents: Anticipate REACH chemical restrictions eliminating legacy water-repellent treatments by accelerating silicone-based and bio-derived alternative R&D. Defend market position through backward integration into certified organic cotton contracting and mycelium leather supply. Channel control via direct-to-consumer platforms captures pricing power and customer data against fast-fashion aggregators.
For New Entrants and Emerging Players: The premium-economy price-point gap in technical outerwear creates entry space for bio-based material specialists. India's tier-2 cities offer the most penetrable geography as branded apparel demand outpaces domestic supply. A rental-subscription go-to-market angle bypasses inventory risk while building authentication credibility.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated sportswear houses with captive Vietnam manufacturing and EU compliance infrastructure. Long-term viability over the next decade rests on digital traceability readiness and bio-material patent pipelines. Watch for ECHA enforcement intensity against PFAS-containing inventory as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Product Passport Integration | EU Green Deal compliance secures market access for European-bound apparel volumes. |
| Bio-Based Material R&D Partnership | Mycelium leather and algae-dye collaborations reduce petroleum dependency in performance footwear. |
| Direct-to-Consumer Platform Launch | Nike's ecosystem model demonstrates pricing control and data capture advantages. |
| Resale Authentication Infrastructure | Blockchain-enabled provenance tracking monetizes circular economy participation for luxury segments. |
| Southeast Asian Manufacturing Expansion | Vietnam's EU-Vietnam Free Trade Agreement tariff advantages attract cut-and-sew investment. |
Methodological Framework
Multi-period observation of fiber sourcing patterns, digital passport adoption timelines, and rental platform subscriber growth anchored the trend analysis, supplemented by interviews with supply chain directors at multinational apparel houses, sustainability officers at luxury brands, procurement leads at fast-fashion retailers, and technical directors at textile testing laboratories. Secondary validation drew from EU ECHA restriction dossiers, US CBP customs entry data, BIS textile labeling notifications, and SEC 10-K filings from publicly traded sportswear companies. Bottom-up capacity modeling and top-down consumption corridor analysis were triangulated against trade flow data.
Segment-weighting across product type, material composition, end-user demographic, and distribution channel dimensions structured the analytical framework. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements across the analysis window. Industry-specific forecast inputs included GB standards implementation timelines and PLI scheme incentive disbursement patterns.
Inputs from ECHA regulatory filings and Vietnam industrial zone investment databases were available through the study window; gaps in subcontracting network visibility beyond tier-2 suppliers introduce uncertainty bands around labor compliance risk assessments. Forecasts reflect documented assumptions on carbon border adjustment mechanism coverage and bio-material cost-down curves. A model refresh is warranted upon material change in EU Green Deal enforcement intensity or REACH substance restriction expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Global Shirt Market
Apparel & Footwear
Outdoor Jacket Market
Apparel & Footwear
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
Women's Dresses and Skirts Market
Apparel & Footwear
Southeast Asia Lingerie Market
Apparel & Footwear
Bra Cups Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Golf Apparel Market
Apparel & Footwear
Asia-Pacific Jeans Market
Apparel & Footwear
Hats Market
Apparel & Footwear
Apparel and Leather Products Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
Asia Pacific Swimwear Market
Apparel & Footwear
Gymnastic Leotards Market
Apparel & Footwear
Global Luxury Underwear Market