
 Nail Buffers Market | 2026-2036
Nail Buffers Market Size, Share, and Industry Trends Forecast 2026-2036
Nail Buffers Market Insights
Subscription-based leasing of electric buffer systems is tilting capital requirements downward for salon entrants. OPI leverages its professional channel relationships to sustain placement in high-end spa facilities. Guangzhou Newnail Cosmetics anchors production scale in the Pearl River Delta, where it controls access to integrated silicone sourcing. Revlon competes through mass-retail distribution that extends brand recognition into home-use segments.
Nail buffers are abrasive or polishing implements engineered to smooth nail plate surfaces, typically constructed with bonded foam layers, silicone coatings, or graded mineral abrasives calibrated to specific grit ranges for controlled material removal. Their primary commercial purpose centers on preparing natural and artificial nails for coating adhesion while delivering cosmetic finish refinement. Electric buffers command premium positioning in professional settings where throughput requirements favor motorized operation, whereas manual buffers retain volume leadership in home-use channels where price sensitivity dominates purchase decisions. Silicone-based buffers are capturing margin pools as durability advantages over foam justify higher unit economics across repeat-purchase cycles.
FDA oversight of cosmetic tool safety in the United States shapes material composition requirements, while REACH enforcement through ECHA restricts certain chemical binders in European-imported buffer products. China's SAMR implements national standards (GB) for personal care appliance safety that electric buffer manufacturers must satisfy for domestic market access. Stakeholders must monitor evolving cross-border chemical compliance obligations as regulatory divergence between major economies complicates unified product platform strategies.
Market Dynamics
REACH enforcement through ECHA is tightening material standards for foam and silicone buffer components, forcing manufacturers to reformulate binders and driving consolidation among European suppliers unable to absorb compliance costs.
Growth Catalysts
- Gel-manicure service proliferation:Professional salons in South Korea are expanding buffer adoption as gel-manicure services multiply, creating pull-through demand for both disposable and electric buffer systems.
- GB standard harmonization:China's SAMR implements national standards for personal care appliance safety that electric buffer manufacturers must satisfy, streamlining domestic market access and reducing certification friction.
- Silicone durability premium:Silicone-based buffers are capturing margin pools as durability advantages over foam justify higher unit economics across repeat-purchase cycles in professional channels.
Market Restraints
- Petrochemical input volatility:Foam buffer production depends on polyurethane feedstocks whose prices fluctuate with crude oil markets, compressing margins for mid-tier manufacturers without captive chemical supply.
- Guangdong supply concentration:Manufacturing clusters in China's Guangdong province control integrated silicone sourcing, creating geographic single-point-of-failure risk for brands without diversified production footprints.
- Manual buffer substitution ceiling:Electric buffer penetration in home-use segments faces resistance from price-sensitive consumers who retain manual buffer preference despite performance gaps.
Strategic Opportunities
- Subscription leasing models:Subscription-based leasing of electric buffer systems is tilting capital requirements downward for salon entrants, opening professional-grade equipment access to independent operators.
- Mass-retail channel expansion:Home-use segments present white space for brands with mass-retail distribution capabilities to extend recognition from cosmetic adjacencies into buffer categories.
- Dual carbon alignment:China's dual carbon goals create regulatory tailwinds for manufacturers developing low-emission silicone synthesis processes and recyclable buffer constructions.
Industry Challenges
- Cross-border compliance divergence:FDA oversight of cosmetic tool safety in the United States shapes material composition requirements differently than REACH enforcement, complicating unified product platform strategies for multinational suppliers.
- Electric buffer certification timelines:SAMR GB standard testing and FDA electrical safety clearance create extended approval cycles that delay new electric buffer model launches in priority markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nail Buffers Market |
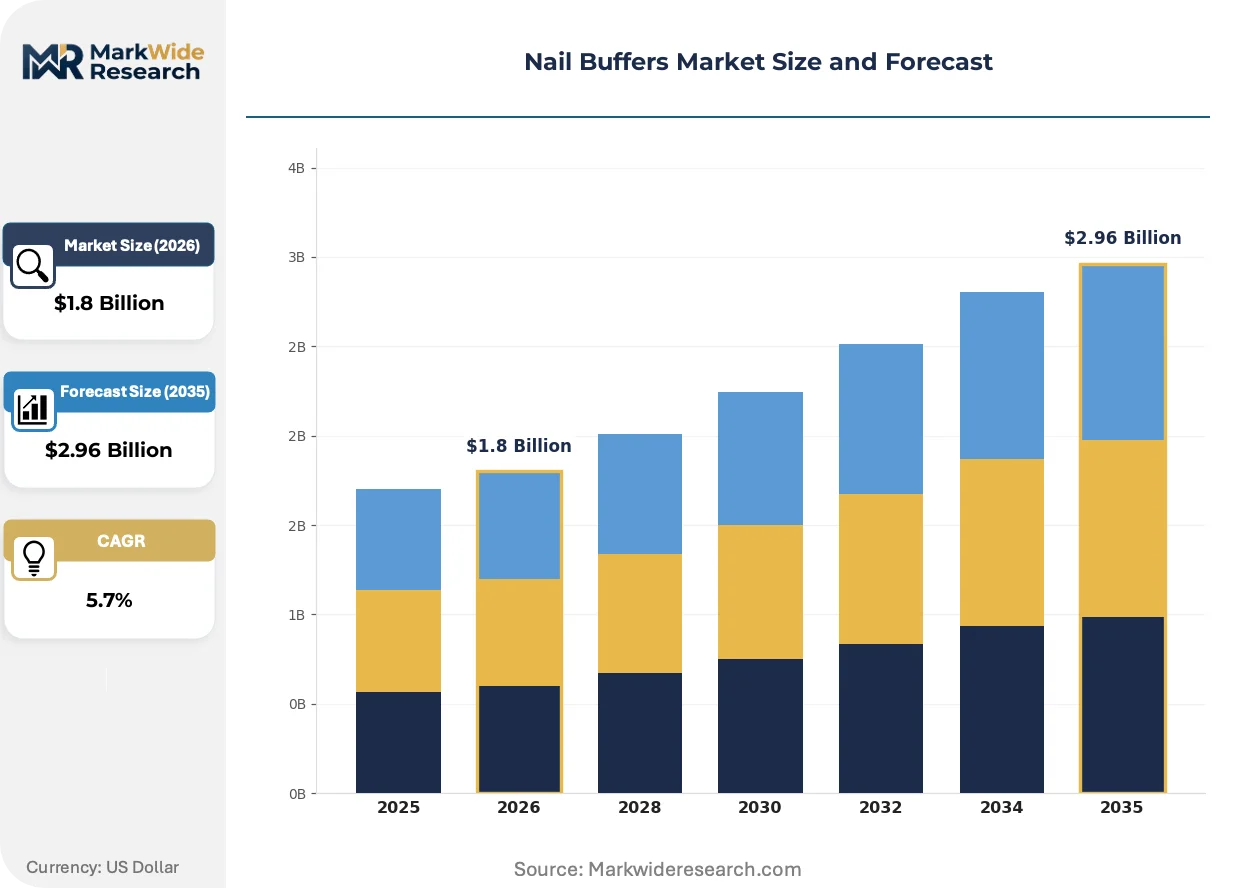
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Buffers, Manual Buffers, Microfiber Buffers, Dual-Sided Buffers Material: Silicone, Foam, Sandpaper, Cotton Finish Type: Matte, Glossy, Satin, High-Gloss End User: Professional Salons, Home Users, Spa Facilities, Nail Technicians |
| Companies Covered | Revlon, Sally Hansen, OPI, Tweezerman, Essie, Coty, L'Oréal, KISS, Guangzhou Newnail Cosmetics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nail Buffers Market Trends and Innovations
Smart motor control systems are digitizing buffer operation parameters, enabling precise RPM regulation and torque feedback that professional technicians leverage for consistent finish quality across service appointments.
Embedded sensor arrays in premium electric buffers is digitizing usage pattern capture, allowing manufacturers to monitor wear-cycle data and predictive maintenance needs across installed salon equipment fleets. Professional chains in South Korea are piloting these connected systems to optimize buffer replacement scheduling and reduce service downtime. The resulting data streams are compressing traditional aftermarket parts margins by enabling direct manufacturer-to-salon consumable fulfillment.
REACH restrictions on chemical binders are forcing reformulation of foam buffer adhesives used in European-imported products, with ECHA substance-of-very-high-concern listings targeting specific isocyanate compounds common in legacy manufacturing. Buffer producers serving EU markets are accelerating migration to water-based adhesive systems despite higher curing energy requirements. Silicone buffer suppliers with pre-validated compliant formulations are capturing shelf space from foam-dependent competitors facing extended requalification timelines.
Home-use buyers are compressing replacement cycles for manual buffers as social media-driven nail care tutorials elevate finish-quality expectations among amateur practitioners. Mass-retail channels are responding with multi-grit buffer kits positioned as essential tools rather than disposable accessories. This behavioral shift is most visible in China's tier-one cities where live-commerce demonstrations drive impulse buffer purchases alongside color cosmetic bundles.
Nail Buffers Market Segmentation
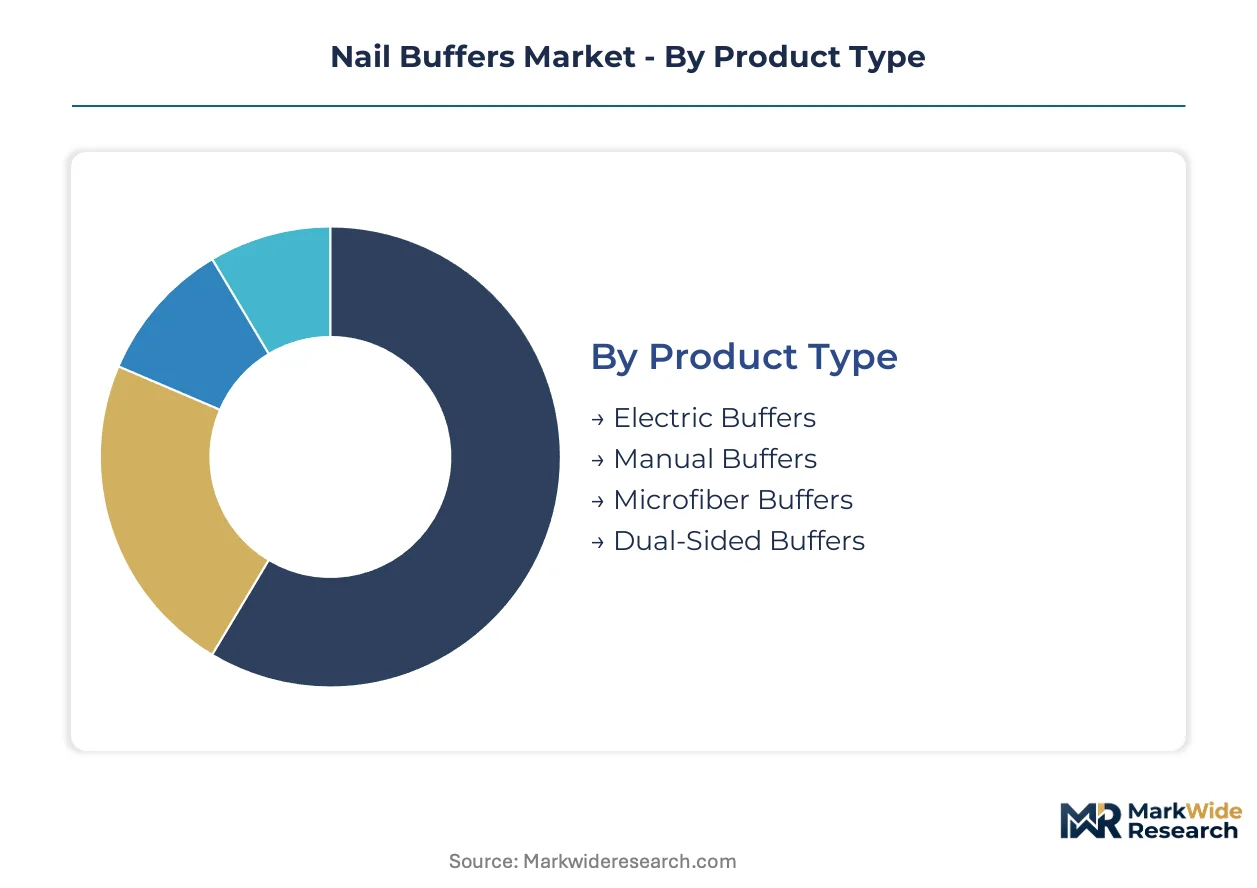
Buffer manufacturers design service protocols and replacement schedules around distinct usage intensities. Product durability requirements diverge sharply between high-throughput professional environments and intermittent home application. Material selection directly shapes warranty exposure and consumable revenue attachment rates across each segment category.
Product Type:
After-sales-service intensity varies dramatically across motorized versus manual systems, with electric units demanding technical support infrastructure that manual buffers never require.
- Electric Buffers:Motorized units with variable RPM control and torque feedback systems command premium positioning in South Korean salon chains where gel-manicure throughput requirements favor consistent power delivery. Professional technicians in Seoul's Gangnam district leverage these systems for service standardization across appointment volumes. Replacement parts and calibration services generate recurring revenue streams that manual alternatives cannot match.
- Manual Buffers:Hand-operated abrasive implements constructed with bonded foam layers or mineral grit surfaces dominate home-use channels where price sensitivity overrides performance specifications. Guangdong manufacturing clusters supply these units at scale for both domestic Chinese consumption and export to North American mass-retail channels. The absence of electrical components eliminates certification friction and simplifies cross-border distribution.
- Microfiber Buffers:Fine-fiber polishing tools designed for final-stage shine refinement without abrasive removal.
- Dual-Sided Buffers:Multi-grit implements combining coarse smoothing and fine polishing surfaces in single units.
By volume, Manual Buffers leads. By growth pace, Electric Buffers is ahead.
Material:
Cost tier stratification separates premium silicone formulations from commodity foam alternatives, with raw material sourcing geography determining margin compression exposure.
- Silicone:Synthetic polymer coatings deliver extended wear cycles that justify unit price premiums in professional settings. Guangzhou Newnail Cosmetics anchors integrated silicone sourcing through Pearl River Delta petrochemical networks. REACH compliance validation for European export requires pre-certified formulation documentation that foam competitors lack.
- Foam:Polyurethane-based bonded layers offer lower entry pricing for price-sensitive home-use segments. Crude oil price volatility directly compresses margins for manufacturers without captive chemical supply. ECHA substance-of-very-high-concern listings targeting isocyanate compounds are forcing accelerated migration to water-based adhesive systems.
- Sandpaper:Mineral-abrasive coated substrates calibrated to specific grit ranges for controlled nail plate material removal.
- Cotton:Natural fiber polishing implements for final buffing stages in traditional manicure protocols.
By installed base, Foam dominates. By margin expansion, Silicone is climbing the fastest.
Finish Type:
Application requirements dictate buffer specification, with coating adhesion chemistry driving surface preparation standards across gel and traditional lacquer systems.
- Matte:Non-reflective surface preparation for specialty coating systems requiring specific mechanical tooth profiles.
- Glossy:High-reflectance finish refinement for standard manicure presentation in professional salon environments.
- Satin:Intermediate sheen specifications balancing aesthetic subtlety with surface protection requirements.
- High-Gloss:Mirror-finish polishing protocols demanding multi-stage buffer progression through graduated grit sequences.
By procedure frequency, Glossy leads. By technique complexity, High-Gloss commands the steepest expansion trajectory.
End User:
Customer type determines procurement channel structure, with institutional buyers negotiating service contracts that individual consumers never access.
- Professional Salons:High-volume service operations in South Korea's expanding gel-manicure market prioritize electric buffer durability and manufacturer-direct parts availability. Subscription-based equipment leasing models are tilting capital requirements downward for independent operators entering the segment.
- Home Users:Individual consumers purchasing through mass-retail or live-commerce channels exhibit compressed replacement cycles driven by social media tutorial exposure. China's tier-one cities demonstrate impulse purchase patterns alongside color cosmetic bundles.
- Spa Facilities:Wellness-integrated nail service operations requiring premium buffer positioning for brand differentiation.
- Nail Technicians:Independent practitioners balancing equipment portability against professional-grade performance requirements.
By unit volume, Home Users leads. By value concentration, Professional Salons is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional salon operators in South Korea, mass-retail home users in the United States, and manufacturing clusters in China's Guangdong province represent the three dominant buyer archetypes shaping regional demand patterns. Each geography exhibits distinct procurement channel preferences and regulatory exposure profiles.
United States
FDA oversight of cosmetic tool safety shapes material composition requirements for buffer imports, particularly around adhesive binders and silicone coatings. Mass-retail distribution channels dominate home-use procurement, with compressed replacement cycles driven by social media tutorial exposure. Independent nail technicians in Florida and California represent a growing professional segment seeking portable equipment solutions.
South Korea
Gel-manicure service proliferation in Seoul's Gangnam district creates pull-through demand for electric buffer systems with variable RPM control. MFDS cosmetic safety standards govern professional-grade equipment certification requirements. Subscription-based equipment leasing models are expanding access for independent salon operators in Busan-Ulsan metropolitan areas.
China
SAMR implements national GB standards for personal care appliance safety that electric buffer manufacturers must satisfy for domestic market access. Guangzhou Newnail Cosmetics anchors integrated silicone sourcing through Pearl River Delta petrochemical networks. Live-commerce demonstrations in Shanghai and Beijing tier-one markets drive impulse buffer purchases alongside color cosmetic bundles.
Germany
REACH enforcement through ECHA restricts chemical binders in foam buffer components, forcing reformulation of polyurethane adhesive systems. Professional spa facilities in Munich and Hamburg prioritize premium silicone buffer positioning for brand differentiation. Water-based adhesive migration timelines create competitive gaps for pre-validated compliant suppliers.
Japan
METI industrial standards and PMDA cosmetic safety protocols govern buffer material specifications for domestic distribution. Precision manufacturing traditions in Osaka-Kobe industrial corridors favor high-durability silicone formulations over commodity foam alternatives. Nail technician licensing requirements in Tokyo metropolitan salons sustain professional-grade equipment demand.
Nail Buffers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent distribution architectures. The market structure tiers into three segments: mass-retail brands commanding shelf-space leverage, professional-channel specialists with salon-direct relationships, and integrated manufacturers controlling upstream silicone supply. Dominant competitive moves include geographic expansion into live-commerce platforms and portfolio diversification across manual and electric product lines.
Among mass-retail beauty conglomerates, Revlon and L'Oréal occupy positions exemplifying brand-recognition leverage into home-use buffer categories. OPI represents the professional-channel archetype, anchoring placement in high-end spa facilities through technician relationship networks. Guangzhou Newnail Cosmetics Co., Ltd. exemplifies the integrated-manufacturer archetype, sitting within Pearl River Delta manufacturing clusters with captive silicone sourcing advantages.
| Leading Market Players |
|---|
| Revlon |
| Sally Hansen |
| OPI |
| Tweezerman |
| Essie |
| Coty |
| L'Oréal |
| KISS |
| Guangzhou Newnail Cosmetics Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Guangdong's silicone buffer manufacturing corridor is compressing supplier margins and accelerating payment-term concessions to maintain offtake volumes. This utilization pressure cascades into pricing softness for foam-based alternatives as manufacturers absorb feedstock volatility to defend market share.
Pricing Analysis
Certification level creates the primary spread between REACH-compliant silicone buffers and uncertified foam alternatives, with ECHA-validated formulations commanding 40-60% premiums in European professional channels. Three-tier pricing structure separates salon-grade electric systems with embedded sensors from standard manual kits and economy disposable units. Cost compression in foam tiers is intensifying because polyurethane feedstock volatility erodes mid-tier manufacturer margins. Home-use segments exhibit highest price sensitivity, while South Korean salon chains prioritize durability over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days have become standard for Guangdong-based manufacturers serving European professional distributors, reflecting working-capital strain from silicone inventory carrying costs. Supply concentrates in China's Pearl River Delta, South Korea's Seoul metropolitan manufacturing belt, and Germany's precision component corridors. Production draws from silicone petrochemical feedstocks, graded mineral abrasives, and electric motor assemblies. Single-source vulnerability around Guangzhou Newnail's integrated silicone sourcing creates geographic concentration risk. Distribution runs through professional salon-direct channels, mass-retail big-box networks, and live-commerce platforms in Chinese tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Profitable participation in this market hinges on controlling REACH-validated silicone formulations or capturing subscription-based equipment leasing infrastructure—capabilities concentrated among fewer than six integrated suppliers globally.
For Market Incumbents: Harden compliance documentation for ECHA substance-of-very-high-concern listings to extend shelf-space advantages over foam competitors facing requalification delays. Deepen upstream control over Pearl River Delta silicone synthesis capacity to offset petrochemical input volatility and secure margin expansion in professional channels. For New Entrants and Emerging Players: Establish a beachhead in China's live-commerce home-use segment where impulse purchase patterns alongside color cosmetic bundles reduce brand-recognition barriers. Target independent nail technicians in Florida and California seeking portable electric solutions, leveraging direct-to-consumer fulfillment to bypass entrenched mass-retail shelf-space controls. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electric buffer manufacturers with embedded sensor fleets generating predictive maintenance data streams and direct consumable fulfillment relationships. Long-term viability favors targets with pre-validated REACH-compliant silicone formulations and installed base density in South Korean salon chains. Monitor ECHA enforcement intensity as the inflection signal—accelerated substance-of-very-high-concern listings would compress requalification timelines and consolidate share among compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Silicone Formulation Migration | ECHA enforcement accelerates competitive consolidation toward pre-validated suppliers. |
| Subscription Equipment Leasing Expansion | Seoul salon operators adopt capital-light models opening professional-grade access. |
| Embedded Sensor Fleet Deployment | Gangnam district chains pilot predictive maintenance compressing aftermarket margins. |
| Live-Commerce Channel Penetration | Shanghai impulse purchase patterns alongside cosmetics bundles reduce entry barriers. |
| Water-Based Adhesive System Transition | European foam buffer producers face extended requalification timelines versus silicone alternatives. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with salon chain procurement directors, electric buffer technical service managers, and Guangdong manufacturing operations leads; and secondary validation through SAMR GB standard filings, ECHA REACH registration databases, and Korean MFDS cosmetic safety notifications. Bottom-up triangulation against top-down trade flow estimates anchored volume and value assessments.
Forecast inputs incorporated electric versus manual product mix shifts, silicone durability premium capture rates, and REACH compliance cost pass-through elasticity across the analysis window. Segmentation modeling spanned product type, material chemistry, finish specification, and end-user procurement channel. CAGRs derived from installed base replacement cycles and professional service throughput expansion in gel-manicure markets.
Sensitivities concentrate around ECHA substance-listing acceleration, crude oil price volatility transmission to polyurethane feedstocks, and SAMR certification timeline extensions for new electric buffer models. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
Deodorant Products Market
Beauty & Personal Care
Global Organic Personal Care and Cosmetic Products Market
Beauty & Personal Care
Personal Care Shower and Bath Market
Beauty & Personal Care
Hair Salon Equipment Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Soap Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
Post-Shave Care Market
Beauty & Personal Care
Facial Makeup Setting Spray Market
Beauty & Personal Care
Global Massage Oil Market
Beauty & Personal Care
Hair Removal Wax Market
Beauty & Personal Care
Cosmetics Foundation Market