
 Fast Fashion Market | 2026-2036
Fast Fashion Market Size, Share, and Industry Trends Forecast 2026-2036
Fast Fashion Market Intelligence
The Gen Z consumer segment is broadening its share of total fast fashion expenditure through TikTok and Instagram-driven purchase cycles. Shein leverages algorithmic demand forecasting to compress design-to-shelf timelines below two weeks. Zara anchors its competitive position through in-house manufacturing in Spain, Portugal, and Morocco that enables rapid inventory replenishment. H&M sustains market presence via its Conscious Collection line, navigating sustainability scrutiny without abandoning price-driven positioning.
Fast fashion denotes apparel and accessory production cycles optimized for rapid trend replication, typically utilizing polyester-cotton blends and viscose fabrics manufactured through cut-make-trim processes with lead times under six weeks. The model serves commercial demand for disposable, trend-responsive clothing at mass-market price points. Apparel dominates absolute revenue contribution while accessories capture expanding margin pools from impulse purchases tied to social media trends. Online retail channels are displacing department stores as the primary distribution mechanism, with specialty stores retaining relevance for experiential browsing among urban consumers. Casual wear and activewear applications are outpacing party wear as hybrid work arrangements reshape daily dressing requirements.
The EU Green Deal, France's AGEC law, and California's SB 657 Transparency in Supply Chains Act are tightening disclosure requirements for textile sourcing, chemical use, and labor practices across major demand markets. These frameworks elevate compliance costs for pure-play fast fashion operators while creating market access barriers for smaller competitors lacking traceability infrastructure. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to absorb compliance investments or accelerate premium positioning before regulatory thresholds harden.
Market Dynamics
Algorithmic demand forecasting is compressing design-to-shelf cycles below fourteen days while EU Green Deal mandates force simultaneous supply chain transparency investments, creating a dual-speed operational reality for fast fashion operators.
Growth Catalysts
- EU Green Deal digital product passport requirements:The EU Green Deal mandates granular textile traceability disclosure, accelerating infrastructure investment among first-mover brands seeking regulatory compliance advantage.
- Vietnam and Bangladesh manufacturing cluster expansion:Southeast Asian production capacity growth supports order volume scaling without proportional labor cost inflation.
- Social commerce platform integration:TikTok and Instagram native checkout features are collapsing discovery-to-purchase friction for Gen Z cohorts.
Market Restraints
- Polyester-cotton blend input cost volatility:Crude oil price fluctuations and cotton harvest variability squeeze margin predictability for synthetic-natural fiber mix producers.
- Single-source viscose supplier concentration:Austrian and Indian viscose fiber producers control critical input volumes, creating geographic supply risk.
- France AGEC law extended producer responsibility:The AGEC law imposes textile waste management cost allocation onto brands, elevating structural operating expenses.
Strategic Opportunities
- India domestic market penetration:India's rising middle-class apparel consumption remains underpenetrated by organized fast fashion relative to population scale.
- Resale platform channel integration:Secondary market infrastructure partnerships offer customer retention mechanisms and sustainability credential accumulation.
- AI-driven size prediction convergence:Machine learning body-scanning technology fused with return logistics is reducing fit-related return rates.
Industry Challenges
- Supply chain reconfiguration for California SB 657 compliance:The Transparency in Supply Chains Act demands labor practice documentation that legacy vendor management systems cannot generate.
- Recycled fiber certification timeline compression:Global Recycled Standard and OEKO-TEX certification backlogs delay sustainable collection launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fast Fashion Market |
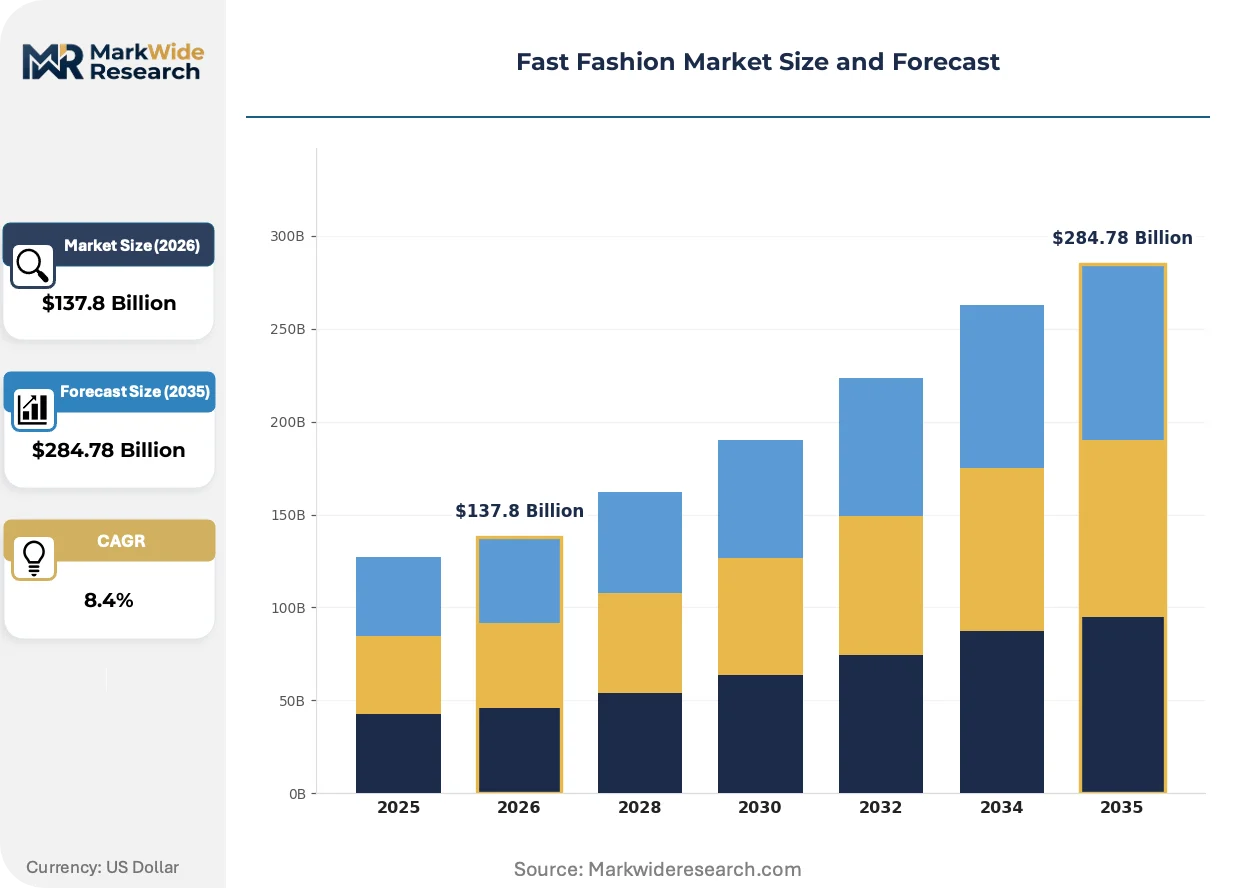
| Market Size in 2026 | $137.8 Billion |
| Market Size in 2035 | $284.78 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Accessories, Footwear, Outerwear, Intimates Distribution Channel: Online Retail, Specialty Stores, Department Stores, Outlet Stores, Pop-up Shops Customer Type: Teens, Young Adults, Urban Consumers, Budget Shoppers, Trend Seekers Application: Casual Wear, Party Wear, Workwear, Activewear, Travel Wear |
| Companies Covered | Zara (Inditex), H&M (Hennes & Mauritz), Shein, Uniqlo (Fast Retailing), Primark, ASOS, Boohoo, Mango, Fashion Nova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fast Fashion Market Strategic Shifts & Innovations
Micro-factory production networks and blockchain-based provenance tracking are fragmenting traditional mass-manufacturing concentration while reshaping competitive advantage sources away from pure scale economies.
On-demand digital textile printing is modularizing colorway and pattern production by enabling single-unit batch economics without screen setup overhead. Mid-tier brands with limited SKU breadth are adopting this capability fastest. The technology is modularizing regional fulfillment center roles into design-finalization nodes rather than pure distribution points.
The EU Green Deal's textile strategy and France's AGEC law are mandating fiber composition disclosure and repair service provision. These frameworks are elevating compliance infrastructure to core competitive capability status. Premium-positioned operators in Germany and France are absorbing these costs through price architecture adjustments.
Social commerce discovery algorithms have compressed trend identification-to-purchase cycles from seasonal to weekly rhythms. Younger consumers now treat apparel as content-responsive rather than wardrobe-building purchases. This behavioral shift is most visible in US and UK urban markets where TikTok Shop penetration exceeds traditional e-commerce growth rates.
Fast Fashion Market Segmentation
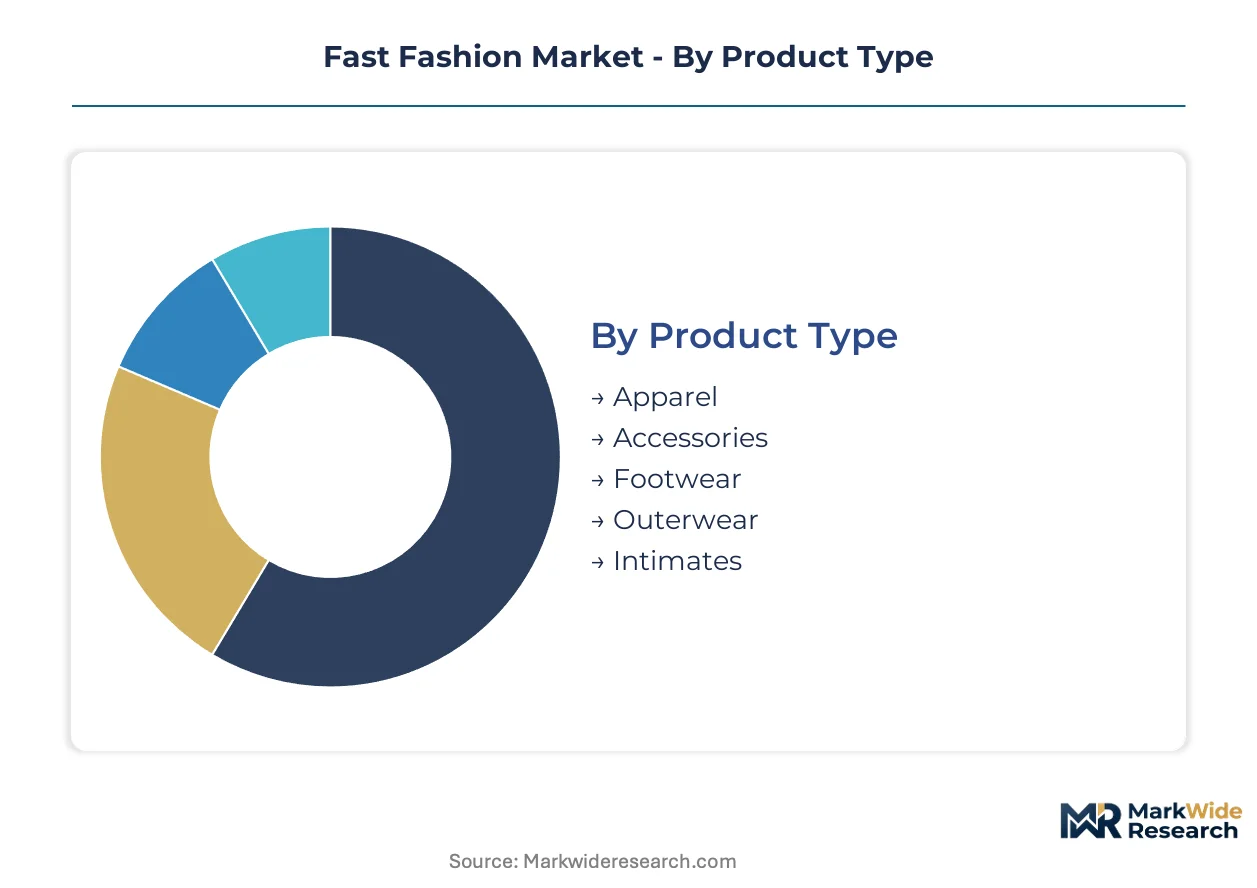
Fast fashion operators configure supply chains and pricing architectures around distinct product velocities, channel economics, and consumption occasions. Segment-level differentiation determines inventory risk exposure, margin capture potential, and regulatory compliance burden across operator portfolios.
Product Type:
Material composition and production velocity define competitive positioning across garment categories.
- Apparel:Polyester-cotton blends and viscose fabrics dominate unit economics through cut-make-trim processes with sub-six-week lead times. Demand concentrates in Southeast Asian manufacturing clusters, particularly Vietnam and Bangladesh, where capacity expansion supports volume scaling without proportional labor cost inflation.
- Accessories:Impulse-driven purchases tied to TikTok and Instagram trends capture expanding margin pools through lower return rates and higher attachment frequency. Gen Z cohorts in US and UK urban markets drive weekly replenishment cycles that outpace traditional seasonal rhythms.
- Footwear:Molded synthetic uppers and cemented construction enable rapid style turnover at mass-market price points.
- Outerwear:Synthetic insulation and water-resistant coatings balance seasonal demand spikes with inventory carry risk.
- Intimates:Seamless knitting technology and stretch-fabric blends support high-velocity replenishment with minimal SKU complexity.
Apparel leads on scale; accessories lead on momentum.
Distribution Channel:
Channel selection determines customer acquisition cost structures and sustainability disclosure requirements.
- Online Retail:Native checkout features on TikTok and Instagram collapse discovery-to-purchase friction for Gen Z consumers. Algorithmic demand forecasting compresses design-to-shelf timelines below fourteen days while elevating return logistics complexity.
- Specialty Stores:Experiential browsing environments retain relevance among urban consumers seeking tactile validation before purchase. France's AGEC law mandates repair service provision for physical retail operators, elevating compliance infrastructure requirements.
- Department Stores:Legacy anchor tenants face displacement as online channels capture traffic and margin.
- Outlet Stores:Off-price clearance mechanisms manage end-of-season inventory without diluting full-price positioning.
- Pop-up Shops:Temporary physical presence tests market receptivity with minimal lease commitment and localized trend responsiveness.
Online retail commands volume concentration; specialty stores retain margin defense capability.
Customer Type:
Demographic and psychographic segmentation shapes marketing spend allocation and product development priorities.
- Teens:Social commerce native behavior drives content-responsive purchase patterns rather than wardrobe-building intent. Weekly trend cycles on TikTok Shop outpace traditional e-commerce growth rates in US and UK markets.
- Young Adults:Hybrid work arrangements reshape daily dressing requirements toward casual wear and activewear applications. EU Green Deal digital product passport mandates elevate transparency expectations among this cohort.
- Urban Consumers:Density-dependent logistics enable same-day fulfillment and experiential retail formats.
- Budget Shoppers:Price-driven positioning sustains volume throughput with compressed per-unit margins.
- Trend Seekers:Early adoption willingness supports premium pricing for limited-drop collections and collaboration releases.
Young adults anchor revenue stability; teens drive steepest expansion trajectory.
Application:
Occasion-based demand patterns determine fabric specification and regional production allocation.
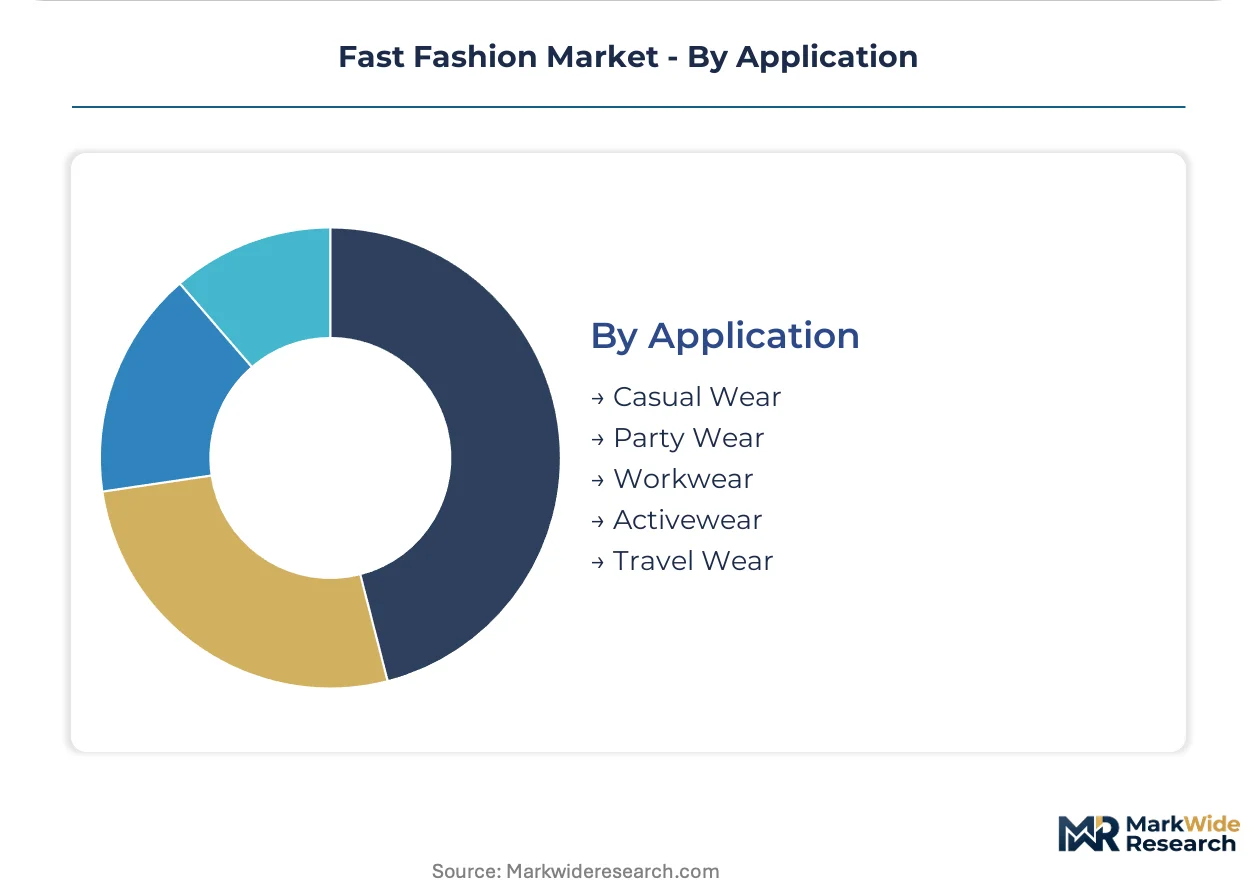
- Casual Wear:Knit fabrics and relaxed silhouettes dominate post-pandemic dressing norms across European and North American markets. Hybrid work persistence sustains demand concentration without seasonal volatility.
- Activewear:Performance synthetic blends and seamless construction capture margin premiums through technical positioning. Southeast Asian manufacturing clusters supply moisture-wicking and compression fabric technologies at scale.
- Party Wear:Occasion-dependent demand faces compression as social frequency normalizes below pre-pandemic levels.
- Workwear:Tailored separates and structured fabrics retain relevance in formal workplace environments.
- Travel Wear:Wrinkle-resistant synthetics and modular layering systems address post-pandemic mobility recovery.
Casual wear holds volume dominance; activewear gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese manufacturing clusters anchor the fastest fashion supply chain expansion, with Bangladesh and Indonesia following closely as alternative production bases reshape procurement geography.
United States
TikTok Shop penetration and Instagram native checkout features drive weekly replenishment cycles among Gen Z consumers in Los Angeles and New York. California's SB 657 Transparency in Supply Chains Act mandates labor practice documentation that legacy vendor systems struggle to generate. Texas and Southeast distribution centers are expanding same-day fulfillment capacity to match urban consumer expectations.
France
Parisian trend-setting sustains demand for rapid style turnover despite regulatory headwinds. The AGEC law imposes extended producer responsibility for textile waste management, elevating structural operating costs. Lyon and Lille manufacturing zones are adapting to repair service mandates for physical retail operators under the same framework.
Germany
Berlin and Hamburg consumers exhibit elevated transparency expectations under EU Green Deal digital product passport requirements. The ECHA chemical use disclosure standards tighten input sourcing protocols for polyester-cotton blend producers. Bavarian logistics hubs are integrating blockchain-based provenance tracking to satisfy premium-tier compliance demands.
United Kingdom
London urban markets display the steepest social commerce growth rates in Europe. The UK's post-Brexit regulatory divergence from EU textile standards creates dual compliance burdens for operators serving both markets. Manchester and Birmingham distribution networks are reconfiguring to handle elevated return logistics complexity from algorithmic demand forecasting.
India
Mumbai and Delhi-NCR underpenetration by organized fast fashion relative to population scale presents expansion opportunity. BIS textile labeling standards and DGFT import duty structures shape competitive positioning for domestic versus international operators. Tiruppur and Surat manufacturing clusters are scaling cut-make-trim capacity to serve both export and emerging domestic demand.
Fast Fashion Market Key Industry Players
Capacity expansion dominates the current landscape as operators race to capture Southeast Asian manufacturing scale before regulatory compliance costs harden. The vendor base concentrates around three tiers: vertically integrated European heritage houses, algorithmic pure-play disruptors, and value-positioned volume specialists. Strategic differentiation runs through supply chain transparency investments versus speed-to-market compression. M&A activity targets resale platform infrastructure and AI-driven size prediction technology.
Within the heritage integrated tier, Zara (Inditex) and H&M (Hennes & Mauritz) exemplify divergent responses to sustainability scrutiny—Zara through captive manufacturing in Spain, Portugal, and Morocco; H&M through its Conscious Collection line. Shein represents the algorithmic pure-play archetype, leveraging demand forecasting to compress design-to-shelf timelines below fourteen days. These three anchors illustrate the competitive tension between regulatory compliance infrastructure and velocity-driven market share capture.
| Leading Market Players |
|---|
| Zara (Inditex) |
| H&M (Hennes & Mauritz) |
| Shein |
| Uniqlo (Fast Retailing) |
| Primark |
| ASOS |
| Boohoo |
| Mango |
| Fashion Nova |
| Others |
Cost & Logistics Intelligence
Gen Z social commerce native behavior concentrates purchasing power in algorithmically-driven discovery channels, compressing margin capture through impulse-driven weekly replenishment cycles rather than planned wardrobe investment. This buyer archetype fragmentation forces operators to absorb return logistics complexity and platform commission structures that erode unit economics across online retail channels.
Pricing Analysis
Direct-to-consumer channel margins compress under platform commission structures from TikTok Shop and Instagram native checkout features, forcing three-tier pricing stratification across premium positioning, standard fast fashion, and ultra-value economy tiers. Price differentiation hinges on EU Green Deal compliance certification tier and geographic delivery cost arbitrage from Southeast Asian manufacturing clusters. Pricing pressure intensifies in the economy tier due to polyester-cotton blend input cost volatility from crude oil fluctuations. Budget shoppers exhibit highest price sensitivity while trend seekers tolerate premium positioning for limited-drop collections.
Supply Chain Analysis
Single-source vulnerability sits with Austrian and Indian viscose fiber producers controlling critical input volumes for rayon-dependent collections. Manufacturing draws from Bangladesh, Vietnam, and Indonesia where cut-make-trim capacity expansion supports volume scaling without proportional labor cost inflation. Raw material dependencies center on petroleum-derived synthetics, cotton harvest variability, and wood-pulp-based cellulosic fibers. Tariff exposure from EU Green Deal digital product passport mandates and France AGEC law extended producer responsibility schemes elevates compliance infrastructure costs. Distribution runs through online retail channels displacing department store legacy anchors, with specialty stores retaining relevance for experiential validation.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in fast fashion rests on AI-driven size prediction technology reducing fit-related return rates and premium-tier sustainability certification capturing price architecture adjustments before regulatory thresholds harden.
For Market Incumbents: Deepen backward integration into captive manufacturing in Spain, Portugal, and Morocco to defend replenishment velocity against pure-play algorithmic disruptors. Invest in blockchain-based provenance tracking infrastructure to preempt EU Green Deal compliance barriers. Anchor market position through repair service provision mandates under France AGEC law rather than absorbing costs as pure overhead. For New Entrants and Emerging Players: India's rising middle-class apparel consumption represents the most penetrable white-space opportunity relative to population scale. Target resale platform channel integration as customer retention mechanism and sustainability credential accumulation. Pursue on-demand digital textile printing partnerships to modularize regional fulfillment centers into design-finalization nodes without screen setup overhead. For Investors and Strategic Acquirers: Private equity firms with consumer portfolio expertise are the most active acquirer in this space, targeting AI-driven size prediction technology and secondary market infrastructure. Long-term viability favors operators with traceability infrastructure already deployed before extended producer responsibility schemes harden. Watch for recycled fiber certification timeline compression as inflection indicator for sustainable collection launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Size Prediction Deployment | Machine learning body-scanning technology reduces fit-related return rates and logistics costs. |
| Resale Platform Channel Integration | Secondary market partnerships offer customer retention and sustainability credential accumulation. |
| Blockchain Provenance Tracking Implementation | Ensures EU Green Deal digital product passport compliance for premium-tier market access. |
| Micro-Factory Production Network Expansion | Fragments mass-manufacturing concentration toward regional design-finalization nodes. |
| Repair Service Provision Infrastructure | France AGEC law mandates elevate compliance to core competitive capability status. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand supply chain directors, social commerce platform partnership leads, Southeast Asian manufacturing cluster managers, and EU regulatory affairs specialists with secondary validation from customs records, SEC 10-K filings of listed operators, and ECHA chemical use disclosure databases. Bottom-up SKU-level demand modeling and top-down market sizing triangulated volume and value estimates.
Segment-weighting approaches distributed growth assumptions across product type, distribution channel, customer demographic, and application occasion dimensions throughout the forecast period. CAGRs derived from algorithmic demand forecasting adoption curves, social commerce penetration rates, and regulatory compliance cost absorption trajectories. Industry-specific inputs included polyester-cotton blend price indices and recycled fiber certification backlog timelines.
Underlying measurement precision varies by segment; accessories and online retail channels carry tighter precision than outerwear and department store legacy channels due to data availability from platform-native checkout disclosures. Forecasts reflect assumptions around EU Green Deal implementation pacing and Gen Z purchase frequency stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Polo Shirt Market
Apparel & Footwear
Sleepwear Market
Apparel & Footwear
Asia-Pacific Sports Apparel Market
Apparel & Footwear
Vegan Footwear Market
Apparel & Footwear
South Korea Denim Jeans Market
Apparel & Footwear
Sports Apparel Embellishment Market
Apparel & Footwear
Innerwear Market
Apparel & Footwear
Plus Size Clothing Market
Apparel & Footwear
Global Apparel and Footwear Market
Apparel & Footwear
Golf Apparel Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
Global Women Pajamas Suits Market
Apparel & Footwear
Global Leggings Market
Apparel & Footwear
Chest Bags Market
Apparel & Footwear
Outdoor Jacket Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market