
 Bra Market | 2026-2036
Bra Market Size, Share, and Industry Trends Forecast 2026-2036
Bra Market Analysis
Direct-to-consumer platforms is rewriting how bras reach buyers, bypassing legacy department store networks. Victoria's Secret & Co. leverages its digital storefront to recover share lost to specialty challengers. Hanesbrands Inc. anchors mass-market volume through big-box retail partnerships. Wacoal Holdings Corp. differentiates via precision sizing and Asian market expertise.
A bra is a structured undergarment engineered with engineered fabrics, underwire or wireless support architecture, and adjustable fastening systems to provide breast support, shaping, and comfort across daily and athletic activities. Sports bras incorporate compression or encapsulation engineering with moisture-wicking polyester-spandex blends for high-impact stability. Wireless and bralette segments are capturing margin pools as comfort-first preferences displace traditional push-up demand. Cotton and lace materials split along occasion-based use, with lace dominating premium eveningwear adjacencies and cotton anchoring everyday rotation.
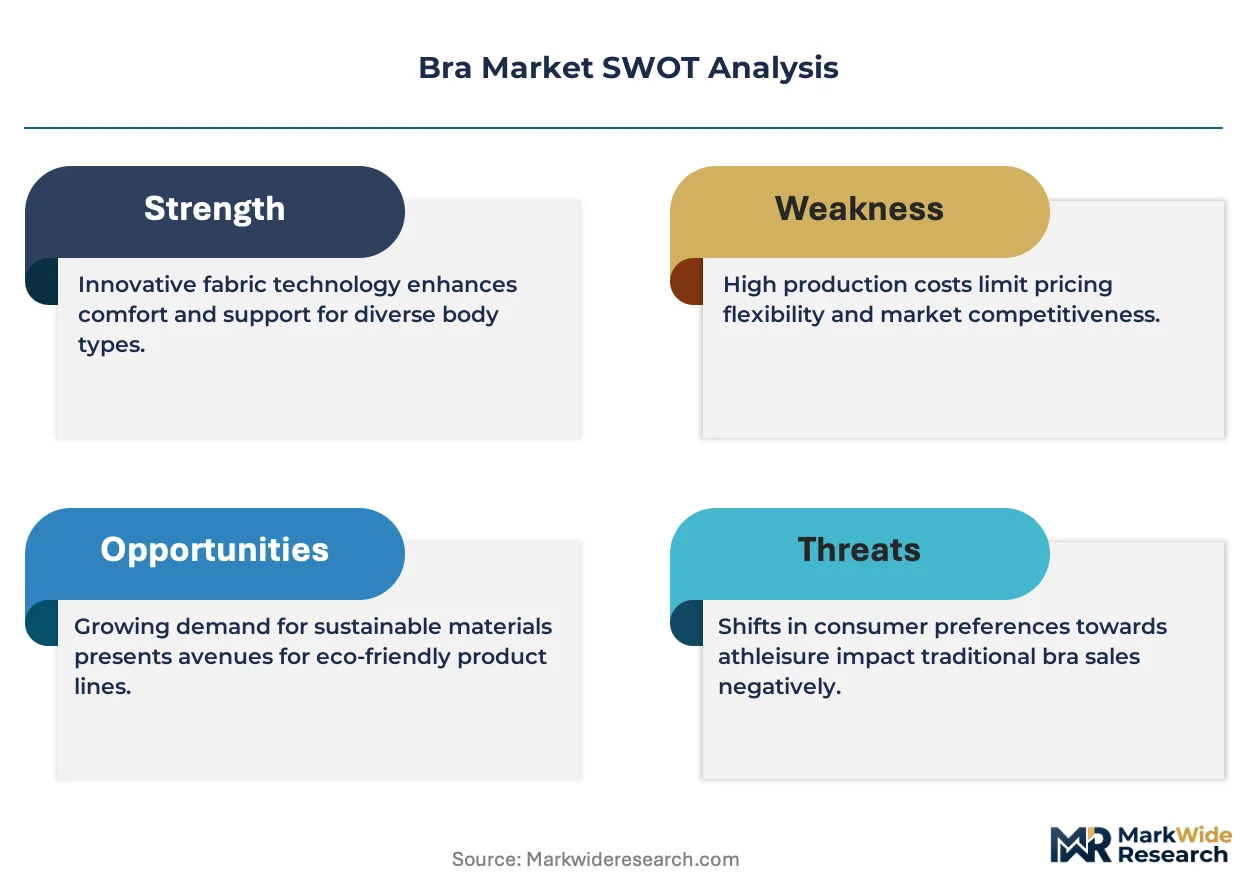
The EU Green Deal and REACH chemical frameworks are restricting hazardous dye substances and mandating recycled content disclosures across European textile imports. The US FTC enforces strict fiber labeling and environmental marketing claims, shaping how brands communicate sustainability to consumers. Stakeholders must monitor evolving chemical compliance thresholds and raw material traceability requirements as regulatory stringency tightens across major demand centers.
Market Dynamics
EU Green Deal chemical restrictions and REACH dye substance bans are forcing bra manufacturers to rebuild supply chains around recycled polyester and bio-based elastane, compressing margins for mid-tier producers unable to absorb reformulation costs.
Growth Catalysts
- Activewear Participation:Fitness participation expansion across North America and Western Europe pulls demand for high-impact sports bras with moisture-wicking performance engineering.
- REACH Chemical Frameworks:European restrictions on hazardous azo dyes and formaldehyde-based finishing agents accelerate adoption of waterless dye technologies and GOTS-certified organic cotton sourcing.
- Domestic Label Scaling:China-based direct-to-consumer brands leverage vertically integrated manufacturing clusters in Guangdong and Zhejiang to compress delivery timelines and undercut legacy import pricing.
Market Restraints
- Elastane Price Volatility:Crude-linked spandex feedstock costs swing with petrochemical indices, squeezing gross margins for wireless and seamless construction categories dependent on high stretch recovery.
- Supply Concentration Risk:Lace and embroidery trim production concentrates in Calais, France and Surat, India, creating single-source vulnerability for premium eveningwear-adjacent bra lines.
- Technical Limitation:Current recycled nylon 6,6 fiber tensile strength falls 12-15% below virgin filament, limiting structural support in underwire channeling and high-compression sports applications.
Strategic Opportunities
- Underpenetrated Geography:India's tier-two and tier-three cities present whitespace for affordable cotton everyday bras as organized retail penetration expands beyond Mumbai and Delhi corridors.
- Regulatory Tailwind:The EU Green Deal's 2030 textile circularity mandate creates first-mover advantage for brands achieving Cradle to Cradle certification and take-back program infrastructure.
- Technology Convergence:3D body scanning and AI-driven fit algorithms converge to reduce return rates for online bra purchases, unlocking direct-to-consumer profitability in previously avoided size ranges.
Industry Challenges
- Technical Talent Scarcity:Apparel engineering programs graduate fewer specialists in intimate apparel pattern-making and graded sizing systems, forcing brands to poach from declining European ateliers.
- Certification Timeline Compression:OEKO-TEX and bluesign audits for new recycled material suppliers stretch 8-14 months, delaying product launches timed to sustainability marketing calendars.
- Legacy System Integration:ERP migration from cut-and-sew job costing modules to unit-level traceability platforms required for Digital Product Passport compliance strains mid-cap IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bra Market |
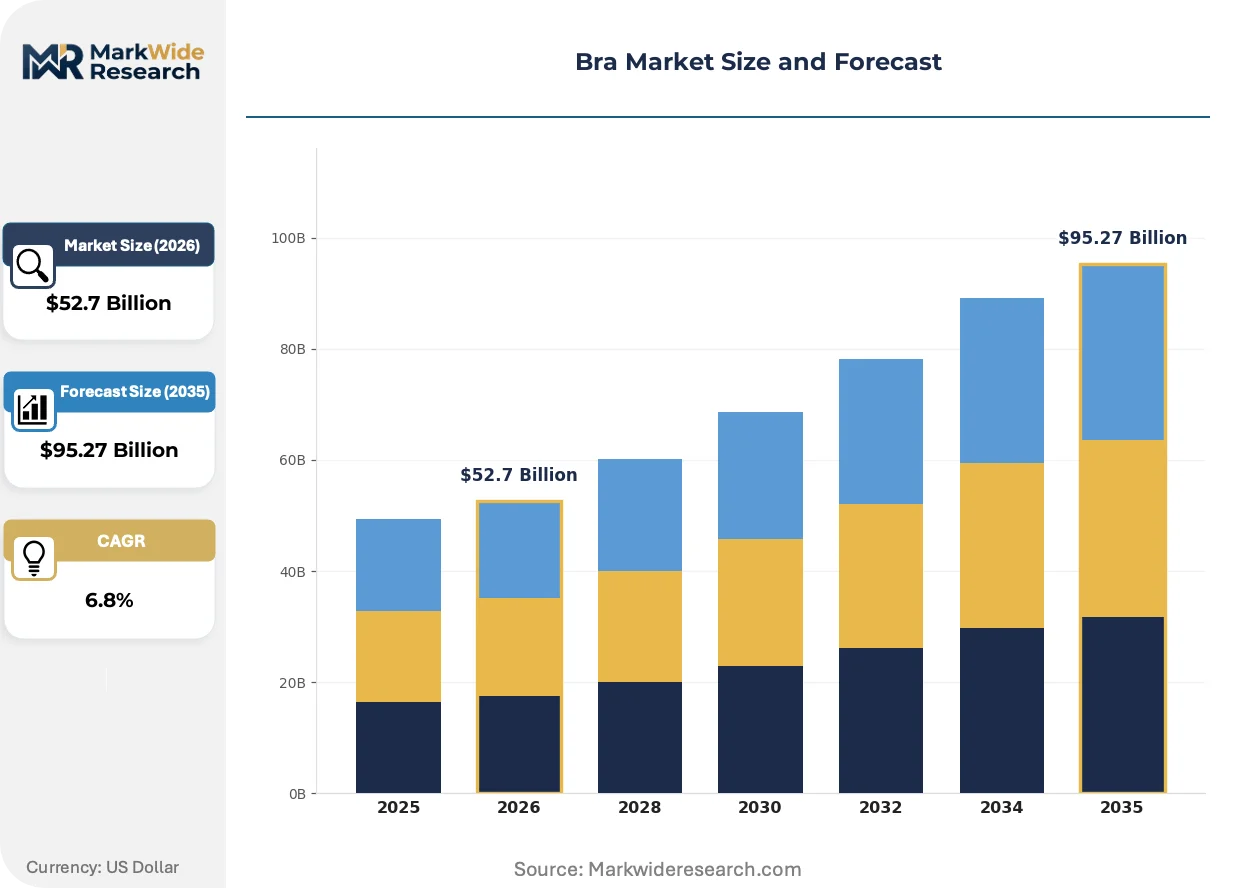
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push-Up, Sports, Bralette, Wireless Material: Cotton, Lace, Polyester, Spandex Size: A Cup, B Cup, C Cup, D Cup End User: Teenagers, Adults, Maternity, Plus Size |
| Companies Covered | Victoria’s Secret & Co., Hanesbrands Inc., PVH Corp., Wacoal Holdings Corp., MAS Holdings Limited, Jockey International Inc., H & M Hennes & Mauritz AB, Triumph Intertrade AG, American Eagle Outfitters Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bra Market Emerging Trajectories
Material science breakthroughs and regulatory disclosure mandates are compressing traditional product development cycles while opening margin pools for transparency-first brands. Three forces now dominate competitive differentiation.
Seamless knitting technology with integrated compression zones eliminates cut-and-sew labor from sports bra production. Performance athletic wear buyers at specialty retailers and boutique fitness studios now specify seamless construction as a baseline requirement. Traditional panel-based assembly with separate cover fabrics and foam lining is rendering obsolete for mid-market activewear lines.
REACH Annex XVII restrictions on NPEOs and PFAS in textile finishing entered full enforcement across EU member states in 2024. Manufacturers must now reformulate water-repellent treatments and dye auxiliaries or face import blockage at Rotterdam and Hamburg ports. Lingerie brands dependent on stain-resistant lace and moisture-management finishes are accelerating substitution to bio-based fluorine-free alternatives.
Subscription-based bra replenishment programs now capture recurring revenue from maternity and nursing segments where size fluctuation drives frequent replacement. Direct-to-consumer platforms displace quarterly department store replenishment orders with algorithm-cued shipment timing. This behavioral shift concentrates most visibly in the United Kingdom and Germany where delivery logistics density supports flexible return windows.
Bra Market Segmentation
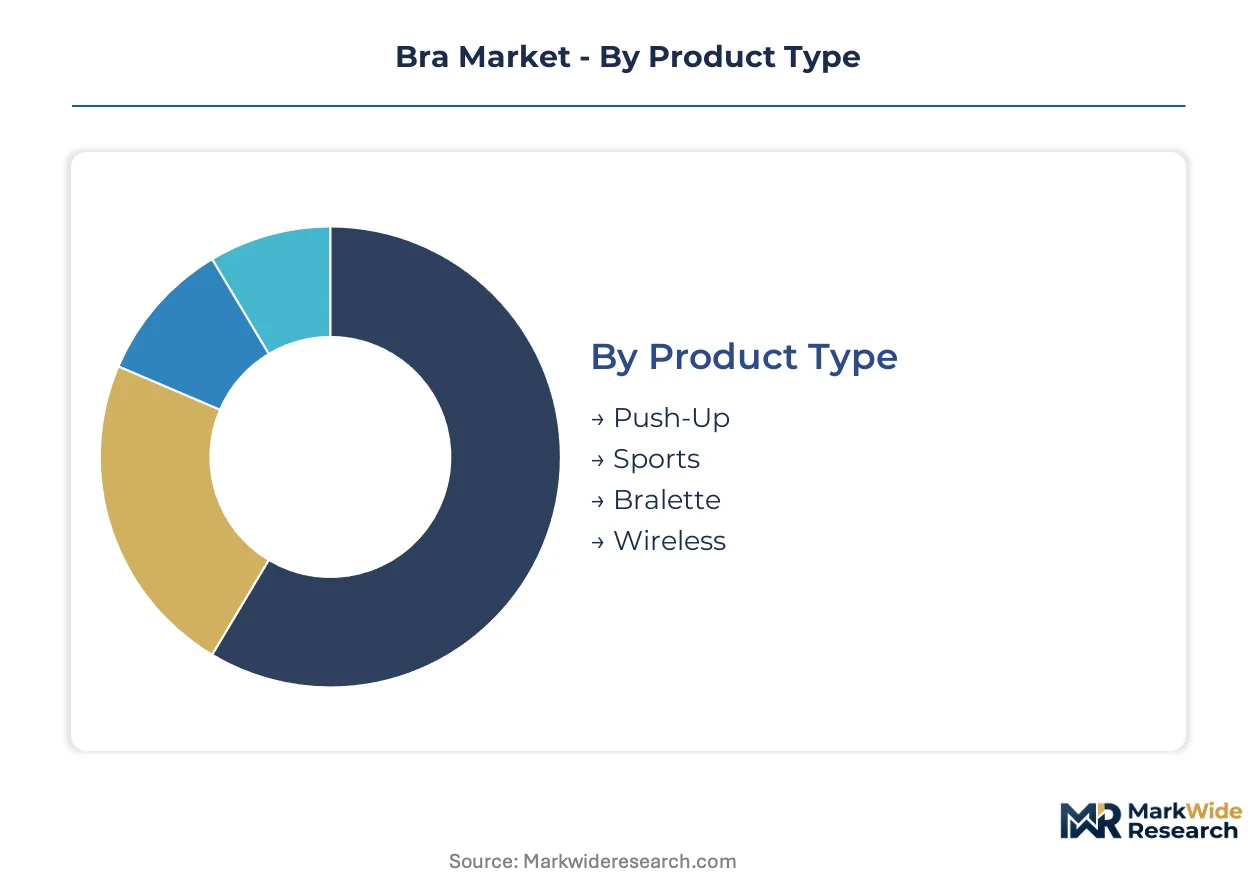
Segmentation in the bra market reveals divergent margin structures and inventory velocity patterns. Product type and material composition dictate manufacturing complexity, while size distribution and end-user demographics shape channel strategy and marketing spend allocation.
Product Type:
Replacement cycles vary dramatically across construction architectures, with athletic and comfort-first formats turning inventory faster than structured eveningwear alternatives.
- Sports:Compression and encapsulation engineering with moisture-wicking polyester-spandex blends handles high-impact stability for running and cross-training. Demand concentrates in North American specialty athletic retailers as boutique fitness studio participation broadens beyond coastal metros.
- Wireless:Eliminated underwire architecture relies on engineered knit zones and wide bottom bands for distributed support. Expansion concentrates in direct-to-consumer channels where comfort-first preferences displace traditional push-up demand among millennial and Gen Z cohorts.
- Push-Up:Structured padding and underwire channeling create cleavage enhancement for eveningwear adjacencies. Mature demand in European department store networks faces compression from casualization trends.
- Bralette:Unlined, wire-free soft cups with minimal support structure serve lounge and sleep-to-street occasions. Fastest inventory turns in Asian e-commerce markets where layering culture drives frequent replacement.
Wireless dominates installed base growth in direct-to-consumer channels. Sports is where expansion concentrates most steeply.
Material:
Raw material selection determines regulatory compliance burden and end-use positioning across occasion-based use cases.
- Polyester:Petroleum-derived filament with superior dimensional stability and dye affinity anchors sports bra production. REACH Annex XVII restrictions on hazardous dye substances are forcing reformulation toward GRS-certified recycled variants in EU-bound supply chains.
- Spandex:Polyurethane-based elastane delivers stretch recovery essential for seamless construction and high-compression athletic applications. Price volatility tied to crude-linked feedstock costs squeezes margins for wireless and seamless categories.
- Cotton:Natural cellulose fiber with breathability properties dominates everyday rotation and sleepwear adjacencies. Indian domestic labels source from Gujarat and Maharashtra spinning clusters to serve price-sensitive tier-two city demand.
- Lace:Delicate openwork fabric from nylon or cotton base yarns commands premium positioning in eveningwear and bridal segments. Production concentrates in Calais, France and Surat, India, creating single-source vulnerability for luxury lines.
Polyester commands volume leadership in athletic applications. Spandex is climbing fastest as seamless construction penetrates mid-market lines.
Size:
Pattern grading complexity and fit algorithm development intensity scale with cup volume, fragmenting manufacturing economics.
- C Cup:Mid-volume breast tissue requiring moderate support structure represents the historical mass-market sweet spot. Highest SKU proliferation in legacy department store assortments.
- D Cup:Heavier tissue mass demands reinforced underwire channeling, wider straps, and engineered lift mechanics. 3D body scanning and AI-driven fit algorithms are reducing return rates for online purchases in this previously avoided range.
- B Cup:Moderate volume with broad styling flexibility supports fashion-forward experimentation and seasonal trend responsiveness. Fastest inventory velocity in fast-fashion retail partnerships.
- A Cup:Minimal support requirements enable lightweight construction and bralette format dominance. Concentrated demand in Asian markets where smaller average cup sizes align with domestic label specialization.
C Cup dominates installed base across legacy retail networks. D Cup is where expansion concentrates as inclusive sizing mandates reshape assortment planning.
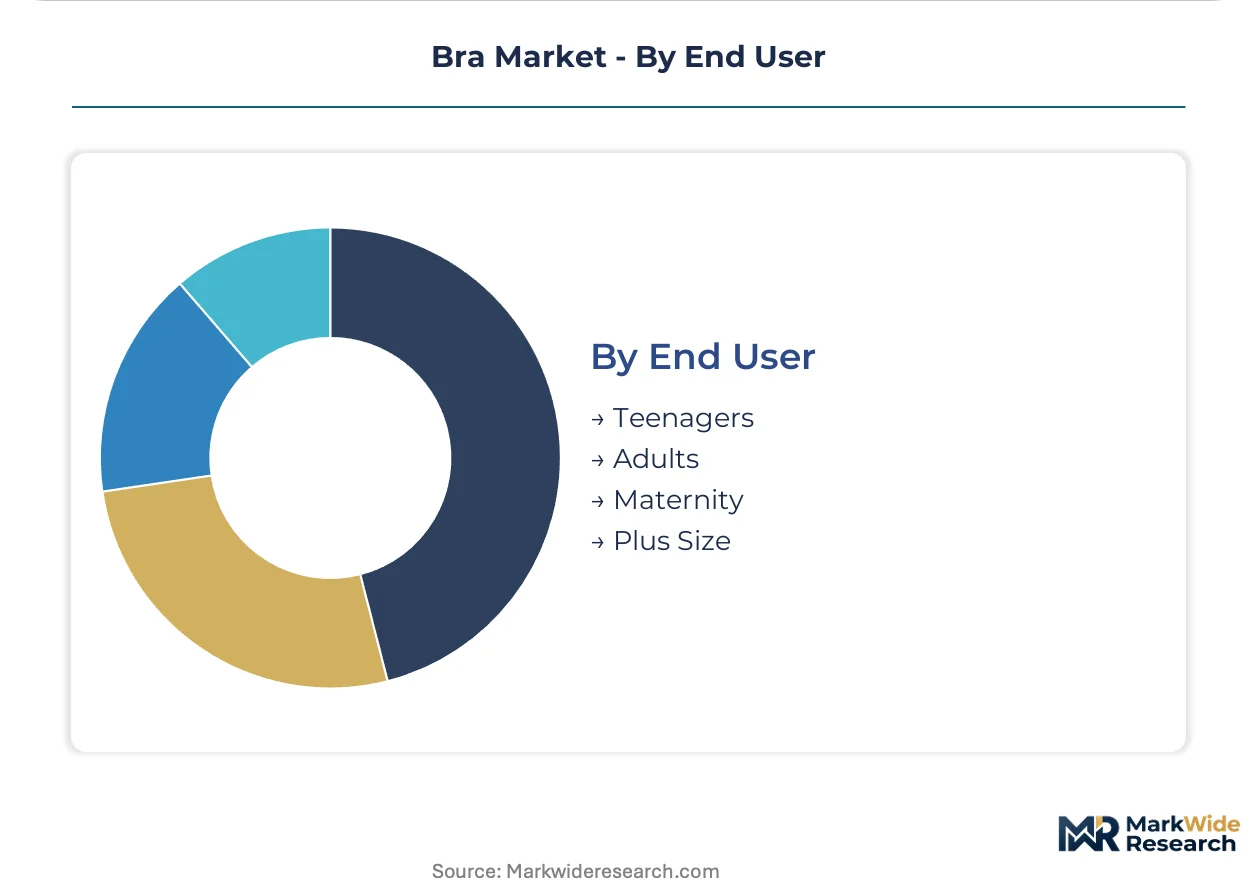
End User:
Life stage and body morphology dictate replacement frequency, price elasticity, and channel preference with minimal overlap between segments.
- Adults:Core demographic with stable size profiles and established brand loyalties drives replenishment economics. Subscription-based bra programs now capture recurring revenue through algorithm-cued shipment timing in UK and German markets.
- Maternity:Fluctuating band and cup dimensions through pregnancy and nursing phases create frequent replacement cycles. Specialized nursing clasp engineering and moisture-wicking linings command price premiums in direct-to-consumer platforms.
- Teenagers:First-bra purchase occasions and rapid growth phases drive trial-oriented pricing and educational marketing investments. Social media discovery patterns concentrate demand on TikTok-native direct-to-consumer brands.
- Plus Size:Extended band and cup range requirements strain legacy grading systems and force dedicated pattern development. Underpenetrated whitespace exists as mid-tier producers avoid the technical investment.
Adults dominate installed base and revenue concentration. Maternity is gaining share fastest through subscription model penetration and size-fluctuation-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors European regulatory pressure, while manufacturing gravity concentrates in Asian textile clusters and North American demand pulls premium innovation.
United States
Specialty athletic retailers and boutique fitness studios drive sports bra demand as boutique studio participation broadens beyond coastal metros. The FTC enforces strict fiber labeling and environmental marketing claims, shaping how brands communicate sustainability. Los Angeles and New York City host emerging direct-to-consumer headquarters where 3D body scanning firms cluster near venture capital.
China
Domestic direct-to-consumer brands leverage vertically integrated manufacturing in Guangdong and Zhejiang to compress delivery timelines. The country's dual carbon goals push textile producers toward renewable energy in dyeing operations. The Pearl River Delta anchors export manufacturing scale while Shanghai-based labels capture premium domestic demand.
Germany
Subscription-based bra replenishment programs capture recurring revenue through algorithm-cued shipment timing. REACH Annex XVII restrictions on NPEOs and PFAS entered full enforcement in 2024, forcing reformulation of water-repellent treatments. Berlin and Hamburg host logistics density supporting flexible return windows for online bra purchases.
India
Tier-two and tier-three cities present whitespace for affordable cotton everyday bras as organized retail penetration expands beyond Mumbai and Delhi. The Bureau of Indian Standards governs textile quality and safety labeling for domestic circulation. Gujarat and Maharashtra spinning clusters supply domestic labels serving price-sensitive demand.
United Kingdom
Direct-to-consumer platforms displace quarterly department store replenishment orders with flexible delivery logistics. The UK's post-Brexit regulatory framework maintains REACH-aligned chemical restrictions on textile imports. London concentrates marketing and e-commerce headquarters for European market entry.
Bra Market Vendor Landscape
Heritage lingerie houses and mass-market apparel conglomerates split the market between premium positioning and volume scale. The vendor base arranges across three tiers: vertically integrated Asian manufacturers, North American direct-to-consumer specialists, and European heritage brands with atelier legacy. Dominant competitive moves include backward integration into textile production and AI-driven fit algorithm licensing.
Within the heritage tier, Victoria's Secret & Co. and Triumph Intertrade AG exemplify established retail network leverage, while Wacoal Holdings Corp. occupies a precision-sizing position anchored in Asian market expertise. These entities represent contrasting geographic origins and structural approaches to intimate apparel manufacturing and distribution.
| Leading Market Players |
|---|
| Victoria's Secret & Co. |
| Hanesbrands Inc. |
| PVH Corp. |
| Wacoal Holdings Corp. |
| MAS Holdings Limited |
| Jockey International Inc. |
| H & M Hennes & Mauritz AB |
| Triumph Intertrade AG |
| American Eagle Outfitters Inc. |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII dye restrictions function as a regulatory chokepoint that widens the pricing spread between certified and uncertified supply tiers while forcing consolidation around compliant manufacturing clusters in Portugal and Turkey. This chemical compliance barrier simultaneously compresses margins for mid-tier producers and rewards brands with captive GOTS-certified organic cotton sourcing.
Pricing Analysis
The customization-premium spread separates standard wireless bras from precision-sized D-cup configurations with 3D-scan fit algorithms. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and vertical integration depth. Price erosion runs through mass-market polyester-spandex blends as Guangdong manufacturers compress delivery timelines. Teenage and first-bra buyers exhibit highest price sensitivity, while maternity subscription segments accept recurring premiums for algorithm-cued replenishment timing.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate supplier-financing arrangements as brands conserve working capital for ERP migration to Digital Product Passport compliance. Manufacturing concentrates in China, Vietnam, and Bangladesh, with lace and embroidery trim drawing from single-source Calais and Surat ateliers. Tariff exposure on EU-bound recycled polyester shipments creates inventory positioning risk. Distribution runs through direct-to-consumer platforms displacing legacy department store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around direct-to-consumer platforms and subscription algorithms, fragmenting traditional wholesale pricing power that department store networks once commanded.
For Market Incumbents: Insulate core sizing expertise by acquiring 3D body scanning firms clustered near Los Angeles and New York City venture capital. Backward integration into GRS-certified recycled polyester production counters REACH-driven margin compression from reformulation costs. Channel control through proprietary fit algorithms reduces return rates in the D-cup expansion segment where technical investment barriers deter mid-tier competitors. For New Entrants and Emerging Players: India's tier-two and tier-three cities present whitespace for affordable cotton everyday bras as organized retail penetration expands beyond Mumbai and Delhi corridors. Gujarat and Maharashtra spinning clusters enable price positioning 20-30% below import alternatives. A direct-to-consumer launch with TikTok-native discovery patterns captures teenage first-bra purchase occasions before brand loyalties solidify. For Investors and Strategic Acquirers: The EU Green Deal's 2030 textile circularity mandate reshapes the acquisition landscape toward Cradle to Cradle-certified producers with operational take-back program infrastructure. Five-to-ten-year viability favors vertically integrated Asian manufacturers with captive dyeing capacity and renewable energy sourcing. The signal to monitor is OEKO-TEX and bluesign audit timeline compression, as 8-14 month certification delays strain sustainability marketing calendars and create distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Bypasses legacy department store networks where Victoria's Secret & Co. and Hanesbrands Inc. anchor shelf presence. |
| 3D Body Scanning Integration | Reduces return rates for online bra purchases in D-cup and plus-size ranges previously avoided by algorithm-deficient competitors. |
| GRS-Certified Recycled Polyester Sourcing | Satisfies REACH Annex XVII restrictions on hazardous dye substances across EU-bound supply chains. |
| Subscription Replenishment Program | Captures recurring revenue from maternity and nursing segments where size fluctuation drives frequent replacement cycles. |
| Cradle to Cradle Certification Investment | Creates first-mover positioning for EU Green Deal's 2030 textile circularity mandate and Digital Product Passport compliance. |
Methodological Framework
A spread of perspectives from intimate apparel brand managers, category buyers at specialty athletic retailers, supply planners at vertically integrated manufacturers, and technical R&D directors at textile mills converged on the working assumptions. Primary interviews combined with secondary validation from SEC 10-K filings, customs and trade data, and OEKO-TEX certification registries. Bottom-up SKU-level demand modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Demand-supply-balance framing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material composition, cup size distribution, and end-user life stage. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Sports bra moisture-wicking performance engineering and wireless construction penetration served as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by algorithm-native direct-to-consumer entrants or state-subsidized Chinese domestic labels would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Surfing Apparel and Accessory Market
Apparel & Footwear
Thimbles Market
Apparel & Footwear
Ethnic Wear Market
Apparel & Footwear
South Korea Denim Jeans Market
Apparel & Footwear
Global Apparel Market
Apparel & Footwear
Ice Hockey Apparel Market
Apparel & Footwear
Women's Socks Market
Apparel & Footwear
Children's Suits and Ensembles Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
Secondhand Apparel Market
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Alpaca Apparel and Accessories Market
Apparel & Footwear
Outdoor Jacket Market
Apparel & Footwear
Women's Coats and Jackets Market