
 Global Apparel Market | 2026-2036
Global Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Apparel Market Analysis
The premium-commodity split in apparel is recalibrating around speed, traceability, and material provenance rather than price alone. Nike leverages vertical integration in performance footwear to control innovation cycles and margin capture. Inditex sustains its fast-fashion dominance through hyper-responsive supply chains that compress design-to-rack timelines. Shein competes on algorithm-driven demand forecasting that minimizes inventory risk in trend-driven categories.
Apparel encompasses garments constructed from woven, knitted, or non-woven textiles through processes including cut-and-sew assembly, seamless knitting, and bonded construction, serving functional, aesthetic, and identity-expression purposes across consumer and professional contexts. Activewear and outerwear command expanding margin pools as technical fabric blends and climate-adaptive designs justify premium positioning. Online retail channels are displacing department stores in volume growth, though specialty stores retain loyalty in luxury leather and wool segments where tactile validation drives purchase confidence.
The EU Green Deal and REACH chemical standards are tightening fiber sourcing and dyeing process requirements across export-oriented manufacturing bases, while China's GB standards and dual carbon goals are forcing domestic mills to retool energy-intensive production lines. Stakeholders must monitor how regulatory fragmentation between European environmental mandates and Asian industrial policy reshapes supplier qualification costs and geographic sourcing decisions.
Market Dynamics
Digital textile printing and on-demand manufacturing are compressing design-to-delivery cycles from months to days, forcing legacy cut-and-sew operations to retool or exit as speed becomes the primary competitive vector.
Growth Catalysts
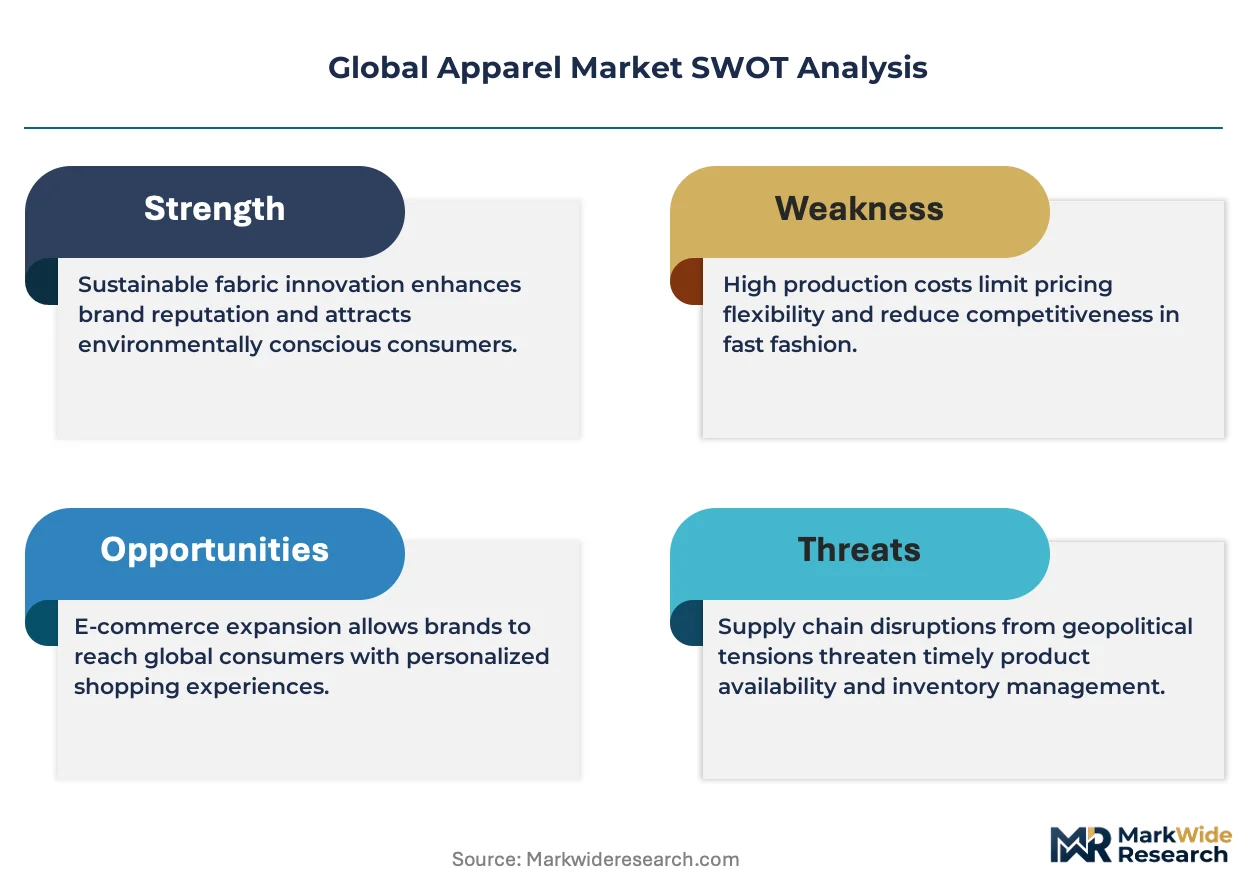
- EU Green Deal chemical standards:REACH-compliant dyeing processes are accelerating adoption of waterless coloration technologies across export-oriented mills in Bangladesh and Vietnam, creating qualification premiums for compliant suppliers.
- Health-conscious millennial demand:Technical fabric blends in activewear categories are commanding margin expansion as consumers prioritize performance attributes over brand heritage in purchase decisions.
- China's domestic manufacturing clusters:Vertical integration from fiber spinning to finished garment in Zhejiang and Guangdong provinces is reducing lead times for global fast-fashion fulfillment.
Market Restraints
- Cotton price volatility:Input cost swings tied to Texas and India harvest cycles are eroding margin predictability for mid-tier woven garment producers lacking forward-contract coverage.
- Polyester supply concentration:PTA and MEG feedstock dependence on Zhejiang and Jiangsu petrochemical complexes creates geographic single-point vulnerability for synthetic apparel supply chains.
- Technical limitation in biodegradable elastane:Spandex alternatives lacking equivalent recovery and durability are constraining sustainable activewear formulation options.
Strategic Opportunities
- India's PLI scheme for textiles:Production-linked incentives for man-made fiber apparel are attracting capacity relocation from cost-pressured Chinese competitors.
- AI-driven demand forecasting:Algorithmic pattern recognition is enabling micro-batch production that minimizes inventory risk in trend-driven categories.
- Secondhand platform infrastructure:Resale channel integration offers margin recovery from post-consumer garments while addressing waste reduction mandates.
Industry Challenges
- Digital pattern-making skill scarcity:3D prototyping and virtual sampling expertise shortages are slowing adoption of zero-waste design workflows among established manufacturers.
- Multi-standard certification timelines:Simultaneous pursuit of OEKO-TEX, GOTS, and ZDHC compliance is extending supplier qualification periods and delaying commercialization.
- Legacy ERP integration friction:Real-time inventory visibility systems are encountering data architecture conflicts with decades-old textile mill management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Apparel Market |
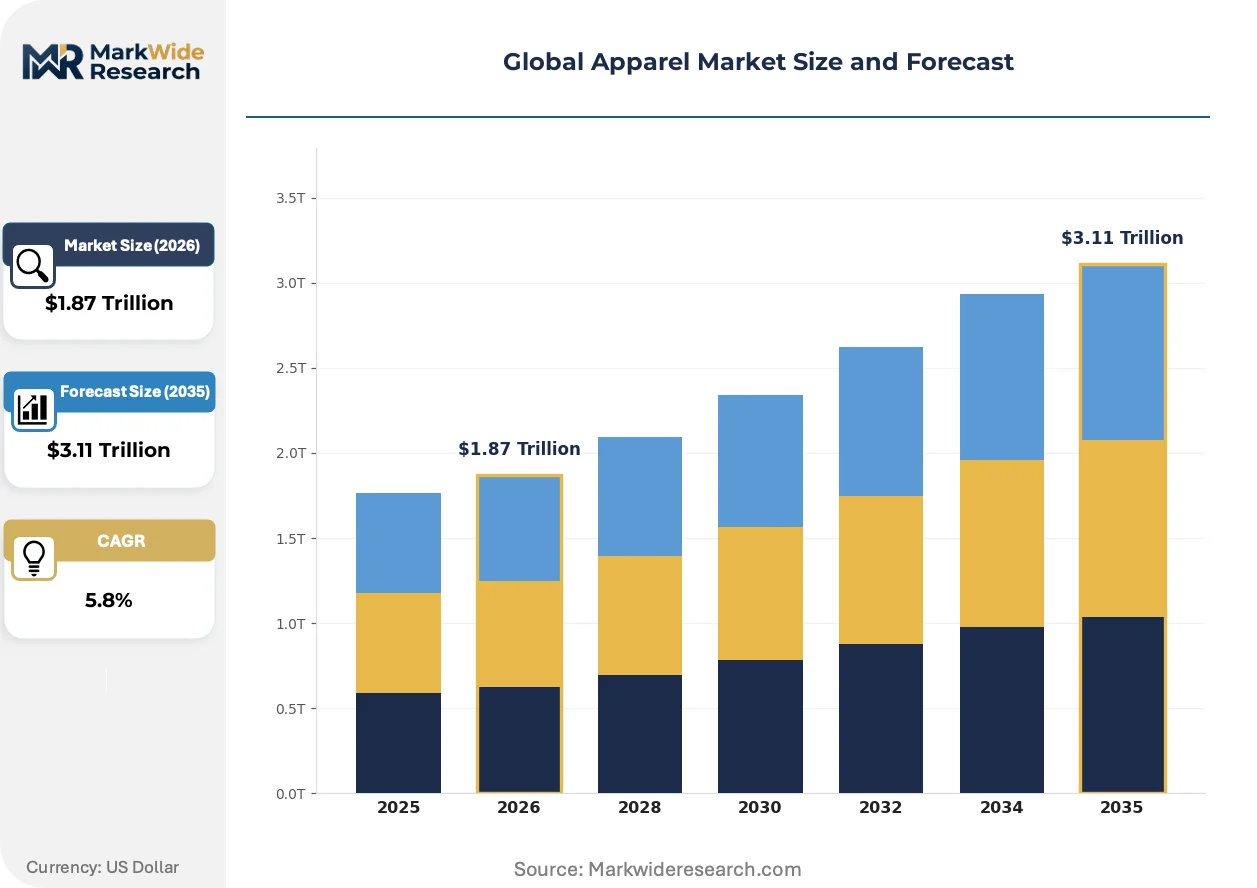
| Market Size in 2026 | $1.87 Trillion |
| Market Size in 2035 | $3.11 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tops, Bottoms, Outerwear, Activewear Consumer Segment: Men, Women, Children, Infants Distribution Channel: Online Retail, Department Stores, Specialty Stores, Discount Stores Material Type: Cotton, Polyester, Wool, Leather |
| Companies Covered | Nike, Inditex, Adidas, LVMH, H&M Hennes & Mauritz, Fast Retailing, Shein, Hermès, TJX Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Apparel Market Emerging Trajectories
Automation is penetrating previously manual garment finishing stages while regulatory pressure on chemical inputs accelerates material science investment. These forces are converging to redefine speed-to-market and environmental accountability as inseparable competitive dimensions.
Digital textile printing is rewriting production economics by eliminating screen-making setup costs and enabling single-unit color customization. Athletic and luxury streetwear brands are adopting this capability at scale, compressing sampling cycles from weeks to hours and enabling geographically distributed micro-factories that serve local demand without inventory risk.
REACH chemical restrictions and China's GB standards on wastewater discharge are forcing dyehouses to invest in closed-loop water systems and bio-based colorants. The industrial consequence is supplier consolidation as smaller facilities lack capital for compliance infrastructure. European outerwear and swimwear categories are most affected, with brands accelerating supplier audits and shortening approved vendor lists.
Direct-to-consumer channel expansion is displacing traditional wholesale relationships as primary revenue drivers for emerging apparel labels. Specialty e-commerce platforms and social commerce integration are replacing department store floor space as the critical discovery mechanism. This shift is most visible in China's domestic market, where live-streaming commerce now captures significant volume in casual and occasion-wear segments previously dominated by mall-based retail.
Global Apparel Market Segmentation
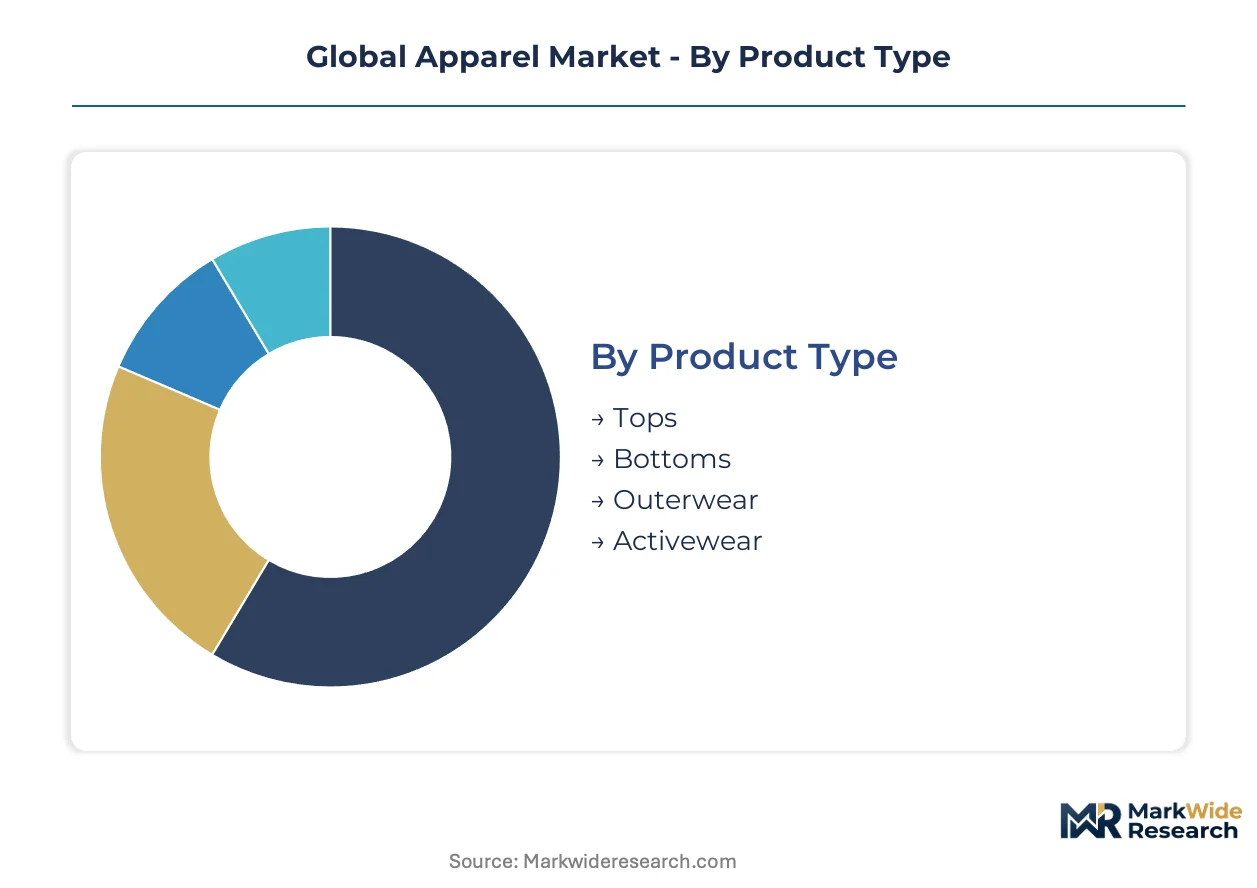
Segmentation in apparel reveals how capital allocation, regulatory exposure, and channel economics split value capture across the value chain. Technical fabric development and compliance infrastructure now drive investment decisions more than scale alone.
Product Type:
Capital intensity varies sharply across garment categories, with technical outerwear and performance activewear requiring specialized bonding equipment and climate-testing facilities that woven tops and basic bottoms do not demand.
- Activewear:Compression fabrics and moisture-wicking synthetic blends incorporate elastane recovery systems and flatlock seam construction. Demand concentrates in China's domestic market where health-conscious millennials prioritize performance attributes over brand heritage, though biodegradable elastane alternatives still lack equivalent durability.
- Outerwear:Laminated membranes and bonded construction methods for waterproof-breathable performance require cleanroom finishing environments and chemical compliance certification. European demand under REACH standards is accelerating supplier consolidation as smaller dyehouses lack capital for closed-loop water systems.
- Tops:Cut-and-sew assembly of woven and knit upper-body garments dominates volume production in Bangladesh and Vietnam, with digital textile printing enabling single-unit color customization that compresses sampling cycles.
- Bottoms:Denim and casual trouser categories face cotton price volatility tied to Texas and India harvest cycles, eroding margin predictability for mid-tier producers lacking forward-contract coverage.
Most installed capacity flows through Tops. Expansion is steepest in Activewear.
Consumer Segment:
Margin structure follows purchasing frequency and size-standardization economics, with women's fast-fashion cycling fastest and children's wear facing the strictest chemical safety compliance burdens.
- Women:Trend-driven purchase patterns with higher unit velocity support algorithmic demand forecasting and micro-batch production models. Shein's algorithm-driven forecasting minimizes inventory risk in this segment.
- Men:Longer replacement cycles and size standardization enable pre-positioned inventory models, with performance categories capturing margin expansion through technical fabric blends.
- Children:OEKO-TEX and GOTS certification requirements extend supplier qualification timelines, with safety standards tightening across EU and Chinese domestic markets.
- Infants:Ultra-soft natural fiber requirements and stringent chemical safety protocols limit viable supplier pools, concentrating production in vertically integrated mills with captive dyeing capacity.
Volume concentration sits with Women. Margin expansion is most pronounced in Infants due to compliance barriers.
Distribution Channel:
Channel economics are inverting as inventory risk transfers from retailer to brand, with digital-native labels capturing customer data that department store wholesale relationships never yielded.
- Online Retail:Direct-to-consumer platforms displace traditional wholesale as primary revenue drivers, with live-streaming commerce in China capturing significant volume in casual and occasion-wear segments.
- Specialty Stores:Tactile validation drives purchase confidence in luxury leather and wool segments, with curated assortment justifying premium positioning through service intensity.
- Department Stores:Foot traffic erosion and inventory risk transfer to vendors are compressing margins, with floor space reductions accelerating across North American and European markets.
- Discount Stores:Price-driven volume competes on sourcing efficiency and basic quality thresholds, with polyester-heavy assortments vulnerable to Zhejiang petrochemical complex supply concentration.
Revenue gravity is shifting toward Online Retail. Physical channel investment now concentrates in Specialty Stores.
Material Type:
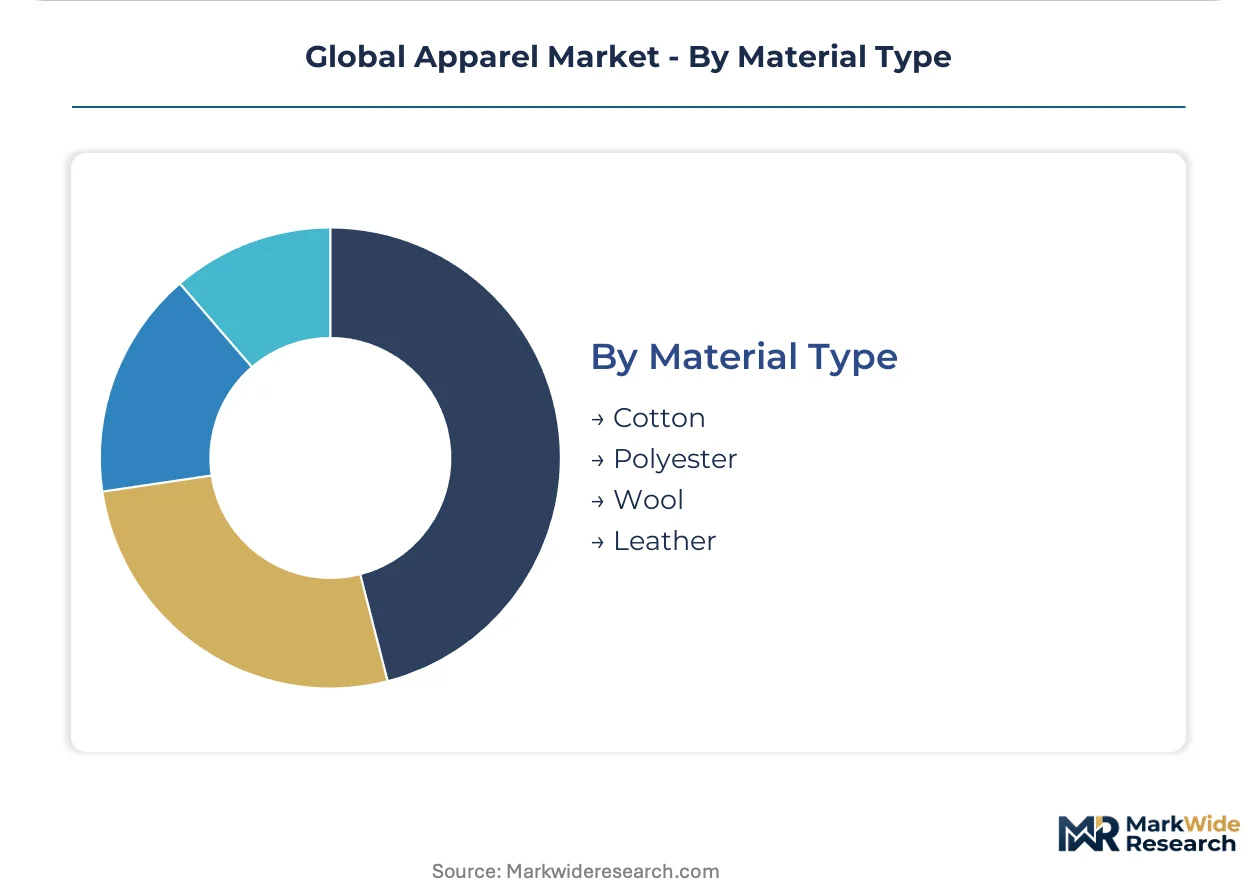
Feedstock geography and regulatory compliance cost determine supplier viability, with natural fibers facing climate volatility and synthetics confronting environmental policy pressure.
- Polyester:PTA and MEG feedstock dependence on Zhejiang and Jiangsu petrochemical complexes creates geographic single-point vulnerability. Recycled PET capacity expansion is accelerating under EU Green Deal pressure.
- Cotton:Natural fiber price swings tied to Texas and India harvest cycles require forward-contract coverage for margin predictability, with organic premiums commanding qualification premiums in European markets.
- Wool:Specialty store distribution retains loyalty where tactile validation drives purchase confidence, with merino technical blends expanding into activewear categories.
- Leather:REACH chemical restrictions and wastewater discharge standards under China's GB regulations are forcing tannery consolidation, with smaller facilities lacking capital for compliance infrastructure.
Volume leadership belongs to Polyester. Fastest share gains are occurring in Cotton as sustainability positioning intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands domestic manufacturing clusters that compress lead times for global fulfillment, while Bangladesh and Vietnam compete for export-oriented cut-and-sew volume under tightening EU chemical standards. Divergent regulatory pressures across these three production hubs are redrawing supplier qualification costs and geographic sourcing decisions.
China
Health-conscious millennials in tier-one cities drive activewear demand toward technical fabric blends. GB standards and dual carbon goals under MEE oversight are forcing Zhejiang and Guangdong mills to retool energy-intensive production lines. Vertical integration from fiber spinning to finished garment in these provinces reduces lead times for fast-fashion fulfillment.
United States
Direct-to-consumer channel expansion displaces department store wholesale relationships for emerging labels. EPA and FTC oversight shapes chemical disclosure requirements for imported textiles. Cotton price volatility tied to Texas harvest cycles erodes margin predictability for mid-tier woven garment producers lacking forward-contract coverage.
Germany
REACH-compliant dyeing processes accelerate adoption of waterless coloration technologies across supplier bases. ECHA chemical restrictions force dyehouse consolidation as smaller facilities lack capital for closed-loop water systems. The country's technical outerwear brands concentrate supplier audits and shorten approved vendor lists.
Vietnam
Export-oriented mills adopt waterless coloration technologies to meet EU Green Deal qualification premiums. The country's man-made fiber apparel sector attracts investment under cost pressures from Chinese competitors. Manufacturing clusters near Ho Chi Minh City and Hanoi serve fast-fashion fulfillment with compressed design-to-rack timelines.
India
Production-linked incentives for man-made fiber apparel under the PLI scheme attract capacity relocation from Chinese competitors. BIS standards and DGFT trade policies shape fiber sourcing requirements. Textile manufacturing concentrates in Gujarat and Tamil Nadu, where integrated mills from fiber to garment capture growing domestic and export demand.
Global Apparel Market Vendor Landscape
Top-tier vendors anchor premium performance and luxury positioning, while mid-tier fast-fashion operators compete on algorithmic demand forecasting and hyper-responsive supply chains. The vendor base stratifies across three archetypes: vertically integrated innovators controlling innovation cycles, speed-focused fast-fashion platforms minimizing inventory risk, and heritage luxury houses commanding tactile validation channels. Consolidation pressure favors M&A activity among mid-tier woven garment producers, while capacity expansion concentrates in India's PLI-attracted clusters and China's domestic manufacturing bases.
Within the vertically integrated tier, Nike and Inditex occupy positions that exemplify divergent speed-to-market strategies. Nike represents the performance-footwear archetype where backward integration into technical fabric development controls margin capture. Inditex anchors the fast-fashion vector through hyper-responsive supply chain architecture. Among algorithm-driven platforms, Shein exemplifies demand-forecasting capabilities that compress design-to-delivery cycles and minimize inventory exposure in trend-driven categories.
| Leading Market Players |
|---|
| Nike |
| Inditex |
| Adidas |
| LVMH |
| H&M Hennes & Mauritz |
| Fast Retailing |
| Shein |
| Hermès |
| TJX Companies |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in Bangladesh and Vietnam, rolled up under state-supported textile park schemes, enforce volume discipline through export quota allocations that insulate pricing from spot-market cotton swings. Family-owned mid-caps in Gujarat and Tamil Nadu absorb margin compression through captive spinning capacity, passing through polyester feedstock cost volatility only at contract renewal points.
Pricing Analysis
Design-to-delivery service bundling separates full-package vendors commanding technical development premiums from cut-and-sew contractors competing on unit labor rates. Pricing stratifies across premium certified tiers, standard compliance grades, and economy spot-market sourcing based on OEKO-TEX and ZDHC certification levels. Price erosion runs through mid-tier woven garment producers as algorithmic forecasting compresses markup windows for trend-driven categories. Fast-fashion retailers exhibit highest price sensitivity, while performance activewear brands accept premium positioning for proprietary fabric blends.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Los Angeles anchor hub-and-spoke patterns that compress last-mile delivery for direct-to-consumer channels. Manufacturing concentrates in Bangladesh, Vietnam, and China, with India's PLI-attracted clusters expanding synthetic fiber capacity. Raw material flows draw from Zhejiang petrochemical complexes for polyester, Texas and India harvest cycles for cotton, and Australian merino stations for technical wool blends. Single-source vulnerability sits with Zhejiang PTA and MEG feedstock concentration. Distribution runs through vertically integrated brand-controlled networks and third-party logistics platforms serving marketplace sellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Apparel Market functions as a regulatory compounder where EU Green Deal chemical standards and China's dual carbon goals force sustained capital redeployment into compliance infrastructure, creating durable demand for certified suppliers.
For Market Incumbents: Lock in supplier audit consolidation by shortening approved vendor lists ahead of REACH enforcement waves, and accelerate backward integration into waterless coloration technologies before qualification premiums widen. Algorithm-driven entrants threaten inventory-turn advantages unless legacy players capture real-time demand data through direct-to-consumer channel control. For New Entrants and Emerging Players: India's PLI scheme for man-made fiber apparel opens a window for capacity positioning outside cost-pressured Chinese manufacturing clusters. Target technical outerwear segments where laminated membrane expertise and cleanroom finishing requirements limit viable competitor pools. Launch through specialty e-commerce platforms with live-streaming commerce integration to bypass department store gatekeepers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier woven garment producers facing cotton price volatility without forward-contract coverage, presenting consolidation targets for vertically integrated acquirers. Long-term viability favors suppliers with captive dyeing capacity and multi-standard certification infrastructure. Watch India's BIS standard enforcement as an inflection signal for domestic market access barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Waterless Coloration Technology Adoption | REACH-compliant dyeing processes in Bangladesh and Vietnam capture EU Green Deal qualification premiums. |
| Direct-to-Consumer Channel Expansion | Live-streaming commerce in China displaces mall-based discovery for casual and occasion-wear segments. |
| Backward Integration into Technical Fabrics | Proprietary compression and moisture-wicking blends defend margin capture in performance activewear. |
| Micro-Batch Production Infrastructure | AI-driven demand forecasting minimizes inventory risk in trend-driven women's fast-fashion categories. |
| Secondhand Platform Integration | Resale channel infrastructure recovers margins from post-consumer garments while meeting waste reduction mandates. |
Methodological Framework
Direct dialogue with brand supply chain directors, textile mill operations managers, dyehouse compliance officers, and specialty retail category buyers grounds qualitative assessment in operational reality. Secondary validation draws from customs and trade data, SEC 10-K filings of listed apparel companies, OEKO-TEX and GOTS certification registries, and EU ECHA restriction proposal documentation. Bottom-up and top-down triangulation reconciles production capacity surveys with consumer expenditure tracking across distribution channels.
Bottom-up modeling builds from fiber input costs, conversion rates, and finished garment pricing across product type, material composition, and channel economics segments. Top-down validation cross-references national textile output statistics and regional import flow data. CAGRs derive from trend extrapolation of activewear adoption rates, digital textile printing penetration, and regulatory compliance cost trajectories. The projection horizon incorporates EU Green Deal implementation phases and China's dual carbon goal milestones as structural inflection points.
Revisions become necessary when regulatory enforcement timelines accelerate, petrochemical feedstock disruptions materialize, or biodegradable elastane breakthroughs alter sustainable activewear formulation economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Apparel Dry Wash Spray Market
Apparel & Footwear
Men's Coats and Jackets Market
Apparel & Footwear
Designer Sneaker Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
Golf Apparel Market
Apparel & Footwear
Women's Trousers Market
Apparel & Footwear
Yoga Clothing Market
Apparel & Footwear
Sports Inspired Clothing Market
Apparel & Footwear
Press-To-Close Zippers Market
Apparel & Footwear
Fast Fashion Market
Apparel & Footwear
Apparel and Leather Products Market
Apparel & Footwear
Sequins Apparels Market
Apparel & Footwear
Women's Suits and Ensembles Market
Apparel & Footwear
Chest Bags Market