
 Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market | 2026-2036
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market Size, Share, and Industry Trends Forecast 2026-2036
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market Insights
Vietnamese and Indonesian apparel manufacturing clusters are pivoting toward specialized sportswear production lines to serve premium brand contracts. Nike, Inc. leverages vertical integration across design and retail channels to maintain margin control in tennis footwear. Adidas AG anchors its golf apparel strength through partnerships with professional tour players and controlled distribution. Asics Corporation specializes in technical tennis shoes with gel-cushioning systems developed through sustained R&D investment in Kobe research facilities.
Tennis and golf apparel and footwear encompasses engineered garments and performance shoes designed for lateral movement stability, swing biomechanics, and extended outdoor exposure, typically incorporating moisture-wicking synthetic blends or treated leather uppers with spikeless or cleated outsole configurations. The primary commercial purpose centers on enhancing athletic performance while signaling lifestyle affiliation through visible branding and club-appropriate aesthetics. Tennis shoes and golf shoes command distinct margin pools due to sport-specific outsole engineering and endorsement dependencies, while activewear spans both categories with breathable mesh constructions representing the fastest-growing material-feature intersection. Accessories remain a mature, lower-volume segment concentrated in wholesale pro-shop channels.
REACH chemical restrictions in Europe limit certain dye and adhesive applications, compelling reformulation of water-resistant coatings across leather and synthetic uppers. The EPA oversees per- and polyfluoroalkyl substance phaseouts affecting water-resistant treatments in US-bound products, while ISO performance testing standards govern slip resistance and abrasion benchmarks that determine retail placement. Stakeholders must monitor evolving PFAS regulatory timelines and biomaterial certification requirements to anticipate sourcing transitions before compliance deadlines compress supplier options.
Market Dynamics
The EU Green Deal's textile sustainability requirements are compressing supplier timelines and forcing material transitions across synthetic uppers and water-resistant coatings before 2030 compliance deadlines.
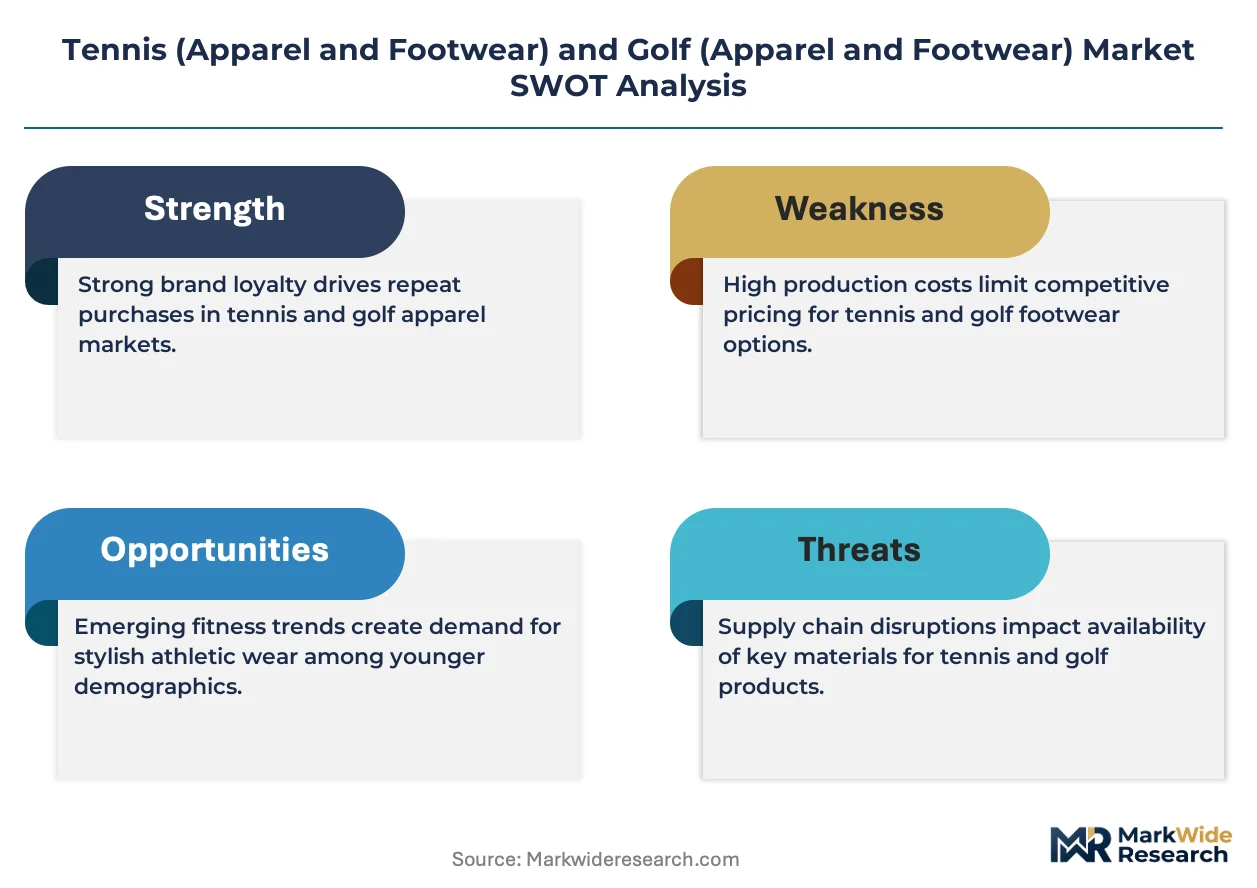
Growth Catalysts
- REACH chemical reformulation mandates:European dye and adhesive restrictions are accelerating adoption of bio-based water-resistant treatments across leather and synthetic footwear uppers.
- Moisture-wicking textile innovation:Breathable mesh constructions with enhanced thermal regulation are pulling recreational athlete purchases toward performance-oriented activewear in United States country clubs and tennis leagues.
- Vietnamese manufacturing cluster specialization:Ho Chi Minh City apparel factories are pivoting dedicated production lines toward sportswear to capture premium brand outsourcing contracts.
Market Restraints
- Petroleum-derived synthetic volatility:Polyester and polyurethane input costs fluctuate with crude oil pricing, compressing margin predictability for moisture-wicking fabric production.
- Indonesian supplier concentration:Premium footwear assembly relies heavily on Java-based manufacturers, creating vulnerability to port congestion and labor availability shocks.
- PFAS phaseout technical gaps:EPA-mandated elimination of per- and polyfluoroalkyl substances in water-resistant coatings lacks drop-in replacements meeting ISO slip-resistance benchmarks.
Strategic Opportunities
- Biomaterial certification tailwinds:USDA BioPreferred and EU Ecolabel standards create procurement preference channels for brands sourcing plant-based upper materials and natural rubber outsoles.
- Direct-to-consumer channel expansion:Bypassing wholesale pro-shop intermediaries allows margin capture and first-party data collection from recreational golfers and tennis league participants.
- Gel-cushioning convergence with biomechanical sensors:Embedding pressure-mapping technology into technical tennis shoes opens premium pricing tiers among competitive amateur segments.
Industry Challenges
- ISO performance testing recertification:Abrasion and slip-resistance benchmark updates require retooling laboratory partnerships and documentation systems across multiple product lines.
- Legacy ERP integration with traceability platforms:Supplier compliance data for EU Green Deal material sourcing must interface with existing inventory management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market |
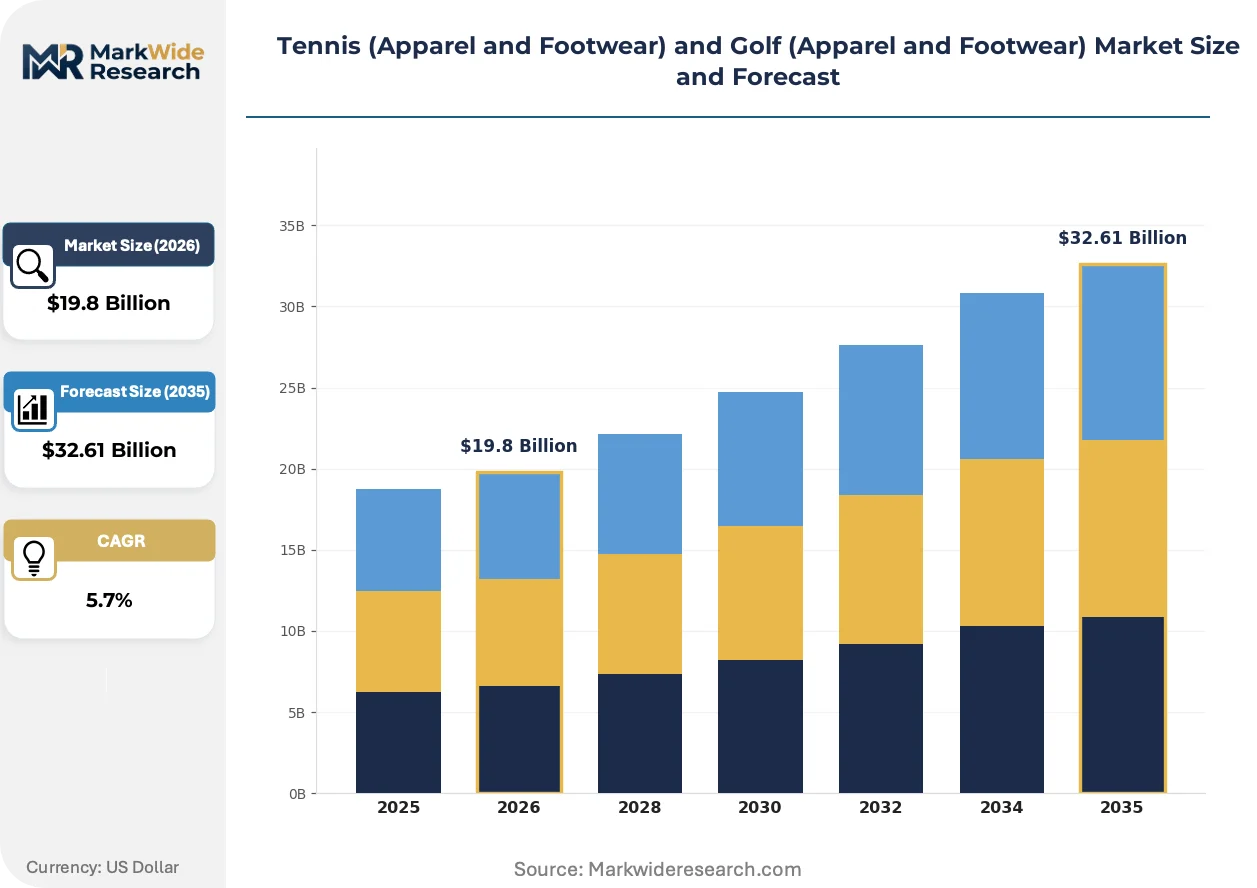
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $32.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tennis Shoes, Golf Shoes, Activewear, Accessories Material: Mesh, Leather, Synthetic, Rubber Feature: Water-Resistant, Breathable, Lightweight, Cushioned Customer Type: Professional Athletes, Recreational Players, Fitness Enthusiasts, Kids |
| Companies Covered | Nike, Inc., Adidas AG, Puma SE, Under Armour, Inc., Lululemon Athletica Inc., Asics Corporation, New Balance Athletics, Inc., Lacoste S.A., Yonex Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market Trends and Innovations
Material science breakthroughs and regulatory chemistry restrictions are simultaneously enabling performance upgrades and forcing formulation overhauls across footwear uppers and activewear textiles.
Spikeless outsole compounds with multi-directional traction lugs are rewriting golf footwear performance standards. Recreational players in United States country clubs are adopting these configurations at accelerating rates, replacing traditional cleated designs. This shift is compressing the addressable market for replaceable cleat suppliers while expanding margin pools for integrated sole manufacturers.
REACH Annex XVII restrictions on perfluorinated chemicals are compelling reformulation of water-resistant treatments across leather golf shoes and synthetic tennis uppers. European manufacturers face compressed transition timelines to bio-based alternatives. The golf apparel segment is responding fastest, with brands accelerating partnerships with chemical suppliers holding OEKO-TEX and bluesign certifications.
Amateur athlete purchasing through specialty retail is fragmenting toward digital fitting tools and subscription replenishment models. United States tennis league participants increasingly size footwear via 3D scanning applications before ordering direct. This pattern is most visible in coastal metropolitan markets where court access apps and equipment platforms share user data, collapsing traditional pro-shop foot traffic.
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market Segmentation
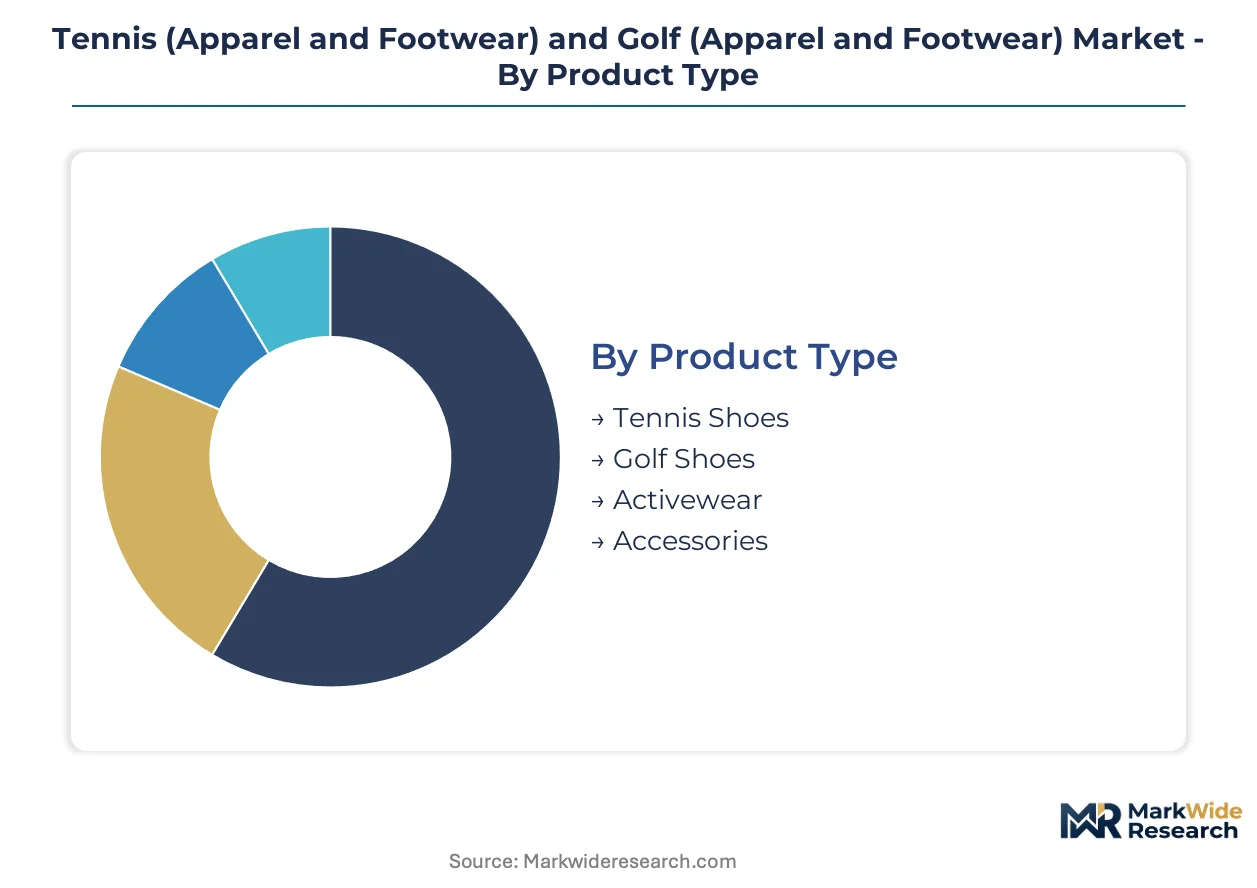
Segmentation in tennis and golf apparel and footwear reveals how capital deployment, material science investments, and channel strategies diverge across product categories. Manufacturers allocate R&D budgets unevenly, with footwear engineering commanding disproportionate resources versus textile development.
Product Type:
Tennis shoes and golf shoes demand the heaviest capital commitment due to sport-specific biomechanical testing, mold development, and athlete endorsement contracts.
- Tennis Shoes:Gel-cushioning systems and lateral stability plates require dedicated R&D facilities. Demand concentrates among United States tennis league participants seeking injury prevention through technical midsole engineering.
- Golf Shoes:Spikeless outsole compounds with multi-directional traction lugs dominate recreational purchasing. United States country club members are replacing traditional cleated designs at accelerating rates, compressing addressable markets for replaceable cleat suppliers.
- Activewear:Breathable mesh constructions span both sports with lower tooling costs than footwear.
- Accessories:Mature wholesale pro-shop segment with minimal capital requirements.
Tennis shoes absorb the bulk of installed capacity; golf shoes are expanding most quickly as spikeless configurations capture recreational demand.
Material:
Material selection determines regulatory exposure and supplier qualification timelines, with petroleum-derived synthetics facing the steepest reformulation pressure.
- Synthetic:Polyester and polyurethane uppers face REACH and EPA phaseout mandates. Ho Chi Minh City manufacturers are accelerating bio-based alternatives to maintain European market access.
- Mesh:Breathable constructions represent the fastest-growing material-feature intersection. Recreational athletes in United States coastal metropolitan markets prioritize thermal regulation in league and club environments.
- Leather:Treated uppers for golf shoes require water-resistant coating reformulation.
- Rubber:Outsole compounds govern slip-resistance certification under ISO standards.
Synthetic materials dominate current production volumes; mesh constructions are climbing the fastest as breathability becomes a baseline purchase criterion.
Feature:
Feature prioritization reflects divergent performance demands between competitive and recreational use cases, with water-resistant treatments facing the most urgent technical transition.
- Water-Resistant:PFAS-free coating development absorbs disproportionate chemical R&D investment. European manufacturers face compressed timelines to meet EU Green Deal compliance deadlines.
- Breathable:Moisture-wicking textile innovation pulls recreational purchases toward performance tier. United States tennis league enrollment growth sustains demand for thermal regulation features.
- Lightweight:Midsole density reduction competes with durability requirements in competitive segments.
- Cushioned:Gel and foam systems differentiate premium tennis footwear positioning.
Water-resistant features command premium pricing; breathable constructions are gaining share fastest as recreational participation broadens.
Customer Type:
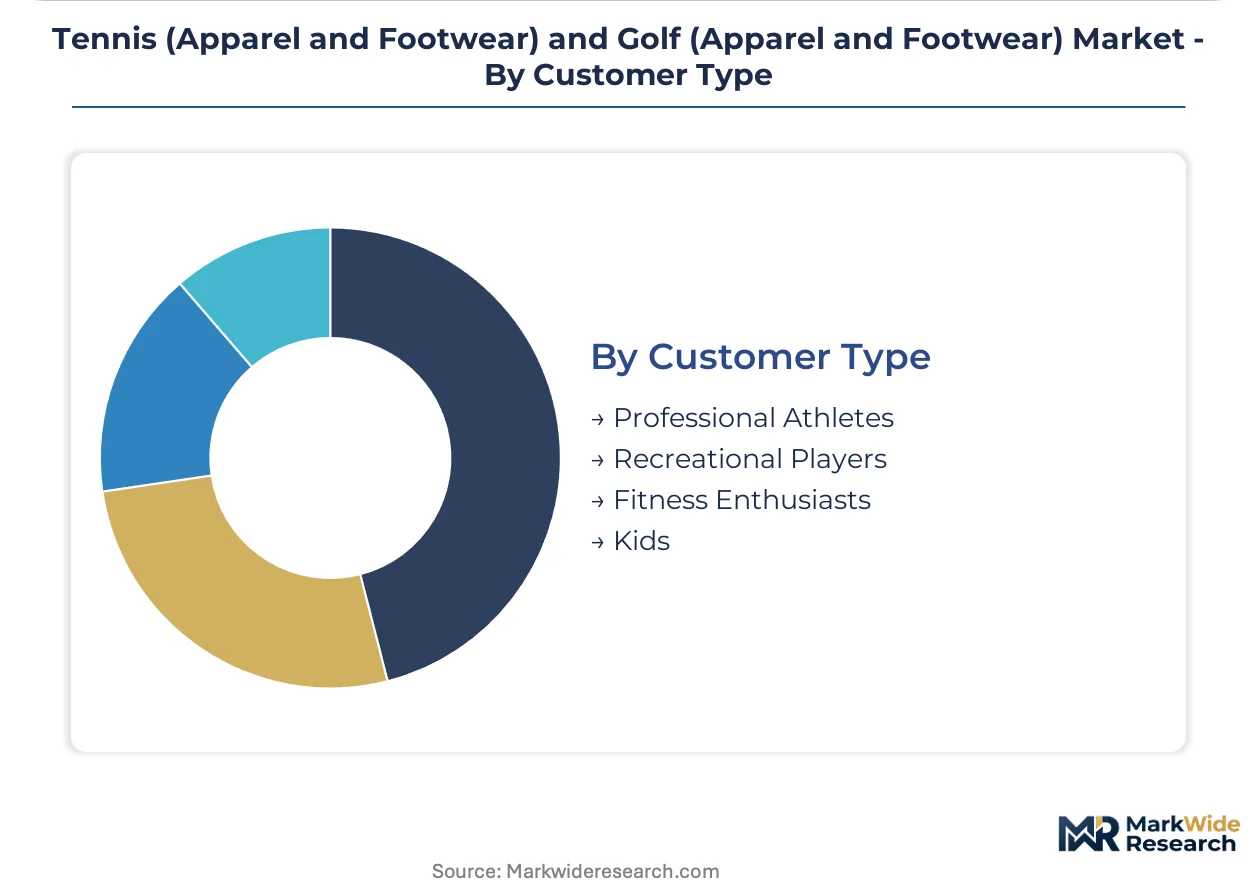
Customer type segmentation determines channel strategy and pricing architecture, with professional athlete sponsorship requiring fundamentally different capital structures than recreational marketing.
- Professional Athletes:Endorsement contracts and tour partnerships demand multi-year guaranteed payments. Adidas AG and others anchor golf apparel strength through controlled distribution tied to player visibility.
- Recreational Players:Direct-to-consumer channel expansion targets this segment with 3D scanning and subscription replenishment. United States court access apps share user data with equipment platforms, collapsing traditional pro-shop foot traffic.
- Fitness Enthusiasts:Cross-sport purchasers blur category boundaries between tennis and general activewear.
- Kids:Volume-driven segment with lower per-unit margins and seasonal purchasing patterns.
Recreational players absorb the bulk of marketing investment; professional athlete segments are expanding most quickly as brands seek tour visibility for credibility transfer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum-derived synthetic feedstock availability in the Texas Gulf Coast and Louisiana corridor anchors North American manufacturing for moisture-wicking textiles. Vietnamese natural rubber plantations and Indonesian palm oil derivatives supply Southeast Asian footwear clusters serving premium brand contracts.
United States
Country club participation in Florida, Arizona, and California sustains golf apparel demand alongside tennis league enrollment growth in coastal metropolitan markets. The EPA oversees PFAS phaseouts affecting water-resistant treatments in domestic-bound footwear. Ho Chi Minh City manufacturers maintain dedicated production lines for US-bound premium sportswear contracts.
Germany
REACH Annex XVII chemical restrictions accelerate bio-based coating adoption across leather golf shoe uppers destined for domestic retail. The EU Green Deal's textile sustainability requirements compress supplier timelines for synthetic material transitions. Bavarian chemical suppliers holding bluesign certifications partner with footwear brands on PFAS-free water-resistant formulations.
Japan
Technical tennis shoe demand concentrates among competitive amateur segments seeking gel-cushioning systems with biomechanical stability. METI standards govern product safety certifications for athletic footwear imports. Kobe research facilities anchor sustained R&D investment in midsole engineering and lateral support plate development.
Vietnam
Ho Chi Minh City apparel factories pivot dedicated production lines toward specialized sportswear to capture premium brand outsourcing contracts. The country's central bank monitors currency stability for export-dependent manufacturing sectors. Binh Duong Province industrial zones expand synthetic upper and mesh construction capacity for North American and European orders.
United Kingdom
Tennis league participation in Greater London and Southeast England drives breathable activewear purchases through direct-to-consumer digital channels. The UK's national environmental regulator enforces REACH-aligned chemical restrictions on imported footwear treatments. Manchester-based textile innovators develop moisture-wicking synthetic blends for club-appropriate athletic aesthetics.
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent wellness-lifestyle positioning through cross-sport activewear lines. The market structure consolidates around vertically integrated multinationals with captive design and retail channels, while mid-tier specialists concentrate on single-sport technical footwear. Three archetypes dominate: performance-engineered footwear specialists, lifestyle-affiliation apparel brands, and direct-to-consumer digital natives. Competitive moves center on backward integration into material sourcing and strategic partnerships with professional tour athletes for credibility transfer.
Within the performance-engineered tier, Nike, Inc. and Adidas AG exemplify scale-driven multinationals with vertical control across design and distribution channels. Asics Corporation occupies a specialist position anchored by technical footwear R&D investment. These three entities represent contrasting strategic postures: the first emphasizes lifestyle branding and athlete endorsement density, the second anchors golf apparel strength through controlled distribution partnerships, and the third concentrates on biomechanical innovation in tennis-specific footwear engineering.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| Puma SE |
| Under Armour, Inc. |
| Lululemon Athletica Inc. |
| Asics Corporation |
| New Balance Athletics, Inc. |
| Lacoste S.A. |
| Yonex Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialists in Vietnamese apparel manufacturing have consolidated Ho Chi Minh City factory networks, compressing supplier margins while extending payment terms that force pricing discipline upstream. This ownership pattern concentrates negotiation leverage with premium brand contractors, reshaping cost absorption across synthetic upper and mesh construction tiers.
Pricing Analysis
Warranty and service bundling remains largely unbundled across tennis and golf footwear, with professional-grade gel-cushioning systems and spikeless outsole compounds commanding premium positioning without extended coverage. Three-tier pricing structure across premium, standard, and economy levels separates tour-endorsed technical footwear from club-channel activewear and mass-market entry products. Pricing pressure stems from petroleum-derived synthetic volatility, with polyester and polyurethane input costs fluctuating alongside crude oil benchmarks. Recreational players in United States country clubs exhibit lowest price sensitivity for biomechanical performance features, while youth and fitness enthusiast segments prioritize unit economics over technical specifications.
Supply Chain Analysis
Reverse-logistics infrastructure for footwear remains underdeveloped, with minimal refurbishment or remanufacturing flows beyond limited warranty replacement programs. Geographic supply concentration centers on Vietnam, Indonesia, and China, with Ho Chi Minh City apparel clusters and Java-based footwear assembly serving premium brand contracts. Raw material dependencies draw from petroleum-derived synthetics, natural rubber plantations, and palm oil derivatives for bio-based coating alternatives. Single-source vulnerability concentrates in Indonesian port infrastructure, where congestion shocks disrupt just-in-time delivery to North American retailers. Distribution runs through wholesale pro-shop intermediaries, though direct-to-consumer channels are capturing share fastest among recreational athlete segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a materials-transition phase, with PFAS-free water-resistant coatings displacing legacy perfluorinated treatments ahead of EPA and EU Green Deal compliance deadlines.
For Market Incumbents: Hedge against regulatory chemistry disruption by accelerating partnerships with Bavarian and Kobe-based suppliers holding bluesign and OEKO-TEX certifications for bio-based coating formulations. Deepen backward integration into Vietnamese synthetic upper production to secure capacity ahead of competing brand contracts. Captive mesh construction lines in Binh Duong Province industrial zones offer margin protection against petroleum input volatility. For New Entrants and Emerging Players: Launch via direct-to-consumer digital channels targeting United States coastal metropolitan tennis league participants, where 3D scanning applications and court access app integrations collapse traditional pro-shop intermediation. White-space concentrates in subscription replenishment models for recreational golfers seeking spikeless outsole replacement cycles. Biomechanical sensor embedding in amateur-grade tennis footwear represents the most penetrable premium tier. For Investors and Strategic Acquirers: USDA BioPreferred certification attainment is the leading indicator that a brand has secured defensible procurement preference channels as EU Ecolabel standards tighten. Long-term viability hinges on material sourcing flexibility across the analysis window, with acquisition targets screening for laboratory partnerships capable of ISO performance testing recertification. Monitor EPA PFAS phaseout timeline acceleration as the critical inflection signal for forced supplier transitions.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Partnership | Secures ECHA REACH compliance for European market access ahead of deadline compression. |
| Direct-to-Consumer Platform Launch | Captures first-party data from United States tennis league and country club participants. |
| Biomechanical Sensor Integration | Opens premium pricing tiers among competitive amateur segments seeking injury prevention. |
| Vietnamese Manufacturing Footprint Expansion | Locks in synthetic upper and mesh construction capacity for North American brand contracts. |
| Bluesign Certification Investment | Qualifies suppliers for Adidas AG and other controlled distribution partnership requirements. |
Research Methodology
Independent corroboration across brand procurement executives, Vietnamese factory operations directors, and European chemical compliance officers underwrites the qualitative findings on material transition timelines. Primary interviews with footwear R&D heads, pro-shop category buyers, and athletic club equipment managers combined with secondary validation through customs trade data, SEC apparel sector filings, and EPA regulatory docket records. Bottom-up demand modeling from tennis league enrollment and country club participation statistics triangulates against top-down synthetic textile and rubber outsole production estimates.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, material composition, performance feature tier, customer archetype, and regional regulatory cluster. CAGRs derive from iterative reconciliation of historical shipment data with forward-looking brand capacity announcements and compliance-driven material substitution curves. Key inputs incorporate REACH Annex XVII chemical restriction phase-in schedules and EPA perfluorinated substance elimination benchmarks.
The model assumes a particular technology adoption path; alternative pathways for bio-based water-resistant coating performance would alter the outlook if ISO slip-resistance certification gaps persist. Forecasts reflect assumptions on supplier qualification timelines and recreational athlete channel migration velocity. Practitioners should monitor ECHA substance restriction updates and Vietnamese central bank currency stability interventions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Press-To-Close Zippers Market
Apparel & Footwear
Driving Apparel Market
Apparel & Footwear
South Africa Denim Jeans Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
Denim Jeans Market
Apparel & Footwear
Global Leggings Market
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
Bra Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Luxury Vegan Men's Fashion Market
Apparel & Footwear
Sports Inspired Clothing Market
Apparel & Footwear
Swimwear and Beachwear Market
Apparel & Footwear
Europe Second-Hand Apparel Market
Apparel & Footwear
Outdoor Apparel and Accessories Market
Apparel & Footwear
Sports Bras Market
Apparel & Footwear
Womens Swimwear Market