
 Hair Serums Ingredient Market | 2026-2036
Hair Serums Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Serums Ingredient Market Foresight
South Korean biotech fermentation capacity is rebalancing the competitive map for peptide-based hair actives. L'Oréal Group leverages captive botanical gardens in Madagascar to secure vanilla planifolia supply chains for premium serum lines. Unilever PLC sustains its position through concentrated R&D spending on scalp microbiome science. Procter & Gamble anchors North American mass-market distribution with pharmacy-retail exclusivity agreements.
Hair serums ingredient denotes the functional raw material inputs—ranging from low-molecular-weight silicones to hydrolyzed keratin complexes and cold-pressed seed oils—formulated at concentrations between 0.5% and 15% w/w to deliver targeted cuticle penetration and cortex conditioning. These inputs undergo emulsion stabilization, liposome encapsulation, or solvent-free extraction before incorporation into leave-in or rinse-off serum vehicles destined for professional and retail channels. Natural oils and protein complexes command the widest margin pools due to clean-label premiums and substantiated damage-repair claims, while silicones face structural compression as sulfate-free and silicone-free positioning gains shelf space across prestige and masstige tiers. Herbal extracts represent the fastest-growing ingredient type, propelled by Ayurvedic and traditional Chinese medicine validation studies entering peer-reviewed dermatology journals.
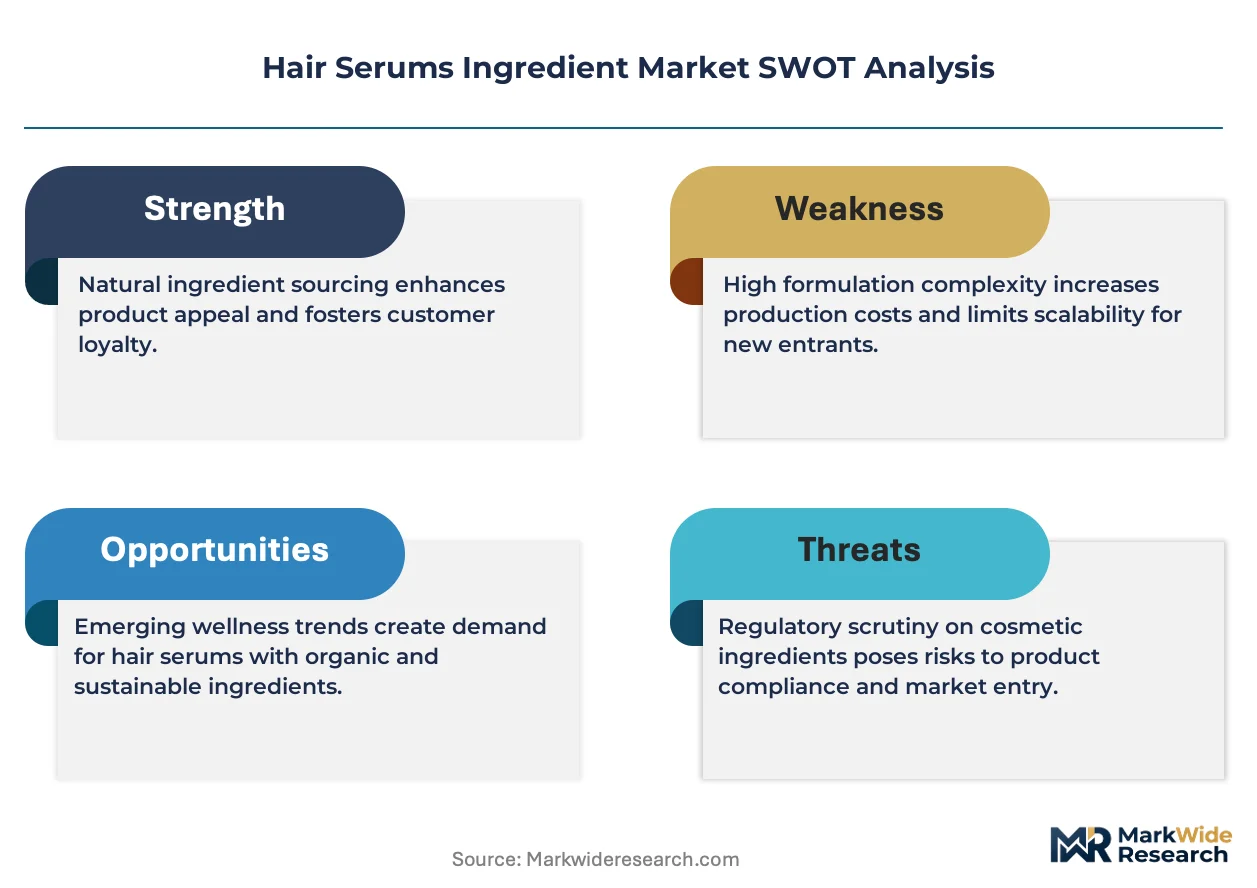
FDA cosmetic labeling requirements and EU REACH annex XVII restrictions on cyclic siloxanes D4/D5/D6 are reshaping permissible ingredient portfolios for brands accessing US and European consumers. India's BIS and CDSCO frameworks govern ayurvedic extract standardization, creating compliance moats for domestic suppliers with pharmacopeial-grade certification. Stakeholders must monitor evolving preservative bans under the EU Green Deal and parallel state-level clean beauty legislation in California to anticipate reformulation cost spikes and raw material substitution timelines.
Market Dynamics
REACH annex XVII restrictions on cyclic siloxanes D4/D5/D6 are forcing wholesale reformulation across silicone-dependent serum portfolios, compressing incumbent supply chains while opening margin pools for bio-based alternatives.
Growth Catalysts
- EU Green Deal preservatory thresholds:Tightening permissible preservative limits under the EU Green Deal are accelerating clean-label ingredient substitution cycles among European formulators seeking compliance moats.
- Salon professional training expansion:Formal ingredient literacy programs for salon professionals in India are expanding addressable demand for pharmacopeial-grade ayurvedic extracts.
- South Korean peptide fermentation:Biotech fermentation capacity in South Korea is electrifying supply availability for hydrolyzed protein complexes previously constrained by extraction yield limits.
Market Restraints
- Silicone input cost volatility:Cyclic siloxane phase-out timelines under REACH are compressing residual supply availability while bio-alternative scale-up remains capital-intensive.
- Ayurvedic extract concentration:Pharmacopeial-grade botanical sourcing clusters narrowly around Kerala and Gujarat, creating geographic supply vulnerability for standardized ashwagandha and amla extracts.
- Preservative efficacy gaps:Clean-label preservative systems face technical limitations in broad-spectrum protection against mold and yeast in water-based serum vehicles.
Strategic Opportunities
- Scalp microbiome science convergence:R&D investment in scalp microbiome-targeted actives is opening white space between dermatology and cosmetic positioning for peptide-lipid hybrid ingredients.
- Direct-to-professional channel innovation:Bypassing traditional distributor tiers through salon-exclusive digital procurement platforms is capturing margin previously allocated to wholesale intermediaries.
- India PLI scheme tailwinds:Production-linked incentive schemes for active pharmaceutical ingredient manufacturing are extending cost advantages to botanical extraction infrastructure.
Industry Challenges
- Reformulation capex intensity:Silicone-free vehicle redevelopment requires investment in new emulsion stabilization equipment and stability testing protocols.
- Pharmacopeial certification timelines:BIS and CDSCO standardization for ayurvedic extracts involves 18-24 month approval windows that delay commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Serums Ingredient Market |
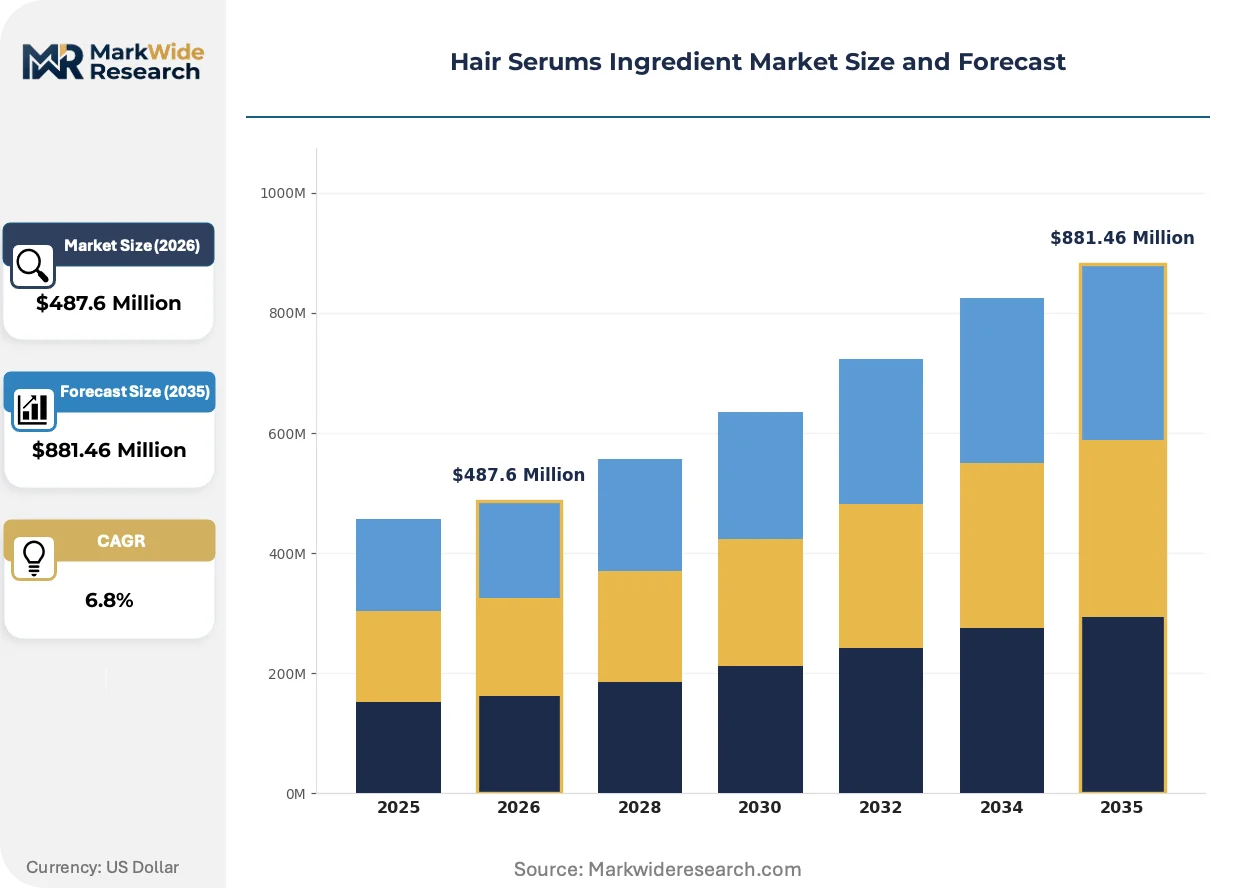
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Natural Oils, Protein Complexes, Herbal Extracts, Silicones Formulation Purpose: Moisturizing, Smoothing, Strengthening, Nourishing Target Hair Type: Curly, Straight, Wavy, Textured Consumer Segment: Salon Professionals, DIY Users, Retail Consumers, Beauty Enthusiasts |
| Companies Covered | L'Oréal Group, Unilever PLC, Procter & Gamble, Mystic Moments, Parchem Fine & Specialty Chemicals, Glamour Cosmetics, Pharmacos, Beiersdorf AG, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Serums Ingredient Market Shifts & Advancements
Liposome encapsulation technology is electrifying bioavailability claims for hydrophobic actives, while regulatory fragmentation across FDA cosmetic labeling and EU REACH annex XVII is complicating unified product architecture.
Fermentation-derived peptide manufacturing is electrifying cost structures for keratin-mimetic actives previously dependent on animal-source hydrolysis. Mid-tier brands in South Korea and India are adopting these inputs at accelerating rates. The technology is electrifying competitive positioning for suppliers with captive bioreactor capacity against traditional extraction houses.
REACH annex XVII D4/D5/D6 restrictions are eliminating cyclic siloxanes from rinse-off and leave-in formulations by 2026-2027. European formulators are rebuilding emulsion systems around volatile alkylmethicones and plant-derived squalane. Prestige serum lines targeting German and French retail channels are absorbing the highest compliance costs while repositioning silicone-free claims as premium differentiators.
Buyer concentration among pharmacy-retail chains is compressing formulation autonomy for mass-market brands. North American mass-market suppliers face unbundled service demands where retailers specify preservative systems and exclude certain INCI-designated ingredients. This pattern is most visible in CVS and Walgreens exclusivity negotiations, where clean beauty scorecard compliance determines shelf placement.
Hair Serums Ingredient Market Segmentation
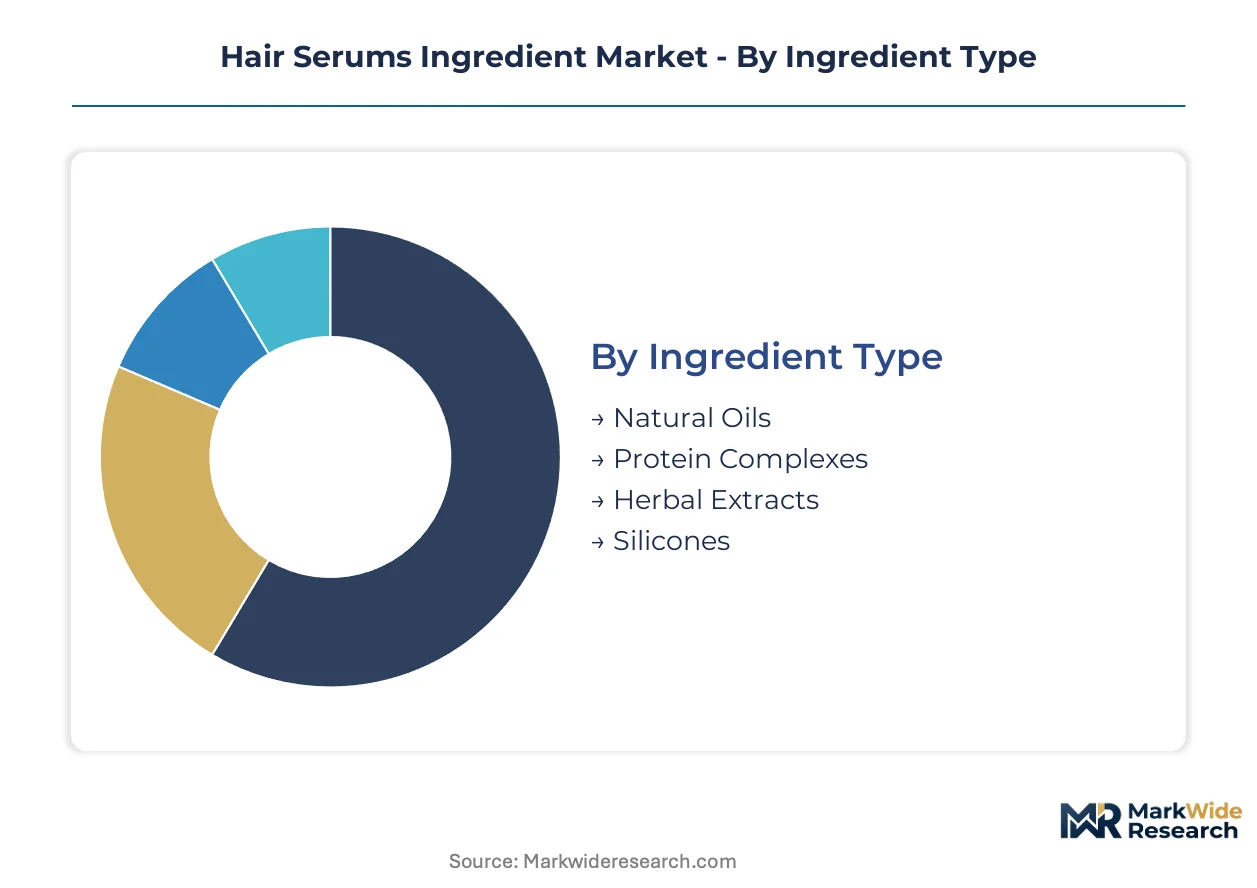
Ingredient stratification in hair serums determines margin capture, regulatory exposure, and supply chain resilience. Formulators select inputs based on clean-label positioning, emulsion compatibility, and substantiated efficacy claims rather than cost alone.
Ingredient Type:
Buyers differentiate by sourcing complexity, certification requirements, and reformulation flexibility under tightening preservative and silicone regulations.
- Natural Oils:Cold-pressed seed oils including argan, jojoba, and marula deliver lipophilic conditioning with high oxidative stability. Demand concentrates in prestige serum lines across Germany and France where silicone-free positioning commands shelf space.
- Protein Complexes:Hydrolyzed keratin and silk amino acids penetrate cortex layers to reduce porosity. South Korean biotech fermentation capacity is electrifying supply availability for peptide-mimetic alternatives previously constrained by extraction yields.
- Herbal Extracts:Standardized Ayurvedic botanicals from Kerala and Gujarat clusters serve India domestic and export channels.
- Silicones:Low-molecular-weight dimethicones face phase-out pressure under EU REACH annex XVII D4/D5/D6 restrictions.
Natural oils lead volumes today; herbal extracts are gaining share fastest.
Formulation Purpose:
End-use application dictates active concentration ranges, vehicle architecture, and stability testing protocols.
- Moisturizing:Humectant-dominant formulations incorporating glycerin and hyaluronic acid derivatives target dehydrated cuticle layers. Salon professionals in India specify these for chemical-treated hair recovery protocols.
- Smoothing:Cationic conditioning agents and volatile silicones reduce friction coefficients for straight and wavy hair types. REACH compliance timelines are compressing residual demand into alkylmethicone alternatives.
- Strengthening:Disulfide bond repair actives penetrate cortex for damaged hair reconstruction.
- Nourishing:Vitamin-lipid complexes support scalp barrier function in leave-in overnight applications.
Moisturizing formulations dominate current production; strengthening applications show the steepest expansion trajectory.
Target Hair Type:
Hair morphology determines molecular weight requirements, spreadability needs, and regional demand concentration.
- Curly:High-porosity cuticle structures demand heavier lipid loads and anti-humectant sealants. Formulation R&D in Brazil targets this segment with coconut-derived film formers.
- Straight:Low-friction surfaces require lightweight silicones or squalane alternatives for gloss without weight. Japanese consumers drive precision in this category.
- Wavy:Intermediate porosity creates hybrid formulation requirements balancing definition and volume.
- Textured:Coily patterns with dense cuticle layering need maximum emollient saturation and pH-balanced acidity.
Straight hair formulations anchor current volume; textured hair applications are expanding most quickly.
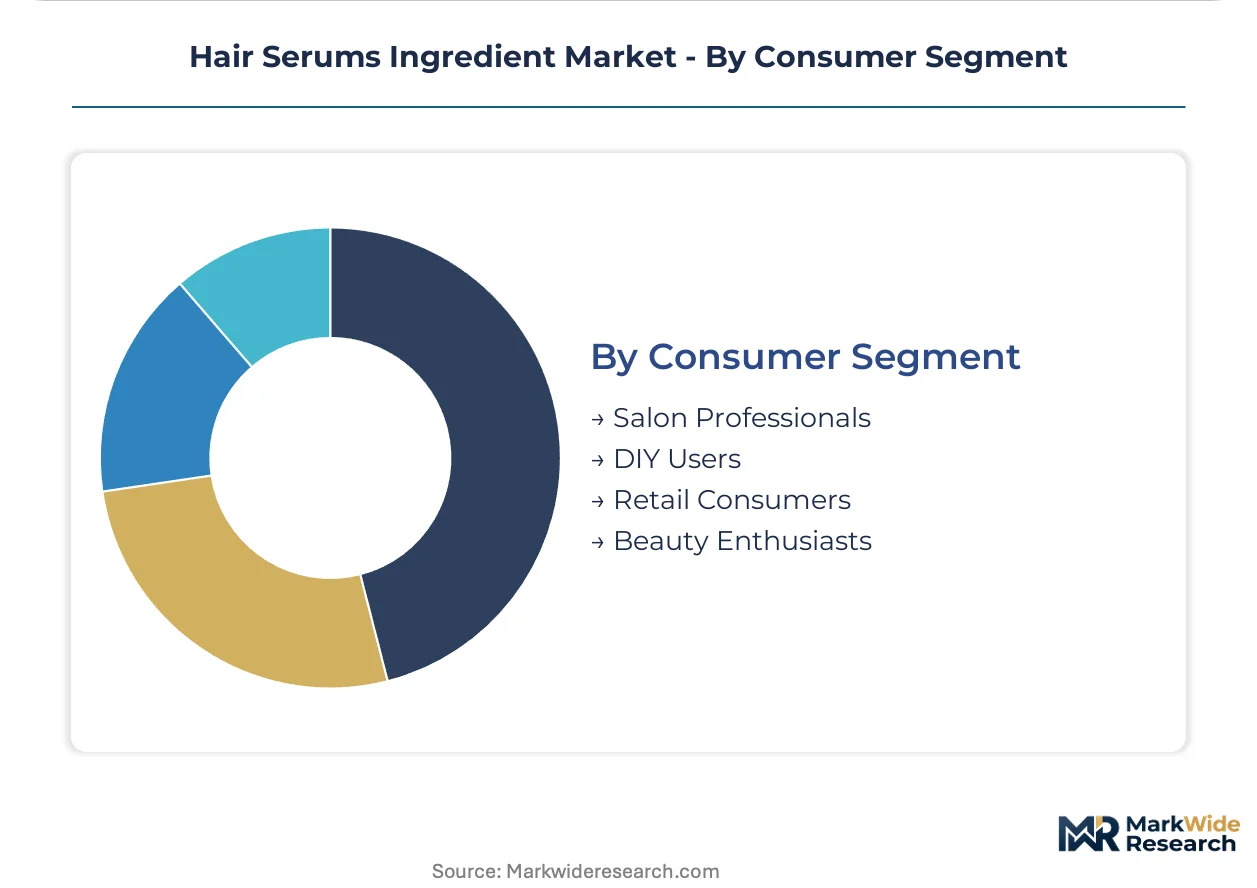
Consumer Segment:
Purchasing authority, technical literacy, and channel access create distinct procurement patterns across buyer types.
- Salon Professionals:Licensed practitioners with ingredient literacy specify pharmacopeial-grade actives and reject mass-market preservative systems. India's formal training expansion is broadening this addressable base.
- DIY Users:Home formulators purchasing raw ingredients direct from suppliers create disintermediation pressure on traditional retail channels.
- Retail Consumers:Pharmacy-retail chains including CVS and Walgreens specify clean beauty scorecard compliance that constrains brand formulation autonomy.
- Beauty Enthusiasts:Social media-influenced purchasers prioritize INCI transparency and sustainability certifications over performance claims alone.
Retail consumers generate highest absolute volumes; salon professionals are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between EU REACH restrictions and India's PLI scheme is creating a compliance-cost arbitrage that shifts fermentation-derived peptide production toward South Korean and Indian manufacturing clusters while European formulators absorb reformulation expenses.
Germany
REACH annex XVII D4/D5/D6 restrictions are eliminating cyclic siloxanes from rinse-off formulations by 2026. German formulators are rebuilding emulsion systems around volatile alkylmethicones and plant-derived squalane. The Rhine-Ruhr industrial corridor houses specialty chemical producers scaling bio-based silicone alternatives for prestige serum lines.
India
Salon professional training expansion and ayurvedic ingredient literacy are broadening demand for pharmacopeial-grade extracts. BIS and CDSCO frameworks govern botanical standardization, creating compliance moats for domestic suppliers. Kerala and Gujarat clusters concentrate standardized ashwagandha and amla extraction capacity for export channels.
South Korea
Biotech fermentation capacity is electrifying supply availability for hydrolyzed protein complexes and peptide-mimetic actives. MFDS cosmetic regulations align with EU preservative thresholds, enabling dual-market product registration. Seoul Capital Area bioreactor facilities are displacing traditional animal-source hydrolysis for keratin-derived inputs.
United States
FDA cosmetic labeling requirements and state-level clean beauty legislation in California are constraining preservative portfolios for mass-market brands. Pharmacy-retail chains including CVS and Walgreens specify clean beauty scorecard compliance that determines shelf placement. New Jersey and California house formulation laboratories serving North American distribution networks.
Brazil
Curly and textured hair segments drive demand for coconut-derived film formers and high-emollient formulations. ANVISA cosmetic regulations maintain preservative permissiveness that attracts reformulated European product lines seeking regulatory refuge. São Paulo anchors Latin American distribution for salon-professional channels.
Hair Serums Ingredient Market Competitive Landscape
European producers anchor the premium-tier ingredient supply; South Korean and Indian specialists hold fermentation and botanical extraction positions. The vendor base stratifies across multinational chemical conglomerates with captive R&D infrastructure, mid-cap regional suppliers with pharmacopeial certification, and niche biotech houses with proprietary peptide platforms. Three archetypes dominate: integrated beauty conglomerates with backward extraction control, independent specialty chemical distributors, and contract fermentation operators. Capacity expansion in Indian botanical extraction and South Korean bioreactor facilities represents the primary competitive vectors.
Among integrated beauty conglomerates, L'Oréal Group and Unilever PLC exemplify archetypes with captive supply chain control over botanical sourcing. Procter & Gamble occupies a position anchoring North American mass-market distribution through pharmacy-retail channel relationships. These three entities represent distinct strategic postures: Madagascar-based vanilla planifolia gardens, concentrated scalp microbiome R&D spending, and pharmacy-retail exclusivity agreements respectively.
| Leading Market Players |
|---|
| L'Oréal Group |
| Unilever PLC |
| Procter & Gamble |
| Mystic Moments |
| Parchem Fine & Specialty Chemicals |
| Glamour Cosmetics |
| Pharmacos |
| Beiersdorf AG |
| Kao Corporation |
| Others |
Supply & Pricing Matrix
Pharmacy-retail scorecard mandates from CVS and Walgreens are squeezing formulation autonomy and forcing ingredient substitutions that compress supplier margins while elevating certified-clean alternatives. This buyer-driven specification shift reroutes procurement toward pharmacopeial-grade botanicals and bio-fermented peptides, restructuring tier relationships and cost allocation across the value chain.
Pricing Analysis
Distributor margin layers in the salon-professional channel absorb the highest absolute cuts as digital procurement platforms disintermediate traditional wholesale tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and extraction method, with cold-pressed seed oils and BIS-standardized ayurvedic extracts commanding the widest spreads. Cost compression in silicone alternatives is intensifying because REACH-compliant alkylmethicone scale-up remains capital-intensive. DIY home formulators show the greatest price elasticity, while prestige salon professionals exhibit the least sensitivity when pharmacopeial-grade claims are substantiated.
Supply Chain Analysis
Specialized fermentation technicians in South Korea and extraction chemists in Kerala and Gujarat face acute demand pressure as bioreactor capacity and pharmacopeial-grade botanical infrastructure expand in parallel. Supply concentration spans South Korea for peptide-mimetic actives, India for standardized ashwagandha and amla extracts, and Germany for bio-based silicone alternatives. Manufacturing draws from cold-pressed argan and marula seed oils, hydrolyzed keratin complexes, and volatile alkylmethicones as silicone replacements. Single-source vulnerability around Kerala and Gujarat clusters for ayurvedic extracts creates geographic concentration risk. Distribution runs through pharmacy-retail chains for mass-market volumes and salon-exclusive digital platforms for professional-grade lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as salon professionals with formal ingredient literacy specifications displace price-driven retail procurement, elevating substantiated efficacy claims over volume discounts.
For Market Incumbents: Cement captive supply positions through backward integration into Kerala and Gujarat extraction infrastructure and Seoul Capital Area bioreactor partnerships. L'Oréal Group's Madagascar vanilla planifolia gardens demonstrate the defensive moat value of botanical supply control. Unilever PLC's concentrated scalp microbiome R&D spending anchors premium positioning against peptide-lipid hybrid entrants. Prioritize pharmacopeial certification investment to maintain salon-professional channel access as BIS and CDSCO frameworks tighten.
For New Entrants and Emerging Players: Salon-exclusive digital procurement platforms offer the most penetrable channel wedge as disintermediation captures margin previously allocated to wholesale tiers. White space concentrates in scalp microbiome-targeted actives between dermatology and cosmetic positioning, and in textured hair formulations for Brazil's curly and coily segments. ANVISA regulatory refuge in Brazil attracts reformulated European product lines seeking preservative permissiveness. Direct-to-professional positioning with pharmacopeial-grade claims bypasses retail scorecard constraints.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap regional suppliers holding pharmacopeial certification and captive bioreactor capacity. Long-term viability over a multi-year horizon favors fermentation-derived peptide specialists displacing animal-source hydrolysis and standardized ayurvedic extract houses with BIS/CDSCO compliance moats. Watch EU Green Deal preservative threshold announcements as the inflection indicator for reformulation capex cycles and raw material substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Extraction | Kerala and Gujarat clusters secure pharmacopeial-grade supply chains for salon-professional channels. |
| Bioreactor Capacity Expansion | Seoul Capital Area facilities displace traditional hydrolysis for keratin-mimetic peptide manufacturing. |
| Direct-to-Professional Digital Platform Launch | Bypassing distributor tiers captures margin and captures salon procurement authority shifts. |
| Scalp Microbiome R&D Investment | Peptide-lipid hybrid development opens dermatology-cosmetic convergence positioning. |
| Clean Beauty Scorecard Compliance Program | CVS and Walgreens shelf placement depends on preservative system transparency and INCI disclosure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with salon professional trainers, cosmetic formulators, pharmacy-retail category buyers, bioreactor operations managers, and ayurvedic extraction facility directors alongside secondary validation. Regulatory filings from ECHA REACH annex XVII updates, FDA cosmetic labeling guidance, BIS pharmacopeial standards, and MFDS cosmetic regulations anchored compliance trend analysis. Trade data, customs records for cold-pressed seed oils, and SEC filings from integrated beauty conglomerates supplemented demand-side calibration. Bottom-up volume builds across ingredient types and formulation purposes triangulated against top-down market sizing from channel shipment data.
Historical reference periods spanning pre- and post-REACH restriction announcement windows anchored elasticity assumptions for silicone substitution rates and peptide adoption curves. The projection horizon incorporates segmentation across ingredient type, formulation purpose, target hair type, and consumer segment with regional regulatory cluster overlays. CAGRs derive from trend extrapolation moderated by reformulation timeline constraints and certification approval windows. Fermentation capacity utilization rates and pharmacopeial-grade extraction yield improvements serve as key industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal preservative ban timelines, South Korean bioreactor scale-up execution, and Kerala/Gujarat climatic variability affecting botanical harvests. Assumptions reflect documented regulatory trajectories and disclosed capacity expansion plans. Material deviation in REACH enforcement intensity or PLI scheme extension timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Cosmetic Palettes Market
Beauty & Personal Care
Personalized Beauty Devices Market
Beauty & Personal Care
Mexico Beauty and Personal Care Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Global Massage Oil Market
Beauty & Personal Care
Global Personal Care Emollients Market
Beauty & Personal Care
North America Beauty and Personal Care Products Market
Beauty & Personal Care
Electric Face Cleanser Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
Bar Soap Market
Beauty & Personal Care
Anti Stretch Mark Products Market
Beauty & Personal Care
Europe Sustainable Personal Care Market
Beauty & Personal Care
United States Male Grooming Products Market
Beauty & Personal Care
Global Organic Personal Care and Cosmetic Products Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
In-Wash Scent Booster Market