
 Heated Jacket Market | 2026-2036
Heated Jacket Market Size, Share, and Industry Trends Forecast 2026-2036
Heated Jacket Market Analysis
Professional trade workers is collapsing into the dominant buyer archetype as recreational demand normalizes post-pandemic. Milwaukee sustains channel dominance through deep placement in construction supply chains and battery ecosystem lock-in with its M12 and M18 platforms. DeWalt competes on parallel tool-battery interoperability, while Makita anchors share in Asia-Pacific through professional-grade heating output ratings and distributor relationships with industrial safety suppliers.
A heated jacket integrates conductive heating elements—typically carbon fiber or stainless steel fiber woven into fabric layers—with a portable power source to maintain core body temperature in cold environments; most units operate at 7.4V to 12V with three to four heat zones delivering 100°F to 135°F output. Rechargeable battery jackets lead volume due to lithium-ion energy density improvements and cross-compatibility with cordless tool platforms, while USB-powered variants capture fastest growth among casual urban commuters. Polyester shell constructions dominate material share for durability and moisture resistance, though nylon blends command premium positioning in alpine and backcountry segments.
FCC certification governs electromagnetic emissions from battery controllers in the United States, while CE marking under EU directives mandates electrical safety and textile flammability compliance for European market access. OSHA cold stress guidelines indirectly shape employer procurement criteria for heated workwear in American construction and logistics sectors. Stakeholders must monitor evolving battery transport regulations and tool-platform interoperability standards as ecosystem lock-in becomes the primary competitive battleground.
Market Dynamics
Battery ecosystem lock-in between cordless tool platforms and heated apparel is compressing buyer choice and reshaping competitive positioning. Tool manufacturers leverage existing battery installed bases to capture apparel attachment revenue, while pure-play apparel brands face channel exclusion.
Growth Catalysts
- OSHA cold stress guidelines:American construction and logistics employers now specify heated workwear in winter safety procurement. This mandates employer-funded replacement cycles.
- Carbon fiber heating elements:Improved conductivity and wash durability extend product lifespans. Professional trade workers accept premium pricing for reliability.
- China:Winter recreation infrastructure expansion and outdoor labor protection mandates drive volume demand in the world's largest manufacturing base.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack input costs fluctuate with cathode material pricing. Manufacturers absorb margin compression or pass through to price-sensitive segments.
- FCC certification timelines:Electromagnetic emissions testing for battery controllers adds 8-14 weeks to product launch schedules. Smaller brands face working capital strain.
- Insulated shell materials:Advanced polyester and nylon blends compete on thermal retention without active heating. Passive alternatives capture budget-conscious recreational buyers.
Strategic Opportunities
- USB-C power delivery standardization:Universal charging compatibility opens heated jacket sales to smartphone-centric urban commuters. This segment lacks tool-platform loyalty.
- Germany:Industrial safety distributor relationships remain underpenetrated by non-European brands. CE marking competence creates entry barriers for unprepared competitors.
- Alpine rescue and emergency services:Extended runtime requirements and visible heating zones command specialized product development. Certification to EN standards enables premium positioning.
Industry Challenges
- Textile-electronics integration:Wash-cycle durability testing requires specialized equipment and protocols. Brands without in-house capabilities outsource to limited qualified labs.
- Cross-platform battery interoperability:Voltage and connector incompatibilities fragment consumer choice. Technical standards bodies have not unified specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heated Jacket Market |
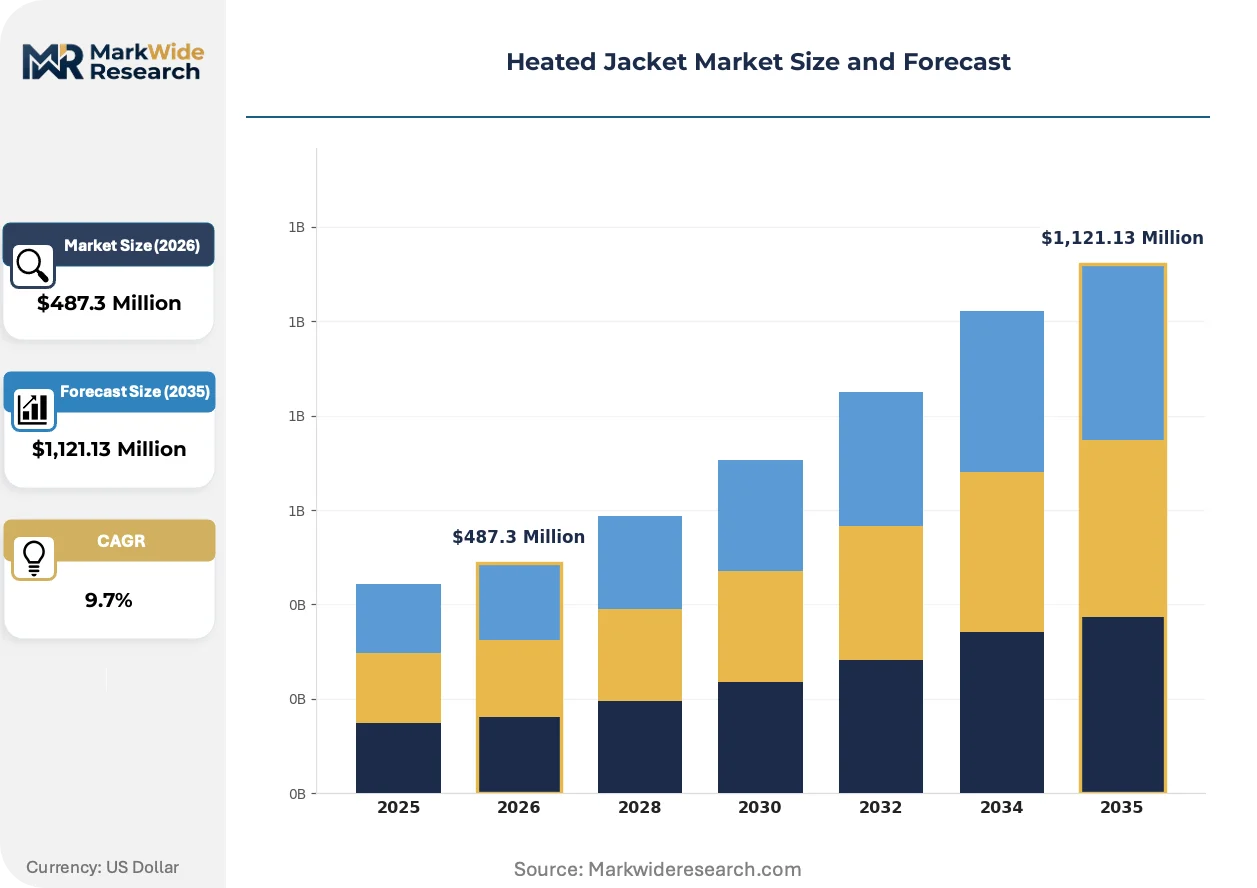
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable Battery, Plug-in, USB-powered, Hybrid Material: Polyester, Nylon, Cotton, Fleece Feature: Water-resistant, Lightweight, Breathable, Quick-drying End User: Outdoor Enthusiasts, Construction Workers, Winter Sports Athletes, Casual Users |
| Companies Covered | Ororo, Makita, Milwaukee, Ravean, Gerbing, DeWalt, Venture Heat, Columbia Sportswear, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heated Jacket Market Emerging Trajectories
Component convergence is compressing heating element profiles and controller footprints while extending runtime expectations. Manufacturers compete on seamless integration rather than raw thermal output.
Graphene-infused conductive films are miniaturizing heating zone controllers to sub-2mm thicknesses. Alpine and backcountry apparel brands adopt these for flexible panel placement without bulk penalty. This is miniaturizing the trade-off between heating coverage and garment drape, enabling slimmer silhouettes in premium outdoor segments.
The EU F-Gas Regulation and parallel chemical restrictions under REACH are phasing out certain hydrophobic treatments in shell fabrics. Manufacturers reformulate DWR coatings to maintain water repellency without restricted fluorocarbons. Outdoor and workwear brands with European distribution face reformulation costs that compress near-term margins.
Employer direct-purchase programs are displacing individual worker reimbursement models in American construction and logistics. Safety managers negotiate fleet pricing with tool-platform vendors. This concentrates volume with ecosystem-integrated suppliers and narrows consideration sets for independent apparel brands.
Heated Jacket Market Segmentation
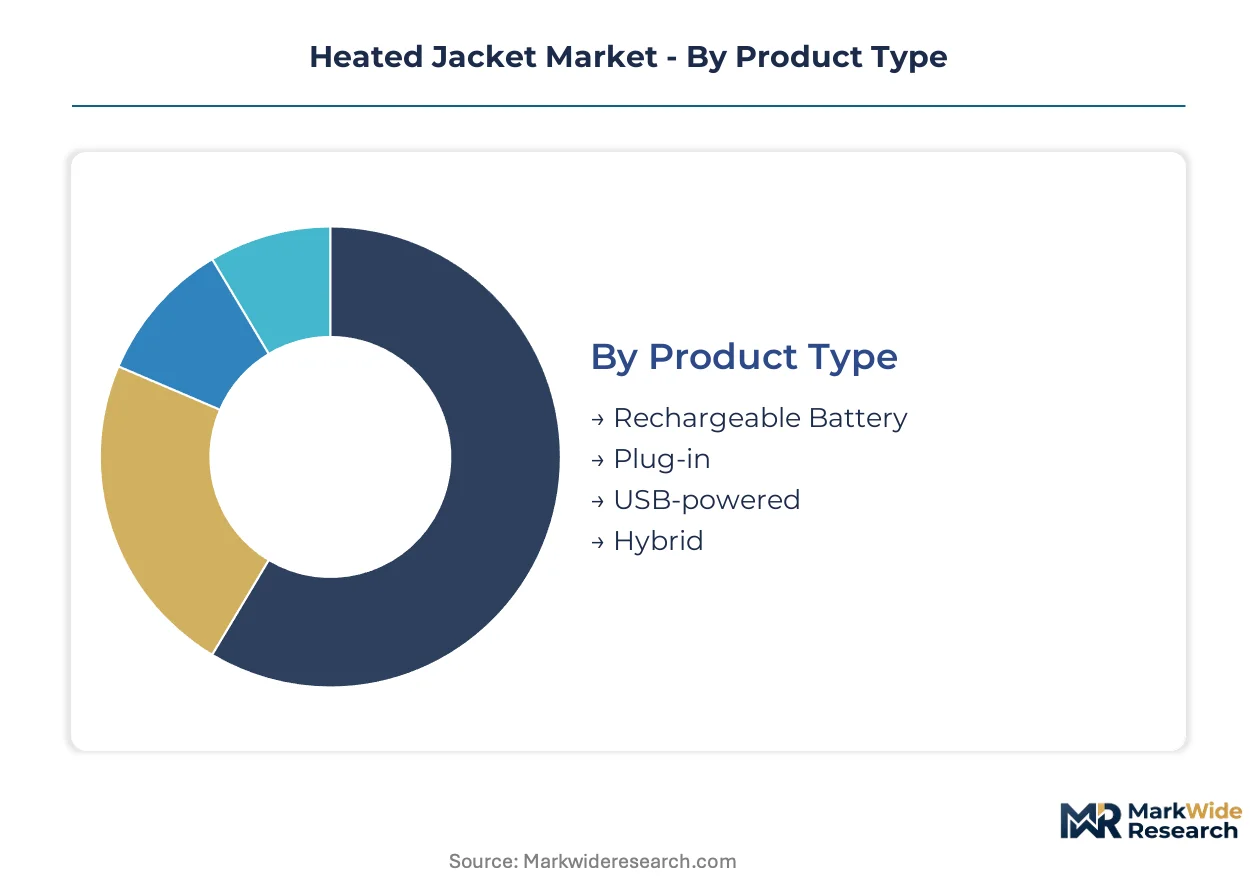
Segmentation in heated jackets determines channel placement and margin architecture. Product type dictates battery ecosystem compatibility, while end-user classification separates professional procurement from retail browsing.
Product Type:
Rechargeable battery variants dominate construction supply channels through tool-platform bundling, while USB-powered units capture urban commuter sales via electronics retailers.
- Rechargeable Battery:Lithium-ion packs operating at 7.4V to 12V integrate with cordless tool platforms. Construction workers in the United States and Germany drive replacement demand through employer-funded safety programs.
- USB-powered:Draws from standard power banks or vehicle ports. Urban commuters in China and casual users in Germany favor this format for smartphone ecosystem compatibility and lower entry cost.
- Plug-in:Tethers to fixed power sources for stationary warming applications.
- Hybrid:Combines battery and plug-in flexibility for extended runtime scenarios.
By volume, Rechargeable Battery leads. By growth pace, USB-powered is climbing the fastest.
Material:
Cost tiers separate professional-grade durability from recreational comfort priorities, with shell construction directly impacting wash-cycle longevity and thermal retention.
- Polyester:Dominates workwear applications for abrasion resistance and moisture-wicking performance. OSHA-compliant employers in the United States specify polyester shells for construction site durability.
- Nylon:Commands alpine and backcountry premium positioning for tear strength and DWR coating compatibility. Winter sports athletes in Germany and Japan prioritize nylon for packability and weather protection.
- Cotton:Serves casual urban segments prioritizing aesthetic familiarity over technical performance.
- Fleece:Provides mid-layer insulation in hybrid jacket systems for outdoor enthusiasts.
Polyester captures the largest unit volumes. Nylon generates the highest per-unit margins.
Feature:
Application context determines which functional attributes become purchase triggers, with professional buyers prioritizing durability certifications and recreational users emphasizing packability.
- Water-resistant:Hydrophobic shell treatments meeting EN 343 or equivalent standards. Construction workers in wet climates and winter sports athletes require this for sustained outdoor exposure.
- Lightweight:Sub-1kg total system weight achieved through graphene heating elements. Alpine rescue services and backcountry skiers in Japan and Germany drive specification demand.
- Breathable:Moisture vapor transmission for high-exertion activities.
- Quick-drying:Reduces downtime between wash cycles for daily-use professional garments.
Water-resistant specifications anchor professional procurement. Lightweight features are gaining share fastest in premium outdoor channels.
End User:
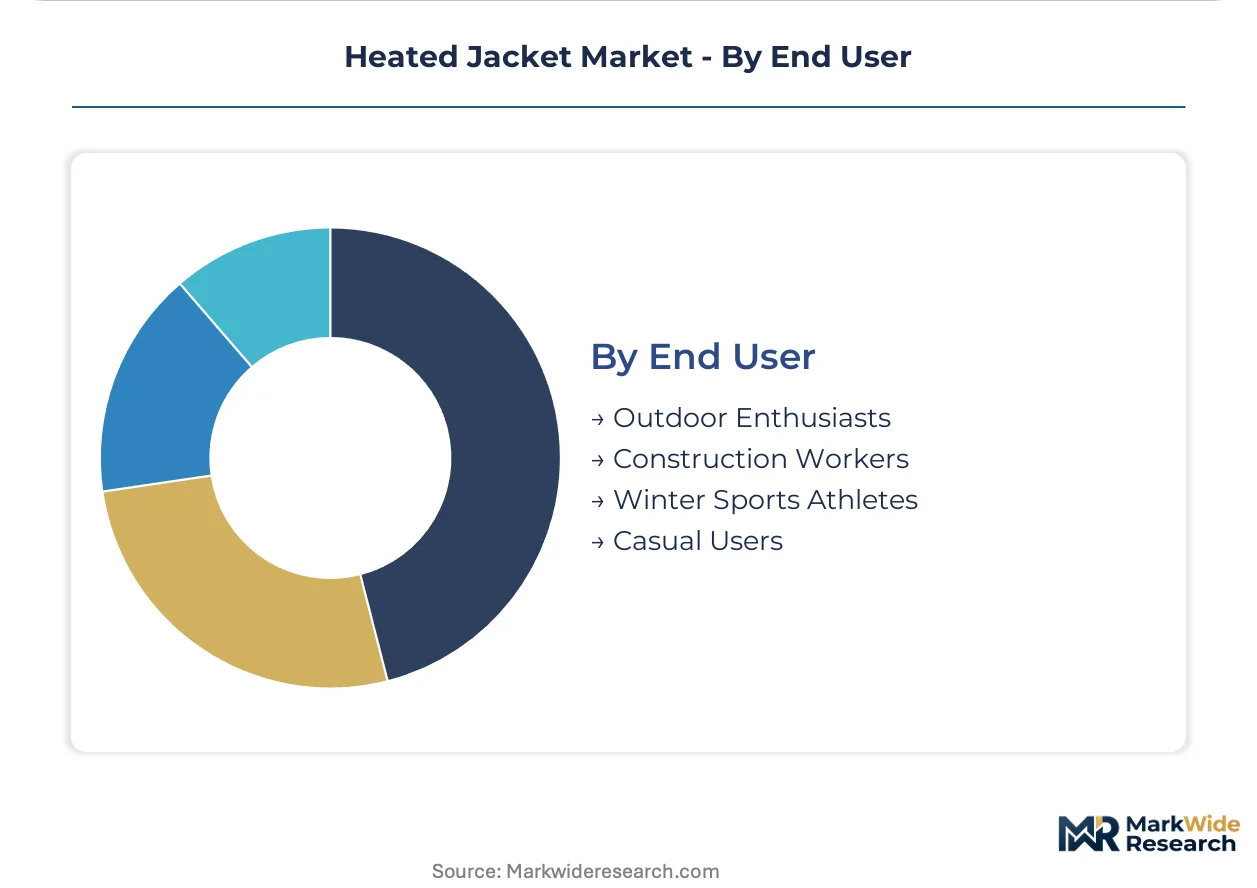
Customer type bifurcates the market between employer-funded safety equipment and individual discretionary purchases, with procurement processes and price sensitivity diverging sharply.
- Construction Workers:Employer-mandated heated workwear under cold stress protection protocols. United States logistics and building trades drive fleet purchasing through direct vendor relationships.
- Outdoor Enthusiasts:Individual buyers prioritizing heating zone flexibility and battery runtime. China's expanding winter recreation infrastructure and Germany's hiking culture support volume demand.
- Winter Sports Athletes:Specialized requirements for visible heating zones and extended runtime.
- Casual Users:Urban commuters seeking smartphone-compatible power solutions.
Construction Workers represent the largest revenue pool. Casual Users are expanding most quickly as USB-C standardization broadens addressable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters for heated apparel concentrate in China, Germany, and the United States, with battery pack assembly and textile-electronics integration driving regional specialization patterns. Cold-weather labor protection mandates and winter recreation infrastructure investments determine demand intensity across national markets.
United States
Construction and logistics employers drive fleet procurement through OSHA cold stress compliance programs. FCC certification requirements for battery controllers create regulatory friction for new entrants. Milwaukee and Chicago anchor industrial distribution networks serving the Great Lakes building trades.
Germany
Industrial safety distributors prioritize CE-marked workwear for manufacturing and outdoor labor sectors. The EU F-Gas Regulation pressures shell fabric suppliers to reformulate hydrophobic treatments. Bavaria's alpine equipment manufacturers specialize in lightweight heating systems for mountain rescue applications.
China
Winter recreation infrastructure expansion and outdoor labor protection mandates generate dual demand streams. GB standards for electrical safety govern domestic product certification. The Yangtze River Delta hosts integrated supply chains combining lithium-ion cell production with textile manufacturing.
Japan
METI energy efficiency guidelines shape battery pack specifications for professional workwear. Winter sports culture in Hokkaido and Nagano prefectures supports premium outdoor segment demand. Osaka-based distributors maintain relationships with industrial safety suppliers across East Asian markets.
Canada
Provincial occupational health regulations in Alberta and Ontario mandate cold-weather protective equipment for energy and construction workers. Health Canada electrical safety standards parallel FCC requirements with additional cold-climate performance testing. Toronto and Calgary serve as procurement hubs for employer-funded heated workwear programs.
Heated Jacket Market Vendor Landscape
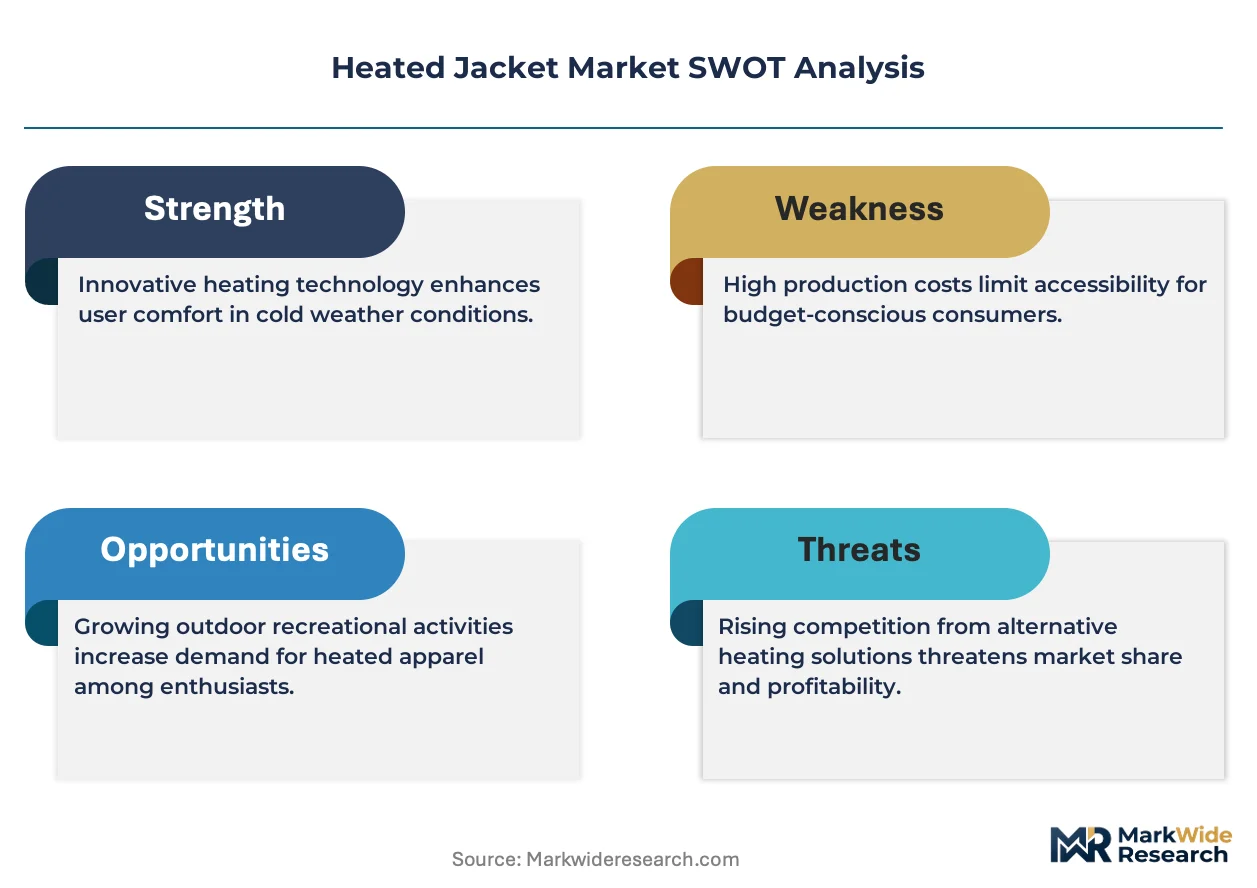
Concentration sits with tool-platform manufacturers leveraging existing battery ecosystems to capture apparel attachment revenue. The vendor base spans three tiers: integrated tool-apparel conglomerates, pure-play heated apparel specialists, and outdoor brands adding thermal technology to existing lines. Strategic moves center on cross-platform battery interoperability negotiations and direct-purchase program cultivation with construction employers.
Among tool-platform integrators, Milwaukee, DeWalt, and Makita exemplify the ecosystem-lock-in archetype. These manufacturers anchor professional procurement channels through construction supply chain relationships and voltage-standard dominance. Pure-play specialists including Ororo, Ravean, and Venture Heat occupy positions serving recreational users and urban commuters outside tool-platform loyalty networks. Columbia Sportswear represents outdoor brand diversification into heated apparel, leveraging existing retail distribution for seasonal thermal product placement.
| Leading Market Players |
|---|
| Ororo |
| Makita |
| Milwaukee |
| Ravean |
| Gerbing |
| DeWalt |
| Venture Heat |
| Columbia Sportswear |
| Bosch |
| Others |
Supply Flow & Price Mechanics
Eight-to-fourteen-week FCC certification timelines for battery controllers compress working capital cycles and concentrate pricing power with tool-platform incumbents who amortize compliance costs across established volumes. This lead-time band shapes how supply chain structure reinforces margin architecture across professional and recreational segments.
Pricing Analysis
OSHA cold stress guidelines dictate the pricing tier structure across employer-funded procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked alpine rescue systems from polyester workwear and USB-powered commuter units. Cost compression in economy tiers is intensifying because lithium-ion cell volatility forces margin trade-offs. Construction employers show least price sensitivity due to mandated safety budgets, while casual urban commuters exhibit highest elasticity.
Supply Chain Analysis
Inventory cycles for graphene-infused conductive films and lithium-ion cell packs hinge on Yangtze River Delta integration capacity. China, Germany, and the United States anchor textile-electronics manufacturing clusters. Raw material flows draw from South Korean cathode suppliers, Japanese controller component specialists, and domestic polyester weavers. Single-source vulnerability concentrates in qualified textile-electronics integration labs. Distribution runs through construction supply chains, industrial safety distributors, and outdoor specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as employer-funded replacement cycles normalize post-pandemic recreational demand collapse. Winter recreation infrastructure investment in China and Germany provides the cyclical uplift.
For Market Incumbents: Consolidate battery ecosystem lock-in through deeper M12 and M18 platform bundling with construction supply chains. Expand in-house textile-electronics integration capabilities to reduce dependency on limited qualified labs. Cross-platform battery interoperability negotiations present the primary defensive lever against pure-play apparel specialists. For New Entrants and Emerging Players: Differentiate on USB-C power delivery standardization to capture smartphone-centric urban commuters outside tool-platform loyalty networks. Target Germany's underpenetrated industrial safety distributor relationships where CE marking competence creates entry barriers. Alpine rescue and emergency services specifications offer white-space positioning through EN standard certification. For Investors and Strategic Acquirers: Long-term, this sits as a safety-equipment consolidation play because employer direct-purchase programs concentrate volume with ecosystem-integrated suppliers. Acquisition targets should display captive battery platform relationships or specialized certification capabilities. Watch for OSHA guideline expansion into logistics and warehousing as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Lock-in construction employers through M12 and M18 ecosystem bundling. |
| CE Marking Pathway Investment | Unlock German industrial safety distributor channels for non-European brands. |
| Textile-Electronics Integration Buildout | Reduce outsourced wash-cycle durability testing dependency. |
| Alpine Rescue Certification Program | Capture premium positioning through EN standard compliance. |
| USB-C Power Delivery Launch | Broaden addressable demand among smartphone-centric urban commuters. |
Methodological Framework
Desk research of customs trade records, FCC certification filings, and construction safety procurement databases preceded structured interviews with heated apparel product managers, industrial safety distributors, textile-electronics integration specialists, and construction fleet procurement officers. Primary fieldwork combined with secondary validation from OSHA guideline documentation, EU F-Gas regulatory texts, and GB standards publications. Bottom-up volume modeling triangulated against top-down category spend analysis.
Variance decomposition across product type, material grade, end-user classification, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included battery energy density improvement curves, employer safety program adoption rates, and winter recreation infrastructure investment flows.
Material uncertainties — lithium-ion cost volatility, certification timeline extensions, and platform interoperability standardization — sit outside the modeled envelope. Forecasts reflect documented assumptions on employer mandate expansion and recreational demand normalization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Brazil Pet Clothing Market
Apparel & Footwear
Multiple Toe Socks Market
Apparel & Footwear
Europe Headwear Market
Apparel & Footwear
North America Jeans Market
Apparel & Footwear
Seamless Underwear for Men Market
Apparel & Footwear
Outdoor Apparel and Accessories Market
Apparel & Footwear
Polo Shirt Market
Apparel & Footwear
Compression and Shapewear Market
Apparel & Footwear
Women's Tights and Leggings Market
Apparel & Footwear
Men's Coats and Jackets Market
Apparel & Footwear
Gymnastic Leotards Market
Apparel & Footwear
Women's Coats and Jackets Market
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
Chest Bags Market
Apparel & Footwear
Lingerie Market
Apparel & Footwear
Compression Wear and Shapewear Market