
 Global Leggings Market | 2026-2036
Global Leggings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Leggings Market Outlook
Capital-intensity divergence between vertically integrated manufacturers and asset-light digital brands is bifurcating competitive returns across the Global Leggings Market. Lululemon Athletica leverages its proprietary fabric development and owned retail footprint to sustain margin capture in the premium activewear tier. Gymshark competes through influencer-native marketing and limited-drop inventory models that minimize working capital exposure.
Leggings are form-fitting lower-body garments engineered with elastomeric fibers, typically containing 15-30% spandex content to deliver four-way stretch recovery and moisture-wicking performance for athletic, casual, and therapeutic applications. The activewear and compression categories anchor volume demand as gym participation and clinical recovery protocols expand. Nylon-spandex blends dominate technical performance segments where abrasion resistance and shape retention command price premiums, while cotton-polyester compositions occupy the leisurewear mass market where breathability and cost efficiency drive purchasing decisions.
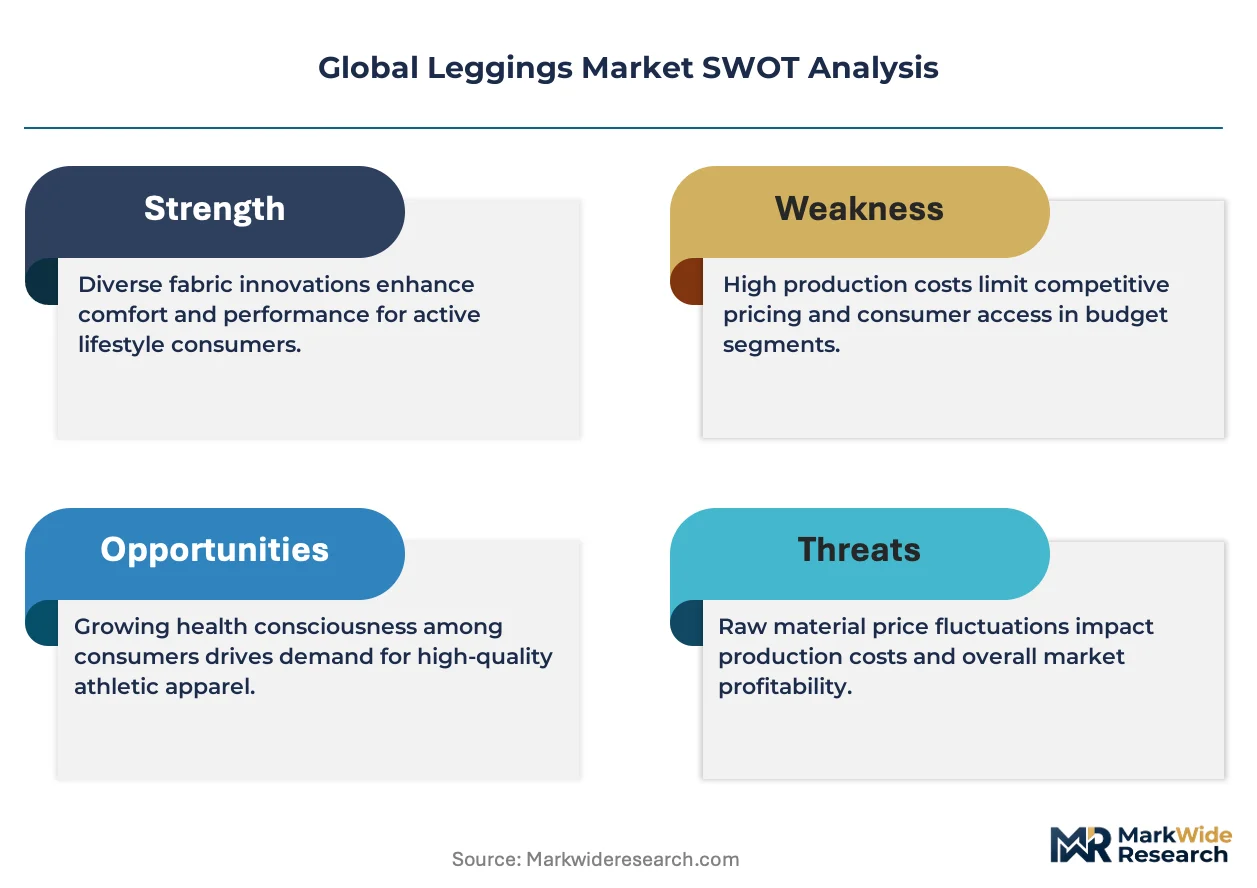
Regulatory scrutiny from REACH in Europe, California's Proposition 65 enforcement, and China's GB standards for textile safety are elevating compliance costs for synthetic dye processes and chemical finishing agents. The EU Green Deal's circular textiles requirements will force reformulation of virgin polyester dependencies across export-oriented supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to absorb certification investments or redirect sourcing toward recycled fiber platforms.
Market Dynamics
Athleisure normalization among remote workers has permanently expanded leggings consumption beyond gym contexts into professional and domestic settings, forcing brands to engineer fabrics that satisfy both performance metrics and workplace-appropriate aesthetics.
Growth Catalysts
- REACH chemical compliance:ECHA's tightened restrictions on azo dyes and formaldehyde-based finishing agents are accelerating adoption of certified recycled polyester streams among EU-exporting suppliers.
- Compression therapy protocols:Clinical rehabilitation programs in Germany and Japan now prescribe medical-grade leggings for post-surgical recovery, opening institutional procurement channels.
- Elastane recycling infrastructure:Carbios enzymatic depolymerization facilities in France are creating closed-loop feedstock for virgin-quality spandex, reducing virgin petrochemical dependency.
Market Restraints
- Spandex supply concentration:Over 70% of global elastane fiber originates from Chinese petrochemical complexes, exposing brands to feedstock volatility and logistics disruption.
- REACH registration costs:ECHA's substance registration fees for novel bio-based elastomers exceed €100,000 per formulation, blocking SME material innovation.
- Cotton price volatility:Drought-induced supply shocks in Texas and Maharashtra are compressing margins on natural-fiber leisurewear lines.
Strategic Opportunities
- India's PLI textile scheme:Production-linked incentives for man-made fiber apparel are attracting contract manufacturers to Gujarat and Tamil Nadu clusters.
- Biometric-integrated fabrics:Convergence of conductive yarn weaving with micro-LED embroidery enables muscle-oxygen monitoring for elite athletic segments.
- Direct-to-consumer microfactories:On-demand knitting automation in Los Angeles and Berlin cuts inventory risk and enables sub-48-hour customization.
Industry Challenges
- Seamless knitting technician scarcity:Santoni machine programming expertise concentrates in Northern Italy, constraining capacity expansion elsewhere.
- Dual certification timelines:Simultaneous OEKO-TEX and bluesign audits extend product launch cycles by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Leggings Market |
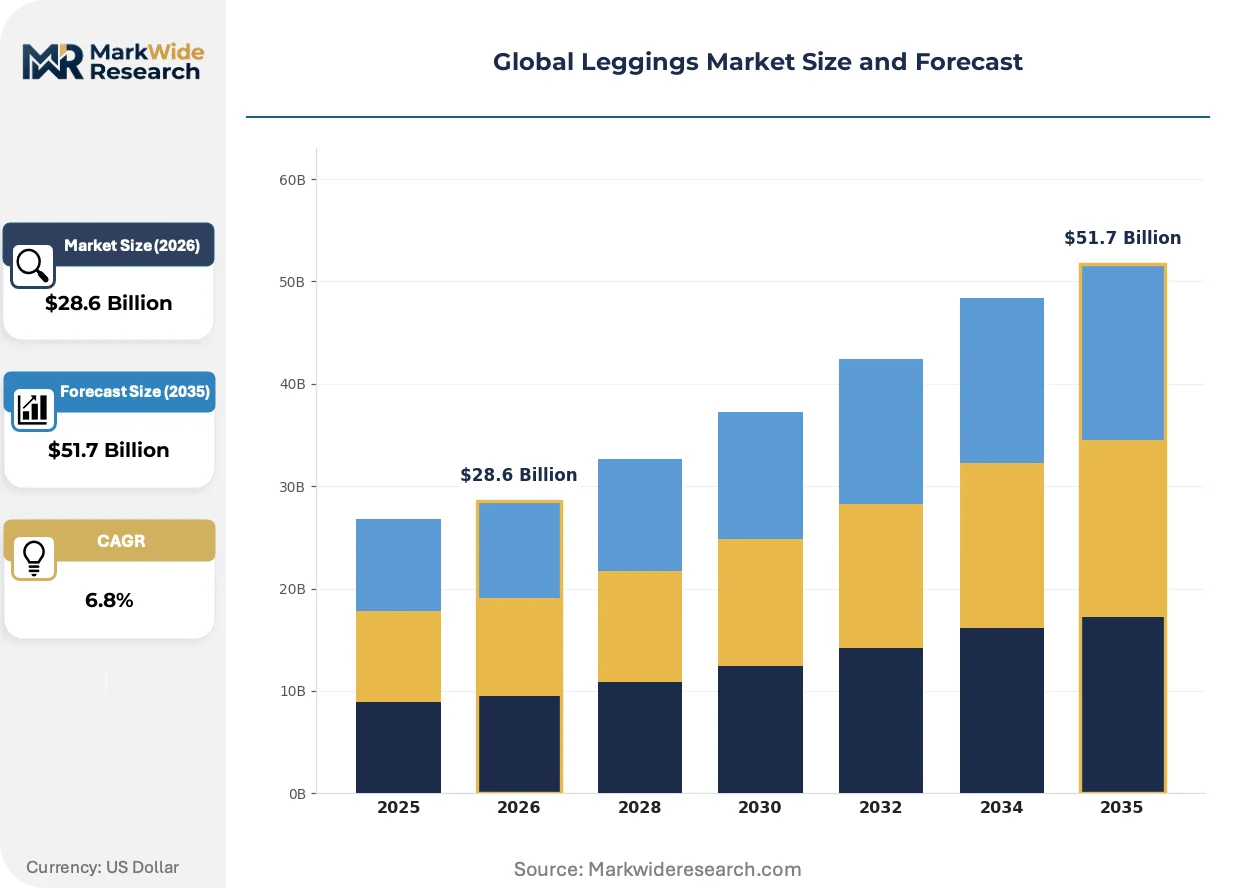
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activewear, Leisurewear, Compression, Fashion Material: Spandex, Cotton, Polyester, Nylon End User: Women, Men, Children, Athletes Distribution Channel: Online, Retail Stores, Specialty Stores, Supermarkets |
| Companies Covered | Lululemon Athletica, Nike, Adidas, Under Armour, Puma, Athleta, Alo Yoga, Fabletics, Gymshark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Leggings Market Strategic Shifts
Material science advances and regulatory pressure on synthetic microfiber shedding are compressing development cycles and forcing concurrent innovation across chemistry, machinery, and end-of-life infrastructure.
Seamless knitting technology is miniaturizing. Whole-garment production on single-cylinder machines eliminates cut-and-sew labor while enabling anatomical compression mapping. Boutique fitness studios in New York and London now specify seamless construction as a baseline requirement. This capability is miniaturizing the competitive advantage once held by large-scale cut-and-sew operations.
EU Green Deal circular textiles mandates will require recycled content minimums and fiber-to-fiber recyclability disclosures by 2030. The regulation forces reformulation of virgin polyester dependencies and accelerates chemical recycling partnerships. Premium activewear brands with EU exposure are pre-positioning take-back programs to secure compliance headroom.
Subscription-based activewear rotation models are displacing outright ownership among urban millennials. Rent the Runway and specialist competitors now offer leggings-as-a-service with hygiene certification and size-flexible exchanges. This consumption-pattern shift concentrates most visibly in coastal US metropolitan markets where closet-space constraints and sustainability signaling overlap.
Global Leggings Market Segmentation
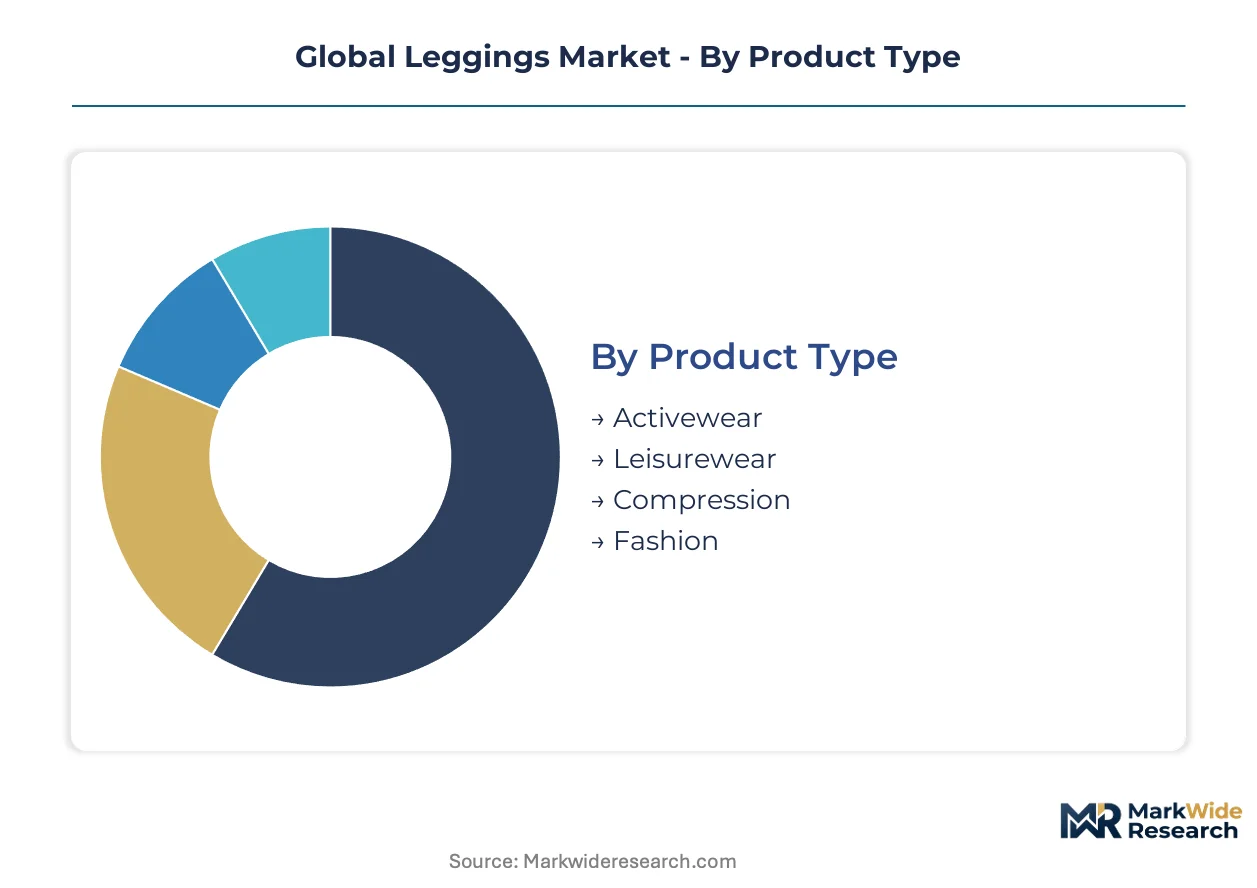
Leggings manufacturers engineer distinct product architectures for each segment, with fiber composition and construction method directly determining which retail channels can deliver margin-appropriate price points. Channel economics force brands to prioritize certain segments over others when allocating limited production capacity.
Product Type:
Channel mix varies sharply across product types, with performance-oriented segments flowing through specialty fitness retailers while mass-market categories dominate supermarket and online channels.
- Activewear:Engineered with 20-30% spandex content for four-way stretch and moisture-wicking performance. Demand concentrates in the United States through direct-to-consumer brands and specialty fitness retailers like Equinox and Barry's Bootcamp, where consumers pay premiums for proprietary fabric technologies and durability guarantees.
- Compression:Medical-grade and athletic compression garments utilize graduated knit structures with 25-35% elastane for targeted pressure distribution. Germany and Japan now prescribe these for post-surgical recovery, opening institutional procurement channels through hospital systems and physical therapy clinics.
- Leisurewear:Cotton-polyester blends prioritize breathability and cost efficiency for domestic and casual workplace settings.
- Fashion:Trend-driven designs with seasonal prints and embellishments target fast-fashion retailers and online marketplaces.
Activewear dominates installed base. Compression is where expansion concentrates.
Material:
Cost tier stratification across material categories determines which brands can compete at premium versus mass-market price points.
- Spandex:Elastomeric fiber delivering 500-700% stretch recovery, typically blended at 15-30% with base fibers. Over 70% of global supply originates from Chinese petrochemical complexes, exposing brands to feedstock volatility and forcing diversification into bio-based alternatives.
- Nylon:Polyamide fiber prized for abrasion resistance and shape retention in technical performance segments. Demand clusters in premium activewear lines where consumers prioritize longevity over initial purchase price.
- Polyester:Dominates volume production through recycled PET streams, driven by EU Green Deal circular textiles mandates.
- Cotton:Natural fiber facing margin pressure from drought-induced supply shocks in Texas and Maharashtra growing regions.
Polyester commands volume leadership. Spandex is climbing the fastest on a value basis.
End User:
Volume concentration and margin profile diverge significantly across demographic segments, with women's lines subsidizing development costs for emerging categories.
- Women:Historical anchor segment with broad product architecture spanning performance, leisure, and fashion applications. The athleisure normalization among remote workers has permanently expanded consumption into professional settings, forcing fabric engineering that satisfies both performance metrics and workplace aesthetics.
- Athletes:Elite and professional segments demand biometric-integrated fabrics with conductive yarn weaving and micro-LED embroidery for muscle-oxygen monitoring. This segment justifies premium pricing through measurable performance advantages.
- Men:Emerging category with growth driven by cross-training adoption and yoga participation normalization.
- Children:Volume play with lower per-unit margins, dependent on seasonal back-to-school purchasing cycles.
Women's lines dominate installed base. Athletes represent the steepest expansion trajectory.
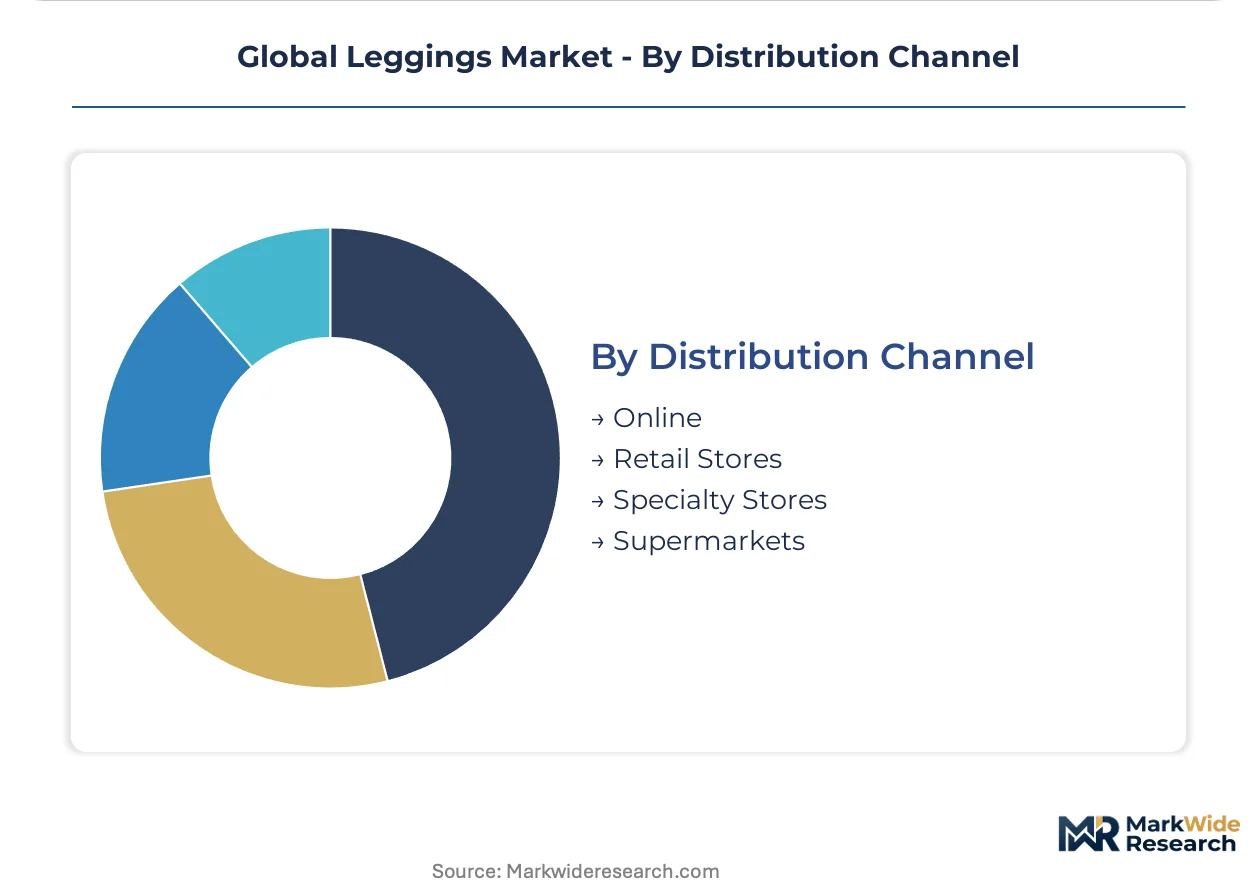
Distribution Channel:
Customer acquisition economics and inventory risk exposure vary dramatically across channel types, favoring asset-light models for new entrants.
- Online:Direct-to-consumer platforms enable sub-48-hour customization through on-demand knitting automation in Los Angeles and Berlin microfactories. Gymshark and similar digital-native brands minimize working capital exposure through limited-drop inventory models and influencer-native marketing.
- Specialty Stores:Curated environments like Lululemon's owned retail footprint sustain margin capture through proprietary fabric development and experiential service.
- Retail Stores:Department store and multi-brand athletic retailers offer broad reach with compressed margins and inventory risk.
- Supermarkets:Mass-market penetration for basic leisurewear lines with minimal brand differentiation.
Online channels dominate new customer acquisition. Specialty stores concentrate premium margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in the United States where direct-to-consumer brands command margin premiums, while contract manufacturing margins compress in Asian export hubs facing compliance cost escalations.
United States
Athleisure normalization among remote workers has permanently expanded leggings consumption into professional settings. California's Proposition 65 enforcement elevates compliance costs for synthetic dye processes. Los Angeles microfactories deploying on-demand knitting automation enable sub-48-hour customization for digital-native brands.
Germany
Clinical rehabilitation programs now prescribe medical-grade compression leggings for post-surgical recovery, opening institutional procurement channels. ECHA's REACH restrictions on azo dyes accelerate certified recycled polyester adoption among domestic brands. Northern Italy's Santoni machine programming expertise constrains seamless knitting capacity expansion elsewhere.
China
Over 70% of global elastane fiber originates from domestic petrochemical complexes, exposing brands to feedstock volatility. GB standards for textile safety regulate chemical finishing agents in export-oriented supply chains. Guangdong and Zhejiang clusters dominate cut-and-sew operations for mass-market leisurewear lines.
India
Production-linked incentives for man-made fiber apparel attract contract manufacturers to Gujarat and Tamil Nadu clusters. BIS certification requirements for textile safety create compliance barriers for SME material innovation. Mumbai and Bangalore house emerging direct-to-consumer brand headquarters targeting domestic athleisure demand.
Japan
Physical therapy clinics prescribe graduated compression garments for athletic recovery and post-surgical protocols. METI standards for textile safety govern chemical content in domestic distribution. Osaka-based knitting technology specialists supply seamless construction equipment to regional apparel manufacturers.
Global Leggings Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Global Leggings Market. Vertically integrated manufacturers with proprietary fabric development command premium positioning, while asset-light digital brands minimize working capital through limited-drop inventory models. The competitive structure bifurcates into premium activewear specialists, mass-market athletic licensors, and influencer-native direct-to-consumer entrants. Dominant competitive moves include strategic partnerships with recycled fiber platforms and geographic expansion into India's PLI-subsidized manufacturing clusters.
Within the premium activewear tier, Lululemon Athletica and Alo Yoga exemplify archetypes combining proprietary material innovation with experiential retail positioning. Gymshark occupies a distinct position among digital-native entrants leveraging influencer-native marketing architectures. These three companies represent the spectrum from owned-retail margin capture to asset-light customer acquisition models reshaping competitive dynamics.
| Leading Market Players |
|---|
| Lululemon Athletica |
| Nike |
| Adidas |
| Under Armour |
| Puma |
| Athleta |
| Alo Yoga |
| Fabletics |
| Gymshark |
| Others |
Value Chain & Pricing Dynamics
Sixty-day inventory cycles at Los Angeles microfactories compress working capital exposure for direct-to-consumer brands while concentrating margin capture among vertically integrated manufacturers with captive spandex supply. This lead-time compression reinforces pricing power asymmetry between asset-light digital entrants and established players with backward integration into proprietary fabric development.
Pricing Analysis
The customization-premium spread separates sub-48-hour configured-to-order leggings from standard inventory, with on-demand knitting automation enabling price premiums through size-flexible exchanges and hygiene certification. Three-tier pricing structure across premium activewear, standard athletic, and economy leisurewear levels reflects differentiation by certification grade and brand positioning. Pricing pressure stems from cotton price volatility in Texas and Maharashtra growing regions compressing margins on natural-fiber lines. Mass-market supermarket channels exhibit highest price sensitivity, while specialty fitness retailers sustain lowest sensitivity through proprietary technology and experiential service.
Supply Chain Analysis
Strait of Malacca transit risk exposes over 70% of global elastane fiber originating from Chinese petrochemical complexes to logistics disruption and feedstock volatility. Manufacturing concentration clusters in Guangdong and Zhejiang for cut-and-sew operations, with emerging diversification into Gujarat and Tamil Nadu under India's PLI textile scheme. Raw material dependencies center on spandex, nylon, and recycled PET streams, with chemical recycling partnerships accelerating under EU Green Deal mandates. Single-source vulnerability in Santoni machine programming expertise constrains seamless knitting capacity expansion. Distribution runs through direct-to-consumer platforms, specialty fitness retailers, and institutional procurement channels for medical-grade compression garments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hospital systems and physical therapy clinics prescribing medical-grade compression, fragmenting historically brand-driven purchasing. This institutional procurement shift elevates compliance certification and volume contracting leverage over traditional marketing differentiation.
For Market Incumbents: Shield premium positioning by deepening backward integration into proprietary fabric development and securing OEKO-TEX plus bluesign dual certification ahead of EU circular textiles mandates. Accelerate capacity addition in India's PLI-subsidized clusters to offset Chinese petrochemical supply concentration. Channel control through owned retail footprints sustains margin capture against influencer-native digital entrants.
For New Entrants and Emerging Players: Bluesign certification fast-track opens institutional procurement channels in Germany and Japan where medical-grade compression prescriptions are expanding. Men's athleisure remains underpenetrated relative to women's lines, offering white-space targeting through cross-training and yoga participation normalization. Direct-to-consumer microfactory deployment in Berlin or Los Angeles enables sub-48-hour customization with minimal working capital exposure.
For Investors and Strategic Acquirers: Long-term, this sits as a circular infrastructure play because chemical recycling partnerships and enzymatic depolymerization facilities will determine feedstock security across the projection horizon. Acquisition targets should combine seamless knitting technical capability with established take-back program infrastructure. The signal to watch is extended producer responsibility framework implementation accelerating fiber-to-fiber recyclability requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Recycling Partnership | Carbios facilities in France create closed-loop spandex feedstock reducing virgin petrochemical dependency. |
| Dual Certification Investment | Simultaneous OEKO-TEX and bluesign audits extend launch cycles but secure EU market access. |
| Microfactory Geographic Expansion | On-demand knitting automation in Los Angeles and Berlin cuts inventory risk and enables customization. |
| Institutional Procurement Channel Development | Hospital system contracts in Germany and Japan open volume channels for medical-grade compression lines. |
| Biometric Fabric R&D | Conductive yarn weaving with micro-LED embroidery enables muscle-oxygen monitoring for elite athletic segments. |
Study Parameters
Initial hypotheses were tested against primary input from brand managers at direct-to-consumer activewear companies, category buyers at specialty fitness retailers, supply planners at vertically integrated manufacturers, and procurement leads at hospital systems, then refined against secondary validation. Trade data from customs records, SEC filings of publicly traded apparel companies, ECHA REACH registration databases, and EU circular textiles policy documents anchored quantitative sizing. Bottom-up channel volume estimates and top-down macroeconomic elasticity checks were triangulated to constrain forecast variance.
Variance decomposition across product type, material composition, end-user demographic, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate blending weighted by current revenue contribution. Forecast inputs incorporated spandex supply concentration risk, REACH compliance cost escalation, and athleisure normalization penetration curves among remote worker populations.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal implementation and stable elastane feedstock pricing; material deviation would warrant model refresh. Specific risks include drought-induced cotton supply shocks, ECHA substance registration fee increases blocking SME material innovation, and seamless knitting technician scarcity constraining capacity expansion. Practitioners should keep alternative scenarios live as extended producer responsibility frameworks and circular textiles mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Loungewear Market
Apparel & Footwear
India Denim Jeans Market
Apparel & Footwear
Football Jerseys Market
Apparel & Footwear
Ice Hockey Apparel Market
Apparel & Footwear
Luxury Fashion Market
Apparel & Footwear
Women's Sports and Swimwear Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Europe Headwear Market
Apparel & Footwear
Men's Coats and Jackets Market
Apparel & Footwear
Maternity Apparels Market
Apparel & Footwear
Luxury Vegan Men's Fashion Market
Apparel & Footwear
Heated Jacket Market
Apparel & Footwear
Chest Bags Market
Apparel & Footwear
North America E-Commerce Apparel Market