
 Polo Shirt Market | 2026-2036
Polo Shirt Market Size, Share, and Industry Trends Forecast 2026-2036
Polo Shirt Market Analysis
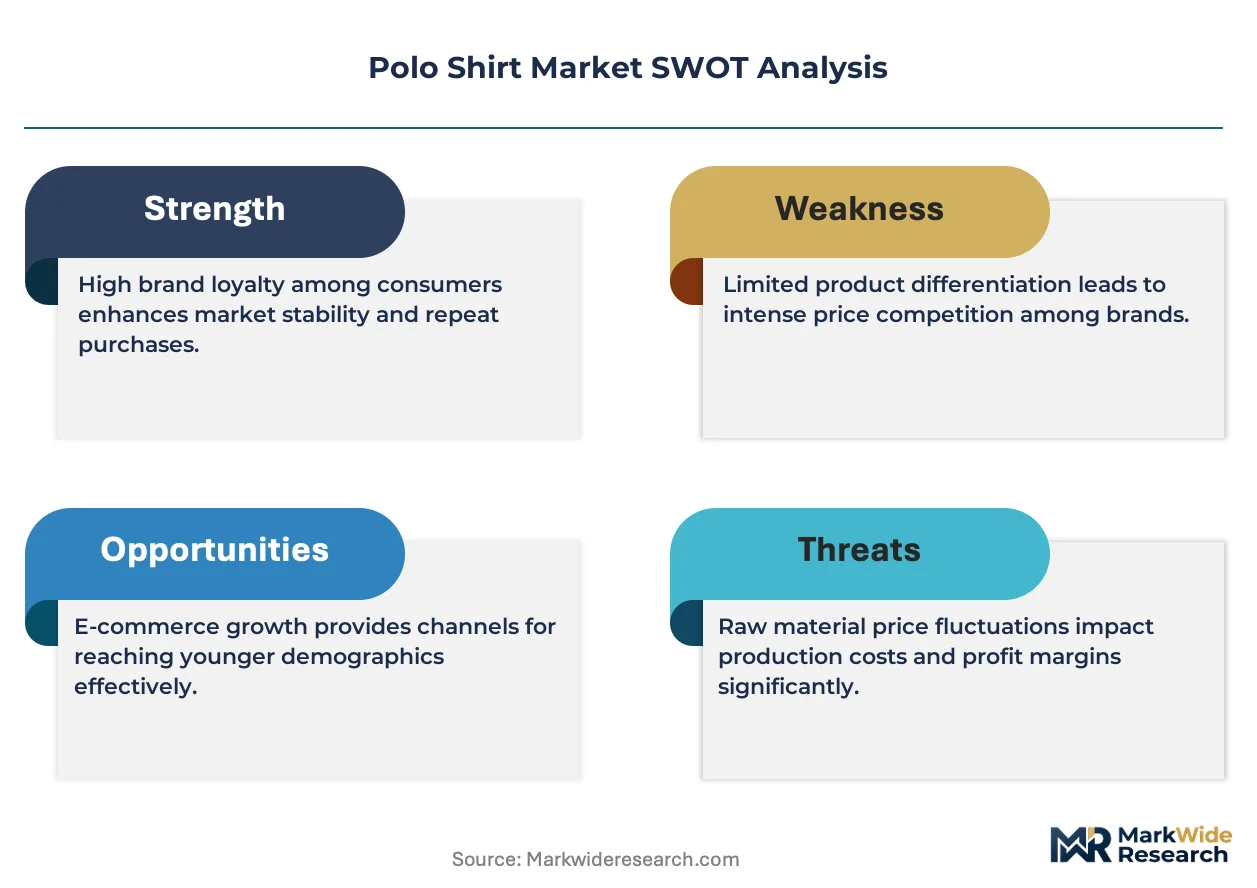
Multi-source cotton procurement is rebalancing toward vertically integrated spinners in India and Turkey as brands seek supply chain transparency. Ralph Lauren Corporation anchors its position through controlled retail distribution and archival design DNA. Lacoste competes via technical sportswear heritage translated into lifestyle collections. Hugo Boss differentiates through precision tailoring standards applied to casual silhouettes.
A polo shirt is a knitted, collared, short-sleeved upper garment typically constructed from piqué cotton or interlock jersey, featuring a placket with two or three buttons and a structured collar that distinguishes it from T-shirts. Its primary commercial purpose spans corporate identity apparel, athletic uniforms, and premium casualwear where breathability and presentability converge. Cotton piqué remains the margin-dominant material tier, while performance fabrics represent the fastest-expanding product type as moisture-wicking and UV-protection properties migrate from athletic to everyday use. Corporate clients constitute a stable demand pool, whereas online retail channels are displacing wholesale as the primary volume pathway for mid-range and budget tiers.
The EU Green Deal's textile sustainability requirements and REACH chemical restrictions are elevating compliance costs for European-bound production, while the US Federal Trade Commission's Green Guides enforce substantiation claims on organic and recycled content labeling. India's Bureau of Indian Standards certifies fiber content accuracy for domestic and export-bound polo shirt manufacturing. Stakeholders must monitor how diverging regional sustainability enforcement affects material sourcing economics and brand positioning strategies.
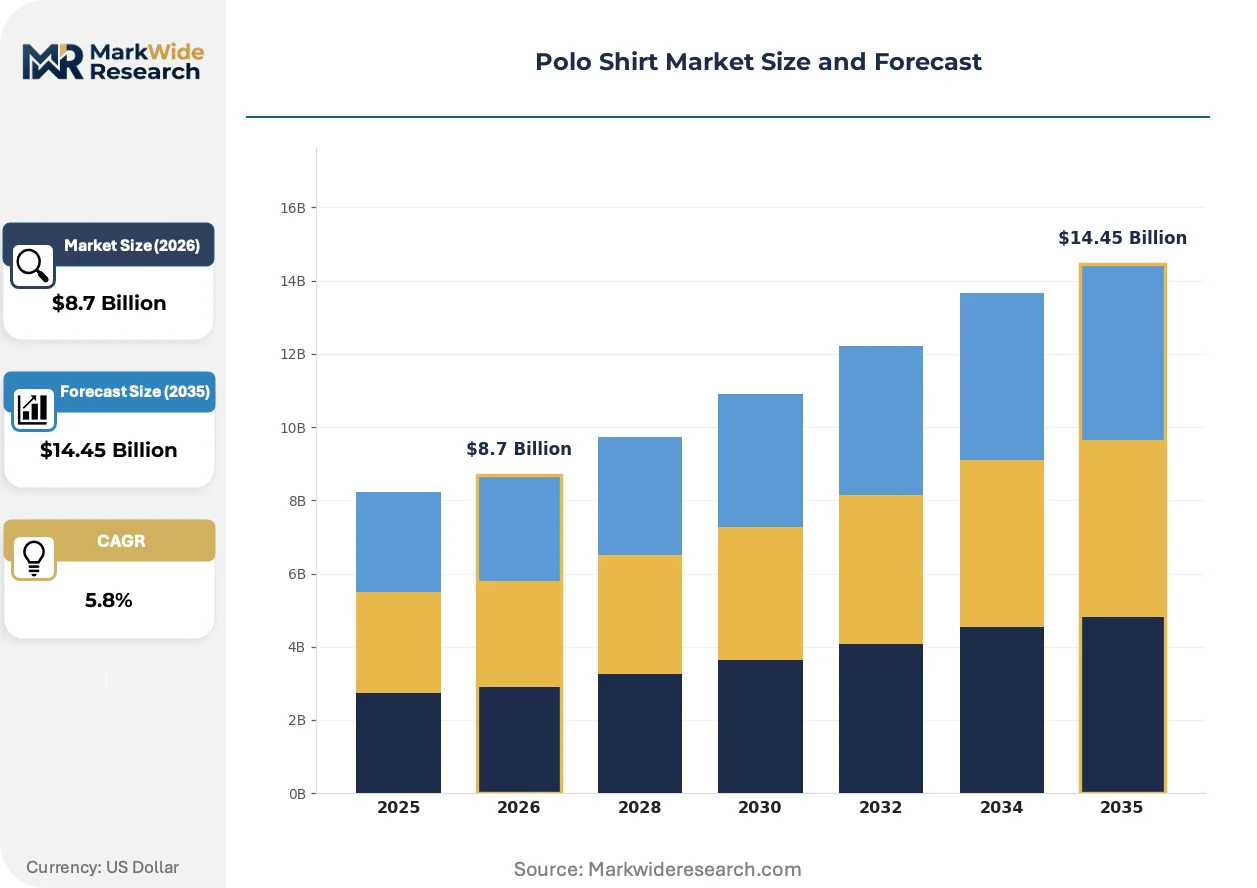
Market Dynamics
Post-pandemic corporate dress code refreshes are colliding with EU Green Deal recycled fiber mandates to restructure material sourcing economics and distribution priorities across the polo shirt value chain.
Growth Catalysts
- EU Green Deal recycled polyester mandates:European-bound production must now incorporate certified recycled content, redirecting spinner procurement toward GRS-certified supply bases in Turkey and India.
- Corporate uniform program expansion:Employers refreshing post-pandemic dress codes are standardizing polo shirts as baseline professional-casual apparel, creating contracted volume pipelines.
- Moisture-wicking fabric migration:Technical performance properties developed for athletic wear are crossing into everyday casual collections, expanding addressable use cases.
Market Restraints
- Cotton price volatility:Weather-driven supply fluctuations in Texas and Maharashtra feed directly into piqué cotton input costs, compressing margin predictability for mid-tier producers.
- REACH chemical compliance burden:ECHA restrictions on dye auxiliaries and finishing agents force reformulation cycles that extend product development timelines by 4-8 months.
- Synthetic fiber substitution threat:Performance-oriented buyers increasingly accept seamless knit polos in technical polyester blends that bypass traditional piqué construction entirely.
Strategic Opportunities
- India domestic market penetration:Bureau of Indian Standards certification alignment positions export-capable manufacturers to capture rising organized retail demand in tier-2 and tier-3 cities.
- D2C channel infrastructure:Direct-to-consumer platforms enable heritage brands to bypass wholesale margin stacking and capture first-party data on fit and color preferences.
- UV-protection property bundling:Technical fabric convergence with dermatological wellness positioning opens premium pricing tiers in sun-belt geographies.
Industry Challenges
- GRS certification backlog:Global Recycled Standard audit queue delays are stretching 14-22 weeks, forcing brands to hold inventory positions ahead of confirmed certification.
- Legacy ERP integration with traceability platforms:Batch-level fiber tracking requires middleware layers that many tier-2 cut-make-trim operators lack technical capacity to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polo Shirt Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Polyester, Blends, Performance Fabrics Customer Type: Retail Consumers, Corporate Clients, Sports Teams, Schools Distribution Channel: Online Retail, Brick-and-Mortar Stores, Wholesale, Direct Sales Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Calvin Klein, Burberry, Ralph Lauren Corporation, Gucci, Prada, Lacoste, Tommy Hilfiger, Brooks Brothers, Hugo Boss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polo Shirt Market Emerging Trajectories
Material science breakthroughs and regulatory compliance architectures are converging to redefine competitive advantage in polo shirt manufacturing and distribution.
Seamless knitting technology is expanding into polo construction from its base in performance undergarments, eliminating side-seam labor and enabling body-mapping ventilation zones. Athletic-lifestyle crossover brands are adopting this at scale for their lifestyle collections. The technology is compressing unit economics for mid-volume production runs while raising quality consistency thresholds.
EU Green Deal textile sustainability requirements are elevating mandatory due diligence across the entire value chain. The Corporate Sustainability Due Diligence Directive forces brands to map sub-tier spinner relationships and document living wage compliance. European-bound production is responding by consolidating supplier panels around vertically integrated Turkish and Indian operations with existing audit infrastructure.
Corporate procurement departments are unbundling uniform program management from traditional workwear distributors. Direct contracting with manufacturers or specialized B2B platforms is displacing multi-brand wholesale relationships in the United States. This pattern concentrates volume with suppliers capable of managing size-run complexity and logo application in-house.
Polo Shirt Market Segmentation
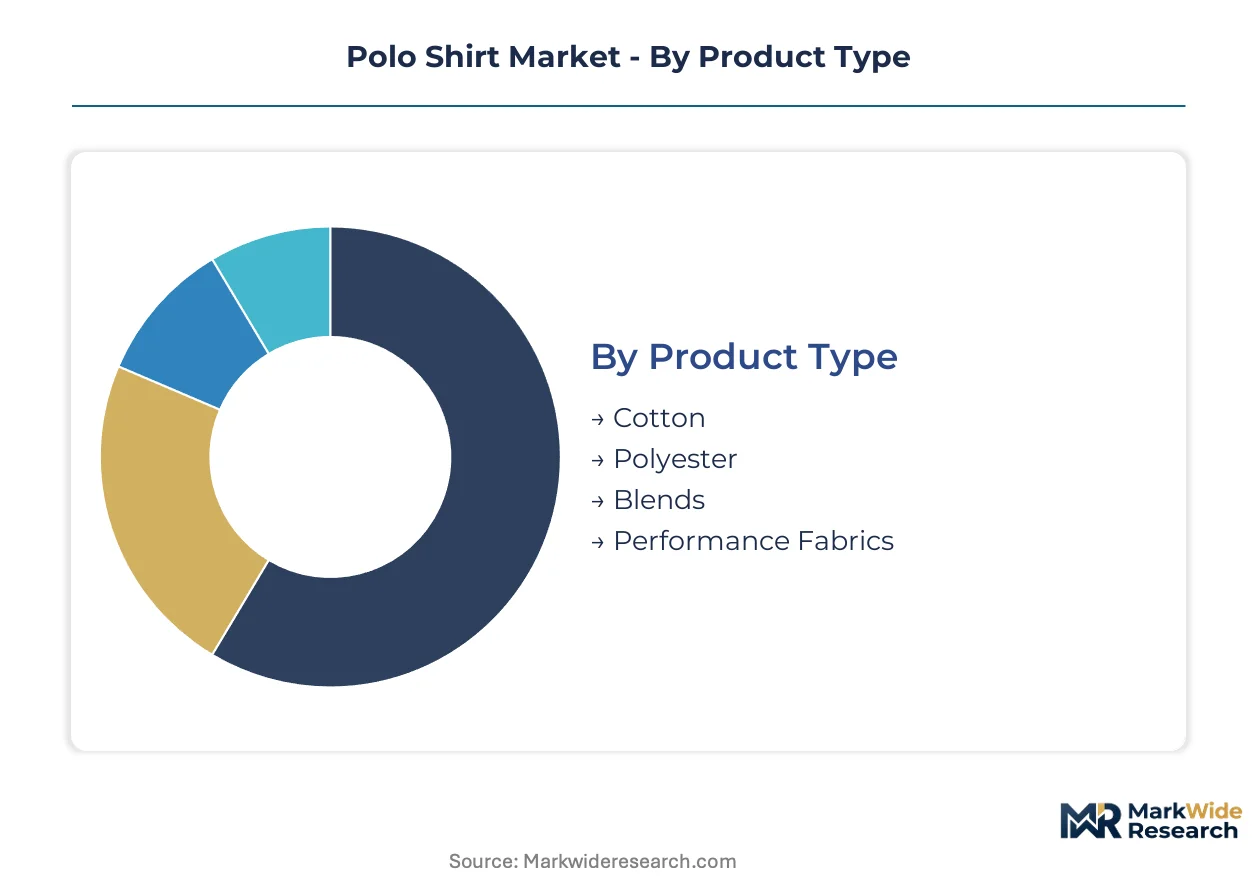
Polo shirt procurement patterns diverge sharply across material grades and buyer categories, with corporate uniform contracts and sustainability certifications now determining which segments capture margin expansion versus volume erosion.
Product Type:
Raw fiber procurement concentrates around spinner relationships in India and Turkey as brands seek GRS-certified supply bases for European-bound production.
- Cotton:Piqué-knit cotton remains the margin-dominant construction, with long-staple Egyptian and Pima varieties commanding price premiums in heritage brand collections. Texas and Maharashtra weather volatility feeds directly into input cost unpredictability for mid-tier producers.
- Performance Fabrics:Moisture-wicking polyester blends and UV-protection finishes are climbing the fastest as athletic-lifestyle crossover demand migrates technical properties into everyday casualwear. Sun-belt geographies and outdoor worker uniforms drive concentrated adoption.
- Polyester:Virgin polyester faces substitution pressure from recycled alternatives under EU Green Deal mandates, redirecting procurement toward GRS-certified supply chains.
- Blends:Cotton-polyester combinations balance cost and durability for high-volume corporate uniform programs requiring extended wash cycles.
Today's leader: Cotton. Tomorrow's challenger: Performance Fabrics.
Customer Type:
Contracted volume pipelines now separate predictable recurring demand from discretionary retail purchasing.
- Corporate Clients:Post-pandemic dress code refreshes are standardizing polo shirts as baseline professional-casual apparel, with procurement departments unbundling uniform management from traditional workwear distributors. Direct manufacturer contracting concentrates volume with suppliers capable of in-house logo application and size-run complexity.
- Retail Consumers:D2C platforms enable heritage brands to bypass wholesale margin stacking and capture first-party data on fit and color preferences, though this segment remains exposed to discretionary spending fluctuations.
- Sports Teams:Athletic uniform contracts require technical fabric certifications and rapid replenishment capabilities, favoring suppliers with seamless knitting technology.
- Schools:Institutional procurement operates on extended tender cycles with heavy emphasis on durability testing and multi-year pricing agreements.
Corporate Clients lock in volume stability. Retail Consumers offer margin expansion through data capture.
Distribution Channel:
Channel economics are restructuring as wholesale relationships lose share to platform-controlled customer relationships.
- Online Retail:First-party data on fit preferences and color demand is displacing wholesale as the primary volume pathway for mid-range and budget tiers, compressing delivery timelines to 24-48 hours.
- Direct Sales:Corporate uniform programs increasingly bypass multi-brand distributors for manufacturer-direct contracting, consolidating volume with B2B-specialized platforms.
- Brick-and-Mortar Stores:Controlled retail distribution anchors heritage brand positioning but requires inventory depth that strains working capital.
- Wholesale:Traditional multi-brand relationships face margin compression as procurement departments centralize contracting authority.
Online Retail captures volume growth. Direct Sales deepens corporate lock-in.
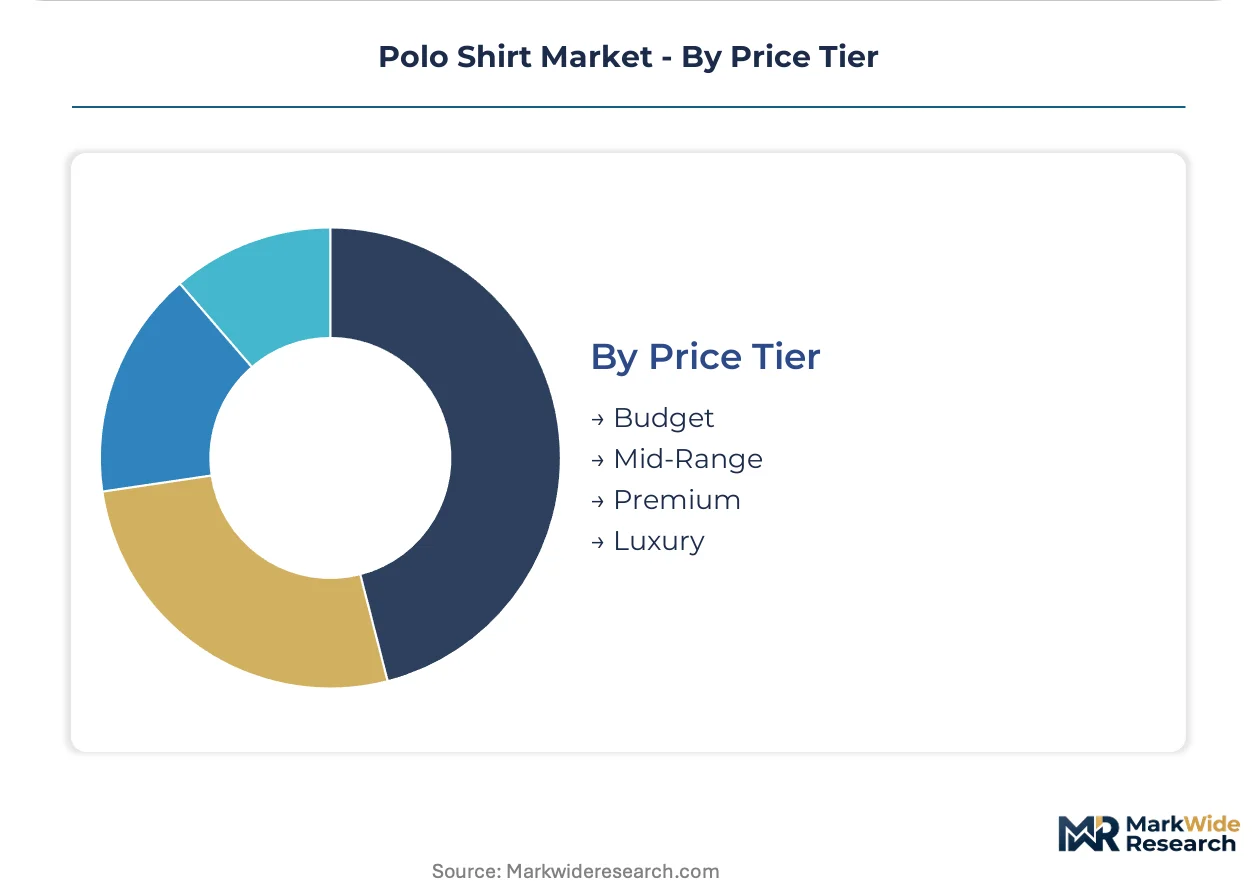
Price Tier:
Certification grade and fiber provenance now separate premium positioning from commodity competition.
- Premium:Archival design DNA and controlled scarcity through limited distribution support pricing power, with organic and recycled content certifications becoming baseline requirements.
- Mid-Range:Volume concentration here exposes margins to cotton price volatility and REACH compliance cost pass-through.
- Budget:Synthetic fiber substitution and seamless knit construction from technical polyester blends bypass traditional piqué economics entirely.
- Luxury:Precision tailoring standards applied to casual silhouettes differentiate positioning, though addressable volume remains constrained.
Premium tier defends through certification scarcity. Budget tier erodes through technical substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting production toward jurisdictions with established certification infrastructure and lower compliance-cost burdens. Manufacturers are consolidating spinner relationships in India and Turkey to satisfy EU Green Deal mandates while maintaining margin structure.
United States
Corporate uniform program expansion drives contracted volume pipelines as employers refresh post-pandemic dress codes. The FTC Green Guides enforce substantiation claims on organic and recycled content labeling. North Carolina's textile corridor hosts concentrated cut-make-trim capacity serving heritage brand collections.
Germany
Precision tailoring standards applied to casual silhouettes differentiate premium positioning in corporate procurement. REACH chemical restrictions from ECHA force reformulation cycles extending product development timelines. Bavaria's industrial clusters anchor technical fabric innovation for athletic-lifestyle crossover collections.
India
Bureau of Indian Standards certification alignment positions export-capable manufacturers for rising organized retail demand in tier-2 and tier-3 cities. The country's PLI scheme incentivizes textile manufacturing scale-up. Tirupur and Surat industrial belts concentrate vertically integrated spinner-to-garment operations.
Turkey
GRS-certified supply bases attract European-bound production seeking compliance with recycled polyester mandates. Proximity to EU markets compresses logistics lead times versus Asian alternatives. Istanbul and Bursa manufacturing zones specialize in quick-turnaround corporate uniform programs.
France
Archival design DNA supports pricing power in heritage brand positioning through controlled scarcity and limited distribution. The EU Green Deal's Corporate Sustainability Due Diligence Directive forces sub-tier spinner relationship mapping. Lyon and Paris fashion clusters anchor technical sportswear heritage translated into lifestyle collections.
Polo Shirt Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue seamless knitting technology and direct-to-consumer platform control. The vendor base stratifies across three tiers: heritage houses with archival design DNA, athletic-lifestyle crossover specialists, and corporate uniform contractors. Dominant competitive moves include backward integration into spinner relationships and D2C channel infrastructure deployment.
Among heritage-brand anchors, Ralph Lauren Corporation and Lacoste exemplify controlled retail distribution strategies, while Hugo Boss occupies a position within precision-tailored casual positioning. These entities represent archetypes of archival design leverage, technical sportswear heritage translation, and tailoring-standard differentiation respectively.
| Leading Market Players |
|---|
| Calvin Klein |
| Burberry |
| Ralph Lauren Corporation |
| Gucci |
| Prada |
| Lacoste |
| Tommy Hilfiger |
| Brooks Brothers |
| Hugo Boss |
| Others |
Supply Flow & Price Mechanics
Texas cotton futures and Maharashtra monsoon indices cascade directly into piqué cotton input costs, compressing margin predictability for mid-tier producers while premium heritage brands absorb volatility through archival design premiums and controlled scarcity.
Pricing Analysis
Input-cost pass-through from weather-driven cotton volatility compresses margins at the standard tier while premium positioning defends through certification scarcity. Three-tier pricing structure across premium, standard, and economy levels separates GRS-certified organic lines from REACH-compliant mid-range production and synthetic-substitution budget tiers. Price differentiation hinges on fiber provenance and spinner certification grade. Corporate uniform buyers exhibit lowest price sensitivity due to contracted volume pipelines, whereas online retail consumers drive compression through comparison shopping.
Supply Chain Analysis
GRS certification gating redirects European-bound production toward vertically integrated spinner-to-garment operations in Turkey and India with existing audit infrastructure. Raw material dependencies center on Egyptian and Pima long-staple cotton, recycled polyester feedstock, and REACH-compliant dye auxiliaries. Single-source vulnerability concentrates in Texas and Maharashtra weather-exposed cotton belts. Distribution runs through direct-to-consumer platforms and manufacturer-direct corporate contracting, displacing traditional multi-brand wholesale relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polo shirt market functions as a stable compounder anchored by corporate uniform program refresh cycles that generate contracted recurring demand insulated from discretionary spending fluctuations.
For Market Incumbents: Lock in corporate uniform program contracts through in-house logo application and size-run complexity capabilities. Deepen backward integration into GRS-certified spinner relationships in Turkey and India to preempt certification backlog delays. Secure direct-to-consumer platform infrastructure to capture first-party fit and color preference data. For New Entrants and Emerging Players: Enter via seamless knitting technology deployment targeting athletic-lifestyle crossover collections where technical fabric convergence commands premium positioning. Target tier-2 and tier-3 Indian cities through Bureau of Indian Standards certification alignment with organized retail penetration. Deploy specialized B2B platforms for corporate uniform program management unbundled from traditional workwear distributors. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated mid-cap specialists possessing captive spinner relationships and GRS certification infrastructure. Long-term viability over a five-to-ten-year horizon favors suppliers with established EU Green Deal compliance architectures. Monitor GRS audit queue duration as inflection indicator for working capital strain and inventory positioning risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spinner Operations | GRS-certified captive supply from Turkish and Indian vertical operations secures EU Green Deal compliance. |
| Direct-to-Consumer Platform Launch | First-party data capture on fit preferences enables heritage brands to bypass wholesale margin stacking. |
| Seamless Knitting Technology Adoption | Body-mapping ventilation zones eliminate side-seam labor while raising quality consistency thresholds. |
| Sustainability Repositioning | Organic and recycled content certifications become baseline requirements for premium tier defense. |
| Corporate Uniform Program Expansion | Direct manufacturer contracting concentrates volume with suppliers managing logo application in-house. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with brand sourcing directors, corporate procurement managers, spinner operations heads, and retail category buyers were triangulated against customs records, Bureau of Indian Standards filings, and EU Green Deal compliance databases. Bottom-up unit economics and top-down market sizing were reconciled across modeling approaches.
Granularity-level modeling captured material grade, customer type, distribution channel, and price tier dimensions across the analysis window. CAGRs were derived from segment-level volume and value trajectories. Forecast inputs incorporated corporate uniform program refresh cycles, REACH reformulation timeline impacts, and GRS certification queue dynamics.
Inputs from spinner operations and corporate procurement departments were available through the study window; gaps in sub-tier living wage compliance documentation introduce uncertainty bands around European-bound production cost assumptions. Forecasts reflect documented assumptions on cotton price volatility and regulatory enforcement intensity. A model refresh is warranted upon material change in EU Green Deal textile sustainability implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Loungewear Market
Apparel & Footwear
Thimbles Market
Apparel & Footwear
Women's Sports and Swimwear Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Electric Heated Shoes Market
Apparel & Footwear
Asia-Pacific Denim Jeans Market
Apparel & Footwear
South Africa Denim Jeans Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Custom Cycling Clothing Market
Apparel & Footwear
Menswear Market
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
Global Luxury Underwear Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
Ethnic Wear Market
Apparel & Footwear
Brazil Pet Clothing Market