
 Headwear Market | 2026-2036
Headwear Market Size, Share, and Industry Trends Forecast 2026-2036
Headwear Market Intelligence
The capital-intensity divergence between automated cut-and-sew operations and artisanal hand-blocking is redrawing competitive boundaries in headwear manufacturing. Nike Inc. leverages vertical integration across polyester performance caps to control material sourcing and dye-sub printing workflows. New Era Cap anchors its position through exclusive licensing agreements with major North American sports leagues, sustaining premium placement across team merchandise channels. Christys' London specializes in hand-felted wool formal hats, occupying a defensible niche where craft heritage commands sustained price premiums.
Headwear encompasses fitted and adjustable coverings for the human head, constructed from woven, knitted, or felted textiles and shaped through blocking, molding, or panel assembly processes with functional parameters spanning brim curvature, crown height, and moisture-wicking performance ratings. Its primary commercial purpose spans sun protection, thermal insulation, athletic performance enhancement, and fashion signaling across casual and formal contexts. Caps dominate volume throughput in licensed sports and streetwear channels where repeat purchase frequency sustains margin pools. Beanies represent the fastest-expanding cold-weather segment as technical wool-acrylic blends displace pure natural fibers in outdoor and workwear applications. Formal hats remain structurally mature, with Borsalino and Lock & Co. competing for share in a contracting but high-margin ceremonial market.
The U.S. Consumer Product Safety Commission enforces flammability standards under the Flammable Fabrics Act, while the EU REACH regulation restricts azo dyes and formaldehyde resins in textile headwear, and the OEKO-TEX Standard 100 certification shapes premium market access across export-oriented manufacturing hubs. These frameworks elevate compliance costs for synthetic material processors but simultaneously create differentiation pathways for certified organic cotton and traceable wool suppliers. Stakeholders must monitor pending PFAS restrictions in both European and North American jurisdictions, as water-repellent treatments face phased elimination that will force reformulation of performance-oriented outdoor headwear lines.
Market Dynamics
REACH compliance in Europe and evolving U.S. textile safety standards are tightening chemical disclosure requirements for synthetic materials, forcing reformulation of performance-oriented outdoor headwear lines and elevating compliance costs across the supply chain.
Growth Catalysts
- Professional sports licensing:North American sports leagues are expanding procurement of licensed caps and performance headwear for team merchandise channels, sustaining premium placement across retail networks.
- Technical wool-acrylic blends:Outdoor and workwear applications are driving adoption of advanced fiber combinations that displace pure natural fibers in cold-weather beanie production.
- China export manufacturing:Domestic sportswear brands and contract manufacturers are scaling technical headband and beanie production for international markets, concentrating supply capacity in key coastal provinces.
Market Restraints
- Petrochemical input volatility:Polyester and acrylic fiber costs fluctuate with crude oil derivatives, compressing margins for synthetic performance cap manufacturers.
- Supply concentration risk:Dye-sub printing workflows and automated cut-and-sew operations cluster in Guangdong and Zhejiang provinces, creating geographic vulnerability to regional disruptions.
- PFAS elimination timeline:Pending restrictions on water-repellent treatments in European and North American jurisdictions will force costly reformulation of outdoor headwear lines before alternative chemistries mature.
Strategic Opportunities
- Certified organic cotton:OEKO-TEX Standard 100 and traceable wool certifications create differentiation pathways for suppliers targeting premium export markets with elevated chemical safety requirements.
- Hand-blocking craft heritage:Formal hat segments command sustained price premiums where artisanal production methods defy automated competition, offering margin protection in contracting ceremonial markets.
- Direct-to-team procurement:Professional sports franchises are consolidating vendor relationships for custom performance headwear, bypassing traditional retail intermediaries.
Industry Challenges
- Flammability testing bottlenecks:U.S. Consumer Product Safety Commission enforcement under the Flammable Fabrics Act creates extended certification timelines for new synthetic material introductions.
- Azodye compliance complexity:EU REACH restrictions on azo dyes and formaldehyde resins require multi-jurisdictional testing protocols that fragment quality assurance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Headwear Market |
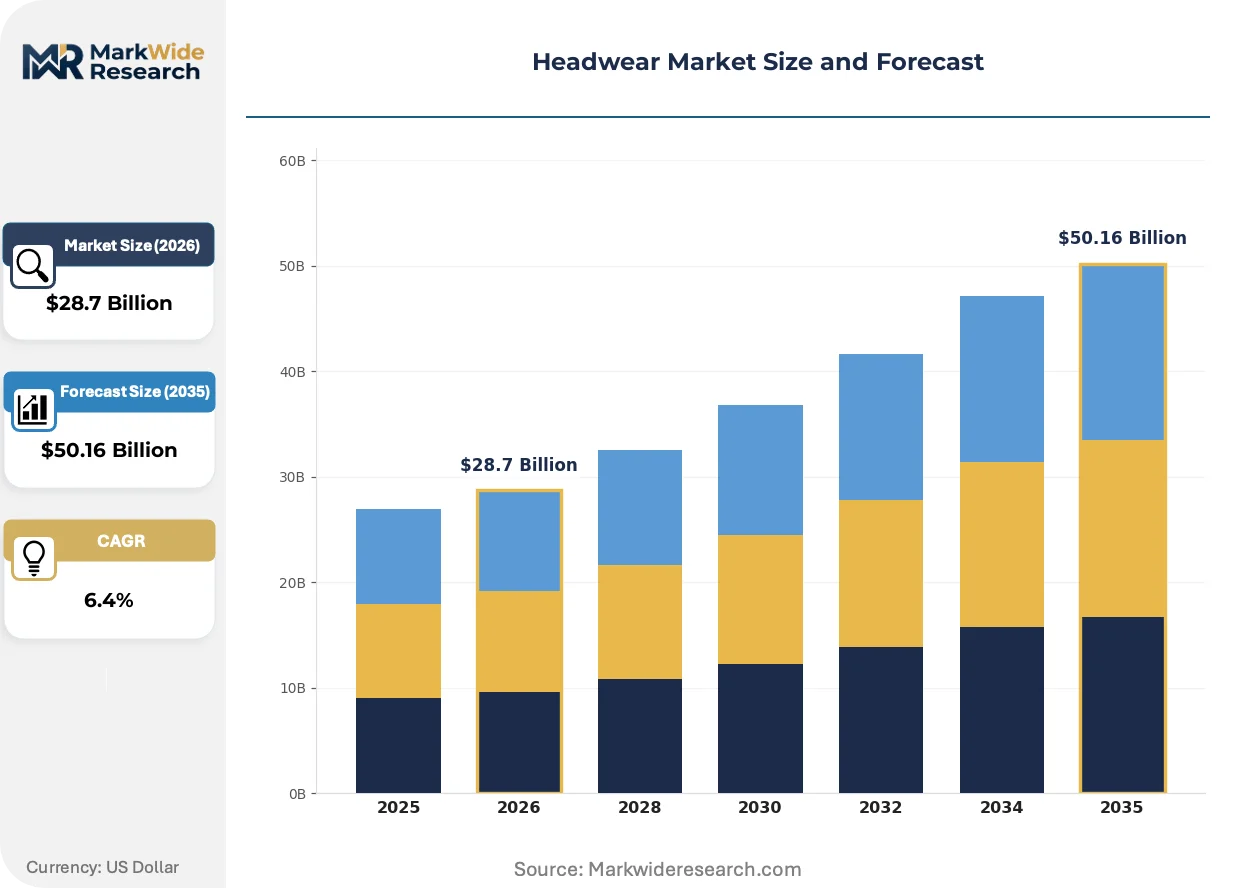
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caps, Hats, Beanies, Headbands Material: Cotton, Polyester, Wool, Acrylic Style: Casual, Formal, Sports, Fashion Target Audience: Men, Women, Children, Unisex |
| Companies Covered | Under Armour Inc., Goorin Bros., Nike Inc., Lock & Co., Borsalino, Adidas AG, Puma SE, Christys' London, New Era Cap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Headwear Market Strategic Shifts & Innovations
Active reshaping of the headwear market centers on material science advances, regulatory chemistry transitions, and procurement model consolidation that together compress development cycles and elevate compliance thresholds.
Moisture-wicking membrane technology is miniaturizing. Advanced hydrophilic coatings now integrate directly into polyester performance cap fabrics rather than layering as separate inserts. Marathon runners and cycling teams are adopting these integrated systems at accelerating rates. The technology is miniaturizing equipment profiles while maintaining breathability ratings, compressing the performance premium previously commanded by specialized outdoor brands.
ECHA's pending PFAS restriction proposal under REACH Annex XVII is forcing water-repellent treatment reformulations across European-exporting manufacturers. Industrial consequence includes accelerated R&D spending on silicone and hydrocarbon alternatives that trade durability for regulatory compliance. Outdoor beanie and technical headband lines destined for Germany, France, and Benelux markets face the most compressed transition timelines, with suppliers front-loading 2025 inventory to bridge certification gaps.
Team merchandise buyers are consolidating vendor rosters from fragmented regional suppliers toward vertically integrated manufacturers with captive dye-sub printing and cut-and-sew capacity. This concentration displaces small-batch jobbers in licensed sports channels. The shift is most visible across Major League Baseball and National Basketball Association procurement offices, where multi-year exclusive agreements now predominate over seasonal bidding.
Headwear Market Segmentation
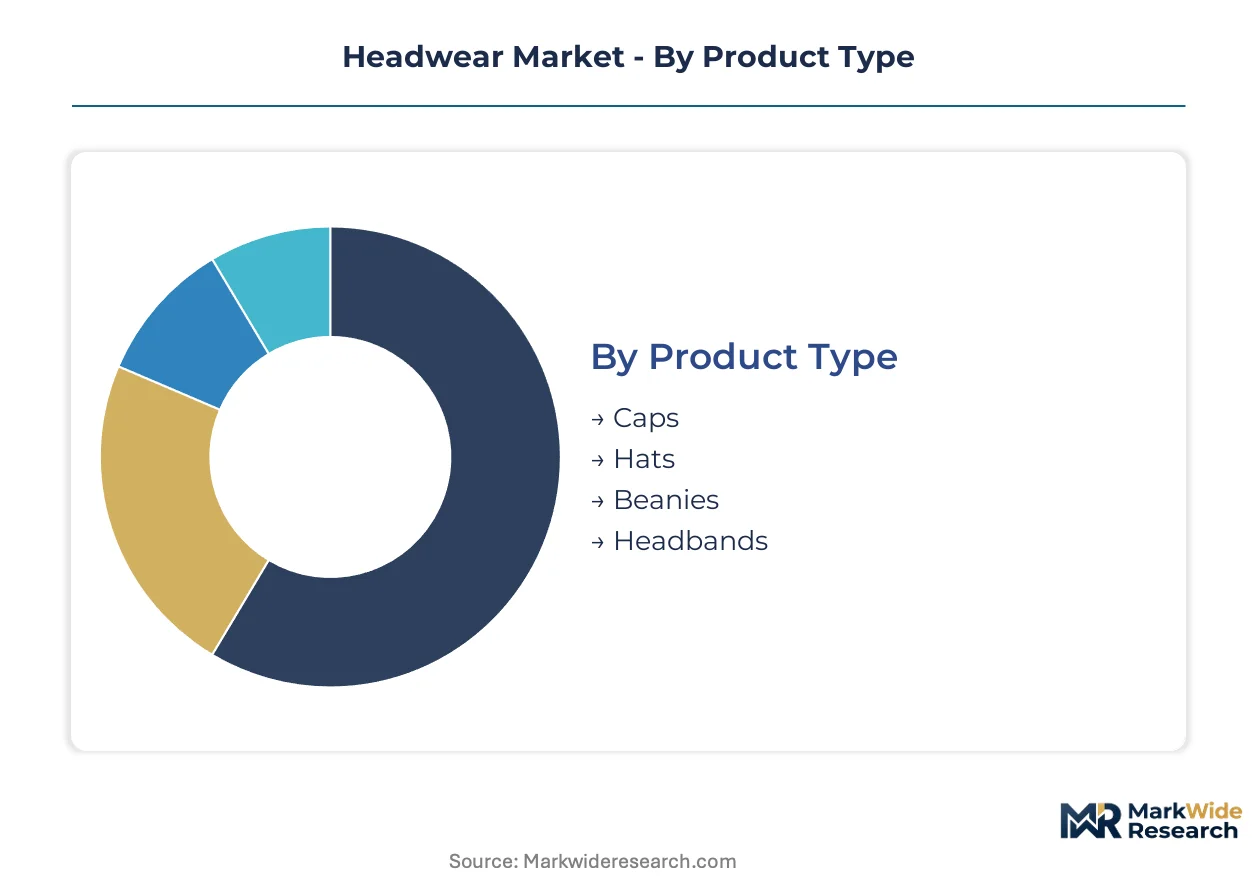
Headwear segmentation reveals distinct procurement channels and margin structures. Licensed sports caps flow through team merchandise buyers, while formal hats occupy boutique retail and ceremonial channels with radically different velocity profiles.
Product Type:
Channel mix varies sharply across product categories. Caps and beanies dominate team merchandise and outdoor retail respectively, while formal hats sustain independent specialty retailers.
- Caps:Six-panel fitted and adjustable constructions with curved or flat brims, typically featuring embroidered logos or dye-sub printed graphics. Demand concentrates in North American professional sports licensing channels where Major League Baseball and National Basketball Association procurement offices consolidate vendor relationships. The segment sustains premium placement through exclusive multi-year agreements.
- Beanies:Knitted cold-weather coverings constructed from wool-acrylic blends or pure merino wool, with ribbed cuffs and varying slouch profiles. Technical fiber combinations in outdoor and workwear applications are displacing pure natural fibers, with China-based contract manufacturers scaling production for export markets.
- Hats:Structured brimmed coverings including fedoras, panamas, and bucket hats, formed through blocking or molding processes. Formal variants command sustained price premiums where artisanal hand-blocking defies automated competition.
- Headbands:Narrow elastic or fabric bands designed for sweat management and hair restraint during athletic activity. Technical moisture-wicking constructions are gaining share in marathon running and cycling team procurement.
Caps dominate installed base. Beanies are where expansion concentrates.
Material:
Cost tier stratification separates premium natural fibers from volume synthetic production, with compliance costs creating additional differentiation layers.
- Polyester:Petroleum-derived synthetic fiber dominating performance cap production for its moisture-wicking properties and dye-sub printing compatibility. Nike Inc. leverages backward integration across polyester supply chains to control material sourcing workflows.
- Cotton:Natural cellulose fiber ranging from basic carded varieties to certified organic long-staple grades. OEKO-TEX Standard 100 certification creates differentiation pathways for suppliers targeting premium export markets with elevated chemical safety requirements.
- Wool:Protein fiber from sheep fleece, valued for thermal insulation and moisture absorption in cold-weather applications. Christys' London and Borsalino compete in hand-felted formal hat segments where craft heritage sustains margins.
- Acrylic:Synthetic polymer fiber mimicking wool properties at lower cost points, commonly blended with wool in beanie production. Petrochemical input volatility compresses margins as crude oil derivative costs fluctuate.
Polyester commands volume throughput. Certified organic cotton is climbing the fastest.
Style:
Application context determines distribution architecture, with sports and fashion styles converging through streetwear channels while formal styles retreat to ceremonial niches.
- Sports:Performance-oriented designs integrating moisture-wicking membranes and aerodynamic profiles for athletic use. Advanced hydrophilic coatings now integrate directly into polyester fabrics rather than layering as separate inserts.
- Casual:Everyday wearable designs emphasizing comfort and versatility across demographic segments. Volume production clusters in Guangdong and Zhejiang provinces with dye-sub printing and automated cut-and-sew capacity.
- Fashion:Trend-driven designs emphasizing aesthetic signaling and brand collaboration. New Era Cap anchors position through exclusive licensing agreements sustaining premium placement.
- Formal:Ceremonial and professional designs including top hats, bowlers, and homburgs requiring hand-blocking craftsmanship. Lock & Co. competes in a contracting but high-margin market where automated competition remains structurally excluded.
Casual styles dominate installed base. Sports styles are gaining share fastest.
Target Audience:
Customer type shapes product development cycles, with unisex designs compressing SKU complexity and men's licensed merchandise sustaining the highest per-unit margins.
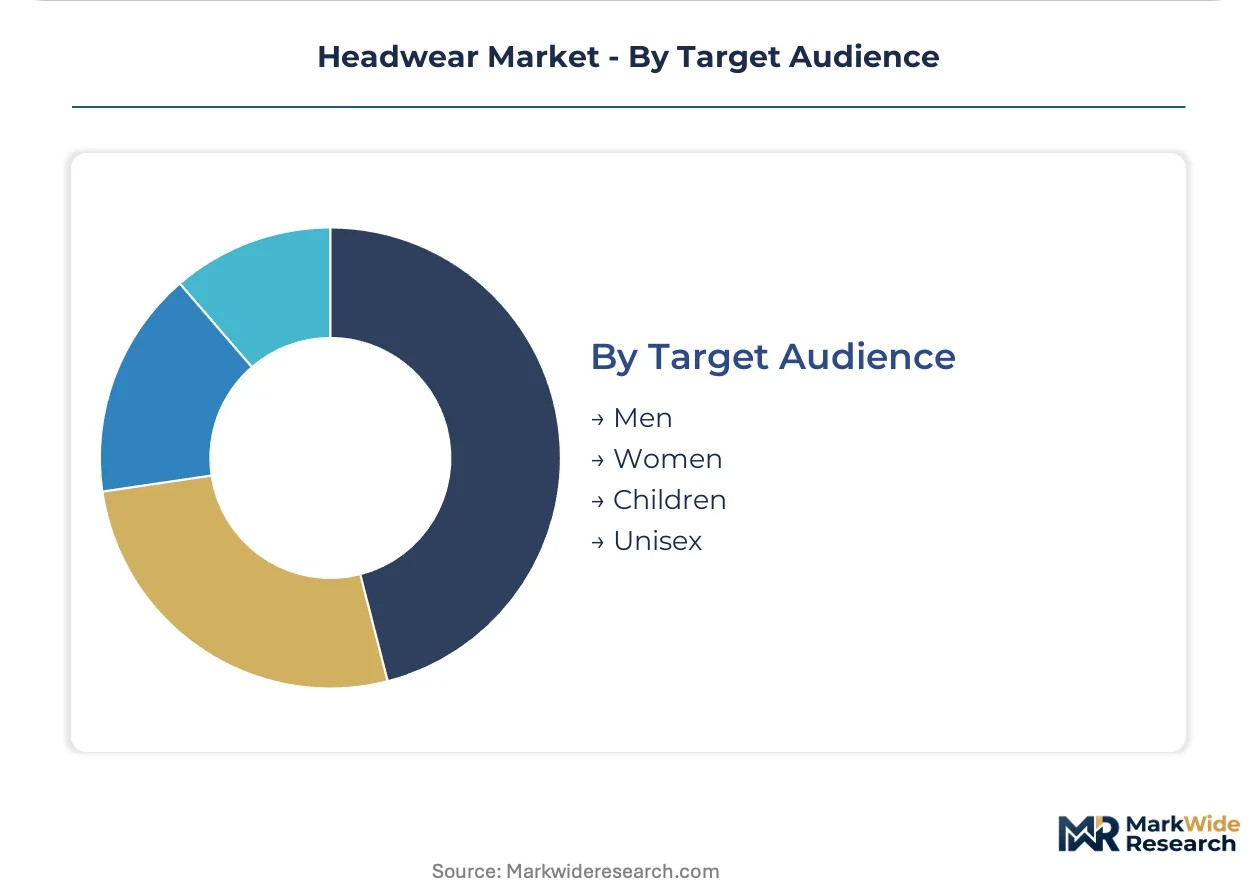
- Men:Largest addressable segment spanning professional sports licensing, outdoor workwear, and formal ceremonial markets. Team merchandise buyers concentrate procurement of licensed caps in this demographic.
- Women:Fashion-forward segment driving beanie and headband diversification with expanded color palettes and decorative embellishments. Direct-to-team procurement models are consolidating vendor relationships for custom performance headwear.
- Children:Size-scaled variants with adjusted crown dimensions and safety-compliant construction. Flammability testing under the U.S. Flammable Fabrics Act creates extended certification timelines.
- Unisex:Adjustable and stretch-fit designs minimizing inventory complexity across retail channels. REACH compliance and evolving textile safety standards elevate chemical disclosure requirements for synthetic materials.
Men's headwear dominates installed base. Unisex designs are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. Professional sports licensing commands premium tolerance in the United States, while contract manufacturing in China competes on unit economics. European buyers prioritize certified compliance over lowest cost.
United States
Major League Baseball and National Basketball Association procurement offices drive licensed cap demand through exclusive multi-year vendor agreements. The Consumer Product Safety Commission enforces flammability standards under the Flammable Fabrics Act, extending certification timelines for synthetic introductions. Los Angeles and New York anchor team merchandise distribution networks with concentrated retail placement.
China
Domestic sportswear brands and contract manufacturers scale technical headband and beanie production for export markets. The Ministry of Ecology and Environment administers dual carbon goals that elevate energy efficiency requirements for textile processing. Guangdong and Zhejiang provinces cluster dye-sub printing workflows and automated cut-and-sew operations, creating geographic concentration risk.
Germany
Outdoor retailers prioritize REACH-compliant technical wool-acrylic blends for cold-weather applications. ECHA's pending PFAS restriction proposal under REACH Annex XVII forces water-repellent treatment reformulations with compressed transition timelines. Bavaria hosts specialized testing laboratories certifying OEKO-TEX Standard 100 compliance for premium export channels.
United Kingdom
Formal hat segments sustain ceremonial demand through heritage craft positioning. The Office for Product Safety and Standards enforces textile labeling regulations that elevate traceability requirements for wool suppliers. London anchors Christys' London and Lock & Co. operations where hand-blocking defies automated competition.
Japan
Fashion-forward consumers drive beanie diversification with expanded color palettes and technical moisture-wicking constructions. METI oversees JIS standards for textile performance claims that shape product development cycles. Tokyo and Osaka concentrate specialty retail placement for premium headwear imports.
Headwear Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes. Automated cut-and-sew specialists compete on throughput velocity, while artisanal hand-blockers defend margin through craft exclusivity. The structure segments into vertically integrated sportswear giants, licensed merchandise specialists, and heritage formal hatters. Dominant competitive moves include exclusive licensing agreements and backward integration into polyester supply chains.
Within the heritage craftsmanship tier, Christys' London and Borsalino occupy positions where hand-felted wool production defies mechanized replication. Nike Inc. anchors the performance-oriented vector through captive control of material sourcing and dye-sub printing workflows. New Era Cap exemplifies the licensed merchandise archetype, sustaining premium placement through exclusive agreements with North American sports leagues.
| Leading Market Players |
|---|
| Under Armour Inc. |
| Goorin Bros. |
| Nike Inc. |
| Lock & Co. |
| Borsalino |
| Adidas AG |
| Puma SE |
| Christys' London |
| New Era Cap |
| Others |
Cost & Logistics Intelligence
Sixty-day dye-sub printing lead times from Guangdong contract manufacturers concentrate pricing power with vertically integrated sportswear giants holding captive cut-and-sew capacity, while artisanal hand-blockers defend margin pools through inventory scarcity and craft exclusivity. This temporal-structure nexus shapes how licensed sports merchandise buyers negotiate multi-year vendor agreements against fragmented regional jobbers.
Pricing Analysis
After-sales licensing royalties and team merchandise renewal contracts drive lifetime value beyond initial unit sales. Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX certified organic cotton from basic polyester and hand-felted wool formal hats. Cost compression in synthetic performance caps is intensifying because petrochemical input volatility compresses margins for manufacturers without backward integration. Mass-market retail buyers exhibit highest price sensitivity; ceremonial formal hat purchasers show lowest.
Supply Chain Analysis
Strategic stockpiling of PFAS-treated inventory ahead of ECHA restriction deadlines contrasts with just-in-time dye-sub workflows for licensed sports caps. Manufacturing concentrates in China, Vietnam, and Bangladesh for cut-and-sew assembly; wool fiber sourcing draws from Australia and New Zealand. Single-source vulnerability clusters in Guangdong and Zhejiang provinces where automated panel assembly feeds North American team merchandise channels. Distribution runs through team procurement offices, outdoor retail networks, and heritage specialty boutiques.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where exclusive licensing agreements function as two-sided networks connecting sports league IP holders with consolidated manufacturing capacity, reshaping procurement from fragmented seasonal bidding toward multi-year ecosystem lock-in.
For Market Incumbents: Consolidate vendor rosters through exclusive multi-year agreements with Major League Baseball and National Basketball Association procurement offices, displacing fragmented regional jobbers. Deepen backward integration into polyester fiber supply chains to offset petrochemical input volatility. Prioritize OEKO-TEX Standard 100 certification investment to defend premium positioning against REACH compliance pressure. For New Entrants and Emerging Players: Lead with technical wool-acrylic beanie production targeting German and Benelux outdoor retailers facing compressed PFAS transition timelines. White-space concentrates in certified organic cotton headbands for marathon running and cycling team procurement. Go-to-market through direct-to-team sales bypassing traditional retail intermediaries. For Investors and Strategic Acquirers: Long-term, this sits as a licensing-arbitrage play because exclusive sports league agreements generate recurring royalty streams with embedded renewal optionality. Target acquisition archetype: vertically integrated manufacturers with captive dye-sub printing and established team merchandise relationships. Watch ECHA PFAS restriction enforcement velocity as inflection indicator for alternative chemistry R&D returns.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Licensing Agreement | Multi-year MLB and NBA contracts lock out competing vendors from premium team merchandise placement. |
| Backward Integration | Captive polyester fiber sourcing insulates Nike from petrochemical cost volatility in performance cap production. |
| Certification Investment | OEKO-TEX Standard 100 compliance opens premium export channels in Germany and Benelux markets. |
| Direct-to-Team Procurement | Bypassing retail intermediaries compresses margin leakage for custom performance headwear contracts. |
| PFAS Alternative Chemistry | Silicone and hydrocarbon water-repellent R&D hedges against ECHA REACH Annex XVII restriction timelines. |
Research Approach
A standing panel of team merchandise procurement directors, outdoor retail category buyers, contract manufacturing operations heads, and heritage formal hat craft specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from U.S. Consumer Product Safety Commission flammability filings, ECHA REACH restriction proposals, OEKO-TEX certification databases, and customs trade records. Bottom-up vendor capacity estimates triangulated against top-down league licensing revenue flows.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling spanned product type, material grade, style application, and target audience demographics. CAGRs derived from fitted trend extrapolation with elasticity adjustments for regulatory intervention scenarios. Industry-specific inputs included dye-sub printing capacity utilization rates and wool-acrylic blend adoption curves in outdoor channels.
The analysis sits within stated boundaries; outcomes outside sustained professional sports licensing growth or accelerated PFAS elimination timelines would require recalibration. Forecasts reflect documented assumptions about team merchandise procurement consolidation and REACH compliance cost pass-through. Revision becomes warranted when ECHA enforcement velocity or polyester feedstock volatility crosses threshold uncertainty bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Streetwear Market
Apparel & Footwear
Heated Jacket Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market
Apparel & Footwear
South Africa Denim Jeans Market
Apparel & Footwear
Maternity Apparels Market
Apparel & Footwear
Menswear Market
Apparel & Footwear
Sports Bras Market
Apparel & Footwear
US Thermal Underwear Market
Apparel & Footwear
Vegan Footwear Market
Apparel & Footwear
Smart Wardrobe Market
Apparel & Footwear
Jeans Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Bathrobe Market
Apparel & Footwear
Global Silk Pajamas Market