
 France Pet Food Market | 2026-2036
France Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
France Pet Food Market Foresight
Single-serve pouch bundling is recalibrating how French households purchase cat food, shifting volume from bulk dry formats to portion-controlled assortments. Royal Canin leverages its veterinary channel dominance to anchor premium prescription diets in clinics across Greater Paris. Mars Incorporated sustains manufacturing scale through its Amiens production facility, while Affinity Petcare specializes in region-specific protein sourcing for its Breton consumer base.
France pet food comprises nutritionally formulated feed products manufactured to species-specific dietary requirements, typically containing protein meals, cereals, fats, vitamins, and minerals processed through extrusion, canning, or retort pouch methods. Its primary purpose is to deliver complete or complementary nutrition for companion animals under controlled safety parameters. Dry food occupies the largest volume share due to shelf stability and cost efficiency, yet wet food and treats capture disproportionate margin pools as owners trade up to perceived freshness and indulgence. Veterinary clinics represent the fastest-growing sales channel, driven by prescription diet authorization and preventive nutrition counseling.
ANSES sets maximum permissible levels for contaminants and additive usage in pet food formulations sold throughout France. The EU Feed Hygiene Regulation mandates HACCP-compliant manufacturing and full ingredient traceability across national supply chains. DGCCRF market surveillance enforces labeling accuracy and penalizes misleading nutritional claims on packaging. Stakeholders must monitor evolving EU packaging waste directives, as mechanical recycling targets for multi-layer pouches will force material redesign decisions within the decade.
Market Dynamics
Pet humanization in Île-de-France and Auvergne-Rhône-Alpes is compressing purchasing cycles for premium wet formats while ANSES traceability mandates force ingredient sourcing transparency across Breton supply chains.
Growth Catalysts
- ANSES Nutritional Guidelines:Tightening contaminant thresholds and additive caps are accelerating formulation upgrades among domestic manufacturers seeking veterinary channel authorization.
- Urban Household Concentration:Paris and Lyon apartment dwellers favor single-serve pouches over bulk dry formats, recalibrating SKU economics toward portion-controlled assortments.
- Veterinary Channel Expansion:Preventive nutrition counseling in Greater Paris clinics is pulling prescription diet volumes away from mass retail.
Market Restraints
- Protein Input Volatility:Region-specific sourcing requirements for Breton consumer bases expose margins to Atlantic fishery and Southwest poultry supply fluctuations.
- Multi-layer Pouch Recycling Deadlines:EU packaging waste directives mandate mechanical recycling targets that will force material redesign investments within the decade.
- Dry Format Commoditization:Shelf-stable kibble faces margin compression as private label volumes concentrate in hypermarket channels.
Strategic Opportunities
- Occitanie and Provence-Alpes-Côte d'Azur Underpenetration:Specialty retail expansion into secondary urban centers outside Paris-Lyon corridor offers first-mover positioning for premium assortments.
- Insect Protein Regulatory Tailwind:EFSA novel food approvals for processed insect meal create pathway for sustainable protein diversification in hypoallergenic formulations.
- Subscription Direct-to-Consumer Models:Portion-customized delivery platforms bypass traditional distributor markups while capturing recurring revenue from digitally native pet owners.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Clinic-level preventive counseling requires specialized training pipelines that French veterinary schools have not yet scaled to meet channel growth.
- HACCP Retrofit Capex Burden:SME manufacturers in Normandy and Brittany face facility upgrade costs to achieve EU Feed Hygiene Regulation compliance without volume offsets.
- Ingredient Traceability System Integration:Legacy ERP platforms at regional co-packers struggle to deliver batch-level documentation demanded by DGCCRF enforcement protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Pet Food Market |
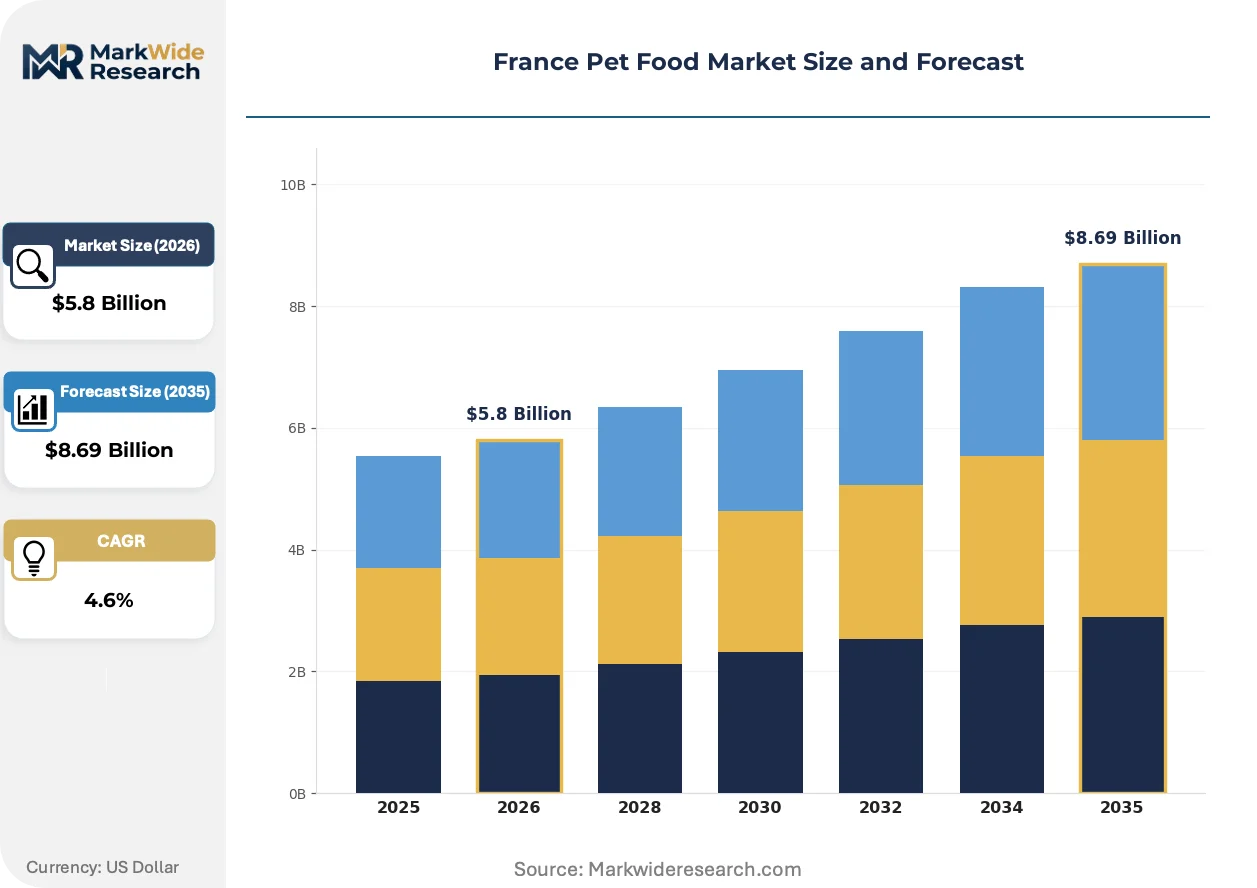
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Semi-Moist Food, Treats, Supplements Pet Type: Dogs, Cats, Birds, Small Mammals, Reptiles Sales Channel: Specialty Pet Stores, Supermarkets & Hypermarkets, Online Retail, Veterinary Clinics Packaging Type: Plastic Bags, Cans & Tins, Pouches, Bottles, Cartons |
| Companies Covered | Hill's Pet Nutrition, Archer Daniels Midland, Royal Canin, Groupe Legris Industries, Colgate-Palmolive, Mars Incorporated, Affinity Petcare, Virbac, Nestle Purina Petcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Pet Food Market Shifts & Advancements
Freshness signaling technologies and circular packaging mandates are recalibrating how French manufacturers formulate, package, and distribute companion animal nutrition across retail and veterinary channels.
Retort pouch barrier films with oxygen scavenging layers are converging with high-pressure processing methods to extend wet food shelf life without synthetic preservatives. Premium brands serving Parisian urban households have adopted these formats fastest, compressing the freshness gap between factory and bowl while justifying 40-60% price premiums over canned alternatives.
EU packaging waste directives are mandating recycled content minimums and design-for-recycling standards that will eliminate non-separable multi-layer structures. DGCCRF surveillance is already penalizing misleading recyclability claims, forcing manufacturers to accelerate mono-material pilot programs or risk shelf delistings ahead of 2030 compliance deadlines.
Subscription-based replenishment is displacing episodic hypermarket stocking among millennial and Gen Z pet owners in Île-de-France. Algorithm-driven portion calculators match delivery frequency to individual animal profiles, capturing recurring revenue while reducing price sensitivity through convenience lock-in rather than promotional dependency.
France Pet Food Market Segmentation
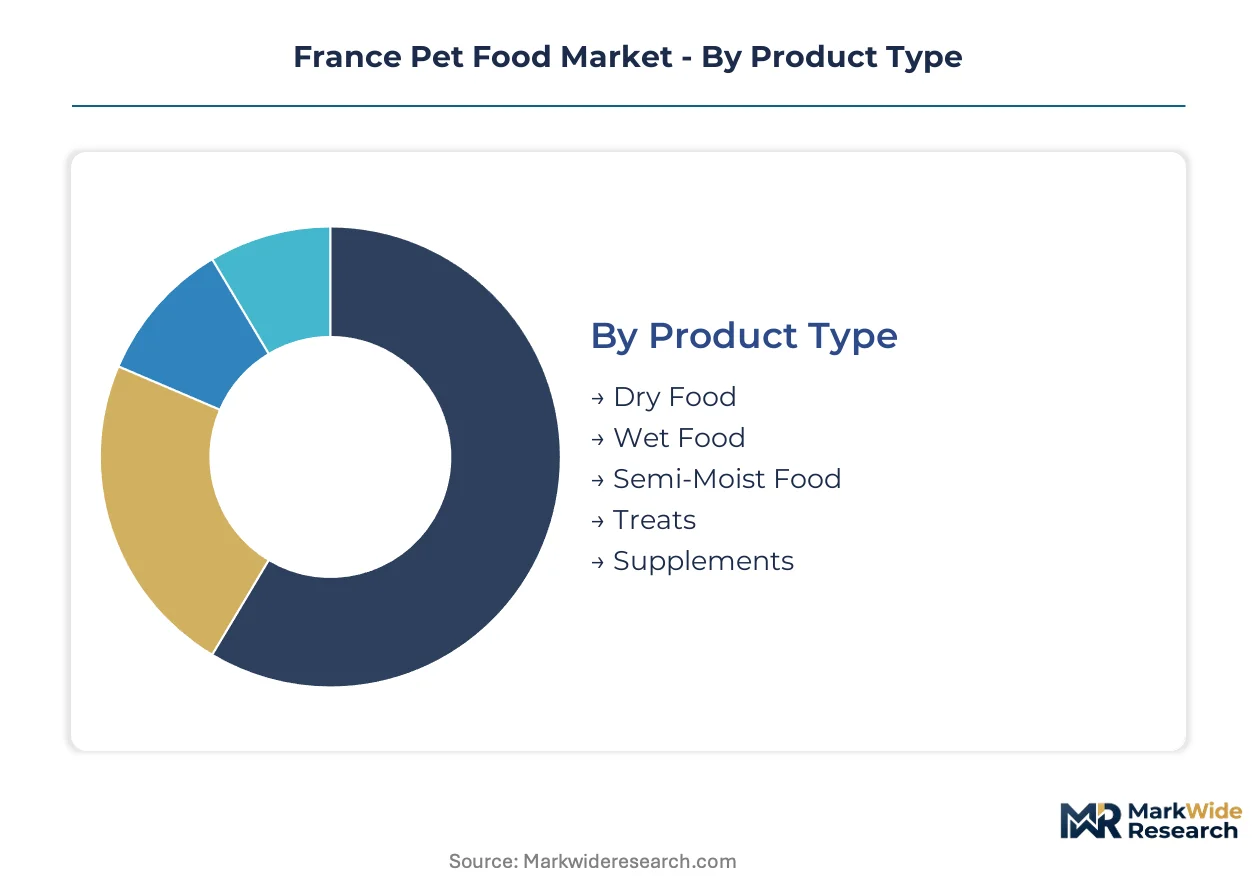
France's pet food segmentation reflects divergent buyer priorities across urban density tiers, with Parisian apartment dwellers trading up to portion-controlled formats while Breton households sustain volume-driven dry food consumption. Veterinary channel authorization and ANSES compliance requirements increasingly determine which segments capture margin expansion versus commoditization pressure.
Product Type:
Cost tier drives the primary purchase decision, with household budget allocation determining format selection across the freshness-convenience spectrum.
- Dry Food:Extruded kibble formulations deliver complete nutrition through shelf-stable carbohydrate-protein matrices with 12-18 month stability. Hypermarket channels in Île-de-France and Auvergne-Rhône-Alpes concentrate volume here, though private label expansion compresses branded margin pools. Dry food leads on scale; wet food leads on momentum.
- Wet Food:High-moisture retort or tray-packed meals containing 75-85% water content with fresh meat or fish as primary ingredients. Single-serve pouch adoption among Lyon and Paris urban households accelerates fastest, pulled by humanization trends and portion control convenience. ANSES contaminant thresholds favor wet format upgrades for veterinary channel positioning.
- Semi-Moist Food:Intermediate moisture soft pellets preserved through humectants and mild acidification, targeting palatability-sensitive pets in transitional diet stages.
- Treats:Indulgence-positioned complementary nutrition including dental chews, training rewards, and functional snacks with limited caloric contribution to daily intake.
- Supplements:Targeted additive formats addressing joint health, coat condition, or digestive support, typically sold through veterinary recommendation in Greater Paris clinics.
Dry formats dominate volume throughput; wet formats command the steepest expansion trajectory as urban household concentration reshapes purchasing patterns.
Pet Type:
Species-specific metabolic requirements dictate formulation complexity and regulatory scrutiny intensity across the French market.
- Dogs:Omnivorous formulations spanning complete dry diets to fresh-frozen raw alternatives, with large-breed and senior life-stage variants driving veterinary channel premiumization. Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur households show strongest demand for breed-specific nutrition.
- Cats:Obligate carnivore formulations with elevated protein and taurine requirements, where wet food penetration exceeds dog categories due to moisture-adequacy concerns. Parisian single-cat households favor premium pouch assortments with the highest per-kilogram pricing in the market.
- Birds:Seed, pellet, and nectar-based diets for companion psittacines and passerines, concentrated in specialty retail channels with regional variation by avicultural tradition.
- Small Mammals:Species-specific fiber and protein balances for rabbits, guinea pigs, and rodents, where hay-based complementary feeding complicates complete diet positioning.
- Reptiles:Live, frozen, and formulated diets for herpetological keepers, representing a niche segment with specialized distribution through exotic pet specialists.
Cats and dogs collectively anchor volume; cat wet food climbs the fastest on per-household spend expansion.
Sales Channel:
Channel selection determines margin capture, with authorization requirements and customer acquisition economics stratifying competitive positioning.
- Specialty Pet Stores:Independent and chain retailers offering curated assortments with staff consultation, concentrated in urban centers where humanization trends sustain premium positioning. Occitanie and Provence-Alpes-Côte d'Azur present underpenetrated expansion terrain for specialty format rollout.
- Supermarkets & Hypermarkets:Mass retail commanding dry food volume through promotional cycling and private label concentration, with hypermarket channels in Île-de-France facing sharpest margin compression.
- Online Retail:Subscription and marketplace platforms capturing digitally native millennial and Gen Z owners through algorithmic replenishment and direct-to-consumer convenience lock-in.
- Veterinary Clinics:Prescription diet authorization and preventive nutrition counseling drive the fastest channel expansion, with Greater Paris clinic density supporting premium therapeutic format penetration.
Mass retail retains volume leadership; veterinary clinics gain share fastest on prescription authorization requirements.
Packaging Type:
Material selection increasingly reflects regulatory compliance pressure as EU packaging waste directives mandate design-for-recycling standards.
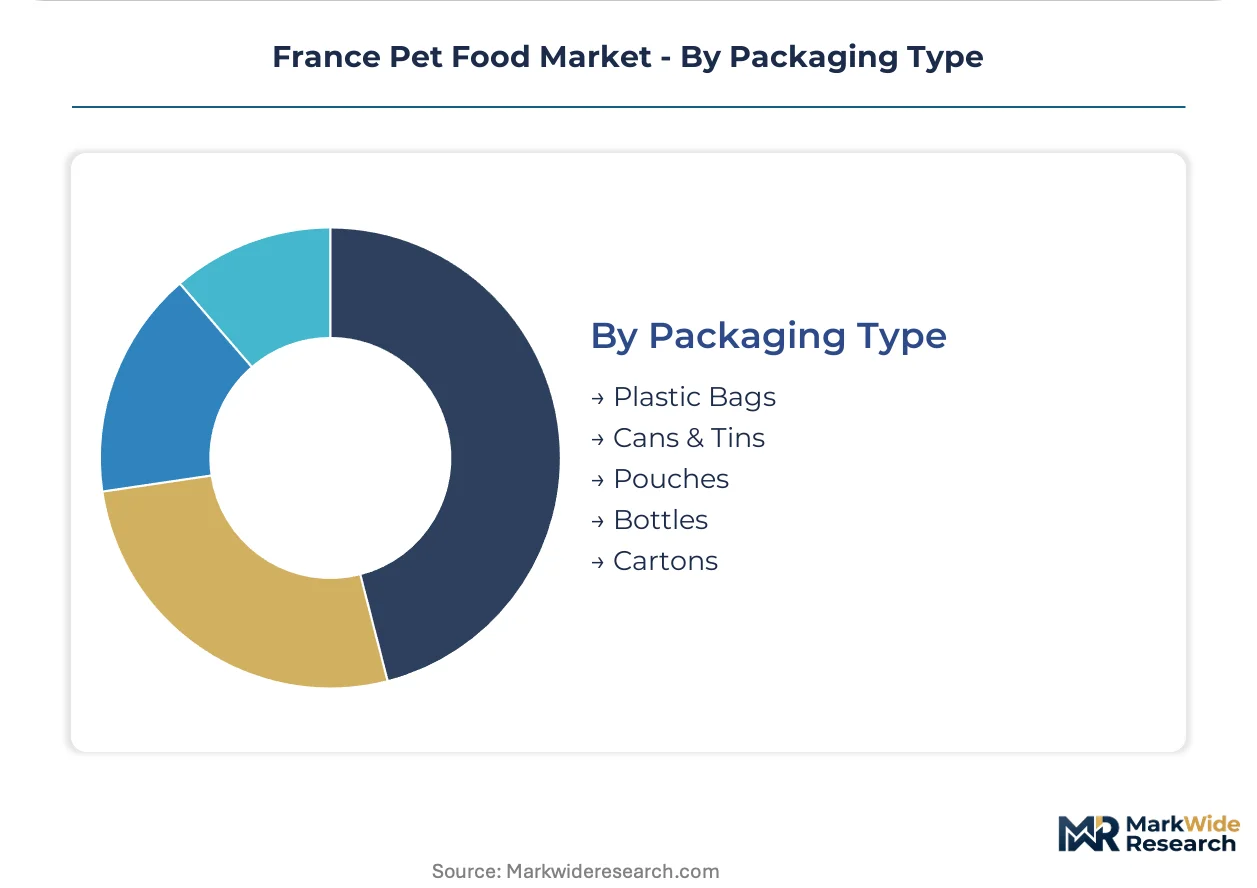
- Plastic Bags:Multi-layer flexible structures dominating dry food bulk formats, facing forced material redesign as mechanical recycling targets eliminate non-separable laminates before 2030 deadlines.
- Cans & Tins:Steel and aluminum rigid containers for wet food with established recycling infrastructure, though weight and logistics costs disadvantage against flexible alternatives.
- Pouches:Retort and cold-fill flexible formats with oxygen barrier layers enabling preservative-free freshness claims, where mono-material pilot programs accelerate to meet DGCCRF surveillance on recyclability accuracy.
- Bottles:Rigid PET or HDPE containers for liquid supplements and gravies, benefiting from established collection and reprocessing streams.
- Cartons:Fiber-based structures with polymer barriers for dry food and treats, where renewable content positioning appeals to sustainability-motivated purchasers in urban markets.
Plastic bags retain installed scale; pouches face the most urgent transformation pressure from circular economy mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's pet food industry traces its modern origins to post-war industrialization in the Loire Valley, where canning expertise from human food processing transferred to companion animal nutrition during the 1960s. This technical foundation established manufacturing corridors that persist today, with formulation science and packaging innovation clustering around historic production centers.
Île-de-France
Parisian apartment households drive single-serve wet food adoption at premium price points, compressing bulk dry format penetration. ANSES headquarters in Maisons-Alfort anchors national contaminant threshold enforcement. Greater Paris clinic density supports veterinary channel prescription diet authorization at scale unmatched elsewhere.
Auvergne-Rhône-Alpes
Lyon's urban corridor replicates Parisian pouch-format preferences while sustaining stronger large-breed dry food demand from suburban households. Regional veterinary schools in Lyon and Saint-Étienne feed talent pipelines for preventive nutrition counseling expansion. Saint-Genis-Laval hosts specialized co-packers serving prescription diet manufacturers.
Brittany
Atlantic fishery proximity enables region-specific protein sourcing for wet food formulations targeting local consumer loyalty. SME manufacturers face HACCP retrofit pressure from EU Feed Hygiene Regulation compliance deadlines. Saint-Malo and Lorient concentrate cold-chain logistics infrastructure for fresh ingredient handling.
Occitanie
Toulouse and Montpellier present underpenetrated terrain for specialty retail expansion outside the Paris-Lyon corridor. Insect protein pilot programs near Narbonne leverage regional agricultural research capacity for novel feed ingredient development. Mediterranean climate sustains outdoor dog ownership patterns supporting larger format dry food consumption.
Provence-Alpes-Côte d'Azur
Affluent coastal households in Nice and Marseille trade up to premium assortments with freshness signaling claims. Seasonal population fluctuations create demand volatility requiring flexible distributor inventory management. Sophia Antipolis technology cluster incubates subscription platform startups targeting digitally native pet owners.
France Pet Food Market Competitive Landscape
Premium-margin players sit above commodity-margin players across veterinary authorization and ingredient traceability dimensions, with prescription diet portfolios commanding 40-60% price premiums over mass retail equivalents. The vendor base stratifies into three tiers: multinational CPG conglomerates with captive manufacturing, mid-cap specialists leveraging region-specific protein sourcing, and private label co-packers serving hypermarket channels. Dominant competitive moves include veterinary channel exclusivity agreements and facility HACCP upgrades to secure ANSES compliance authorization.
Within the multinational tier, Mars Incorporated and Nestle Purina Petcare anchor mass-market volume through established production infrastructure, while Royal Canin occupies a distinct position emphasizing veterinary channel prescription diet specialization. Among domestic specialists, Affinity Petcare exemplifies region-specific sourcing strategies tied to Breton consumer preferences. These three entities represent the primary competitive archetypes: scale-driven CPG, veterinary-authorized therapeutic, and regionally anchored specialty.
| Leading Market Players |
|---|
| Hill's Pet Nutrition |
| Archer Daniels Midland |
| Royal Canin |
| Groupe Legris Industries |
| Colgate-Palmolive |
| Mars Incorporated |
| Affinity Petcare |
| Virbac |
| Nestle Purina Petcare |
| Others |
Supply & Pricing Matrix
Atlantic fishery price indices and Southwest poultry feed cost benchmarks cascade through Breton wet food supply chains, compressing margin pools at economy tiers while veterinary-authorized premiums in Greater Paris absorb input volatility through subscription lock-in.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the French market, with ANSES compliance certification and veterinary channel authorization serving as the primary price differentiation drivers. Pricing pressure stems from private label expansion in hypermarket channels, eroding branded dry food margins. Economy-tier buyers in Brittany and Occitanie exhibit highest price sensitivity, while subscription-dependent urban households in Île-de-France show lowest elasticity.
Supply Chain Analysis
Freight cost differentials between Atlantic port facilities and inland distribution centers concentrate wet food manufacturing in Saint-Malo and Lorient corridors. Raw material sourcing draws from Atlantic fishery operations, Southwest poultry integrators, and Normandy cereal processors. Single-source vulnerability in region-specific protein inputs exposes Breton manufacturers to quota fluctuations. Distribution runs through veterinary clinic networks, specialty retail chains, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France pet food market compounds steadily as pet humanization in Île-de-France and Auvergne-Rhône-Alpes sustains premium format demand regardless of macroeconomic cycles.
For Market Incumbents: Lock in veterinary channel exclusivity agreements before clinic consolidation accelerates, and accelerate HACCP facility retrofits to preempt ANSES enforcement actions that would disqualify non-compliant products from prescription authorization. Private label encroachment in hypermarket dry food segments demands defensive portfolio pruning toward wet format specialization. For New Entrants and Emerging Players: EFSA novel food approvals in Europe open a window for insect protein hypoallergenic formulations targeting sustainability-motivated urban households. Occitanie and Provence-Alpes-Côte d'Azur specialty retail underpenetration offers white-space positioning outside Paris-Lyon corridor dominance. Direct-to-consumer subscription platforms with algorithmic portion customization provide the most penetrable go-to-market angle for digitally native customer acquisition. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale manufacturers possessing ANSES-authorized production infrastructure and established veterinary clinic relationships. Five-to-ten-year viability hinges on circular packaging compliance rather than volume scale. Monitor EFSA processing approvals for novel protein sources as the inflection signal for sustainable formulation leadership transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Exclusivity Agreement | Prescription diet authorization locks in recurring revenue streams through clinic-based preventive nutrition counseling. |
| HACCP Facility Certification | EU Feed Hygiene Regulation compliance qualifies manufacturers for ANSES veterinary channel authorization. |
| Mono-Material Packaging Pilot | DGCCRF recyclability surveillance demands design-for-recycling standards ahead of EU packaging waste directive deadlines. |
| Insect Protein Formulation Launch | EFSA novel food approvals enable sustainable protein diversification for hypoallergenic therapeutic diets. |
| Subscription Platform Development | Algorithmic replenishment captures convenience-driven urban households in Île-de-France with recurring revenue models. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with veterinary nutritionists, specialty retail category managers, manufacturing operations directors, and DGCCRF enforcement officials with secondary validation through ANSES contaminant threshold publications, EU Feed Hygiene Regulation compliance databases, customs trade records, and Nielsen retail audit data. Bottom-up volume modeling and top-down value estimation triangulated to cross-verify segment outputs.
Historical reference periods anchored the projection horizon, with analytical frameworks modeling product type, pet species, sales channel, packaging format, and regional urban density tier dimensions. CAGRs derived from trend extrapolation adjusted for regulatory inflection points and channel shift velocities. Forecast inputs incorporated ANSES guideline revision timelines and EU packaging waste directive compliance schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Atlantic fishery quota disruptions or accelerated veterinary clinic consolidation. Model outputs reflect documented assumptions on pet humanization elasticity and subscription adoption curves. A model refresh is warranted upon material change in EFSA novel protein approval timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Corrector Spray Market
Pet Care Products
Organic Pet Food Market
Pet Care Products
Frozen Pet Food Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
US Dog Food Market
Pet Care Products
UK Pet Training Services Market
Pet Care Products
Pet Tick and Flea Prevention Market
Pet Care Products
Dog Life Jacket Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
Smart Pet Camera Market
Pet Care Products
Taiwan Pet Food Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Pet Selfie Tools Market
Pet Care Products
Herbal Pet Shampoo Market
Pet Care Products
Hair Dryer for Pets Market