
 Russia Automotive Eps Market | 2026-2036
Russia Automotive Eps Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Automotive Eps Market Analytics
Multi-source procurement for electric power steering subassemblies is pivoting toward hybrid models that blend captive production with qualified external suppliers. JTEKT Corporation leverages its integrated motor-and-gear production lines to serve Russian OEM programs with reduced logistics exposure. ZF Friedrichshafen AG anchors its position through localized rack-and-pinion assembly capacity that bypasses cross-border component bottlenecks. Robert Bosch GmbH competes by sustaining electronics module sourcing flexibility across multiple certified foundries.
Russia Automotive EPS denotes an electromechanical steering assistance system where a brushless DC motor applies torque to the steering column or rack, replacing hydraulic pumps and fluid circuits with a controller unit drawing under 80 amps at peak load. Its primary purpose is to reduce fuel consumption by eliminating engine-driven hydraulic parasitic losses while enabling lane-keeping and automated parking functions. Passenger Vehicles occupies the dominant application tier due to volume scale across compact and mid-size platforms, while Electric Vehicles represents the fastest-expanding segment as native high-voltage architectures integrate steer-by-wire readiness. Injection Molding dominates the technology dimension for housing and gear casing production, though Compression Molding retains relevance for noise-dampening mount components where material porosity controls vibration transmission.
Rosstandart enforces GOST R certification for steering system safety and electromagnetic compatibility, while the Eurasian Economic Commission's TR CU 018/2011 technical regulation mandates type approval before market placement across the customs union. These frameworks compel suppliers to maintain in-country testing partnerships and documentation archives that lengthen qualification cycles but raise barriers to unregistered imports. Stakeholders must monitor how Russia's import-substitution directives and evolving automotive localization thresholds reshape supplier eligibility criteria for state-backed fleet procurement programs.

Market Dynamics
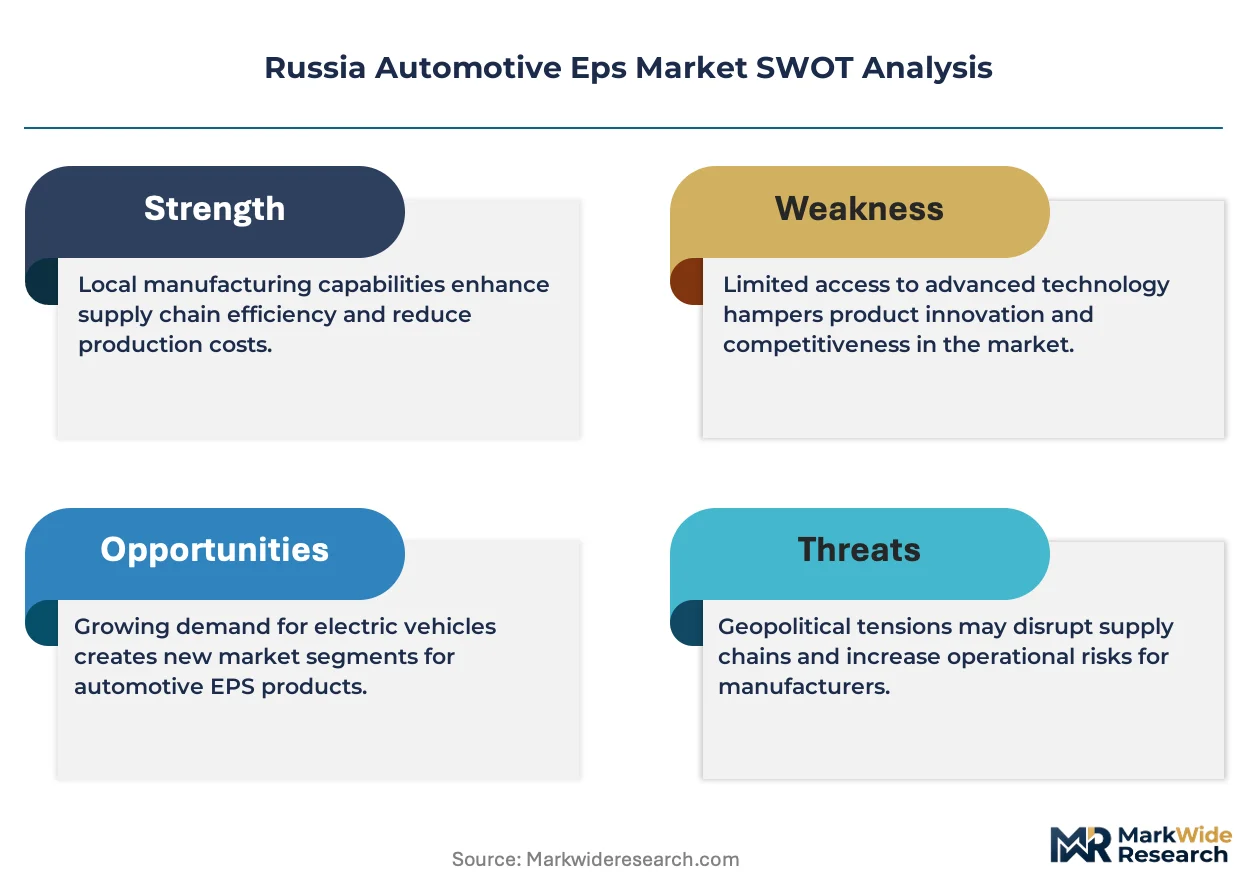
Russia's import-substitution mandate is restructuring the Automotive EPS supplier base, compelling foreign component makers to localize motor winding and controller assembly within the Eurasian Economic Union customs territory or forfeit state fleet procurement eligibility.
Growth Catalysts
- TR CU 018/2011 type-approval mandates:Technical regulations from the Eurasian Economic Commission create compliance barriers that filter out non-certified imports, expanding addressable market share for registered domestic assembly operations.
- Brushless DC motor architectures:Native high-voltage electric vehicle platforms demand EPS systems with steer-by-wire readiness, pulling advanced electromechanical designs into mid-volume production schedules.
- Central Federal District clustering:Moscow-region assembly plants concentrate demand within a 300-kilometer radius, reducing inbound logistics costs for tier-1 suppliers maintaining regional warehousing footprints.
Market Restraints
- Semiconductor input volatility:Controller unit ASICs and MOSFET arrays face sourcing instability from East Asian foundries, compressing gross margins on EPS electronics modules.
- Rosstandart certification timelines:GOST R safety and electromagnetic compatibility testing extends product qualification cycles by 8-14 months versus comparable European homologation procedures.
- Hydraulic steering residual presence:Heavy commercial vehicle segments retain engine-driven pump systems for load-bearing durability, capping EPS penetration in high-torque applications.
Strategic Opportunities
- Volga Federal District expansion:Nizhny Novgorod and Togliatti assembly corridors remain undersupplied relative to Central District density, offering first-mover warehouse positioning advantages.
- State-backed fleet electrification:Russian government procurement directives for municipal and federal vehicle fleets mandate escalating local content ratios, qualifying localized EPS suppliers for preferential contract awards.
- Injection molding-compression molding hybridization:Gear housing production lines that combine high-precision injection for structural casings with porosity-controlled compression for vibration-dampening mounts command premium positioning.
Industry Challenges
- Embedded software certification backlog:Functional safety validation under ISO 26262 for EPS controller firmware strains in-country testing partnership capacity, delaying program launches.
- Cross-border tier-2 supplier fragility:Gear cutting and bearing subcomponent sourcing from Baltic states faces customs friction, forcing expedited requalification of alternative Eurasian suppliers.
- High-voltage architecture integration complexity:Steer-by-wire readiness requirements demand coordination between EPS motor windings and vehicle-level 400V+ power distribution systems, stretching systems engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Automotive Eps Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Insulation, Soundproofing, Structural Foam, Reusable Molds End User: Vehicle Manufacturers, Aftermarket Suppliers, Tier-1 Suppliers, Custom Fabricators Technology: Injection Molding, Blow Molding, Compression Molding, Extrusion Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles |
| Companies Covered | JTEKT Corporation, ZF Friedrichshafen AG, NSK Ltd, Nexteer Automotive Corporation, Robert Bosch GmbH, Mitsubishi Electric Corporation, GKN PLC, Denso Corporation, Hyundai Mobis Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Automotive Eps Market Evolving Landscape
Electromechanical steering architectures are displacing hydraulic assistance across Russian passenger vehicle platforms, while regulatory pressure on electromagnetic compatibility and functional safety accelerates design standardization.
Rack-mounted EPS configurations with integrated brushless DC motors is overtaking column-mounted designs in compact and mid-size vehicle segments. AvtoVAZ and GAZ Group assembly programs specify rack-mounted units for packaging efficiency and steering feel precision. This topology is compressing demand for standalone steering column suppliers and consolidating subsystem sourcing toward full-rack integrators.
Rosstandart's tightened electromagnetic compatibility enforcement under GOST R 51317 series standards is forcing controller PCB redesigns with enhanced shielding and filtered power entry. Industrial consequence includes mandatory in-country EMC chamber testing that extends development cycles. Passenger vehicle platforms with advanced driver assistance features face the steepest compliance burden, driving tier-1 suppliers toward pre-certified modular controller architectures.
Buyer concentration among Moscow-region OEMs is consolidating procurement decisions into centralized technical committees that specify pan-platform EPS standards. Tier-2 component distributors serving regional assembly plants face disintermediation as tier-1 integrators establish direct supplier-managed inventory programs. This concentration is most visible in the Central Federal District, where three final assemblers account for the majority of annual EPS call-off volumes.
Russia Automotive Eps Market Segmentation
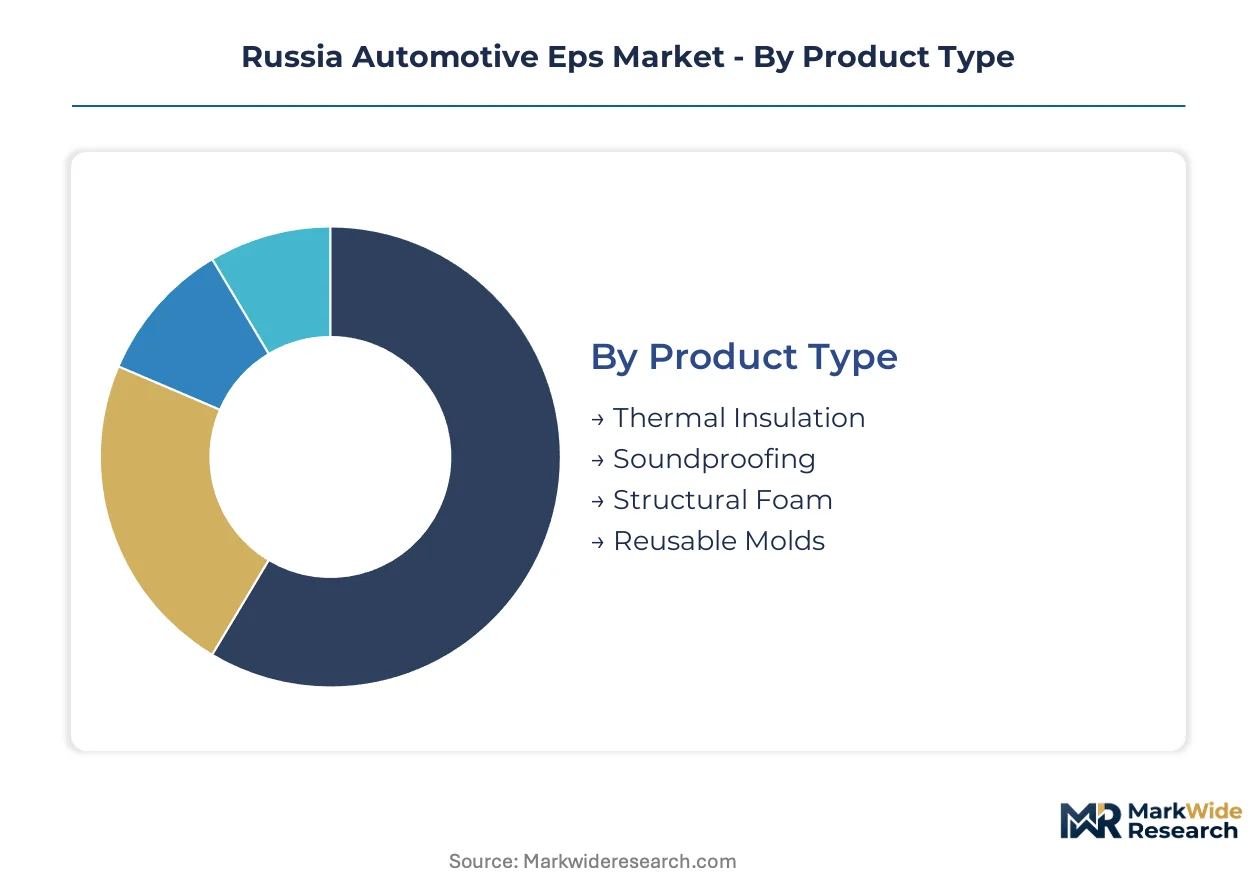
Russia Automotive EPS procurement patterns diverge sharply across product architectures and customer tiers. Segmentation reveals where localization mandates concentrate compliance investment and where import substitution creates supplier switching opportunities.
Product Type:
Volume production favors standardized thermal and acoustic solutions, while specialized structural applications command premium positioning.
- Thermal Insulation:Expanded polypropylene and melamine foam laminates manage heat flux from brushless DC motor windings and controller housings. AvtoVAZ assembly lines in Togliatti specify this grade for under-bonnet EPS electronics protection.
- Soundproofing:Multi-layer acoustic barriers with mass-loaded vinyl cores dampen gear mesh noise in rack-mounted EPS units. Demand clusters in Moscow-region premium vehicle programs where cabin refinement thresholds exceed baseline segment requirements.
- Structural Foam:Rigid polyurethane cores reinforce steering column mounting brackets without metallic mass penalties.
- Reusable Molds:Aluminum toolsets for prototype and low-volume EPS housing validation reduce per-unit tooling amortization for GAZ Group niche platforms.
Mature deployment sits with Thermal Insulation. Newer deployment is concentrated in Structural Foam.
End User:
Procurement authority concentrates at the tier-1 integrator level, though state fleet mandates are elevating vehicle manufacturer direct sourcing.
- Vehicle Manufacturers:AvtoVAZ, GAZ Group, and Moscow-region OEMs wield specification authority over EPS subsystem architectures. Their centralized technical committees increasingly mandate Eurasian Economic Union local content ratios for state procurement eligibility.
- Aftermarket Suppliers:Independent distributors service aging hydraulic-to-EPS conversion demand in regions beyond Central Federal District service coverage.
- Tier-1 Suppliers:JTEKT, ZF, and Bosch maintain direct supplier-managed inventory programs with Moscow-region assembly plants.
- Custom Fabricators:Small-batch specialists produce EPS mounting brackets and adapter plates for commercial vehicle retrofit applications.
Established sourcing relationships dominate Tier-1 Suppliers. Emerging sourcing flexibility is concentrated in Vehicle Manufacturers.
Technology:
Process selection tracks precision requirements and production scale, with hybrid methods gaining traction for complex EPS housings.
- Injection Molding:High-pressure thermoplastic injection produces dimensionally precise gear casings and motor housings with cycle times under 60 seconds. Central Federal District suppliers favor this method for volume call-off schedules from Moscow-region OEMs.
- Compression Molding:Controlled porosity in glass-mat thermoplastic composites yields vibration-dampening EPS mount components. The process retains relevance where acoustic isolation outweighs structural loading demands.
- Blow Molding:Hollow-section ducting for EPS controller cooling channels reduces material usage versus solid extrusion.
- Extrusion:Continuous profile production generates sealing gaskets and wire conduit for EPS wiring harness protection.
High-volume deployment sits with Injection Molding. Specialized deployment is concentrated in Compression Molding.
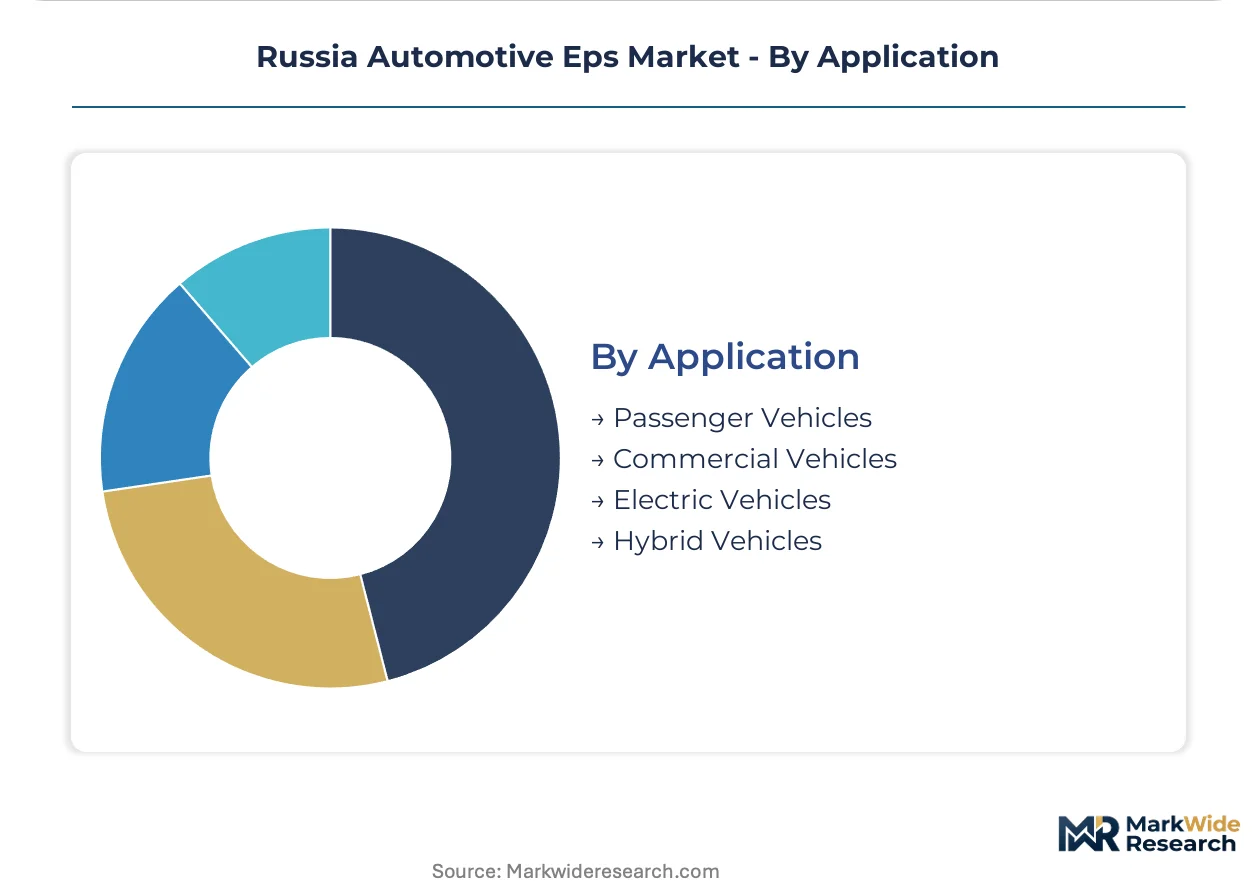
Application:
Platform electrification is redrawing segment boundaries as high-voltage architectures demand steer-by-wire-ready EPS designs.
- Passenger Vehicles:Compact and mid-size platforms generate the largest annual EPS call-off volumes. Rack-mounted configurations with integrated brushless DC motors dominate AvtoVAZ and GAZ Group specifications for packaging efficiency.
- Electric Vehicles:Native 400V+ architectures require EPS systems with redundant torque sensors and fail-operational controller firmware. This segment is expanding most quickly as Russian state fleet electrification mandates accelerate platform development.
- Commercial Vehicles:Heavy-duty segments retain hydraulic steering for load-bearing durability, capping EPS penetration in high-torque applications.
- Hybrid Vehicles:Dual-powertrain platforms demand EPS designs compatible with both 12V auxiliary and high-voltage propulsion electrical systems.
Volume concentration sits with Passenger Vehicles. Steepest expansion trajectory is concentrated in Electric Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and copper feedstock availability from the Ural Mountains anchors Russia's automotive component manufacturing base. Domestic OEMs source EPS motor laminations and controller housings from metallurgical clusters near Chelyabinsk and Magnitogorsk. Rosstandart certification requirements and Eurasian Economic Union technical regulations shape supplier qualification timelines across all production zones.
Central Federal District
Moscow-region assembly plants generate the densest EPS call-off volumes in Russia. TR CU 018/2011 type-approval mandates from the Eurasian Economic Commission filter supplier eligibility for state procurement programs. Togliatti and the surrounding Samara Oblast corridor concentrate AvtoVAZ production lines that specify rack-mounted EPS configurations for compact vehicle platforms.
Volga Federal District
Nizhny Novgorod and Kazan assembly corridors remain undersupplied relative to Central District density. GAZ Group specifications for commercial vehicle EPS retrofits pull demand toward hybrid hydraulic-electromechanical systems. Local warehousing gaps force tier-1 suppliers to maintain extended inventory buffers for just-in-sequence delivery to Gorky Automobile Plant facilities.
Northwestern Federal District
St. Petersburg automotive cluster hosts foreign OEM joint ventures with elevated import content thresholds. Rosstandart electromagnetic compatibility testing under GOST R 51317 series standards extends product qualification cycles for controller modules. The region's Baltic Sea port access historically facilitated gear cutting and bearing subcomponent imports now facing customs friction.
Siberian Federal District
Krasnoyarsk and Novosibirsk industrial zones concentrate aftermarket EPS conversion demand for aging vehicle fleets. Remote service coverage gaps sustain independent distributor networks for hydraulic-to-electromechanical steering retrofits. Regional technical universities partner with tier-2 suppliers for localized motor winding training programs.
Southern Federal District
Rostov-on-Don and Krasnodar assembly nodes serve agricultural and commercial vehicle segments with residual hydraulic steering preference. State-backed fleet electrification mandates are pulling 400V-ready EPS designs into municipal vehicle procurement specifications. The region's Black Sea port infrastructure supports limited direct component import channels bypassing Central District distribution hubs.
Russia Automotive Eps Market Competitive Landscape
Localization mandates dominate the current landscape as foreign component makers establish Eurasian Economic Union assembly capacity. The supplier base consolidates around tier-1 integrators with direct OEM relationships and captive motor-controller production. Three archetypes occupy distinct positions: full-system integrators with rack-and-pinion assembly lines, electronics specialists focusing on controller firmware and torque sensors, and hybrid producers blending captive manufacturing with qualified external gear sourcing. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers seek to meet Rosstandart certification timelines and state fleet procurement eligibility thresholds.
Among Japanese- and German-based tier-1 suppliers, JTEKT Corporation, ZF Friedrichshafen AG, and Robert Bosch GmbH occupy positions exemplifying the full-system integrator archetype. JTEKT represents integrated motor-and-gear production approaches that reduce logistics exposure for Russian OEM programs. ZF anchors its competitive stance through localized rack-and-pinion assembly capacity designed to bypass cross-border component bottlenecks. Bosch exemplifies electronics module sourcing flexibility across multiple certified foundries, a pattern that addresses semiconductor input volatility affecting controller unit production.
| Leading Market Players |
|---|
| JTEKT Corporation |
| ZF Friedrichshafen AG |
| NSK Ltd |
| Nexteer Automotive Corporation |
| Robert Bosch GmbH |
| Mitsubishi Electric Corporation |
| GKN PLC |
| Denso Corporation |
| Hyundai Mobis Co |
| Others |
Value Network & Pricing Analysis
Moscow-region OEM technical committees concentrate procurement authority for rack-mounted EPS configurations, compressing supplier margins through consolidated volume negotiations and standardized pan-platform specifications. This buyer concentration shifts pricing power toward tier-1 integrators with captive motor-controller production, while tier-2 distributors face disintermediation.
Pricing Analysis
Warranty and field-service bundling separates full-system integrators from component-only suppliers, with JTEKT and ZF commanding premium positioning through embedded calibration support and rapid-response technical teams. Price differentiation rests on Rosstandart GOST R certification tier and local content ratio eligibility for state fleet procurement. Cost compression in electronics modules is intensifying because semiconductor input volatility from East Asian foundries squeezes controller unit margins. Aftermarket conversion specialists serving Siberian and Southern Federal Districts exhibit highest price sensitivity, while Central Federal District OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Inbound freight costs from East Asian semiconductor foundries and German precision gear-cutting operations dominate landed cost structures for controller ASICs and rack-and-pinion subassemblies. Motor laminations and copper windings draw from Ural Mountain metallurgical clusters near Chelyabinsk and Magnitogorsk, while rare-earth magnet sourcing hinges on Chinese processed neodymium supply. Single-source vulnerability in brushless DC motor controller firmware creates qualification bottlenecks. Distribution runs through tier-1 integrator direct supplier-managed inventory programs anchored at Moscow-region assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive motor winding and controller assembly capacity determines state procurement eligibility. Players are pursuing backward integration into semiconductor sourcing partnerships and in-country EMC testing infrastructure.
For Market Incumbents: Anchor defensive positioning through accelerated Rosstandart certification pipeline investment and exclusive warehousing partnerships in the undersupplied Volga Federal District. Threat of emerging domestic motor-winding specialists with state-backed localization mandates demands pre-emptive capacity lock-up in Nizhny Novgorod corridor. Priority lever: direct supplier-managed inventory programs that disintermediate tier-2 distributors.
For New Entrants and Emerging Players: Tier-2 gear-cutting and bearing subcomponent distributors represent the most penetrable channel archetype, particularly in Siberian Federal District aftermarket conversion demand. White-space targets include commercial vehicle hybrid hydraulic-electromechanical retrofit systems and municipal fleet 400V-ready EPS specifications. Go-to-market angle: technical training partnerships with regional universities for localized motor winding qualification.
For Investors and Strategic Acquirers: The window for entry favors electronics specialists with ISO 26262 functional safety validation capabilities and existing Eurasian Economic Union assembly footprint. Long-term viability centers on acquisition of controller firmware developers with cleared Rosstandart EMC testing backlogs. Signal to watch: state fleet electrification mandate acceleration shifting local content ratio thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Motor Winding Localization | Captive production in Eurasian Economic Union territory secures state procurement eligibility under TR CU 018/2011. |
| Controller Firmware Certification | ISO 26262 functional safety validation clears Rosstandart backlog and accelerates program launch timelines. |
| Volga District Warehousing | First-mover positioning in Nizhny Novgorod reduces logistics exposure to GAZ Group assembly corridors. |
| Semiconductor Sourcing Partnership | Multi-foundry agreements with East Asian suppliers buffer ASIC and MOSFET input volatility. |
| Steer-by-Wire R&D Investment | Native high-voltage architecture compatibility captures Electric Vehicle segment expansion trajectory. |
Research Methodology
Multi-period observation of vehicle production call-off volumes, Rosstandart certification timelines, and tier-1 supplier inventory positioning anchored the trend analysis, supplemented by interviews with OEM platform engineers, tier-1 procurement leads, aftermarket distributors, and EMC testing laboratory directors. Secondary validation drew from Eurasian Economic Commission TR CU 018/2011 regulatory filings, vehicle registration databases, customs import records for steering system components, and metallurgical cluster output reports from Chelyabinsk and Magnitogorsk. Bottom-up segment sizing triangulated against top-down macroeconomic automotive production forecasts.
Segment-weighting approaches applied differential growth assumptions across passenger vehicle, electric vehicle, commercial vehicle, and hybrid vehicle propulsion architectures. Modeled dimensions included rack-mounted versus column-mounted EPS topology, injection molding versus compression molding process selection, and Central versus Volga versus Siberian Federal District demand clustering. CAGRs were derived from production volume trajectories and content-per-vehicle penetration curves. Industry-specific inputs incorporated brushless DC motor adoption rates and state fleet electrification procurement mandate intensity.
Caveats apply where semiconductor supply disruptions, Rosstandart certification timeline extensions, or Eurasian Economic Union technical regulation amendments could materially shift the outlook. Forecasts reflect assumptions about localization threshold enforcement and import-substitution policy continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
Automotive LED Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
Switchrack Assemblies Market
Automotive Electrical & Electronics
China Electric Power Steering Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
Motor Vehicle Sensor Market
Automotive Electrical & Electronics
Germany X by Wire Systems Market
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Automotive Electronic Expansion Valve Market
Automotive Electrical & Electronics
Automotive Esim Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market