
 Automotive Alternator Market | 2026-2036
Automotive Alternator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Alternator Market Intelligence
The transition to 48-volt mild-hybrid architectures is tilting alternator design toward higher power density and integrated starter-generator units. Denso Corporation leverages its semiconductor expertise to control the integrated power module segment. Robert Bosch GmbH anchors European supply relationships through localized production networks. Mitsubishi Electric Corporation competes on thermal management innovation for brushless platform variants.
An automotive alternator converts mechanical energy from the engine into electrical power through electromagnetic induction, typically generating 12V or 48V output at 1,000–6,000 RPM rotor speeds to charge batteries and supply vehicle electrical loads. Brushless alternators are gaining share in premium applications where reduced maintenance and extended service life justify unit cost premiums. High output alternators represent the fastest-expanding product category as commercial trucks and construction machinery add electric auxiliary systems. OEMs capture the dominant end-user channel through long-term platform contracts, while aftermarket suppliers occupy fragmented regional service networks.
NHTSA fuel economy mandates and EPA tailpipe emissions rules in the United States are forcing automakers to adopt higher-efficiency charging systems that reduce parasitic engine load. ECE regulations in Europe and China's GB standards for vehicle electrical systems are converging on stricter efficiency testing protocols that favor brushless and compact alternator designs. Stakeholders must monitor how 48-volt architecture penetration rates across passenger and commercial vehicle segments reshape supplier qualification requirements and capital allocation priorities.
Market Dynamics
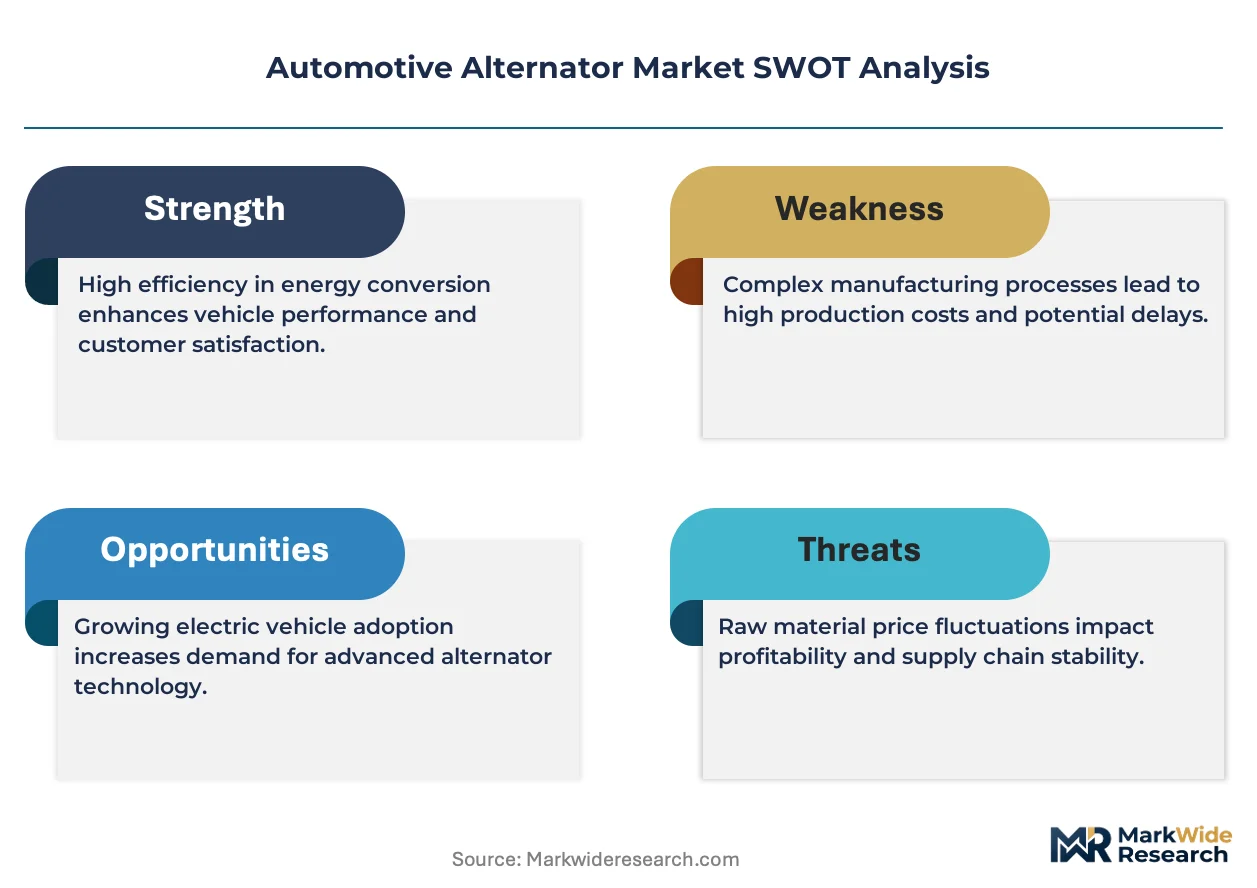
The 48-volt mild-hybrid transition is compressing legacy 12-volt architectures and forcing suppliers to requalify around integrated starter-generator specifications. This voltage migration is redrawing component boundaries and capital allocation priorities across the supply base.
Growth Catalysts
- EPA tailpipe mandates:NHTSA fuel economy rules compel automakers to adopt higher-efficiency charging systems that reduce parasitic engine load across light-duty and commercial vehicle platforms.
- Commercial fleet electrification:Fleet operators pursuing lower total cost of ownership are expanding investments in high-output charging systems for electric auxiliary systems on trucks and construction machinery.
- China's domestic production scaling:Local supply chain maturation and GB standards convergence are concentrating demand as domestic vehicle production volumes expand.
Market Restraints
- Copper and rare earth price volatility:Magnet materials and winding copper expose margins to commodity swings that compress unit economics for brushless platform variants.
- Semiconductor supply concentration:Integrated power module dependency on East Asian foundry capacity creates qualification bottlenecks for 48-volt system ramps.
- Legacy 12-volt infrastructure lock-in:Decades of vehicle electrical system standardization create friction against voltage architecture transitions in aftermarket service networks.
Strategic Opportunities
- India commercial vehicle electrification:PLI scheme incentives for automotive component manufacturing are opening qualification pathways for localized alternator production.
- Construction machinery electrification:Electric auxiliary systems on excavators and loaders represent underpenetrated demand for high-output brushless units.
- ISO 26262 functional safety convergence:Emerging requirements for generator control systems create certification-based differentiation for suppliers with semiconductor integration capabilities.
Industry Challenges
- Power electronics talent scarcity:Integrated starter-generator development requires embedded software and thermal management expertise that competes with broader automotive electronics hiring.
- Dual voltage platform complexity:Engineering organizations must maintain parallel 12-volt and 48-volt development tracks while managing legacy service part obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Alternator Market |
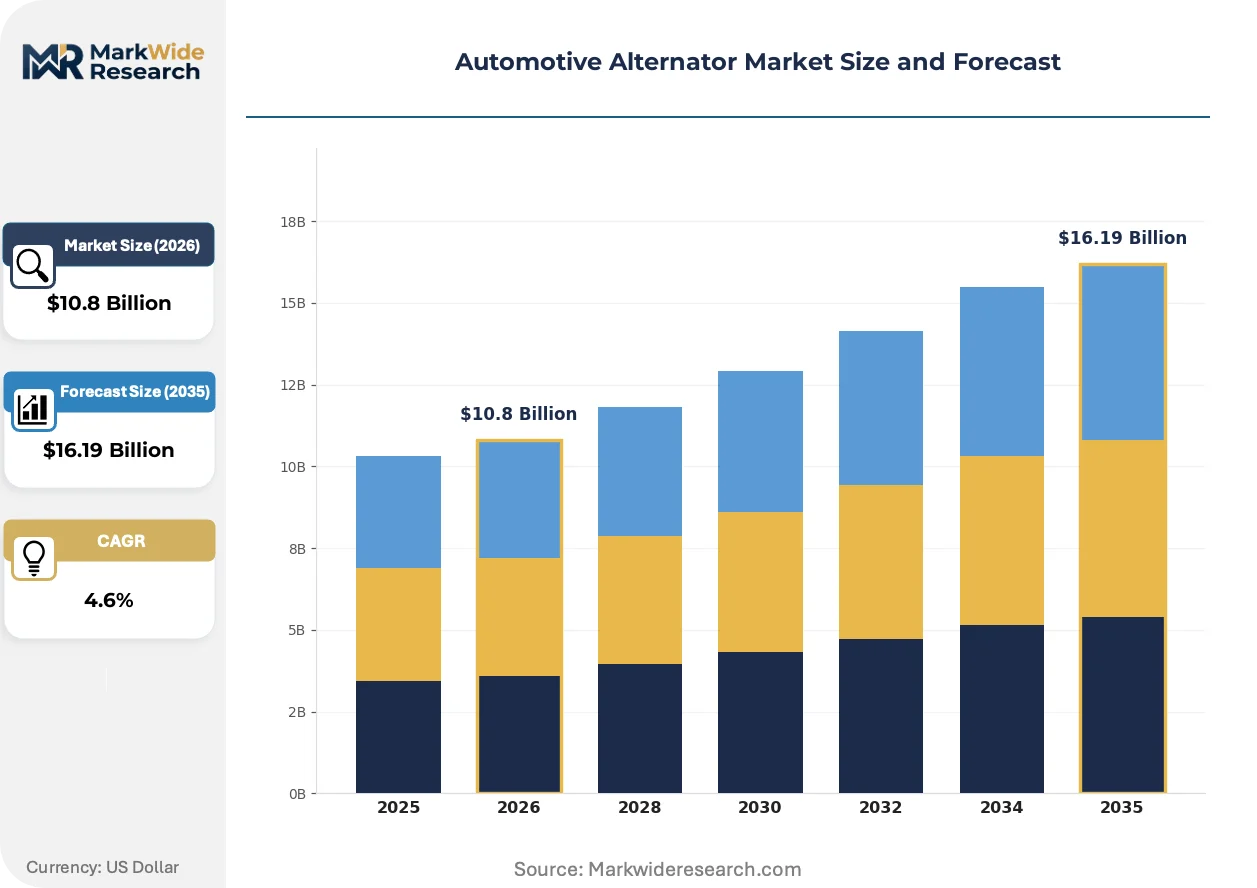
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $16.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brush Alternators, Brushless Alternators, High Output Alternators, Compact Alternators, Heavy Duty Alternators Technology: Voltage Regulator, Internal Fan Cooling, External Fan Cooling, Rectifier Type, Slip Ring Type Application: Passenger Vehicles, Commercial Trucks, Construction Machinery, Agricultural Equipment, Two-Wheelers End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Repair Shops |
| Companies Covered | Mitsubishi Electric Corporation, HELLA GmbH & Co. KGaA, Denso Corporation, Mitsuba Corp., Cummins Inc, Valeo, Hitachi Astemo, Ltd., BorgWarner Inc., Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Alternator Market Strategic Shifts & Innovations
Alternator technology is fragmenting across voltage tiers as electrification depth varies by vehicle segment and regional regulatory intensity. Suppliers are repositioning around thermal management and power density rather than commodity volume.
Brushless alternator architectures are hybridizing permanent magnet and claw-pole designs to capture efficiency gains without full rare earth dependency. Premium passenger and commercial truck segments are adopting these variants fastest. The technology is hybridizing maintenance intervals and service life expectations, compressing aftermarket replacement revenue pools.
China's GB standards for vehicle electrical systems are converging with ECE efficiency testing protocols, creating transnational qualification benchmarks. Automakers face unified test cycles that favor compact, brushless designs with documented parasitic loss reductions. European and Chinese passenger vehicle segments are responding with accelerated 48-volt platform commitments.
Fleet procurement is consolidating around total cost of ownership models that unbundle alternator specification from engine supplier packages. Large commercial operators in North America are negotiating direct component sourcing agreements. This pattern is most visible in long-haul trucking where electrified auxiliary loads dominate specification decisions.
Automotive Alternator Market Segmentation
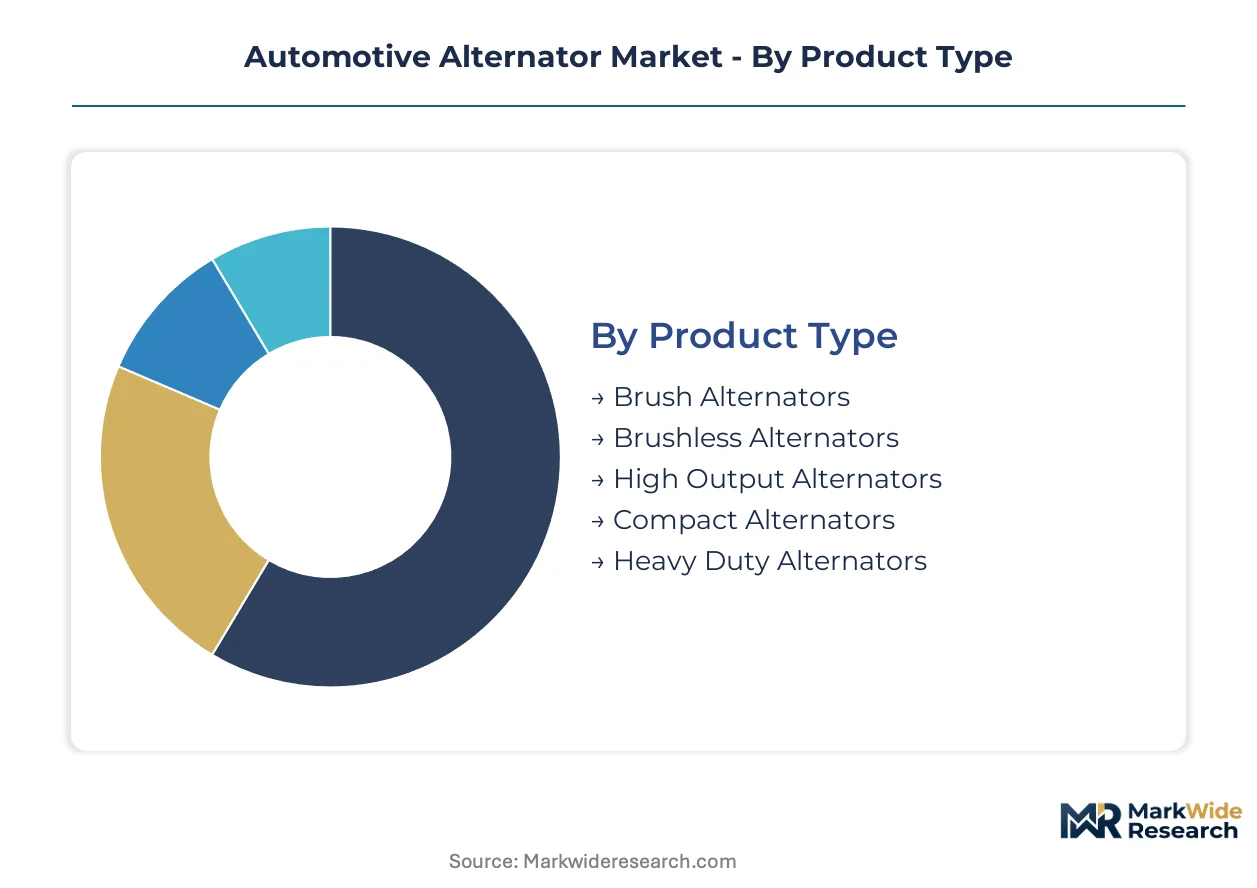
Alternator market segmentation reveals divergent replacement cycles across product tiers, with brushless platforms extending service intervals while high-output units face accelerated wear from electrified auxiliary loads. Technology and application boundaries are blurring as 48-volt architectures force cross-category engineering investments.
Product Type:
Replacement frequency varies dramatically across this category, with brush-based designs turning over fastest in aftermarket channels while brushless units stretch OEM platform lifecycles.
- Brush Alternators:Claw-pole rotor designs with carbon brush contact systems dominate legacy vehicle parc and price-sensitive replacement demand. Fleet operators in the United States running older commercial truck platforms sustain volume through high-turnover maintenance schedules.
- Brushless Alternators:Permanent magnet and induction-based designs eliminate wear components, extending service intervals beyond 250,000 miles in long-haul applications. Premium passenger segments in Germany and Japan specify these variants for reduced total cost of ownership despite 40-60% unit cost premiums.
- High Output Alternators:200A+ rated units serve electric auxiliary systems on refrigerated trucks and construction machinery. Demand concentrates where fleet electrification investments outpace 48-volt platform transitions.
- Compact Alternators:Reduced envelope designs integrate with downsized engine bays in passenger vehicles. Chinese domestic OEMs specify these for front-wheel-drive platform density requirements.
- Heavy Duty Alternators:Reinforced bearing systems and enhanced thermal management address continuous-duty commercial and off-highway applications. Mining and agricultural equipment specifications drive qualification requirements.
Brush alternators anchor the volume base in aftermarket channels while brushless designs gain share at the steepest rate through OEM platform commitments.
Technology:
Cost tier differentiation separates commodity electromechanical components from semiconductor-integrated control systems commanding engineering premiums.
- Voltage Regulator:Solid-state and electromechanical variants manage field current to maintain stable output across RPM ranges. Integrated circuit-based designs with LIN bus communication are displacing discrete component architectures in European passenger vehicle platforms.
- Internal Fan Cooling:Integrated rotor-mounted impellers reduce external envelope requirements but limit peak thermal capacity. Compact passenger vehicle applications in Japan and South Korea favor this configuration for packaging efficiency.
- External Fan Cooling:Separate blower assemblies enable higher continuous output ratings for commercial truck and construction machinery duty cycles. North American heavy-duty specifications require this thermal management approach.
- Rectifier Type:Diode bridge configurations convert AC rotor output to DC battery charging current. Press-fit and soldered assembly variants create tiered reliability and cost positioning.
- Slip Ring Type:Copper-carbon contact systems or wireless inductive power transfer methods deliver field current to rotating rotors. Inductive designs eliminate maintenance in premium brushless platforms.
Conventional electromechanical technologies sustain aftermarket margins while semiconductor-integrated voltage regulation expands fastest through 48-volt system mandates.
Application:
Customer type concentration separates high-volume standardized supply from specification-intensive direct procurement relationships.
- Passenger Vehicles:12-volt and 48-volt architectures span mass-market through luxury segments with divergent power density requirements. Chinese and European OEMs are accelerating 48-volt mild-hybrid commitments that reshape supplier qualification criteria.
- Commercial Trucks:Sleeper cab auxiliary loads and electrified trailer systems drive 200A+ output requirements. United States fleet operators negotiate direct component sourcing outside engine supplier packages to optimize total cost of ownership.
- Construction Machinery:Electric auxiliary systems on excavators and loaders create underpenetrated demand for high-output brushless units. Equipment rental fleets in the United States and Germany are standardizing electrified specifications.
- Agricultural Equipment:Seasonal duty cycles and field-contaminated environments demand sealed bearing systems and enhanced corrosion protection. Brazilian and Indian tractor manufacturers specify locally sourced alternators for cost positioning.
- Two-Wheelers:Compact single-phase designs serve motorcycle and scooter electrical loads with minimal packaging envelopes. India's domestic two-wheeler production sustains high-volume demand for standardized 12-volt units.
Passenger vehicle applications concentrate volume through platform standardization while commercial truck specifications gain share fastest through fleet direct procurement.
End User:
Supply concentration patterns distinguish consolidated OEM channel relationships from fragmented regional aftermarket networks.
- OEMs:Long-term platform contracts with integrated starter-generator specifications lock in supplier engineering resources. Volkswagen Group, Toyota, and Stellantis qualification processes span 24-36 month development cycles.
- Aftermarket Suppliers:Regional distributors and private label brands serve vehicle parc replacement demand through price-competitive sourcing. United States and European aftermarket channels fragment across national distribution networks.
- Vehicle Assemblers:Contract manufacturers and kit assembly operations procure alternators as part of complete powertrain modules. Indian and Thai export-oriented assembly plants drive volume through cost-optimized specifications.
- Repair Shops:Independent service networks and dealership service departments execute warranty and post-warranty replacements. Diagnostic capability requirements are rising with 48-volt system complexity.
OEM channel relationships anchor revenue concentration through platform lock-in while aftermarket suppliers gain share fastest through expanding vehicle parc and extended service intervals on premium platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal pronounced asymmetries across major automotive manufacturing zones. China maintains substantial alternator component trade surpluses while Germany and Japan balance high-value unit exports against rare earth magnet imports. The United States runs persistent deficits in brushless platform variants.
China
Domestic vehicle production scaling and local supply chain maturation are compressing import dependency for 48-volt system components. GB standards for vehicle electrical systems are converging with international efficiency testing protocols. Yangtze River Delta manufacturing clusters around Shanghai are expanding integrated starter-generator foundry capacity.
United States
Commercial truck fleet electrification investments are accelerating demand for high-output charging systems above 200A ratings. EPA tailpipe mandates and NHTSA fuel economy rules are compelling OEMs to adopt higher-efficiency charging architectures. Michigan and Ohio automotive corridors are reshoring alternator assembly operations for heavy-duty platforms.
Germany
Premium passenger vehicle segments are specifying brushless alternator variants with 40-60% unit cost premiums for extended service intervals. ECE regulations are enforcing stricter efficiency testing protocols that favor compact designs. Baden-Württemberg supplier networks anchor European qualification processes for integrated power modules.
Japan
Thermal management innovation for brushless platform variants is concentrating engineering resources around permanent magnet efficiency gains. METI industrial policy supports semiconductor-integrated voltage regulation development. Kanto region production facilities are transitioning claw-pole rotor lines to hybrid permanent magnet architectures.
India
PLI scheme incentives for automotive component manufacturing are opening qualification pathways for localized alternator production. Commercial vehicle electrification is penetrating tractor and two-wheeler segments with cost-optimized specifications. Tamil Nadu and Gujarat assembly plants are expanding export-oriented capacity for standardized 12-volt units.
Automotive Alternator Market Key Industry Players
On the supply side, the industry is consolidating around integrated starter-generator capabilities while fragmenting across voltage tier specializations. Tier-one suppliers with semiconductor integration expertise are capturing 48-volt platform contracts. Three strategic archetypes dominate: diversified automotive electronics conglomerates, powertrain-focused component specialists, and regional cost-optimized fabricators. Competitive moves center on backward integration into magnet materials and strategic partnerships for East Asian foundry capacity access.
Among diversified automotive electronics conglomerates, Denso Corporation and Mitsubishi Electric Corporation exemplify the integrated power module segment, while Robert Bosch GmbH anchors European supply relationships through localized production networks. These players occupy positions defined by semiconductor control capabilities and thermal management engineering depth rather than commodity volume scale.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| HELLA GmbH & Co. KGaA |
| Denso Corporation |
| Mitsuba Corp. |
| Cummins Inc |
| Valeo |
| Hitachi Astemo, Ltd. |
| BorgWarner Inc. |
| Robert Bosch GmbH |
| Others |
Cost & Logistics Intelligence
Rare earth magnet concentration in China and copper winding supply from Chilean and Indonesian smelters anchor cost structures for brushless alternator variants, concentrating margin pools with semiconductor-integrated suppliers who control voltage regulation IP. OEM platform contracts extract volume discounts that compress unit economics for commodity claw-pole fabricators serving aftermarket channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on ISO 26262 certification grade and thermal management performance. Price differentiation rests on semiconductor integration depth and geographic delivery cost from Yangtze River Delta versus Midwestern US assembly points. Cost compression in 12-volt legacy tiers is intensifying because of overcapacity in claw-pole rotor fabrication. Fleet procurement teams exhibit lowest price sensitivity when specifying 48-volt integrated starter-generator systems for long-haul platforms.
Supply Chain Analysis
Extended payment terms from European OEMs and supply-chain finance facilities from Japanese trading houses shape working capital requirements for Tier 2 winding suppliers. Manufacturing concentrates in China, Germany, and Mexico for final assembly, with rare earth magnets drawing from Chinese separation facilities and copper rod feeding from Chilean and Zambian concentrate. Single-source vulnerability in East Asian foundry capacity for integrated power modules threatens 48-volt system ramps. Distribution runs through captive OEM logistics networks for platform supply and fragmented national distributors for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 48-volt mild-hybrid transition constitutes a high-growth disruption as NHTSA fuel economy mandates and EPA tailpipe rules force architecture migrations across light-duty and commercial vehicle segments.
For Market Incumbents: Harden semiconductor integration capabilities through backward integration into magnet materials and captive voltage regulation IP development. Denso Corporation's integrated power module positioning demonstrates how thermal management engineering depth defends against claw-pole commoditization. Prioritize Baden-Württemberg and Kanto region R&D concentration for ECE and METI qualification alignment. For New Entrants and Emerging Players: Build out construction machinery electrification specifications for high-output brushless units serving electric auxiliary systems on excavators and loaders. India's PLI scheme incentives offer the most penetrable geography for localized alternator production with cost-optimized specifications. Pursue direct equipment rental fleet relationships in Germany and the United States to bypass entrenched engine supplier package deals. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 48-volt integrated starter-generator development tracks as embedded software and thermal management expertise requirements escalate. Target acquisition candidates with semiconductor control capabilities and existing OEM platform qualifications rather than commodity winding operations. Monitor GB standards convergence with ECE efficiency testing protocols as the inflection signal for transnational supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Starter-Generator Platform Standardization | Denso and Bosch capture 48-volt contracts through semiconductor-integrated voltage regulation dominance. |
| Rare Earth Magnet Supply Agreement | Backward integration into Chinese separation capacity secures brushless alternator cost positioning against commodity swings. |
| Thermal Management Engineering Partnership | Mitsubishi Electric leverages Kanto region R&D concentration for permanent magnet efficiency gains. |
| Construction Machinery Electrification Expansion | High-output brushless units penetrate underdeveloped electric auxiliary system demand in German and US rental fleets. |
| India PLI Scheme Manufacturing Localization | Tamil Nadu and Gujarat assembly plants qualify for cost-optimized 12-volt and 48-volt export capacity. |
Research Approach
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and commercial fleet maintenance directors anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA and NHTSA regulatory filings, and ECE efficiency testing protocol documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed the analytical approach with bull, base, and bear cases for 48-volt architecture penetration rates across passenger and commercial vehicle segments. Segmentation dimensions modeled included voltage tier, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from unit volume trajectories and average selling price evolution, with semiconductor supply constraints and copper price volatility as key sensitivity inputs.
Practitioners should monitor GB standards implementation timelines and East Asian foundry capacity utilization for early signals of qualification bottlenecks or supply disruptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market
Automotive Electrical & Electronics
Automotive Electric Power Steering ECU Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive Thermoelectric Generator Market
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
Stair Lift Motors Market
Automotive Electrical & Electronics
Commercial Vehicle Switches and Relays Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market
Automotive Electrical & Electronics
Automotive Battery Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market