
 Neurofeedback Systems Market | 2026-2036
Neurofeedback Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Neurofeedback Systems Market Outlook
North American neurofeedback device manufacturing is consolidating as specialized producers scale electrode array production and cloud analytics infrastructure. BrainMaster Technologies leverages its FDA-registered hardware ecosystem to anchor clinical sales channels across the United States. Thought Technology Ltd. competes through modular amplifier architectures that sustain integration with third-party software platforms. Neuroelectrics Corporation differentiates via dry-electrode headset designs that reduce setup friction in multi-site research protocols.
Neurofeedback systems deploy real-time electroencephalography signal processing to train self-regulation of brainwave patterns, typically sampling cortical electrical activity at 256 Hz or higher through 19-32 channel montages for clinical-grade applications. EEG headsets dominate hardware revenue due to recurring electrode replacement cycles and amplifier upgrade paths, while software platforms capture expanding margin pools through subscription-based remote monitoring tools for home-based ADHD protocols. Cloud-based delivery modes are displacing on-premise installations in wellness center deployments where capital budgets favor operational expenditure models.
FDA 510(k) pathways and CE marking under the EU Medical Device Regulation shape product development timelines and clinical claim substantiation for neurofeedback manufacturers. HIPAA compliance requirements and GDPR data governance frameworks constrain how patient brainwave data traverses cloud-hosted analytics pipelines. Stakeholders must monitor evolving reimbursement codes for biofeedback-assisted therapy across Medicare, statutory health insurers in Germany, and Japan's Ministry of Health, Labour and Welfare to anticipate demand inflection points in institutional procurement cycles.
Market Dynamics
Clinical reimbursement pathways for non-pharmacological ADHD interventions are restructuring procurement authority from hospital capital committees to outpatient mental health networks, compressing sales cycles and elevating software subscription economics over hardware margins.
Growth Catalysts
- FDA 510(k) clearance streamlining:Expedited review pathways for biofeedback devices with predicate device claims accelerate market entry timelines for EEG hardware manufacturers targeting pediatric neurology practices.
- Cloud-native architecture adoption:Browser-based signal processing eliminates on-premise server requirements, enabling wellness center deployments without dedicated IT infrastructure.
- German statutory health insurance integration:Emerging reimbursement codes for biofeedback-assisted psychotherapy under statutory health insurers expand addressable patient populations beyond private-pay segments.
Market Restraints
- Silver-silver chloride electrode supply concentration:Three specialized chemical suppliers control high-purity electrode material output, exposing manufacturers to input cost volatility and qualification delays.
- EU MDR clinical evidence requirements:Expanded post-market surveillance obligations and notified body capacity constraints extend CE marking timelines for Class IIa neurofeedback devices.
- Pharmacological substitution persistence:Stimulant medications retain first-line status in ADHD treatment protocols, limiting neurofeedback penetration in institutional settings with embedded psychiatry departments.
Strategic Opportunities
- Japan's Ministry of Health, Labour and Welfare reimbursement expansion:Pending coverage decisions for cognitive behavioral interventions incorporating biofeedback could unlock institutional procurement in Tokyo and Osaka metropolitan health systems.
- Remote patient monitoring convergence:Integration of EEG headsets with telehealth platforms enables asynchronous clinician oversight of home-based training protocols.
- Performance optimization applications:Executive coaching and sports psychology segments represent underpenetrated demand verticals beyond clinical indications.
Industry Challenges
- Clinical neurophysiologist talent scarcity:Specialized training requirements for qEEG interpretation and protocol customization constrain service delivery scaling.
- HIPAA-GDPR data sovereignty alignment:Cross-border cloud hosting of brainwave recordings requires jurisdictional segmentation of analytics infrastructure.
- Interoperability certification complexity:Multiple competing EEG data formats impede seamless integration with electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurofeedback Systems Market |
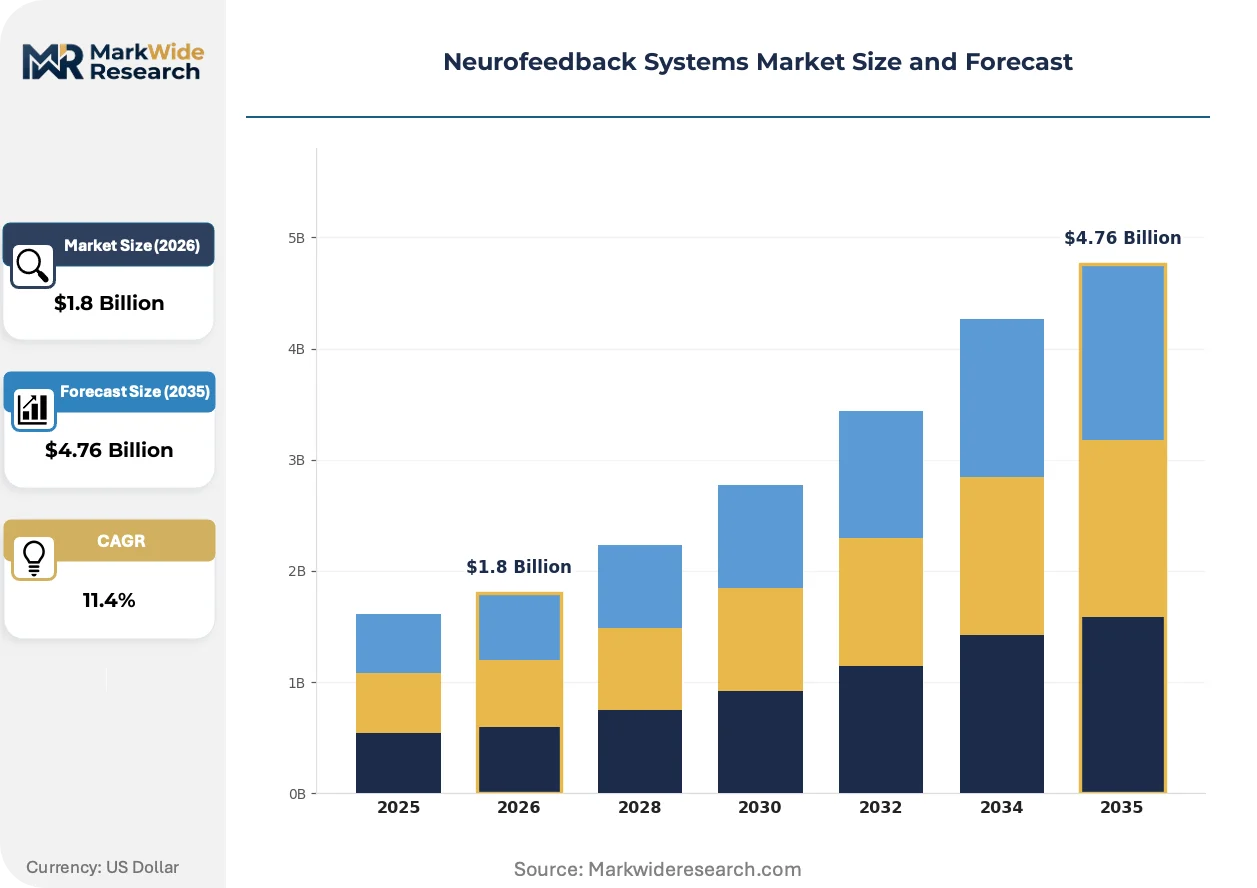
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Devices, EEG Headsets, Software Platforms, Biofeedback Equipment Application: Stress Management, ADHD Treatment, Sleep Disorders, Performance Enhancement End User: Clinics, Research Institutions, Rehabilitation Centers, Wellness Centers Delivery Mode: On-Premise, Cloud-Based, Hybrid, Mobile Applications |
| Companies Covered | BrainMaster Technologies, Inc., Mind Media B.V., NeuroCare Group GmbH, Mitsar Co. Ltd., BEE Medic GmbH, Myndlift Ltd., Thought Technology Ltd., Neurobit Systems, Neuroelectrics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurofeedback Systems Market Strategic Shifts
Dry-electrode sensor arrays and edge-computing signal processors are collapsing the setup friction that historically restricted neurofeedback to specialized clinics, enabling ambulatory and home-based deployment models.
Dry-electrode conductive polymer formulations eliminate conductive gel application requirements, reducing session preparation time from fifteen minutes to under two minutes. Pediatric mental health clinics and school-based intervention programs are adopting these headsets at accelerated procurement rates. This hardware simplification is decentralizing service delivery from hospital neurophysiology departments to community mental health centers and educational settings.
EU Medical Device Regulation enforcement through notified body reorganization has elevated clinical evidence requirements for neurofeedback software claiming therapeutic efficacy. Manufacturers must now submit randomized controlled trial data for CE marking renewals, compressing competitive differentiation toward evidence-generation capabilities. German and French regulatory submissions currently face the longest assessment queues, prompting firms to prioritize Swissmedic and TGA pathways for parallel market access.
Subscription-based remote monitoring platforms are displacing perpetual-license software sales in wellness center and private practice segments. Buyers increasingly prioritize operational expenditure models that bundle hardware refreshes, cloud analytics, and clinical support. This preference shift is most pronounced in United States metropolitan markets where capital equipment budgets face heightened scrutiny from private equity-backed practice aggregators.
Neurofeedback Systems Market Segmentation
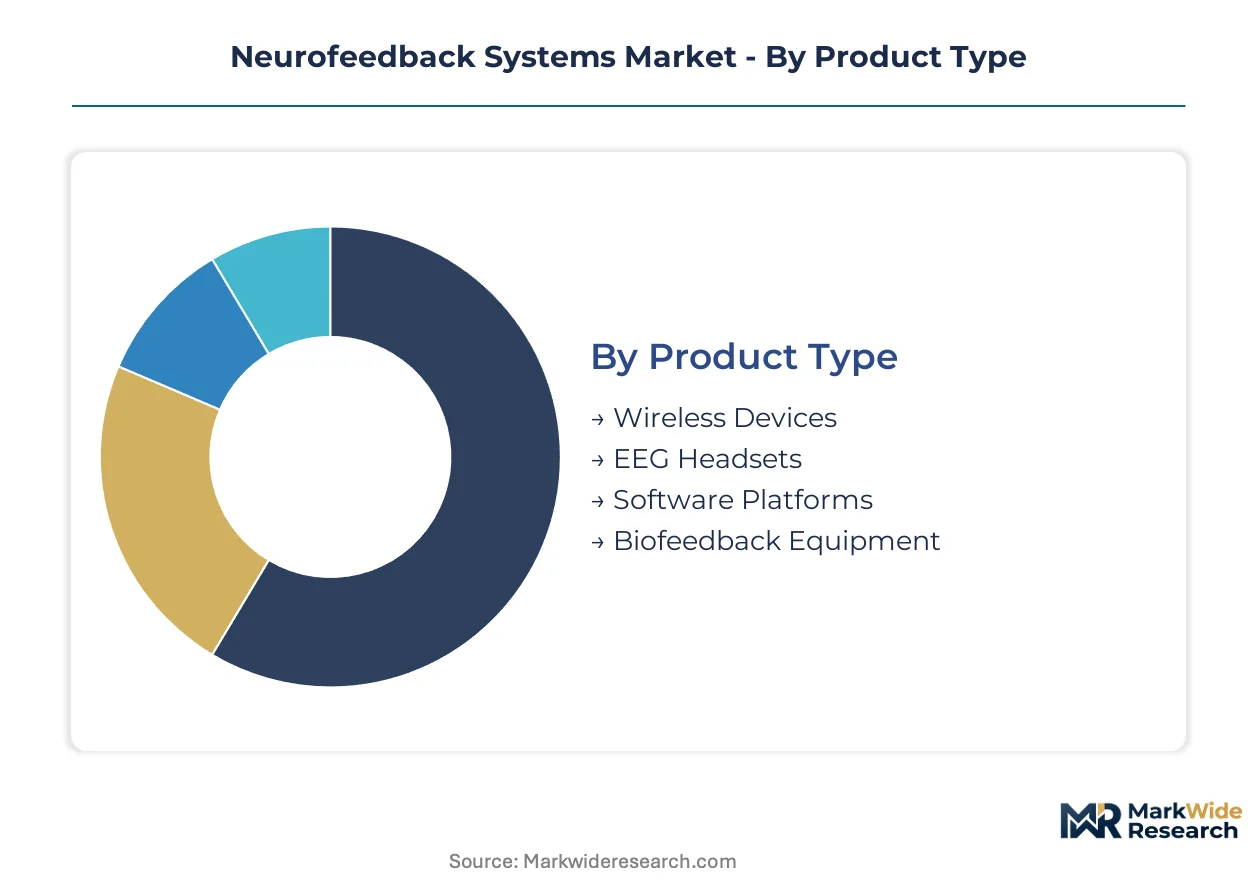
Neurofeedback systems fragment across hardware, software, and service dimensions that each carry distinct regulatory burdens and margin profiles. Understanding where FDA 510(k), CE marking, and HIPAA compliance obligations concentrate reveals which segments justify premium pricing versus commodity positioning.
Product Type:
FDA 510(k) clearance requirements fall heaviest on EEG headsets and biofeedback equipment, while software platforms face lighter regulatory scrutiny but escalating cybersecurity validation.
- EEG Headsets:Multi-channel electrode arrays sampling at 256 Hz or higher constitute the clinical revenue core. Demand concentrates in United States pediatric neurology practices where FDA-cleared hardware anchors insurance reimbursement eligibility.
- Software Platforms:Real-time signal processing algorithms and protocol customization tools generate recurring subscription revenue. Cloud-native architectures are displacing perpetual licenses in wellness center deployments across Germany where operational expenditure models dominate procurement.
- Wireless Devices:Bluetooth-enabled ambulatory monitors enable home-based training protocols.
- Biofeedback Equipment:Peripheral physiological sensors measuring galvanic skin response and heart rate variability complement EEG systems.
EEG Headsets sits at the top of the volume ranking, with Software Platforms climbing the fastest.
Application:
Cost tier stratification separates institutional reimbursement pathways from direct-to-consumer wellness spending, with ADHD treatment commanding premium pricing through medical channel validation.
- ADHD Treatment:FDA-cleared neurofeedback protocols for pediatric attention disorders represent the largest reimbursed indication. United States outpatient mental health networks drive procurement volume as reimbursement codes mature under Medicare and commercial insurers.
- Stress Management:Corporate wellness programs and executive coaching applications deploy lower-cost dry-electrode systems. Demand is expanding fastest in Japan's metropolitan corporate health programs where non-pharmacological interventions gain regulatory favor.
- Sleep Disorders:Home-based insomnia protocols leverage portable EEG hardware.
- Performance Enhancement:Sports psychology and cognitive optimization applications target private-pay consumers.
ADHD Treatment commands the highest average selling prices, while Stress Management is gaining share fastest.
End User:
Customer type determines procurement authority structure, with clinics consolidating purchasing decisions and research institutions driving technology refresh cycles.
- Clinics:Outpatient mental health and neurophysiology practices represent the primary reimbursed service delivery channel. United States private equity-backed practice aggregations are standardizing on cloud-subscription models that bundle hardware refreshes and clinical support.
- Research Institutions:Academic medical centers and pharmaceutical trials operations demand highest-channel-count systems with open API architectures. Procurement concentrates in Germany's Max Planck Institute network and United States NIH-funded consortia.
- Rehabilitation Centers:Post-stroke and traumatic brain injury applications require specialized protocol libraries.
- Wellness Centers:Non-medical service providers prioritize rapid-setup dry-electrode systems.
Clinics generate the highest absolute revenue, with Research Institutions showing the steepest expansion trajectory.
Delivery Mode:
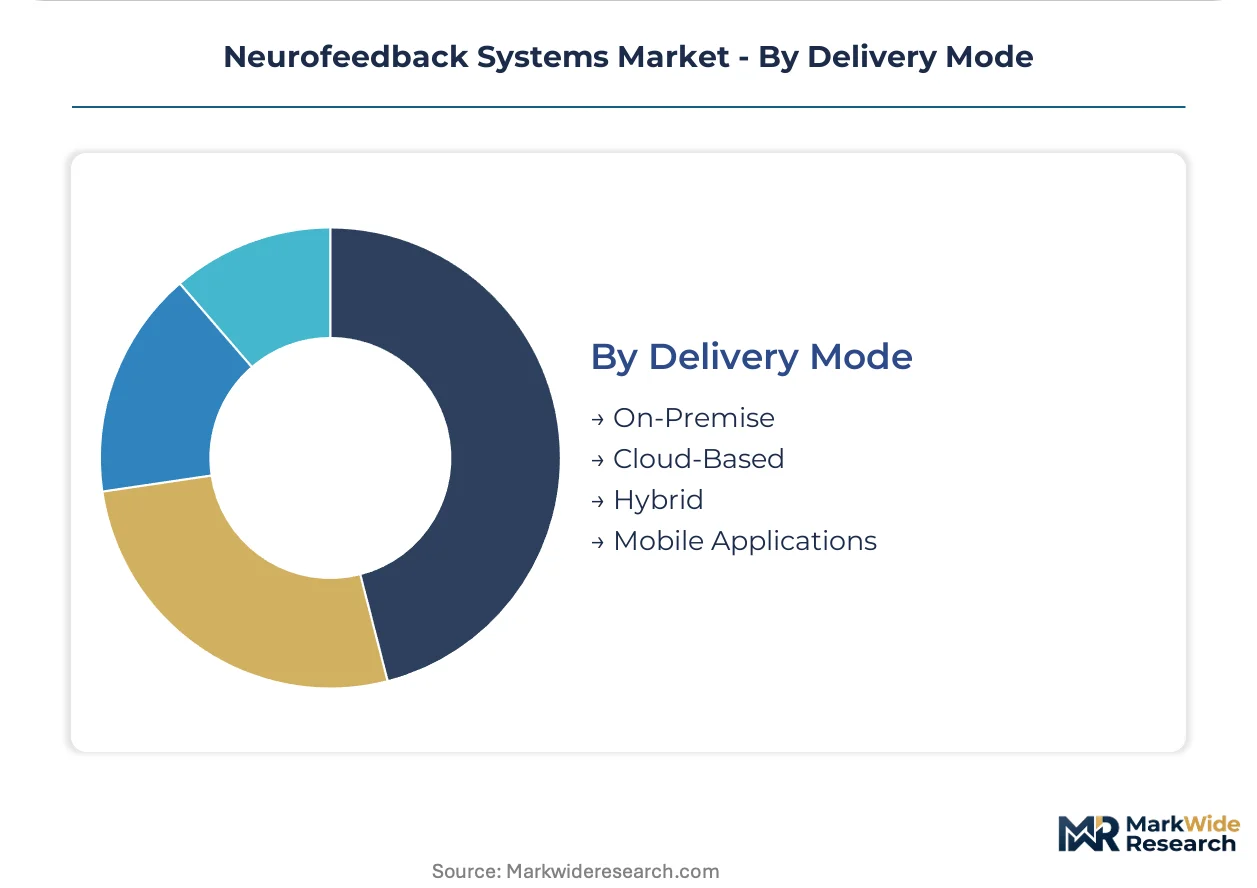
Margin structure varies sharply across deployment architectures, with cloud-based delivery capturing expanding software attach rates versus hardware-centric on-premise installations.
- Cloud-Based:Browser-accessible signal processing eliminates local server infrastructure requirements. Wellness center deployments across United States metropolitan markets favor this operational expenditure model as capital budgets face heightened scrutiny.
- Hybrid:Edge-computing preprocessors with cloud analytics backup balance latency sensitivity and scalability. Research protocols in Japan and Germany adopt this architecture for multi-site data aggregation under GDPR and HIPAA constraints.
- On-Premise:Local server installations persist in high-security government and military applications.
- Mobile Applications:Smartphone-integrated consumer-grade neurofeedback targets wellness and performance segments.
Cloud-Based delivery sits at the top of the volume ranking, with Hybrid architectures climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EU MDR compliance costs push hardware assembly toward jurisdictions with streamlined medical device pathways. Switzerland and Australia now host expanding production clusters serving European demand through mutual recognition agreements.
United States
Outpatient mental health networks in Texas and Florida are accelerating procurement of FDA-cleared EEG systems as Medicare reimbursement codes mature for biofeedback-assisted ADHD protocols. The FDA's 510(k) review streamlining for predicate device claims compresses market entry timelines. BrainMaster Technologies anchors domestic manufacturing in Ohio while serving pediatric neurology practices across the Southeast.
Germany
Statutory health insurance integration for biofeedback-assisted psychotherapy is expanding addressable patient populations beyond private-pay segments in Bavaria and North Rhine-Westphalia. CE marking under EU MDR imposes extended clinical evidence requirements that favor established manufacturers with randomized controlled trial portfolios. Berlin hosts the densest concentration of neurophysiology research consortia driving protocol standardization.
Japan
Pending Ministry of Health, Labour and Welfare coverage decisions for cognitive behavioral interventions incorporating biofeedback could unlock institutional procurement in Tokyo and Osaka metropolitan health systems. METI's regulatory harmonization initiatives align domestic standards with FDA pathways. Kansai region medical device clusters are scaling dry-electrode production for regional export.
Switzerland
Swissmedic's accelerated assessment pathways for Class IIa neurofeedback devices attract manufacturers seeking parallel market access while EU notified body queues extend. Zurich and Basel host specialized electrode material suppliers serving German and French OEMs. The country's data sovereignty frameworks position it as a cloud analytics hub for GDPR-sensitive brainwave processing.
Australia
TGA's streamlined medical device registration enables faster market entry for EEG hardware targeting Asia-Pacific research institutions. Sydney and Melbourne academic medical centers demand highest-channel-count systems with open API architectures for multi-site pharmaceutical trials. The country's therapeutic goods regulator maintains mutual recognition arrangements that facilitate export certification to Southeast Asian markets.
Neurofeedback Systems Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue wellness-center and home-based deployment models with simplified hardware architectures. The vendor base stratifies across three tiers: FDA-registered specialists serving reimbursed clinical channels, modular platform builders enabling third-party software integration, and dry-electrode innovators collapsing setup friction for ambulatory applications. Dominant competitive moves include cloud-subscription bundling that converts capital equipment sales to recurring revenue, and strategic partnerships with telehealth platforms for remote patient monitoring convergence.
Among North American specialists, BrainMaster Technologies and Thought Technology Ltd. exemplify contrasting hardware philosophies—BrainMaster anchoring clinical sales through FDA-registered ecosystem depth, Thought Technology sustaining integration flexibility via modular amplifier designs. Neuroelectrics Corporation occupies a distinct position within the dry-electrode tier, representing the sensor-simplification vector that enables decentralized service delivery. These three archetypes—ecosystem-anchored, integration-flexible, and friction-reducing—capture the competitive vectors reshaping procurement authority from hospital capital committees to outpatient networks.
| Leading Market Players |
|---|
| BrainMaster Technologies, Inc. |
| Mind Media B.V. |
| NeuroCare Group GmbH |
| Mitsar Co. Ltd. |
| BEE Medic GmbH |
| Myndlift Ltd. |
| Thought Technology Ltd. |
| Neurobit Systems |
| Neuroelectrics Corporation |
| Others |
Value Chain & Pricing Dynamics
EU MDR sustainability compliance for silver-silver chloride electrode sourcing gates qualified supply and premium-tier pricing access. Manufacturers bearing certified green chemistry credentials command tier-one positioning with United States pediatric neurology networks and German statutory insurers, while uncertified competitors face margin compression in wellness center channels.
Pricing Analysis
Distributor margin layers absorb fifteen to twenty-five points before hardware reaches clinic procurement committees, compressing manufacturer netbacks on EEG headsets. Three-tier pricing structure across premium, standard, and economy levels separates FDA-registered clinical systems from CE-marked wellness devices and unregulated consumer headsets. Pricing pressure stems from cloud-subscription bundling that converts capital equipment sales to recurring revenue models with lower upfront recoveries. Research institutions demonstrate lowest price sensitivity due to grant-funded procurement, while corporate wellness programs negotiate aggressively on per-seat economics.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific electrode material suppliers has prompted regionalization of final assembly to Switzerland and Australia. High-purity silver chloride chemistry concentrates in Germany, Japan, and the United States, while amplifier PCB fabrication rests on Taiwanese and South Korean contract manufacturers. Single-source vulnerability persists at the specialty chemical tier where three qualified suppliers control medical-grade electrode output. Distribution runs through authorized clinical equipment distributors in reimbursed channels and direct e-commerce in wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where reimbursement code maturation is filtering procurement toward FDA-cleared, evidence-backed systems and away from unvalidated wellness hardware.
For Market Incumbents: Lock in electrode supply contracts with German and Japanese chemical specialists before EU MDR qualification windows narrow. Deepen backward integration into cloud analytics infrastructure to capture recurring revenue streams that offset hardware margin erosion from private equity-backed practice aggregators. For New Entrants and Emerging Players: Launch via direct-to-clinic subscription models targeting United States outpatient mental health networks in Texas and Florida where reimbursement codes are newest and incumbent relationships remain shallow. Dry-electrode pediatric applications represent the most penetrable white space. For Investors and Strategic Acquirers: Roll-up economics work for cloud-native neurofeedback platforms because fragmented software vendors lack the capital to fund FDA 510(k) renewal trials under tightened EU MDR evidence requirements. Watch German statutory insurance reimbursement expansion as the signal for institutional demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | FDA-registered hardware anchors insurance reimbursement eligibility in United States pediatric neurology. |
| CE Marking Renewal Investment | EU MDR clinical evidence requirements compress competitive differentiation toward trial-capable manufacturers. |
| Cloud-Subscription Bundling | Operational expenditure models displace capital sales in wellness center deployments across metropolitan markets. |
| Electrode Supply Agreement | Silver-silver chloride concentration with three qualified suppliers creates qualification-delay risk for scaling manufacturers. |
| Telehealth Platform Partnership | Remote patient monitoring convergence enables asynchronous clinician oversight of home-based ADHD protocols. |
Study Parameters
Bottom-up clinic deployment modeling reconciled against top-down hardware shipment tracking forms the analytical core of this study. Primary interviews with pediatric neurologists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, CE marking databases, CMS Medicare reimbursement codes, and German statutory insurance procedure catalogs. Top-down supply-side estimates derived from amplifier and electrode manufacturer capacity disclosures triangulate against bottom-up demand aggregation.
Historical trendline analysis across installed base expansion and protocol reimbursement adoption informs the projection framework. Segmentation dimensions modeled include product type, application indication, end-user category, and delivery mode architecture. CAGRs were derived from elasticity-adjusted demand curves incorporating reimbursement code maturation timelines and regulatory pathway velocity across FDA, EU MDR, and Swissmedic jurisdictions. Forecast inputs include electrode replacement cycle frequency and cloud analytics attach rates.
Several conditions sit outside the modeled scope, including unforeseen regulatory pathway reversals, raw material supply disruptions, and pharmacological substitution breakthroughs in ADHD treatment. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Middle East and Africa Biomedical Sensors Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
Digital Orthodontics Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Artificial Eye Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Compression Therapy Devices Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Skin Revitalizing Handheld Devices Market