
 Turnstiles Access Control Systems Market | 2026-2036
Turnstiles Access Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Turnstiles Access Control Systems Market Analytics
Asian contract manufacturers is restructuring turnstile component supply chains to reduce lead times for electromechanical assemblies. Boon Edam leverages integrated R&D facilities in the Netherlands to sustain design leadership in optical entry solutions. Gunnebo anchors its position through captive metal fabrication capacity for full-height perimeter security barriers. dormakaba Group competes across Europe by controlling distribution channels for RFID credential integration modules.
Turnstiles Access Control Systems encompass electromechanically or optically gated pedestrian entry devices, typically fabricated from stainless steel or aluminum alloy frameworks with throughput ratings between 25 and 60 persons per minute, designed to regulate human flow while authenticating credentials against access permissions. Optical turnstiles command premium positioning in corporate offices where glass-wing aesthetics and sub-second response times justify higher procurement budgets, while full-height variants dominate transportation hubs requiring anti-tailgating physical containment. Biometric technology adoption is accelerating fastest among event organizers seeking frictionless crowd ingress, though smart card systems retain installed-base dominance across educational institutions with legacy credential investments.
FAA security directives for airport perimeter control, EU GDPR biometric data processing requirements, and OSHA workplace safety standards for emergency egress pathways collectively shape product certification demands and procurement specifications across jurisdictions. EMA-equivalent national regulators in target markets increasingly mandate audit trails for credential database access, compelling vendors to embed tamper-evident logging architectures. Stakeholders must monitor evolving AI governance frameworks for facial recognition deployments, as pending classification rules threaten to bifurcate addressable markets between compliant and non-compliant system architectures.
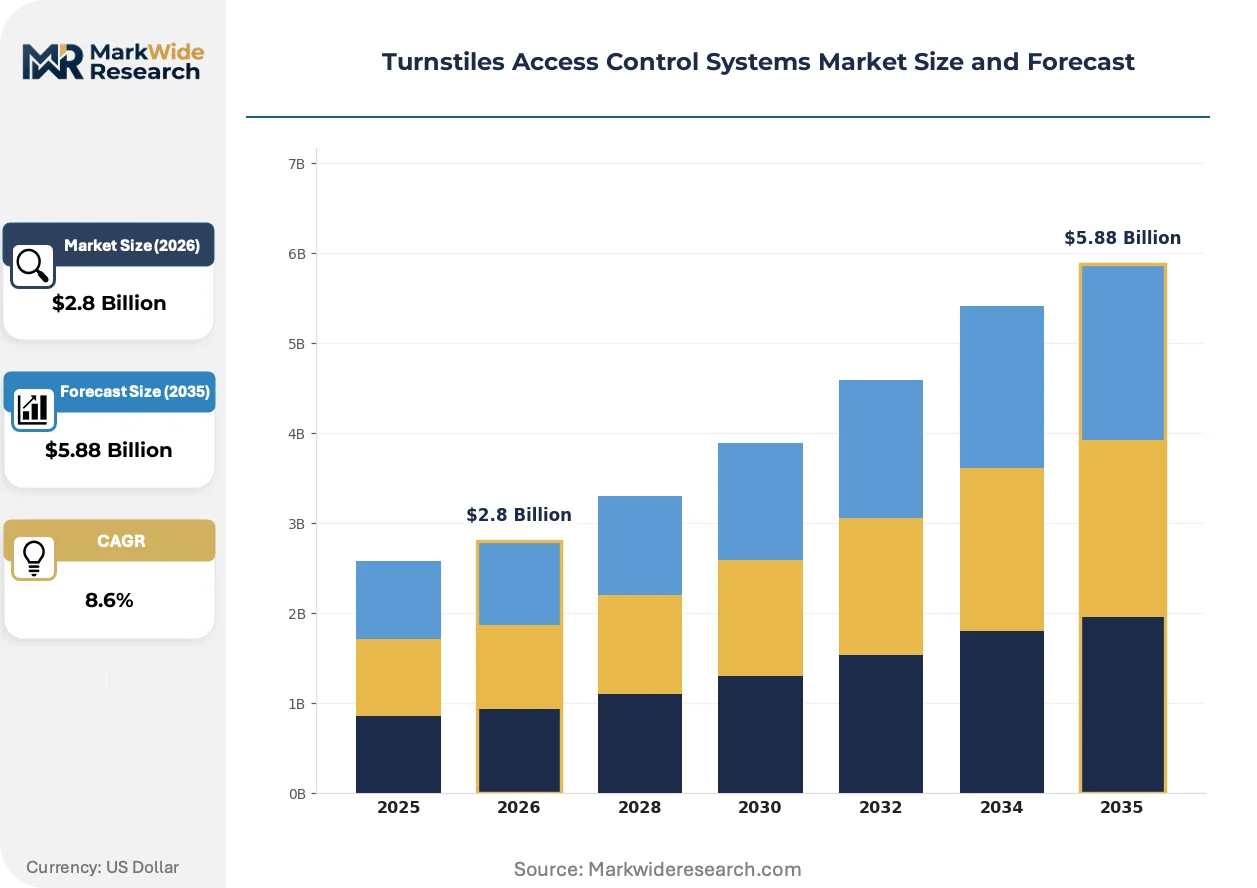
Market Dynamics
Biometric authentication deployment at mass-transit nodes and entertainment venues is compressing replacement cycles for legacy credential systems while forcing vendors to re-architect hardware for GDPR and EU AI Act compliance.
Growth Catalysts
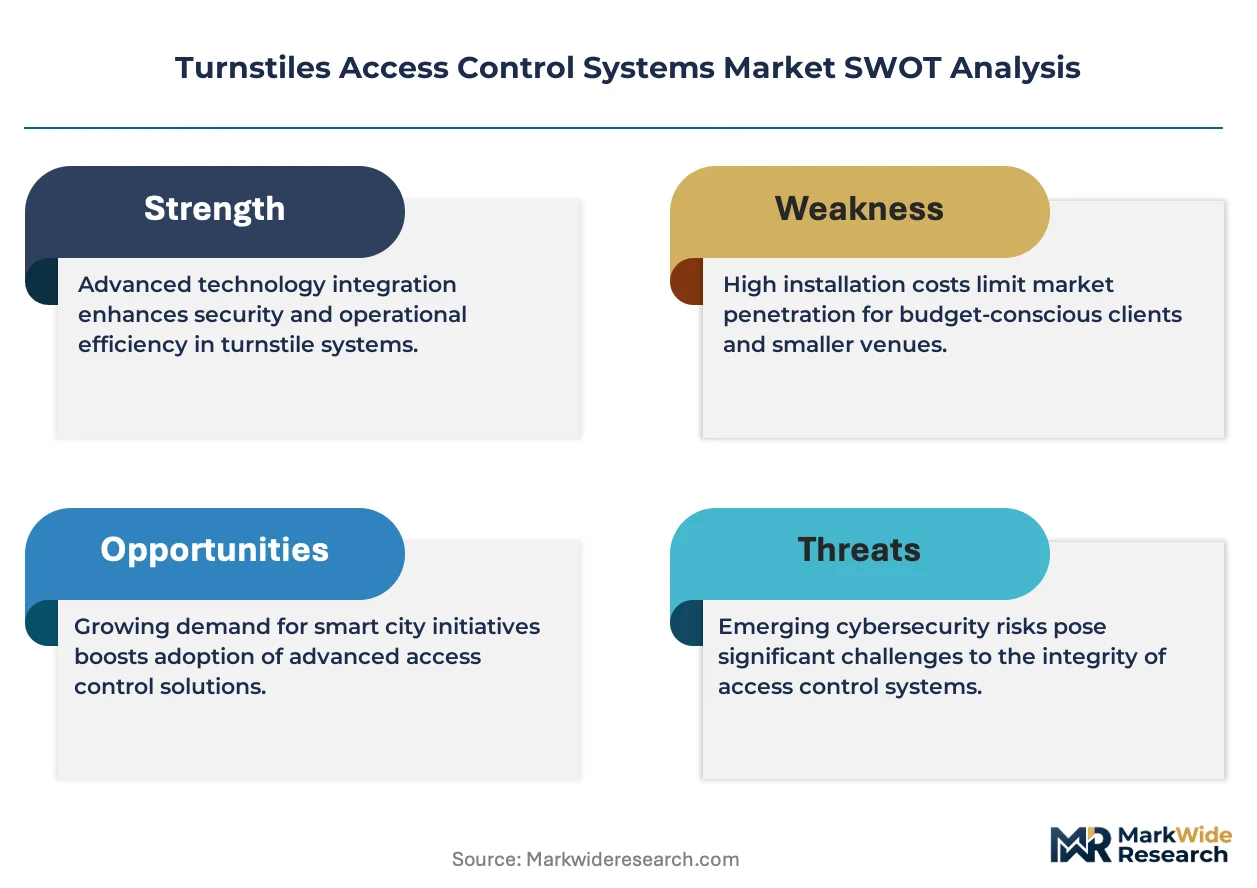
- EU AI Act biometric governance:Stadium operators in Germany and France are accelerating optical turnstile procurement to meet facial recognition audit requirements before enforcement deadlines.
- Rail infrastructure modernization:Deutsche Bahn and SNCF station access programs are driving demand for full-height barriers with integrated RFID credential modules.
- Frictionless crowd ingress technology:Palm-vein and facial recognition systems are displacing smart card readers at event venues seeking sub-second throughput rates.
Market Restraints
- Stainless steel input volatility:Electromechanical assembly costs fluctuate with alloy pricing, squeezing margins on full-height perimeter barriers.
- Component supply concentration:Asian contract manufacturers control electromechanical subassembly capacity, exposing European integrators to extended lead times.
- GDPR biometric data friction:Consent management complexity and data retention limits create procurement hesitation among educational institutions with legacy credential investments.
Strategic Opportunities
- Underpenetrated Nordic transit:Sweden and Norway rail authorities lag in optical turnstile deployment, presenting first-mover openings for compliant vendors.
- Convergence of AI and edge computing:On-device facial recognition processing reduces latency and cloud dependency for high-throughput venues.
- Service unbundling:Maintenance and credential management subscriptions are creating recurring revenue streams distinct from hardware sales.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for tamper-evident logging architectures outpaces qualified labor supply in Western Europe.
- Multi-jurisdiction certification timelines:FAA security directives for airport applications, EMA-equivalent national mandates, and OSHA emergency egress standards require parallel compliance tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turnstiles Access Control Systems Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Height Turnstiles, Half Height Turnstiles, Optical Turnstiles, Tripod Turnstiles Technology: Electromechanical, RFID, Biometric, Smart Card Applications: Transportation Hubs, Sports Facilities, Corporate Offices, Educational Institutions End User: Governments, Commercial Enterprises, Event Organizers, Healthcare Facilities |
| Companies Covered | Boon Edam, Gunnebo, dormakaba Group, Alvarado Manufacturing, Automatic Systems, PERCo, Turnstar Systems, Hayward Turnstiles, Smarter Security, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turnstiles Access Control Systems Market Evolving Landscape
Hardware architectures are bifurcating between aesthetic-driven corporate installations and ruggedized transportation deployments, while regulatory pressure on biometric data handling forces redesign of credential database structures.
Computer vision-based tailgating detection is expanding into optical turnstile product lines. Corporate campus security teams in the Netherlands and Switzerland are specifying glass-wing barriers with embedded stereo cameras for occupancy counting. This capability compression is collapsing the distinction between physical access control and space utilization analytics.
EU AI Act risk classification rules are forcing facial recognition vendors to segregate product architectures. High-risk biometric deployments must embed audit trails and human oversight interfaces, increasing bill-of-materials complexity for stadium and airport applications. German integrators are responding by pre-certifying hardware platforms against anticipated enforcement standards.
Buyer committees at multinational corporations are consolidating vendor relationships across facility portfolios. Procurement functions in France and Belgium are mandating pan-European service coverage and unified credential management platforms. This concentration is squeezing regional distributors and favoring vendors with captive installation networks.
Turnstiles Access Control Systems Market Segmentation
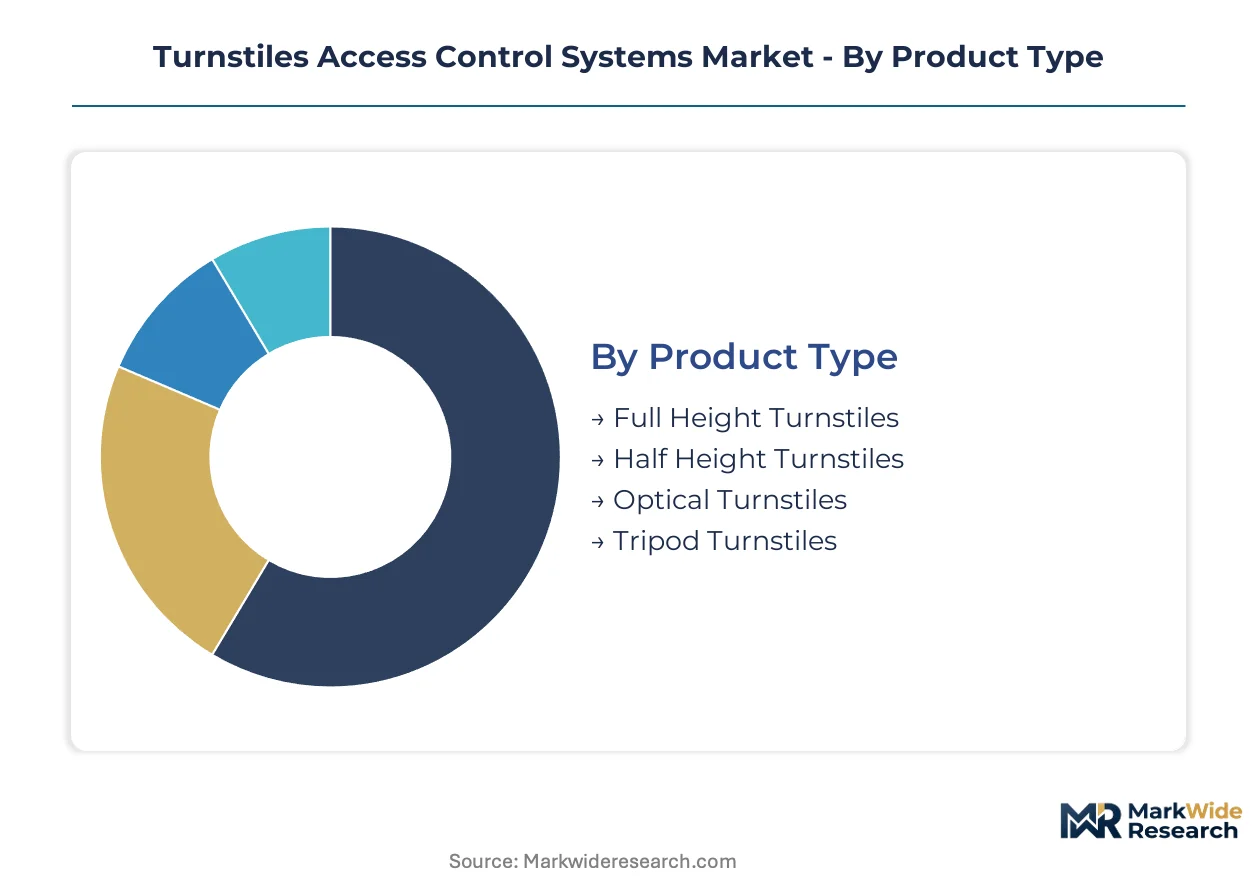
Procurement committees in stadiums, transit authorities, and corporate campuses evaluate turnstile systems through divergent technical and aesthetic lenses. Segmentation reveals how buyer priorities split across physical containment requirements, credential authentication methods, and throughput specifications.
Product Type:
Facility security managers select product types based on tailgating risk tolerance and architectural integration requirements.
- Full Height Turnstiles:Steel-barrier enclosures extending from floor to ceiling provide absolute pedestrian containment. Deutsche Bahn and SNCF deploy these at unstaffed rail platforms where fare evasion risks are acute.
- Optical Turnstiles:Glass-wing barriers with infrared detection arrays deliver sub-second throughput for premium corporate lobbies. Dutch and Swiss banking headquarters specify these for occupancy analytics integration.
- Half Height Turnstiles:Waist-level barriers balance physical deterrence with emergency egress compliance.
- Tripod Turnstiles:Three-arm rotating mechanisms dominate budget-constrained educational retrofits.
Volume sits with full-height barriers in transportation; growth tilts toward optical systems in corporate and entertainment venues.
Technology:
Credential authentication methods are diverging between legacy infrastructure preservation and biometric modernization.
- Biometric:Facial recognition and palm-vein scanners compress ingress times below one second. German stadium operators are deploying these ahead of EU AI Act enforcement deadlines for high-risk system classification.
- Smart Card:Contactless credential readers retain dominance across university campuses with sunk investments in student ID infrastructure. GDPR consent management complexity slows replacement cycles here.
- RFID:Proximity and long-range credential modules integrate with existing access control networks.
- Electromechanical:Token and ticket-based mechanisms persist in legacy transit systems with minimal IT infrastructure.
Installed base concentrates in smart card systems; steepest expansion trajectory belongs to biometric deployments at mass-transit nodes and event venues.
Applications:
End-use environments impose distinct throughput, durability, and aesthetic specifications on vendor selection.
- Transportation Hubs:Rail and metro stations demand 60 persons-per-minute throughput with vandal-resistant construction. Swedish and Norwegian authorities are accelerating procurement for station modernization programs.
- Corporate Offices:Glass-wing optical barriers with visitor management integration command premium positioning. Netherlands and Switzerland campuses specify stereo camera occupancy counting.
- Sports Facilities:Frictionless crowd ingress drives biometric adoption at German and French stadiums.
- Educational Institutions:Legacy credential investments and procurement budget constraints favor retrofit compatibility.
Revenue concentrates in transportation infrastructure; margin expansion is climbing the fastest in corporate office deployments.
End User:
Budget authority and compliance obligations shape procurement processes across buyer categories.
- Governments:Transit authorities and public building administrators mandate multi-vendor qualification and pan-European service coverage. French and Belgian procurement functions are consolidating vendor relationships.
- Commercial Enterprises:Multinational corporations specify unified credential management across facility portfolios. This concentration pressures regional distributors.
- Event Organizers:Temporary and permanent venue operators prioritize throughput speed over capital cost.
- Healthcare Facilities:Infection control and emergency egress requirements influence barrier selection.
Contract value aggregates with government buyers; decision velocity is gaining share fastest among commercial enterprises consolidating vendor panels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel fabrication clusters in Germany's Ruhr region and Guangdong's Pearl River Delta anchor component supply for electromechanical turnstile assemblies. Raw material proximity to assembly facilities shortens procurement cycles for full-height barrier manufacturers serving transportation infrastructure.
Germany
Deutsche Bahn's station modernization program and Bundesliga stadium security upgrades drive optical turnstile procurement. The EU AI Act enforcement timeline compels facial recognition vendors to embed audit-trail architectures before 2025 deadlines. Bavarian integrators in Munich pre-certify hardware platforms against anticipated biometric governance standards.
France
SNCF rail access programs and Parisian corporate campus expansions sustain demand for glass-wing barriers with visitor management integration. CNIL consent-management requirements complicate biometric deployments in educational institutions. Lyon-based security distributors consolidate vendor panels to meet pan-European service coverage mandates from multinational buyers.
United States
FAA security directives for airport perimeter control and OSHA emergency egress standards shape certification requirements for full-height barriers. Stadium operators in Texas and California accelerate frictionless ingress technology adoption. Chicago-area fabricators supply electromechanical subassemblies for transit authorities modernizing legacy token-based systems.
China
MIIT standards for smart city infrastructure and GB certification for public building access equipment regulate domestic procurement. Metro authorities in Shenzhen and Chengdu deploy high-throughput optical barriers with palm-vein authentication. Guangdong contract manufacturers restructure supply chains to reduce lead times for European integrators.
United Kingdom
Transport for London station upgrades and Premier League venue security investments sustain demand for RFID-integrated credential systems. The Information Commissioner's Office biometric guidance creates procurement hesitation among university campuses with legacy smart card infrastructure. Scottish rail authorities lag in optical turnstile deployment, presenting first-mover openings for compliant vendors.
Turnstiles Access Control Systems Market Competitive Landscape
Global majors compete with regional champions across distribution reach and certification bandwidth. The vendor base stratifies between integrated design-to-installation providers and component-specialist fabricators. Three archetypes dominate: captive-metal-fabrication full-height barrier manufacturers, optical-solution design leaders with integrated R&D facilities, and RFID-credential module distributors controlling European channels. Competitive moves concentrate on pre-certification against anticipated EU AI Act enforcement and consolidation of pan-European service networks.
Among Dutch-heritage design leaders, Boon Edam occupies a position exemplifying integrated R&D-to-manufacturing architecture for premium optical entry solutions. Gunnebo anchors the full-height perimeter security tier through captive metal fabrication capacity. The dormakaba Group sits within the European distribution-control archetype, competing across credential integration modules. These three represent divergent strategic postures: design-led premium positioning, manufacturing-scale cost discipline, and channel-capture recurring revenue models.
| Leading Market Players |
|---|
| Boon Edam |
| Gunnebo |
| dormakaba Group |
| Alvarado Manufacturing |
| Automatic Systems |
| PERCo |
| Turnstar Systems |
| Hayward Turnstiles |
| Smarter Security |
| Others |
Value Network & Pricing Analysis
Transit authority procurement programs in Germany and France concentrate contract value with vendors offering unified credential management platforms, compressing pricing power toward pan-European service coverage models. This buyer consolidation forces tiered pricing structures that separate premium optical systems with embedded biometric audit trails from standard RFID-integrated barriers and economy-grade electromechanical assemblies.
Pricing Analysis
Extended warranty and credential management subscriptions are unbundling from hardware sales to create recurring revenue streams distinct from capital procurement. Three-tier pricing structure across premium, standard, and economy levels separates glass-wing optical barriers with stereo camera analytics from full-height steel enclosures and basic tripod mechanisms. Cost compression in full-height perimeter barriers is intensifying because stainless steel alloy input volatility squeezes electromechanical assembly margins. Educational institutions with legacy smart card infrastructure exhibit highest price sensitivity, while corporate campuses in the Netherlands and Switzerland accept premium positioning for aesthetic-driven installations.
Supply Chain Analysis
Dual-sourcing requirements from Deutsche Bahn and SNCF mandate multi-supplier qualification for electromechanical subassemblies, reducing single-source vulnerability. Component fabrication concentrates in China's Guangdong Pearl River Delta, Germany's Ruhr region, and South Korean precision metalworking clusters. Raw material dependencies rest on stainless steel alloy feedstock, infrared sensor arrays, and RFID credential modules. Tariff exposure on Chinese electromechanical components threatens margin stability for European integrators. Distribution runs through captive installation networks controlled by Dutch-heritage design leaders and regional security distributors consolidating vendor panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric authentication deployment is displacing legacy credential systems across stadium and transit applications, creating a technology-transition phase that rewards compliance-ready hardware architectures.
For Market Incumbents: Hedge against GDPR biometric data friction by embedding tamper-evident logging architectures before EU AI Act enforcement deadlines. Pre-certify hardware platforms against anticipated high-risk system classification rules to defend market position in German stadium and airport procurement cycles. Channel control through captive installation networks remains the priority lever against distributor consolidation pressure.
For New Entrants and Emerging Players: Swedish and Norwegian rail authorities present an underserved buyer archetype lagging in optical turnstile deployment, offering first-mover openings for compliant vendors. Palm-vein authentication modules for frictionless crowd ingress represent the most penetrable technology segment. A service-unbundling go-to-market angle targeting maintenance subscriptions can bypass capital procurement barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor European distributors with pan-European service coverage capabilities in France and Belgium, where multinational buyer consolidation is squeezing regional players. Long-term viability across the analysis window hinges on biometric governance compliance bandwidth rather than hardware scale. The signal to watch is EU AI Act enforcement timeline adherence as an inflection indicator for vendor survival.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Audit-Trail Architecture Pre-Certification | EU AI Act compliance deadlines in Germany and France demand embedded human oversight interfaces. |
| Pan-European Service Network Consolidation | French and Belgian procurement functions mandate unified credential management across facility portfolios. |
| Credential Management Subscription Unbundling | Recurring revenue streams separate from hardware sales reduce capital procurement cycle dependency. |
| On-Device Facial Recognition Edge Computing | Stadium operators in Texas and California seek sub-second throughput with reduced cloud dependency. |
| Nordic Transit Authority First-Mover Positioning | Swedish and Norwegian rail modernization programs lag optical barrier deployment versus continental Europe. |
Research Methodology
Regulatory filings from EMA-equivalent national regulators, EU AI Act implementation guidance, and customs trade data on stainless steel alloy imports formed the secondary backbone. Primary interviews with stadium security directors, transit authority procurement leads, biometric systems integrators, and corporate facility managers combined with secondary validation. Bottom-up triangulation across product type, technology, application, and end-user segmentation dimensions anchored volume estimates, while top-down cross-checks against rail infrastructure investment databases ensured consistency.
Historical trendline analysis of Deutsche Bahn and SNCF station modernization expenditure patterns informed baseline assumptions across the projection horizon. Segmentation dimensions modeled include product architecture containment level, credential authentication method, throughput specification tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted deployment curves reflecting EU AI Act compliance deadlines and rail infrastructure program timelines. Stainless steel input cost volatility and electromechanical assembly lead time fluctuations served as industry-specific forecast sensitivity inputs.
Revisions become necessary when EU AI Act enforcement interpretations harden, GDPR biometric consent management requirements shift, or rail infrastructure appropriation schedules deviate from announced programs. Deviation in stainless steel alloy pricing volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Europe Home Security System Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
Global Automated Border Control Market
Access Control Systems
India Access Control Hardware Market
Access Control Systems
Network Access Control Market
Access Control Systems
Programmable Safety Systems Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
Smart Entry System Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market
Access Control Systems
United States Smart Lock Market
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
Middle East and Africa Proximity Access Control Market
Access Control Systems
Home Control and Security Systems Market