
 Indoor Air Quality Monitor Market | 2026-2036
Indoor Air Quality Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Air Quality Monitor Market Outlook
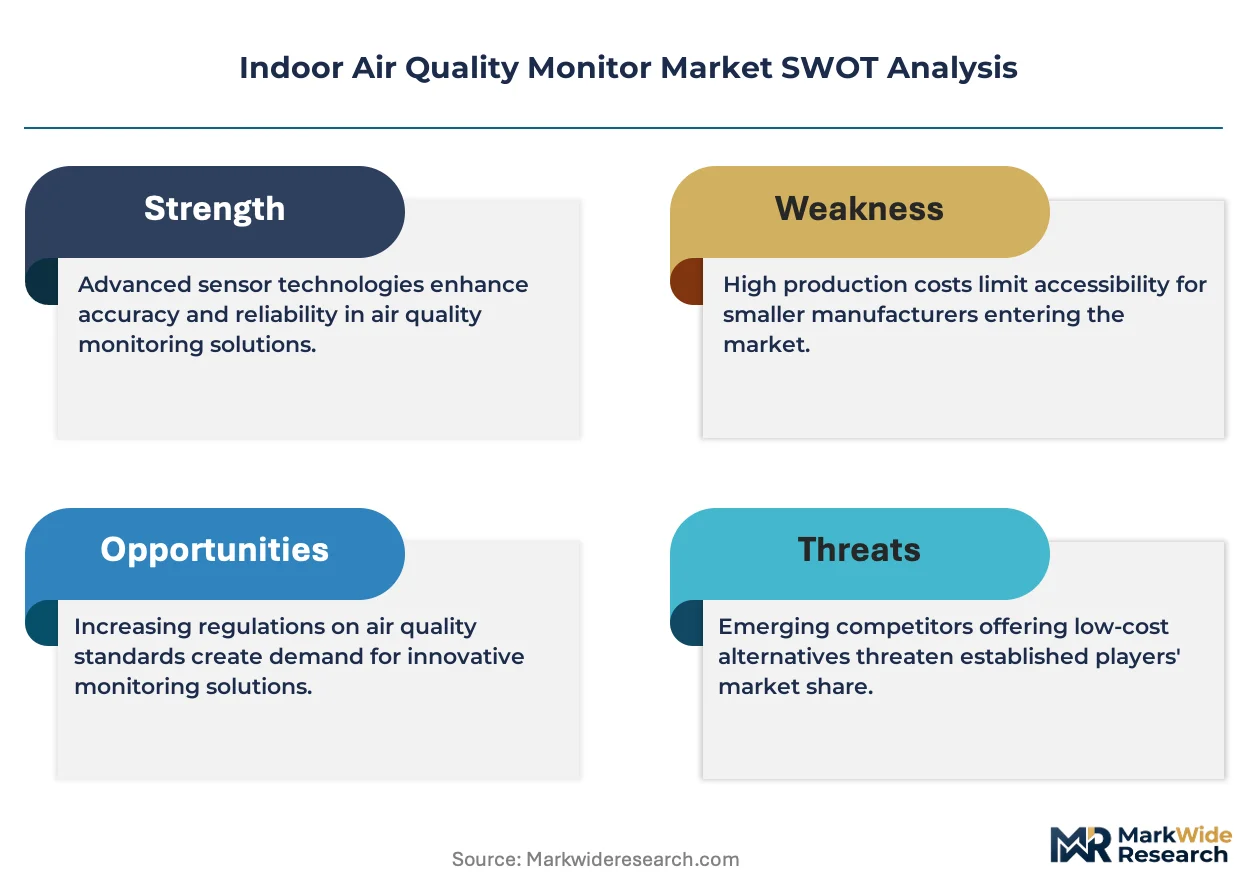
EPA indoor air quality guidelines is restructuring compliance costs for building operators entering the monitor market. Thermo Fisher Scientific leverages its analytical instrument heritage to sustain premium positioning in laboratory-grade detection. Honeywell International anchors its portfolio through integrated building automation systems that embed air quality modules. Aeroqual specializes in optical sensor miniaturization for compact residential deployments.
Indoor air quality monitors are electrochemical or optical sensing instruments that detect particulate matter, volatile organic compounds, carbon dioxide, and other airborne contaminants at concentrations measured in parts per billion. These devices serve commercial and industrial managers who must verify ventilation performance against occupational exposure limits. Portable monitors currently lead unit shipments due to flexibility in facility audits and temporary site assessments, while integrated systems capture the dominant share of installed value through hardwired building management connections. MEMS sensors represent the fastest-expanding technology segment as semiconductor foundries drive unit costs downward for mass-market applications.
OSHA ventilation standards and the US Green Building Council LEED certification framework shape product specifications and procurement criteria across North American commercial construction. EPA enforcement of radon and fine particulate thresholds sustains replacement demand in educational institutions and healthcare facilities. Stakeholders must monitor evolving sensor calibration requirements and interoperability protocols as building electrification accelerates retrofit cycles.
Market Dynamics
Building electrification mandates and ventilation code tightening are forcing facility managers to replace legacy detection hardware with networked multi-parameter systems that feed real-time data into building management platforms.
Growth Catalysts
- EPA Indoor Air Quality Guidelines:The US EPA's tightening of pollutant thresholds for particulate matter and volatile organic compounds is compelling school districts and healthcare facilities to upgrade monitoring infrastructure.
- German Federal Building Energy Code:Germany's mandate for continuous air quality tracking in public structures is concentrating procurement demand from municipal building operators seeking compliant instrumentation.
- MEMS Sensor Cost Compression:Semiconductor foundry scale economies are driving unit costs downward for electrochemical and optical sensing elements, enabling mass-market residential deployments.
Market Restraints
- Sensor Calibration Volatility:Drift in electrochemical sensor accuracy requires quarterly recalibration cycles that inflate total cost of ownership for commercial users.
- Optical Component Supply Concentration:Laser diode and photodetector fabrication concentrates in East Asian foundries, exposing monitor manufacturers to single-source risk.
- Interoperability Protocol Fragmentation:Competing communication standards between BACnet, Modbus, and emerging wireless mesh protocols complicate integration with legacy building automation systems.
Strategic Opportunities
- Underpenetrated Residential Segment:Consumer awareness of indoor pollutant exposure remains nascent in suburban housing markets, creating white space for sub-$200 connected devices.
- Healthcare Ventilation Verification:Operating room and isolation ward managers seek portable audit tools to validate HVAC performance against Joint Commission standards.
- LEED Certification Premium:The US Green Building Council's indoor environmental quality credit requirements are incentivizing developers to specify integrated monitoring systems in new construction.
Industry Challenges
- Embedded Firmware Talent Scarcity:Shortage of engineers skilled in low-power wireless stack development and edge computing architectures delays product release cycles.
- Multi-Agency Certification Timelines:Simultaneous pursuit of FCC radio approval, EPA equivalency method designation, and CE marking extends time-to-revenue by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Air Quality Monitor Market |
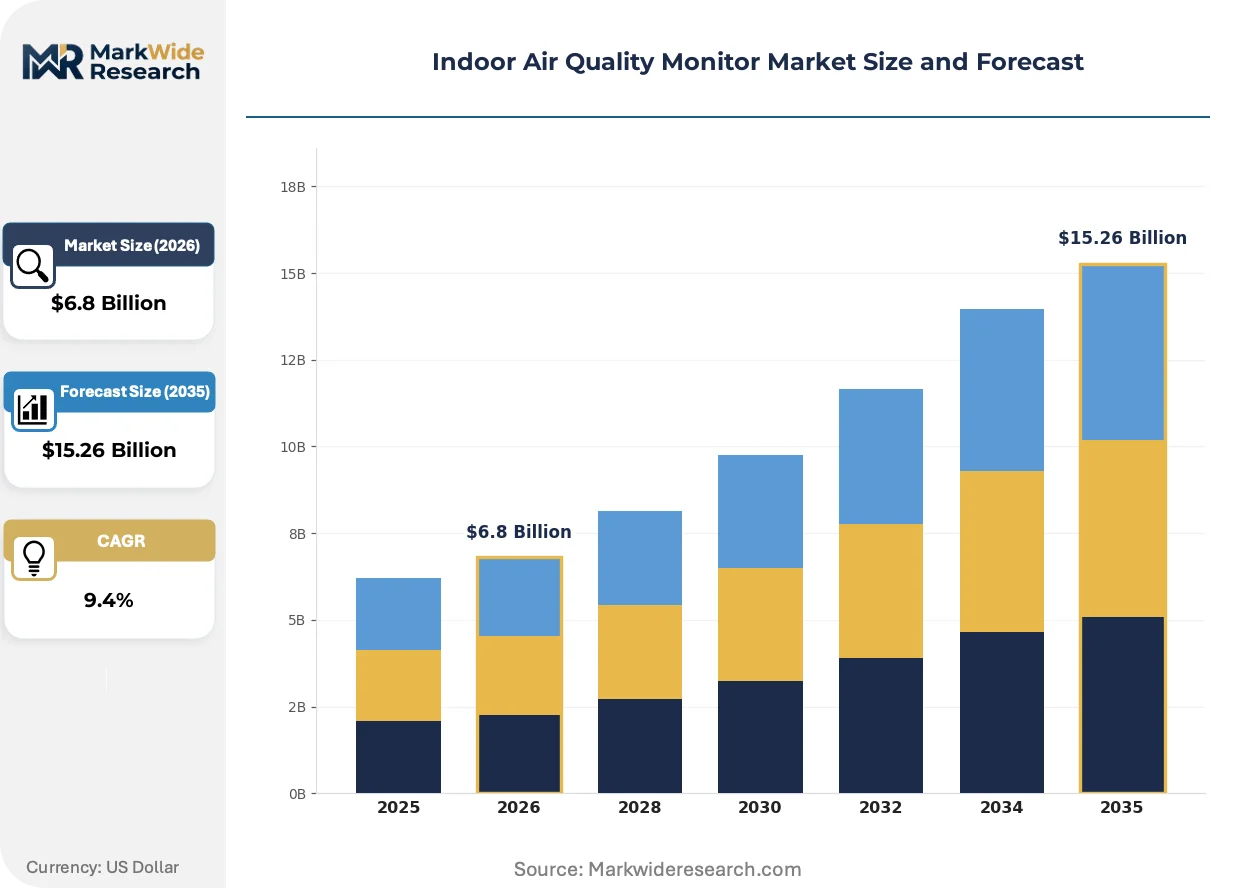
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Wall-Mounted Monitors, Desktop Monitors, Multi-Parameter Monitors Technology: Electrochemical Sensors, Optical Sensors, MEMS Sensors, PID Sensors End User: Residential Users, Commercial Spaces, Industrial Facilities, Educational Institutions Installation Type: Hardwired Systems, Wireless Systems, Standalone Units, Integrated Systems |
| Companies Covered | Thermo Fisher Scientific Inc., Siemens AG, Emerson Electric Co., Honeywell International Inc., Teledyne Technologies Inc., HORIBA Ltd., Aeroqual Ltd., Testo SE & Co. KGaA, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Air Quality Monitor Market Strategic Shifts
Sensor fusion architectures and edge AI inference are compressing the latency between pollutant detection and automated building system response, reshaping how facilities manage ventilation energy against air quality tradeoffs.
Optical particle counters utilizing laser scattering and photodiode arrays are expanding into portable industrial hygiene applications. Manufacturing plant safety managers deploy these units for spot-checking welding fume exposure and solvent vapor accumulation. The technology is expanding into temporary construction site monitoring where hardwired infrastructure proves impractical.
REACH restrictions on heavy metals in electronic components are forcing redesigns of electrochemical sensor housings and electrode materials. European monitor manufacturers must reformulate mercury-free reference electrodes and lead-free solder joints. Laboratory-grade instrument suppliers face the steepest compliance burden as their certification-dependent customers demand full material disclosure.
Facility managers increasingly bundle air quality monitoring with energy management service contracts rather than purchasing hardware outright. Third-party HVAC service providers capture recurring revenue streams by installing and maintaining sensor networks under multi-year agreements. This arrangement concentrates in commercial office portfolios in Germany and the Netherlands where building owners prioritize operational expenditure predictability over capital deployment.
Indoor Air Quality Monitor Market Segmentation
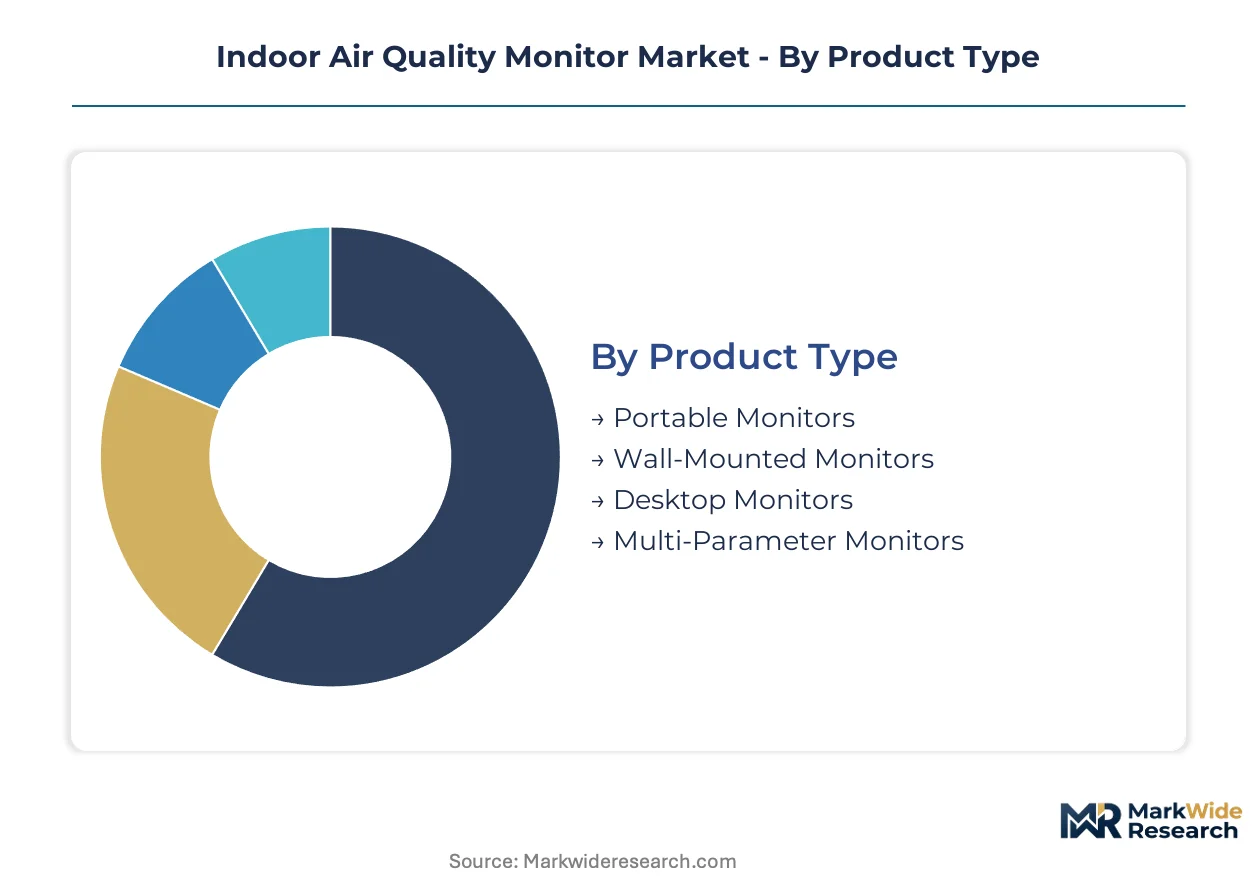
Segmentation in indoor air quality monitoring reveals divergent technical requirements between embedded building infrastructure and portable audit applications. Facility managers prioritize hardwired integration for continuous compliance, while industrial hygienists demand mobility for spot assessments. Understanding these structural splits guides product positioning and channel strategy.
Product Type:
Integration depth varies sharply across form factors, with portable units serving intermittent audit needs while wall-mounted and multi-parameter systems anchor permanent building infrastructure.
- Portable Monitors:Battery-powered handheld units with electrochemical or optical sensing cores deliver spot measurements for industrial hygiene teams and HVAC contractors. Demand concentrates in Germany and the Netherlands where facility managers conduct quarterly ventilation audits under federal energy code mandates, though quarterly recalibration requirements inflate total ownership costs.
- Multi-Parameter Monitors:Networked instruments simultaneously track particulate matter, volatile organic compounds, carbon dioxide, and humidity through modular sensor arrays. Healthcare facilities in the United States are expanding procurement to meet Joint Commission ventilation verification standards and EPA tightening of indoor pollutant thresholds.
- Wall-Mounted Monitors:Fixed-installation units designed for continuous ambient monitoring in commercial corridors and patient waiting areas.
- Desktop Monitors:Compact plug-in devices targeting residential and small office environments with single-room coverage.
Volume placements concentrate in portable monitors; the faster expansion belongs to multi-parameter monitors.
Technology:
Cost tier stratification separates mature electrochemical platforms from emerging MEMS architectures that semiconductor foundries are driving toward mass-market price points.
- MEMS Sensors:Microelectromechanical systems fabricated at semiconductor foundries integrate electrochemical or optical transduction at chip-scale dimensions. Residential deployments in suburban United States housing markets are accelerating as unit costs compress, though drift sensitivity requires more frequent replacement cycles than laboratory-grade alternatives.
- Electrochemical Sensors:Amperometric cells with liquid electrolyte and gas-permeable membranes measure target analytes through redox reactions at parts-per-billion sensitivity. Commercial building operators in Germany rely on these for regulatory compliance despite quarterly recalibration burdens that service providers are bundling into multi-year maintenance contracts.
- Optical Sensors:Laser scattering and photodiode detection systems for particulate counting without consumable reagents.
- PID Sensors:Photoionization detectors using ultraviolet lamps to ionize volatile organic compounds for broad-spectrum detection.
Electrochemical sensors retain the largest installed base; MEMS sensors are climbing the fastest on foundry scale economies.
End User:
Application maturity spans from nascent residential awareness to deeply regulated industrial hygiene protocols with established procurement workflows.
- Commercial Spaces:Office building operators and retail facility managers deploy integrated monitoring networks to satisfy LEED certification credits and operational expenditure predictability goals. The US Green Building Council's indoor environmental quality requirements are incentivizing developers in the United States to specify hardwired systems in new construction.
- Industrial Facilities:Manufacturing plant safety managers utilize portable optical particle counters for welding fume exposure and solvent vapor monitoring. Temporary construction site applications in Germany favor wireless deployments where hardwired infrastructure proves impractical.
- Residential Users:Homeowners and apartment dwellers with limited awareness of indoor pollutant exposure risks.
- Educational Institutions:School districts responding to EPA enforcement of radon and fine particulate thresholds.
Commercial spaces generate the highest unit value; industrial facilities show the steepest expansion trajectory on regulatory enforcement intensity.
Installation Type:
Customer type bifurcation separates capital-prioritizing building owners from operational-expenditure-focused service contract adopters.
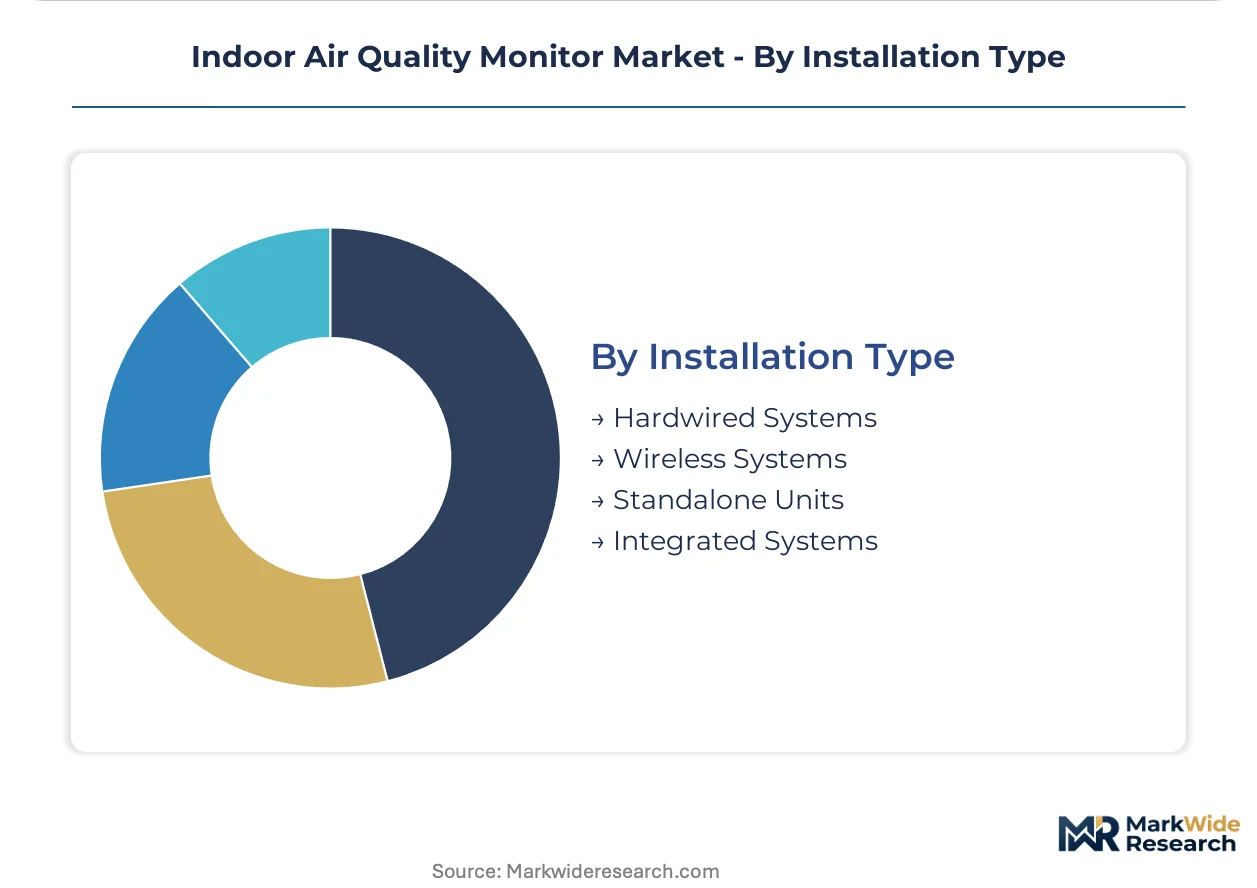
- Integrated Systems:Hardwired sensor networks feeding real-time data into BACnet or Modbus building management platforms enable automated ventilation response. Facility managers in Germany and the Netherlands increasingly procure through third-party HVAC service providers under multi-year agreements rather than purchasing hardware outright.
- Wireless Systems:Battery-powered mesh networks using emerging protocols that bypass legacy building automation infrastructure. Interoperability fragmentation between competing standards complicates integration, delaying product release cycles for manufacturers lacking embedded firmware engineering depth.
- Hardwired Systems:Permanently installed units with dedicated power and data cabling for mission-critical applications.
- Standalone Units:Self-contained devices with local display and no network connectivity for basic residential use.
Integrated systems dominate installed value; wireless systems are gaining share fastest on retrofit market flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German free economic zones and US Opportunity Zones are concentrating manufacturing investment for sensor fabrication and monitor assembly. Tax-advantaged districts in Bavaria and Texas anchor production clusters serving European and North American procurement channels.
United States
School districts and healthcare facility managers drive multi-parameter monitor procurement under EPA tightening of indoor pollutant thresholds. OSHA ventilation standards and LEED certification requirements from the US Green Building Council reshape building automation specifications. Greater Boston's medical technology corridor hosts laboratory-grade instrument development serving Joint Commission compliance needs.
Germany
Municipal building operators concentrate demand for continuous air quality tracking under federal building energy code mandates. REACH restrictions on heavy metals force electrochemical sensor redesigns eliminating mercury and lead from reference electrodes. Stuttgart's automotive supplier ecosystem diversifies into MEMS sensor fabrication for residential monitor cost compression.
China
Semiconductor foundries drive MEMS sensor unit costs downward through scale economies in electrochemical and optical transduction. GB standards for indoor environmental quality tighten compliance requirements for commercial building operators. Shenzhen's electronics manufacturing cluster dominates optical component supply for laser scattering particle counters.
Netherlands
Commercial office portfolio managers prioritize operational expenditure predictability through third-party HVAC service contracts bundling sensor networks. ECHA oversight of chemical substance registration affects electrochemical sensor electrolyte formulations. Eindhoven's high-tech systems sector anchors wireless mesh protocol development for building automation integration.
Japan
METI efficiency standards for building energy management accelerate integrated monitoring system deployment in new commercial construction. JIS certification requirements for measurement instrumentation sustain premium positioning for laboratory-grade suppliers. Osaka's industrial equipment manufacturers expand portable optical particle counter production for temporary construction site applications.
Indoor Air Quality Monitor Market Competitive Environment
German producers anchor one tier; US specialists hold premium laboratory-grade positioning through analytical instrument heritage. The vendor base splits between diversified conglomerates with building automation integration capabilities and focused sensor technology developers. Three archetypes dominate: integrated building systems providers, semiconductor-enabled MEMS specialists, and precision analytical instrument manufacturers. Competitive moves concentrate on strategic partnerships for protocol interoperability and geographic expansion through regional HVAC service channel agreements.
Among diversified technology conglomerates, Siemens AG and Emerson Electric Co. exemplify the integrated building systems archetype, embedding air quality modules within broader automation portfolios. Thermo Fisher Scientific Inc. occupies the precision analytical tier, sustaining premium positioning through laboratory-grade detection heritage. Honeywell International Inc. anchors the North American market through building management platform integration, representing the convergence of sensor hardware with software-enabled facility control.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Siemens AG |
| Emerson Electric Co. |
| Honeywell International Inc. |
| Teledyne Technologies Inc. |
| HORIBA Ltd. |
| Aeroqual Ltd. |
| Testo SE & Co. KGaA |
| 3M Company |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between laboratory-grade precision instruments and mass-market MEMS devices manifests in pricing spreads exceeding five-to-one, with supply chain configurations tracking this split through captive semiconductor foundries serving commodity tiers versus specialized analytical component suppliers anchoring premium positioning.
Pricing Analysis
Lead-time-driven pricing stratification rewards expedited delivery premiums for laboratory-grade instruments while spot inventory discounts concentrate in residential MEMS segments. Three-tier pricing structure across premium, standard, and economy levels separates Joint Commission-compliant healthcare monitors from commercial building automation modules and sub-$200 residential units. Pricing pressure stems from semiconductor foundry scale economies compressing MEMS sensor costs downward. Residential buyers exhibit highest price sensitivity; healthcare procurement committees prioritize certification pedigree over unit cost.
Supply Chain Analysis
Domestic-content mandates in Germany's federal procurement rules and US Buy American provisions for school district installations are reshaping sourcing toward regional sensor assembly. Optical component fabrication concentrates in China, Taiwan, and Japan; electrochemical cell production centers on Germany and the United States. Raw material dependencies span laser diodes, photodetectors, and specialty electrolyte formulations. Single-source vulnerability concentrates in East Asian photodetector foundries. Distribution runs through HVAC service providers bundling hardware into multi-year maintenance contracts in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around building automation integration capabilities, with MEMS cost compression and multi-agency certification timelines forcing sub-scale sensor developers toward acquisition or exit.
For Market Incumbents: Anticipate margin compression in portable monitor segments as semiconductor foundries enable new entrants to undercut on MEMS-based devices. Defensive consolidation moves center on acquiring wireless mesh protocol engineering talent to resolve interoperability fragmentation, and securing exclusive HVAC service channel agreements in Germany and the Netherlands to lock out competitors from the fastest-expanding procurement mode.
For New Entrants and Emerging Players: The mid-tier pricing gap between $800 commercial multi-parameter systems and $150 residential units offers white-space positioning for connected devices with professional-grade VOC detection at consumer price points. Target suburban US housing markets through direct-to-consumer channels, leveraging foundry partnerships to compress BOM costs below incumbent thresholds while bypassing legacy building automation integration requirements.
For Investors and Strategic Acquirers: Re-rating potential sits with MEMS-enabled specialists possessing FDA-equivalency method designations given accelerating healthcare ventilation verification demand. Long-term viability favors acquisition targets with captive firmware engineering teams and existing EPA equivalency certifications. Watch Joint Commission enforcement intensity as the inflection signal for laboratory-grade instrument demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Development | Edge AI inference integration enables automated ventilation response, differentiating integrated systems from standalone units. |
| Multi-Agency Certification Investment | Simultaneous EPA equivalency, FCC approval, and CE marking access accelerates time-to-revenue for healthcare-focused entrants. |
| HVAC Service Channel Partnership | Third-party maintenance contract bundling captures recurring revenue streams in German and Dutch commercial portfolios. |
| MEMS Foundry Scale Partnership | Semiconductor fabrication alliances compress unit costs for residential market penetration against electrochemical incumbents. |
| Wireless Mesh Protocol Standardization | BACnet and Modbus interoperability investment resolves integration friction delaying building automation retrofit cycles. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with facility managers, HVAC service contract directors, biomedical engineers at healthcare systems, electrochemical sensor R&D leads, and semiconductor foundry planning officers. Secondary sources encompassed EPA enforcement databases, Joint Commission ventilation standards documentation, German federal building energy code regulatory texts, and REACH restriction updates from ECHA. Bottom-up unit shipment estimates triangulated against top-down building stock penetration models.
Data-stream reconciliation across sensor technology cost curves, regulatory compliance timeline assumptions, and regional procurement pattern shifts generated volume and value outputs across the projection horizon. Segmentation dimensions modeled included product type integration depth, sensor technology cost tier, end-user regulatory maturity, and installation type capital versus operational expenditure preference. CAGRs derived from fitted adoption curves incorporating MEMS cost compression trajectories and building electrification retrofit cycle timing.
Inputs from EPA enforcement databases and German municipal procurement records were available through the study window; gaps in real-time wireless mesh protocol adoption rates introduce uncertainty bands around wireless system share projections. Forecasts reflect documented assumptions regarding semiconductor foundry capacity expansion and regulatory calibration requirement stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Digital Olfaction Products Market
Sensors
Smart Barcode Readers Market
Sensors
Global Remote Tank Monitoring System Market
Sensors
Sensor Landscape in Robotics and ADAS Vehicle Market
Sensors
Robot Sensor Market
Sensors
Transport Monitoring System Market
Sensors
Refrigeration Monitoring Market
Sensors
Vision Positioning System Market
Sensors
Terrestrial Laser Scanning System Market
Sensors
Vibration Monitoring Market
Sensors
Surface Haptic Technology Market
Sensors
Automatic Number Plate Recognition (ANPR) Market
Sensors
Yield Monitoring Systems Market
Sensors
Barcode Scanner Market
Sensors
Consumer 3D Sensing Products Market
Sensors
Transportation Sensors Market