
 Global Stadium Lighting Market | 2026-2036
Global Stadium Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stadium Lighting Market Intelligence
Entertainment venues hosting hybrid concert-sport programming is recalibrating fixture specification toward tunable white and RGBW systems. Signify leverages its Interact Sports platform to anchor control-system revenue in European football grounds. Musco Sports Lighting sustains its position through factory-direct project engineering that eliminates distributor margin. Panasonic Corporation dominates Asian baseball and cricket venue retrofits with integrated broadcast-camera synchronization.
Stadium lighting encompasses high-output luminaires engineered to deliver uniform illuminance across playing surfaces, typically achieving color rendering indices above 90 and glare ratings compliant with FIFA, UEFA, or IESNA broadcast standards. LED floodlights have displaced metal halide lamps as the dominant product type due to instantaneous restrike capability and 50,000-hour operational life. Permanent fixtures generate the largest revenue pool among installation categories, though portable systems command premium pricing for temporary event infrastructure. Professional sports arenas absorb the majority of capital expenditure, while educational institutions represent a volume-driven replacement cycle for aging high pressure sodium lamps.
The EU F-Gas Regulation and RoHS directive restrict mercury-containing lamp imports, compelling specifiers toward LED-only designs in Europe. EPA hazardous waste rules in the United States impose cradle-to-grave tracking on spent metal halide and high pressure sodium lamps, elevating total cost of ownership for legacy technologies. China's GB standards for sports venue lighting mandate minimum efficacy thresholds that favor domestic LED manufacturers. Stakeholders must monitor evolving broadcast standards from FIFA and the International Olympic Committee, as 8K ultra-high-definition production will tighten flicker and color-tolerance requirements beyond current specifications.
Market Dynamics
Legacy metal halide infrastructure across professional sports venues faces accelerated decommissioning as the EU F-Gas Regulation mandates mercury-free illumination and broadcast standards tighten color-tolerance thresholds for ultra-high-definition production.
Growth Catalysts
- EU F-Gas Regulation:The phase-out of mercury-containing lamps across member states forces stadium operators toward LED retrofits, eliminating restrike delays and reducing hazardous waste disposal liabilities.
- 8K broadcast readiness:FIFA and International Olympic Committee production standards are tightening flicker requirements, compelling venues to upgrade legacy systems that cannot meet sub-0.5% flicker thresholds.
- Tournament hosting cycles:Germany, China, and Brazil are synchronizing stadium modernization with upcoming international competition obligations, concentrating capital expenditure in specific metropolitan clusters.
Market Restraints
- LED driver supply concentration:Semiconductor foundry capacity constraints in East Asia create bottlenecks for high-wattage constant-current drivers essential for floodlight assemblies.
- Legacy fixture sunk costs:Metal halide installations with remaining operational life represent stranded assets that delay full-system replacement decisions despite operational inefficiencies.
- Specialized installation labor scarcity:Rigging and photometric calibration expertise for high-mast sports lighting commands premium wages in markets with limited certified contractor pools.
Strategic Opportunities
- Hybrid venue programming:Entertainment complexes hosting concert-sport crossover events require tunable white and RGBW systems that single-purpose sports venues lack, creating specification premiums.
- EPA hazardous waste tracking:Cradle-to-grave documentation requirements for spent metal halide lamps in the United States elevate total cost of ownership for legacy technologies, accelerating replacement economics.
- Integrated control platforms:IoT-enabled lighting management systems that synchronize with broadcast camera feeds represent unbundled revenue streams beyond hardware sales.
Industry Challenges
- Photometric calibration expertise:Maintaining uniformity ratios and glare ratings compliant with IESNA standards requires specialized technicians that regional contractors struggle to retain.
- Legacy electrical infrastructure compatibility:Aging stadium power distribution systems often require upstream transformer upgrades to support LED inrush characteristics and harmonic filtering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stadium Lighting Market |
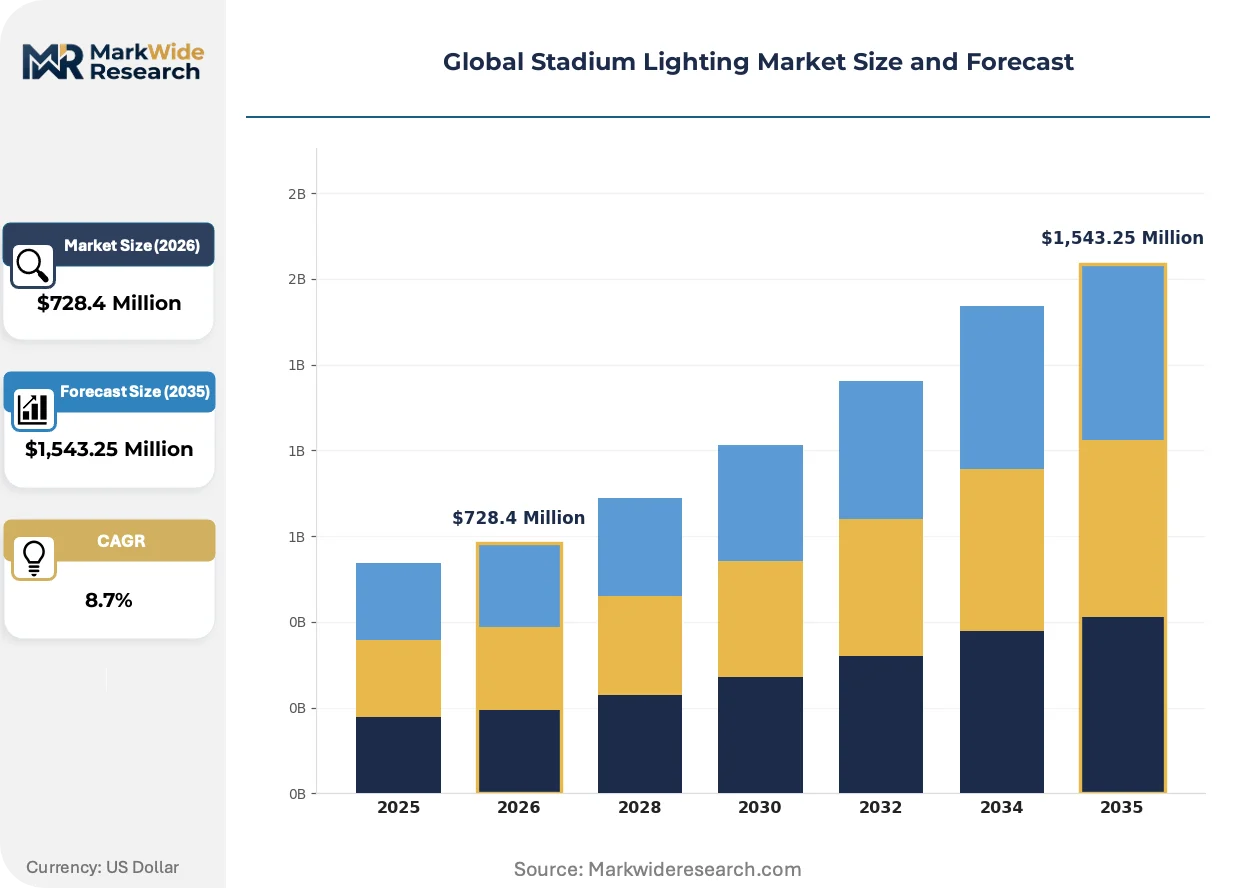
| Market Size in 2026 | $728.4 Million |
| Market Size in 2035 | $1,543.25 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Floodlights, Metal Halide Lamps, High Pressure Sodium Lamps, Halogen Lamps, Induction Lamps Application: Sports Events, Concerts, Ceremonial Functions, Training Sessions, Broadcasting Installation: Permanent Fixtures, Portable Systems, Hybrid Installations, Temporary Setups End User: Professional Sports Arenas, Educational Institutions, Community Parks, Entertainment Venues |
| Companies Covered | Philips Lighting, Hubbell Incorporated, Musco Sports Lighting, Panasonic Corporation, Zumtobel Group, Signify, Eaton Corporation, General Electric, Acuity Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stadium Lighting Market Strategic Shifts & Innovations
Broadcast-quality illumination specifications are compressing product lifecycles as venue operators prioritize instantaneous restrike capability and spectral tunability over pure lumen output metrics.
RGBW LED modules with independent channel control are rewriting fixture specification standards for venues hosting hybrid entertainment programming. Arena operators in North America and Western Europe are specifying these systems for concert-sport crossover events that demand color temperature shifts between 2700K and 6500K within minutes. The technology is compressing the addressable market for single-purpose white-only floodlights while expanding control-system attach rates.
China's GB standards for sports venue lighting now mandate minimum efficacy thresholds that domestic LED manufacturers can meet more readily than importers. The MIIT-aligned certification process favors local supply chains for stadium projects receiving state funding, creating procurement preference structures that multinational vendors must navigate through joint ventures or technology licensing. Provincial sports bureaus in Guangdong and Jiangsu are enforcing these standards most stringently for facilities hosting national competitions.
Service unbundling is fragmenting traditional equipment-procurement relationships as venue operators separate lighting hardware from control-system integration and ongoing photometric maintenance. Municipal stadium authorities in Brazil and Germany now issue distinct RFPs for fixture supply, software platforms, and multi-year uniformity guarantees. This pattern is most visible in publicly owned venues where procurement regulations favor discrete contract awards over single-source turnkey arrangements.
Global Stadium Lighting Market Segmentation
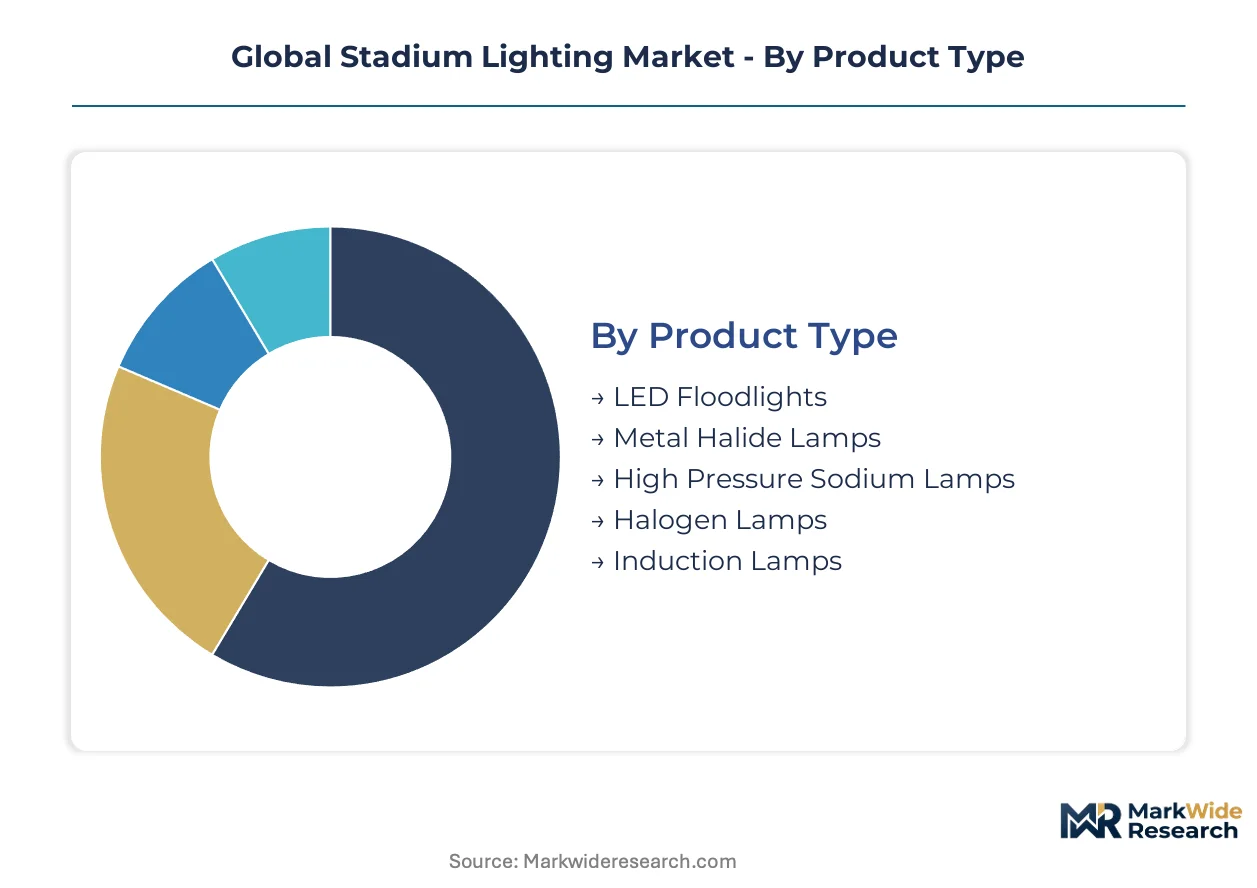
Stadium lighting procurement splits sharply between volume-driven replacement cycles and premium specification for broadcast-ready venues. Understanding where capital concentrates across product, application, and end-user dimensions reveals which segments command pricing power versus which compete on operational cost reduction.
Product Type:
LED floodlights capture the premium tier while legacy technologies retain residual volume in price-sensitive retrofits.
- LED Floodlights:Solid-state arrays delivering 130+ lumens per watt with sub-0.5% flicker tolerance for 8K broadcast compliance. Demand clusters in German football grounds and Chinese national stadiums where GB standards and EU F-Gas Regulation eliminate mercury alternatives.
- Metal Halide Lamps:Ceramic arc-tube designs still specified for budget-constrained educational facilities in Brazil and community parks with remaining fixture life. EPA hazardous waste tracking elevates total cost of ownership, accelerating phase-out decisions.
- High Pressure Sodium Lamps:Amber-spectrum legacy systems prevalent in municipal parks across India and Southeast Asia where efficacy concerns outweigh color rendering priorities.
- Halogen Lamps:Tungsten-halogen technology limited to small-scale training facilities and emergency backup applications requiring instant ignition.
- Induction Lamps:Electrodeless fluorescent systems occupying niche positions in industrial-adjacent venues seeking 100,000-hour lifespan without LED driver complexity.
Today's leader: LED Floodlights. Tomorrow's challenger: Induction Lamps in specific longevity-critical niches.
Application:
Broadcast and hybrid entertainment programming command specification premiums over pure athletic functionality.
- Sports Events:FIFA and UEFA compliant illumination for professional competition, requiring uniformity ratios above 0.7 and glare ratings below 50. Brazilian and German stadium modernization cycles concentrate demand here.
- Concerts:RGBW tunable systems enabling 2700K-6500K shifts within minutes. North American and Western European arena operators specify these for crossover programming that single-purpose venues cannot accommodate.
- Ceremonial Functions:Spectral precision for opening ceremonies and award presentations, often requiring temporary augmentation of base sports lighting.
- Training Sessions:Reduced uniformity standards permitting lower-cost LED arrays in practice facilities adjacent to main venues.
- Broadcasting:Camera-synchronized flicker control and color-temperature stability for ultra-high-definition production, representing the most stringent specification tier.
Sports Events anchor current revenue. Concerts are gaining share fastest as hybrid venue programming expands.
Installation:
Permanent infrastructure absorbs majority capital while temporary systems extract premium pricing for event-specific deployment.
- Permanent Fixtures:High-mast pole installations with 25-year structural lifecycles, dominant in professional sports arenas and major entertainment venues across China and Germany.
- Portable Systems:Mobile tower units and truss-mounted arrays for tournament overflow venues and temporary concert infrastructure, commanding 40-60% price premiums over equivalent permanent output.
- Hybrid Installations:Fixed base systems with modular augmentation capacity, specified by municipal authorities in Brazil seeking flexibility between sporting and cultural programming.
- Temporary Setups:Rapid-deployment rigging for one-off events, prevalent in emerging market cities hosting inaugural international competitions without permanent venue infrastructure.
Permanent Fixtures dominate installed base value. Portable Systems offer the steepest margin expansion trajectory.
End User:
Professional venues drive specification innovation while educational and community segments sustain replacement volume.
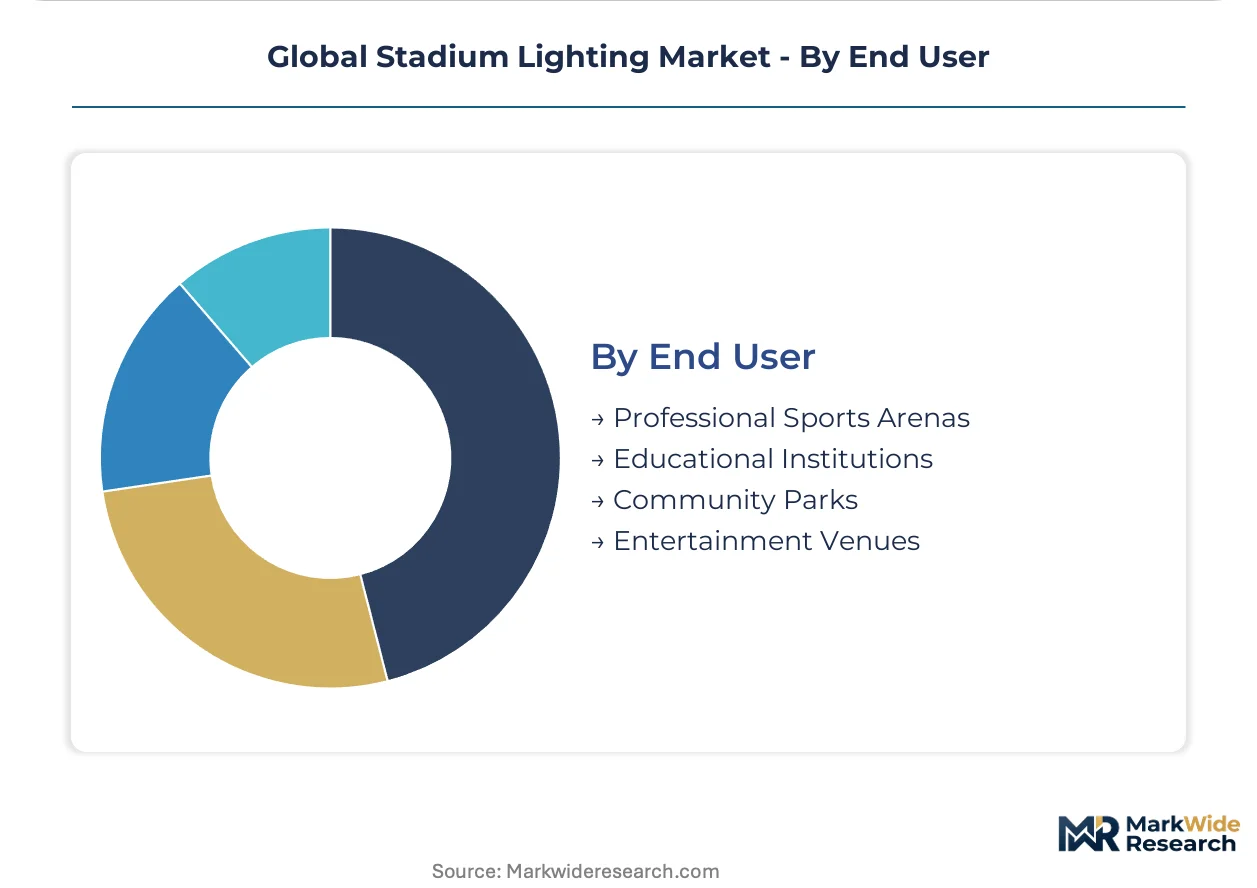
- Professional Sports Arenas:Broadcast-standard facilities with dedicated capital budgets for LED retrofits, concentrated in tournament-hosting obligations across Germany, China, and Brazil.
- Educational Institutions:High school and university stadiums replacing aging high pressure sodium installations, representing volume-driven demand with compressed procurement timelines.
- Community Parks:Municipal facilities where operational cost reduction outweighs broadcast compliance, prevalent in Indian and Southeast Asian markets.
- Entertainment Venues:Multi-purpose arenas and amphitheaters requiring spectral tunability for hybrid concert-sport programming, commanding control-system attach rates above hardware-only sales.
Professional Sports Arenas set technology direction. Entertainment Venues are expanding most quickly as programming formats converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate assembly to jurisdictions with lower compliance costs for mercury-free certification and extended producer responsibility frameworks.
Germany
Bundesliga stadium modernization and UEFA tournament obligations drive LED retrofit demand across Munich, Dortmund, and Berlin venues. The EU F-Gas Regulation enforces mercury-free mandates that eliminate metal halide imports. Bavaria's sports infrastructure clusters concentrate engineering procurement for broadcast-compliant floodlight systems.
China
MIIT-aligned GB standards mandate minimum efficacy thresholds that domestic LED manufacturers satisfy more readily than foreign competitors. The dual carbon goals accelerate phase-outs of legacy high pressure sodium installations in municipal venues. Guangdong and Jiangsu provincial sports bureaus enforce certification stringently for national competition facilities.
Brazil
FIFA World Cup hosting obligations concentrate capital expenditure in São Paulo and Rio de Janeiro metropolitan stadiums. ANVISA hazardous material protocols impose cradle-to-grave tracking on imported lighting components. Minas Gerais and Paraná state governments are synchronizing regional venue upgrades with federal tournament infrastructure commitments.
United States
EPA hazardous waste rules elevate total cost of ownership for metal halide systems through mandatory spent-lamp documentation. Entertainment venues in Los Angeles and Las Vegas specify RGBW tunable systems for hybrid concert-sport programming. Texas and Florida municipal authorities issue discrete RFPs for fixture supply and control-system integration.
India
Bureau of Indian Standards efficacy mandates and PLI scheme incentives favor domestic LED assembly for sports venue retrofits. High pressure sodium lamps retain residual share in community parks where color rendering requirements remain secondary to operational cost reduction. Maharashtra and Karnataka state sports departments concentrate procurement for cricket stadium modernization.
Global Stadium Lighting Market Key Industry Players
Technology licensing dominates the current landscape as manufacturers secure patent access for flicker-control algorithms and broadcast-synchronization protocols. The vendor base stratifies across three tiers: integrated conglomerates with control-system platforms, specialized sports-lighting engineering firms, and regional fixture assemblers serving price-sensitive retrofits. Two strategic archetypes have emerged: broadcast-technology specialists anchoring premium specification tiers, and factory-direct project engineers eliminating distributor margin. Competitive intensity centers on M&A activity for IoT platform capabilities and geographic expansion through joint ventures in markets with local content requirements.
Among integrated lighting conglomerates, Signify and Panasonic Corporation occupy positions that exemplify divergent geographic anchoring strategies. Signify leverages its Interact Sports platform to secure recurring control-system revenue across European football venues. Panasonic Corporation anchors Asian market presence through integrated broadcast-camera synchronization capabilities for baseball and cricket retrofits. Musco Sports Lighting represents the factory-direct archetype, sustaining competitive position through elimination of distributor margin in project engineering.
| Leading Market Players |
|---|
| Philips Lighting |
| Hubbell Incorporated |
| Musco Sports Lighting |
| Panasonic Corporation |
| Zumtobel Group |
| Signify |
| Eaton Corporation |
| General Electric |
| Acuity Brands |
| Others |
Cost & Logistics Intelligence
LED driver semiconductor costs cascade through three pricing tiers as East Asian foundry capacity constraints tighten margins on high-wattage constant-current components destined for floodlight assemblies. German and Chinese stadium operators absorb premium pricing for broadcast-compliant fixtures while Brazilian municipal buyers negotiate volume discounts on educational retrofits.
Pricing Analysis
Distributor margin elimination distinguishes factory-direct project engineering from channel-dependent competitors. Project-based pricing dominates professional sports arenas where photometric calibration and multi-year uniformity guarantees bundle with hardware. Certification grade—specifically FIFA and UEFA compliance tiers—separates premium specification from standard LED arrays. Cost compression in the educational segment intensifies as high-pressure sodium replacement cycles compress procurement timelines. Community parks and municipal facilities exhibit highest price sensitivity; broadcast-ready venues demonstrate lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German Bundesliga and Chinese national stadium clusters. Manufacturing concentrates in China, Germany, and Japan where LED chip fabrication and precision optics production anchor supply. Raw material dependencies include gallium nitride wafers, aluminum heat sinks, and polycarbonate lens arrays. Single-source vulnerability in semiconductor foundry capacity creates bottleneck risk for high-wattage driver procurement. Distribution runs through factory-direct engineering teams and specialized sports lighting contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in control-system attach rates and service unbundling as venue operators separate hardware procurement from IoT platform integration. LED efficacy improvements and mercury-phase-out regulations accelerate premium-tier specification.
For Market Incumbents: To counter factory-direct competitors eliminating distributor margin, incumbents should deepen backward integration into LED driver production and secure captive supply of gallium nitride components. Certification investment in FIFA and UEFA compliance tiers protects specification premium against price-driven challengers. For New Entrants and Emerging Players: Enter via portable systems for temporary tournament infrastructure where 40-60% price premiums over permanent fixtures create margin headroom. Brazilian state-level stadium modernization and Indian cricket venue retrofits represent the most penetrable geographies. Go-to-market positioning should emphasize rapid-deployment rigging expertise for inaugural international competitions. For Investors and Strategic Acquirers: Consolidation pressure builds where IoT platform capabilities fragment across hardware vendors lacking software integration competence. Long-term viability favors broadcast-technology specialists with flicker-control patent portfolios over pure fixture assemblers. Acquisition targets include regional contractors with certified photometric calibration expertise. The signal to watch is tournament hosting cycle announcements concentrating capital expenditure in specific metropolitan clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Control Platform Integration | Signify's Interact Sports anchors recurring revenue beyond one-time fixture sales. |
| Backward Integration into Drivers | Captive semiconductor supply insulates margins from East Asian foundry bottlenecks. |
| Factory-Direct Project Engineering | Musco's elimination of distributor margin sustains competitive positioning in premium tiers. |
| Joint Venture Licensing | MIIT-aligned GB standards in China compel foreign vendors toward technology transfer arrangements. |
| Photometric Maintenance Contracts | Service unbundling creates multi-year revenue streams separate from hardware procurement. |
Research Approach
Coverage spans Germany, China, Brazil, the United States, and India, with primary inputs from each market cluster. Stadium operators, lighting procurement officers, electrical contractors, and broadcast production engineers provided demand-side intelligence. Secondary validation drew from EU F-Gas Regulation filings, EPA hazardous waste documentation, MIIT GB standard certifications, and FIFA/UEFA broadcast compliance databases. Bottom-up fixture shipment analysis and top-down venue modernization budget triangulation anchored market sizing.
Rate-of-change decomposition separated volume growth from specification mix shift across the projection horizon. Segmentation dimensions modeled include product type, application tier, installation category, and end-user archetype. CAGRs derived from tournament hosting cycle phasing, regulatory phase-out deadlines, and broadcast standard evolution. Industry-specific inputs incorporated LED efficacy improvement curves and semiconductor foundry capacity utilization.
Inputs from stadium operators and procurement databases were available through the study window; gaps in real-time fixture pricing transparency introduce uncertainty bands around premium-tier estimates. Forecasts reflect assumptions regarding tournament hosting commitments and regulatory enforcement timelines. Supply chain disruption scenarios and broadcast standard acceleration could revise trajectory. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Studio Lighting Equipment Market
Lighting
GCC Smart Lighting Market
Lighting
Solid-State Lighting Source Market
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Illuminating Signs Market
Lighting
Explosion Proof Lighting Market
Lighting
Ambient Lighting Market
Lighting
Bulb Market
Lighting
Smart Lamp Market
Lighting
Cleanroom Lighting Market
Lighting
Industrial UV-C Disinfection Lighting Market
Lighting
LED Solar Lighting Market
Lighting
Street Lighting Market
Lighting
Global Flame Proof Lighting Market
Lighting
LED Eye Protection Desk Lamp Market
Lighting
Tritium Light Source Market