
 Global Epilepsy Monitoring Devices Market | 2026-2036
Global Epilepsy Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Epilepsy Monitoring Devices Market Foresight
Subscription-based leasing for long-term video EEG systems is reconfiguring capital deployment across hospital networks and smaller neurology clinics. Medtronic leverages its implantable neuromodulation infrastructure to anchor invasive monitoring portfolios in tertiary care centers. Natus Medical sustains dominance in diagnostic hardware through backward integration into electrode manufacturing and software calibration. Empatica differentiates via wearable sensor miniaturization targeted at pediatric and ambulatory populations.
Epilepsy monitoring devices encompass electrophysiological recording instruments that capture, amplify, and analyze neuronal electrical activity through scalp or intracranial electrodes, typically sampling at 256–1024 Hz with 16–256 channels to localize seizure foci and classify epileptiform discharges. These systems serve primarily to guide surgical resection planning, quantify therapy response, and enable remote seizure surveillance in chronic care settings. Video EEG monitoring retains the largest installed base in pre-surgical evaluation workflows, while wearable sensors represent the fastest-expanding margin pool as home-based long-term monitoring protocols gain clinical acceptance. Cloud-based analytics sits at an earlier commercialization stage but attracts concentrated R&D investment from vendors seeking recurring revenue models.
FDA premarket notification requirements under 21 CFR Part 892 shape hardware safety benchmarks and software validation protocols for seizure detection algorithms entering the US market. EMA's MDR framework and Japan's PMDA QMS ordinance impose additional clinical evidence standards that lengthen registration timelines but elevate barriers against non-compliant entrants. WHO's integration of epilepsy into universal health coverage targets is expanding reimbursable access pathways in lower-income health systems. Stakeholders must weigh regulatory capital requirements against the pace of wearable form-factor innovation to calibrate portfolio bets between institutional and decentralized care models.
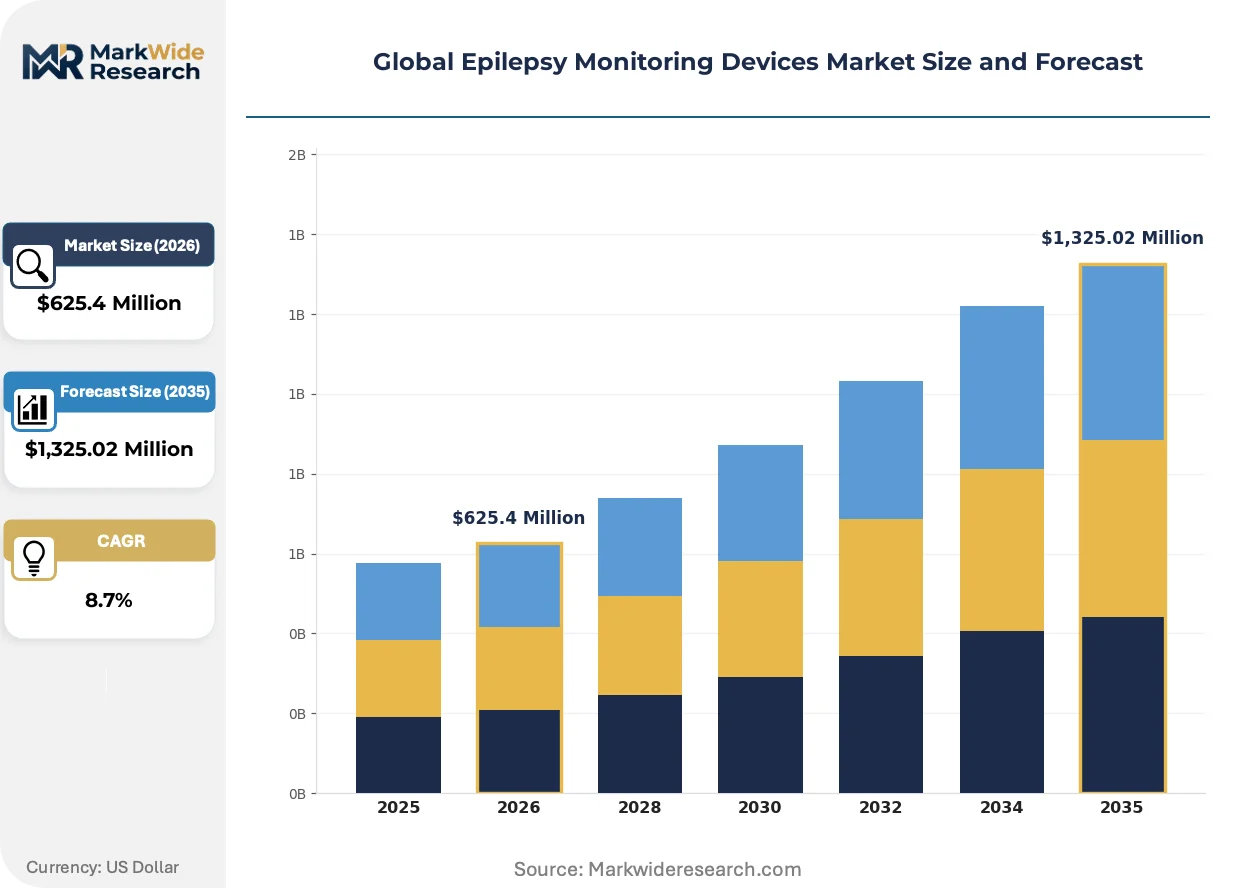
Market Dynamics
Subscription-based leasing for long-term video EEG systems is reconfiguring capital deployment across hospital networks and smaller neurology clinics, compressing upfront procurement cycles while extending vendor lock-in periods through bundled software and calibration services.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated clearance pathways for wearable seizure detection algorithms reduce time-to-market for novel sensors targeting pediatric ambulatory populations.
- Hospital Neurology Departments:Scaling adoption of ambulatory monitoring systems to reduce inpatient bed utilization and capture reimbursement under remote patient monitoring codes.
- WHO Universal Health Coverage Integration:Epilepsy inclusion in national health benefit packages expands reimbursable access pathways across lower-income health systems in Sub-Saharan Africa and South Asia.
Market Restraints
- Silver and Conductive Polymer Input Volatility:Electrode manufacturing costs fluctuate with precious metal markets, squeezing margins for disposable scalp sensor producers.
- EMA MDR Clinical Evidence Requirements:Extended post-market surveillance obligations and notified body capacity constraints lengthen EU certification timelines by 12-18 months for novel wearable form factors.
- Intracranial EEG Substitution by MEG:Magnetoencephalography non-invasive source localization is capturing pre-surgical evaluation volume in tertiary centers with existing magnetometer infrastructure.
Strategic Opportunities
- Home-Based Long-Term Monitoring Protocols:Wearable sensor miniaturization enables seizure surveillance outside institutional settings, opening reimbursement negotiations with US Medicare Advantage plans and German statutory health insurers.
- Cloud-Based Analytics Recurring Revenue Models:Vendors are repositioning hardware margins toward subscription telemetry interpretation services, capturing lifetime value through algorithm updates and clinical decision support.
- Japan's PMDA QMS Ordinance Harmonization:Streamlined quality management system recognition for ISO 13485-certified manufacturers reduces dual-audit burden and accelerates East Asian market entry.
Industry Challenges
- Electroencephalography Technologist Talent Scarcity:Specialized training programs for 10-20 system channel configuration and artifact recognition lag device deployment, creating interpretation bottlenecks in community hospital settings.
- Legacy EMR Integration Complexity:Proprietary data formats from established video EEG platforms resist seamless connectivity with Epic and Cerner architectures, forcing costly middleware development or manual transcription workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Epilepsy Monitoring Devices Market |
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,325.02 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video EEG Monitoring, Ambulatory EEG, Invasive Monitoring, Outpatient Monitoring, Intracranial EEG Technology: Wireless EEG, Digital EEG, Portable EEG, Wearable Sensors, Cloud-Based Analytics Application: Seizure Detection, Pre-Surgical Evaluation, Long-Term Monitoring, Sleep Disorder Analysis, Neurofeedback End User: Neurology Clinics, Specialized Diagnostic Centers, Research Laboratories, Home Care Providers |
| Companies Covered | Masimo Corporation, Medtronic, Natus Medical, Empatica, Boston Scientific Corporation, Compumedics, The Magstim Co. Ltd., BioSerenity, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Epilepsy Monitoring Devices Market Shifts & Advancements
Wearable sensor architectures and algorithmic seizure classification are compressing the boundary between institutional diagnostics and consumer-grade health monitoring, forcing incumbents to defend installed bases through software lock-in while enabling insurgent entry via direct-to-clinic distribution.
Artificial intelligence-driven automated spike and seizure detection is rendering obsolete manual electroencephalographer review for routine ambulatory monitoring in US sleep and epilepsy centers. Community neurology practices in Texas and Florida are adopting FDA-cleared algorithms for first-pass screening, reducing specialist interpretation burden while compressing report turnaround from 72 hours to 4 hours. This capability shift is enabling scalable remote monitoring services that bypass traditional hospital-based EEG laboratory infrastructure entirely.
EMA's Medical Device Regulation (MDR) framework is elevating clinical evidence standards for software-as-a-medical-device components, forcing wearable seizure detection vendors to generate prospective validation data in European epilepsy centers. The notified body capacity crunch is selectively advantaging manufacturers with existing Class III implantable neuromodulation portfolios who can leverage established quality management systems. German and French tertiary centers are prioritizing procurement of MDR-certified systems to preempt supply discontinuity risks.
Direct-to-clinic distribution via specialized neurology device sales representatives is displacing traditional hospital procurement consortium contracting for ambulatory EEG systems. Independent neurology practices in California and New York are purchasing wearable monitoring hardware through vendor financing programs rather than health system capital committees. This channel shift concentrates vendor relationship investment on clinical workflow integration rather than group purchasing organization rebate structures.
Global Epilepsy Monitoring Devices Market Segmentation
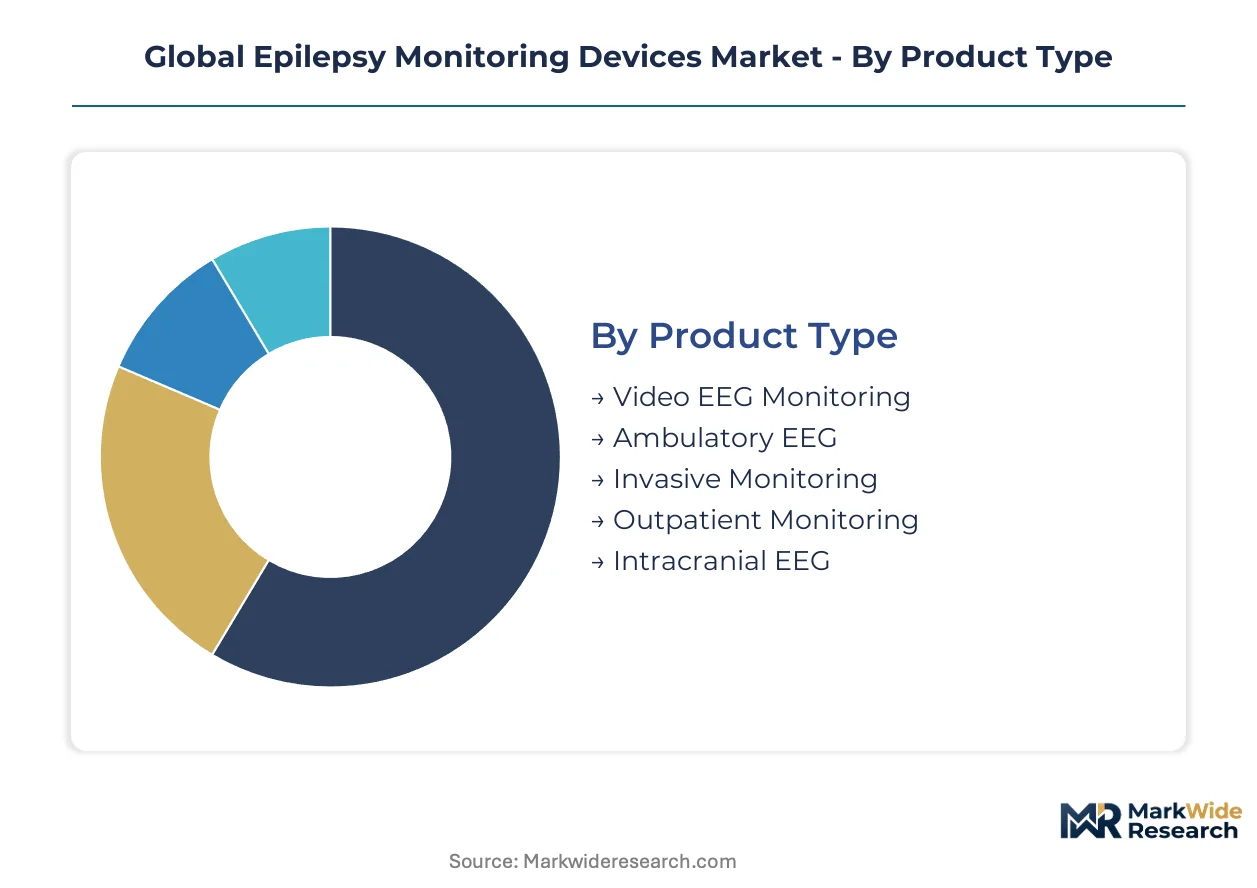
Epilepsy monitoring devices fragment across clinical workflows from invasive pre-surgical evaluation to ambulatory home surveillance. Segmentation strategy determines vendor positioning between capital-intensive hospital hardware and recurring-revenue wearable services.
Product Type:
Use-case spectrum spans acute diagnostic precision in tertiary centers to longitudinal seizure surveillance outside institutional walls.
- Video EEG Monitoring:Multi-channel scalp recording synchronized with video capture enables seizure semiology correlation for pre-surgical planning. Demand concentrates in US Level 3 and 4 epilepsy centers where 24-7 technologist staffing supports continuous inpatient admission protocols.
- Ambulatory EEG:Portable 24-72 hour recording systems with patient event logging support outpatient seizure characterization without hospitalization. German statutory health insurers have expanded ambulatory EEG reimbursement codes, accelerating clinic procurement across Bavaria and North Rhine-Westphalia.
- Invasive Monitoring:Subdural grid and depth electrode arrays provide high-resolution localization for resection planning in pharmacoresistant cases.
- Outpatient Monitoring:Same-day EEG services in dedicated neurology clinics capture routine diagnostic volume with compressed turnaround times.
- Intracranial EEG:Stereotactic depth electrodes target mesial temporal and insular foci inaccessible to scalp recording.
Established volume favors Video EEG Monitoring; emerging adoption favors Ambulatory EEG.
Technology:
Cost tier stratification separates high-channel institutional systems from single-lead consumer-form-factor sensors.
- Wireless EEG:Bluetooth and proprietary radio protocols eliminate tethering to bedside amplifiers, enabling patient mobility during long-term monitoring. Japanese tertiary centers in Tokyo and Osaka prioritize wireless systems for pediatric epilepsy units where movement artifact reduction improves data quality.
- Digital EEG:High-resolution analog-to-digital conversion with 24-bit sampling preserves signal fidelity for spike detection algorithms. US hospital networks standardize on digital platforms to support cloud archiving and multi-site neurologist interpretation.
- Portable EEG:Battery-powered compact amplifiers target emergency department and ambulance deployment for post-ictal assessment.
- Wearable Sensors:Accelerometer-integrated wrist and chest bands enable multi-day seizure surveillance outside clinical settings.
- Cloud-Based Analytics:Centralized algorithm processing shifts computational burden from bedside hardware to vendor-hosted infrastructure.
Hardware margins concentrate in Digital EEG; recurring revenue potential climbs fastest in Cloud-Based Analytics.
Application:
Customer workflow integration determines whether devices serve screening, surgical planning, or chronic disease management functions.
- Seizure Detection:Automated algorithmic classification of ictal and interictal discharges reduces electroencephalographer review burden. Texas and Florida community neurology practices adopt FDA-cleared detection software for first-pass ambulatory screening, compressing report turnaround from 72 hours to 4 hours.
- Pre-Surgical Evaluation:Multi-modal localization combining EEG, MRI, and PET guides resection margins in pharmacoresistant epilepsy. Demand clusters in US comprehensive epilepsy centers with established neurosurgical programs.
- Long-Term Monitoring:Extended recording protocols quantify seizure frequency for therapy adjustment and clinical trial endpoints.
- Sleep Disorder Analysis:Overnight EEG-polysomnography integration captures nocturnal seizures and differential diagnoses.
- Neurofeedback:Real-time EEG display enables patient-driven brain state modulation for adjunctive seizure management.
Clinical validation depth favors Pre-Surgical Evaluation; addressable population expansion favors Seizure Detection.
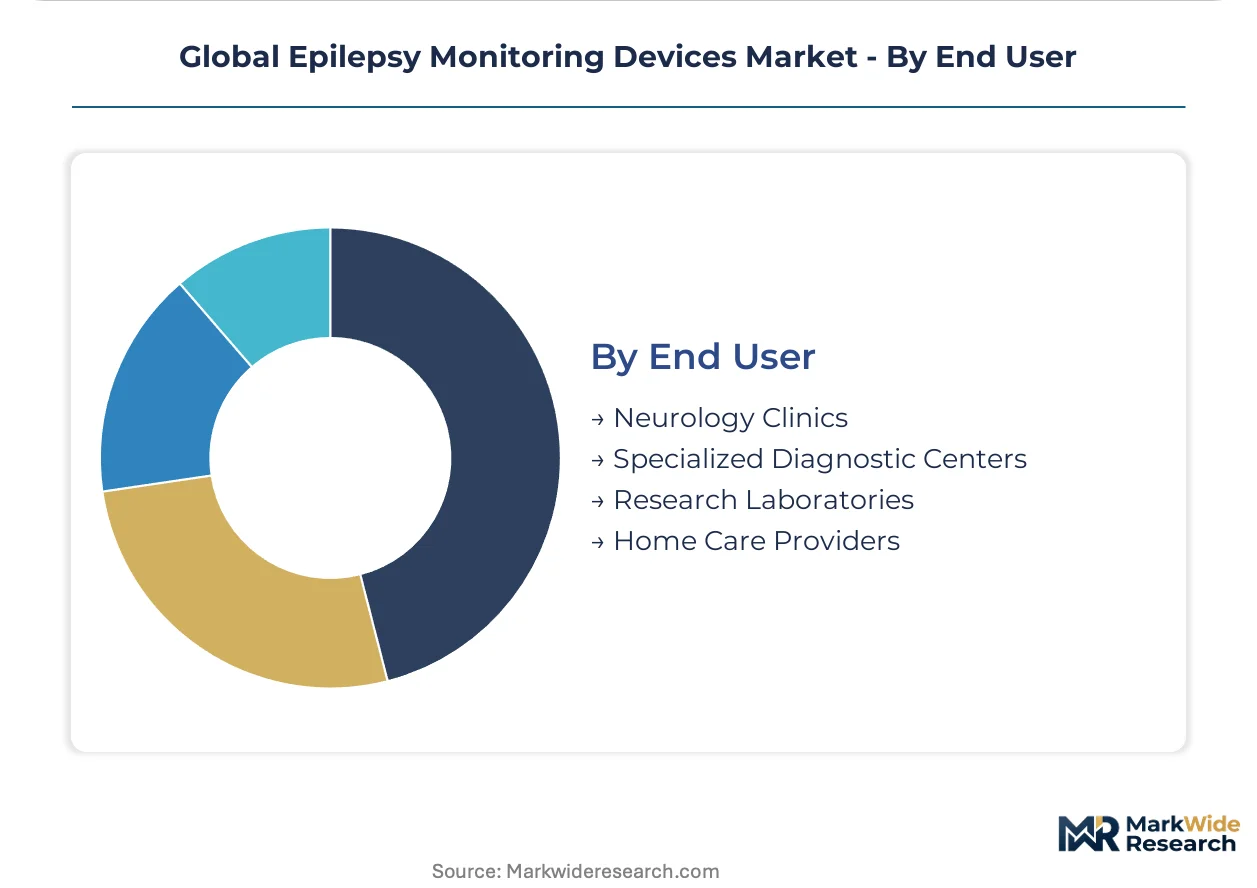
End User:
Procurement authority and reimbursement pathway shape vendor sales motion and pricing architecture.
- Neurology Clinics:Independent and hospital-affiliated outpatient practices drive ambulatory EEG volume through direct-to-clinic distribution channels. California and New York practices purchase wearable hardware through vendor financing rather than health system capital committees.
- Specialized Diagnostic Centers:Dedicated epilepsy monitoring units with 10-20 bed capacity handle pre-surgical evaluation referrals from regional networks.
- Research Laboratories:Academic medical centers generate prospective validation data for algorithm development and regulatory submissions.
- Home Care Providers:Durable medical equipment suppliers and remote patient monitoring platforms extend seizure surveillance to residential settings.
Procurement volume concentrates in Neurology Clinics; reimbursement innovation targets Home Care Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net trade flows in epilepsy monitoring hardware tilt toward deficit positions in markets lacking domestic electrode manufacturing, while surplus economies leverage precision electronics infrastructure to capture export share in wearable sensor assemblies.
United States
FDA breakthrough device designations for wearable seizure detection algorithms compress clearance timelines from 18 months to 6-8 months for pediatric-focused entrants. Remote patient monitoring reimbursement codes under CMS expand ambulatory EEG coverage in Medicare Advantage plans. Level 3 and 4 epilepsy centers in Houston, Cleveland, and New York anchor pre-surgical evaluation demand for video EEG systems.
Germany
Statutory health insurers expanded ambulatory EEG reimbursement codes in 2023, accelerating clinic procurement across Bavaria and North Rhine-Westphalia. EMA MDR certification timelines lengthen by 12-18 months for novel wearable form factors due to notified body capacity constraints. Tertiary centers in Berlin and Munich prioritize MDR-certified systems to preempt supply discontinuity risks.
Japan
PMDA QMS ordinance harmonization with ISO 13485 standards reduces dual-audit burden for foreign manufacturers seeking East Asian market entry. Wireless EEG systems dominate pediatric epilepsy units in Tokyo and Osaka where movement artifact reduction improves data quality. METI funding for digital health infrastructure accelerates cloud-based analytics adoption in university hospitals.
India
WHO universal health coverage integration expands reimbursable epilepsy care access in national health benefit packages. CDSCO medical device rules impose clinical trial requirements for software-as-medical-device components that delay wearable sensor registrations by 8-14 months. Specialized epilepsy centers in Mumbai, Delhi-NCR, and Bangalore concentrate pre-surgical evaluation capacity.
United Kingdom
NICE technology appraisal guidelines condition NHS reimbursement on demonstrated cost-effectiveness against standard video EEG monitoring. MHRA post-Brexit regulatory autonomy enables accelerated recognition of FDA-cleared algorithms through reliance pathways. Comprehensive epilepsy centers in London, Oxford, and Manchester handle tertiary referrals from regional networks lacking intracranial monitoring capability.
Global Epilepsy Monitoring Devices Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability clusters: implantable neuromodulation platforms, diagnostic hardware with backward integration into electrode manufacturing, and wearable sensor miniaturization specialists. Strategic archetypes include diversified medtech conglomerates defending installed bases through software lock-in, pure-play neurology device vendors capturing ambulatory volume via direct-to-clinic distribution, and digital health insurgents leveraging algorithmic differentiation to bypass traditional procurement channels. Dominant competitive moves center on subscription-based leasing reconfigurations that extend vendor lock-in periods, and cloud-based analytics repositioning that shifts hardware margins toward recurring telemetry interpretation services.
Within the diversified medtech tier, Medtronic anchors invasive monitoring portfolios through implantable neuromodulation infrastructure, while Nihon Kohden Corporation represents Japanese precision electronics capabilities in diagnostic hardware. Among pure-play neurology specialists, Natus Medical exemplifies backward integration strategies through captive electrode manufacturing and software calibration control, and Empatica occupies the wearable sensor miniaturization position targeting pediatric and ambulatory populations outside institutional settings.
| Leading Market Players |
|---|
| Masimo Corporation |
| Medtronic |
| Natus Medical |
| Empatica |
| Boston Scientific Corporation |
| Compumedics |
| The Magstim Co. Ltd. |
| BioSerenity |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Silver electrode manufacturing concentrates in Japanese and German precision electronics clusters, anchoring margin capture in scalp sensor production while wearable miniaturization shifts value toward algorithm developers and cloud analytics vendors.
Pricing Analysis
Hospital neurology departments anchor pricing structures around three-tier differentiation across premium FDA-breakthrough certified systems, standard CE-marked diagnostic hardware, and economy-grade ambulatory recorders. Price differentiation hinges on channel certification tier and bundled software calibration services. Cost compression in disposable electrode tiers intensifies because silver and conductive polymer input volatility squeezes producers. Community neurology practices in Texas and Florida exhibit highest price sensitivity, while US Level 4 epilepsy centers prioritize clinical validation depth over procurement cost.
Supply Chain Analysis
Export-control restrictions on high-resolution analog-to-digital converters and wireless telemetry chipsets limit component flows from US and Japanese semiconductor fabs to wearable sensor assemblers. Manufacturing concentrates in China for consumer-grade accelerometer integration, Germany for precision electrode fabrication, and Japan for 24-bit sampling hardware. Raw material dependencies span silver chloride coatings, medical-grade silicone substrates, and lithium-polymer cells. Single-source vulnerability in FDA-cleared algorithm training datasets creates supply risk. Distribution runs through specialized neurology device sales representatives and direct-to-clinic vendor financing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable seizure detection algorithms have crossed regulatory inflection points with FDA breakthrough designations, compressing commercialization timelines and opening reimbursement negotiations with Medicare Advantage plans.
For Market Incumbents: Insulate video EEG installed bases through software lock-in and backward integration into electrode manufacturing. Defend against MEG substitution in pre-surgical evaluation by embedding AI-driven automated spike detection. Prioritize EMA MDR certification investment to preempt supply discontinuity risks in German tertiary centers.
For New Entrants and Emerging Players: Build out cloud-based analytics recurring revenue models targeting independent neurology practices in California and New York. Home-based long-term monitoring protocols represent the most penetrable white space. Pursue direct-to-clinic distribution with vendor financing programs rather than health system capital committee channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wearable sensor miniaturization specialists lacking MDR certification pathways. Long-term viability over the next decade hinges on algorithmic differentiation and reimbursement strategy execution. Watch FDA breakthrough device designation velocity as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated clearance compresses time-to-market for pediatric-focused wearable entrants. |
| EMA MDR Certification Pathway | Notified body capacity constraints selectively advantage manufacturers with established QMS infrastructure. |
| Hospital System Partnership | Level 3 and 4 epilepsy centers anchor pre-surgical evaluation demand for video EEG systems. |
| Software Companion Development | Cloud-based analytics shifts hardware margins toward recurring telemetry interpretation services. |
| Reimbursement Strategy | Medicare Advantage remote patient monitoring codes expand ambulatory EEG coverage in the US. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR submissions, CMS reimbursement databases, and hospital procurement records. Interviews with epilepsy center directors, biomedical engineers, GPO contracts managers, and wearable sensor R&D heads were triangulated with bottom-up channel checks and top-down market sizing across product type, technology, application, and end-user segmentation dimensions.
Forecast inputs span ambulatory EEG reimbursement code expansion, wearable sensor miniaturization cost curves, and algorithm validation study completion rates across the analysis window. Segmentation modeling incorporates device class, channel configuration, certification tier, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and ambulatory adoption elasticity.
Stress conditions across silver price volatility, notified body capacity constraints, and MEG technology substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on FDA clearance timelines and statutory health insurer reimbursement decisions. Cross-checking against CMS Medicare Advantage enrollment trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
UAE Patient Monitoring Equipment Market
Patient Monitoring
Medical Telemetry Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
South America Respiratory Monitoring Market
Patient Monitoring
Multiparameter Patient Monitoring System Market
Patient Monitoring
Pain Monitoring Devices Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market