
 Superconducting Quantum Chip Market | 2026-2036
Superconducting Quantum Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Superconducting Quantum Chip Market Insights
Multi-source procurement of dilution refrigerators and niobium-based substrates is pivoting toward captive supply chains as foundry capacity tightens. IBM Corporation leverages its internal quantum foundry in New York to secure wafer supply for transmon devices. Google Quantum AI anchors its Sycamore roadmap through vertical control over cryogenic packaging and control electronics. Rigetti Computing specializes in quantum-classical hybrid architectures, differentiating its Quantum Cloud Services through rapid annealer deployment cycles.
Superconducting quantum chips are integrated circuits fabricated from thin-film aluminum or niobium on silicon substrates, operating at millikelvin temperatures in dilution refrigerators to maintain qubit coherence for gate-based quantum computation. Their primary purpose is executing quantum algorithms for cryptography, optimization, and molecular simulation with computational advantages over classical processors. Quantum processors command the dominant share of product type revenue, while control electronics represent the fastest-growing margin pool as cryogenic CMOS and room-temperature digital backends multiply per-qubit channel counts. Among end users, government research labs absorb the largest funding volumes, though financial services firms are emerging as high-margin early adopters for portfolio optimization and risk modeling.
The U.S. National Institute of Standards and Technology and the European Quantum Flagship program shape demand through funding allocation criteria that prioritize domestic supply chains and export-controlled fabrication tools. China's Ministry of Science and Technology channels state capital toward indigenous cryogenic foundry capacity, constraining Western equipment vendors' market access. Finland's VTT Technical Research Centre and IQM's Espoo facility illustrate how national research institutes and startups co-develop fabrication standards that influence procurement specifications across Northern Europe. Stakeholders must monitor how quantum computing export controls and cryogenic equipment licensing regimes restructure cross-border component flows.
Market Dynamics
Captive cryogenic foundry capacity is consolidating competitive advantage as dilution refrigerator lead times stretch beyond 18 months and niobium substrate supply tightens among specialty metallurgy suppliers.
Growth Catalysts
- NIST Quantum Initiative:United States federal procurement mandates prioritize domestic superconducting processor fabrication, channeling public R&D funding toward transmon qubit development at national laboratories.
- Transmon coherence extension:Advances in thin-film aluminum deposition and surface passivation protocols are pushing qubit relaxation times past 100 microseconds, enabling deeper quantum circuits.
- Financial services algorithm demand:Portfolio optimization workloads at major investment banks are creating pull-through for cloud-accessible superconducting quantum processing units.
Market Restraints
- Helium-3 supply concentration:Russian and Qatari isotope enrichment facilities control over 80 percent of global dilution refrigerator coolant supply, exposing foundry operations to geopolitical disruption.
- Cryogenic CMOS fabrication bottleneck:Only two European foundries maintain qualified processes for 4K-compatible control electronics, constraining per-qubit channel scaling.
- Superconducting qubit thermal sensitivity:Millikelvin operating requirements limit deployment flexibility and mandate permanent infrastructure investment at customer sites.
Strategic Opportunities
- Finnish quantum cluster expansion:VTT Technical Research Centre and IQM's Espoo facility are establishing open-access multi-project wafer runs for European startup ecosystem access to niobium-based fabrication.
- Hybrid quantum-classical integration:Convergence of superconducting processors with photonic interconnects is enabling modular quantum computing architectures that bypass monolithic chip scaling limits.
- China indigenous foundry buildout:Ministry of Science and Technology capital allocation is creating captive cryogenic equipment supply chains that Western vendors cannot access.
Industry Challenges
- Cryogenic engineering talent scarcity:Universities produce fewer than 200 qualified dilution refrigerator specialists annually worldwide, creating hiring bottlenecks at scaling foundries.
- Qubit calibration automation gaps:Manual tuning protocols for transmon frequency alignment consume 40-60 percent of system uptime, compressing effective computational throughput.
- Export control compliance complexity:Dual-use technology classifications under Wassenaar Arrangement and national export regimes are fragmenting cross-border component flows and delaying procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superconducting Quantum Chip Market |
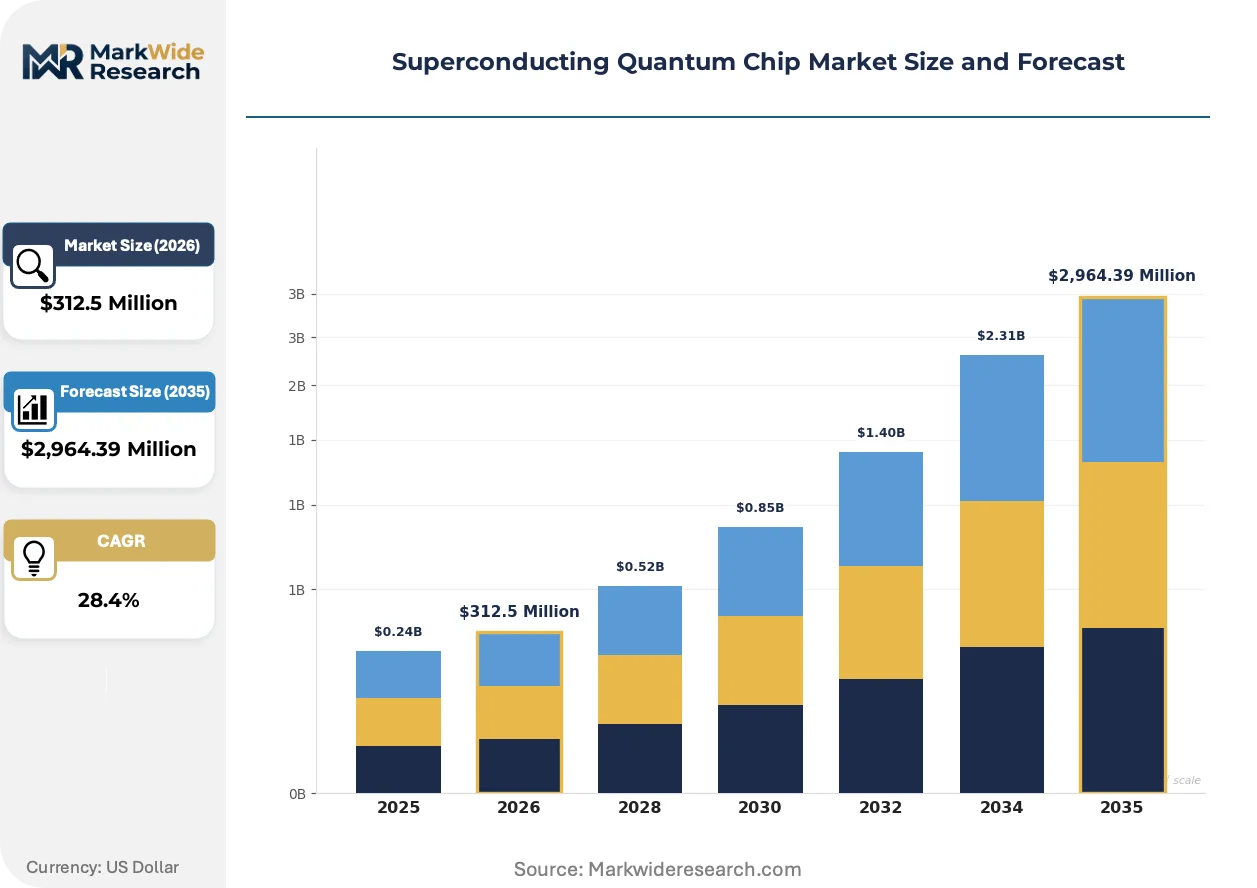
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $2,964.39 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quantum Processors, Quantum Annealers, Control Electronics, Coherent Feedback Systems End User: Aerospace, Telecommunications, Government Research Labs, Financial Services Technology: Fluxonium, Transmon, Qubit Coupling, Cryogenic Circuits Application: Cryptography, Drug Discovery, Material Science, Artificial Intelligence |
| Companies Covered | IBM Corporation, Google Quantum AI, Intel Corporation, Rigetti Computing, IonQ, Toshiba Corporation, SEEQQC, IQM, QuantWare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superconducting Quantum Chip Market Trends and Innovations
Superconducting quantum chip development is pivoting toward vertical control of cryogenic packaging and control electronics as external supply chains prove insufficient for roadmap velocity.
Fluxonium qubit architectures are consolidating technical attention as an alternative to transmon designs for certain algorithm classes. Google Quantum AI and academic consortia are advancing fluxonium coherence properties toward practical two-qubit gate fidelities. This technology consolidation is compressing the evaluation window for alternative superconducting modalities before foundry process commitments lock in.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing dilution refrigerator manufacturers toward closed-cycle gas recovery systems and alternative refrigerant blends. Industrial consequence includes 15-25 percent capex inflation for new cryogenic infrastructure. European national quantum programs are responding with dedicated capital grants for equipment refurbishment rather than new procurement.
Cloud-based quantum processing access is displacing on-premise system acquisition among mid-scale research users. Amazon Braket and IBM Quantum Network are aggregating demand from university physics departments and startup algorithm developers. This channel shift concentrates most visible in the United States and United Kingdom, where research funding agencies now prioritize cloud credits over capital equipment allocations in grant programs.
Superconducting Quantum Chip Market Segmentation
Superconducting quantum chip procurement decisions pivot on thermal performance specifications, algorithm compatibility, and foundry qualification status. Buyers prioritize segments offering verified coherence times and domestic supply chain provenance under tightening export controls.
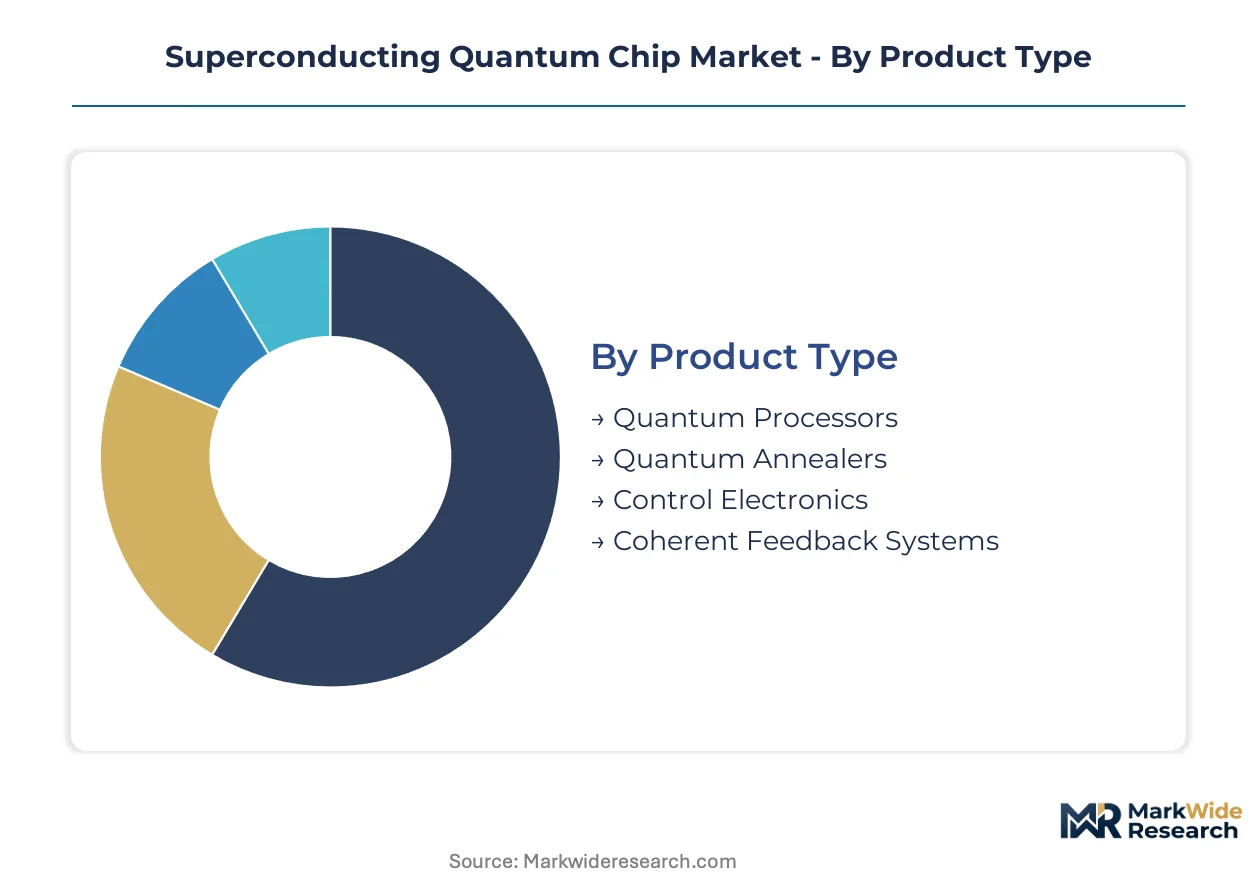
Product Type:
Capital allocation intensity and per-unit margin profiles determine purchasing committee composition across product categories.
- Quantum Processors:Gate-based integrated circuits fabricated from thin-film aluminum or niobium on silicon substrates, executing quantum algorithms at millikelvin temperatures. Government research labs in the United States absorb the dominant procurement volumes, driven by NIST federal mandates prioritizing domestic fabrication for cryptography workloads.
- Control Electronics:Cryogenic CMOS and room-temperature digital backends managing per-qubit channel counts and pulse sequencing. Financial services firms in London and New York are emerging as high-margin early adopters, pulled by portfolio optimization algorithm demand and cloud-accessible processing unit procurement.
- Quantum Annealers:Specialized architectures for combinatorial optimization using superconducting flux qubits. Rigetti Computing deploys rapid deployment cycles through Quantum Cloud Services.
- Coherent Feedback Systems:Real-time error correction modules integrating measurement and feedforward control. Academic consortia in Finland and the Netherlands pilot open-access multi-project wafer integration.
Quantum Processors leads on scale; Control Electronics leads on momentum.
End User:
Funding mechanism structure—direct procurement versus research grants versus cloud credits—shapes vendor engagement models.
- Government Research Labs:National quantum initiatives channel public funding into domestic foundries and testing facilities. The U.S. National Institute of Standards and Technology and the European Quantum Flagship program prioritize domestic supply chains and export-controlled fabrication tools in funding allocation criteria.
- Financial Services:Investment banks and hedge funds deploy quantum processing for risk modeling and derivative pricing. Portfolio optimization workloads at major institutions create pull-through for cloud-accessible superconducting quantum processing units.
- Aerospace:Satellite communication and navigation system manufacturers evaluate quantum cryptography for secure link protocols. Defense contractors in the United States and United Kingdom pilot transmon-based encryption key distribution.
- Telecommunications:Network operators explore quantum-safe infrastructure migration paths. Chinese state-owned carriers integrate indigenous cryogenic foundry output under Ministry of Science and Technology capital allocation.
Government Research Labs dominates current funding absorption; Financial Services climbs fastest on margin expansion.
Technology:
Foundry process commitment timelines and coherence property benchmarks determine technology selection lock-in risk.
- Transmon:Capacitively shunted charge qubits with extended relaxation times through thin-film aluminum deposition and surface passivation protocols. Advances are pushing qubit relaxation times past 100 microseconds, enabling deeper quantum circuits at Google Quantum AI and IBM Corporation facilities.
- Fluxonium:Heavy superconducting circuits with intrinsic protection against charge noise, consolidating technical attention as an alternative for certain algorithm classes. Google Quantum AI and academic consortia are advancing coherence properties toward practical two-qubit gate fidelities.
- Qubit Coupling:Resonator-mediated and direct capacitive coupling architectures enabling multi-qubit gates. IQM's Espoo facility and VTT Technical Research Centre co-develop fabrication standards influencing Northern European procurement specifications.
- Cryogenic Circuits:Superconducting interconnect and packaging solutions maintaining signal integrity at millikelvin temperatures. Only two European foundries maintain qualified processes for 4K-compatible control electronics, constraining supply.
Transmon anchors installed base; Fluxonium gains share fastest on algorithmic versatility.
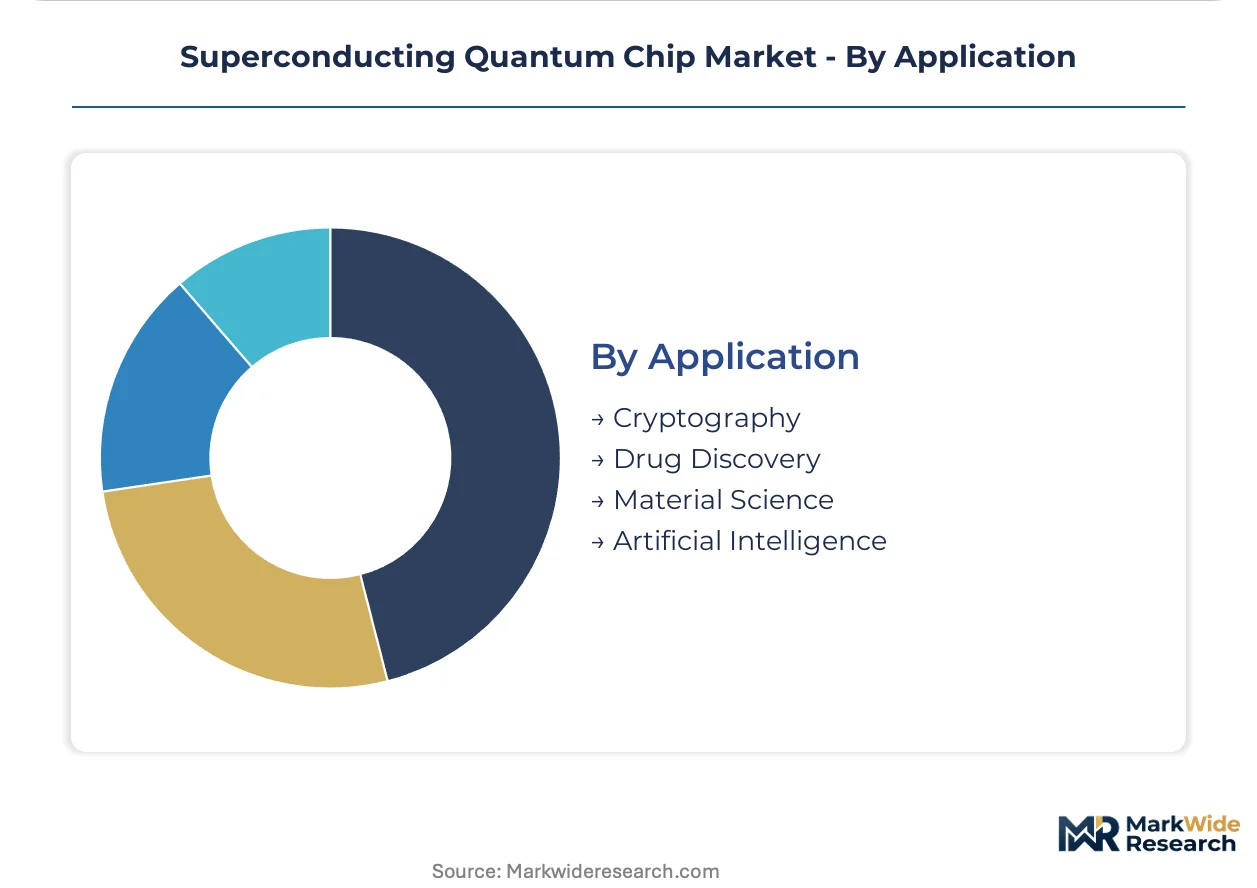
Application:
Computational advantage verification requirements and classical benchmark comparability shape adoption sequencing.
- Cryptography:Quantum key distribution and post-quantum cryptographic protocol development. United States federal procurement mandates prioritize domestic superconducting processor fabrication for national security workloads.
- Artificial Intelligence:Quantum machine learning kernels for pattern recognition and generative modeling. Cloud-based access through Amazon Braket and IBM Quantum Network aggregates university and startup demand.
- Drug Discovery:Molecular simulation and protein folding energy landscape mapping. Pharmaceutical companies in Switzerland and Germany evaluate hybrid quantum-classical integration for binding affinity calculations.
- Material Science:Quantum chemistry simulations for catalyst and battery electrolyte design. National laboratories in China channel state capital toward indigenous cryogenic foundry capacity for materials research.
Cryptography commands current funding concentration; Artificial Intelligence shows steepest expansion trajectory on cloud accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Espoo quantum cluster in Finland anchors superconducting chip fabrication capacity outside traditional semiconductor hubs, channeling public research funding into niobium-based foundry infrastructure that supplies Northern European academic and startup demand.
United States
NIST federal procurement mandates prioritize domestic transmon processor fabrication for cryptography workloads at national laboratories. The CHIPS and Science Act directs public capital toward cryogenic foundry capacity expansion. IBM Corporation's quantum foundry in New York secures captive wafer supply for government contract fulfillment.
China
Ministry of Science and Technology capital allocation builds indigenous dilution refrigerator and cryogenic CMOS supply chains for materials science simulation. State-owned telecommunications carriers integrate domestic foundry output under quantum-safe infrastructure mandates. Beijing and Hefei research institutes pilot multi-qubit systems for satellite cryptography applications.
Finland
VTT Technical Research Centre and IQM's Espoo facility co-develop fabrication standards influencing procurement specifications across Northern Europe. EU Quantum Flagship program funding prioritizes open-access multi-project wafer runs for regional startup ecosystem access. The Finnish quantum cluster exports cryogenic packaging expertise to German and Dutch research consortia.
Germany
EU F-Gas Regulation restrictions force dilution refrigerator manufacturers toward closed-cycle gas recovery systems, inflating cryogenic infrastructure capex. The country's central research funding agency allocates capital grants for equipment refurbishment rather than new procurement. Munich and Stuttgart host hybrid quantum-classical integration pilots linking superconducting processors with photonic interconnects.
United Kingdom
Research funding agencies prioritize cloud credits over capital equipment allocations in grant programs, concentrating demand through Amazon Braket and IBM Quantum Network access. The national quantum computing center partners with Rigetti Computing for quantum annealer deployment. London financial services firms pilot portfolio optimization workloads on cloud-accessible superconducting processing units.
Superconducting Quantum Chip Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid quantum-classical integration architectures. The vendor base separates into three functional tiers: captive foundry operators with vertical control over cryogenic packaging, cloud platform aggregators monetizing access rather than hardware ownership, and specialty component suppliers for niobium substrates and dilution refrigerator subsystems. Dominant competitive moves include strategic partnerships between chip fabricators and cloud service providers, plus geographic expansion through national quantum initiative funding capture.
Among captive foundry operators, IBM Corporation and Google Quantum AI exemplify the vertical-integration archetype, maintaining in-house control over transmon device fabrication and cryogenic system integration. Rigetti Computing occupies a distinct position within the hybrid architecture specialist tier, differentiating through quantum-classical deployment cycles. IQM represents the European national-champion model, anchoring Finnish supply chain development through VTT Technical Research Centre collaboration.
| Leading Market Players |
|---|
| IBM Corporation |
| Google Quantum AI |
| Intel Corporation |
| Rigetti Computing |
| IonQ |
| Toshiba Corporation |
| SEEQQC |
| IQM |
| QuantWare |
| Others |
Pricing and Supply Chain Analysis
Helium-3 isotope enrichment costs cascade through dilution refrigerator manufacturing into quantum processor pricing tiers, with Russian and Qatari supply concentration amplifying volatility for foundries procuring cryogenic infrastructure. Government research labs absorb premium pricing for domestic fabrication compliance, while cloud-accessible quantum processing units compete on subscription economics.
Pricing Analysis
Input-cost pass-through from niobium substrate and cryogenic CMOS shortages drives pricing stratification across premium, standard, and economy tiers. Premium tiers command certification under NIST quantum initiative mandates and verified transmon coherence benchmarks; standard tiers serve academic cloud credit programs with relaxed performance specifications. Price erosion runs through the economy tier as Chinese indigenous foundry buildout expands regional supply. Financial services firms exhibit lowest price sensitivity, prioritizing algorithmic advantage over per-qubit economics.
Supply Chain Analysis
Photoresist and specialty metallurgy supply rests on Japanese and German chemical producers, constraining niobium thin-film deposition throughput for transmon device fabrication. Raw material dependencies center on helium-3 coolant, high-purity aluminum sputtering targets, and 4K-compatible CMOS wafers. Single-source vulnerability concentrates in European cryogenic foundry capacity for control electronics. Distribution runs through captive foundry direct sales for government contracts and cloud platform aggregators for research users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
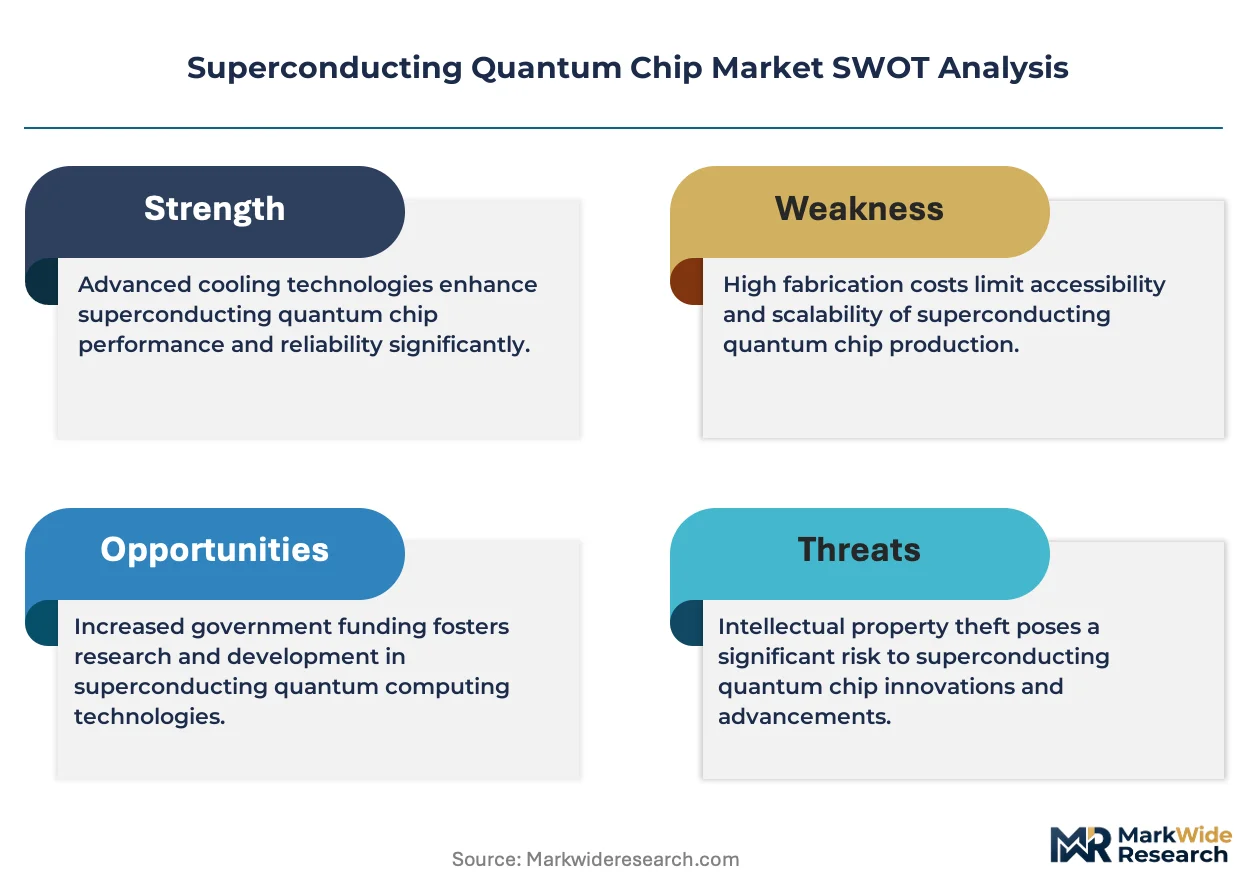
Margin expansion in superconducting quantum chips hinges on cryogenic CMOS cost-down curves and premium-tier demand from financial services algorithm deployment, offsetting helium-3 supply volatility.
For Market Incumbents: Extend coherence time advantages through surface passivation R&D investment, locking in government procurement preference. Secure captive niobium substrate supply through backward integration into specialty metallurgy partnerships. Defend against fluxonium architecture substitution by accelerating transmon gate fidelity roadmaps.
For New Entrants and Emerging Players: Launch via open-access multi-project wafer services targeting European startup ecosystem demand underserved by IBM and Google captive foundries. Penetrate hybrid quantum-classical integration segments where photonic interconnect convergence creates architectural white space. Position against cryogenic engineering talent scarcity through automated qubit calibration software.
For Investors and Strategic Acquirers: Consolidation pressure builds where cryogenic foundry capacity scarcity meets national quantum initiative funding concentration. Five-to-ten year viability favors vertically integrated players with dilution refrigerator supply chain control. Target acquisition archetype: specialty component suppliers with helium-3 recycling technology or cryogenic CMOS design capability. Watch export control expansion under Wassenaar Arrangement as inflection signal for cross-border deal flow restriction.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Foundry Capacity Expansion | NIST procurement mandates prioritize domestic fabrication for national laboratory cryptography workloads. |
| Hybrid Quantum-Classical Integration | Photonic interconnect convergence enables modular architectures bypassing monolithic chip scaling limits. |
| Cloud Platform Partnership | Amazon Braket and IBM Quantum Network aggregate mid-scale research demand displacing on-premise acquisition. |
| Fluxonium Architecture Development | Google Quantum AI advances alternative qubit designs threatening transmon installed base dominance. |
| Helium-3 Recycling Technology | EU F-Gas Regulation restrictions force closed-cycle gas recovery systems inflating cryogenic infrastructure capex. |
Research Methodology
Coverage spans the United States, China, Finland, Germany, and the United Kingdom, with primary inputs from each regional quantum initiative administration. Foundry operations directors, dilution refrigerator procurement leads at national laboratories, cryogenic CMOS design engineers, cloud platform product managers, and financial services quantitative research heads contributed structured interviews. Secondary validation drew from NIST funding allocation disclosures, EU Quantum Flagship program documentation, Chinese Ministry of Science and Technology capital allocation announcements, SEC filings from listed quantum computing vendors, and cryogenic equipment trade flow data. Bottom-up quantum processor shipment estimates triangulated against top-down national quantum program budget allocations.
Rate-of-change decomposition across the projection horizon segmented volume and value by product type, end user, technology, and application dimensions. Transmon qubit coherence time trajectories, dilution refrigerator lead time dynamics, and cloud credit allocation patterns informed analytical framework inputs. CAGRs derived from fitted adoption curves calibrated to government procurement cycle timing and financial services pilot-to-production transition rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control escalation or helium-3 supply disruption scenarios. Forecasts reflect assumptions regarding national quantum initiative funding continuity and cryogenic engineering talent pipeline expansion. Specific risk factors include Wassenaar Arrangement dual-use technology reclassification and EU F-Gas Regulation enforcement intensity. A small set of named triggers—export control expansion, helium-3 supply interruption, fluxonium gate fidelity breakthrough—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Consumer Electronics Chip Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
VR Gaming Hardware Chipsets Market
Chipset and Processors
Optical Microcontrollers Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Automotive Smart Chip Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Self-Learning Neuromorphic Chip Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Global Wireless Chipsets Market
Chipset and Processors
Application Processor Market