
 Oilfield Market | 2026-2036
Oilfield Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Market Outlook
Integrated service bundling is hardening across drilling and completion packages, compressing vendor lists for production companies. Schlumberger Limited leverages its full-cycle portfolio to anchor long-term contracts in complex reservoirs. Halliburton Company competes through specialized hydraulic fracturing capabilities in North American shale basins. Baker Hughes Company differentiates via digital twins and predictive maintenance platforms for offshore assets.
An oilfield encompasses the surface and subsurface infrastructure, drilling apparatus, wellbore completions, and production systems engineered to extract, process, and transport hydrocarbons from geological formations, typically operating at pressures from 2,000 to 15,000 psi and temperatures exceeding 150°C depending on reservoir depth. Drilling Services commands the largest revenue pool among service types due to capital intensity and rig day-rate structures, while Enhanced Oil Recovery represents the fastest-expanding technology segment as mature basins require tertiary extraction methods to sustain output. Production Companies as an end-user category drive the bulk of procurement volume, though Service Providers are capturing margin through integrated project management contracts that span exploration through field development.
The US EPA enforces methane performance standards that compel leak detection and repair investments across upstream operations, while BIS certification requirements in India constrain equipment imports and shape local sourcing strategies. OSHA workplace safety mandates and API technical specifications further structure operational protocols for drilling contractors and energy corporations operating in regulated jurisdictions. Stakeholders must weigh regulatory compliance costs against reservoir economics when selecting between conventional and enhanced recovery pathways.
Market Dynamics
Integrated service bundling across drilling and completion packages is compressing vendor lists and locking in long-term contracts for full-cycle providers. This structural consolidation is reshaping competitive positioning in complex reservoir development.
Growth Catalysts
- Deepwater exploration off Brazil:Production companies are deploying capital toward subsea tiebacks and floating production systems in the Santos and Campos basins. Pre-salt formations are attracting integrated project awards.
- US EPA methane performance standards:Leak detection and repair mandates are accelerating equipment replacement cycles across upstream operations. Compliance spending is creating demand for next-generation monitoring systems.
- Enhanced Oil Recovery adoption:CO2 injection and chemical flooding are expanding in mature Permian and North Sea fields. Tertiary extraction methods are sustaining output from depleted reservoirs.
Market Restraints
- Specialized rig and equipment supply concentration:Fabrication capacity for high-specification offshore rigs clusters in South Korean and Singaporean yards. Lead times for critical components now extend 18-24 months.
- Capital intensity of deepwater development:Subsea infrastructure and floating platform costs require multi-billion-dollar commitments before first production. Project sanctioning delays are common when oil price volatility exceeds threshold levels.
- Substitution by renewables and electrification:Utility-scale solar and offshore wind are capturing utility procurement budgets in OECD markets. Long-term oil demand uncertainty is compressing exploration budgets.
Strategic Opportunities
- Saudi Arabia offshore field development:The kingdom's Marjan and Zuluf expansion programs are creating demand for integrated drilling and production packages. Local content requirements are opening partnership pathways for international service providers.
- Digital twin convergence with predictive maintenance:Real-time reservoir simulation combined with equipment health monitoring is reducing unplanned downtime. Offshore operators are piloting autonomous intervention systems.
- India BIS certification tailwinds:Domestic manufacturing incentives and import constraints are reshaping equipment sourcing strategies. Joint ventures with Indian fabricators are securing market access.
Industry Challenges
- Experienced petroleum engineer scarcity:Demographic retirements and university enrollment declines are constraining technical staffing for complex reservoir characterization. Competition for subsurface expertise is intensifying.
- Legacy SCADA integration complexity:Brownfield digitization requires retrofitting 1990s-era control systems with modern IoT architectures. Cybersecurity certification timelines are extending project schedules.
- API specification compliance costs:Updated wellhead and Christmas tree standards are forcing recertification of existing inventory. Testing backlog at accredited facilities is delaying equipment deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Market |
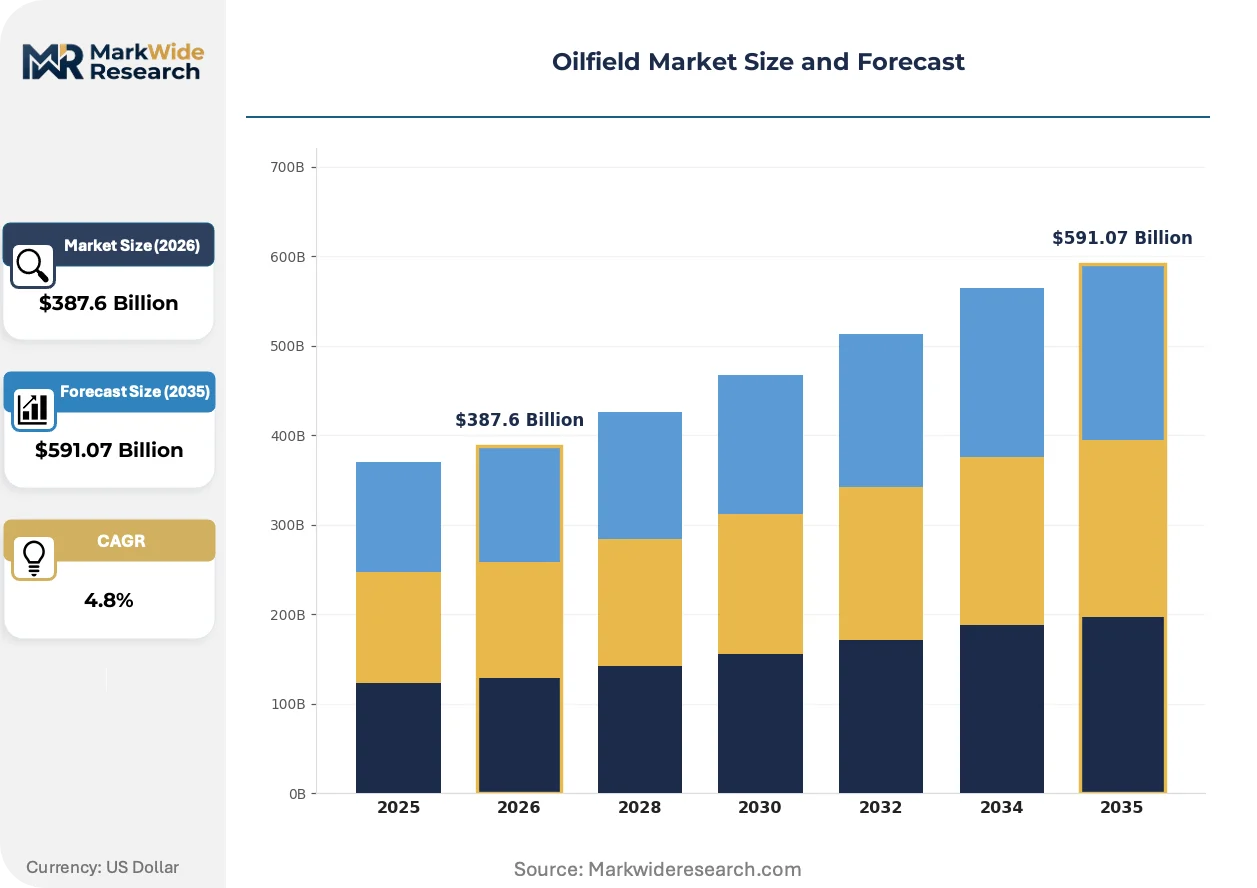
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling Services, Maintenance Services, Well Completion, Exploration Services Technology: Offshore Technology, Onshore Technology, Hydraulic Fracturing, Enhanced Oil Recovery End User: Exploration Companies, Production Companies, Service Providers, Energy Corporations Application: Upstream Exploration, Production Operations, Field Development, Reservoir Management |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International plc, TechnipFMC plc, National Oilwell Varco, Inc., Saipem S.p.A., ChampionX Corporation, SLB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Market Strategic Shifts
Automation and data integration are converging to reshape how hydrocarbons are extracted, monitored, and optimized across the well lifecycle. Three developments are particularly consequential for competitive positioning.
Digital twin technology is unifying subsurface modeling with surface facility operations in real-time simulation environments. Offshore operators in the North Sea and Gulf of Mexico are deploying these systems to optimize artificial lift schedules and predict equipment failures before they occur. This convergence is compressing the traditional separation between reservoir engineering and production operations.
The US EPA's methane performance standards are compelling systematic leak detection and repair programs across upstream assets. Operators must deploy optical gas imaging and continuous monitoring sensors to identify fugitive emissions at compressor stations and well pads. Shale producers in the Permian and Bakken are reconfiguring facility designs to minimize pneumatic device counts and eliminate routine flaring.
Integrated project management contracts are displacing discrete service procurement in complex reservoir developments. National oil companies in Saudi Arabia and Brazil are bundling exploration, drilling, and production responsibilities under single-source agreements. This consolidation is visible in recent pre-salt and offshore megaproject awards where full-cycle accountability is prioritized over unit-rate competition.
Oilfield Market Segmentation
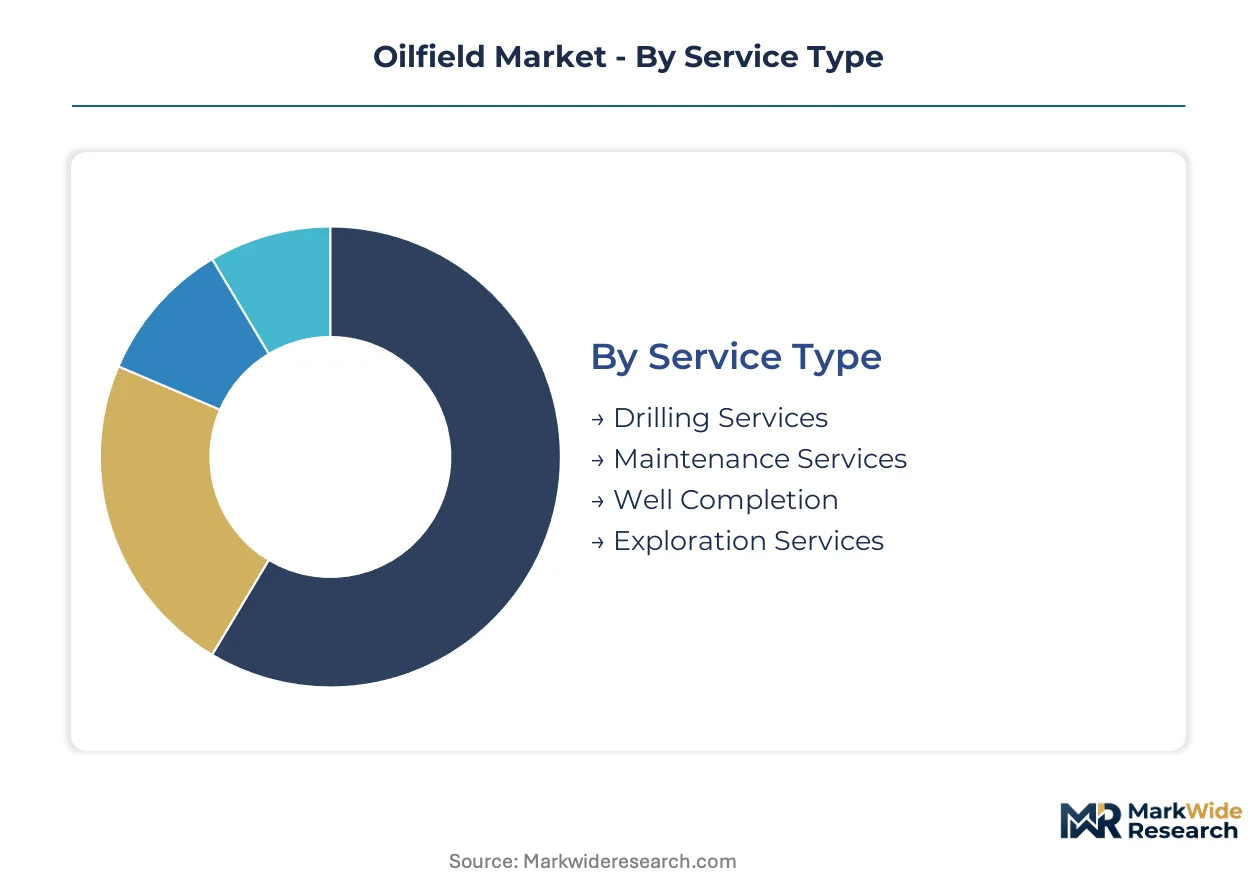
Segmentation in the oilfield market reflects divergent capital deployment strategies across reservoir types, regulatory environments, and operational maturity. Procurement patterns differ sharply between offshore megaprojects requiring integrated service bundles and shale basins favoring modular, price-competitive drilling packages.
Service Type:
Technology intensity and asset specificity define competitive positioning across service categories.
- Drilling Services:Capital-intensive rig operations and day-rate contracting structures dominate revenue concentration. Demand clusters in Saudi Arabia's offshore expansions and Brazil's pre-salt developments where extended-reach drilling requires high-specification equipment.
- Well Completion:Multi-stage hydraulic fracturing and intelligent completion systems characterize this segment. North American shale operators in the Permian and Bakken drive procurement volume for plug-and-perf and sliding-sleeve technologies.
- Maintenance Services:Predictive maintenance platforms and workover rig deployments sustain mature field output.
- Exploration Services:Seismic acquisition and subsurface characterization support frontier basin evaluation.
Drilling Services leads on scale; Well Completion leads on momentum.
Technology:
Cost tier stratification separates frontier deepwater investments from mature basin optimization plays.
- Offshore Technology:Subsea production systems, floating platforms, and tieback infrastructure command premium engineering margins. Brazil's Santos Basin and Saudi Arabia's Marjan field anchor deployment concentration for subsea trees and riser systems.
- Enhanced Oil Recovery:CO2 injection, chemical flooding, and thermal methods extend productive life of depleted reservoirs. The Permian Basin and North Sea mature fields are expanding tertiary recovery adoption as primary production declines.
- Onshore Technology:Conventional land rigs and artificial lift systems serve established production bases.
- Hydraulic Fracturing:Pressure pumping fleets and proppant logistics enable unconventional resource extraction.
Offshore Technology commands the highest capital commitment per barrel; Enhanced Oil Recovery is climbing the fastest as basin maturity advances.
End User:
Procurement centralization versus fragmentation shapes vendor relationship structures.
- Production Companies:Integrated operators and national oil companies drive bulk procurement volume through multi-year framework agreements. Saudi Aramco and Petrobras are consolidating vendor lists for full-cycle project accountability.
- Service Providers:Drilling contractors and integrated service firms capture margin through project management contracts spanning exploration through production. Schlumberger and Halliburton are anchoring long-term relationships in complex reservoir developments.
- Exploration Companies:Independent operators and junior E&Ps focus on frontier acreage evaluation.
- Energy Corporations:Diversified utilities and conglomerates with upstream portfolios.
Production Companies lead on scale; Service Providers lead on margin capture through integrated contracting.
Application:
Maturity stage determines technology selection and service bundling intensity.
- Upstream Exploration:Seismic imaging, wildcat drilling, and appraisal programs target new reserve additions. Brazil's pre-salt licensing rounds and Guyana-Suriname basin activity concentrate capital deployment.
- Production Operations:Artificial lift optimization, facility maintenance, and throughput maximization sustain cash flow from producing assets. US shale operators are automating well pad operations to reduce lifting costs.
- Field Development:Greenfield infrastructure construction and brownfield expansion programs.
- Reservoir Management:Real-time monitoring, simulation updating, and recovery strategy adjustment.
Production Operations leads on scale; Upstream Exploration leads on capital intensity per project.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern oilfield services industry traces its commercial origins to early twentieth-century Texas and Oklahoma, where rotary drilling technology and well logging first achieved industrial scale. Today's geographic footprint reflects both this heritage and subsequent shifts toward frontier basins and national oil company dominance.
United States
Permian Basin operators drive demand for hydraulic fracturing fleets and horizontal drilling packages. The EPA enforces methane performance standards that compel leak detection investments across upstream assets. Houston anchors the global headquarters concentration for integrated service providers and equipment fabricators.
Saudi Arabia
Marjan and Zuluf offshore expansion programs generate procurement volume for subsea production systems and extended-reach drilling. Local content requirements under Vision 2030 reshape partnership structures for international vendors. Dhahran's industrial cluster hosts the kingdom's primary petroleum engineering and equipment manufacturing capabilities.
Brazil
Pre-salt formations in the Santos and Campos basins attract capital toward floating production systems and subsea tiebacks. ANP licensing rounds and local content mandates structure contractor selection for integrated project awards. Rio de Janeiro concentrates engineering expertise and offshore vessel support infrastructure.
China
Shale gas development in Sichuan and tight oil production in Xinjiang expand demand for pressure pumping and artificial lift technologies. MIIT and NMPA standards govern equipment certification and import substitution programs. Beijing-Tianjin-Hebei corridor houses state-owned oilfield service enterprises and domestic rig manufacturing.
Norway
North Sea mature field rejuvenation and Arctic frontier exploration sustain demand for enhanced oil recovery and harsh-environment drilling packages. Petroleum Safety Authority regulations and CO2 storage mandates shape project economics and technology selection. Stavanger's subsea engineering cluster leads offshore technology development and supplier concentration.
Oilfield Market Competitive Environment
The competitive structure tilts toward integrated full-cycle providers capable of anchoring multi-year framework agreements. National oil companies in Saudi Arabia and Brazil have compressed vendor lists, favoring contractors with drilling-through-production accountability. Two archetypes dominate: diversified technology integrators and specialized basin-focused operators. Consolidation through asset acquisitions and strategic alliances for local content compliance represent the primary competitive moves reshaping market share distribution.
Among North American-dominant service enterprises, Schlumberger Limited and Halliburton Company exemplify the integrated archetype, anchoring long-term positions through full-cycle portfolio breadth. Baker Hughes Company occupies a differentiated tier through digital infrastructure and predictive maintenance platforms. These three entities represent the structural concentration visible in complex reservoir developments and integrated project awards.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| TechnipFMC plc |
| National Oilwell Varco, Inc. |
| Saipem S.p.A. |
| ChampionX Corporation |
| SLB |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed national oil companies in Saudi Arabia and Brazil anchor procurement volumes through multi-year framework agreements, compressing vendor lists and hardening price discipline for drilling and completion packages. Their concentration of capital deployment toward pre-salt and offshore megaprojects feeds directly into supply chain configuration, with fabrication capacity clustering in South Korean and Singaporean yards serving these state-led buyers.
Pricing Analysis
Day-rate contracting for high-specification offshore rigs structures the dominant pricing model, with premiums attaching to extended-reach and harsh-environment capabilities. Price differentiation separates premium-tier subsea systems from standard land rigs and economy-tier workover equipment, with certification to API specifications and local content compliance driving tier placement. Cost compression in North American shale basins is intensifying because operator consolidation and fleet rationalization are concentrating buying power among fewer production companies. Independent operators in the Permian and Bakken exhibit the highest price sensitivity, while national oil companies in Saudi Arabia prioritize full-cycle accountability over unit-rate competition.
Supply Chain Analysis
Freight costs for oversized subsea components and floating production system modules constrain sourcing flexibility, with heavy-lift vessel availability dictating project scheduling. Fabrication capacity concentrates in South Korea, Singapore, and China, where specialized yards hold order backlogs for high-specification offshore rigs. Raw material dependencies span high-grade steel alloys, subsea wellhead forgings, and advanced composite riser materials. Single-source vulnerability runs through South Korean yard concentration for critical floating platform hulls. Distribution runs through integrated project management contracts that bundle exploration through production responsibilities under single-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oilfield market reads as a late-cycle quality story, with capital rotating toward enhanced recovery and digital infrastructure as conventional exploration budgets compress. Demand is shifting toward premium specifications for methane-compliant equipment and predictive maintenance platforms.
For Market Incumbents: Deploy digital twin integration as the primary lever to anchor long-term contracts in complex reservoir developments. Consolidate vendor relationships through backward integration into subsea component manufacturing to defend margin position against specialized rig supply concentration. Expand certification capacity for EPA methane performance standards to capture compliance-driven replacement cycles across upstream operations.
For New Entrants and Emerging Players: Capture white-space opportunity in India BIS-certified equipment manufacturing through joint ventures with domestic fabricators. Target predictive maintenance software for mature North Sea fields where brownfield digitization lags reservoir complexity. Position through outcome-based contracting models that align vendor compensation with production uptime rather than day-rate structures.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap specialists with stranded conventional rig assets and limited digital capabilities. The five-to-ten year viability window favors service providers with full-cycle portfolios and established relationships with national oil companies. Watch for inflection signals in Saudi Aramco and Petrobras vendor list consolidation announcements as indicators of contract flow concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Bundling | Schlumberger and Halliburton anchor multi-year framework agreements spanning drilling through production. |
| Digital Twin Deployment | Baker Hughes differentiates through real-time reservoir simulation combined with predictive maintenance platforms. |
| Local Content Partnership | International vendors joint-venture with Indian fabricators to secure BIS certification and market access. |
| Methane Compliance Investment | Equipment manufacturers recertify inventory to EPA performance standards, accelerating replacement demand. |
| Enhanced Recovery Expansion | CO2 injection and chemical flooding adoption extends productive life of Permian and North Sea mature fields. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drilling contractors, production company procurement officers, subsea engineering directors, and petroleum safety regulators with secondary validation. Bottom-up rig count and day-rate data from EIA and OPEC sources triangulated against top-down capital expenditure disclosures from integrated operators. SEC filings, ANP licensing round documentation, and Saudi Aramco supplier framework announcements provided secondary anchor points.
Segment-weighting across service type, technology tier, end-user category, and application maturity structured the analytical framework over the projection horizon. Drilling Services, Well Completion, and Enhanced Oil Recovery dimensions were modeled with geographic overlays for Brazil, Saudi Arabia, and US shale basins. CAGRs derived from historical rig deployment patterns and announced greenfield sanctioning timelines, with inputs from subsea order backlog analysis and EPA compliance cost estimates.
Commodity price volatility, regulatory enforcement intensity, and renewable substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about national oil company capital discipline and deepwater project sanctioning thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Electric Fracking Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
Smart Well Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Drilling Bits Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Delayed Coker Unit Process Technology Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Mexico Oil and Gas Market