
 Oil and Gas Separation Equipment Market | 2026-2036
Oil and Gas Separation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Separation Equipment Market Intelligence
EPA effluent guidelines for offshore oil and gas platforms is shifting the cost-of-entry calculus for separation equipment vendors, as compliance now mandates higher-performance three-phase and electrostatic systems. Schlumberger leverages its integrated project delivery model to anchor large-scale offshore contracts across multiple basins. Alfa Laval differentiates through compact centrifugal modules that reduce footprint on congested platforms. TechnipFMC sustains engineering leadership in subsea separation, where pressure-rated designs command premium positioning.
Oil and gas separation equipment encompasses pressure vessels engineered to partition crude oil, natural gas, brine, and solids through gravity settling, centrifugal force, or electrostatic coalescence, typically operating at pressures from 50 to 5,000 psi and temperatures up to 350°F to condition hydrocarbon streams for transport or refining. Three-phase separators dominate upstream production installations due to their ability to simultaneously separate oil, gas, and water in a single vessel, though electrostatic coalescing units are gaining share in heavy-oil applications where emulsion stability demands higher energy input. Gravity separation technology remains the workhorse across midstream processing, while membrane separation occupies a nascent but growing niche in produced-water polishing for reinjection compliance.
EPA offshore discharge rules, API 12J design standards, and NORSOK P-100 Norwegian shelf requirements collectively shape equipment specifications, certification burdens, and aftermarket retrofit cycles across North American and North Sea markets. Brazil's national petroleum regulator and Mexico's ASEA impose analogous local-content and environmental thresholds that vendors must navigate for project qualification. Stakeholders must weigh capex commitments against regulatory trajectory uncertainty, particularly as produced-water reinjection standards tighten and carbon-intensity disclosures extend to supply-chain equipment sourcing.
Market Dynamics
Produced-water volumes from unconventional reservoirs are overwhelming legacy gravity separation infrastructure across the Permian Basin and Bakken Shale, forcing operators toward higher-throughput electrostatic and centrifugal systems that can handle rising water cuts without footprint expansion.
Growth Catalysts
- EPA Offshore Discharge Rules:Tightening oil-in-water limits for Gulf of Mexico platforms mandate three-phase separator upgrades, accelerating replacement cycles for vessels exceeding fifteen years of service.
- Brazil Pre-Salt Development:Deepwater fields off the Santos Basin require subsea separation modules to handle high-pressure, high-temperature flows at depths exceeding 2,000 meters.
- Electrostatic Coalescence:Heavy-oil producers in Canada and Venezuela deploy high-voltage grids to break stable water-in-oil emulsions that gravity settlers cannot resolve economically.
Market Restraints
- Specialized Alloy Costs:Duplex stainless steel and Inconel cladding for sour service applications face price volatility tied to nickel and molybdenum commodity swings.
- Fabrication Concentration:Pressure vessel manufacturing clusters in Houston, Singapore, and Rotterdam create geographic supply risk during hurricane or labor disruption events.
- Gravity Settler Performance Ceiling:Conventional horizontal separators hit throughput limits below 10,000 barrels per day for high-water-cut streams, constraining retrofit economics.
Strategic Opportunities
- Guyana-Suriname Basin:ExxonMobil and consortium partners are qualifying subsea separation vendors for phased developments requiring compact, retrievable processing modules.
- Membrane Polishing:Ceramic and polymeric membranes for produced-water reinjection compliance represent a greenfield attach market to conventional separation trains.
- EU Methane Regulation:Fugitive emission monitoring mandates create demand for closed-loop separator designs with integrated vapor recovery units on North Sea platforms.
Industry Challenges
- ASME VIII Division 1 Certification:Third-party pressure vessel qualification timelines extend eighteen to twenty-four months, delaying project FIDs for offshore developments.
- Legacy SCADA Integration:Brownfield separator automation retrofits must interface with proprietary control architectures from decades-old platform installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Separation Equipment Market |
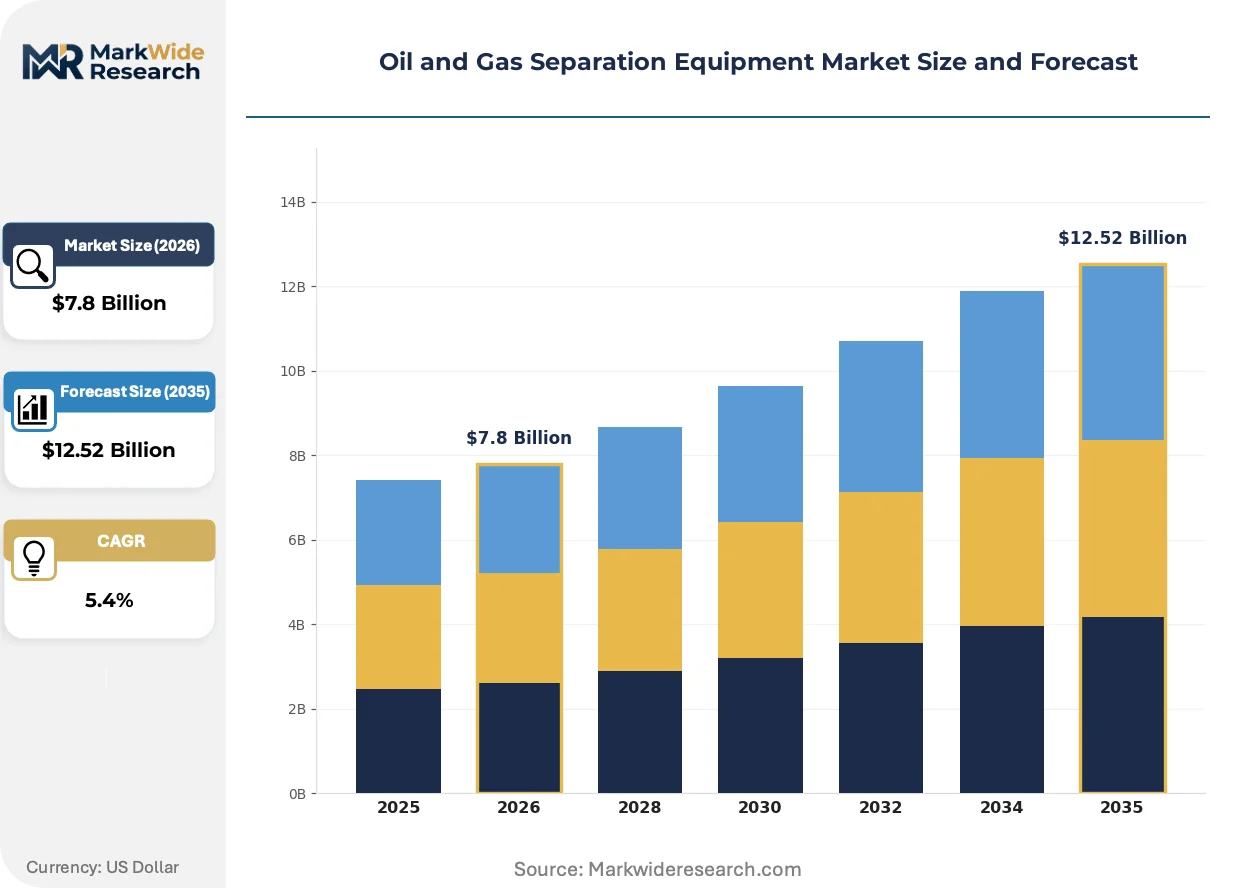
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Three-Phase Separators, Two-Phase Separators, Heater Treaters, Electrostatic Separators, Desanders Technology: Gravity Separation, Centrifugal Separation, Membrane Separation, Electrostatic Coalescing, Cyclonic Separation Application: Upstream Production, Midstream Processing, Downstream Refining, Natural Gas Treatment, Petrochemical Processing End User: Oil Producers, Pipeline Operators, Refining Contractors, Gas Processing Plants, Petrochemical Firms |
| Companies Covered | Worthington Industries, GEA Group, Alfa Laval, HAT International, Schlumberger, ACS Manufacturing, TechnipFMC, Valerus, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Separation Equipment Market Strategic Shifts & Innovations
Equipment form factors and control architectures are compressing installation timelines while regulatory pressure on discharge quality forces step-change performance improvements across offshore and onshore basins.
Compact electrostatic treater technology is modularizing field deployment for shale operators facing pad space constraints. Permian producers now specify skid-mounted units rated for 5,000 psi in 40-foot container footprints, eliminating civil foundation work and cutting commissioning from weeks to days. This shift is modularizing supplier business models toward lease-operate-maintain contracts rather than outright equipment sales.
API 12J design standards are tightening allowable liquid carryover specifications for gas scrubbers and three-phase separators. The 2024 revision reduces oil-in-gas limits by 30 percent for offshore applications, forcing vendors to add internal mist elimination stages or face disqualification from Gulf of Mexico and North Sea tenders. Fabricators in Louisiana and Norway are re-engineering vessel internals to meet the revised droplet separation efficiency curves.
Integrated service contracts are displacing component-only procurement for offshore megaprojects. Brazilian pre-salt operators now bundle separator supply with installation, commissioning, and ten-year maintenance under single-source agreements. This consolidation is visible in the Búzios and Mero field developments, where Petrobras has shifted from multi-vendor EPC splits to integrated processing package awards that reduce interface risk.
Oil and Gas Separation Equipment Market Segmentation
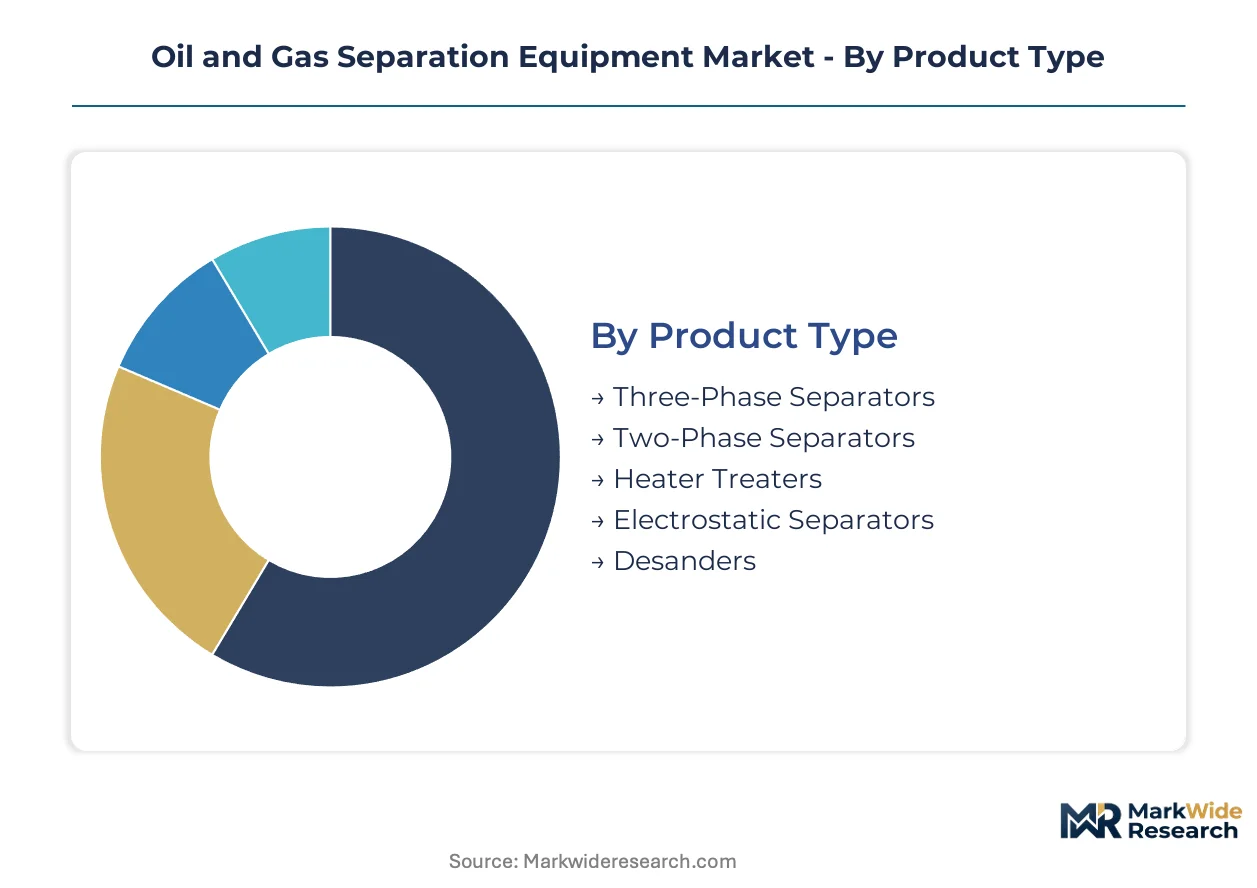
Equipment segmentation in the oil and gas separation market tracks the divergence between legacy infrastructure replacement cycles and emerging technology adoption curves. Each dimension—product type, technology, application, and end user—carries distinct procurement patterns shaped by regulatory pressure, water-cut economics, and field-specific operating conditions.
Product Type:
Upgrade and replacement cycles dominate procurement flows across all product categories, with fifteen-year vessel retirement timelines compressing as API 12J standards tighten discharge specifications.
- Three-Phase Separators:These pressure vessels simultaneously partition oil, gas, and produced water through gravity settling and internal weir arrangements, typically rated for 1,440 psi working pressure. Demand clusters in the Permian Basin and Gulf of Mexico offshore platforms where EPA effluent rules mandate simultaneous three-stream separation. Operators face retrofit economics against brownfield space constraints.
- Two-Phase Separators:Simpler vessel architectures separate only gas from liquid hydrocarbons, serving gas-lift systems and early-production facilities. Canadian oil sands and Venezuelan heavy-oil fields deploy these for primary knock-out service ahead of downstream electrostatic treatment. Lower capital intensity suits marginal well economics.
- Heater Treaters:Direct-fired or indirect-fired vessels apply thermal energy to reduce crude viscosity and accelerate water droplet coalescence. Bakken Shale operators specify these for high-paraffin crudes.
- Electrostatic Separators:High-voltage grids generate electric fields that destabilize water-in-oil emulsions. Brazil's pre-salt developments and Canadian thermal projects drive specification.
- Desanders:Cyclonic or gravitational solids-removal units protect downstream pumps and meters. North Sea installations and Middle East carbonate fields require these for sand-laden production streams.
Volume placements concentrate in three-phase separators; the faster expansion belongs to electrostatic separators.
Technology:
Technology selection maps directly to produced-water volume trajectories and footprint constraints, with high-water-cut unconventional reservoirs forcing migration beyond conventional gravity settling.
- Gravity Separation:The foundational mechanism exploits density differentials between oil, gas, and water phases in horizontal or vertical vessel configurations. Midstream processing terminals across Texas, Louisiana, and Rotterdam harbor rely on these for bulk separation where space permits and residence times of 3-5 minutes are acceptable. Tightening oil-in-water limits are pushing this technology toward its performance ceiling.
- Centrifugal Separation:Rotating bowl or disc-stack configurations generate artificial gravity fields exceeding 10,000 G, enabling compact footprints for offshore platforms. Alfa Laval's disc-stack modules serve North Sea installations where deck space commands premium positioning. High rotational speeds demand precise maintenance protocols.
- Membrane Separation:Ceramic or polymeric barriers filter dispersed oil droplets below 15 microns for reinjection-grade water quality. Permian Basin operators pilot these for produced-water polishing ahead of saltwater disposal well injection.
- Electrostatic Coalescing:Alternating current fields promote droplet aggregation in heavy-oil applications where thermal methods prove uneconomical. Venezuela's Orinoco Belt and Canada's Athabasca region specify these for bitumen emulsion breaking.
- Cyclonic Separation:Tangential inlets generate vortex flows that separate phases by centrifugal force without moving parts. Subsea developments off Brazil and West Africa deploy these for compact gas-liquid separation at depth.
Gravity separation retains the largest installed base; membrane separation is climbing the fastest as reinjection standards tighten.
Application:
Application segmentation reflects the upstream-to-downstream value chain, with each link imposing distinct pressure ratings, metallurgy requirements, and automation specifications.
- Upstream Production:Wellhead separation handles unprocessed reservoir fluids at pressures from 500 to 5,000 psi and temperatures to 350°F. US onshore shale and Brazil's pre-salt deepwater anchor procurement volumes. High water cuts and corrosive H2S content drive alloy specification.
- Midstream Processing:Gathering system facilities consolidate multiple well streams for transport conditioning. Permian Basin pipeline injection specifications and NGL recovery requirements shape equipment sizing.
- Downstream Refining:Desalting vessels prepare crude for atmospheric distillation through electrostatic dehydration. US Gulf Coast and Rotterdam refining clusters specify these.
- Natural Gas Treatment:Inlet separators protect amine units and molecular sieve dehydration systems from liquid slugs. Appalachian shale gas processing expansions drive demand.
- Petrochemical Processing:Steam cracker feed pretreatment and pyrolysis gas separation require corrosion-resistant alloys. US Gulf Coast and Middle East integrated complexes specify these.
Upstream production commands the largest capital allocation; downstream refining offers the most stable replacement-cycle visibility.
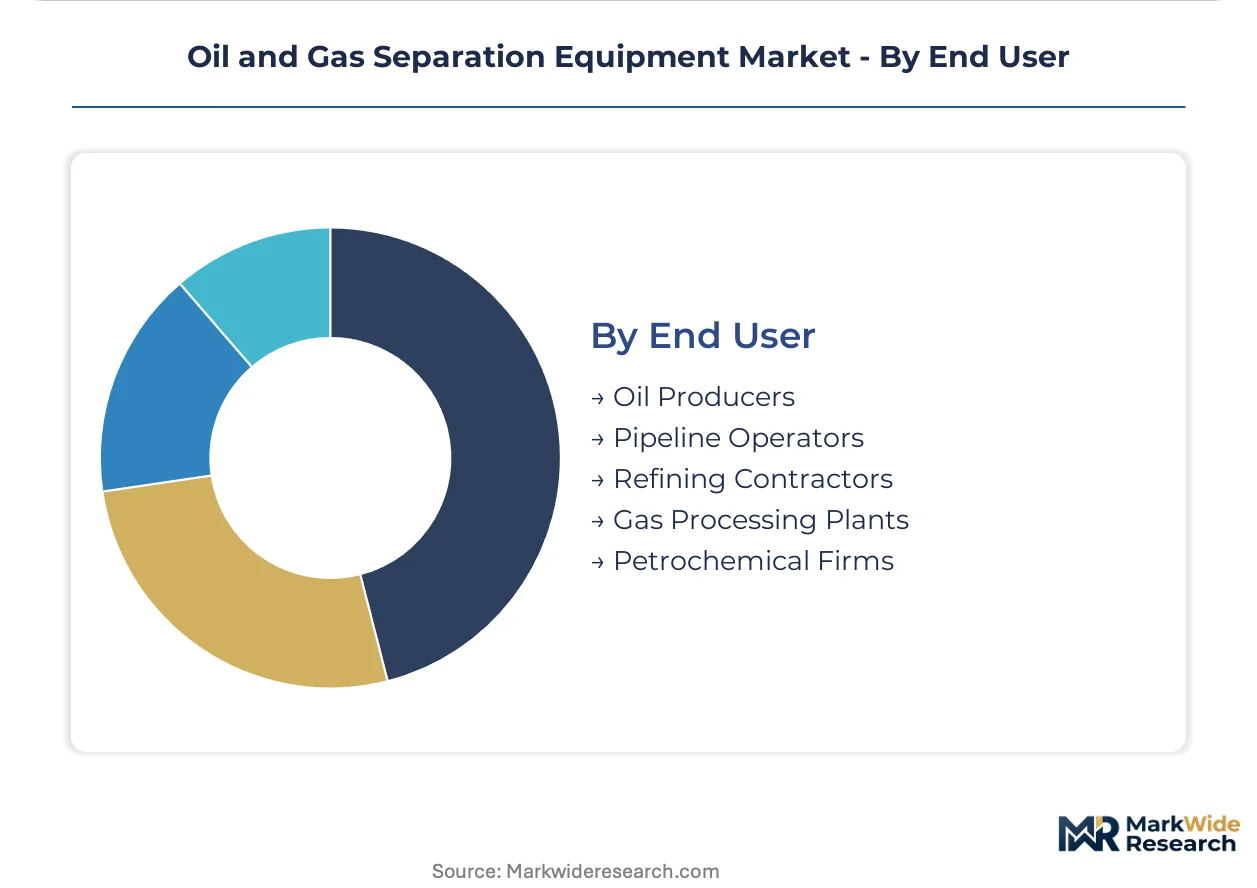
End User:
End-user procurement patterns diverge between integrated operators with captive engineering capabilities and midstream specialists seeking packaged solutions.
- Oil Producers:Exploration and production companies—ExxonMobil, Petrobras, independent Permian operators—specify separation trains as part of field development engineering. These buyers prioritize reliability metrics and regulatory compliance documentation over first cost.
- Pipeline Operators:Midstream transportation companies require inlet separation at compressor stations and custody transfer points. US interstate pipeline FERC regulations and Brazilian ANP specifications govern equipment selection.
- Refining Contractors:Engineering-procurement-construction firms bundle separation units into turnaround and expansion projects. TechnipFMC and similar integrators source to project-specific performance guarantees.
- Gas Processing Plants:NGL extraction and dewpoint control facilities demand high-efficiency gas-liquid separation ahead of cryogenic units. Appalachian and Permian gas processing buildouts drive specification.
- Petrochemical Firms:Olefins and aromatics producers require specialized separation for feedstock purification. US Gulf Coast and Middle East capacity expansions anchor demand.
Oil producers generate the largest equipment orders; gas processing plants are gaining share fastest with shale gas infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater exploration contractors in the Gulf of Mexico and offshore Brazil are expanding separator procurement faster than any other demand concentration. API 12J and NORSOK P-100 standards are tightening allowable oil-in-water discharge limits across multiple jurisdictions simultaneously.
United States
Permian Basin operators face produced-water volumes that strain legacy separation infrastructure beyond design capacity. EPA offshore discharge rules for Gulf of Mexico platforms mandate three-phase separator upgrades, accelerating replacement cycles for vessels exceeding fifteen years of service. Fabricators in Louisiana and Texas are re-engineering vessel internals to meet revised droplet separation efficiency curves.
Brazil
Pre-salt developments in the Santos Basin require subsea separation modules rated for high-pressure, high-temperature flows at depths exceeding 2,000 meters. The national petroleum regulator imposes local-content thresholds that vendors must navigate for project qualification. Petrobras has shifted from multi-vendor EPC splits to integrated processing package awards at Búzios and Mero fields.
Norway
North Sea platforms face EU methane regulation mandates for fugitive emission monitoring and closed-loop separator designs with integrated vapor recovery units. NORSOK P-100 standards shape equipment specifications and certification burdens across the Norwegian shelf. Bergen and Stavanger engineering clusters specialize in pressure-rated designs for harsh-environment offshore installations.
Canada
Heavy-oil producers in Alberta's Athabasca region deploy electrostatic coalescing units to break stable water-in-oil emulsions that gravity settlers cannot resolve economically. Thermal projects drive specification for high-voltage grid systems. Calgary-based engineering firms anchor procurement for oil sands separation infrastructure.
Mexico
ASEA environmental thresholds and local-content requirements govern equipment selection for offshore developments in the Gulf of Mexico. Deepwater contractors are qualifying separation vendors for phased field developments requiring compact, retrievable processing modules. Ciudad del Carmen fabrication yards serve as the primary supply hub for Mexican offshore projects.
Oil and Gas Separation Equipment Market Key Industry Players
North American fabricators anchor one tier for onshore shale applications; European specialists hold premium positioning for offshore and subsea systems. The vendor base separates into integrated project delivery organizations, compact module specialists, and subsea engineering leaders. Three strategic archetypes dominate: full-service EPC integrators, footprint-optimized technology providers, and pressure-rated deepwater designers. M&A activity concentrates on acquiring subsea separation capabilities, while capacity expansion targets Gulf of Mexico and Brazilian fabrication yards.
Within the integrated service tier, Schlumberger and TechnipFMC exemplify vendors bundling separator supply with installation, commissioning, and long-term maintenance under single-source agreements. Alfa Laval occupies a position among compact technology specialists, representing the footprint-optimized archetype for congested platform environments. These three companies anchor the competitive structure across deepwater and unconventional basins.
| Leading Market Players |
|---|
| Worthington Industries |
| GEA Group |
| Alfa Laval |
| HAT International |
| Schlumberger |
| ACS Manufacturing |
| TechnipFMC |
| Valerus |
| Honeywell |
| Others |
Cost & Logistics Intelligence
Nickel and molybdenum commodity indices cascade through duplex stainless steel procurement costs, compressing margins for pressure vessel fabricators serving sour-service applications while stratifying equipment pricing across certification tiers. Buyers face step-up premiums for NORSOK P-100 and API 12J compliant systems as alloy volatility feeds into project quotations.
Pricing Analysis
Volume procurement separates from margin capture across the equipment spectrum. Project-based contracting dominates offshore megaprojects, while lease-operate-maintain models gain traction in Permian shale applications. Price differentiation hinges on ASME VIII Division 1 certification status and integrated service bundling. Cost compression in standard gravity settlers intensifies as Chinese fabricators enter mid-tier supply. Independent Permian operators exhibit highest price sensitivity; Petrobras and ExxonMobil consortiums prioritize performance guarantees over first cost.
Supply Chain Analysis
Specialty alloy supply rests on Austrian and Swedish specialty steel producers for super-duplex grades, with Japanese and South Korean mills anchoring high-nickel cladding feedstock. Pressure vessel fabrication concentrates in Houston, Singapore, and Rotterdam harbor clusters. Nickel price volatility and hurricane exposure across Gulf Coast fabrication yards constitute primary supply chain risks. Distribution runs through EPC integrators for offshore developments and direct OEM relationships for onshore shale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendor consolidation accelerates as EPA offshore discharge rules and API 12J revisions raise certification barriers beyond mid-tier fabricator capabilities. Weaker players face exit pressure from eighteen-month ASME qualification timelines and alloy cost volatility.
For Market Incumbents: Cement subsea engineering leadership through captive R&D in pressure-rated designs for Brazil's pre-salt depths. Defend against modular electrostatic specialists by acquiring compact centrifugal technology providers. Prioritize backward integration into specialty alloy supply through long-term offtake agreements with European mills. For New Entrants and Emerging Players: EPA effluent guideline tightening in the Gulf of Mexico opens a window for three-phase separator retrofit specialists. Target Permian Basin water-handling bottlenecks with skid-mounted electrostatic units sized for 40-foot container deployment. Pursue lease-operate-maintain contracts rather than capital equipment sales to bypass incumbent EPC relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor membrane separation technology developers in Texas and Alberta engineering clusters. Long-term viability rests on produced-water reinjection compliance tightening across multiple jurisdictions. Watch ceramic membrane pilot results in Permian saltwater disposal applications as inflection signal for technology substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Separation Module Development | Petrobras integrated awards at Búzios and Mero fields anchor premium positioning. |
| Compact Electrostatic Treater Manufacturing | Permian pad space constraints drive 5,000 psi skid-mounted specifications. |
| Membrane Polishing Technology Acquisition | Ceramic filtration for reinjection compliance represents greenfield attach opportunity. |
| Specialty Alloy Supply Integration | Long-term nickel and molybdenum offtakes hedge against commodity volatility. |
| Integrated Service Contract Expansion | Single-source agreements reduce interface risk for Brazilian pre-salt developments. |
Research Approach
Independent corroboration across API certification databases, pressure vessel registration filings, and offshore project development trackers underwrites the qualitative findings. Primary interviews with fabrication yard operations managers, EPC procurement leads, and downstream maintenance directors combined with secondary validation from ASME boiler and pressure vessel code records, EPA effluent guideline dockets, and NORSOK standard revision histories. Bottom-up equipment shipment tallies and top-down capital expenditure forecasts triangulate market sizing.
Comparable historical periods anchored the projection horizon to replacement cycle patterns and regulatory implementation lags. Segmentation modeling spanned product type, technology mechanism, application stage, and end-user procurement archetype across the analysis window. CAGRs derived from equipment unit economics and alloy cost pass-through assumptions. Forecast inputs incorporated produced-water volume trajectories from shale basins and deepwater project sanctioning timelines.
The model assumes a particular technology adoption path; alternative pathways for membrane separation would alter the outlook if reinjection standards tighten faster than ceramic cost curves permit. Forecasts reflect assumptions on regulatory implementation pacing and alloy price mean reversion. A small set of triggers—EPA guideline enforcement intensity, Petrobras local-content threshold adjustments, and nickel market structural shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Middle East and Africa Drill Collar Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
North America Oil and Gas Storage Tank Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
Oil & Gas Static and Rotating Equipment Market
Oil & Gas
United States Oil and Gas Midstream Market
Oil & Gas
North America Hydraulic Fracturing Fluids Market
Oil & Gas
North America Shale Market
Oil & Gas
Oil and Gas Pipeline Coatings Market
Oil & Gas
Oilfield Services Market