
 Soil Stabilization Materials Market | 2026-2036
Soil Stabilization Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Stabilization Materials Market Intelligence
Buyer concentration in civil contracting is pivoting toward tier-one infrastructure conglomerates with multi-year government mandates. Sika AG leverages polymer-based stabilization chemistry to differentiate across European road rehabilitation tenders. BASF SE anchors cementitious additive supply through integrated raw material sourcing. Caterpillar Inc. competes on equipment-integrated application systems that bind material sales to machinery contracts.
Soil stabilization materials encompass binders and admixtures—lime, Portland cement, fly ash, bitumen emulsions, synthetic polymers, and enzymatic compounds—that chemically or mechanically modify soil engineering properties including bearing capacity, plasticity index, and compressibility for load-bearing earthworks. These materials transform marginal or expansive soils into engineered subgrades suitable for highways, airfields, embankments, and building foundations, typically achieving California Bearing Ratio improvements exceeding original soil values by factors of four to ten. Cementitious additives and lime currently occupy the largest share of material type revenue, reflecting decades of standardized highway agency specifications and lowest-quantified-cost procurement protocols. Polymer and enzyme segments represent faster-growing chemistry platforms where margin pools concentrate, driven by performance guarantees in problematic soil geologies and reduced curing time requirements that compress project schedules.
US state DOT specifications incorporate ASTM and AASHTO test methods enforced by FHWA pavement performance audits, while India's Ministry of Road Transport and Highways mandates IRC-guided mix designs with BIS certification for commercial lime and cement modifiers. REACH registration requirements in Europe constrain polymer additive formulations, elevating compliance costs for SNF Holding Company and Graymont export portfolios into EU member states. Stakeholders must monitor evolving carbon-accounting frameworks for construction materials, as embodied-emissions disclosure obligations begin penetrating public infrastructure procurement criteria across multiple jurisdictions.
Market Dynamics
Government pavement durability mandates across India and China are compressing project timelines and forcing rapid chemistry transitions from traditional lime-cement blends toward polymer-modified systems that cure faster and perform in expansive soil geologies.
Growth Catalysts
- IRC-Guided Mix Design Mandates:India's Ministry of Road Transport and Highways enforces IRC specifications that require commercial lime and cement modifiers for national highway subgrades, creating standardized demand pull across state contracting agencies.
- Polymer Chemistry Performance Guarantees:Synthetic polymer stabilizers reduce curing windows from 28 days to 7 days, enabling contractors to meet penalty-structured completion schedules on airfield and embankment projects.
- Fly Ash Utilization Protocols:China's MEE environmental compliance frameworks mandate industrial byproduct incorporation in infrastructure corridors, diverting material from landfill toward cementitious additive supply streams.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic polymer binders depend on ethylene and propylene derivatives whose price swings compress formulation margins for specialty additive producers.
- REACH Registration Burden:ECHA chemical registration requirements in Europe elevate compliance costs for polymer additive exporters, constraining market entry for non-EU chemistry portfolios.
- Enzymatic Compound Shelf Instability:Biological stabilizers face degradation risks in warm-climate storage and transport, limiting distribution radius from production facilities.
Strategic Opportunities
- Carbon-Accounting Procurement Criteria:Embodied-emissions disclosure obligations in public infrastructure tenders across Germany and France create first-mover advantage for low-carbon binder formulations.
- Equipment-Integrated Application Systems:Machinery OEMs are bundling stabilization material supply with fleet contracts, opening captive distribution channels that bypass traditional chemical distributors.
- Expansive Clay Geology Specialization:Texas Gulf Coast and Australian black cotton belt regions present underpenetrated demand for enzyme-based soil modification where lime fails.
Industry Challenges
- Geotechnical Engineer Scarcity:Specialized soil mechanics expertise required for mix design optimization is concentrated among aging practitioners, creating project bottlenecks.
- AASHTO Certification Timelines:US state DOT approval processes for novel stabilizer chemistries extend 18-24 months, delaying commercialization of improved formulations.
- Legacy Subgrade Assessment Integration:Digital soil mapping and drone-based compaction monitoring require retrofitting into established quality assurance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Stabilization Materials Market |
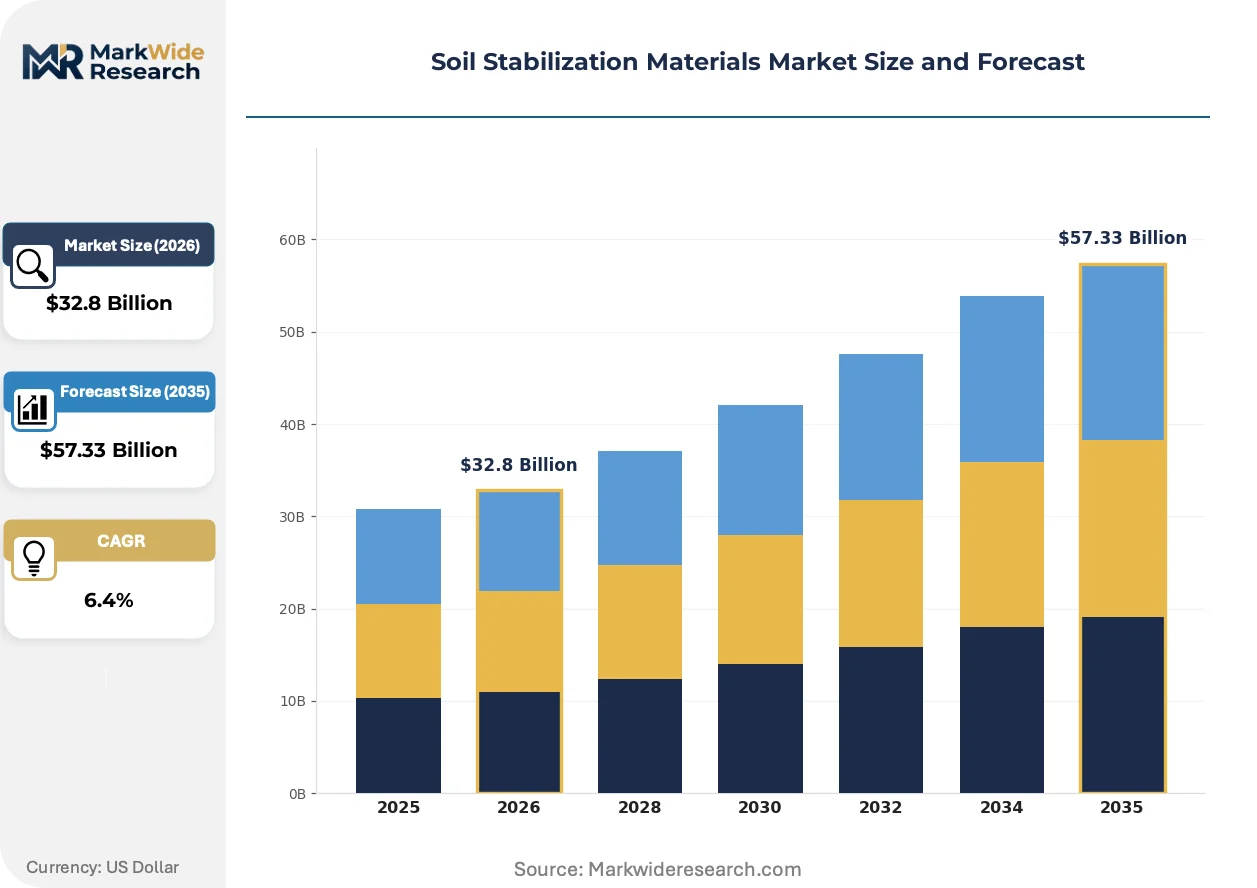
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lime, Fly Ash, Cementitious Additives, Polymers, Enzymes, Bitumen Application: Road Construction, Embankments, Foundation Works, Slope Stabilization, Airfield Paving, Landscaping End User: Civil Contractors, Government Agencies, Mining Operators, Agricultural Developers, Military Installations, Environmental Consultants Form: Powder, Liquid, Granular, Emulsion, Paste, Fiber-Reinforced |
| Companies Covered | Wirtgen Group, Caterpillar Inc., AB Volvo, Fayat Group, Carmeuse, Sika AG, Graymont, BASF SE, SNF Holding Company Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Stabilization Materials Market Strategic Shifts & Innovations
Stabilization chemistry is fragmenting into application-specific formulations while regulatory carbon accounting and equipment-integrated delivery models reshape competitive boundaries between material suppliers and machinery providers.
Polymer-modified emulsion systems are modularizing road rehabilitation workflows by enabling same-day trafficking on reconstructed subgrades. European road agencies in Germany and France are specifying these chemistries for urban corridor projects where lane closure duration determines contractor selection. The technology compresses project schedules from weeks to days, forcing traditional lime suppliers to demonstrate equivalent performance or absorb delay penalties.
REACH registration requirements under ECHA jurisdiction are constraining polymer additive formulations entering EU member states, elevating compliance costs that favor established registrants with existing dossiers. The regulation fragments supply availability across European tenders, with non-registered chemistries excluded from publicly funded infrastructure bids. Specialized stabilizer producers are responding by acquiring or partnering with EU-based registration holders rather than pursuing independent authorization.
Buyer concentration among tier-one infrastructure conglomerates with multi-year government mandates is displacing fragmented civil contractor procurement. India's NHAI and state PWDs now bundle stabilization material supply into 5-year framework agreements with pre-qualified vendors. This consolidation compresses supplier margins while rewarding integrated providers who can guarantee volume and technical support across multiple simultaneous projects.
Soil Stabilization Materials Market Segmentation
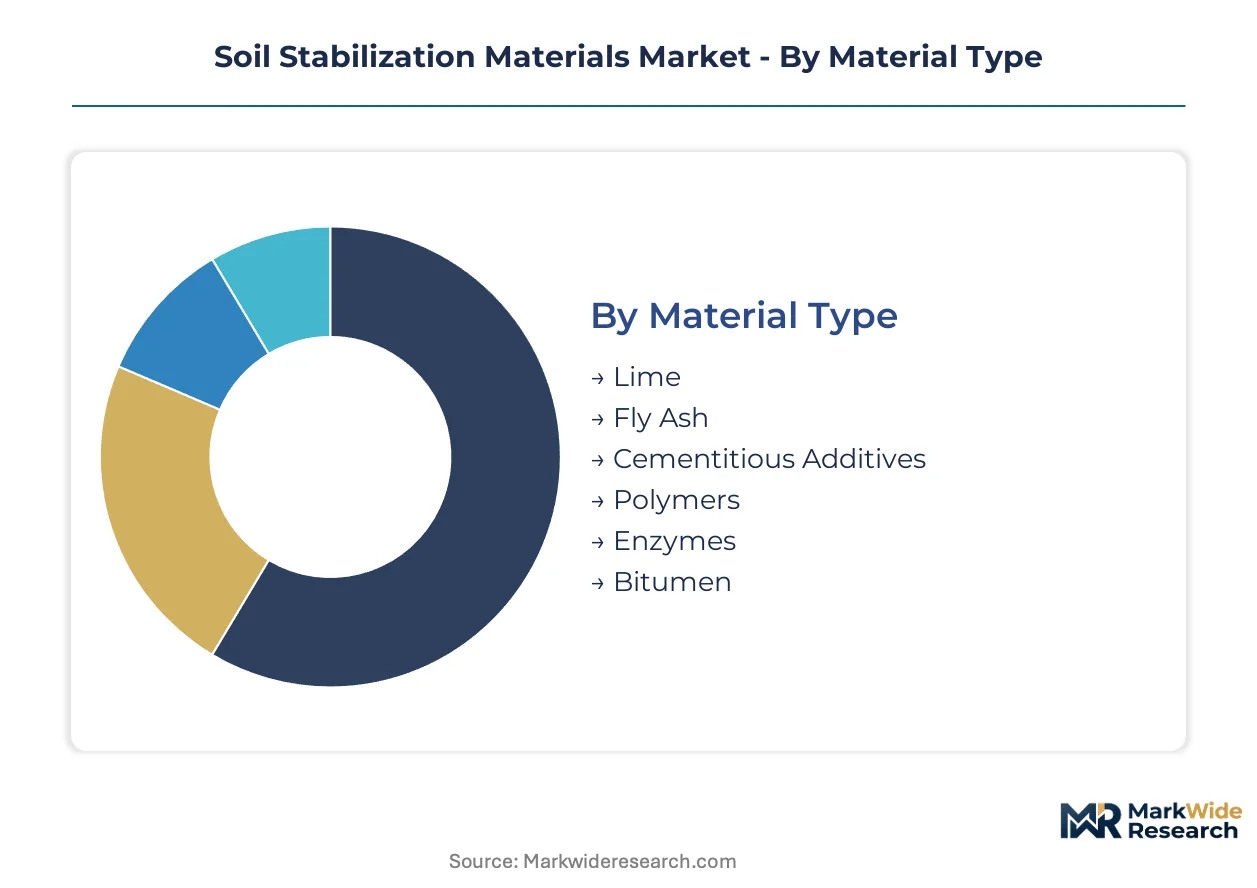
Segmentation in soil stabilization materials reveals how chemistry selection, application environment, and delivery format interlock with procurement workflows. Contractors specify materials against geotechnical reports, while government mandates increasingly dictate allowable formulations by project type.
Material Type:
Integration depth varies sharply—cementitious additives and lime function as standalone bulk commodities, while polymers and enzymes embed within engineered systems requiring technical service support.
- Cementitious Additives:Portland cement and blended hydraulic binders provide standardized strength gain with predictable 28-day curing profiles. India's Ministry of Road Transport and Highways mandates IRC-guided mix designs with BIS certification, embedding these materials in national highway subgrade specifications.
- Polymers:Synthetic polymer stabilizers—polyacrylamides, polyurethane prepolymers, and vinyl acetate derivatives—reduce curing windows from 28 days to 7 days through ionic bonding with clay particles. German road agencies specify these for urban corridor rehabilitation where lane closure duration determines contractor selection.
- Lime:Quicklime and hydrated lime remain the lowest-quantified-cost option for expansive soil modification, with calcium oxide content specifications enforced by state DOT testing protocols.
- Fly Ash:Class C and Class F coal combustion byproducts serve as pozzolanic extenders in cementitious blends, with China's MEE environmental compliance protocols mandating utilization in infrastructure corridor projects.
- Enzymes:Biological catalytic compounds—proprietary formulations of fermented organic catalysts—modify clay particle surface chemistry without cementitious reaction, suited to black cotton belt geologies where lime-induced heave risks exist.
- Bitumen:Cutback and emulsion bitumen binders provide waterproofing and flexural fatigue resistance in cold-climate pavement reconstruction.
Volume placements concentrate in cementitious additives and lime; the steepest expansion trajectory belongs to polymers.
Application:
Cost tier segmentation separates high-volume, specification-driven road work from specialized projects commanding premium pricing for performance guarantees.
- Road Construction:National highway, urban arterial, and rural road subgrade stabilization consumes the majority of material volume, with FHWA pavement performance audits enforcing ASTM and AASHTO test method compliance across US state DOT contracts.
- Airfield Paving:Runway and taxiway subgrades demand CBR improvements exceeding original soil values by factors of six to ten, with FAA specifications mandating polymer-modified systems for rapid return-to-service requirements.
- Embankments:Earth fill and structural fill applications utilize lime and fly ash blends for moisture conditioning and long-term settlement control.
- Foundation Works:Building pad and industrial floor subgrades employ cementitious stabilization for bearing capacity enhancement in expansive clay regions.
- Slope Stabilization:Cut and fill slope face protection combines soil nailing with polymer spray application for erosion resistance.
- Landscaping:Golf course construction and recreational trail surfacing represent emerging demand for low-carbon enzymatic stabilizers in environmentally sensitive jurisdictions.
Premium pricing concentrates in airfield paving; the fastest volume climb occurs in road construction procurement bundles.
End User:
Customer type determines technical support intensity and contract structure—government agencies standardize specifications while mining operators demand site-specific mix optimization.
- Civil Contractors:Tier-one infrastructure conglomerates with multi-year government mandates now bundle stabilization material supply into framework agreements, compressing supplier margins while rewarding integrated technical support capabilities.
- Government Agencies:India's NHAI and state PWDs enforce pre-qualified vendor lists with IRC specification compliance, creating standardized demand pull across national highway projects.
- Mining Operators:Haul road and tailings dam construction in remote locations requires mobile batching equipment and on-site geotechnical support.
- Agricultural Developers:Farm-to-market road and irrigation canal embankment projects utilize lower-specification lime and fly ash blends.
- Military Installations:Rapid airfield damage repair and expeditionary construction demand polymer systems with 24-hour curing for tactical aircraft operations.
- Environmental Consultants:Brownfield remediation and contaminated site capping projects specify low-permeability cementitious barriers.
Contract volume aggregates with civil contractors; the expanding share flows to government agency framework agreements.
Form:
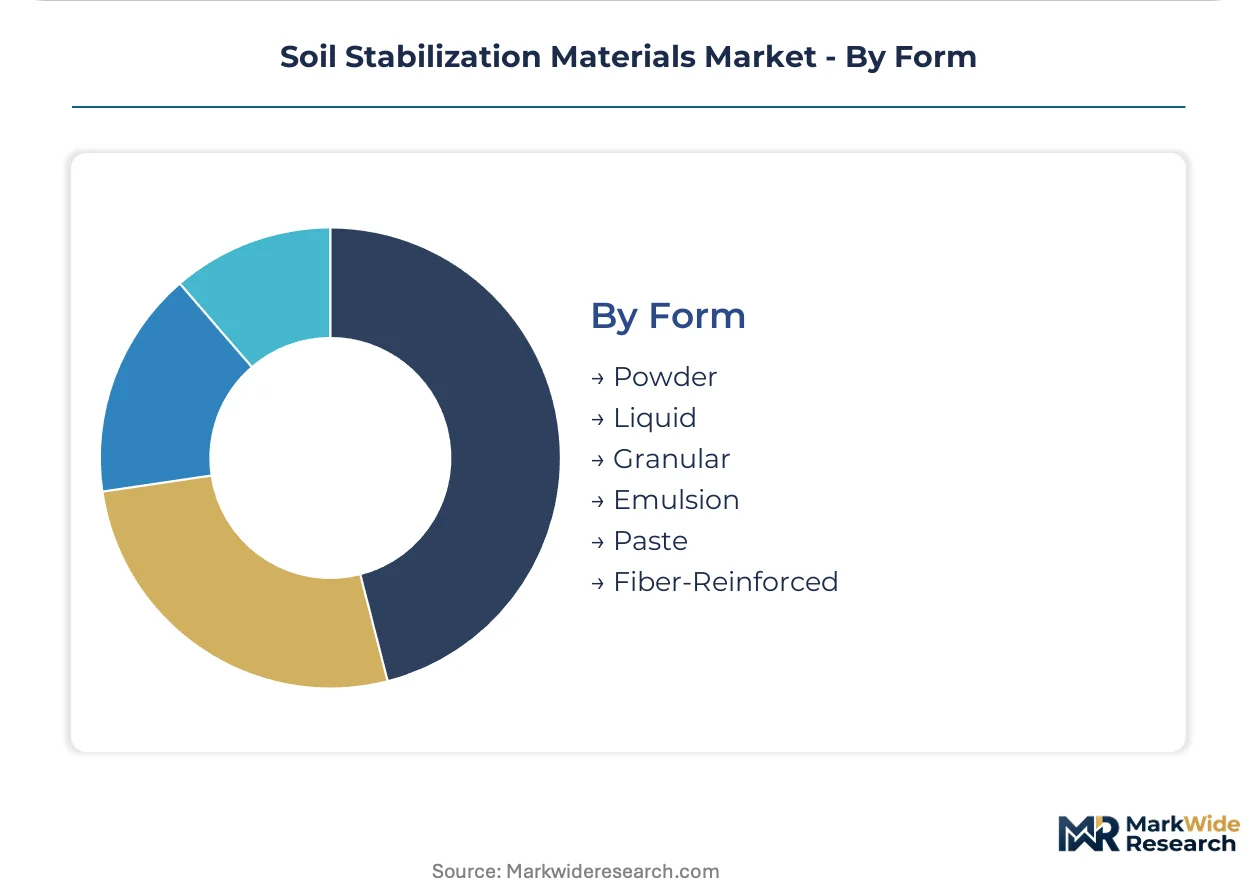
Supply chain configuration favors powder and liquid formats for bulk logistics, while emulsion and fiber-reinforced systems require specialized application equipment.
- Powder:Dry lime, cement, and fly ash ship in pneumatic tankers for silo storage at batch plants, enabling continuous mixing operations.
- Liquid:Polymer solutions and enzymatic compounds distribute in totes and tank trucks with temperature-controlled transport requirements.
- Emulsion:Polymer-modified bitumen emulsions enable same-day trafficking on reconstructed subgrades, with German and French urban corridor specifications driving demand.
- Granular:Pelletized lime and controlled low-strength material aggregates suit remote sites lacking batch plant infrastructure.
- Paste:Pre-mixed cementitious grouts inject into voided soils and sinkhole remediation applications.
- Fiber-Reinforced:Polypropylene and glass fiber additives distribute as dry blends for crack resistance in cement-stabilized layers.
Logistics volume centers on powder; the most rapid format innovation appears in emulsion systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Asia-Pacific infrastructure corridors and North American pavement rehabilitation programs, with procurement patterns diverging between government-mandated specification compliance and performance-guaranteed contractor selection.
United States
FHWA pavement performance audits enforce ASTM and AASHTO test methods across state DOT contracts, compressing approval timelines for novel stabilizer chemistries. Texas Gulf Coast expansive clay geologies generate specialized demand for enzyme-based modifications where traditional lime induces heave. Dallas-Fort Worth metro contractors bundle polymer supply with rapid-curing airfield subgrade specifications.
China
MEE environmental compliance protocols mandate industrial byproduct utilization in infrastructure corridor projects, diverting fly ash from landfill toward cementitious additive streams. Dual carbon goals accelerate low-carbon binder procurement criteria in provincial tenders. Yangtze River Delta megaprojects integrate Class F fly ash as pozzolanic extenders in highway subgrade blends.
India
IRC-guided mix design mandates from the Ministry of Road Transport and Highways require BIS-certified commercial lime and cement modifiers for national highway subgrades. NHAI framework agreements consolidate procurement among pre-qualified vendors across five-year contracting windows. Maharashtra state PWDs enforce standardized additive specifications on Mumbai-Nagpur expressway segments.
Germany
ECHA REACH registration requirements constrain polymer additive formulations, elevating compliance costs for non-EU chemistry portfolios entering publicly funded infrastructure bids. CSRD-aligned embodied-emissions disclosure obligations penetrate procurement criteria for federal transport tenders. Bavarian road agencies specify polymer-modified emulsion systems for urban corridor rehabilitation with same-day trafficking requirements.
Australia
Black cotton belt geologies across Queensland and New South Wales present underpenetrated demand for enzymatic stabilizers where lime-based modification risks long-term heave. State road authorities benchmark California Bearing Ratio improvements against IRC and AASHTO specifications for cross-border contractor qualification. Perth metropolitan earthworks contractors trial low-carbon binder alternatives for government building foundation mandates.
Soil Stabilization Materials Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue equipment-integrated delivery models and carbon-accounting premium positioning. The vendor base stratifies between bulk commodity suppliers with captive raw material sourcing and specialty additive formulators competing on technical service intensity. Three archetypes dominate: integrated chemical conglomerates with REACH-registered polymer portfolios, regional lime and cement distributors serving specification-driven DOT contracts, and machinery OEMs bundling material supply with fleet financing. Consolidation pressure intensifies through framework agreement procurement consolidation and backward integration into raw material extraction.
Within the machinery-integrated tier, Wirtgen Group and Caterpillar Inc. exemplify equipment manufacturers capturing material sales through captive distribution channels tied to fleet contracts. Among chemical specialists, Sika AG occupies a position representing polymer-based stabilization chemistry differentiation across European rehabilitation tenders. BASF SE anchors the integrated chemical conglomerate archetype with cementitious additive supply chains. Graymont and Carmeuse exemplify regional bulk commodity suppliers concentrated in lime production for specification-driven infrastructure markets.
| Leading Market Players |
|---|
| Wirtgen Group |
| Caterpillar Inc. |
| AB Volvo |
| Fayat Group |
| Carmeuse |
| Sika AG |
| Graymont |
| BASF SE |
| SNF Holding Company Inc. |
| Others |
Cost & Logistics Intelligence
Captive lime production in India and China anchors supply positions for tier-one infrastructure conglomerates while compressing margins for distributors lacking upstream quarry control. This backward integration into limestone extraction secures volume guarantees for NHAI framework agreements but forces specialty polymer suppliers to compete on technical service intensity rather than feedstock cost.
Pricing Analysis
Volume placements in cementitious additives and lime operate on contract-based long-term offtake with thin margins, while polymer and enzyme segments command premium-mid-economy pricing differentiation based on performance guarantees and curing speed. BIS certification and REACH registration act as quality-grade barriers that sustain price premiums for compliant suppliers. Cost compression in bulk lime runs through framework agreement consolidation, as India's state PWDs bundle multi-year procurement into pre-qualified vendor lists. Civil contractors with government mandates exhibit lowest price sensitivity due to pass-through mechanisms, whereas agricultural developers face acute pressure on low-specification blends.
Supply Chain Analysis
Freight economics from limestone quarries in Rajasthan and Guangdong province dictate regional supply radii for bulk commodities, with pneumatic tanker logistics tethering powder format distribution to batch plant proximity. Quicklime and hydrated lime draw from captive kiln operations in India, China, and the United States, while synthetic polymer feedstocks hinge on ethylene derivative availability from Gulf Coast petrochemical complexes. Single-source vulnerability concentrates in Class F fly ash supply from coal-dependent power generation regions. Distribution runs through equipment-integrated channels where Wirtgen and Caterpillar bundle material supply with machinery fleet contracts, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Framework agreement procurement consolidation is forcing weaker regional lime distributors toward acquisition or exit, as tier-one conglomerates demand volume guarantees across simultaneous projects. This structural pressure favors integrated producers with captive raw material positions.
For Market Incumbents: Hedge polymer margin erosion by acquiring EU-based REACH registration holders rather than pursuing independent ECHA authorization, while deepening captive limestone reserves in Maharashtra and Rajasthan to secure NHAI volume commitments. Machinery OEMs bundling stabilization supply with fleet financing threaten traditional chemical distribution channels.
For New Entrants and Emerging Players: Capture enzymatic compound demand in Queensland's black cotton belt and Texas Gulf Coast expansive clay geologies where lime-induced heave risks disqualify traditional stabilizers. Partner with mobile batching equipment providers to bypass established distributor networks in remote mining haul road projects.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty additive formulators with REACH-registered polymer portfolios and technical service capabilities, as carbon-accounting procurement criteria in Germany and France create acquisition premiums for low-carbon binder developers. Watch for MEE enforcement tightening on fly ash utilization mandates as inflection signal for cementitious substitute demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Quarries | Captive feedstock secures NHAI framework agreement eligibility against import-dependent competitors. |
| REACH Registration Acquisition | Pre-built ECHA dossiers unlock EU public infrastructure tenders excluding non-registered chemistries. |
| Equipment-Integrated Distribution Partnership | Caterpillar and Wirtgen fleet contracts create captive material sales channels bypassing distributors. |
| Enzymatic Formulation R&D Investment | Black cotton belt specialization commands premium pricing where lime stabilization fails. |
| Carbon-Accounting Certification Program | CSRD-aligned embodied-emissions disclosure meets German federal transport tender procurement criteria. |
Research Approach
Trade statistics from India's Ministry of Commerce, China's General Administration of Customs, and US Census Bureau export records formed the secondary backbone for volume triangulation. Primary interviews with NHAI procurement officers, state PWD technical directors, geotechnical engineering consultants, lime plant operations managers, and polymer R&D directors at Sika and BASF validated mix design specifications and curing performance claims. Bottom-up project pipeline analysis across national highway, airfield, and mining haul road segments reconciled against top-down material consumption estimates from cement and lime industry associations.
Historical trendline analysis of lime, cement, and fly ash pricing across Indian, Chinese, and US markets informed elasticity assumptions over the projection horizon. The analytical framework segmented demand by material type, application environment, end-user contract structure, and regional regulatory cluster, with CAGRs derived from project completion timelines and infrastructure budget allocations. Industry-specific inputs included IRC specification revision cycles, AASHTO certification queue lengths, and MEE environmental compliance enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH registration backlog clearance, petrochemical feedstock volatility, and carbon-accounting mandate adoption rates across EU member states. Forecasts reflect documented assumptions on government pavement durability enforcement and framework agreement procurement consolidation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Industrial Heaters Market
Industrial Materials
Plastic Gears Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Twin Screw Extruders Market
Industrial Materials
North America Medical Plastics Extrusion Market
Industrial Materials
Modified Wood Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Polymer Bearing Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Fly Ash Market
Industrial Materials
Argon Knife Market
Industrial Materials
United States Ceramic Roller Bearings Market
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Global Industrial Chain Market