
 Twin Screw Extruders Market | 2026-2036
Twin Screw Extruders Market Size, Share, and Industry Trends Forecast 2026-2036
Twin Screw Extruders Market Outlook
Modular extrusion line configurations is repositioning buyer procurement patterns as compounders seek plug-and-play subsystems rather than monolithic turnkey installations. Coperion GmbH leverages its integrated compounding systems to dominate high-throughput polymer applications. KraussMaffei Group anchors its position through deep specialization in medical-grade extrusion with cleanroom-compatible architectures. Leistritz Extrusionstechnik GmbH differentiates via precision micro-compounding systems for engineering plastics.
Twin screw extruders are continuous processing machines employing two intermeshing screws within a heated barrel to mix, melt, and convey materials with precise shear control and residence time management. These systems achieve dispersive and distributive mixing through controlled screw geometry, operating typically at L/D ratios exceeding 40:1 for demanding compounding tasks. Corotating intermeshing designs lead the product type landscape due to superior self-wiping action and throughput consistency in polymer compounding. The automotive end-user segment commands attention as lightweighting mandates intensify demand for long-fiber reinforced thermoplastics requiring specialized extrusion architectures.
REACH registration requirements and EU Green Deal circular economy protocols are mandating recycled content verification across European compounding operations. China's SAMR enforcement of GB standards for food-contact plastics and NMPA medical device material traceability rules are raising compliance barriers for imported extrusion systems. FDA 21 CFR compliance for pharmaceutical hot-melt extrusion adds a parallel regulatory track in United States healthcare applications. Stakeholders must monitor evolving extended producer responsibility frameworks that will reshape equipment specifications for post-consumer recycled feedstock processing.
Market Dynamics
Modular extrusion line configurations are repositioning buyer procurement patterns as compounders seek plug-and-play subsystems rather than monolithic turnkey installations. REACH chemical safety standards and China's GB standards for recycled polymer content are tightening material traceability requirements simultaneously.
Growth Catalysts
- Bioplastics compounding:Automotive interior panel applications are expanding adoption across European OEM supply chains as lightweighting mandates intensify.
- REACH registration protocols:Chemical safety verification requirements are mandating equipment upgrades for recycled content traceability in European compounding operations.
- Rhine-Ruhr industrial corridor:Machinery maker clustering near polymer research institutes in Germany is accelerating R&D-to-commercialization cycles for next-generation systems.
Market Restraints
- Specialized alloy supply concentration:Bimetallic barrel liners and nitrided screw elements depend on concentrated European and Japanese metallurgical suppliers.
- Cleanroom architecture costs:Medical-grade extrusion systems require ISO 14644-1 compliant enclosures that inflate capital requirements substantially.
- Long-fiber thermoplastic processing limits:Current screw geometries face throughput ceilings when processing carbon fiber reinforced polymers above 50% fiber loading.
Strategic Opportunities
- Post-consumer recycled feedstock processing:Extended producer responsibility frameworks across Germany, France, and Italy are creating equipment demand for contaminated polymer streams.
- Pharmaceutical hot-melt extrusion:FDA 21 CFR compliance requirements are opening specialized system demand for continuous drug manufacturing applications.
- Micro-compounding precision:Engineering plastics processors in medical device and electronics verticals require sub-kilogram batch consistency that conventional systems cannot deliver.
Industry Challenges
- Interdisciplinary engineering talent scarcity:System design requires simultaneous expertise in polymer rheology, thermal management, and mechanical drive systems that few training programs integrate.
- Legacy control system integration:Brownfield installations must bridge proprietary PLC architectures with modern Industry 4.0 data protocols without disrupting validated production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twin Screw Extruders Market |
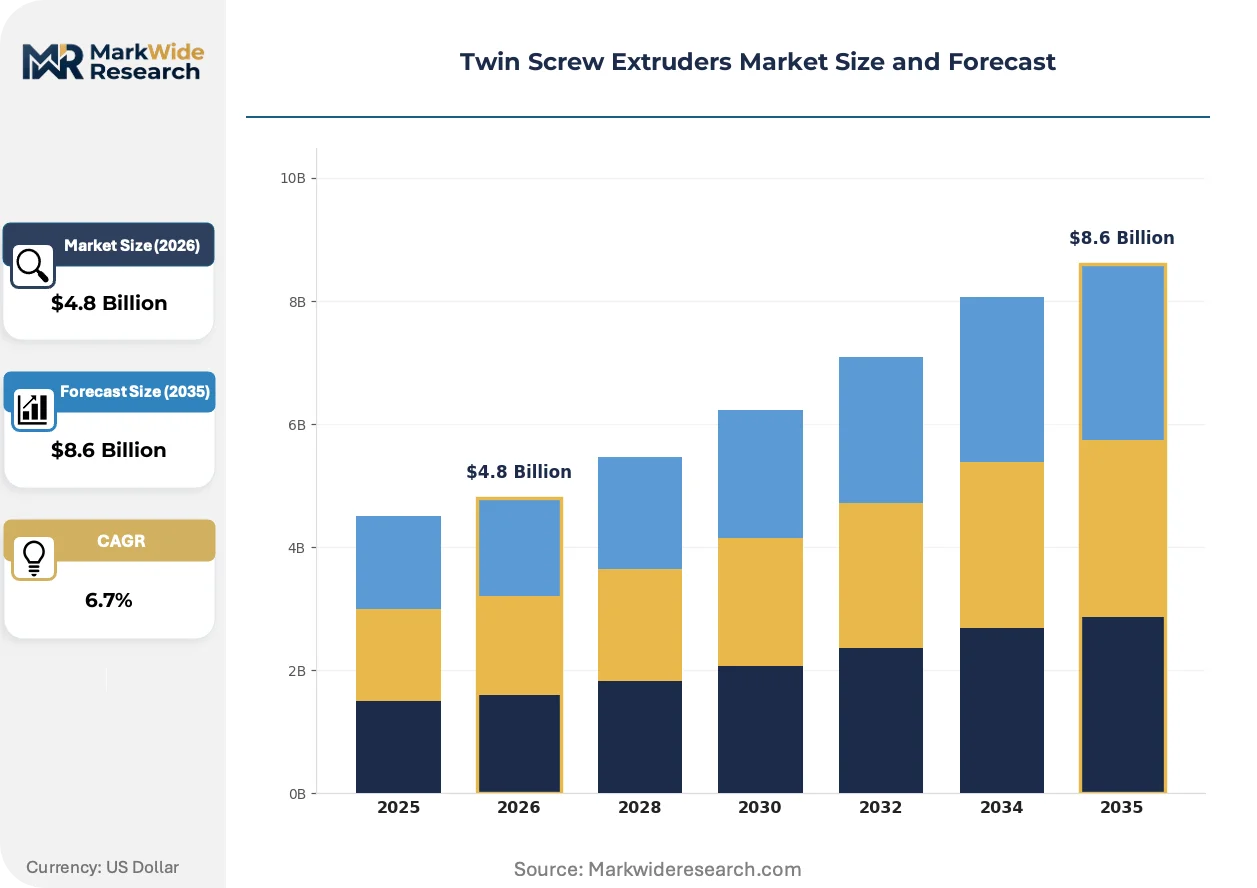
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corotating, Counterrotating, Co-extruders, Side-Feed Material: Polymer, Rubber, Food, Chemical Application: Compounding, Mixing, Pelletizing, Coating End User: Packaging, Automotive, Construction, Electronics |
| Companies Covered | Coperion GmbH, KraussMaffei Group, Leistritz Extrusionstechnik GmbH, The Japan Steel Works Ltd., Bühler Group, Milacron, Battenfeld-Cincinnati, CPM Extrusion Group, Nanjing Jieya Extrusion Equipment Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twin Screw Extruders Market Strategic Shifts
Digital twin simulation and predictive maintenance algorithms are compressing commissioning timelines while enabling remote process optimization. Equipment manufacturers are embedding sensor arrays directly into barrel sections and screw shafts to capture real-time rheological data.
Adaptive screw geometry systems are integrating electrically actuated kneading blocks that reconfigure flight profiles during operation without mechanical changeovers. Medical device compounders in Switzerland and Germany are piloting these architectures for multi-product campaigns. The technology is integrating process development and production phases into unified continuous workflows that eliminate scale-up validation bottlenecks.
ECHA's SCIP database requirements under the Waste Framework Directive are forcing extrusion operators to document polymer additive migration characteristics across entire supply chains. Compounders serving automotive and electronics verticals must now retrofit existing lines with enhanced material tracking infrastructure. German and French processors are responding fastest, driven by OEM audit requirements that cascade from Brussels regulatory implementation.
Compounders are unbundling after-sales service contracts from equipment purchases, preferring performance-based maintenance agreements indexed to uptime guarantees. This shift disrupts traditional distributor channels that historically bundled spare parts, training, and technical support. The transformation is most visible in Germany's automotive supply base, where Tier 1 suppliers negotiate outcome-based service level agreements directly with machinery makers.
Twin Screw Extruders Market Segmentation
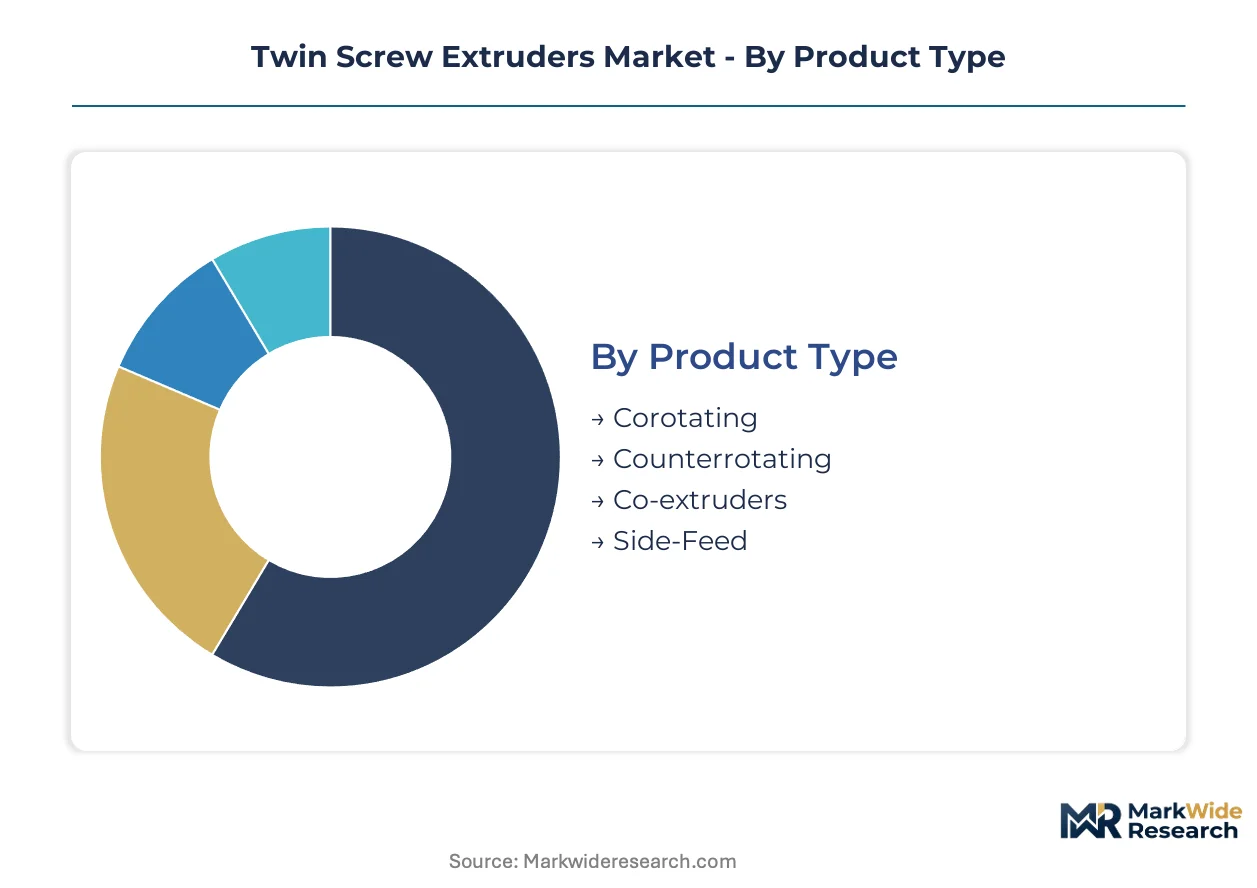
Twin screw extruder segmentation reveals divergent equipment architectures optimized for shear intensity, thermal profile, and residence time control. Each category reflects distinct processing physics that dictate capital allocation patterns across polymer compounders and specialty material processors.
Product Type:
Standardized corotating designs dominate high-volume polymer compounding, while specialized counterrotating and co-extrusion architectures command premium positioning for shear-sensitive or multi-layer applications.
- Corotating:Intermeshing screws rotate in the same direction, delivering self-wiping action that prevents material stagnation and ensures throughput consistency in continuous polymer compounding. Demand concentrates in Germany's Rhine-Ruhr automotive supply chain, where OEM lightweighting mandates require long-fiber reinforced thermoplastic processing at L/D ratios exceeding 40:1.
- Counterrotating:Screws turn in opposite directions, generating lower shear and reduced heat buildup suited to temperature-sensitive PVC, wood-plastic composites, and devolatilization tasks. European window profile extruders in Austria and Germany favor these systems for rigid PVC formulations where thermal degradation risks override throughput priorities.
- Co-extruders:Enable simultaneous processing of multiple polymer streams through dedicated barrels for multi-layer film, sheet, and pipe applications.
- Side-Feed:Permit downstream injection of fillers, fibers, or additives without disrupting established melt profiles in masterbatch production.
Leading the category by volume: Corotating. Growing fastest: Side-Feed.
Material:
Material-driven segmentation tracks feedstock rheology, thermal stability, and regulatory compliance burdens that reshape screw geometry and barrel alloy specifications.
- Polymer:Thermoplastic and thermoset processing commands the largest equipment footprint, spanning commodity resins through high-performance engineering plastics. Germany's automotive Tier 1 suppliers drive specification intensity here, with REACH-mandated recycled content verification forcing retrofits to existing extrusion lines.
- Rubber:Continuous mixing and devulcanization applications require specialized screw profiles with extended feed sections and controlled compression ratios. Southeast Asian tire manufacturers in Thailand and Indonesia are expanding capacity for silica-reinforced compounds that demand precise temperature management.
- Food:Extrusion cooking and texturization of starches, proteins, and cereals operates under strict hygiene protocols with FDA and EFSA compliance requirements.
- Chemical:Reactive extrusion for polymerization, grafting, and controlled degradation applies continuous processing to batch chemical synthesis.
Polymer generates the largest installed base. Food applications are climbing fastest on plant-based protein expansion.
Application:
Application segmentation distinguishes between value-added processing steps, with compounding and pelletizing representing capital-intensive entry points versus mixing and coating as downstream optimization stages.
- Compounding:Incorporates additives, fillers, and reinforcements into base polymers to achieve specified mechanical, thermal, or aesthetic properties. China's GB standards for recycled polymer content are accelerating equipment upgrades among compounders serving electronics and automotive export markets.
- Pelletizing:Converts melt streams into uniform solid feedstock for subsequent injection molding or extrusion, with underwater and strand-cut variants tailored to polymer viscosity. Italian compounders near Milan are investing in pelletizing-integrated lines to serve Mediterranean packaging converters.
- Mixing:Achieves dispersive and distributive homogenization without necessarily altering material form for intermediate processing stages.
- Coating:Applies polymer layers onto substrates including wire, cable, and metal strip through crosshead die configurations.
Compounding holds the largest revenue share. Pelletizing is expanding most quickly on recycled feedstock processing demand.
End User:
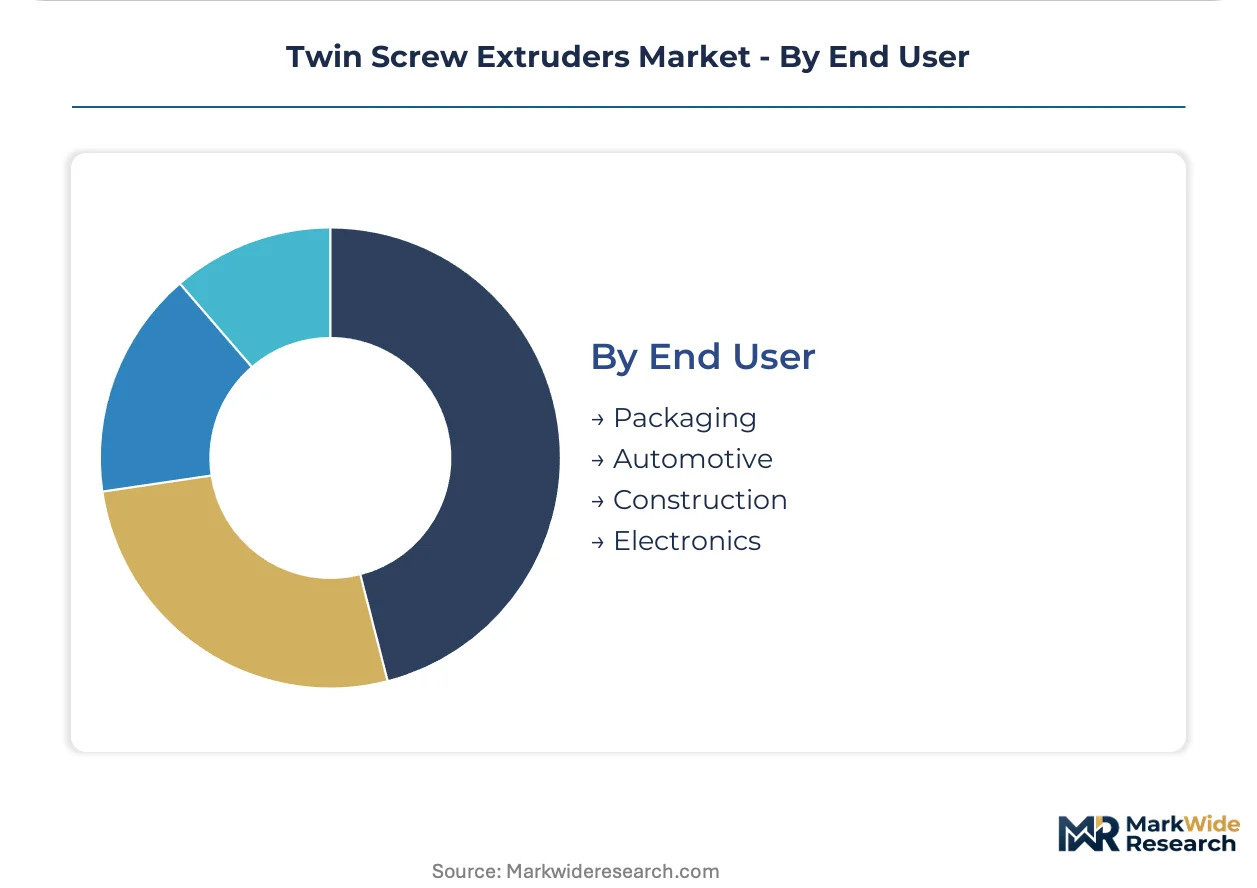
End-user segmentation maps equipment specifications to industry-specific regulatory frameworks, with automotive and packaging imposing the most stringent material traceability requirements.
- Automotive:Lightweighting mandates and interior air quality standards drive demand for long-fiber reinforced thermoplastics and low-VOC bioplastics. European OEMs audit Tier 1 suppliers for ECHA SCIP database compliance, forcing extrusion line retrofits with enhanced additive migration tracking.
- Packaging:Food-contact safety, barrier performance, and recyclability specifications shape equipment selection for film, sheet, and rigid container production. France's extended producer responsibility frameworks are mandating post-consumer recycled content thresholds that favor specialized devolatilization extruders.
- Construction:Pipe, profile, and weatherstrip extrusion for infrastructure applications emphasizes durability and weathering resistance over precision.
- Electronics:Compounding of flame-retardant and conductive polymers for connectors, housings, and cable insulation requires cleanroom-compatible architectures and lot-level traceability.
Automotive leads by capital expenditure intensity. Packaging is gaining share fastest on circular economy regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures the majority of precision twin screw extrusion systems while China and the United States absorb the largest installed base volumes. Production clusters concentrate near polymer research infrastructure and automotive OEM supply chains.
Germany
Automotive lightweighting mandates from BMW and Volkswagen drive specification intensity for long-fiber reinforced thermoplastic systems. REACH registration protocols under ECHA enforcement require compounders to verify recycled content traceability. The Rhine-Ruhr corridor hosts machinery makers adjacent to polymer research institutes, compressing R&D-to-commercialization cycles for next-generation extrusion architectures.
China
Domestic compounding capacity expansion for electronics and automotive export markets sustains equipment procurement. SAMR enforcement of GB standards for food-contact plastics and NMPA medical device material traceability rules raise compliance barriers for imported systems. The Yangtze River Delta concentration of compounders near Shanghai drives demand for high-throughput pelletizing-integrated lines.
United States
Pharmaceutical hot-melt extrusion for continuous drug manufacturing opens specialized system demand. FDA 21 CFR compliance requirements add a parallel regulatory track for healthcare applications. The Gulf Coast petrochemical corridor supports compounders serving packaging converters with post-consumer recycled feedstock processing equipment.
Japan
Precision micro-compounding for engineering plastics in medical device and electronics verticals requires sub-kilogram batch consistency. METI industrial policy supports advanced materials processing equipment development. The Nagoya-Toyota industrial zone anchors demand for cleanroom-compatible extrusion systems serving semiconductor packaging compounders.
Italy
Extended producer responsibility frameworks mandate post-consumer recycled content thresholds in packaging applications. France's regulatory pressure cascades into Italian compounder equipment upgrade cycles. The Milan-Turin industrial corridor concentrates pelletizing-integrated line investments serving Mediterranean packaging converters.
Twin Screw Extruders Market Competitive Environment
The competitive structure tilts toward integrated systems specialists with captive polymer process knowledge. German and Swiss machinery builders hold premium positioning through proximity to automotive OEM specification-setting. Three archetypes dominate: full-line integrators with compounding system expertise, precision specialists serving medical-grade applications, and scale-driven manufacturers addressing commodity polymer volumes. Strategic moves center on modular subsystem unbundling and performance-based service contracting indexed to uptime guarantees.
Among German-based integrated specialists, Coperion GmbH and KraussMaffei Group occupy positions reflecting deep compounding system heritage, while Leistritz Extrusionstechnik GmbH exemplifies the precision micro-compounding archetype for engineering plastics applications. These entities anchor the premium tier through proximity to Rhine-Ruhr automotive specification-setting and direct OEM audit relationships.
| Leading Market Players |
|---|
| Coperion GmbH |
| KraussMaffei Group |
| Leistritz Extrusionstechnik GmbH |
| The Japan Steel Works Ltd. |
| Bühler Group |
| Milacron |
| Battenfeld-Cincinnati |
| CPM Extrusion Group |
| Nanjing Jieya Extrusion Equipment Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal circular economy protocols gate qualified supply access for extrusion systems processing post-consumer recycled feedstocks, with premium-tier pricing reserved for architectures demonstrating ECHA SCIP database compliance and REACH-registered material traceability. OEM audit requirements cascade from Brussels through Tier 1 automotive suppliers, bifurcating equipment vendors into certified premium providers and excluded standard-tier competitors.
Pricing Analysis
Margin tightening in standard-grade extrusion systems reflects Chinese manufacturer price competition and commoditization of corotating designs below L/D 40:1. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade ISO 14644-1 compliant systems from automotive compounding lines and basic masterbatch equipment. Cost compression accelerates in standard tiers as Nanjing Jieya and domestic Chinese producers expand capacity for commodity polymer processing. Tier 1 automotive suppliers demonstrate lowest price sensitivity due to OEM audit compliance requirements, while packaging converters in Southern Europe exhibit highest sensitivity to capital expenditure timing.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and China anchor hub-and-spoke patterns for precision screw elements and bimetallic barrel liners. Critical inputs draw from concentrated European and Japanese metallurgical suppliers for nitrided alloys, plus specialized drive system components from German and Swiss electromechanical manufacturers. Single-source vulnerability concentrates in bimetallic liner production, where two Japanese suppliers control premium corrosion-resistant formulations. Distribution runs through machinery maker direct channels for premium systems, with third-party industrial distributors handling spare parts and standard-tier equipment in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin simulation and adaptive screw geometry architectures are displacing legacy fixed-geometry systems, compressing commissioning timelines and enabling multi-product campaigns without mechanical changeovers.
For Market Incumbents: Hedge against modular subsystem unbundling by acquiring precision sensor and control technology providers, securing proprietary data protocol ecosystems that lock compounders into integrated upgrade paths. Defend premium positioning through captive polymer process knowledge centers in the Rhine-Ruhr corridor, reinforcing direct OEM audit relationships that Chinese competitors cannot replicate. Prioritize performance-based service contracts indexed to uptime guarantees, displacing traditional distributor channels before competitors establish equivalent outcome-based offerings. For New Entrants and Emerging Players: Adaptive screw geometry with electrically actuated kneading blocks offers technology-first wedge into pharmaceutical hot-melt extrusion and medical device micro-compounding, segments where FDA 21 CFR compliance barriers deter established commodity players. Target Swiss and German medical device compounders piloting unified continuous workflows, where scale-up validation bottlenecks create urgent demand for process-development-integrated production systems. Pursue direct sales partnerships with polymer research institutes, leveraging co-development credibility to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: First commercial deployment of real-time rheological sensor arrays embedded in barrel sections is the leading indicator that predictive maintenance algorithms have crossed from pilot to revenue-generating adoption, signaling inflection in equipment-as-a-service business model viability. Frame long-term positioning around five-to-ten year extended producer responsibility framework expansion across European packaging markets, prioritizing acquisition targets with proven contaminated polymer stream processing architectures. Monitor German automotive OEM Tier 1 supplier consolidation patterns as early signal for compounding equipment procurement centralization.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Subsystem Unbundling | Enables plug-and-play procurement patterns as compounders reject monolithic turnkey installations. |
| Performance-Based Service Contracting | Indexes maintenance agreements to uptime guarantees, disrupting traditional spare parts bundling in Germany's automotive supply base. |
| Adaptive Screw Geometry Commercialization | Integrates process development and production phases for Swiss medical device multi-product campaigns. |
| Post-Consumer Recycled Feedstock Certification | Positions systems for ECHA SCIP database compliance under EU Green Deal extended producer responsibility frameworks. |
| Pharmaceutical Hot-Melt Extrusion Specialization | Captures FDA 21 CFR compliant system demand for continuous drug manufacturing applications. |
Study Parameters
Document review covered regulatory filings with ECHA and FDA, machinery maker technical specifications, and polymer compounder procurement disclosures, complemented by interviews with plant engineers at automotive Tier 1 suppliers, technical R&D directors at German extrusion system manufacturers, aftermarket service heads at distributor networks, and procurement leads at packaging converters. Secondary validation drew from customs trade data for extrusion equipment imports, SEC filings of listed machinery makers, and industry association capacity surveys. Bottom-up equipment shipment tracking and top-down polymer compounding capacity expansion analysis were triangulated against disclosed order backlogs.
Segment-level outputs across the projection horizon reflect modeled interactions between product type architectures, material rheology requirements, application processing intensity, and end-user regulatory compliance burdens. The analytical framework incorporated screw geometry specifications, L/D ratio distributions, and cleanroom compatibility tiers as industry-specific segmentation dimensions. CAGRs were derived from regression analysis of historical equipment procurement patterns against polymer demand forecasts and regulatory implementation timelines, with particular weighting for REACH registration protocol phase-ins and China's GB standards enforcement trajectory.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated extended producer responsibility framework adoption or supply chain disruption in Japanese bimetallic liner production. Outputs reflect documented assumptions regarding regulatory implementation schedules, OEM lightweighting mandate continuity, and polymer research institute R&D-to-commercialization cycle stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Steel Processing Market
Industrial Materials
Hose Reinforcement Wire Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Global Friction Materials Market
Industrial Materials
Anode Carbon Block Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
Global High Pressure Seals Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
Magnet Rings Market
Industrial Materials
Catalyst Bins Market
Industrial Materials
Wood Shavings Market
Industrial Materials
United States Graphite Electrodes Market
Industrial Materials
Weatherstrip Seal Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Modified Wood Market