
 Global Isocyanate Market | 2026-2036
Global Isocyanate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Isocyanate Market Intelligence
The ISO 14001 environmental management certification requirement for Tier 1 automotive suppliers is collapsing the distinction between commodity and specialty isocyanate producers. This standard mandates rigorous environmental performance, impacting raw material sourcing. Covestro AG leverages its large-scale production of MDI and TDI to serve high-volume construction and automotive markets. BASF SE, in contrast, differentiates with a broad portfolio of specialized polyurethane systems for coatings and adhesives.
Isocyanates are a family of highly reactive chemical compounds defined by the functional group -N=C=O, with diisocyanates being the most common type. Their principal industrial function is serving as a monomer in the production of polyurethanes through reaction with polyols. Methylene diphenyl diisocyanate (MDI) and toluene diisocyanate (TDI) represent the largest product segments by volume, primarily for foam production. The construction end-user sector remains the dominant application area, driven by demand for rigid foams in building insulation.
Regulatory frameworks from the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) under REACH impose stringent controls on isocyanate handling and worker exposure due to their toxicity. In China, Ministry of Ecology and Environment (MEE) directives on volatile organic compound (VOC) emissions influence formulations for paints and coatings. Producers must now navigate a complex trade-off between material performance, cost, and escalating environmental compliance requirements across key jurisdictions.
Market Dynamics
Escalating environmental compliance mandates from regulators like the European Chemicals Agency and China's Ministry of Ecology and Environment are the central force shaping the market. Producers face a complex trade-off between material performance, cost, and adherence to tightening chemical safety standards across key jurisdictions.
Growth Catalysts
- Building Energy Codes:Stricter energy efficiency standards in construction mandate high-performance insulation, directly benefiting polyurethane rigid foam applications.
- Automotive Lightweighting:The automotive sector's push for vehicle weight reduction increases use of polyurethane foams in seating and interior components.
- Specialty Electronics Applications:China's electronics manufacturing hubs drive demand for specialized isocyanate formulations used in adhesives and protective coatings.
Market Restraints
- Feedstock Price Volatility:The cost structure is tied to volatile pricing of petrochemical inputs like benzene and toluene, creating margin pressure for producers.
- Worker Exposure Regulations:Stringent occupational safety rules from the EPA and ECHA impose significant handling and ventilation costs due to isocyanate toxicity.
- Non-Isocyanate Substitutes:The development of non-isocyanate polyurethanes (NIPUs) presents a long-term substitution threat, particularly in consumer-facing applications.
Strategic Opportunities
- Cold Chain Logistics:Expansion of refrigerated transport for pharmaceuticals and food offers a growth vector for high-efficiency rigid polyurethane foam insulation.
- Chemical Recycling Processes:EU policies on circularity create opportunities to develop methods for recovering monomers from end-of-life polyurethane products.
- Smart Insulation Materials:Integrating sensors with polyurethane foams can create intelligent building materials that monitor thermal performance and structural health.
Industry Challenges
- High Capital Intensity:The construction of world-scale MDI and TDI production facilities requires substantial capital investment and long lead times, creating high barriers to entry.
- Navigating Divergent Regulations:Producers must manage a complex and evolving landscape of chemical regulations, such as REACH and MEE VOC rules, which differ across key markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Isocyanate Market |
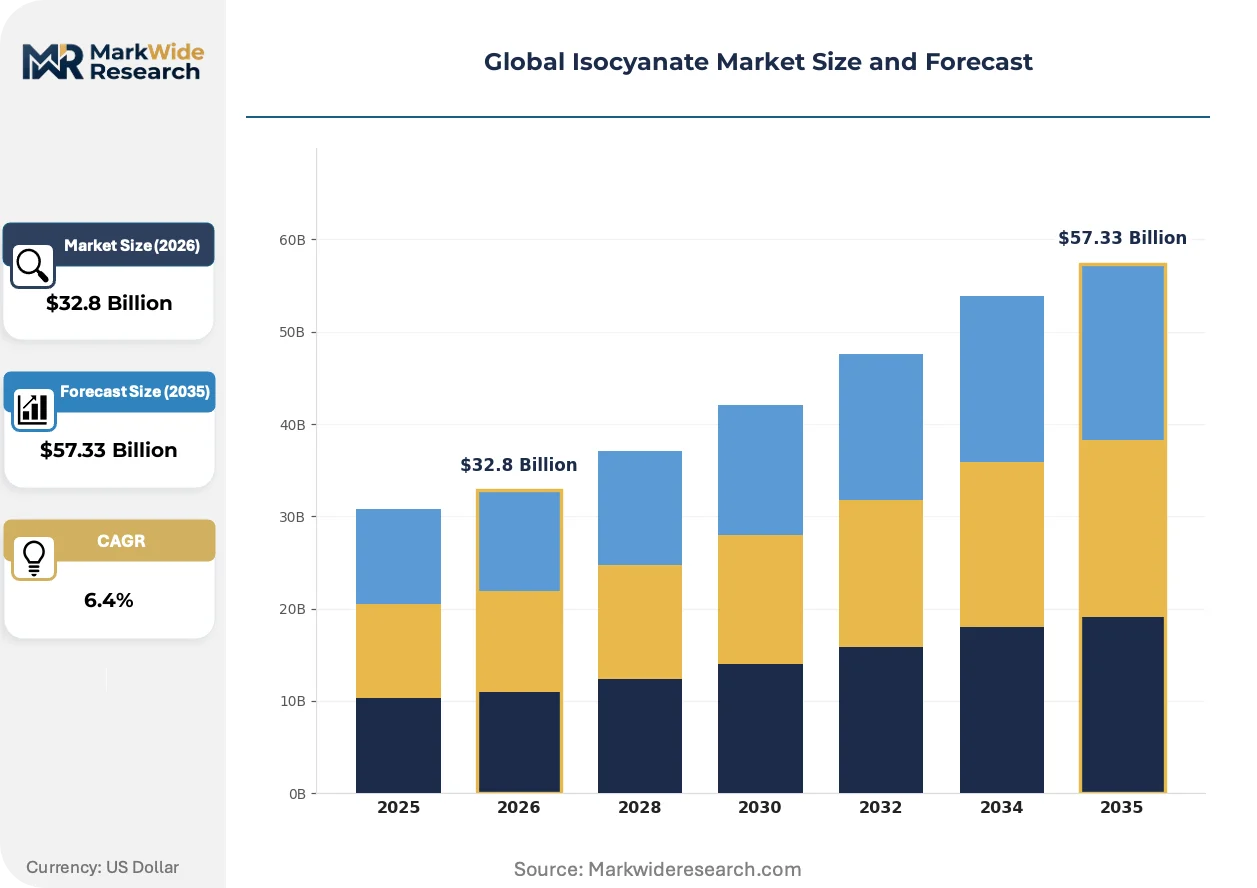
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MDI, TDI, HDI, IPDI, Polymeric Isocyanates Application: Foam Production, Coatings, Adhesives Sealants, Elastomers, Paints End User Industry: Construction, Automotive OEMs, Furniture Manufacturing, Footwear, Electronics Form: Liquid, Solid, Powder, Prepolymers, Blends |
| Companies Covered | Evonik Industries AG, DowDuPont Inc., BASF SE, LANXESS AG, Wanhua Chemical Group Co. Ltd, Covestro AG, Mitsui Chemicals Inc., Asahi Kasei Corporation, Huntsman International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Isocyanate Market Strategic Shifts & Innovations
A fundamental shift toward sustainable chemistry and performance differentiation is underway. This movement extends beyond bio-based feedstocks to encompass process innovations that reduce environmental footprints and enable new functionalities in end-use applications like coatings and foams.
Bio-based isocyanates derived from renewable feedstocks offer a sustainable alternative to traditional petrochemical-based monomers. Adhesives and coatings manufacturers are leading the adoption to meet consumer demand for greener products and comply with VOC regulations. This development is fragmenting the commodity-driven market, creating a premium niche for materials with verified environmental credentials.
The European Union's new REACH restriction on diisocyanates mandates comprehensive training and certification for all professional and industrial users. This regulation fundamentally alters downstream handling procedures to protect worker health from respiratory and skin sensitization risks. Small-to-medium enterprises in sectors like construction and automotive repair face the greatest compliance burden, potentially accelerating a shift to lower-isocyanate formulations.
Certification-driven procurement is becoming a decisive factor, particularly for Tier 1 automotive suppliers. The mandate for ISO 14001 environmental management certification is displacing purchasing decisions based solely on price and volume. This shift is most pronounced in the European automotive sector, where OEMs cascade sustainability scorecards down to their raw material suppliers, including isocyanate producers.
Global Isocyanate Market Segmentation
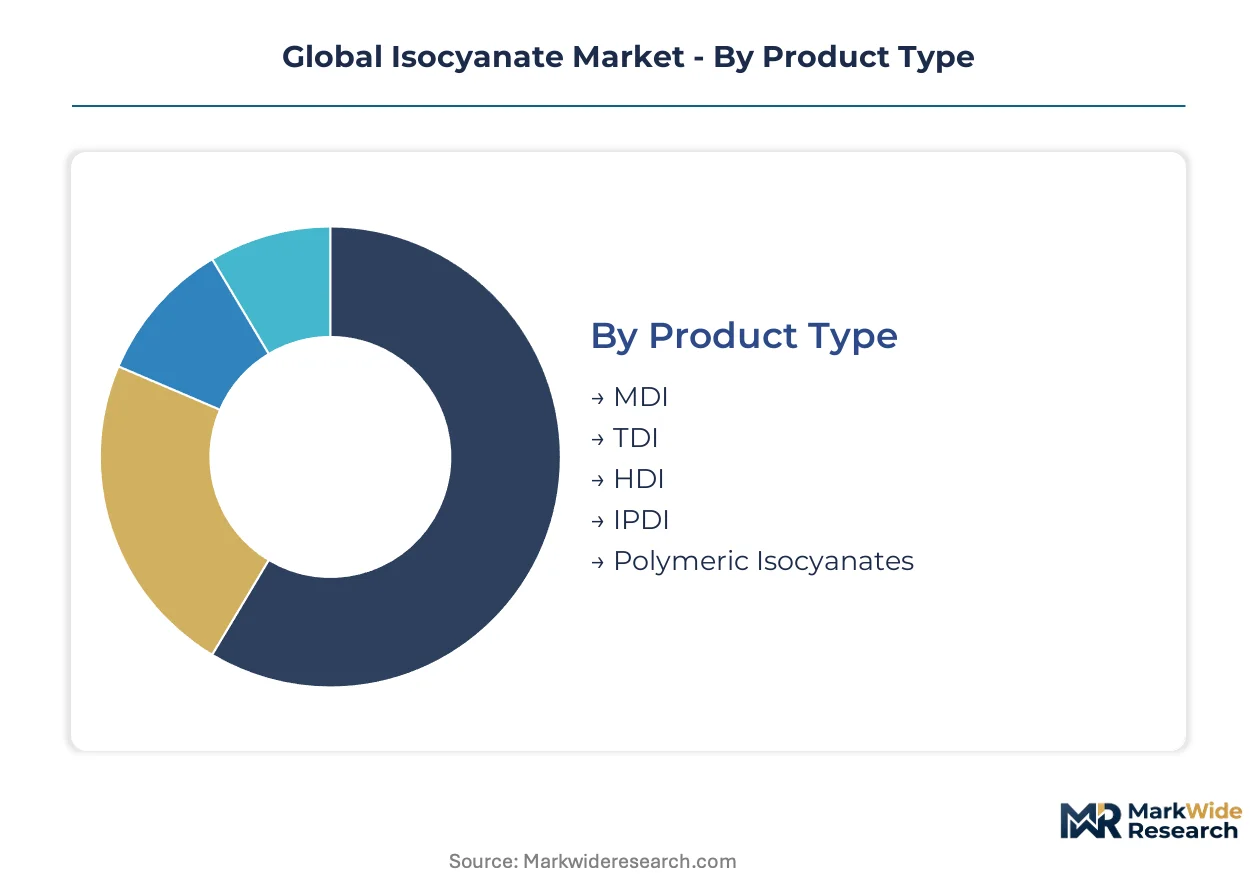
The global isocyanate market's structure reflects diverse industrial requirements and evolving regulatory landscapes, necessitating a granular understanding of product types, applications, end-user industries, and forms. This segmentation highlights the specialized nature of demand and supply dynamics across various sectors, from high-volume construction to niche electronics applications.
Product Type:
The distribution of isocyanate products through various industrial channels reveals distinct end-use preferences and regulatory compliance needs for each type.
- MDI:Methylene diphenyl diisocyanate is a primary building block for rigid and flexible polyurethane foams, characterized by its low volatility and high reactivity. Demand is concentrating in the construction sector for insulation materials, driven by stringent building energy codes across Europe and North America.
- TDI:Toluene diisocyanate primarily serves in the production of flexible polyurethane foams, particularly for automotive seating and furniture cushioning, valued for its elasticity. The automotive sector's push for lightweighting in Germany and China increases TDI consumption for interior components.
- HDI:Hexamethylene diisocyanate is a key component in high-performance polyurethane coatings and adhesives, offering excellent UV resistance and durability.
- IPDI:Isophorone diisocyanate contributes to specialty coatings and elastomers, providing superior hardness and chemical resistance for industrial applications.
- Polymeric Isocyanates:These are multi-functional isocyanates used in rigid foam formulations and binders, offering enhanced cross-linking and improved mechanical properties.
By volume, MDI leads the market. By growth pace, HDI is ahead, particularly in high-performance coating formulations.
Application:
The functional utility of isocyanates varies significantly across their diverse applications, influencing material selection based on performance requirements and processing characteristics.
- Foam Production:This application segment utilizes isocyanates, primarily MDI and TDI, to create rigid and flexible polyurethane foams through reaction with polyols. The construction industry's need for high-performance thermal insulation in European buildings drives significant demand for rigid foams.
- Coatings:Isocyanates provide durability, chemical resistance, and UV stability to polyurethane coatings, essential for protective and decorative finishes. China's industrial manufacturing hubs are driving demand for specialized coating formulations in electronics and automotive sectors.
- Adhesives Sealants:Polyurethane-based adhesives and sealants, formulated with various isocyanates, offer strong bonding and flexibility for construction and automotive assembly.
- Elastomers:Isocyanates are crucial for producing polyurethane elastomers, which exhibit high elasticity, abrasion resistance, and load-bearing capabilities for industrial components.
- Paints:In paint formulations, isocyanates enhance adhesion, hardness, and weatherability, especially for automotive and industrial protective coatings.
Foam production commands the largest share of isocyanate applications. Coatings are expanding most quickly, driven by industrial and automotive needs.
End User Industry:
The customer types served by the isocyanate market are distinct, each with specific requirements for material performance, regulatory compliance, and cost structures.
- Construction:This sector utilizes isocyanates extensively in rigid polyurethane foams for building insulation, roofing, and structural panels. Stricter energy efficiency mandates from the European Union and the US Environmental Protection Agency directly benefit demand for high-performance insulation materials.
- Automotive OEMs:Original Equipment Manufacturers use isocyanates for flexible foams in seating, interior components, and lightweight structural parts. The global automotive industry's focus on vehicle weight reduction to improve fuel efficiency and electric vehicle range boosts polyurethane foam consumption.
- Furniture Manufacturing:Flexible polyurethane foams are widely used in furniture for cushioning, mattresses, and upholstery, providing comfort and durability.
- Footwear:Isocyanates are critical in the production of polyurethane soles and components for athletic and casual footwear, offering flexibility and impact absorption.
- Electronics:China's advanced electronics manufacturing hubs demand specialized isocyanate formulations for potting compounds, adhesives, and protective coatings in sensitive electronic devices.
The construction sector represents the largest end-user segment for isocyanates. Automotive OEMs are experiencing significant growth due to lightweighting initiatives.
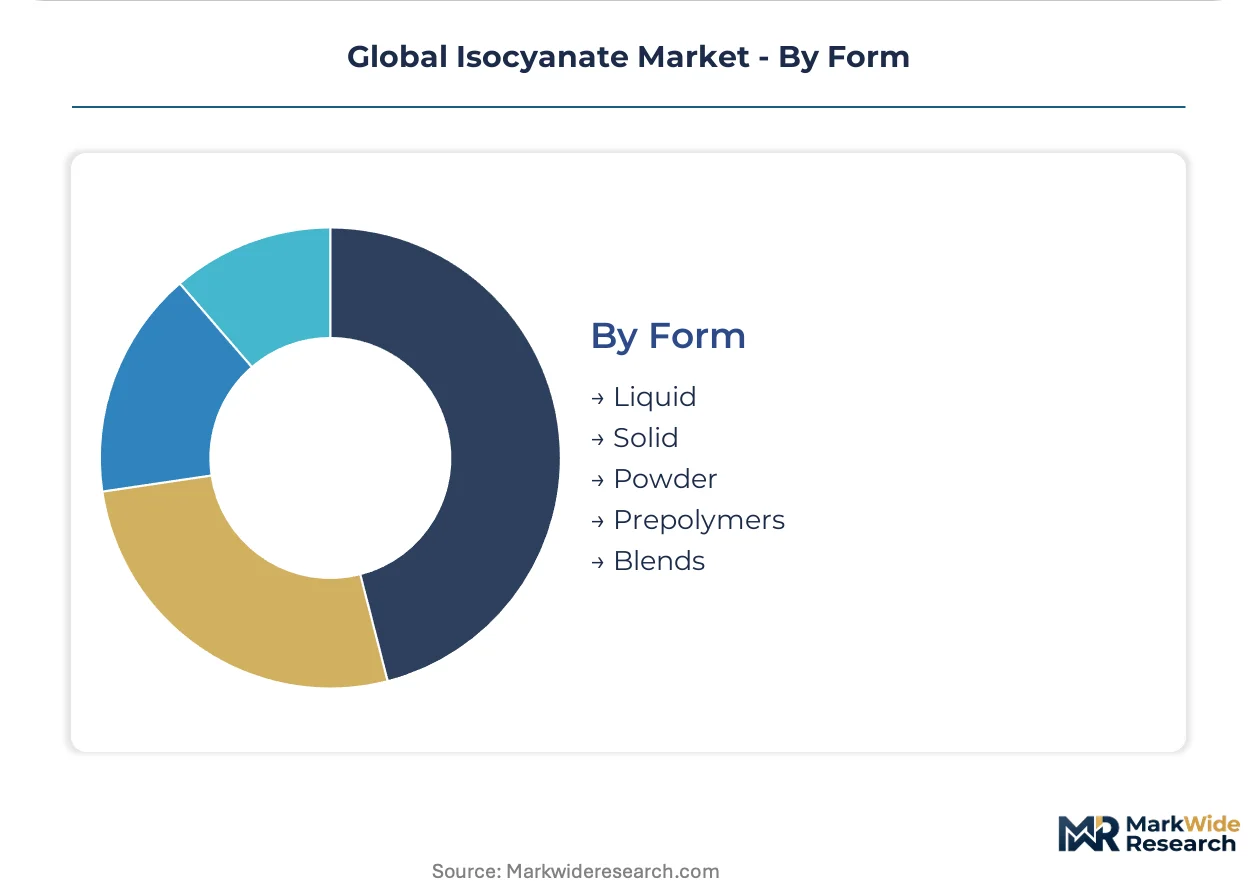
Form:
The physical form of isocyanates influences their handling, processing, and suitability for different manufacturing processes, impacting supply chain logistics and safety protocols.
- Liquid:Liquid isocyanates, such as MDI and TDI, are the most common form, offering ease of handling and precise dosing in large-scale polyurethane production. Their use dominates in continuous processing for foams and coatings, particularly in industrial settings across Germany and China.
- Prepolymers:These are partially reacted isocyanates with polyols, designed to reduce volatility and improve processing safety and performance in specific applications. Demand for prepolymers is rising in specialty adhesive and sealant formulations to meet stringent worker exposure regulations from the European Chemicals Agency.
- Solid:Solid isocyanates are used in niche applications where low volatility and specific curing profiles are required, often in powder coatings or specialty resins.
- Powder:Powdered isocyanates find application in powder coatings and certain adhesive systems, providing advantages in storage stability and formulation flexibility.
- Blends:Isocyanate blends combine different types or forms to achieve tailored performance characteristics, optimizing reactivity and final product properties for specific customer needs.
Liquid forms of isocyanates account for the highest market share. Prepolymers are exhibiting the steepest expansion trajectory, driven by safety and performance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in advanced manufacturing hubs and construction sectors drives the global isocyanate market. These regions exhibit strong demand for high-performance insulation, lightweight automotive components, and specialized electronic materials. Regulatory compliance and sustainability initiatives also significantly influence regional market dynamics and investment decisions.
China
China's advanced manufacturing hubs drive significant demand for specialized isocyanate formulations in electronics and automotive applications. The Ministry of Ecology and Environment (MEE) directives on volatile organic compound (VOC) emissions influence paint and coating formulations. Industrial clusters in the Yangtze River Delta and Pearl River Delta are central to this consumption, especially for polyurethane coatings and adhesives.
Germany
Germany's automotive and construction industries are key consumers of isocyanates, particularly for flexible foams in vehicles and rigid foams for building insulation. The European Chemicals Agency (ECHA) and REACH regulations impose stringent controls on chemical handling and worker exposure. Major chemical production sites in the Ruhr area and Bavaria supply the region's industrial base.
United States
The United States construction sector demands substantial volumes of rigid polyurethane foams for high-performance insulation in residential and commercial buildings. The US Environmental Protection Agency (EPA) mandates stricter energy efficiency standards and worker exposure regulations. Industrial activity along the Gulf Coast and in the Midwest supports both raw material production and end-use manufacturing.
Japan
Japanese automotive and electronics sectors drive demand for high-performance isocyanate-based coatings and adhesives, emphasizing durability and precision. The Ministry of Economy, Trade and Industry (METI) promotes sustainable chemical management and industrial innovation. Manufacturing centers in the Kanto and Kansai regions are focal points for specialized polyurethane applications.
India
India's expanding construction and furniture manufacturing industries fuel the consumption of isocyanates, especially for flexible foams and insulation materials. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for construction materials and chemical products. Industrial zones in Gujarat and Maharashtra are emerging as key manufacturing and processing hubs.
Global Isocyanate Market Key Industry Players
Player mix skews toward large, integrated chemical producers with global footprints and significant production capacities. The market structure exhibits tiered consolidation, with a few dominant players controlling substantial market share for commodity isocyanates. Strategic archetypes include large-scale commodity suppliers and specialized system formulators. Dominant competitive moves include capacity expansion and portfolio diversification.
On the premium-tier vector, Covestro AG and BASF SE exemplify companies offering broad portfolios and specialized solutions, leveraging their extensive R&D capabilities. Wanhua Chemical Group Co. Ltd, a China-based entity, represents a rapidly expanding player in both commodity and specialty segments, challenging established incumbents with significant production scale. These companies anchor the industry's competitive dynamics, driving innovation in sustainable chemistry and high-performance applications.
| Leading Market Players |
|---|
| Evonik Industries AG |
| DowDuPont Inc. |
| BASF SE |
| LANXESS AG |
| Wanhua Chemical Group Co. Ltd |
| Covestro AG |
| Mitsui Chemicals Inc. |
| Asahi Kasei Corporation |
| Huntsman International LLC |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements, often with volume commitments, lock in both supply access and price visibility for large-scale industrial buyers. This contract structure mitigates short-term market volatility for MDI and TDI, ensuring consistent material flow to major polyurethane manufacturers.
Pricing Analysis
Cost-plus agreements, frequently indexed to crude oil and natural gas prices, dominate bulk isocyanate procurement. Price differentiation stems from product purity grades and certification levels, particularly for specialized HDI and IPDI formulations. Pricing softness reflects overcapacity in some commodity segments, especially for MDI from Chinese producers. Automotive OEMs and Tier 1 suppliers are highly price-sensitive, while specialty electronics manufacturers prioritize performance over cost.
Supply Chain Analysis
Just-in-time inventory strategies characterize large-volume isocyanate consumption by automotive and construction sectors, while specialty applications maintain strategic stockpiles. Geographic supply concentrates in China, Germany, and the United States, reflecting major production hubs. The industry relies heavily on petrochemical inputs like benzene, toluene, and propylene. Geopolitical trade restrictions present a structural risk to global material flows. Distribution runs through direct sales channels to large manufacturers and a network of specialized distributors for smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isocyanate market increasingly reflects a buyer-power shift, driven by the consolidation of Tier 1 automotive suppliers demanding higher sustainability standards.
For Market Incumbents: Consolidate production capabilities through strategic acquisitions in high-growth regions like Asia to leverage economies of scale. Invest in R&D for bio-based feedstocks to counter the long-term threat from non-isocyanate substitutes. Secure control over critical raw material supply chains to mitigate feedstock price volatility and ensure operational continuity.
For New Entrants and Emerging Players: Differentiate on sustainability credentials, focusing on low-VOC formulations or bio-based isocyanates for niche markets. Target smaller specialty adhesive and coating formulators who require customized solutions and technical support. A direct technical sales approach, emphasizing product performance and environmental compliance, offers a penetrable go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated specialty chemical producers with strong R&D pipelines in sustainable polyurethane technologies. These companies often possess robust intellectual property and command premium pricing for differentiated products. The long-term viability favors those capable of navigating tightening environmental regulations. A signal to watch is the widespread adoption of chemical recycling processes for end-of-life polyurethane products.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Increases supply to meet demand from China's electronics and automotive manufacturing hubs. |
| Bio-based Feedstock R&D | Addresses environmental compliance and consumer demand for greener polyurethane products. |
| Specialty Formulation Development | Captures premium margins in high-performance coatings and adhesives for electronics. |
| Chemical Recycling Investment | Aligns with EU circular economy policies, creating value from end-of-life polyurethane waste. |
| Digital Supply Chain Integration | Enhances transparency and efficiency in raw material sourcing and product distribution. |
Research Approach
A spread of perspectives from chemical engineers, procurement managers, regulatory compliance officers, and R&D directors converged on the working assumptions for this study. Primary interviews with these industry stakeholders provided qualitative insights, triangulated with quantitative data from secondary sources. This comprehensive approach ensured both bottom-up and top-down validation of market trends, drawing from ECHA reports, MEE directives, company financial statements, and industry association publications.
Market segmentation dimensions modeled included product type, application, end-user industry, form, and regional regulatory compliance across the analysis window. Compound annual growth rates were derived through a proprietary analytical framework, incorporating historical data and projected future trends. Key industry-specific forecast inputs included petrochemical feedstock prices and the impact of evolving energy efficiency mandates in construction.
Material uncertainties — such as geopolitical trade disputes or rapid technological breakthroughs in non-isocyanate polyurethanes — sit outside the modeled envelope of this report. Forecasts reflect assumptions documented at the time of publication, but remain dynamic. Revision becomes warranted when significant shifts in global energy prices or major regulatory overhauls cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Specialty Oils Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Global Acid Proof Lining Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Dynamite Market
Industrial Chemicals
Chlorine Trifluoride Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Process Chromatography Market
Industrial Chemicals
Nano-Bubble Generator Market