
 Hand Wrappers Market | 2026-2036
Hand Wrappers Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Wrappers Market Foresight
China is tilting its packaging machinery output toward semi-automatic and automatic wrapper systems for export markets. Signode Industrial Group leverages its steel and plastic strapping heritage to anchor industrial packaging channels with integrated wrapping solutions. Aetna Group sustains European manufacturing scale while competing aggressively in North American food service segments through specialized distributor partnerships. Intertape Polymer Group dominates pressure-sensitive tape adjacencies that extend naturally into hand wrapper film and paper categories.
Hand wrappers are portable or bench-mounted devices that apply stretch film, shrink film, or paper around palletized goods, individual products, or food items using manual crank, lever, or battery-assisted mechanisms with tension control typically ranging from 50% to 300% pre-stretch. Their primary commercial purpose is to secure loads for transport, extend shelf life through barrier protection, or present retail merchandise with tamper-evident sealing. Semi-automatic wraps lead unit volume in manufacturing end use where throughput demands outpace manual capacity but capital constraints block full automation. Shrink wraps command premium positioning in retail and gift packaging applications where optical clarity and printed branding justify higher material costs. Polypropylene film anchors the material mix across food packaging due to its balance of clarity, sealability, and compliance with FDA food-contact regulations.
FDA food-contact substance notifications govern material safety for hand wrappers serving direct food applications, while OSHA ergonomic standards influence equipment design for repetitive workplace use. The EU Packaging and Packaging Waste Regulation, adopted under the EU Green Deal framework, mandates recycled content thresholds that reshape material sourcing for exporters serving European e-commerce and retail channels. California's SB 54 extended producer responsibility law imposes phased recycling targets that cascade through domestic supply chains. Stakeholders must monitor how divergent state-level packaging laws across the United States fragment compliance costs versus federal preemption efforts that could standardize requirements.
Market Dynamics
Labor cost inflation across food service operations is accelerating the shift from manual wrapping stations toward semi-automatic and battery-assisted hand wrapper systems, compressing payback periods for equipment upgrades.
Growth Catalysts
- OSHA Ergonomic Mandates:Workplace safety standards in the United States are compelling quick-service restaurant chains to replace repetitive manual wrapping with mechanical assist devices, expanding equipment replacement cycles.
- Centralized Commissary Expansion:Food service operators are consolidating production into high-throughput facilities where semi-automatic wrappers anchor packaging lines, driving volume procurement of tension-controlled systems.
- California SB 54 Phased Targets:Extended producer responsibility laws are forcing packaging buyers to source recyclable film formats, creating compliance-driven demand for wrapper systems compatible with post-consumer content films.
Market Restraints
- Resin Price Volatility:Polypropylene and polyethylene feedstock fluctuations compress margin stability for film suppliers serving hand wrapper end users.
- Equipment Import Concentration:Semi-automatic system manufacturing clusters in China expose North American distributors to tariff and shipping cost variability.
- Biodegradable Film Performance Gap:Compostable alternatives to conventional stretch films exhibit inferior elongation and puncture resistance, limiting substitution in high-tension applications.
Strategic Opportunities
- Untapped Mexico Food Processing:Expanding tortilla and prepared food manufacturing in Guanajuato and Querétaro lacks localized wrapper equipment distribution, creating channel entry potential.
- Printed Shrink Film Branding:Retail and gift packaging segments are adopting high-clarity printed films that command premium positioning over plain stretch alternatives.
- Battery-Assist Technology Convergence:Lithium-ion power systems are merging with mechanical tension controls to enable cordless operation in remote catering and mobile food service contexts.
Industry Challenges
- Cross-Contamination Certification:FDA food-contact notifications require extensive migration testing timelines that delay new film formulations from reaching commercial deployment.
- Legacy Equipment Integration:Commissary kitchens operating mixed-vintage packaging lines face control-system incompatibility when upgrading to digitally tensioned wrapper units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Wrappers Market |
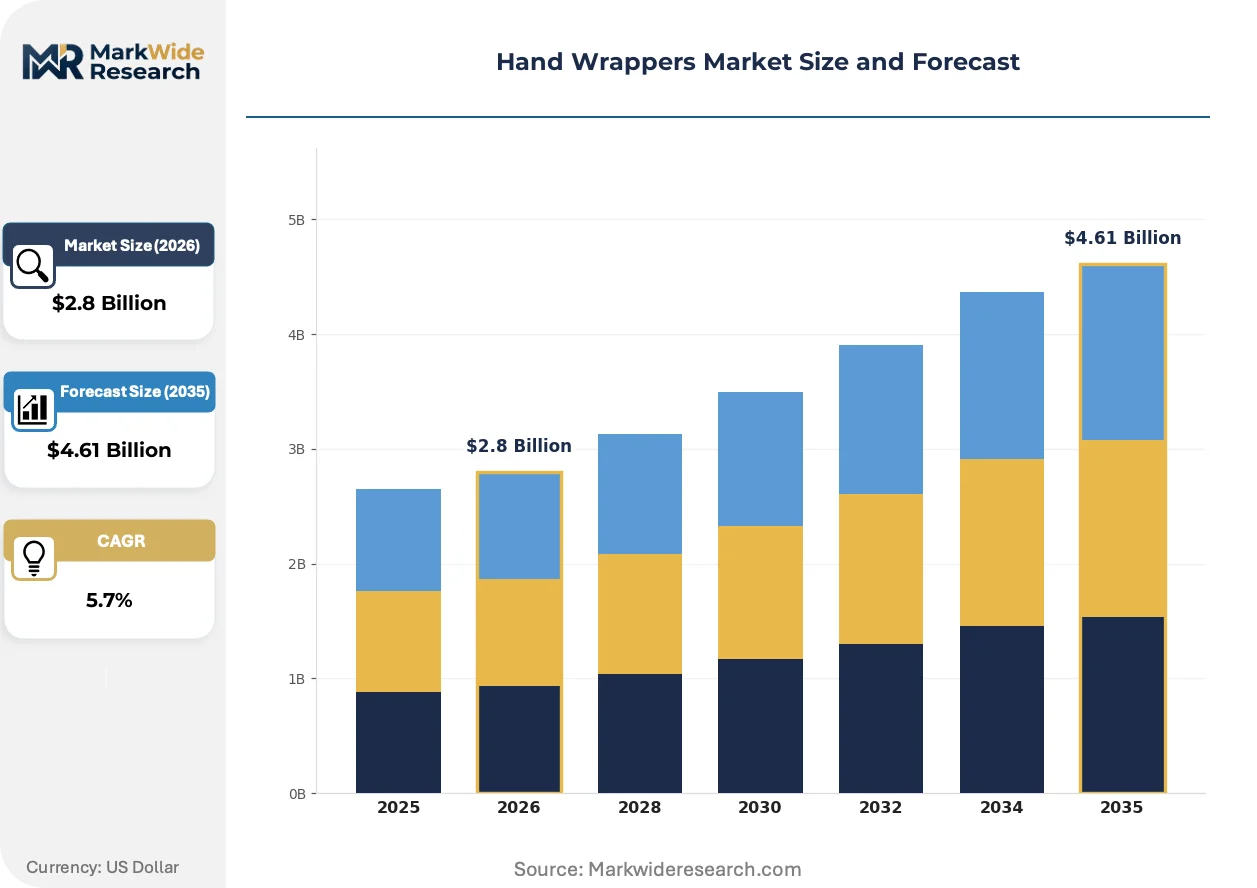
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Wraps, Automatic Wraps, Semi-Automatic Wraps, Shrink Wraps Application: Food Packaging, Retail Packaging, Industrial Packaging, Gift Packaging Material: Polypropylene, Polyethylene, Paper, Cellophane End User: Retail Stores, Food Service, Manufacturing, E-Commerce |
| Companies Covered | Signode Industrial Group, Aetna Group, PAC Worldwide Corporation, Intertape Polymer Group, M.J. Maillis Group, Shurtape Technologies, Tach-It, ProPack, Crown Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Wrappers Market Shifts & Advancements
Digital tension control and connected diagnostics are transforming hand wrappers from passive mechanical tools into data-generating assets that feed production optimization software.
Smart wrapper systems with embedded load sensors and Bluetooth connectivity are virtualizing quality assurance by transmitting wrap consistency metrics directly to commissary kitchen management platforms. Quick-service restaurant chains with centralized production facilities are piloting these units to reduce film waste and document compliance. Equipment vendors are compressing service intervals by enabling remote diagnostics that flag bearing wear and battery degradation before field failure.
The EU Packaging and Packaging Waste Regulation is mandating recycled content thresholds that reshape material sourcing for exporters serving European e-commerce and retail channels. Film suppliers must reformulate polypropylene grades to incorporate post-consumer resin without sacrificing clarity or seal strength. Hand wrapper equipment manufacturers are responding with expanded tension ranges to accommodate the variable elongation properties of recycled-content films.
Buyer consolidation among national food service distributors is compressing procurement cycles and unbundling after-sales service from equipment sales. Large distributors are demanding direct-to-warehouse fulfillment and centralized technical support, displacing the traditional territory-based dealer network. This pattern is most visible in the United States, where Sysco and US Foods volume commitments are reshaping vendor sales organization structures.
Hand Wrappers Market Segmentation
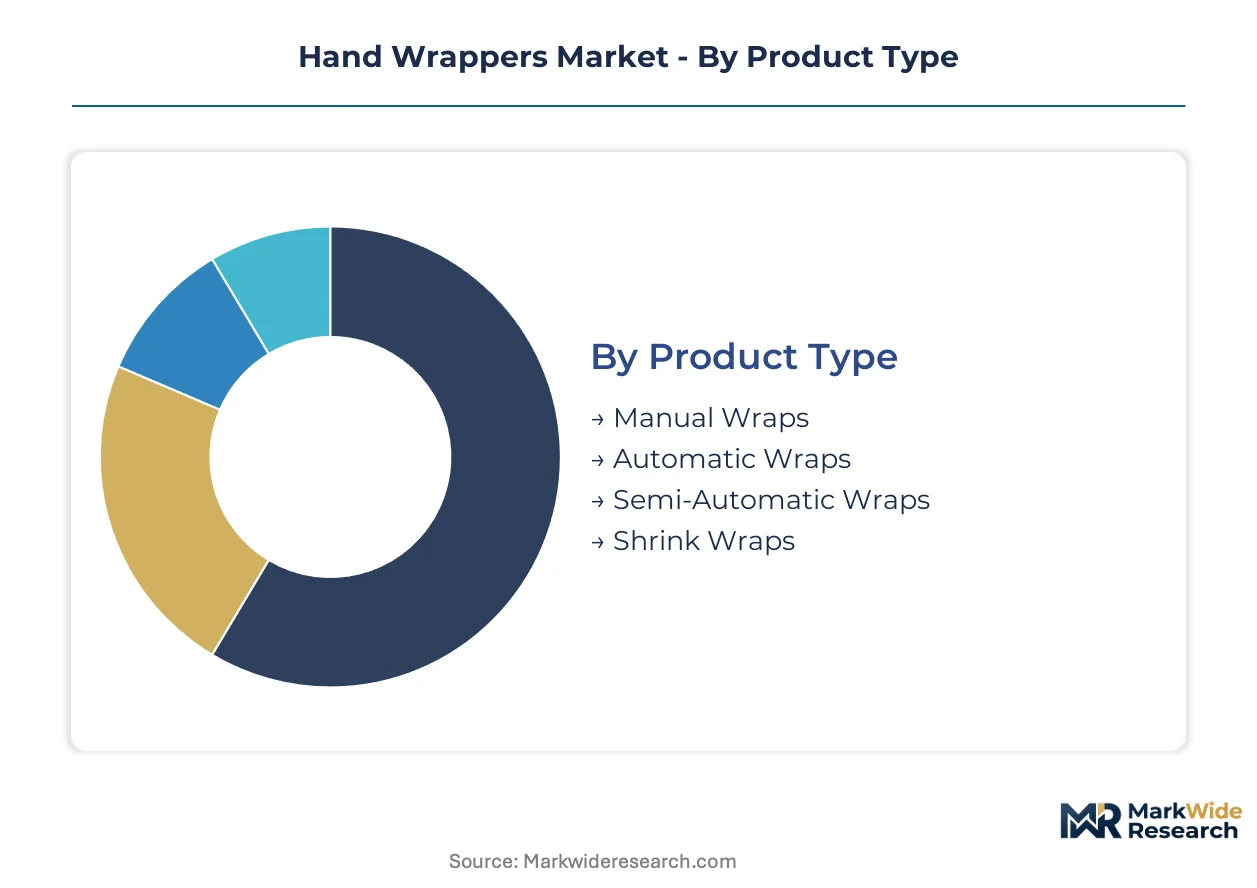
Hand wrapper procurement patterns diverge sharply across equipment sophistication levels, application environments, and material compliance requirements. Equipment vendors configure service networks and spare parts logistics around these segment boundaries, as downtime costs vary by end-use intensity.
Product Type:
After-sales-service intensity escalates with mechanical complexity, driving vendor investment in field technician density and remote diagnostics capabilities.
- Semi-Automatic Wraps:Mechanical crank or lever systems with pre-stretch tension control dominate manufacturing floors where throughput exceeds manual capacity. Food service commissaries in the United States anchor demand as labor cost inflation compresses payback periods for equipment upgrades.
- Automatic Wraps:Motorized systems with programmable wrap patterns serve high-volume palletizing operations in centralized distribution centers. Battery-assist variants are gaining traction in mobile catering contexts where power access is unreliable.
- Manual Wraps:Basic hand-held dispensers without mechanical advantage satisfy low-volume retail and small food service operations with minimal capital budgets.
- Shrink Wraps:Heat-activated film systems command premium positioning in gift and retail segments where optical clarity and tamper-evident sealing justify higher material costs.
By volume, Semi-Automatic Wraps leads. By growth pace, Automatic Wraps is ahead.
Application:
Regulatory exposure and hygiene protocol stringency shape equipment specification and material selection across use cases.
- Food Packaging:Direct-contact applications subject to FDA food-substance notifications drive demand for polypropylene films with migration-tested formulations. Quick-service restaurant chains and commissary kitchens in the United States concentrate procurement of tension-controlled systems with washdown-rated components.
- Industrial Packaging:Pallet load stabilization for manufacturing and logistics operations prioritizes film puncture resistance and load containment force over optical properties.
- Retail Packaging:Point-of-sale presentation requirements favor printed shrink films with high-clarity finishes that support brand visibility.
- Gift Packaging:Seasonal demand spikes and premium positioning sustain niche demand for decorative cellophane and specialty paper formats.
Food Packaging generates the largest equipment installed base. Retail Packaging is climbing the fastest as printed film adoption accelerates.
Material:
Film formulation decisions cascade through equipment tension range requirements and recycling compliance obligations.
- Polypropylene:Dominates food-contact applications through its balance of clarity, seal strength, and FDA compliance. California's SB 54 phased targets are forcing reformulation to incorporate post-consumer resin without sacrificing elongation properties.
- Polyethylene:Lower-cost alternative for industrial stretch applications where optical clarity is secondary to puncture resistance and load retention.
- Paper:Compostable formats serve gift and specialty food segments where sustainability positioning outweighs barrier performance limitations.
- Cellophane:Niche premium applications in confectionery and floral packaging where biodegradability and dead-fold characteristics command price premiums.
Polypropylene holds the largest volume share. Paper is gaining share fastest as compostable mandates proliferate.
End User:
Procurement scale and technical support expectations fragment the customer base from national distributors to independent operators.
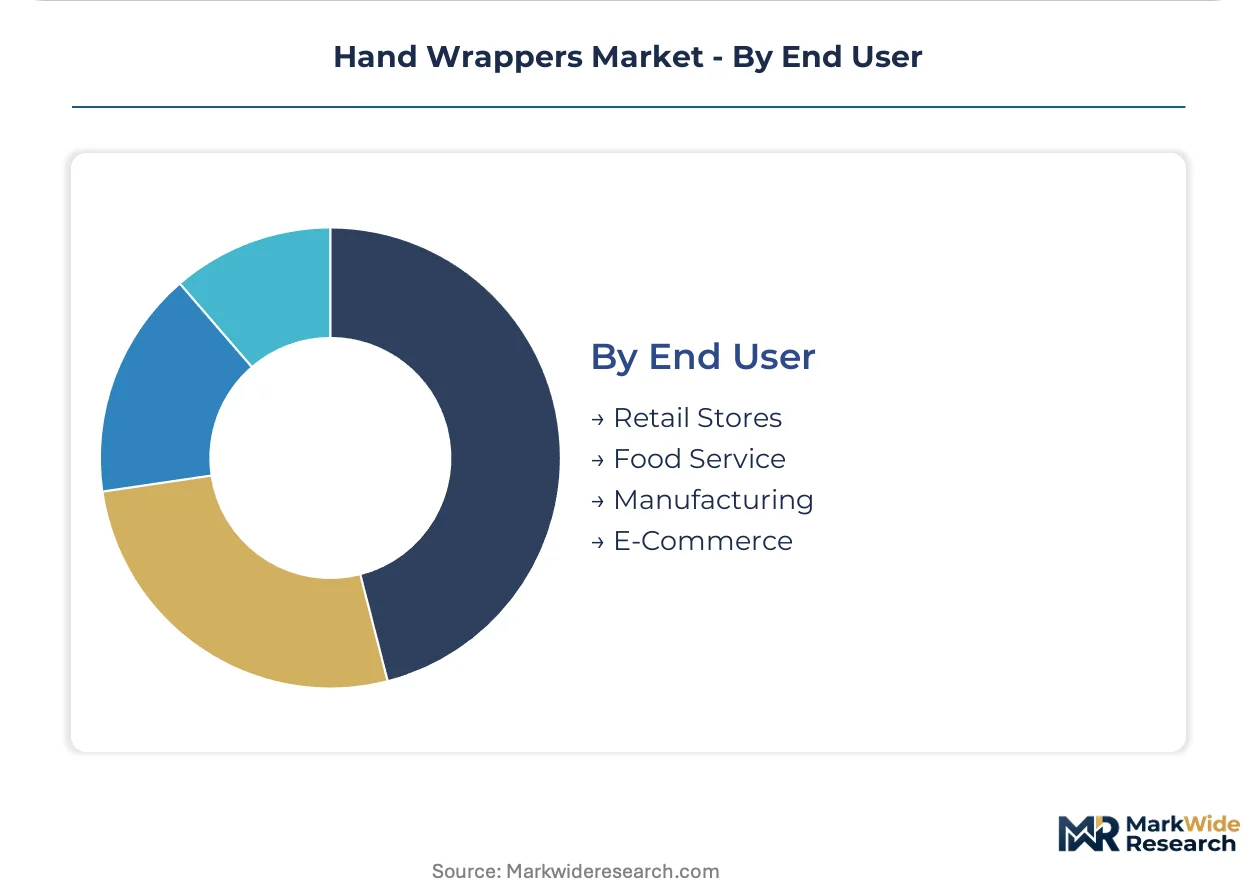
- Food Service:National chains and centralized commissaries drive volume procurement of semi-automatic systems with centralized technical support agreements. OSHA ergonomic mandates are accelerating replacement of manual wrapping stations in quick-service restaurant back-of-house operations.
- Manufacturing:Industrial palletizing operations demand heavy-duty equipment with extended service intervals and rapid spare parts availability.
- Retail Stores:Single-location and small-chain operators prioritize low capital outlay over advanced features, sustaining demand for manual wrap dispensers.
- E-Commerce:Fulfillment center operators are piloting connected wrapper systems with load sensor diagnostics to reduce film waste and document quality compliance.
Food Service concentrates the highest equipment value per location. E-Commerce is expanding most quickly as fulfillment network density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States operators prioritize semi-automatic tension-controlled systems for commissary throughput, while European buyers emphasize recycled-content compatibility under EU Packaging and Packaging Waste Regulation mandates. Chinese manufacturing clusters export battery-assisted units to Southeast Asian food processing hubs.
United States
Quick-service restaurant chains and centralized commissary kitchens drive equipment procurement volume. OSHA ergonomic standards accelerate replacement of manual wrapping stations with mechanical-assist devices. Chicago and Dallas-Fort Worth metropolitan areas concentrate food service distribution infrastructure where national distributors consolidate wrapper procurement.
Germany
Industrial palletizing operations in Baden-Württemberg and North Rhine-Westphalia anchor demand for heavy-duty stretch film systems. EU Green Deal framework mandates recycled content thresholds that reshape material sourcing for domestic and export-oriented manufacturers. Munich-based equipment vendors serve Central European food processing clusters with integrated wrapping solutions.
China
Packaging machinery output tilts toward semi-automatic and automatic systems for export markets across Southeast Asia and Africa. National dual carbon goals pressure domestic film suppliers to reformulate polypropylene grades with post-consumer resin. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces dominate wrapper equipment fabrication.
Mexico
Expanding tortilla and prepared food manufacturing in Guanajuato and Querétaro states lacks localized wrapper equipment distribution networks. Proximity to United States supply chains creates cross-border procurement dependencies for tension-controlled systems. Mexico City metropolitan area concentrates food service distributor headquarters that coordinate regional equipment deployment.
India
Food processing sector growth in Maharashtra and Gujarat drives demand for cost-optimized manual and semi-automatic wrapping systems. FSSAI food safety regulations govern material compliance for direct-contact applications in domestic and export-oriented units. Bangalore and Hyderabad technology corridors incubate startup ventures exploring battery-assisted wrapper designs for mobile catering contexts.
Hand Wrappers Market Competitive Landscape
Capability concentration sits with specialized European and North American fabricators; scale advantage sits with integrated packaging conglomerates serving multi-regional distributor networks. The vendor base separates into three strategic archetypes: steel and plastic strapping heritage players extending into film-based solutions, pressure-sensitive tape specialists diversifying into wrapper adjacencies, and dedicated packaging machinery manufacturers with regional service density. Competitive moves center on distributor partnership consolidation and remote diagnostics capability deployment to compress after-sales service intervals.
Among North American-anchored conglomerates, Signode Industrial Group and Intertape Polymer Group exemplify divergent entry paths into hand wrapper markets. Signode leverages its industrial strapping heritage to anchor heavy-duty applications, while Intertape extends pressure-sensitive tape expertise into film and paper wrapper categories. Aetna Group represents European manufacturing scale competing through specialized distributor partnerships in food service segments. These three occupy positions across the capability-scale spectrum without direct segment overlap.
| Leading Market Players |
|---|
| Signode Industrial Group |
| Aetna Group |
| PAC Worldwide Corporation |
| Intertape Polymer Group |
| M.J. Maillis Group |
| Shurtape Technologies |
| Tach-It |
| ProPack |
| Crown Holdings |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese packaging machinery clusters is compressing export pricing for semi-automatic hand wrapper systems while simultaneously eroding margin buffers for North American distributors facing tariff exposure. This utilization imbalance forces suppliers to absorb freight volatility and extend payment terms to defend market position, reshaping procurement economics across food service and industrial channels.
Pricing Analysis
Long-term equipment offtake contracts dominate procurement between national food service distributors and wrapper manufacturers, insulating volume buyers from resin price spikes while locking in service bundling. Price differentiation rests on FDA food-contact certification tier and after-sales technician density, with premium-positioned vendors commanding spreads for washdown-rated components. Pricing pressure stems from Chinese import competition in the battery-assist segment, eroding margins on mid-tier mechanical systems. Small retail operators exhibit acute price sensitivity, whereas centralized commissaries prioritize total cost of ownership over capital outlay.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Yangtze River Delta equipment fabricators are anchoring distributor relationships across Southeast Asian export markets. Manufacturing concentrates in China, Germany, and the United States, with polypropylene film feedstock drawing from Gulf Coast petrochemical complexes and Middle Eastern resin suppliers. Tariff exposure on Chinese semi-automatic systems creates vulnerability for North American distributors reliant on cross-Pacific sourcing. Distribution runs through national food service distributors consolidating procurement for quick-service restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hand wrapper penetration in Mexico's expanding tortilla and prepared food manufacturing represents early-cycle expansion, with OSHA ergonomic mandates in the United States simultaneously accelerating replacement demand for mechanical-assist systems.
For Market Incumbents: Insulate service revenue streams by embedding remote diagnostics capabilities that compress technician dispatch intervals and lock in multi-year maintenance contracts. Deepen backward integration into polypropylene film compounding to control post-consumer resin formulation costs as California SB 54 compliance tightens. Prioritize distributor exclusivity renewals in Dallas-Fort Worth and Chicago logistics corridors where national food service operators concentrate procurement.
For New Entrants and Emerging Players: Establish a beachhead in Mexico's Guanajuato and Querétaro food processing clusters where localized wrapper equipment distribution remains underdeveloped. Target battery-assist manual wrappers for mobile catering contexts in Indian metropolitan corridors, leveraging lithium-ion cost curves to undercut semi-automatic alternatives. Pursue private-label partnerships with regional food service distributors seeking to unbundle after-sales service from equipment markups.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among European equipment fabricators with embedded service contracts and spare parts captive supply, offering superior cash flow visibility over pure manufacturing plays. Acquisition screening should prioritize vendors with FDA food-contact notification libraries and tension-control IP applicable to recycled-content film formats. Monitor California SB 54 enforcement intensity as an inflection signal for compliance-driven equipment replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Remote Diagnostics Deployment | Bluetooth-enabled load sensors transmit wrap consistency metrics to commissary kitchen platforms, reducing film waste. |
| Backward Integration into Film Compounding | In-house polypropylene formulation with post-consumer resin secures California SB 54 compliance without supplier dependency. |
| Battery-Assist Technology Convergence | Lithium-ion power systems merge with mechanical tension controls for cordless operation in remote catering contexts. |
| Distributor Partnership Consolidation | Direct-to-warehouse fulfillment agreements with Sysco and US Foods displace territory-based dealer networks. |
| EU Recycled Content Compliance | Expanded tension ranges accommodate variable elongation properties of post-consumer resin films for European export channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food-contact substance notifications, OSHA ergonomic standard filings, EU Packaging and Packaging Waste Regulation documentation, and California SB 54 implementation guidance. Primary interviews engaged equipment procurement directors at national food service distributors, plant engineers at centralized commissary facilities, aftermarket service heads at wrapper manufacturers, and regulatory affairs leads at polypropylene film suppliers. Secondary validation drew from customs trade data, SEC equipment vendor filings, and state-level extended producer responsibility tracking databases. Bottom-up equipment shipment analysis triangulates against top-down food service operator capital expenditure surveys.
Forecast inputs incorporate equipment replacement cycles driven by OSHA ergonomic mandates, resin price elasticity effects on film formulation decisions, and distributor consolidation patterns across North American food service channels. Segmentation modeling spans product type sophistication, application regulatory exposure, material compliance tier, and end-user procurement scale. CAGRs derive from installed base growth adjusted for technology substitution effects and regional penetration rate differentials. Battery-assist adoption curves and recycled-content film compatibility thresholds represent critical forecast sensitivity parameters.
Sensitivities concentrate around California SB 54 enforcement pacing, Chinese equipment import tariff trajectories, and biodegradable film performance breakthroughs that could displace conventional polypropylene. Forecasts embed assumptions regarding labor cost inflation persistence and quick-service restaurant commissary expansion rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tape Dispenser Market
Tapes
Dicing Tapes Market
Tapes
Global Construction Tape Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Paper Gummed Tape Market
Tapes
Thermal Release Tapes Market
Tapes
Thermoplastic Tape Market
Tapes
Coding Foils and Tapes Market
Tapes
Thermal Transfer Tapes Market
Tapes
Wire Harness Tape Market
Tapes
Invisible Tapes Market
Tapes
Filament Tapes Market
Tapes
Kraft Paper Tapes Market
Tapes
Tape Banding Machine Market
Tapes
Labels, Tapes and Films Market
Tapes
North America Packaging Tapes Market