
 Beer Dispensing Machine Market | 2026-2036
Beer Dispensing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Dispensing Machine Market Insights
Connected dispensing telemetry is tilting equipment design toward IoT-enabled flow monitoring and predictive maintenance architectures. Micro Matic A/S leverages its draft-system heritage to anchor European on-premise accounts with integrated keg-management platforms. Perlick Corporation sustains premium positioning through stainless-steel fabrication specialization for commercial bar installations. HOSHIZAKI CORPORATION competes on refrigeration-dispensing convergence, extending its ice-equipment distribution into draft systems across Asia-Pacific.
A beer dispensing machine is a pressurized fluid-handling apparatus engineered to store, cool, and dispense carbonated beverages from kegs or pressurized containers through regulated tap mechanisms, typically operating at 10-14 PSI for CO2 systems and 30-40 PSI for nitrogen blends. Its primary commercial purpose is to maintain product integrity—temperature stability, carbonation consistency, and sanitary delivery—while enabling high-volume service in licensed venues. Tower configurations dominate installed base in pubs and stadium concourses where throughput priority overrides footprint constraints, while portable units represent the fastest-expanding category as event planners and catering operators seek deployment flexibility without permanent infrastructure. Electric technology segments capture widening margin pools as venues replace manual systems with programmable pour control and integrated payment interfaces.
The FDA Food Code governs food-contact surface materials and clean-in-place protocols for equipment deployed in US foodservice establishments, while EU Regulation 1935/2004 mandates migration testing for plastic and rubber components in contact with alcoholic beverages across European markets. CE marking requirements under the Machinery Directive additionally shape electrical and pressure-safety design standards for equipment sold within the European Economic Area. Stakeholders must monitor evolving energy-efficiency labeling schemes and refrigerant-phase regulations, as these will determine which cooling-system architectures remain compliant across key jurisdictions.
Market Dynamics
Stadium and arena operators are consolidating procurement power around automated dispensing systems, forcing equipment vendors to bundle telemetry, payment integration, and predictive maintenance into single-platform contracts rather than standalone hardware sales.
Growth Catalysts
- IoT-enabled flow monitoring:Connected telemetry architectures allow venue operators to track pour volumes in real time, reducing waste and enabling dynamic pricing adjustments during events.
- EU F-Gas Regulation phase-down:The refrigerant transition timeline accelerates replacement cycles for aging cooling systems in European pubs and stadiums, creating upgrade demand for compliant electric dispensing units.
- German specification precision:The country's technical standards for food-contact surfaces and pressure safety elevate baseline equipment requirements, pulling adjacent European markets toward higher-grade component sourcing.
Market Restraints
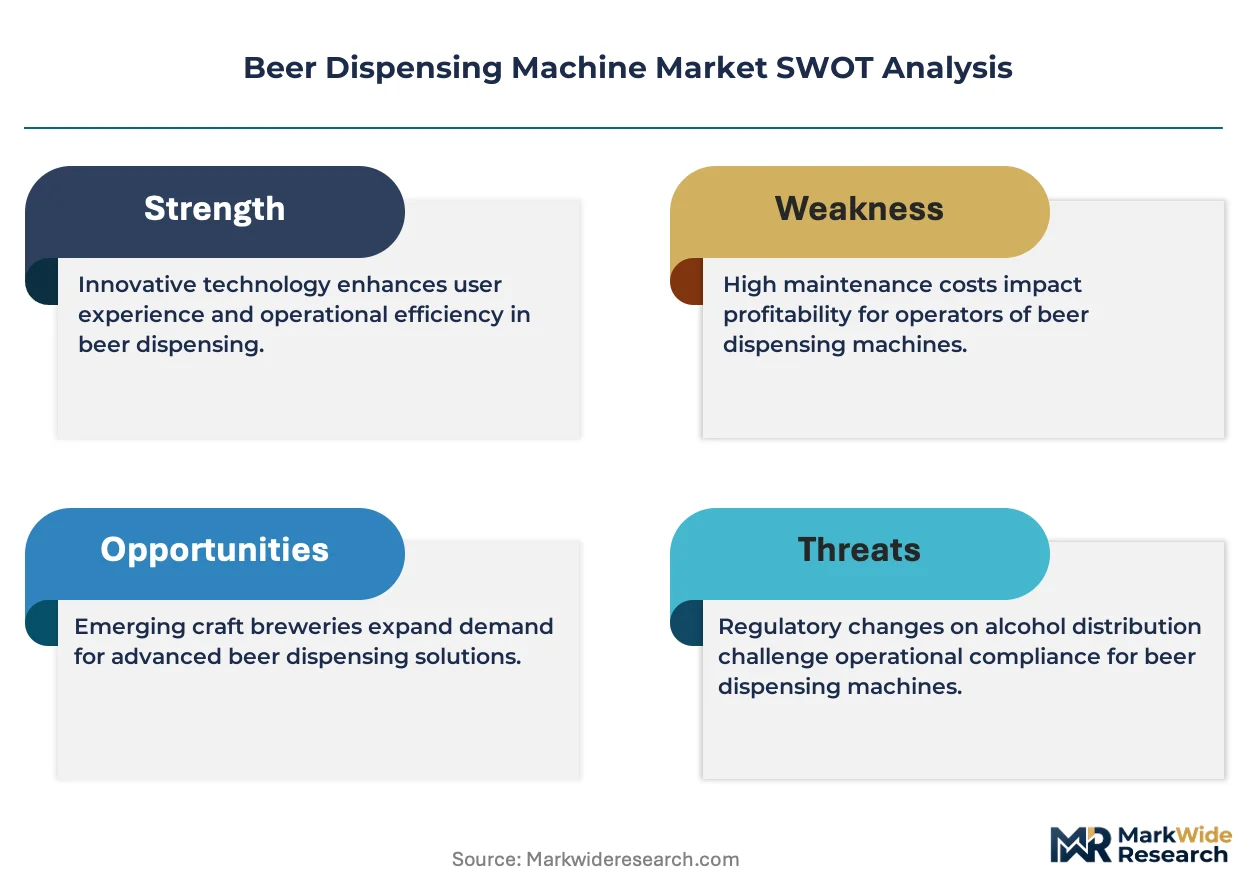
- Stainless steel input volatility:Fluctuations in nickel and chromium prices compress fabrication margins for premium tower configurations, particularly affecting specialized commercial bar installations.
- CE marking compliance costs:The Machinery Directive's electrical and pressure-safety testing requirements create capital barriers for smaller equipment assemblers attempting European market entry.
- Manual pour substitution persistence:Traditional gravity-fed systems retain cost advantages in low-volume venues, slowing penetration in rural and independent pub segments.
Strategic Opportunities
- Portable unit deployment:Event planners and catering operators in France and Spain seek battery-powered dispensing systems for outdoor festivals without permanent infrastructure.
- Refrigeration-dispensing convergence:Integration of ice-equipment distribution networks with draft systems creates channel efficiency in Asia-Pacific growth markets.
- Clean-in-place automation:FDA Food Code sanitation protocols drive demand for self-cleaning line architectures in US foodservice establishments, opening premium pricing tiers.
Industry Challenges
- Refrigerant technician scarcity:The specialized skill set required for F-Gas-compliant cooling system maintenance outpaces vocational training pipeline capacity in several European markets.
- Legacy tap integration complexity:Stadium operators face retrofit friction when connecting programmable pour control to existing keg infrastructure, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Dispensing Machine Market |
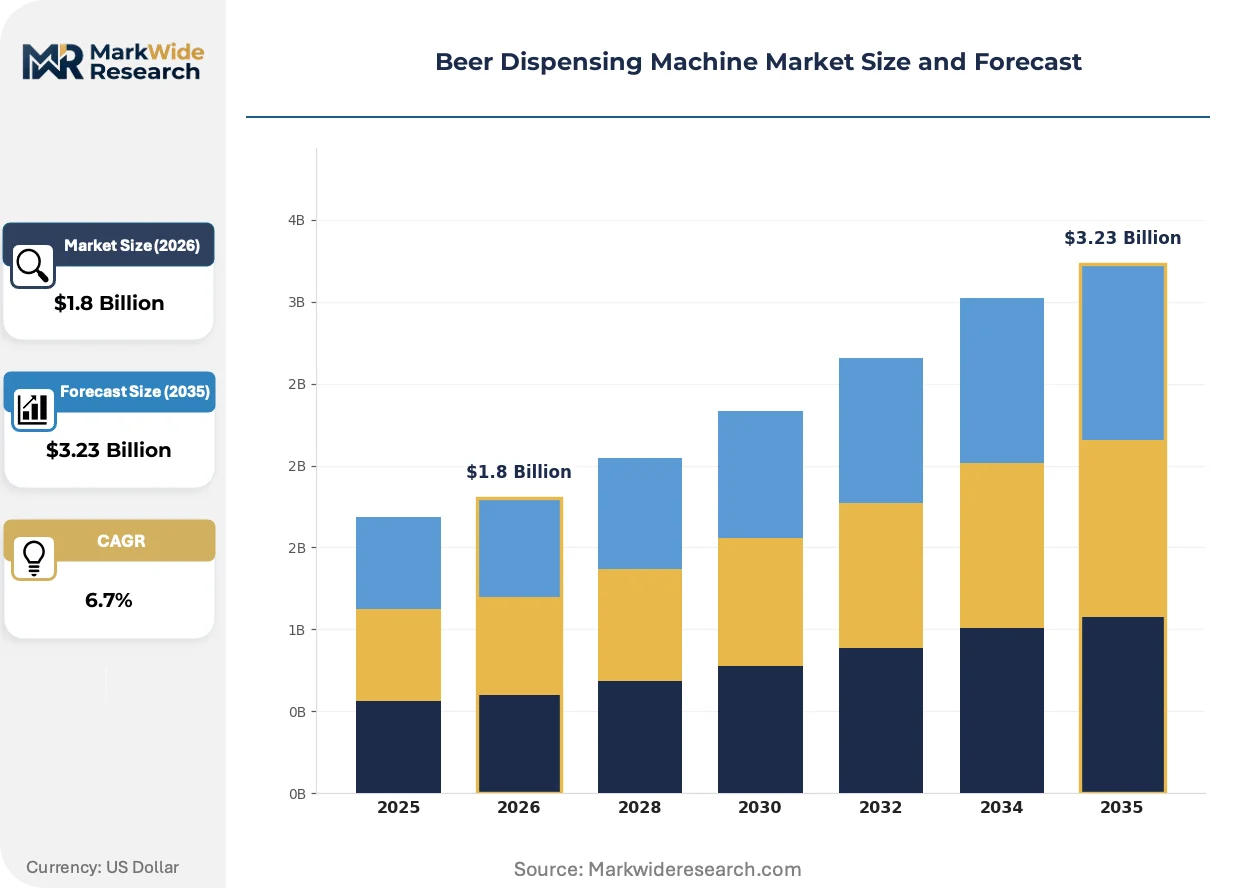
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Tower, Portable, Wall-mounted Technology: CO2 Pressure, Nitrogen, Electric, Manual Application: Pubs, Restaurants, Home Use, Catering End User: Commercial, Residential, Event Planners, Hospitality |
| Companies Covered | Micro Matic A/S, Perlick Corporation, True Manufacturing Company, Beverage-Air Corporation, Kegco, Beerjet GmbH, CELLI S.p.A., HOSHIZAKI CORPORATION, Bottoms Up Draft Beer Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Dispensing Machine Market Trends and Innovations
Equipment architectures are converging around data-centric service models, with hardware margins compressing while software-enabled performance guarantees and usage-based billing expand vendor revenue streams.
Telemetry-enabled dispensing systems are digitizing pour-level data capture for inventory optimization and loss prevention. Large venue operators in Germany and the United States are deploying these platforms fastest, replacing manual keg-check routines with automated depletion alerts and reorder triggers. The technology is digitizing how beverage distributors manage replenishment logistics, compressing response times from days to hours.
The EU F-Gas Regulation is mandating refrigerant transition timelines that disqualify older cooling architectures from new installations. Equipment manufacturers must redesign heat-exchange systems around lower-GWP alternatives, accelerating R&D expenditure recovery through premium pricing on compliant models. Stadium operators in France and Italy face the steepest compliance deadlines, driving near-term replacement demand.
Buyer consolidation among stadium management groups is compressing vendor negotiation cycles and unbundling after-sales service from hardware contracts. Large venue operators now procure dispensing systems through centralized procurement offices, displacing decentralized purchasing by individual concession managers. This pattern is most visible in North American sports entertainment complexes, where multi-venue operators standardize equipment specifications across portfolios.
Beer Dispensing Machine Market Segmentation
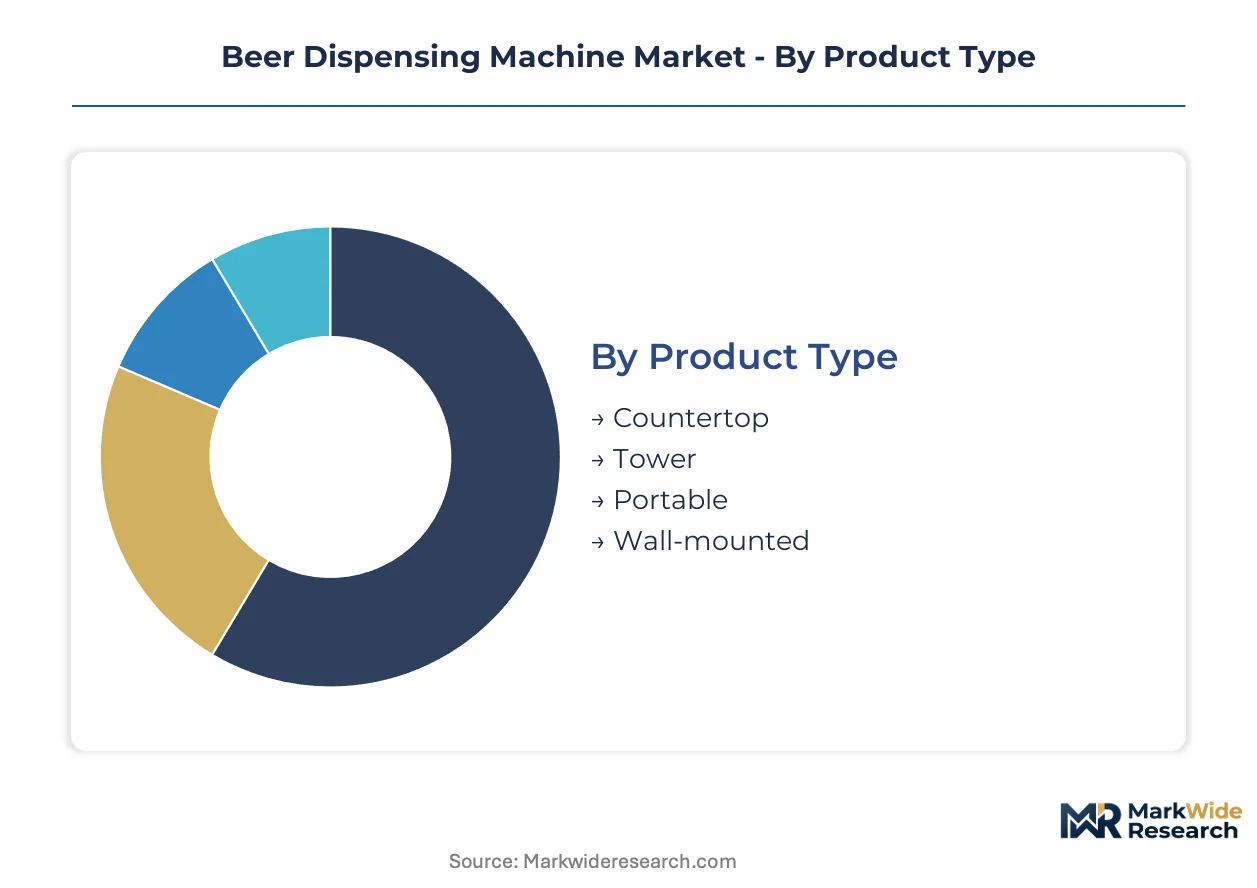
Segmentation in beer dispensing equipment reveals how venue scale, service velocity, and infrastructure permanence dictate technical specifications. Manufacturers configure pressure systems, cooling architectures, and form factors to match distinct throughput requirements across installed-base and mobile deployment scenarios.
Product Type:
Mature tower configurations coexist with emerging portable formats as venues balance throughput permanence against deployment flexibility.
- Tower:Vertical multi-tap assemblies constructed from stainless steel or chrome-plated brass, engineered for high-volume concurrent pouring in licensed venues. Stadium concourses in Germany and the United States specify tower units for their capacity to serve multiple patrons simultaneously during peak event intervals. These systems anchor the installed base through durability and brand visibility advantages.
- Portable:Battery-powered or manual-pressurized units with integrated cooling coils, designed for temporary outdoor service without fixed infrastructure. Event planners in France and Spain procure portable systems for music festivals and sporting events where permanent dispensing lines cannot be installed. Catering operators value rapid deployment and breakdown capabilities.
- Countertop:Compact single or dual-tap units occupying minimal surface area, suited for restaurants with limited bar footprint.
- Wall-mounted:Space-efficient configurations recessing dispensing hardware into vertical surfaces, common in narrow pub interiors.
Tower configurations retain volume leadership; portable units hold the steepest expansion curve.
Technology:
Cost tiers separate pneumatic legacy systems from programmable electric architectures commanding premium positioning.
- Electric:Microprocessor-controlled flow metering with programmable pour volumes, temperature regulation, and integrated payment interfaces. Commercial operators in North American sports venues deploy electric systems to reduce waste through precise portion control and telemetry-enabled inventory tracking. The technology captures widening margin pools as venues modernize from manual alternatives.
- CO2 Pressure:Conventional carbon dioxide-driven dispensing at 10-14 PSI, maintaining carbonation integrity for standard lagers and ales. Pubs across the United Kingdom and Ireland retain CO2 systems for their operational simplicity and lower maintenance burden. The installed base remains substantial despite limited programmability.
- Nitrogen:Higher-pressure 30-40 PSI systems producing cascading pour characteristics for stouts and nitrogenated beers.
- Manual:Gravity-fed or hand-pump mechanisms requiring no external gas supply, persisting in low-volume independent venues.
CO2 pressure technology retains volume leadership; electric systems hold the steepest expansion curve.
Application:
Customer type differentiation separates high-frequency commercial service from intermittent residential consumption patterns.
- Pubs:Licensed on-premise establishments serving draft beer as core revenue, requiring durable equipment with rapid recovery cooling. British and Irish pub operators prioritize reliability and ease of technician access over advanced features. The segment concentrates procurement volume in established beer-drinking markets.
- Catering:Mobile food and beverage service providers executing temporary events, weddings, and corporate functions. Catering operators in Italy and Spain source portable dispensing equipment with rapid setup protocols and minimal technical support requirements. Demand concentrates in Mediterranean markets with strong outdoor event cultures.
- Restaurants:Full-service dining establishments offering limited draft selection as complement to food menus.
- Home Use:Residential consumers installing compact dispensing systems for personal entertainment.
Pubs retain volume leadership; catering holds the steepest expansion curve.
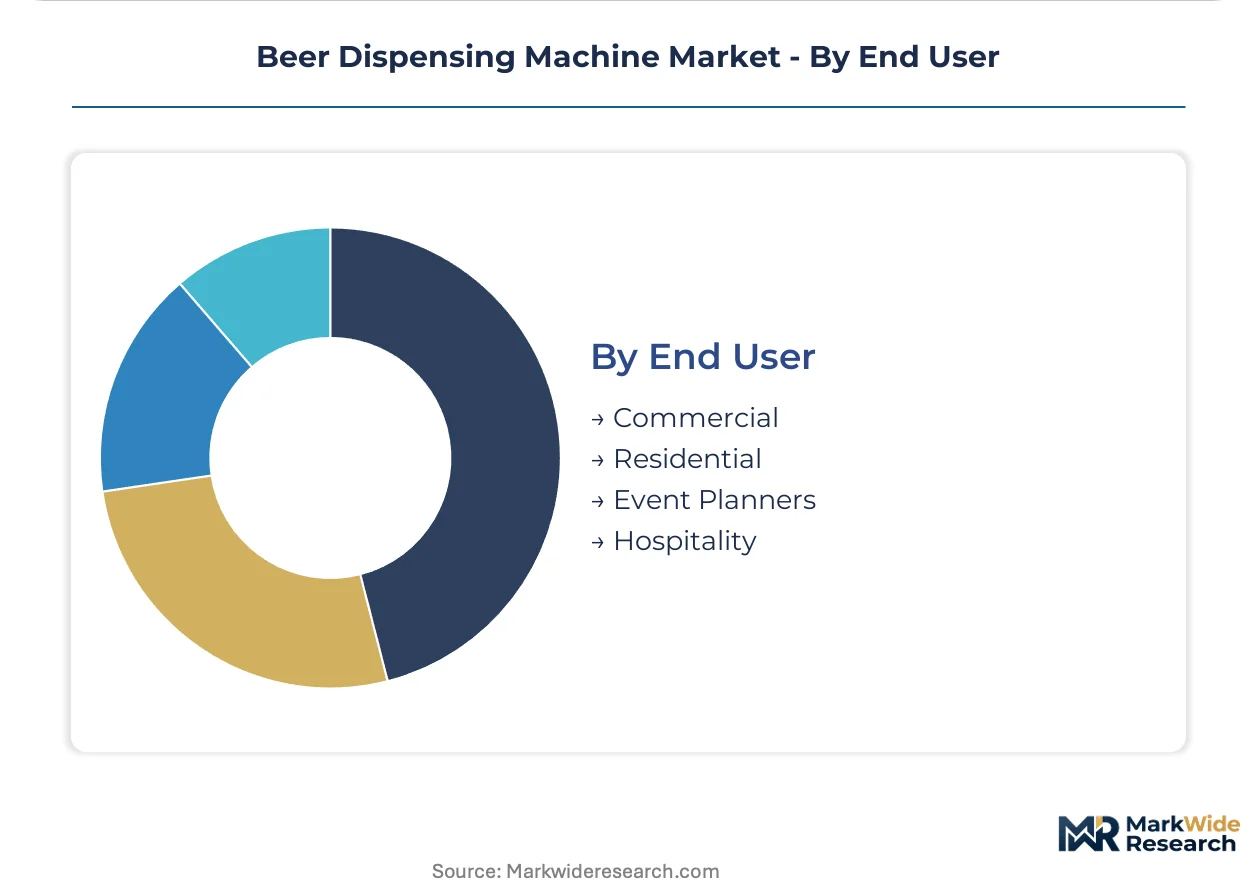
End User:
Margin structures diverge between consolidated commercial procurement and fragmented residential purchasing.
- Commercial:Licensed venues, stadium operators, and hospitality groups purchasing equipment through centralized procurement offices. Large venue operators in the United States negotiate multi-unit contracts bundling hardware, telemetry, and maintenance services. This segment commands the highest average transaction values and longest replacement cycles.
- Event Planners:Specialized operators coordinating temporary beverage service for festivals, conferences, and private functions. Event planners in Germany and the Netherlands lease or purchase portable dispensing equipment seasonally, creating demand spikes aligned with summer festival calendars. The segment exhibits pronounced cyclicality.
- Residential:Individual consumers acquiring compact systems for home entertainment.
- Hospitality:Hotels and resorts integrating dispensing equipment into guest service operations.
Commercial end users retain volume leadership; event planners hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment manufacturers export precision-engineered dispensing systems to stadium operators across the United States and France, establishing a trade corridor that shapes procurement standards in both origin and destination markets.
United States
Stadium management groups in Dallas and Atlanta consolidate procurement through centralized offices, bundling telemetry-enabled dispensing systems with predictive maintenance contracts. FDA Food Code provisions on food-contact surfaces govern equipment sanitation protocols for venues serving food and beverage. Los Angeles and Chicago anchor the commercial installed base, where large-format entertainment complexes standardize specifications across multi-venue portfolios.
Germany
Bavarian technical standards for pressure safety and food-contact precision elevate baseline equipment requirements throughout European procurement. EU F-Gas Regulation phase-down timelines accelerate replacement cycles for aging cooling systems in Munich and Frankfurt stadiums. The country's draft-system heritage concentrates engineering expertise in Stuttgart and Nuremberg, where fabricators supply integrated keg-management platforms to on-premise accounts.
France
Outdoor festival operators in Provence and the Loire Valley seek battery-powered portable dispensing units for temporary deployment without fixed infrastructure. CE marking requirements under the Machinery Directive shape electrical and pressure-safety design standards for equipment sold within the European Economic Area. Lyon and Marseille host seasonal demand spikes aligned with summer event calendars, creating cyclical procurement patterns among catering operators.
Japan
Refrigeration-dispensing convergence drives equipment procurement as venue operators replace manual systems with programmable pour control. METI energy-efficiency labeling schemes influence cooling-system architecture selection for new installations. Tokyo and Osaka concentrate demand from high-frequency commercial service establishments, where throughput requirements favor tower configurations with rapid recovery cooling.
United Kingdom
Pub operators in Manchester and Birmingham prioritize reliability and technician access over advanced features, retaining CO2 pressure systems for operational simplicity. British technical standards for beverage dispensing equipment align with broader European pressure-safety frameworks. London anchors premium-tier procurement, where commercial bar installations specify stainless-steel fabrication for brand visibility advantages.
Beer Dispensing Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Equipment vendors serving consolidated stadium procurement offices negotiate multi-year service contracts that bundle hardware, telemetry, and maintenance into single-platform agreements. Product specialists retain positioning through stainless-steel fabrication expertise or refrigeration-dispensing convergence. The competitive arena features tiered pricing stratification across premium, standard, and economy levels, alongside geographic expansion into Asia-Pacific growth markets and backward integration into component manufacturing.
Within the heritage-fabricator tier, Micro Matic A/S and Perlick Corporation exemplify divergent specialization strategies. Micro Matic A/S occupies a position anchored in European on-premise account relationships, while Perlick Corporation represents premium positioning through commercial bar installation focus. HOSHIZAKI CORPORATION sits within the refrigeration-convergence archetype, leveraging ice-equipment distribution networks to extend draft system penetration across Asia-Pacific venues. These three entities collectively illustrate how technical heritage and channel control determine competitive positioning without requiring scale parity.
| Leading Market Players |
|---|
| Micro Matic A/S |
| Perlick Corporation |
| True Manufacturing Company |
| Beverage-Air Corporation |
| Kegco |
| Beerjet GmbH |
| CELLI S.p.A. |
| HOSHIZAKI CORPORATION |
| Bottoms Up Draft Beer Systems |
| Others |
Pricing and Supply Chain Analysis
Stuttgart's precision-engineering cluster shapes downstream pricing power through captive stainless-steel fabrication capacity and integrated keg-management platform development. German component sourcing elevates baseline equipment specifications, compressing margin pools for assemblers lacking backward integration into pressure-system manufacturing.
Pricing Analysis
Current-generation electric dispensing systems command 40-60% premiums over prior-generation CO2 pressure units, while next-generation IoT-enabled telemetry architectures justify further markups through predictive maintenance bundling. A three-tier pricing structure across premium, standard, and economy levels separates stainless-steel tower configurations from chrome-plated brass alternatives and entry-level portable units. Cost compression in economy tiers is intensifying because nickel and chromium price volatility erodes fabrication margins for specialized commercial bar installations. Event planners and catering operators exhibit highest price sensitivity, prioritizing deployment flexibility over durability; stadium management groups show lowest sensitivity, accepting premium positioning for telemetry integration and multi-year service contracts.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for electronic control modules and refrigeration compressors. Component sourcing concentrates in Germany for precision pressure valves, China for microprocessor-controlled flow meters, and Italy for compact cooling coils. Stainless steel feedstock draws from Finnish and Swedish mills, while integrated circuit dependencies rest on Taiwanese and South Korean foundries. Single-source vulnerability in specialized F-Gas-compliant heat exchangers creates procurement bottlenecks as EU regulatory deadlines accelerate. Distribution runs through beverage-equipment distributors with draft-system technical expertise, anchored by Micro Matic's European on-premise network and HOSHIZAKI's Asia-Pacific ice-equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity because predictive maintenance contracts and telemetry-enabled usage-based billing expand vendor revenue streams faster than hardware depreciation cycles.
For Market Incumbents: Pre-empt portable unit commoditization by anching premium positioning through clean-in-place automation certification and backward integration into stainless-steel tower fabrication. Battery-powered dispensing system entrants from Asia-Pacific threaten margin pools in the fastest-expanding category; defend through captive supply of F-Gas-compliant cooling architectures and exclusive stadium procurement office relationships. For New Entrants and Emerging Players: Establish a beachhead in France and Spain's outdoor festival segment through battery-powered portable units with rapid-deployment protocols and minimal technical support requirements. Catering operators in Mediterranean markets seek deployment flexibility without permanent infrastructure; penetrate through seasonal leasing models and summer event calendar alignment rather than capital equipment sales. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because telemetry-enabled service contracts and predictive maintenance bundling transform transactional hardware sales into multi-year revenue streams. Target acquisition candidates with installed-base density in German or North American stadium markets and proven IoT platform integration. The signal to watch is consolidation velocity among stadium management groups and their migration toward centralized procurement offices with standardized specification requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | Stadium operators in Dallas and Atlanta demand real-time pour volume tracking for dynamic pricing adjustments during events. |
| F-Gas Compliance Transition | EU Regulation mandates heat-exchanger redesigns, creating replacement demand in Munich and Frankfurt venues. |
| Clean-in-Place Automation | FDA Food Code sanitation protocols open premium pricing tiers in Los Angeles and Chicago foodservice establishments. |
| Portable Unit Battery Optimization | Provence festival operators require extended runtime without fixed infrastructure, favoring lithium-ion architectures. |
| Refrigeration-Dispensing Convergence | Tokyo and Osaka venues integrate ice-equipment distribution with draft systems for channel efficiency gains. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with stadium procurement directors, commercial bar installation contractors, catering fleet managers, and beverage distributor operations leads. Secondary validation drew from FDA Food Code provisions, EU F-Gas Regulation filings, CE marking documentation under the Machinery Directive, and METI energy-efficiency labeling schemes. Bottom-up equipment shipment analysis triangulated against top-down venue construction and renovation expenditure patterns.
Calibration against historical replacement cycles and regulatory compliance deadlines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type configuration, technology generation, application throughput requirements, and end-user procurement consolidation status. CAGRs derived from fitted growth curves incorporating stadium operator telemetry adoption rates, refrigerant phase-down timelines, and portable unit penetration in outdoor event markets.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity prices, vocational training pipeline capacity for F-Gas technician certification, or stadium construction financing costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and buyer consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Scotch Whisky Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
US Alcohol E-Commerce Market
Alcoholic Beverages
Beer Kegs Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Global Liquor Confectionery Market
Alcoholic Beverages
Alcohol-Free Pineapple Beer Market
Alcoholic Beverages
Sparkling Wine Market
Alcoholic Beverages
United States Beer Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
Canned Cocktails Market
Alcoholic Beverages
Mead Beverage Market
Alcoholic Beverages
Gin Market
Alcoholic Beverages
Vodka Seltzer Market