
 Rotels Market | 2026-2036
Rotels Market Size, Share, and Industry Trends Forecast 2026-2036
Rotels Market Analytics
Germany is reshaping competitive dynamics in the rotels landscape through its heritage of precision engineering and rolling hospitality infrastructure. Georg Höltl GmbH & Co.KG anchors the premium segment with decades of specialized rail-cruise manufacturing expertise. Das Rollende Hotel leverages modular interior systems to sustain operational flexibility across European routes. Truck Surf Hotel differentiates through adventure-lifestyle positioning that commands pricing power in experiential travel niches.
Rotels comprise self-contained, mobile food preparation and hospitality units engineered for thermal efficiency, compact footprint, and transit compatibility, typically integrating stainless steel construction, insulated compartments, and standardized power interfaces for grid or generator operation. Their primary purpose centers on enabling commercial food service and temporary lodging in locations lacking fixed infrastructure. Premium rotels and hybrid rotels capture expanding margin pools as operators prioritize energy autonomy and guest experience elevation over baseline utility. Electric rotels gain traction in urban catering applications where emissions restrictions tighten operational constraints.
Germany's KBA enforces vehicle safety and emissions compliance that shapes rotel chassis certification and powertrain selection. The EU Green Deal and REACH chemical standards further constrain material choices while accelerating electric propulsion adoption across member states. Stakeholders must monitor regulatory divergence between European emissions frameworks and emerging appliance efficiency mandates in North American jurisdictions to anticipate certification burdens and market access requirements.
Market Dynamics
Commercial kitchen operators across Germany, the United States, and Japan are consolidating procurement around electric and hybrid rotel configurations as municipal emissions ordinances tighten operational constraints on diesel-powered mobile units. This technology pivot compresses replacement cycles while elevating certification requirements for chassis and powertrain integration.
Growth Catalysts
- Commercial Kitchen Infrastructure:Food service operators in Germany deploy rolling hotel units to serve remote event locations and construction sites where fixed infrastructure remains unavailable. KBA vehicle safety standards ensure transit compatibility across European rail networks.
- EU Green Deal Acceleration:REACH chemical standards and emissions mandates push manufacturers toward stainless steel construction with reduced hazardous material content. Electric propulsion systems gain regulatory preference in urban catering corridors.
- Hybrid Powertrain Maturation:Battery-generator hybrid configurations extend operational autonomy for mobile hospitality units operating off-grid. Thermal efficiency improvements reduce fuel consumption during extended deployments.
Market Restraints
- Stainless Steel Input Volatility:Nickel and chromium price fluctuations compress fabrication margins for insulated compartment manufacturers in Germany and Italy. Long-term supply contracts with Korean and Indonesian smelters partially hedge exposure.
- Chassis Supply Concentration:Specialized rail-compatible undercarriage production concentrates among three German engineering houses. Bottlenecks in forged axle components extend lead times during peak order windows.
- Diesel Substitution Pressure:Municipal zero-emission zones in Paris, London, and Amsterdam restrict conventional generator operation. Operators face stranded asset risk on recently purchased diesel units.
Strategic Opportunities
- Japanese Adventure Tourism:Ski resort operators and coastal surf camps seek mobile lodging solutions for seasonal population surges. METI tourism infrastructure incentives partially offset import certification costs for European manufacturers.
- US Appliance Efficiency Alignment:Department of Energy standards create compliance pathway for electric rotels entering commercial kitchen rental fleets. Grid-interface standardization reduces installation friction at temporary event sites.
- Solar-Thermal Convergence:Photovoltaic roof integration with vacuum-insulated food compartments extends off-grid operational duration. Campsite operators in Australia and New Zealand pilot configurations eliminating generator dependency entirely.
Industry Challenges
- Multi-Domain Certification Timeline:Simultaneous KBA vehicle approval, EU appliance safety marking, and national food hygiene licensing extends product launch cycles by 14-18 months. Documentation translation and test repetition across jurisdictions consume engineering resources.
- Rail-Highway Interface Engineering:Bogie-to-truck conversion systems require specialized mechanical integration expertise scarce outside German and Swiss rolling stock clusters. Training programs at technical universities in Dresden and Zurich address pipeline gaps slowly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotels Market |
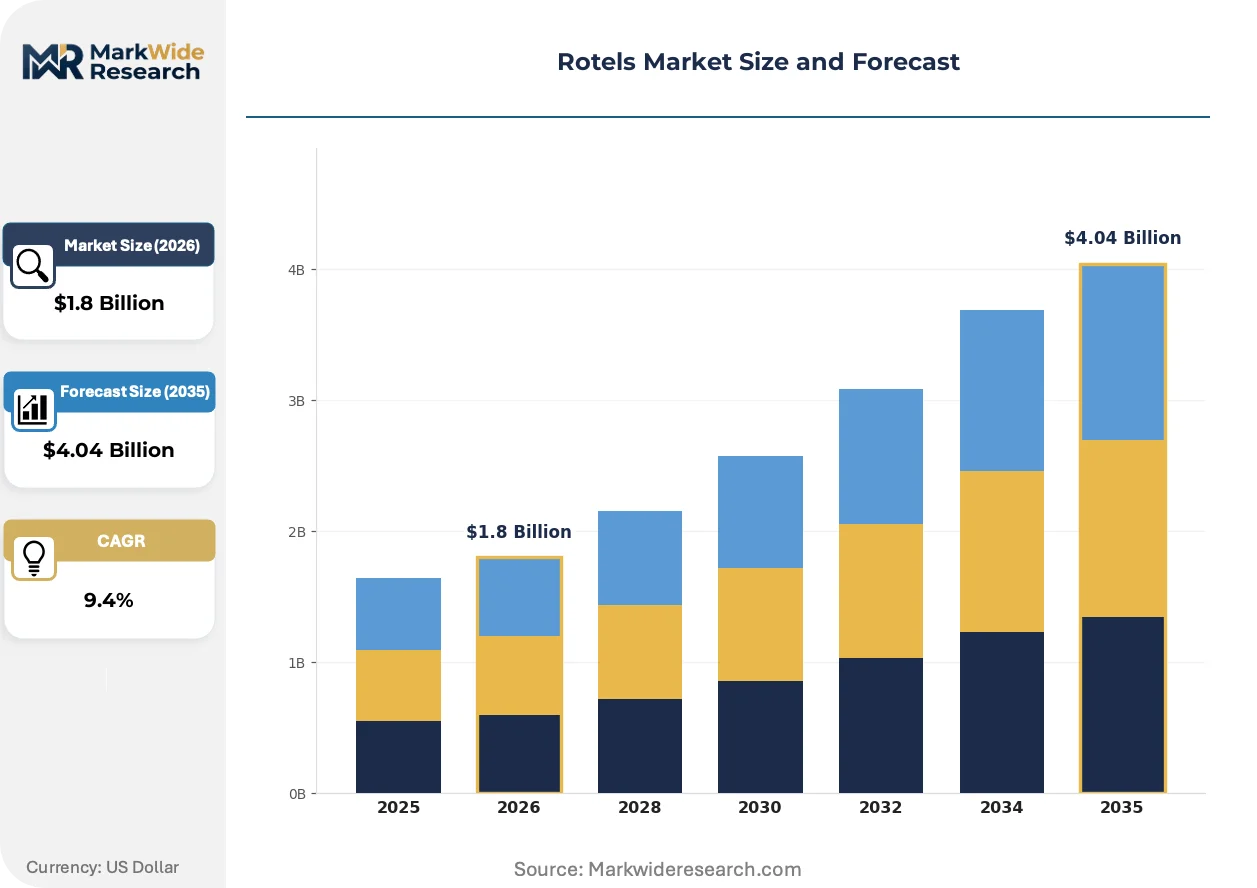
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Rotels, Premium Rotels, Electric Rotels, Hybrid Rotels Application: Home Use, Commercial Kitchens, Food Trucks, Catering Services End User: Households, Restaurants, Event Planners, Retailers Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Georg Höltl GmbH & Co.KG (Rotel Tours), Das Rollende Hotel, Truck Surf Hotel, Radisson Blue, Audley Travel Group Limited, Palace on Wheels, Midnight Trains, Airstream, Winnebago Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotels Market Evolving Landscape
Mobile hospitality engineering is converging with electric vehicle powertrain development and modular construction methods, compressing development cycles while expanding operational versatility across transit modes and terrain types.
Solid-state battery packs with lithium-iron-phosphate chemistry are migrating from passenger electric vehicles into rotel auxiliary power systems. German commercial kitchen operators now specify 8-hour silent operation capability for urban catering deployments. This technology is migrating from automotive volume manufacturing into low-production mobile hospitality equipment, reducing per-kilowatt-hour costs and enabling thermal management integration previously uneconomical at rotel scale.
REACH chemical registration requirements now mandate full material disclosure for insulated compartment foams and surface coatings entering European Union circulation. Manufacturers reformulate polyurethane insulation to eliminate isocyanate classifications triggering extended hazard evaluation. German producers lead compliance adaptation, while North American exporters face documentation gaps delaying market access.
Equipment-as-service contracting now dominates rotel procurement among multinational event management firms. Ownership transfer to specialist operators shifts maintenance burden and residual value risk while guaranteeing uptime availability. This model concentrates most visibly in German-speaking markets where rolling hotel heritage supports sophisticated asset utilization forecasting.
Rotels Market Segmentation
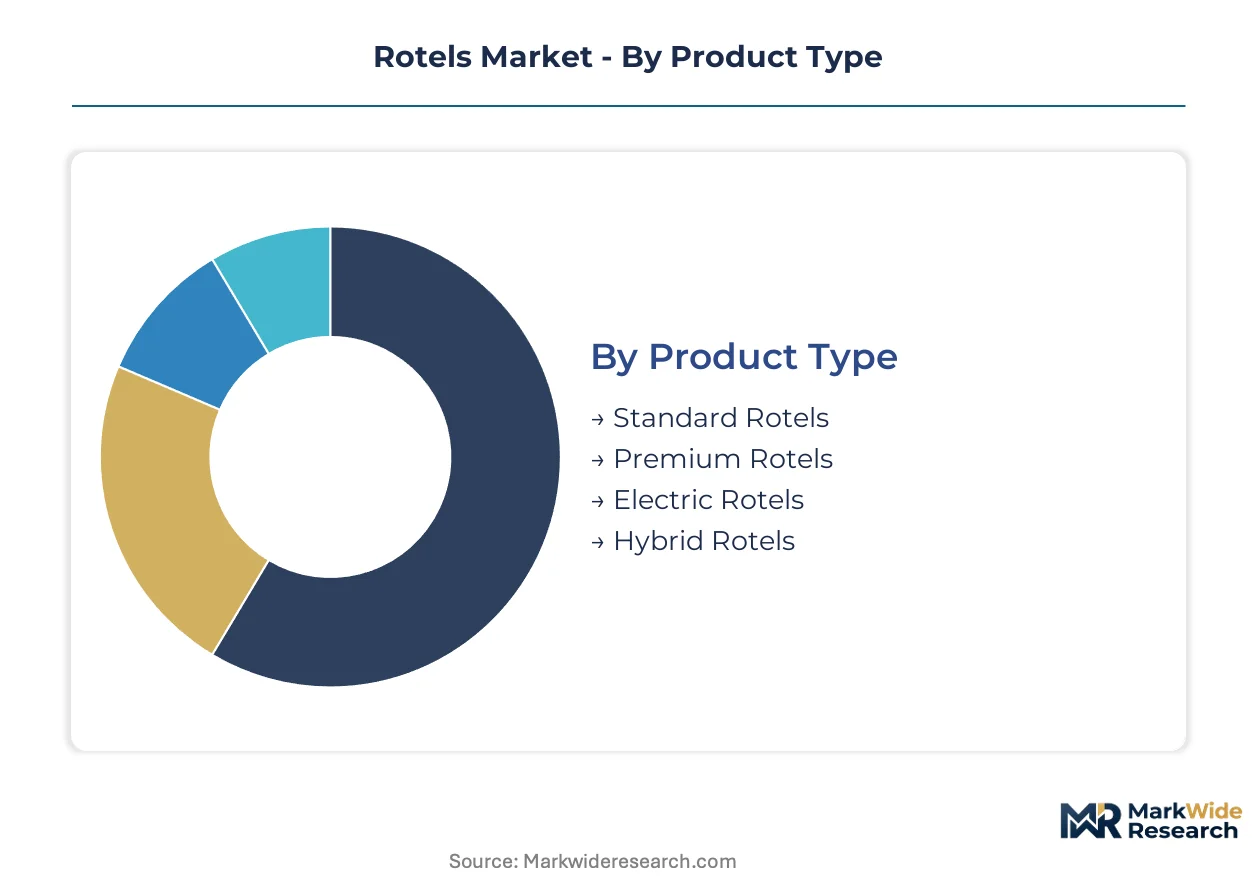
Rotel configurations vary sharply by thermal performance tier, mobility architecture, and powertrain integration. Each segment carries distinct certification burdens, margin profiles, and replacement cycle dynamics that shape procurement patterns across hospitality and food service verticals.
Product Type:
Cost tier differentiation determines thermal efficiency specifications, insulation depth, and powertrain sophistication across the rotel landscape.
- Standard Rotels:Baseline stainless steel construction with polyurethane foam insulation and diesel generator power. Municipal zero-emission zones in Paris and Amsterdam now restrict deployment, compressing residual values.
- Premium Rotels:Vacuum-insulated compartments with modular interior systems and rail-compatible undercarriage certification. German rolling hotel operators specify these for extended European route deployments where guest experience metrics drive renewal decisions.
- Electric Rotels:Grid-interface standardization and lithium-iron-phosphate auxiliary power systems. Urban catering corridors in Germany specify 8-hour silent operation capability.
- Hybrid Rotels:Battery-generator configurations extending off-grid autonomy. Campsite operators in Australia pilot solar-thermal roof integration eliminating generator dependency.
Premium rotels command the established base. The steepest expansion runs through electric rotels.
Application:
Deployment setting dictates chassis requirements, transit mode compatibility, and regulatory exposure across operational environments.
- Commercial Kitchens:Heavy-duty stainless steel construction with NSF food safety certification and reinforced axle assemblies. German construction site operators and event management firms consolidate procurement here as fixed infrastructure gaps persist.
- Catering Services:Rapid-deployment configurations with standardized power interfaces and compact footprint optimization. METI tourism infrastructure incentives in Japan accelerate adoption for seasonal resort operations.
- Food Trucks:Highway-optimized suspensions with municipal vending permit compatibility. Diesel substitution pressure intensifies as London and Paris expand zero-emission zones.
- Home Use:Reduced-scale thermal compartments with consumer appliance safety marking. Limited penetration outside enthusiast segments due to capital intensity.
Commercial kitchens anchor current procurement volumes. Catering services are climbing the fastest as experiential event formats multiply.
End User:
Customer type determines ownership model preferences, maintenance sophistication, and financing structure across the equipment lifecycle.
- Restaurants:Equipment-as-service contracting dominates, shifting residual value risk to specialist operators. German-speaking markets concentrate this model.
- Event Planners:Rental fleet access prioritizes uptime guarantees over capital deployment. Multinational event management firms drive standardization.
- Households:Minimal penetration limited by purchase price and storage constraints.
- Retailers:Resale channel development for secondary market liquidity.
Restaurants hold the dominant share. Event planners are gaining share fastest as temporary infrastructure demand surges.
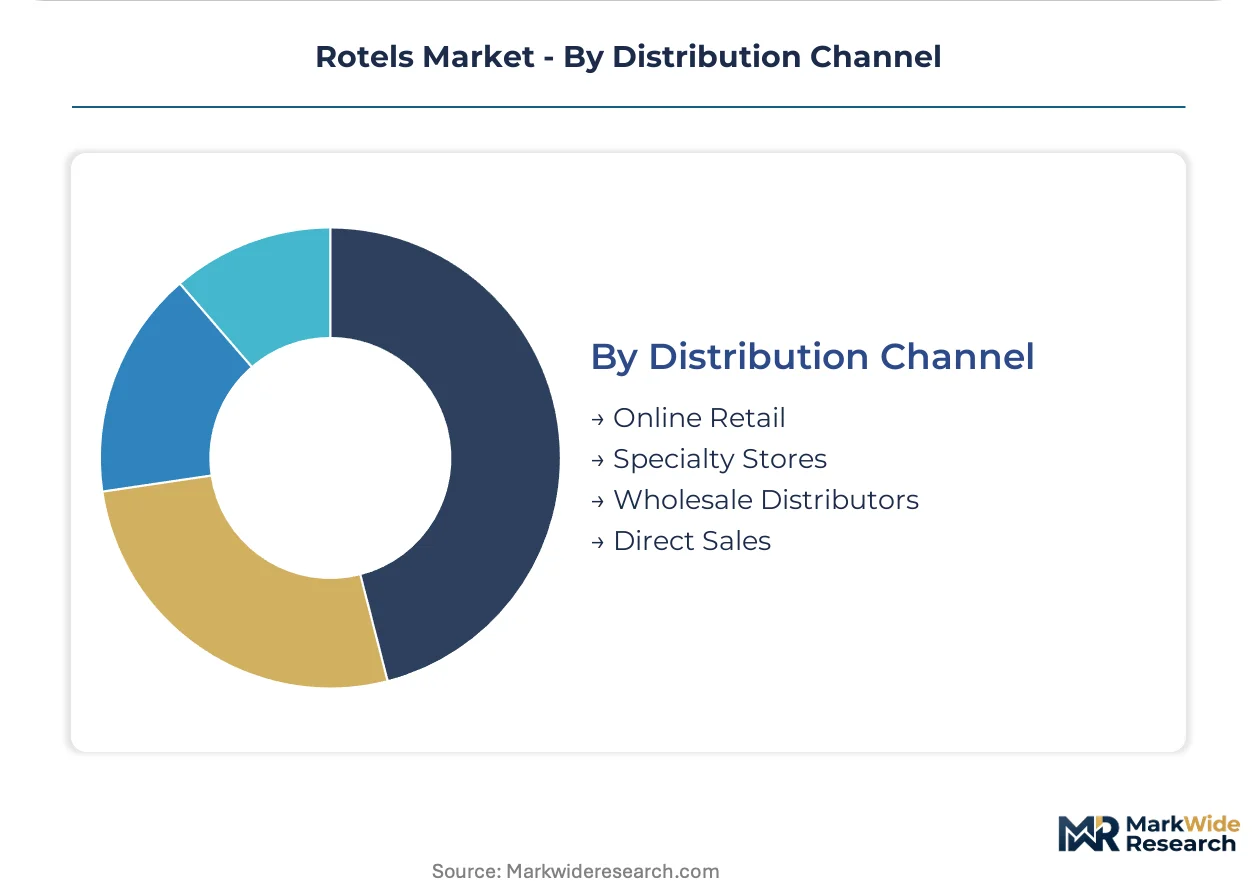
Distribution Channel:
Channel structure reflects customer technical sophistication, after-service requirements, and transaction scale across procurement workflows.
- Direct Sales:Manufacturer-led specification engineering for rail-highway conversion systems and KBA chassis certification. German rolling stock clusters concentrate this channel.
- Wholesale Distributors:Inventory positioning for standardized commercial kitchen configurations with rapid fulfillment timelines.
- Specialty Stores:Curated selection for adventure tourism and lifestyle hospitality segments.
- Online Retail:Limited traction due to technical consultation requirements and installation complexity.
Direct sales capture the premium tier. Wholesale distributors are expanding most quickly as fleet standardization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys rotels primarily for rail-cruise hospitality, while Japan and the United States favor mobile commercial kitchen configurations for seasonal events and construction sites. This consumption-mix differential shapes divergent certification requirements and supply chain sourcing patterns across major demand centers.
Germany
Rolling hotel operators command premium procurement volumes for extended European route deployments. KBA vehicle safety standards enforce rigorous chassis certification for rail-highway conversion systems. Engineering clusters in Dresden and Nuremberg concentrate specialized bogie-to-truck integration expertise.
United States
Event management firms and construction site operators drive commercial kitchen rotel adoption for temporary infrastructure gaps. Department of Energy appliance efficiency standards create compliance pathways for electric configurations entering rental fleets. Manufacturing activity clusters in the Midwest and Pacific Northwest around stainless steel fabrication networks.
Japan
Ski resort operators and coastal surf camps seek mobile lodging solutions for seasonal tourism surges. METI tourism infrastructure incentives partially offset import certification costs for European manufacturers. Technical consultation concentrates in Osaka and Nagoya for rail-compatible undercarriage adaptation.
Australia
Campsite operators pilot solar-thermal roof integration eliminating generator dependency for off-grid hospitality deployments. National electrical safety standards govern grid-interface standardization for electric rotel configurations. Queensland and Western Australia anchor experiential tourism demand for adventure-lifestyle mobile units.
France
Municipal zero-emission zones in Paris restrict diesel-powered mobile kitchen operation, accelerating electric rotel specification. ANSM and environmental regulators enforce chemical disclosure requirements for insulated compartment materials. Lyon and Marseille concentrate catering fleet operators adapting to emissions ordinances.
Rotels Market Competitive Landscape
Capability concentration sits with specialized rail-cruise manufacturers possessing decades of KBA certification expertise; scale advantage sits with diversified mobile hospitality fabricators serving broader geographic markets. The vendor base stratifies across three tiers: heritage rail specialists, modular hospitality engineers, and adventure-lifestyle positioning specialists. Dominant competitive moves include equipment-as-service contracting shifts and hybrid powertrain portfolio diversification.
Within the heritage specialist tier, Georg Höltl GmbH & Co.KG anchors premium rail-cruise manufacturing lineage, while Das Rollende Hotel exemplifies modular interior system flexibility for European route operators. Truck Surf Hotel occupies the adventure-lifestyle positioning vector commanding pricing power in experiential travel niches.
| Leading Market Players |
|---|
| Georg Höltl GmbH & Co.KG (Rotel Tours) |
| Das Rollende Hotel |
| Truck Surf Hotel |
| Radisson Blue |
| Audley Travel Group Limited |
| Palace on Wheels |
| Midnight Trains |
| Airstream |
| Winnebago Industries |
| Others |
Value Network & Pricing Analysis
Rhine-Alpine corridor freight rates transmit stainless steel input volatility from German fabrication clusters into downstream price differentiation between rail-certified premium units and highway-optimized standard configurations. KBA chassis certification costs concentrate pricing power with specialized engineering houses in Dresden and Nuremberg, while nickel and chromium price swings from Korean and Indonesian smelters compress margins on polyurethane-insulated compartments.
Pricing Analysis
Geographic price spreads between German rail-cruise configurations and Australian solar-thermal pilot units reflect certification tier and powertrain sophistication. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-insulated rail-compatible units from diesel-generator highway models and reduced-scale home-use variants. Cost compression in standard rotels intensifies as Paris and Amsterdam zero-emission zones strand recently purchased diesel assets. Event planners exhibit highest price sensitivity due to rental fleet uptime guarantees, while rolling hotel operators accept premium pricing for guest experience metrics.
Supply Chain Analysis
Tariff exposure between Indonesia and Germany for nickel and chromium concentrates supply risk in stainless steel fabrication networks. Component sourcing draws from German chassis engineering houses, Italian insulation manufacturers, and Korean battery cell producers. Forged axle bottlenecks from three specialized suppliers extend lead times during peak order windows. Distribution runs through direct sales for rail-highway conversion systems and wholesale distributors for standardized commercial kitchen configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric propulsion mandates across European municipalities and Japanese METI tourism infrastructure incentives create a high-growth disruption window for mobile hospitality equipment. The technology pivot from diesel-generator to battery-hybrid configurations compresses replacement cycles while elevating multi-domain certification requirements.
For Market Incumbents: Entrench KBA certification expertise through capacity addition in Dresden and Nuremberg engineering clusters. Deepen backward integration into lithium-iron-phosphate auxiliary power systems to offset Korean battery cell supply concentration. Defend against emerging modular hospitality engineers by accelerating equipment-as-service contracting penetration in German-speaking markets.
For New Entrants and Emerging Players: Japanese ski resort and coastal surf camp underpenetration offers white-space entry with lower certification burden than European rail networks. Target Australian campsite operators piloting solar-thermal roof integration as the most penetrable segment. Pursue METI tourism infrastructure incentive alignment as the primary go-to-market angle for import cost offset.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified rolling stock manufacturers with underutilized rail-cruise fabrication capacity. Long-term viability hinges on electric powertrain transition completion and hybrid configuration standardization. Monitor KBA approval timeline compression as the inflection signal for margin recovery in premium tier manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Portfolio Diversification | Battery-generator configurations extend operational autonomy for off-grid Australian campsite deployments. |
| Equipment-as-Service Contracting Expansion | Ownership transfer to specialist operators concentrates in German-speaking markets with rolling hotel heritage. |
| Rail-Highway Conversion System Investment | Bogie-to-truck integration expertise scarcity outside Dresden and Zurich clusters creates defensive moat. |
| Solar-Thermal Roof Integration Development | Photovoltaic vacuum-insulated compartment convergence eliminates generator dependency for Queensland operators. |
| REACH Chemical Registration Compliance Acceleration | Isocyanate-free polyurethane reformulation mandates separate German producers from documentation-lagged North American exporters. |
Research Methodology
Initial hypotheses were tested against primary input from rolling hotel operations directors, commercial kitchen fleet managers, KBA certification engineers, and stainless steel fabrication procurement leads and refined through secondary validation. Primary fieldwork combined structured interviews with German rail-cruise manufacturers and Australian campsite operators. Secondary sources included KBA vehicle approval databases, EU REACH chemical registration filings, METI tourism infrastructure incentive disclosures, and stainless steel trade flow customs records. Bottom-up unit economics and top-down market sizing were triangulated against operating fleet data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application setting, end-user ownership model, and powertrain architecture. CAGRs were derived from replacement cycle compression analysis and technology adoption curve fitting. Forecast inputs incorporated KBA approval timeline trajectories and municipal zero-emission zone expansion schedules.
Macroeconomic conditions sit as an overlay; deviation in nickel and chromium commodity prices, freight rate volatility on Asia-Europe corridors, or EU Green Deal implementation pace would shift the trajectory. Forecasts reflect documented assumptions on powertrain cost decline curves and certification harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Coconut Alcohol Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Beer Fermenter Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Yorker Spouts Market
Alcoholic Beverages
Fruit Wine Market
Alcoholic Beverages
Portable Keg System Market
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
Dark Spirits Market
Alcoholic Beverages
Commercial Wine Dispenser Market