
 Spirits Miniatures Market | 2026-2036
Spirits Miniatures Market Size, Share, and Industry Trends Forecast 2026-2036
Spirits Miniatures Market Analytics
Premium and super-premium spirit expressions in sub-200ml formats is collapsing the historical gap between miniature novelty and full-bottle quality credentials. Diageo leverages its global distribution architecture to secure duty-free placement across major airport hubs. William Grant & Sons differentiates through limited-edition miniature releases tied to its aged malt portfolios. Pernod Ricard anchors its travel retail strategy with region-exclusive miniature assortments that command price premiums over standard domestic offerings.
Spirits miniatures denote distilled alcoholic beverages packaged in containers typically ranging from 30ml to 200ml, produced through standard pot or column still distillation followed by dilution to 40-50% ABV for bottling in glass, plastic, or metal formats designed for single-serve or sample-scale consumption. Their primary commercial purpose spans airline hospitality, hotel minibars, gift sets, collector markets, and regulatory-compliant sampling programs where full-bottle distribution proves impractical. Whiskey miniatures capture the largest value share as aged expression premiums translate into higher per-milliliter pricing, while plastic bottle packaging grows fastest as brands navigate weight restrictions in airline logistics and sustainability mandates in European retail. Duty-free shops concentrate margin pools through exclusive miniature bundles unavailable in domestic channels.
FDA labeling requirements for alcohol content and allergen disclosure shape product standards for US-bound miniature shipments, while the EU's Single-Use Plastics Directive and REACH chemical compliance frameworks restrict substrate choices across European distribution. EFSA and national regulators within the EU enforce varying maximum container sizes and labeling languages that fragment packaging runs. Stakeholders must monitor evolving packaging regulations in key export destinations and calibrate substrate investments against the operational cost of multi-SKU compliance.
Market Dynamics
The EU's Single-Use Plastics Directive is forcing substrate migration across European distribution channels, while airline weight restrictions simultaneously pull packaging toward lighter formats. These dual pressures compress legacy glass-heavy supply chains and reward multi-substrate manufacturing flexibility.
Growth Catalysts
- REACH Chemical Compliance:European substrate regulations are accelerating investment in recyclable polymers and aluminum formats that satisfy ECHA registration requirements.
- Airline Minibar Replenishment:Premium carriers in the United States and Gulf states are expanding miniature whiskey and gin selections as passenger experience investments recover post-pandemic.
- Duty-Free Exclusive Bundles:Airport retail operators are commissioning region-specific miniature assortments unavailable through domestic e-commerce channels.
Market Restraints
- Aluminum Input Volatility:Miniature metal format production faces cost pressure from London Metal Exchange aluminum price swings and energy-intensive smelting.
- Glass Supply Concentration:Specialty miniature bottle manufacturing clusters in France and northern Italy create geographic vulnerability for premium whiskey expressions.
- Container Size Fragmentation:EFSA and national EU regulators enforce varying maximum miniature volumes that prevent packaging standardization across member states.
Strategic Opportunities
- India Duty-Free Expansion:Mumbai and Delhi airport retail privatization is opening placement slots for super-premium miniature portfolios previously excluded from domestic distribution.
- Biopolymer Substrate Convergence:PHA and PLA material advances combined with blow-molding process improvements are enabling petroleum-free miniature bottles.
- Hotel Minibar Digital Integration:Smart inventory systems in luxury hospitality chains are creating demand for RFID-tagged miniature formats with consumption-tracking capability.
Industry Challenges
- Multi-SKU Compliance Talent:Packaging engineers capable of navigating FDA, EFSA, and national labeling language requirements simultaneously remain scarce.
- Substrate Certification Timelines:Novel recyclable materials face extended EU food-contact approval cycles that delay product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spirits Miniatures Market |
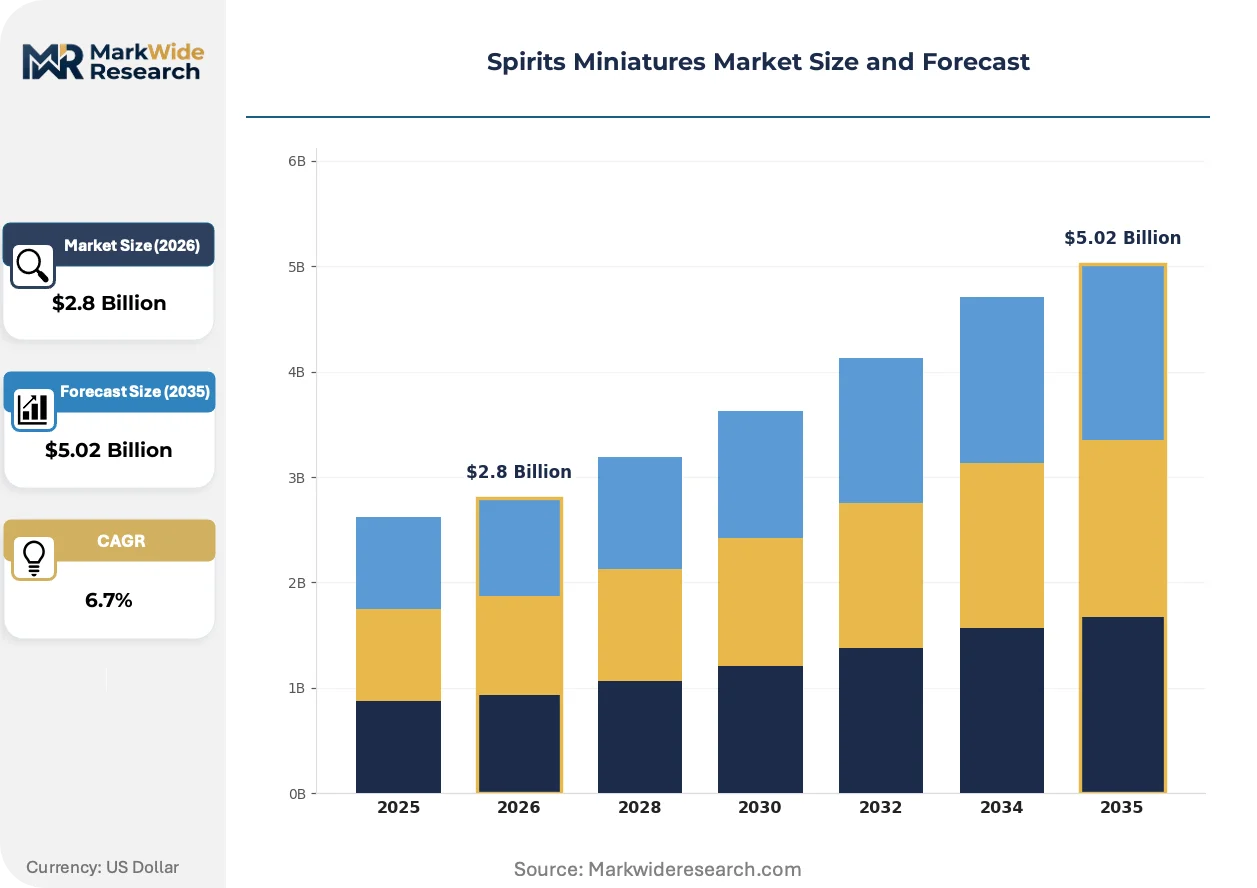
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whiskey, Vodka, Gin, Rum Packaging Type: Glass Bottles, Plastic Bottles, Tins, Cartons End User: Retailers, Collectors, Event Organizers, Restaurants Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Duty-Free Shops |
| Companies Covered | Beam Suntory, William Grant & Sons, Diageo, Plastipak Holdings, Graham Packaging, Pernod Ricard, Bacardi Limited, LYS Packaging, Brown-Forman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spirits Miniatures Market Evolving Landscape
Packaging substrate selection is splitting into parallel development tracks as sustainability mandates collide with logistics economics. This divergence is creating distinct competitive positions based on material science capability rather than traditional brand equity.
Barrier-coated paperboard formats are bifurcating the miniature spirits market between premium glass-retaining expressions and mass-market substrate substitution. Airlines operating transatlantic routes are piloting these containers for weight reduction, while whiskey distillers with aged stock resist format migration to preserve perceived quality. The technology is compressing margin structures for mid-tier brands caught between sustainability commitments and heritage positioning requirements.
REACH Annex XVII restrictions on certain plastic additives are eliminating legacy PVC and specific phthalate formulations from European miniature production. Manufacturers are reformulating polymer blends or migrating to polyethylene terephthalate alternatives that satisfy ECHA substance restrictions. Whiskey miniatures in sub-100ml formats face the steepest reformulation costs due to extended spirit-alcohol contact time requirements.
Collector-driven procurement through specialized e-commerce platforms is fragmenting traditional duty-free channel concentration. Enthusiast communities in the United States and United Kingdom are sourcing limited-edition miniature releases directly from distillery webstores, bypassing airport retail markups. This behavior is most visible in single-malt whiskey segments where age-statement miniatures command secondary market premiums.
Spirits Miniatures Market Segmentation
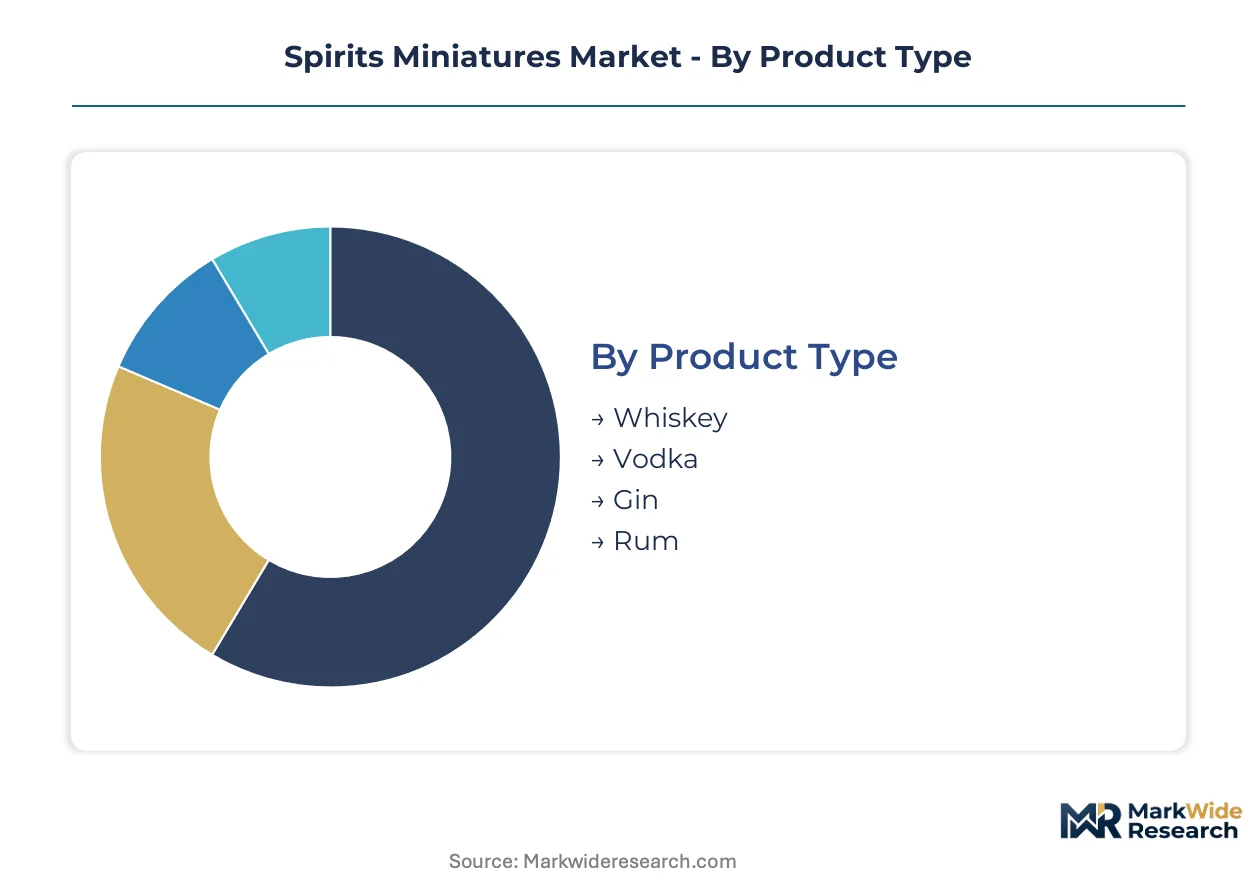
Segmentation in spirits miniatures reflects divergent compliance burdens across substrates and channels. Regulatory fragmentation forces parallel supply chains, while end-use economics determine format selection.
Product Type:
REACH Annex XVII and FDA labeling rules create divergent formulation requirements across spirit categories, with aged expressions facing stricter substrate contact standards.
- Whiskey:Aged malt and grain distillates in 40-50% ABV formulations demand oxygen-impermeable packaging to preserve phenolic complexity. Premium carriers in the United States and Gulf states stock miniature whiskey assortments for first-class cabin service, with super-premium expressions commanding placement priority.
- Vodka:Neutral spirit at 40% ABV permits lighter substrate migration due to minimal extractable compound sensitivity. EEA distribution channels favor vodka miniatures in recyclable PET formats that satisfy EFSA food-contact approvals.
- Gin:Botanical-forward distillates with volatile terpene profiles require barrier-coated containers to prevent flavor degradation.
- Rum:Cane-based spirits spanning white to aged expressions show format flexibility across glass and aluminum substrates.
Whiskey handles the majority of throughput; vodka is the fastest mover on share.
Packaging Type:
Weight restrictions in airline logistics and EU plastic mandates are compressing legacy glass dominance while accelerating multi-substrate manufacturing investment.
- Glass Bottles:Borosilicate and flint glass formats remain mandatory for super-premium aged expressions where perceived quality hinges on traditional presentation. Duty-free shops in Paris Charles de Gaulle and Dubai International commission exclusive glass miniature bundles unavailable through domestic channels.
- Plastic Bottles:PET and emerging PHA polymers satisfy airline weight restrictions and REACH compliance timelines simultaneously. Lighter formats reduce fuel surcharges on transatlantic routes while navigating ECHA substance restrictions.
- Tins:Aluminum formats face London Metal Exchange price volatility but offer circular economy credentials under EU packaging waste directives.
- Cartons:Barrier-coated paperboard pilots on transatlantic routes test weight reduction limits for mid-tier spirit categories.
Glass bottles retain margin concentration; plastic bottles are climbing the fastest.
End User:
Procurement authority and volume scale separate institutional buyers from enthusiast segments with divergent price elasticity and format requirements.
- Retailers:Supermarket and convenience chains stock standardized 50ml formats with uniform labeling for inventory efficiency.
- Collectors:Age-statement miniature releases from Scottish and Japanese distilleries trade through specialized e-commerce platforms with secondary market premiums.
- Event Organizers:Regulatory-compliant sampling programs for trade shows and festivals require tamper-evident miniature formats with batch traceability.
- Restaurants:Fine dining establishments in London, New York, and Singapore deploy premium miniature selections for pairing menus and minibar curation.
Retailers dominate volume throughput; collectors are expanding most quickly.
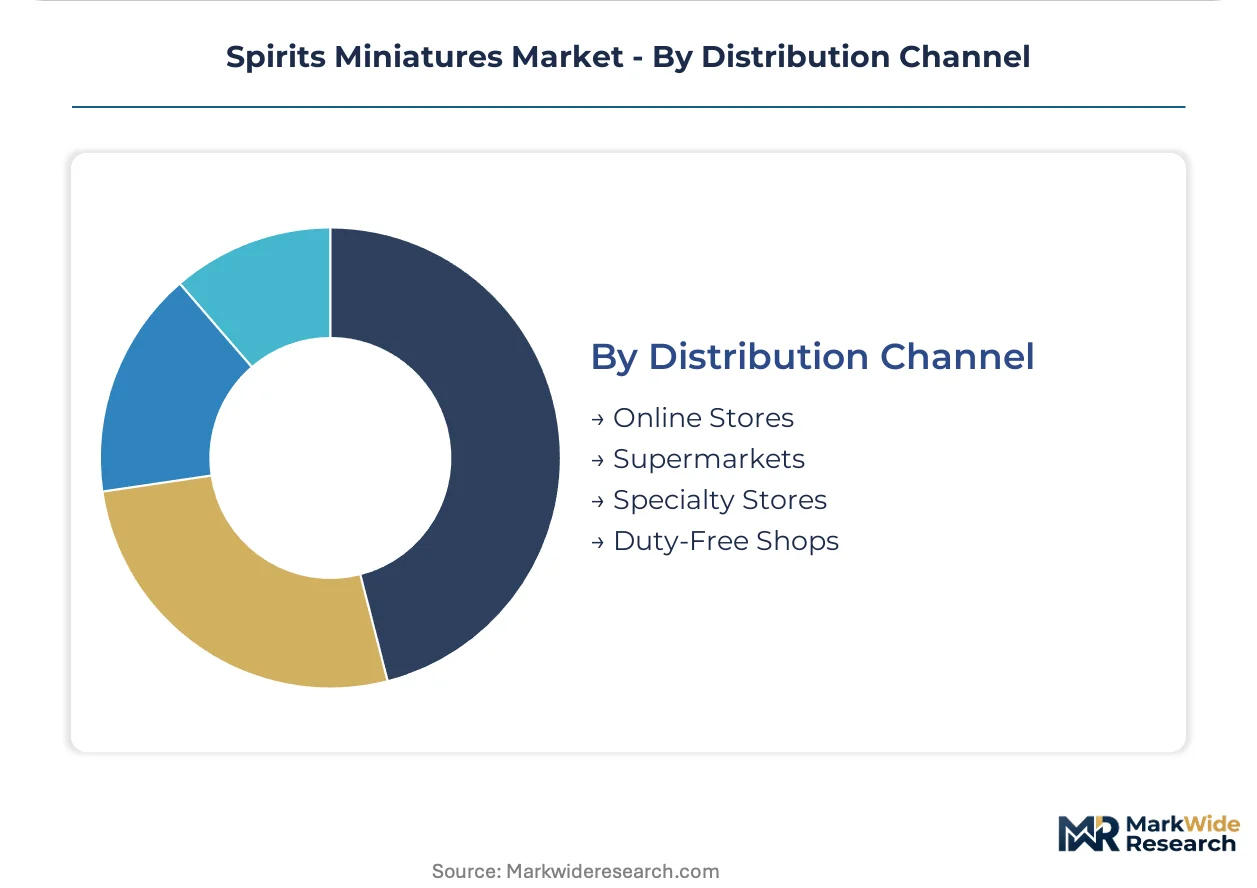
Distribution Channel:
Channel selection determines regulatory exposure, with duty-free and online formats facing distinct compliance architectures across jurisdictions.
- Online Stores:Direct-to-consumer distillery webstores bypass airport retail markups for limited-edition releases. FDA labeling for US-bound shipments and national language requirements fragment packaging runs.
- Supermarkets:Mass-market volume concentration demands standardized formats that satisfy domestic container size regulations.
- Specialty Stores:Curated spirits retailers in Edinburgh, Louisville, and Tokyo stock regional miniature assortments with provenance documentation.
- Duty-Free Shops:Airport retail operators commission region-exclusive bundles with pricing premiums over domestic e-commerce channels. Mumbai and Delhi airport privatization opens placement slots for super-premium portfolios.
Duty-free shops capture margin concentration; online stores are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty glass manufacturing clusters in France and northern Italy concentrate premium miniature bottle supply chains, while airline logistics hubs in the United States and Gulf states drive demand for lightweight substrate formats. Regulatory fragmentation across FDA, EFSA, and national EU frameworks forces parallel packaging runs that inflate operational costs for multinational distributors.
United States
Craft distillers in Kentucky and Tennessee compete with legacy brands for travel retail shelf space at Hartsfield-Jackson Atlanta and Dallas Fort Worth hubs. FDA labeling requirements for alcohol content and allergen disclosure shape product standards for all miniature shipments bound for domestic channels. Chicago and Louisville anchor midwest distribution networks serving hotel minibar replenishment contracts.
Germany
Frankfurt and Munich airports commission region-exclusive miniature assortments unavailable through domestic e-commerce channels. REACH chemical compliance frameworks restrict substrate choices across European distribution, forcing reformulation of legacy polymer blends. Bavarian packaging engineers navigate ECHA registration requirements for recyclable aluminum formats.
United Kingdom
Scottish distilleries release age-statement miniatures that trade through specialized platforms with secondary market premiums. EFSA and national regulators enforce varying maximum container sizes that prevent packaging standardization across EU member states. Edinburgh and Glasgow clusters concentrate premium whiskey miniature production for export markets.
India
Mumbai and Delhi airport retail privatization opens placement slots for super-premium miniature portfolios previously excluded from domestic distribution. The country's national food safety regulator enforces labeling language requirements that fragment packaging specifications. Maharashtra and Karnataka states host emerging hospitality supply chains targeting luxury hotel minibar contracts.
United Arab Emirates
Dubai International anchors Gulf state demand for premium gin and whiskey miniature selections in first-class cabin service. The country's national standards body aligns with international aviation safety protocols for alcohol transport and storage. Emirates and Etihad procurement teams negotiate direct contracts with European distillers for exclusive miniature bundles.
Spirits Miniatures Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the spirits miniatures value chain. Distillers with aged stock portfolios compete on liquid quality credentials, while packaging specialists optimize substrate weight and compliance timelines. The structure segments into global beverage conglomerates, regional craft distillers, and substrate-focused packaging converters. Dominant competitive moves include duty-free exclusive bundling and multi-substrate manufacturing flexibility investments.
Among global beverage conglomerates, Diageo and Pernod Ricard exemplify archetypes leveraging global distribution architecture to secure airport hub placement. William Grant & Sons occupies a position within the family-owned distiller tier, differentiating through limited-edition releases tied to aged malt portfolios. These three companies represent contrasting strategic positions: scale-driven duty-free negotiation, heritage-focused collector market cultivation, and portfolio diversification across spirit categories.
| Leading Market Players |
|---|
| Beam Suntory |
| William Grant & Sons |
| Diageo |
| Plastipak Holdings |
| Graham Packaging |
| Pernod Ricard |
| Bacardi Limited |
| LYS Packaging |
| Brown-Forman |
| Others |
Value Network & Pricing Analysis
Aluminum substrate migration replacing glass in airline-served miniatures simultaneously redraws European supply geography and compresses per-unit pricing economics across transatlantic routes. REACH Annex XVII compliance timelines and London Metal Exchange volatility fragment procurement strategies between premium glass-retaining expressions and mass-market aluminum formats.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European distribution channels by forcing substrate reformulation costs into final pricing. Three-tier pricing structure across premium, standard, and economy levels separates super-premium glass-retaining whiskey expressions from aluminum gin formats and PET vodka miniatures. Price differentiation hinges on oxygen-barrier certification tier and volume procurement scale, with airline caterers showing highest sensitivity and collector segments demonstrating inelastic demand for age-statement releases. Cost compression in mid-tier aluminum formats is intensifying because smelting energy costs and ECHA registration fees stack onto base material inputs.
Supply Chain Analysis
Inventory lead times for specialty miniature glass extend 14-20 weeks due to concentrated borosilicate manufacturing in France and northern Italy. Geographic supply concentration centers on French glass foundries, Italian specialty bottle converters, and German aluminum extrusion facilities. Raw material dependencies draw from silica sand deposits, primary aluminum ingot, and food-grade polymer resins. Single-source vulnerability permeates premium whiskey miniature supply where Scottish distilleries rely on two French glass suppliers for heritage-format packaging. Distribution runs through duty-free airport operators, hospitality procurement consortia, and direct-to-consumer distillery webstores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spirits miniatures occupy an early-cycle expansion trajectory as airline passenger experience investments rebound and premium hospitality chains digitize minibar inventory systems. Collector market penetration through specialized e-commerce platforms remains underdeveloped relative to full-bottle secondary trading.
For Market Incumbents: Fortify substrate flexibility through multi-format manufacturing partnerships that hedge against REACH chemical compliance evolution and aluminum price volatility. Secure exclusive duty-free placement at Mumbai and Delhi airports ahead of competitor portfolio entries. Vertical integration into barrier-coated paperboard R&D protects margin position as airline weight restrictions intensify.
For New Entrants and Emerging Players: Anchor in biopolymer substrate innovation where PHA and PLA material advances combined with blow-molding improvements enable petroleum-free positioning. Target collector segments with age-statement miniature releases distributed through direct-to-consumer channels bypassing airport retail markups. Go-to-market leverage rests on distillery webstore exclusivity with batch-traceability documentation.
For Investors and Strategic Acquirers: Capital is best deployed toward packaging converters with multi-substrate certification capabilities spanning FDA, EFSA, and national EU labeling frameworks. Long-term viability favors specialists capable of navigating 18-24 month EU food-contact approval cycles without operational disruption. Signal to monitor: duty-free passenger traffic recovery rates at Dubai International and Singapore Changi as inflection indicator for premium miniature demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Substrate Manufacturing Flexibility | REACH Annex XVII compliance and airline weight restrictions reward converters capable of glass, aluminum, and polymer format switching. |
| Duty-Free Exclusive Bundling | Airport retail operators at Paris Charles de Gaulle and Dubai International commission region-specific assortments unavailable through domestic e-commerce. |
| Biopolymer Substrate Development | PHA and PLA material advances combined with blow-molding process improvements enable petroleum-free miniature bottles for sustainability-positioned brands. |
| Direct-to-Consumer Channel Expansion | Distillery webstores bypass airport retail markups for limited-edition releases targeting collector communities in the United States and United Kingdom. |
| Smart Inventory System Integration | RFID-tagged miniature formats with consumption-tracking capability address luxury hospitality chain demand for automated minibar replenishment. |
Research Methodology
Desk research of customs trade databases, SEC filings from packaging converters, and ECHA substance registration records preceded structured interviews with distillery procurement directors, airline catering supply managers, duty-free retail operators, and hospitality minibar category buyers. Primary fieldwork validated substrate migration timelines and pricing elasticity assumptions across glass, aluminum, and polymer formats. Secondary triangulation incorporated EU packaging waste directive implementation schedules and airline fuel surcharge methodologies. Bottom-up volume estimates from individual airport hub throughput reconciled against top-down spirits industry miniature format share assumptions.
Variance decomposition across the projection horizon isolates substrate substitution rates, regulatory compliance cost pass-through, and channel mix evolution as primary uncertainty sources. Segmentation dimensions modeled include spirit category, packaging substrate, end-use application, and distribution channel with geographic regulatory cluster overlay. CAGRs derive from logistic diffusion curves fitted to airline passenger recovery patterns and hospitality capital expenditure cycles. Industry-specific forecast inputs encompass London Metal Exchange aluminum forward curves and ECHA food-contact approval pipeline status.
Decision-makers should treat outputs as directional under sustained airline passenger experience investment and REACH enforcement continuity assumptions; material deviation would warrant model refresh. Specific risk factors include abrupt single-use plastics directive enforcement acceleration, aluminum smelting energy cost spikes, and duty-free passenger traffic stagnation at major hub airports. Revision becomes warranted when biopolymer substrate cost parity crosses threshold viability against petroleum-based alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
Global Beer Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
Cannabis Drinks Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
Canned Wine Market
Alcoholic Beverages
Wine Cellar Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Rum Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Moscato Wine Market