
 Whey Based Vodka Market | 2026-2036
Whey Based Vodka Market Size, Share, and Industry Trends Forecast 2026-2036
Whey Based Vodka Market Analytics
Precision fermentation of dairy whey is reconfiguring how distilleries source base alcohol, replacing traditional grain and potato substrates with lactose-rich byproduct streams. Broken Shed Distilleries leverages New Zealand whey supply chains to anchor its production economics. Wheyward Spirit differentiates through closed-loop partnerships with regional cheesemakers. Yes Whey competes on flavor neutrality achieved through advanced enzymatic treatment of whey permeate.
Whey based vodka denotes a clear distilled spirit manufactured by fermenting lactose derived from cheese production byproducts, typically achieving 95% ABV before dilution to bottling strength; the process yields a gluten-free, subtly sweet base spirit marketed toward allergen-conscious and sustainability-oriented drinkers. Premium vodka commands the highest margin pool among product type segments, while flavored vodka extends addressable occasions through botanical and fruit infusions. Online stores represent the fastest-growing distribution channel, though bars retain disproportionate influence on consumer trial and brand discovery.
The Alcohol and Tobacco Tax and Trade Bureau (TTB) governs label standards and production permits for whey-based spirits in the United States, while the FDA oversees lactose-derived ingredient safety classifications. EFSA's novel food evaluations shape whey vodka market access across European Union member states. Stakeholders must monitor evolving dairy waste classification rules and craft spirit tax incentives that determine regional production viability.
Market Dynamics
The EU Green Deal's circular economy mandates are forcing dairy processors and distilleries into formal valorization partnerships, transforming whey from waste liability to contracted feedstock. This regulatory compression is restructuring supplier-buyer power dynamics across the spirits value chain.
Growth Catalysts
- Farm-to-bottle movements:Regional craft distilling clusters in the United States leverage proximity to dairy operations, shortening feedstock transport distances and locking in supply security through direct farmer contracts.
- REACH compliance pathways:ECHA's streamlined chemical safety assessments for fermentation-derived alcohols are reducing novel food approval timelines for whey-based spirits entering European markets.
- Precision fermentation advances:Enzymatic lactose hydrolysis technologies are improving fermentation efficiency, enabling smaller-batch production economics that match artisanal positioning.
Market Restraints
- Whey supply seasonality:Cheese production cycles create feedstock availability mismatches, forcing distilleries to invest in cold storage infrastructure or accept volatile input costs.
- Grain vodka substitution threat:Established commodity vodka producers benefit from decades of brand equity and scale economies that whey-based entrants cannot immediately match on shelf price.
- TTB label friction:The Alcohol and Tobacco Tax and Trade Bureau's classification ambiguity around "whey spirits" terminology creates permit delays and marketing restrictions for new entrants.
Strategic Opportunities
- Online direct-to-consumer channels:E-commerce platforms bypass traditional three-tier distribution, allowing craft whey vodka brands to capture margin and build subscription relationships with sustainability-conscious households.
- Carbon labeling convergence:EU Green Deal corporate sustainability reporting requirements are creating procurement preference for verified low-carbon spirits among hospitality groups.
- Botanical infusion extensions:Flavored vodka applications leveraging whey vodka's subtle sweetness profile open occasion expansion into dessert cocktails and aperitif segments.
Industry Challenges
- Fermentation microbiology expertise gap:Distilleries struggle to hire lactose-optimized yeast strain specialists, slowing process optimization and batch consistency achievement.
- Co-product handling complexity:Post-distillation whey residue management requires coordination with agricultural regulators and local waste authorities, adding operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whey Based Vodka Market |
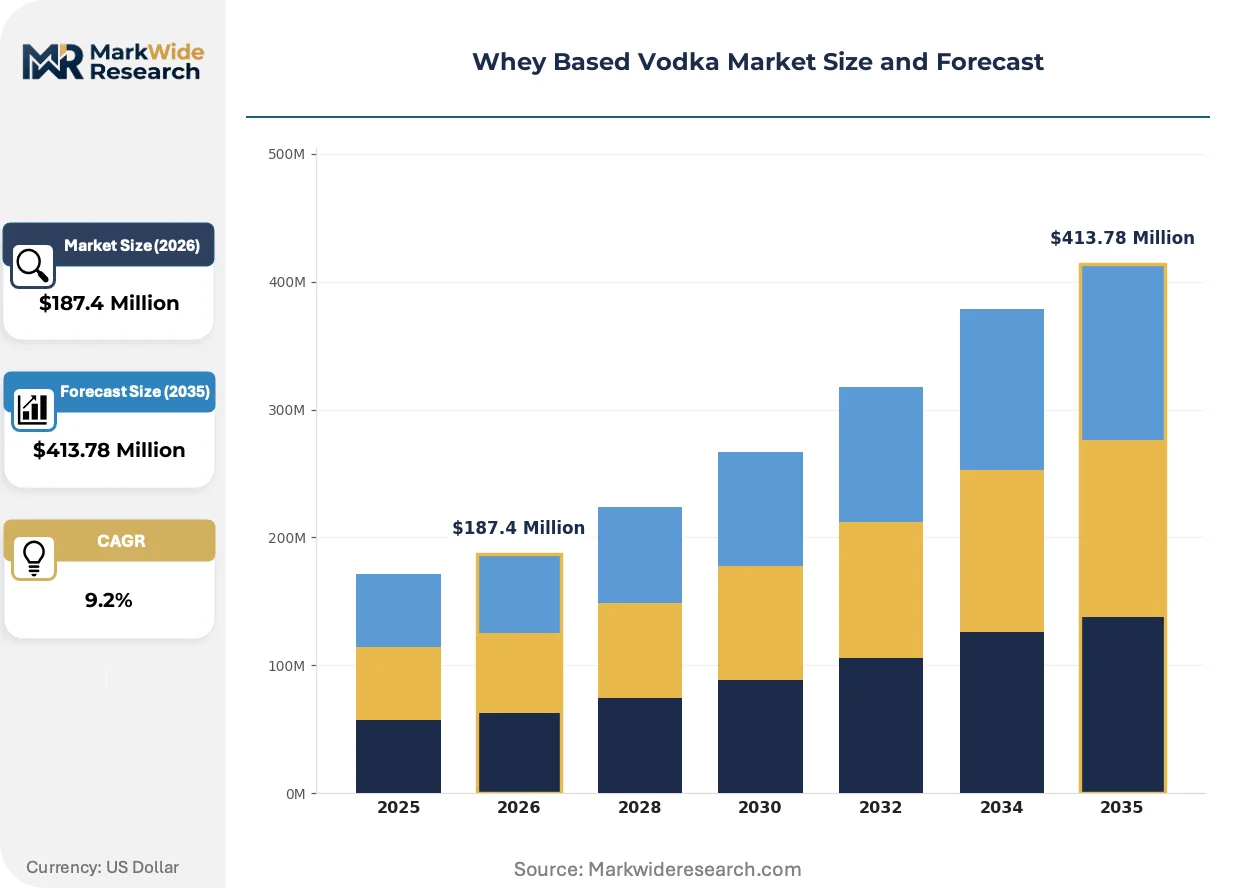
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $413.78 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Vodka, Flavored Vodka, Organic Vodka, Premium Vodka Distribution Channel: Retail Stores, Online Stores, Duty-Free Shops, Bars End User: Consumers, Hotels, Restaurants, Catering Services Alcohol Content: 35% ABV, 40% ABV, 45% ABV, Others |
| Companies Covered | Yes Whey, Broken Shed Distilleries, Wheyward Spirit, TMK Creamery and Distillery, TenHead Distillery, Vermont Spirits, Carbery, Lactanol, ONE ROQ Spirits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whey Based Vodka Market Evolving Landscape
Sustainability credentialing is becoming the primary axis of competitive differentiation, with carbon footprint verification and circular economy storytelling displacing traditional provenance marketing. Three technological and behavioral shifts are compressing incumbent advantage windows.
Enzymatic treatment of whey permeate is collapsing the flavor neutrality gap between dairy-derived and grain-based base spirits. Craft cocktail bars in Copenhagen and Brooklyn are adopting these vodkas for signature programs that highlight ingredient transparency. The technology is collapsing price premiums previously commanded by ultra-premium wheat vodkas, forcing grain incumbents to defend position through heritage narrative rather than functional superiority.
EFSA's novel food evaluation frameworks are tightening safety documentation requirements for lactose-derived alcohols entering European Union commerce. Distilleries must now submit comprehensive toxicological dossiers before market authorization. Small-scale producers in France and Ireland are responding by pooling regulatory compliance resources through cooperative structures.
Certification-driven purchasing is reshaping hospitality procurement, with sustainability officers at hotel chains and restaurant groups mandating third-party verified spirits. Whey vodka's inherent circular economy narrative satisfies these procurement screens where conventional grain vodka fails. This pattern concentrates most visibly in Nordic markets, where government procurement guidelines prioritize climate-impact disclosures for all beverage alcohol purchases.
Whey Based Vodka Market Segmentation
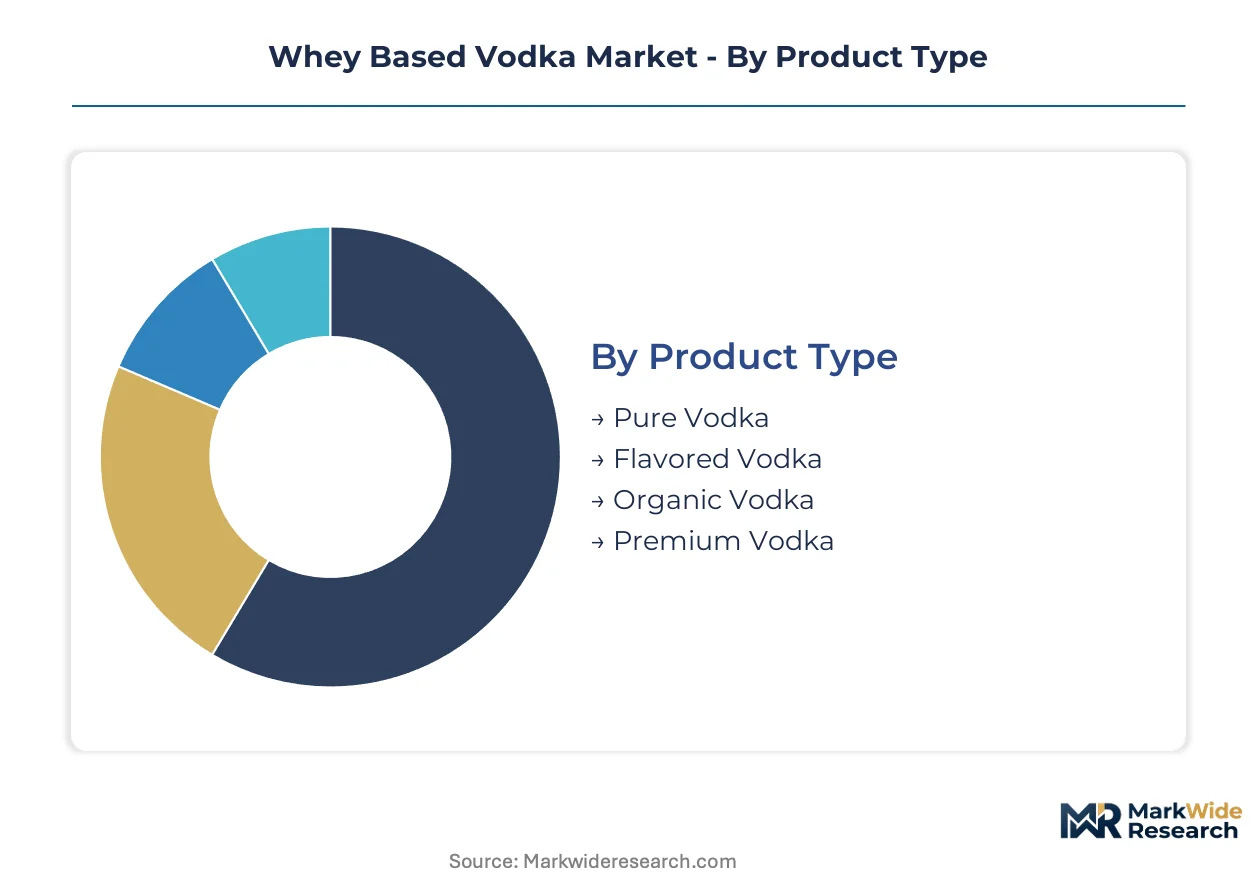
Whey vodka producers must navigate divergent margin structures across product tiers while distribution channel fragmentation reshapes customer acquisition economics. Segmentation reveals where sustainability premiums convert to pricing power versus commodity pressure.
Product Type:
Use-case spectrum spans entry-level mixing spirits through certified organic sipping vodkas, with protein-origin storytelling commanding tiered price realization.
- Premium Vodka:Achieves 95% ABV through multi-column distillation of hydrolyzed whey permeate, positioning for craft cocktail bars in Copenhagen and Brooklyn where ingredient transparency drives menu placement. The segment captures highest absolute margins through limited-batch releases and single-origin dairy partnerships.
- Flavored Vodka:Botanical and fruit infusions leverage whey vodka's subtle residual sweetness for dessert cocktail and aperitif occasions, extending addressable drinking moments beyond traditional vodka occasions. Expansion concentrates in Nordic markets where flavor innovation commands hospitality procurement preference.
- Pure Vodka:Unflavored base spirit targeting gluten-free and allergen-conscious households through enzymatically treated lactose fermentation.
- Organic Vodka:Certified organic whey feedstock from grass-fed dairy operations, appealing to sustainability-verified procurement channels.
The dominant share belongs to Premium Vodka, while Flavored Vodka is closing the gap fastest.
Distribution Channel:
Channel cost structures determine brand building feasibility for craft entrants versus incumbent shelf presence.
- Online Stores:Direct-to-consumer platforms bypass three-tier distribution markups, enabling subscription relationships with sustainability-conscious households and margin retention for small-batch producers. E-commerce expansion accelerates most quickly in markets with relaxed spirits shipping regulations.
- Bars:On-premise trial drives brand discovery through bartender advocacy and signature cocktail programs, though slotting fees and inventory risk concentrate power with established distributors. Brooklyn and Copenhagen cocktail bars anchor early adoption clusters for whey vodka visibility.
- Retail Stores:Off-premise shelf placement demands distributor relationships and TTB label compliance investment, favoring scaled producers.
- Duty-Free Shops:Travel retail exposure targets international tourists with sustainability storytelling in airport environments.
Online Stores are expanding most quickly, though Bars retain disproportionate influence on consumer trial.
End User:
Procurement authority differs sharply between individual purchase decisions and institutional sustainability mandates.
- Restaurants:Menu placement decisions integrate corporate sustainability reporting requirements, with whey vodka's circular economy narrative satisfying EU Green Deal procurement screens where conventional grain vodka fails. Nordic hotel chains and restaurant groups mandate third-party verified spirits.
- Consumers:Direct purchases respond to allergen-free positioning and farm-to-bottle storytelling, with regional craft distilling clusters in the United States leveraging proximity to dairy operations for supply security.
- Hotels:Beverage program standardization across properties favors contract relationships with verified low-carbon spirits suppliers.
- Catering Services:Event-based demand fluctuates with seasonal celebration patterns and corporate hospitality budgets.
Restaurants command the highest volume commitment per account, while Consumers deliver the steepest expansion trajectory through direct channel adoption.
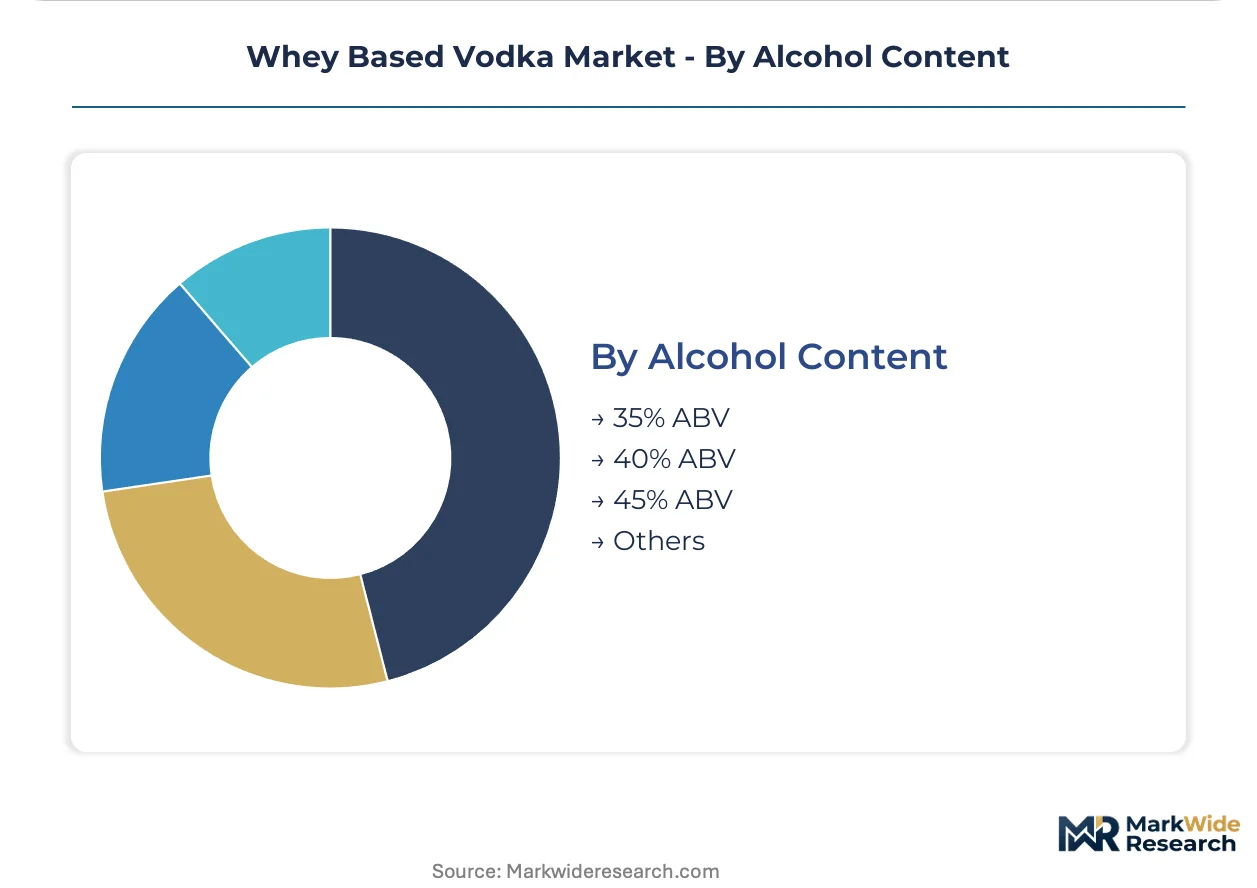
Alcohol Content:
Proof standards align with regional regulatory floors and mixing versus sipping occasions.
- 40% ABV:Standard bottling strength meeting TTB minimums for vodka classification in the United States and EFSA novel food frameworks in European Union markets. Dominates commercial volume through compatibility with established cocktail specifications.
- 45% ABV:Elevated proof for bartender-preferred mixing applications where dilution control matters, concentrated in craft cocktail bar adoption.
- 35% ABV:Reduced proof variants targeting flavored vodka extensions and lower-tariff regulatory categories in select jurisdictions.
- Others:Specialty proofs including cask-strength releases and market-specific regulatory adaptations.
40% ABV holds established share leadership, while 45% ABV gains ground fastest among on-premise specialist accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in whey-based vodka remain nascent, with production concentrated in domestic craft clusters rather than cross-border trade. Regional regulatory differentiation shapes where fermentation capacity expands fastest.
United States
Farm-to-bottle movements in Wisconsin and New York drive regional whey vodka production, with craft distilleries locking supply contracts with nearby cheesemakers. TTB label standards and production permits govern market entry, though classification ambiguity around "whey spirits" creates friction. Brooklyn and Hudson Valley anchor early adoption clusters where bartenders feature ingredient transparency on cocktail menus.
New Zealand
Dairy waste valorization partnerships transform whey from disposal liability to contracted feedstock for distillation operations. Biosecurity regulations and agricultural waste management frameworks shape processor-distillery coordination. Broken Shed Distilleries leverages South Island whey supply chains to anchor production economics in Canterbury dairy heartland.
France
Artisanal distilling traditions merge with circular economy mandates under EU Green Deal implementation, accelerating whey fermentation adoption in Normandy and Brittany. EFSA novel food evaluation requirements demand comprehensive toxicological dossiers before market authorization. Small-scale producers in Calvados and Côtes-d'Armor respond by pooling regulatory compliance resources through cooperative structures.
Ireland
Grass-fed dairy operations supply certified organic whey feedstock for premium vodka positioning targeting sustainability-verified procurement channels. EPA waste licensing and agricultural residue handling rules determine post-distillation residue management protocols. County Cork and County Tipperary concentrate production where Carbery maintains dairy processing integration.
Sweden
Government procurement guidelines prioritize climate-impact disclosures for beverage alcohol purchases, concentrating demand for verified low-carbon spirits in Stockholm and Gothenburg hospitality markets. REACH compliance pathways streamline chemical safety assessments for fermentation-derived alcohols. Nordic hotel chains mandate third-party verified spirits across beverage programs.
Whey Based Vodka Market Competitive Landscape
On the supply side, the industry is fragmented across craft-scale distilleries and dairy-integrated processors, with no dominant volume leader emerging yet. Strategic archetypes include dairy-processor spinoffs leveraging captive whey streams, independent craft distilleries building regional farm partnerships, and contract fermentation specialists serving private-label brands. Competitive moves concentrate on strategic partnerships with cheesemakers for feedstock security and capacity expansion through modular fermentation systems.
Within the craft distillery archetype, Yes Whey, Broken Shed Distilleries, and Wheyward Spirit occupy positions illustrating distinct geographic and partnership strategies. Yes Whey exemplifies flavor neutrality achievement through advanced processing. Broken Shed Distilleries anchors New Zealand supply chain integration. Wheyward Spirit represents closed-loop regional cheesemaker partnership models. These three collectively demonstrate how sustainability credentialing and feedstock proximity define competitive positioning in this emerging category.
| Leading Market Players |
|---|
| Yes Whey |
| Broken Shed Distilleries |
| Wheyward Spirit |
| TMK Creamery and Distillery |
| TenHead Distillery |
| Vermont Spirits |
| Carbery |
| Lactanol |
| ONE ROQ Spirits |
| Others |
Value Network & Pricing Analysis
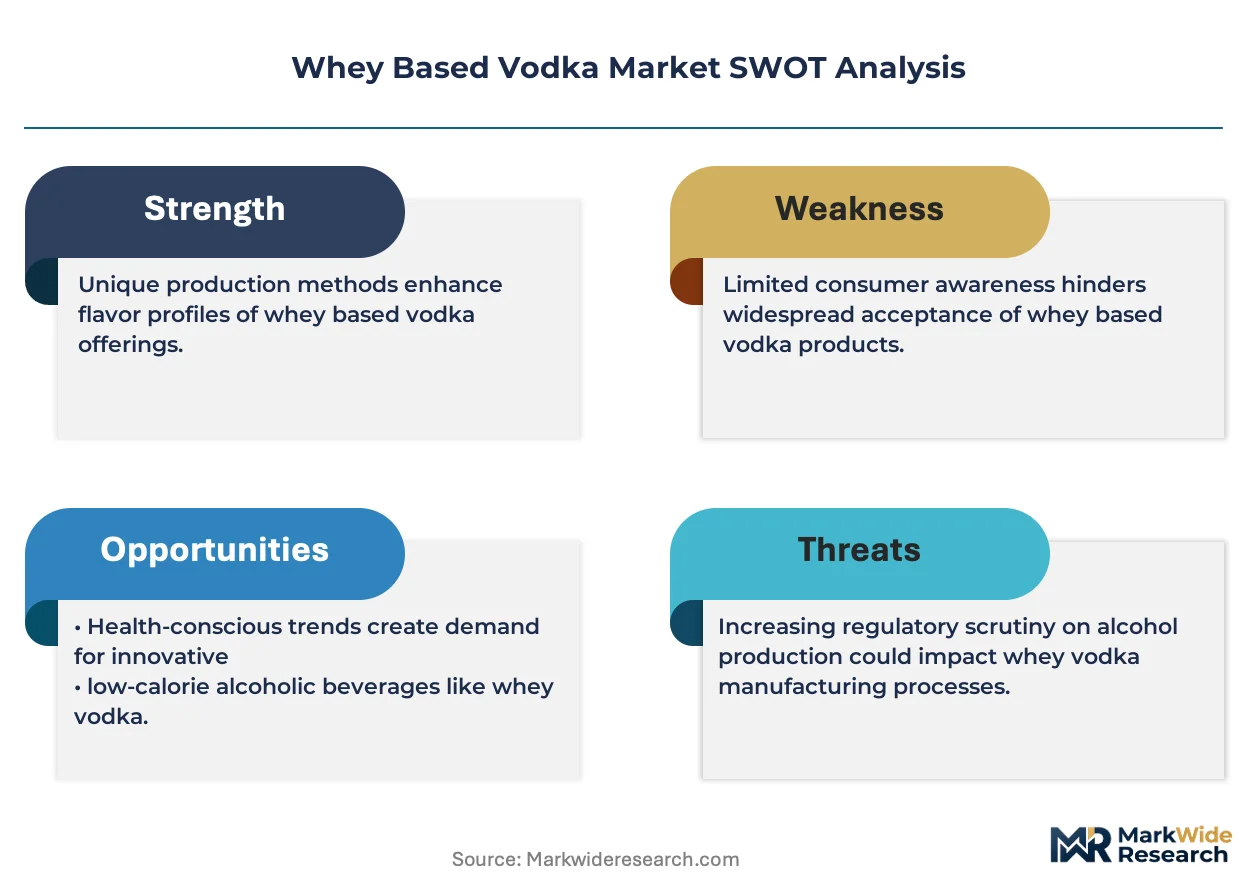
Undercapacity in New Zealand whey processing facilities is compressing feedstock contract terms and forcing distilleries toward premium positioning to recover input cost volatility. This utilization squeeze simultaneously tightens supplier bargaining power and rewards brands that can pass through sustainability premiums to allergen-conscious buyers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that locks cheese processors into multi-year whey supply agreements. Price differentiation rests on certification grade (organic grass-fed versus conventional dairy) and volume scale, with small-batch producers facing cost compression as cold storage infrastructure investments strain working capital. Pricing pressure stems from grain vodka incumbents defending shelf position through promotional discounting. Hospitality procurement teams demonstrate lowest price sensitivity, while retail channel consumers exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and European Union dairy markets dominates supply chain risk assessment for whey vodka exporters. Feedstock concentration centers on New Zealand, the United States, and Ireland, with enzymatic lactose hydrolysis equipment and specialized fermentation yeast strains representing critical component dependencies. Single-source vulnerability in precision fermentation technology suppliers creates chokepoint exposure. Distribution runs through three-tier wholesale networks for retail penetration, though direct-to-consumer e-commerce is displacing traditional routes for craft entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Circular economy platform economics are reconfiguring spirits procurement, with EU Green Deal interoperability requirements forcing distillery-cheesemaker data sharing on carbon footprint verification.
For Market Incumbents: Pre-empt grain vodka substitution threats by deepening backward integration into regional dairy operations and securing exclusive organic whey streams. Lock in TTB label classification clarity through early regulatory engagement before competitors exploit permit delays. Certification investment in EFSA novel food frameworks defends European market access against emerging entrants. For New Entrants and Emerging Players: Build out white-space presence in Nordic hospitality procurement channels where government sustainability mandates create verified low-carbon spirits demand. Target online direct-to-consumer subscription models as the most penetrable distribution vector, bypassing three-tier markups. Lead go-to-market with carbon labeling transparency that satisfies corporate sustainability reporting requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular fermentation system deployments, reducing minimum viable scale thresholds. Long-term viability favors acquisition targets with locked dairy processor partnerships and established EFSA dossier progress. Watch for TTB classification clarity on "whey spirits" terminology as the signal indicating regulatory friction resolution and category legitimization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Operations | Captures whey feedstock security through direct cheesemaker contracts in Wisconsin and New York. |
| EFSA Novel Food Dossier Submission | Unlocks EU market access through streamlined REACH compliance pathways for fermentation-derived alcohols. |
| Direct-to-Consumer Platform Launch | Bypasses three-tier distribution markups and builds subscription relationships with sustainability households. |
| Carbon Labeling Certification Program | Satisfies Nordic government procurement guidelines mandating climate-impact disclosures for beverage alcohol. |
| Modular Fermentation Capacity Expansion | Enables small-batch economics matching artisanal positioning through enzymatic lactose hydrolysis advances. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with distillery operations managers, dairy processor procurement leads, craft cocktail bar beverage directors, and TTB regulatory affairs specialists; and secondary validation against FDA lactose classification rulings, EFSA novel food evaluation databases, EU Green Deal circular economy implementation reports, and customs trade flow records. Bottom-up fermentation capacity estimates triangulated against top-down spirits category consumption models.
Forecast inputs span product type tiering, distribution channel fragmentation, ABV regulatory categories, and end-user procurement authority across the projection horizon. CAGRs were derived from segmented volume build-ups incorporating whey supply seasonality patterns and craft distilling permit approval timelines. Modeled variables include enzymatic treatment technology adoption curves and sustainability certification penetration rates.
Practitioners should monitor TTB classification rulings, EFSA evaluation timelines, and EU dairy waste reclassification proposals for early signals of regulatory friction or acceleration. Forecasts embed assumptions on feedstock contract standardization and carbon labeling convergence that warrant reassessment against operating developments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Food-Grade Alcohol Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Mezcal Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Pub Cellar Equipment Market
Alcoholic Beverages
Alcoholic Flavors Market
Alcoholic Beverages
Grain Alcohol Market
Alcoholic Beverages
Rhum Agricole Market
Alcoholic Beverages
Fruit Brandy Market
Alcoholic Beverages
Mead Beverage Market
Alcoholic Beverages
Europe Tequila Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
Global Wine Coolers Market
Alcoholic Beverages
Russia Tequila Market
Alcoholic Beverages
Isoamyl Alcohol Market
Alcoholic Beverages
Mushroom Beer Market