
 Hard Tea Market | 2026-2036
Hard Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Hard Tea Market Intelligence
The shift toward spirits-based formulations using real brewed tea is unwinding the market's reliance on malt-based flavor systems. Boston Beer Company sustains its leadership through the scale of its Twisted Tea brand. Molson Coors competes by expanding its portfolio of non-beer alcoholic beverages. Meanwhile, Constellation Brands leverages its distribution network to introduce new hard tea products.
Hard tea is an alcoholic ready-to-drink beverage made by fermenting or mixing brewed tea with an alcohol source like malt or distilled spirits. These products typically feature an alcohol by volume between 4% and 7% and are designed as alternatives to beer and hard seltzers. Among flavor profiles, Citrus and Berry variants command the largest share due to broad consumer appeal. The Medium alcohol content category sees the highest sales velocity, primarily through off-premise distribution channels like grocery and convenience stores.
Producers navigate a complex regulatory environment defined by bodies like the US Alcohol and Tobacco Tax and Trade Bureau (TTB) and Health Canada. These agencies' rules on alcohol base type directly influence product taxation, labeling, and market access pathways. Beverage manufacturers must therefore decide whether to pursue malt-based or spirits-based formulations, a choice that fundamentally shapes their go-to-market strategy and cost structure.
Market Dynamics
The hard tea market's trajectory is fundamentally shaped by the regulatory and cost distinctions between malt-based and spirits-based formulations. This bifurcation forces producers to make foundational strategic choices that dictate taxation, distribution pathways, and ultimate product positioning.
Growth Catalysts
- Favorable Demographics:Demand from millennial and Gen Z consumers for lower-calorie, sessionable alcoholic beverages drives adoption, as these cohorts seek alternatives to traditional beer and wine.
- Product Innovation:The introduction of sugar-free options and the use of exotic fruit and botanical flavorings are broadening the product's appeal beyond classic lemon and peach profiles.
- Channel Expansion:In markets like the United States and Canada, legislative changes are expanding the availability of ready-to-drink products in grocery and convenience store channels, increasing consumer access.
Market Restraints
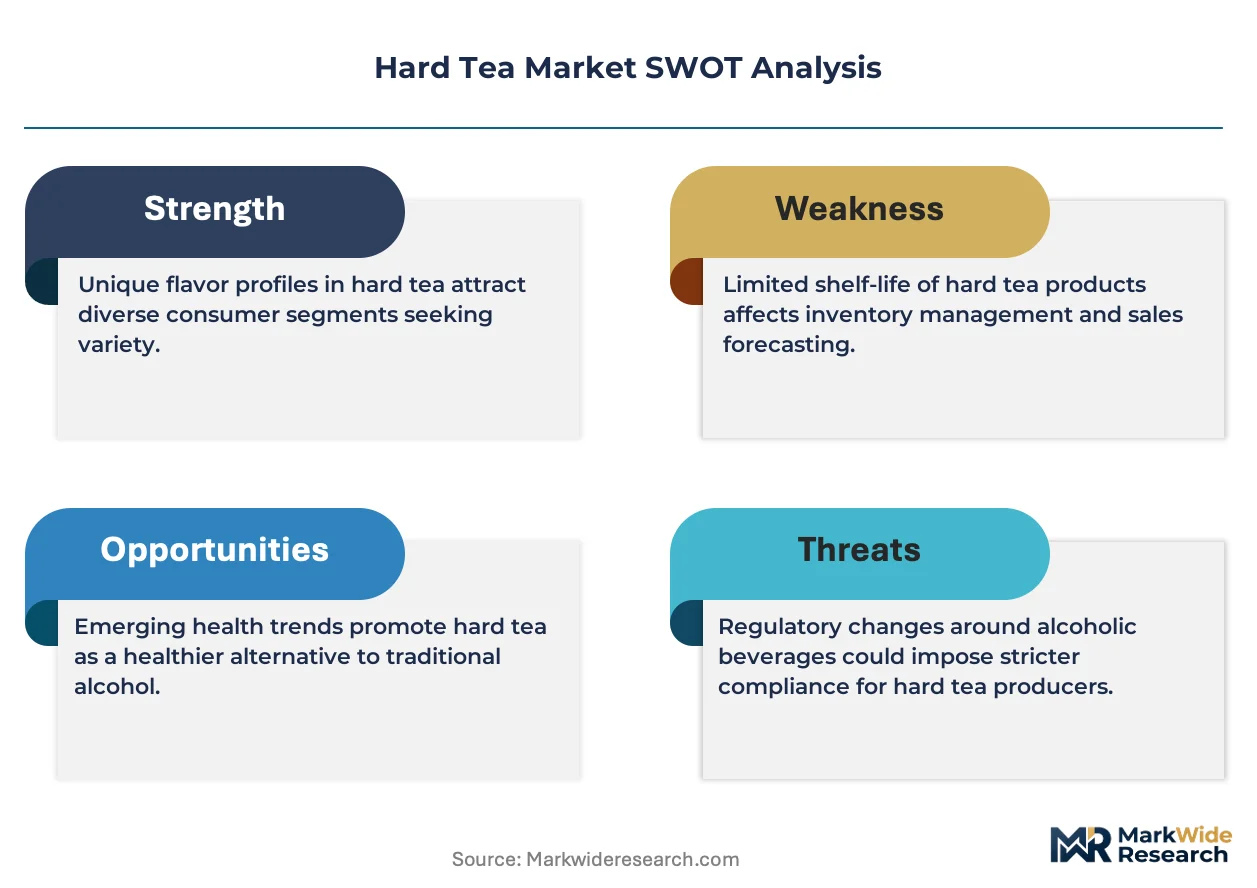
- Regulatory Complexity:Divergent taxation and distribution laws for spirits-based versus malt-based beverages, enforced by bodies like the US TTB, create significant compliance and cost hurdles.
- Input Cost Volatility:Producers are exposed to price fluctuations for key agricultural inputs, including specific varietals of tea leaves, cane sugar, and natural fruit flavorings.
- Intense Competition:Hard tea competes for limited retail shelf space and consumer share-of-mind against established ready-to-drink categories like hard seltzer, canned cocktails, and wine spritzers.
Strategic Opportunities
- Geographic Expansion:Significant white space exists in markets with strong non-alcoholic tea traditions but low hard tea penetration, such as the United Kingdom, Germany, and Japan.
- Premiumization:Developing high-end hard teas using artisanal tea blends, premium spirits, and sophisticated packaging can capture value from consumers willing to pay more for craft products.
- On-Premise Presence:Expanding into on-premise channels like bars, restaurants, and event venues via draft offerings and as a cocktail ingredient opens a new revenue stream beyond off-premise retail.
Industry Challenges
- Production Consistency:Maintaining a uniform flavor profile at industrial scale is a significant challenge when using real brewed tea, which is subject to natural batch and seasonal variations.
- Labeling Compliance:Adhering to complex labeling mandates from regulators regarding the declaration of alcohol base, nutritional facts, and allergen information requires specialized legal and operational expertise.
- Distribution Access:New and smaller brands face high barriers to entry in securing partnerships within the entrenched, multi-tiered alcohol distribution system dominated by larger players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hard Tea Market |
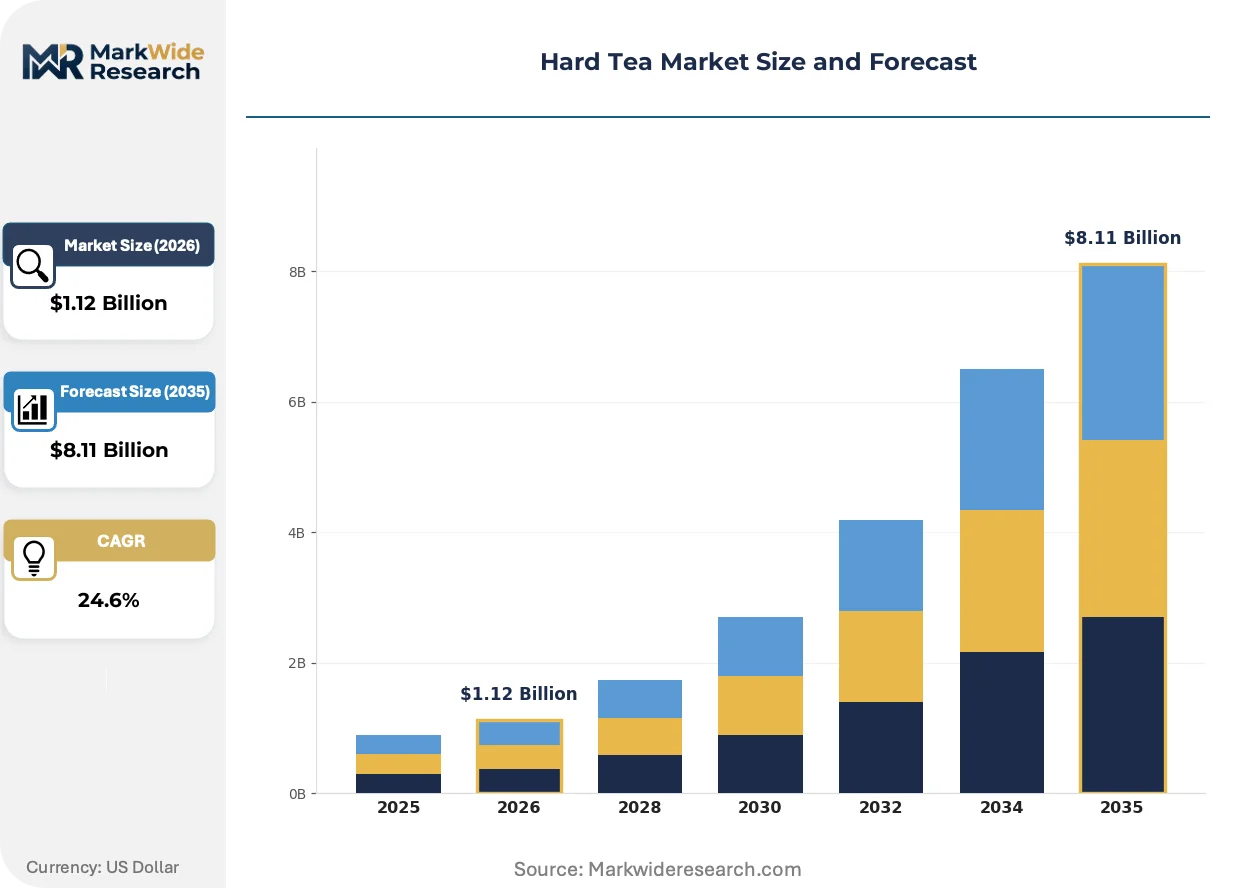
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $8.11 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Can, Bottle, Draft, Keg Flavor Profile: Citrus, Berry, Herbal, Spiced Alcohol Content: Low, Medium, High, Ultra Distribution Channel: Retail, Online, On-Premise, Off-Premise |
| Companies Covered | Boston Beer Company, Molson Coors Beverage Company, Anheuser-Busch InBev, Pabst Brewing Company, Constellation Brands, Diageo, Loverboy Inc., Cisco Brewers, Two Chicks Drinks LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hard Tea Market Strategic Shifts & Innovations
Product sophistication is reshaping the hard tea category, moving it beyond simple malt-based alternatives toward beverages defined by authentic ingredients and transparent production methods. This evolution reflects a broader consumer demand for higher-quality, ready-to-drink options.
Spirits-based formulations that feature real brewed tea offer a more authentic taste and cleaner ingredient panel. Health-conscious consumers are increasingly choosing these products over legacy malt-based versions. This consumer-led shift toward premium ingredients is supplanting the market's historical reliance on artificial flavor systems and high-fructose corn syrup.
The US Alcohol and Tobacco Tax and Trade Bureau (TTB) continues to enforce rules that create distinct tax and distribution frameworks for malt-based versus spirits-based ready-to-drink beverages. This regulatory divergence directly influences a manufacturer's cost structure and go-to-market strategy. Consequently, the choice of alcohol base becomes a critical decision that affects a product's final price, channel eligibility, and consumer perception of quality.
A prominent behavioral shift is the rising consumer use of direct-to-consumer (DTC) websites and third-party alcohol delivery applications for purchasing hard tea. This e-commerce trend enables smaller, craft-oriented brands to bypass gatekeepers in the traditional three-tier distribution system and build direct relationships with their customers. This model is gaining the most traction in dense urban markets across North America and Europe with mature logistics networks.
Hard Tea Market Segmentation
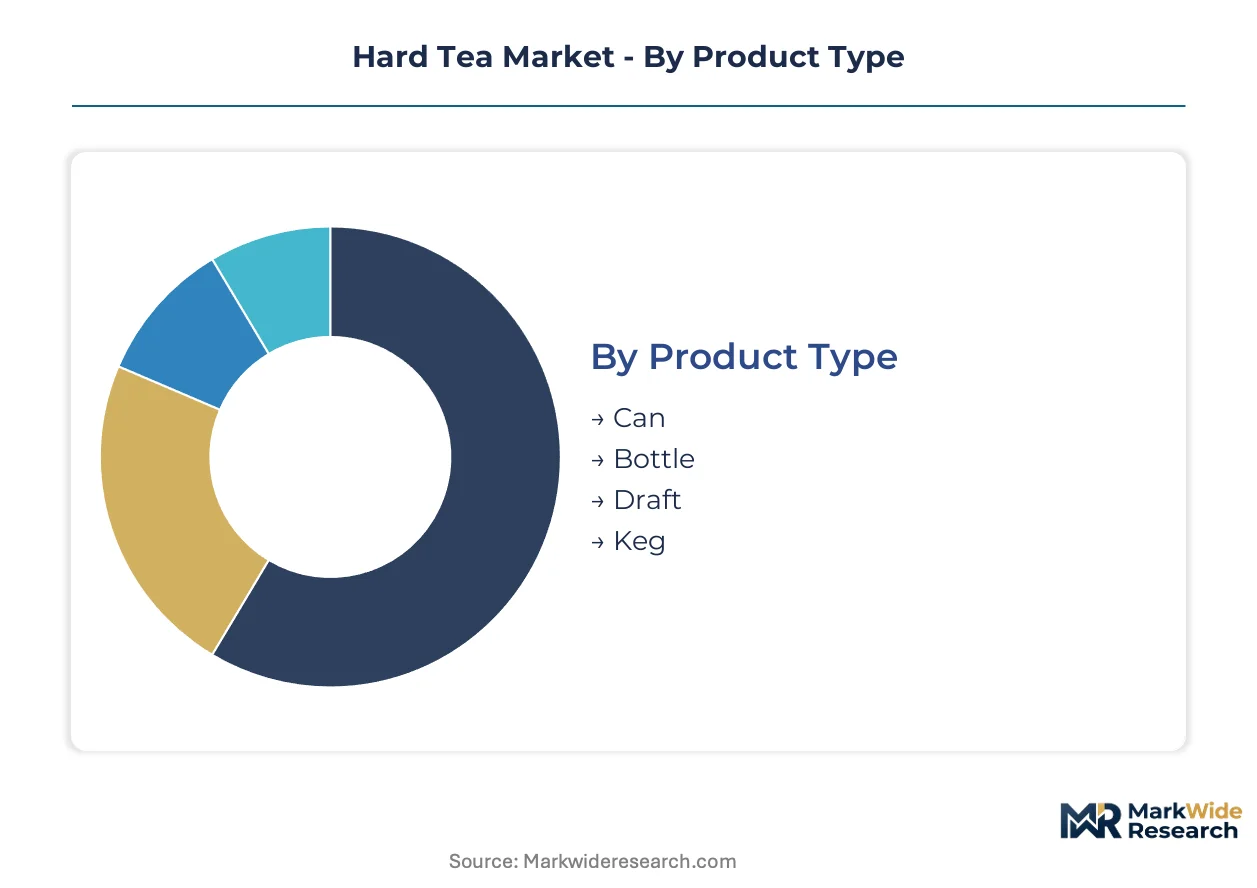
The Hard Tea market delineates across several dimensions, reflecting diverse consumer preferences and varied go-to-market strategies. Understanding these segments is critical for producers to tailor product development, optimize distribution networks, and effectively target specific consumer cohorts. This granular analysis provides a framework for assessing market opportunities and competitive positioning within the evolving beverage alcohol landscape.
Product Type:
Product packaging directly influences distribution channels, with certain formats dominating off-premise retail while others cater to on-premise consumption or home delivery.
- Can:Canned hard tea products, typically aluminum, offer portability, light protection, and rapid chilling, making them ideal for outdoor events and casual consumption. Demand concentrates within off-premise channels like grocery stores and convenience outlets, driven by consumer preference for single-serve, grab-and-go convenience.
- Bottle:Bottled hard teas, often glass, convey a premium aesthetic and can preserve flavor integrity over longer periods, appealing to consumers seeking a more refined experience. These formats find strong demand in both off-premise specialty stores and on-premise venues where presentation and perceived quality are paramount.
- Draft:Draft hard tea, served from kegs, provides a fresh, taproom-style experience for on-premise establishments, enhancing social consumption settings.
- Keg:Kegs enable bulk supply to bars and restaurants, supporting high-volume on-premise sales and reducing packaging waste for operators.
Can products dominate the hard tea installed base. Bottle formats concentrate expansion for on-premise premiumization.
Flavor Profile:
Consumer taste preferences significantly shape the market for hard tea, influencing product innovation and seasonal offerings across various regions.
- Citrus:Citrus-flavored hard teas, including lemon, lime, and grapefruit, deliver a refreshing and tangy taste profile, resonating with a broad consumer base seeking crisp beverages. This segment commands the largest market share, particularly in North American urban centers, due to its classic appeal and versatility.
- Berry:Berry variants, encompassing strawberry, raspberry, and blueberry, offer a sweet and often tart flavor, appealing to consumers desiring fruit-forward and approachable options. Demand for these profiles is strong among younger demographics in coastal regions, who often favor sweeter and more experimental beverage choices.
- Herbal:Herbal hard teas, featuring ingredients like mint or hibiscus, cater to consumers seeking unique, sophisticated, and often less sweet flavor experiences.
- Spiced:Spiced hard teas, infused with elements such as ginger or cinnamon, provide warming and complex notes, often gaining traction during colder seasons or for specific culinary pairings.
Citrus flavors maintain widespread appeal. Herbal and Spiced profiles gain traction among consumers seeking novel taste experiences.
Alcohol Content:
Different alcohol content levels cater to varied consumer drinking occasions and preferences, from sessionable options to more potent alternatives.
- Medium:Medium alcohol content hard teas, typically ranging from 4% to 7% ABV, strike a balance between flavor and effect, making them highly sessionable. This segment experiences the highest sales velocity, especially among millennial consumers in metropolitan areas, who value controlled consumption and sustained enjoyment.
- Low:Low alcohol content products, typically below 4% ABV, target health-conscious consumers seeking lighter, less intoxicating options for extended social occasions. Demand is growing among Gen Z consumers in wellness-focused markets, who prioritize moderation and calorie awareness.
- High:High alcohol content hard teas, often above 7% ABV, offer a more potent drinking experience for consumers desiring stronger effects from fewer servings.
- Ultra:Ultra alcohol content variants, exceeding 10% ABV, serve a niche market of consumers seeking maximum potency, often mimicking spirits-based ready-to-drink cocktails.
The medium alcohol content segment drives the bulk of hard tea sales. Low ABV options are gaining share fastest among health-conscious and younger consumer groups.
Distribution Channel:
Distribution channels significantly impact product accessibility, pricing strategies, and ultimately, the profitability margins for hard tea manufacturers.
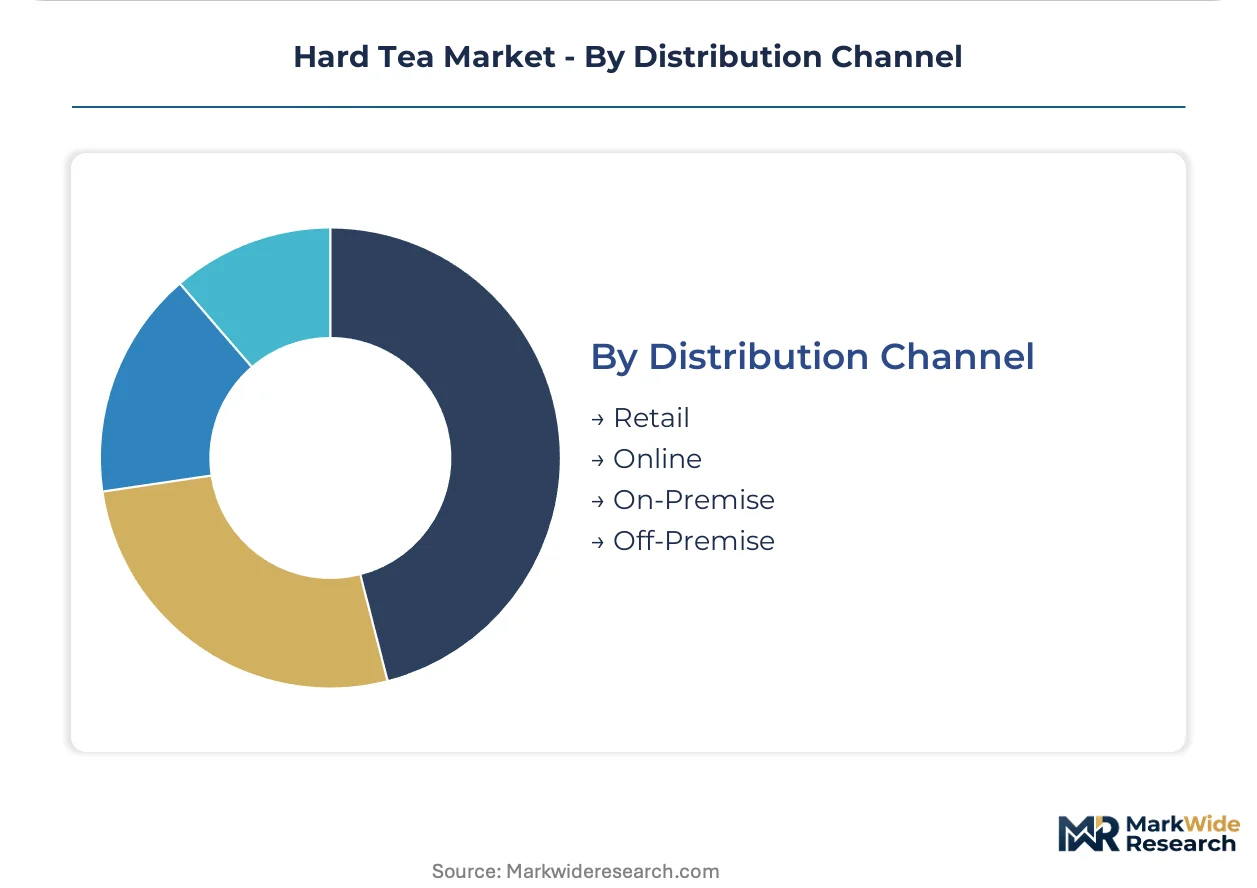
- Off-Premise:Off-premise channels, encompassing grocery stores, convenience stores, and liquor shops, serve as the primary sales avenue for hard tea, enabling home consumption. This channel drives the majority of market volume, fueled by consumer demand for convenience and competitive pricing, especially in suburban and rural areas.
- Online:Online distribution, through direct-to-consumer websites and third-party delivery apps, offers convenience and expanded reach for niche hard tea brands. This channel grows rapidly in dense urban markets across North America and Europe, supported by mature logistics and evolving consumer purchasing habits.
- Retail:Retail distribution broadly covers physical stores where products are sold directly to consumers, including both off-premise and some specialized on-premise outlets.
- On-Premise:On-premise channels like bars, restaurants, and event venues provide immediate consumption opportunities, often influencing brand perception through curated experiences.
Off-premise sales remain the foundation of hard tea distribution. Online channels are demonstrating significant potential for market penetration and brand building.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration in the hard tea market primarily reflects established distribution networks and consumer familiarity within key North American economies. Producers leverage existing alcohol infrastructure to scale operations and accelerate product penetration. This strategic focus on mature markets supports early-stage category development before wider international expansion.
United States
Demand in the United States is strong among millennial and Gen Z consumers seeking lower-calorie alcoholic alternatives. The US Alcohol and Tobacco Tax and Trade Bureau (TTB) regulates alcohol base types, influencing taxation and labeling. Urban centers like New York City and Los Angeles show high demand for spirits-based hard tea products.
Canada
Canadian consumers increasingly adopt hard tea as an alternative to traditional beer and hard seltzers. Health Canada establishes guidelines for alcoholic beverage labeling and marketing, impacting product messaging. Major metropolitan areas such as Toronto and Vancouver exhibit robust sales velocity through expanded retail channels.
United Kingdom
The United Kingdom presents significant growth opportunities due to its strong non-alcoholic tea tradition and evolving consumer preferences. UK excise duties differentiate between various alcohol categories, influencing product pricing and market entry strategies. London's vibrant hospitality sector offers a prime environment for on-premise hard tea consumption.
Germany
German consumers are exploring new ready-to-drink options, creating an opening for hard tea products. The German Federal Ministry of Food and Agriculture oversees food and beverage regulations, including alcohol content and labeling. Berlin's diverse cultural scene and younger demographic contribute to early adoption patterns.
Japan
Japanese consumers appreciate innovative beverage formats and sophisticated flavor profiles, aligning with premium hard tea offerings. Japan's National Tax Agency regulates alcohol production and distribution, impacting market access for new brands. Tokyo's extensive convenience store network provides a critical pathway for product availability.
Hard Tea Market Key Industry Players
Concentration sits with large beverage conglomerates leveraging their vast distribution networks and marketing budgets. The market structure exhibits a tiered consolidation, with established players dominating off-premise channels. Strategic archetypes include diversified alcohol producers and specialized ready-to-drink innovators. Dominant competitive moves involve portfolio diversification into non-beer alcoholic beverages and extensive geographic expansion.
Major beverage conglomerates like Boston Beer Company and Molson Coors Beverage Company exemplify the scale-driven approach to hard tea market penetration. Boston Beer Company, with its Twisted Tea brand, sustains leadership through established brand recognition and widespread availability. Molson Coors Beverage Company competes by expanding its portfolio of non-beer alcoholic beverages, diversifying its offerings across the ready-to-drink segment. Constellation Brands also occupies a significant position, utilizing its robust distribution network to introduce new hard tea products and expand consumer reach. These entities anchor the market, driving innovation in flavor profiles and packaging formats while navigating complex regulatory landscapes.
| Leading Market Players |
|---|
| Boston Beer Company |
| Molson Coors Beverage Company |
| Anheuser-Busch InBev |
| Pabst Brewing Company |
| Constellation Brands |
| Diageo |
| Loverboy Inc. |
| Cisco Brewers |
| Two Chicks Drinks LLC. |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for key agricultural inputs like tea leaves and fruit flavorings lock in both supply access and price visibility for hard tea producers. This contract structure mitigates volatility for manufacturers navigating dynamic raw material markets. Price sensitivity among consumers in off-premise channels also shapes procurement strategies.
Pricing Analysis
The US Alcohol and Tobacco Tax and Trade Bureau (TTB) dictates the pricing tier structure for hard tea, influencing taxation based on alcohol base type. The dominant pricing model is per-unit transactional, primarily through off-premise retail channels. Price differentiation stems from the alcohol base (spirits-based formulations command a premium) and established brand recognition. Pricing pressure intensifies due to fierce competition from hard seltzers and canned cocktails. Off-premise consumers exhibit high price sensitivity, while buyers of premium, spirits-based variants are less sensitive.
Supply Chain Analysis
Container availability and port congestion can impact inbound logistics costs for tea leaves sourced from India and China, alongside flavorings from global suppliers. Raw material dependencies center on specific tea varietals, cane sugar, and natural fruit flavorings. The alcohol base production for hard tea concentrates in North America, particularly the United States. Input cost volatility, especially for agricultural commodities, represents a significant structural risk. Distribution runs through a multi-tiered alcohol system, primarily via off-premise retailers like grocery and convenience stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense as established beverage alcohol incumbents navigate the growing threat from hard seltzer. Product innovation and channel control are critical for sustained growth.
For Market Incumbents: Fortify core brand positions through continuous product innovation, focusing on sugar-free and spirits-based formulations to counter evolving consumer preferences. Leverage existing distribution networks to ensure pervasive availability, especially within off-premise channels. Diversify portfolios into adjacent non-beer alcoholic beverages to capture broader ready-to-drink market share. Invest in marketing that highlights the authentic ingredients and real brewed tea advantage against generic malt-based competitors.
For New Entrants and Emerging Players: Certification fast-track for novel flavor profiles or organic ingredients can open new market segments. Target underpenetrated geographic markets with strong non-alcoholic tea traditions, such as the United Kingdom and Japan, leveraging local flavor preferences. Focus on premiumization strategies, using artisanal tea blends and sophisticated packaging to attract discerning consumers. Utilize direct-to-consumer (DTC) websites and third-party delivery applications as a go-to-market angle to bypass traditional distribution gatekeepers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among brands with strong customer loyalty and repeat purchases, often driven by unique flavor profiles or health-conscious positioning. Long-term viability rests on brands demonstrating consistent innovation in flavor and formulation, alongside effective channel penetration. Acquisition targets should prioritize specialized ready-to-drink innovators with established craft-oriented consumer bases or strong distribution partnerships. The signal to watch is the sustained displacement of malt-based hard teas by spirits-based alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand spirits-based formulations | This shift addresses consumer demand for higher quality and cleaner ingredient labels in the hard tea market. |
| Invest in sugar-free product development | This innovation appeals to health-conscious millennial and Gen Z consumers seeking lower-calorie alcoholic beverages. |
| Strengthen off-premise distribution partnerships | This ensures broad product availability and leverages the primary sales channel for hard tea products. |
| Target on-premise market entry | This expands revenue streams and enhances brand visibility through curated experiences in bars and restaurants. |
| Geographic expansion into Asia-Pacific | This taps into markets with strong non-alcoholic tea traditions, offering significant white space for hard tea growth. |
Research Approach
Desk research of industry association reports, government trade statistics, and company annual filings preceded structured interviews with beverage manufacturers, distribution channel partners, and regulatory experts. This approach combined primary insights with secondary validation to build a comprehensive market view. Bottom-up data aggregation and top-down market sizing provided triangulation for robust market estimates.
The forecast framework utilized variance decomposition to project market growth across the analysis window, considering various influencing factors. Segmentation dimensions modeled included product type, flavor profile, alcohol content, distribution channel, and key geographic regions. Compound annual growth rates were derived from historical trends and projected market drivers, incorporating inputs like consumer preference shifts towards healthier options and regulatory changes impacting alcohol base.
The analysis sits within stated boundaries; outcomes outside significant shifts in consumer preferences or regulatory frameworks would require recalibration. Forecasts reflect assumptions regarding market dynamics and competitive landscapes over the projection horizon. Practitioners should keep alternative scenarios live as new competitive entrants or unforeseen supply chain disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Moonshine Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Wine Cellar Market
Alcoholic Beverages
Beer Fermenter Market
Alcoholic Beverages
RTD Cocktails Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Orange Wine Market
Alcoholic Beverages
Wine Fermentation Equipment Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Sake Market