
 Middle East and Africa Solar and Motorcycle Battery Market | 2026-2036
Middle East and Africa Solar and Motorcycle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Solar and Motorcycle Battery Market Foresight
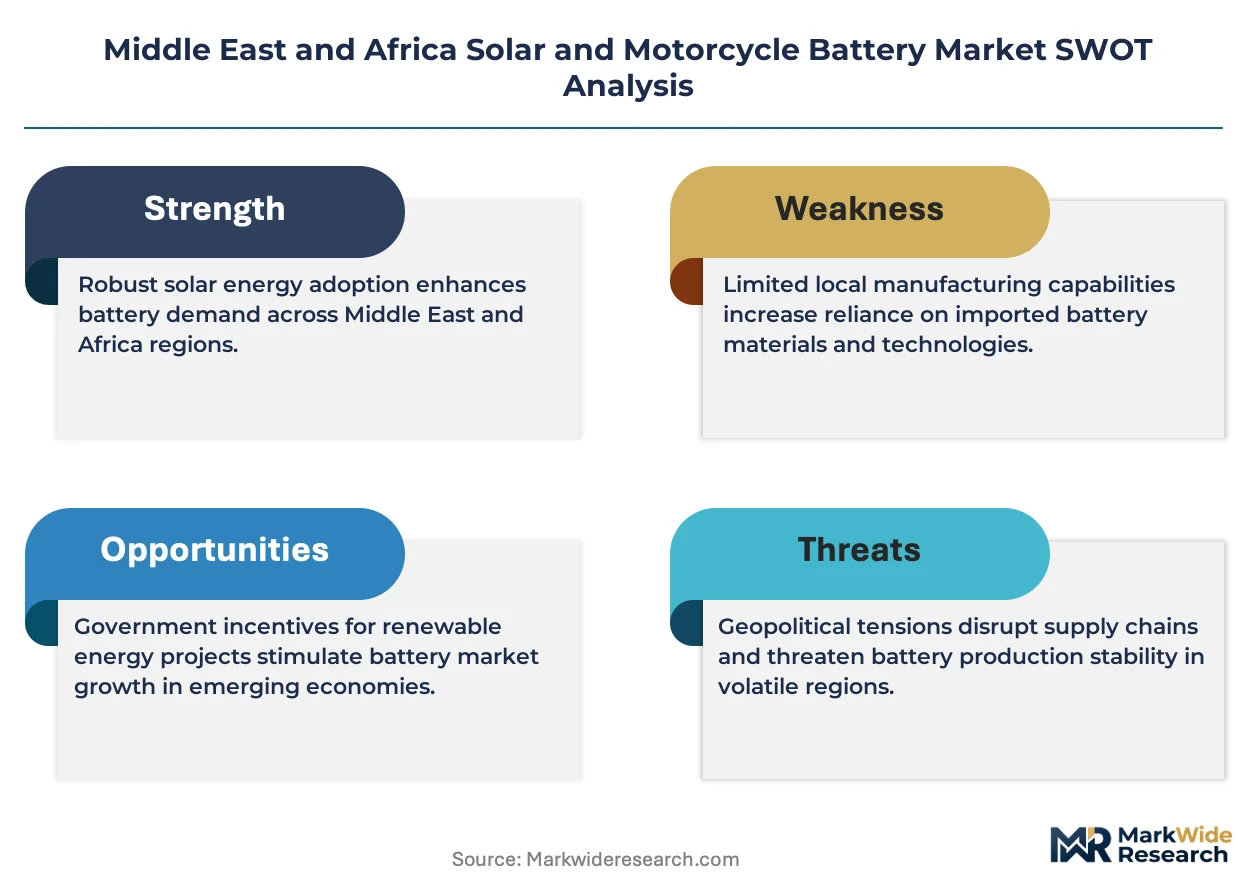
IEC 61427 certification for solar storage batteries is rotating the competitive landscape toward manufacturers with validated cycle-life testing. Panasonic leverages its Osaka-based R&D pipeline to sustain product qualification for desert-climate deployments. Exide Technologies anchors its position through captive lead recycling and established distributor networks across Southern Africa. GS Yuasa International Ltd. competes on motorcycle OEM supply agreements with assembly plants in Egypt and Nigeria.
The Middle East and Africa Solar and Motorcycle Battery encompasses electrochemical energy storage devices engineered for photovoltaic absorption systems and two-wheeler propulsion, typically specified for operating temperatures exceeding 45°C ambient with cycle depths of 50-80% for solar applications and cold-cranking amp ratings above 100A for motorcycle starting. These devices buffer intermittent solar irradiance for off-grid installations and provide ignition energy for internal combustion motorcycles across low-electrification regions. Lithium Ion chemistry captures the fastest growth trajectory as cell prices decline and solar photovoltaic installations scale, while Lead Acid retains volume dominance in motorcycle starting applications due to established recycling infrastructure and price accessibility. The Automotive application segment channels significant throughput through OEM supply contracts, whereas the Residential end user category expands through installer-led solar-storage bundles in peri-urban settlements.
South Africa's National Energy Regulator enforces grid-connection standards that mandate battery inverter compliance, while Nigeria's Standards Organization specifies import testing for automotive batteries that shapes cross-border trade flows. Egypt's Industrial Development Authority coordinates local assembly incentives that condition market access for foreign cell suppliers. Stakeholders must track how evolving storage mandates from national utilities and shifts in raw material export restrictions from lithium-producing African states reshape procurement geography and qualification timelines.
Market Dynamics
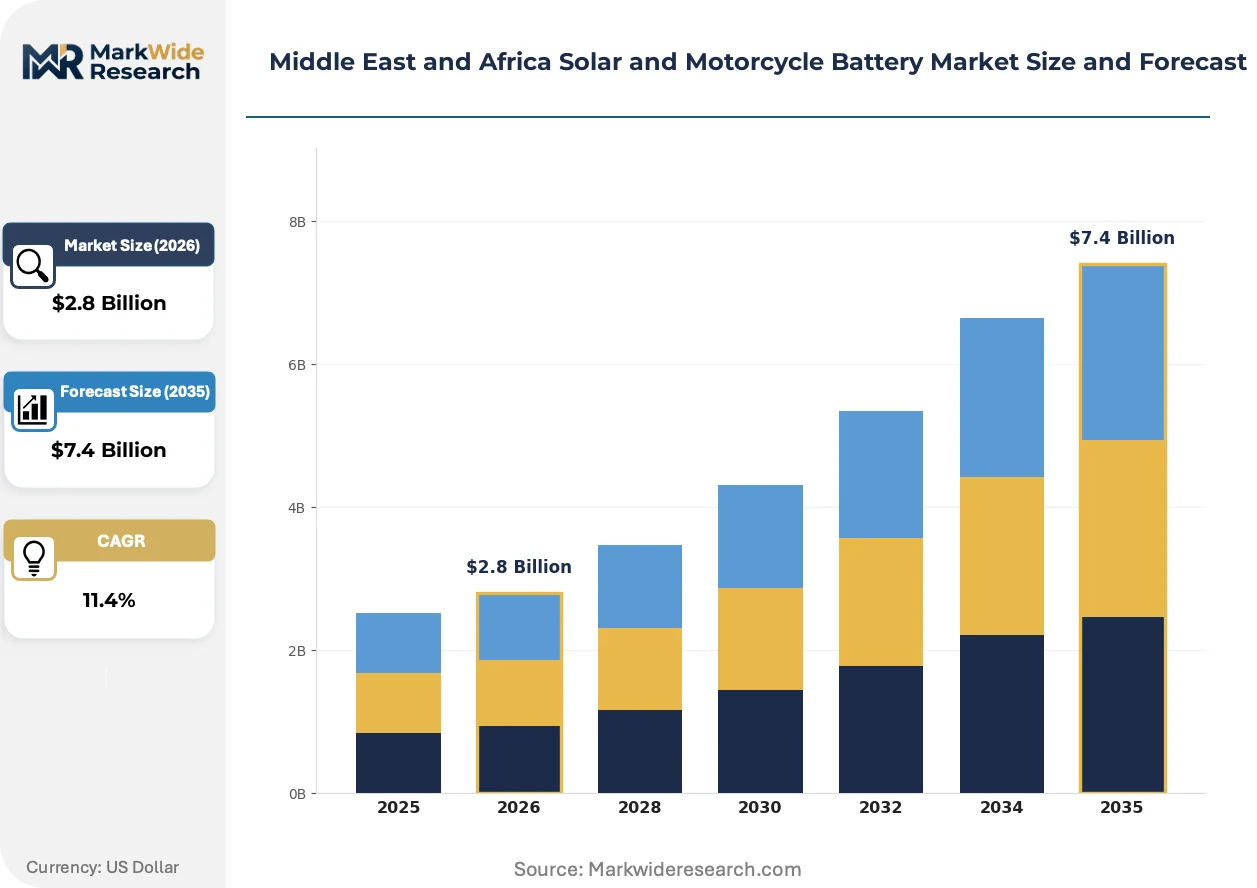
Falling lithium-ion cell costs and South Africa's updated Integrated Resource Plan are redirecting capital toward solar-storage hybrids across the region, compressing lead-acid dominance in stationary applications while motorcycle starting batteries retain established chemistry preferences.
Growth Catalysts
- IEC 61427 certification:Validated cycle-life testing requirements rotate procurement toward manufacturers with desert-climate qualification capabilities, elevating technical barriers for unproven entrants.
- Off-grid telecom towers:Tower operators in Nigeria and Kenya are bundling solar-storage systems into rural infrastructure rollouts, creating anchor demand for deep-cycle battery configurations.
- Falling cell costs:Lithium-ion price declines enable solar-storage hybrids to displace pure diesel backup in peri-urban settlements, expanding addressable market for installers.
Market Restraints
- Raw material export restrictions:Lithium-producing African states are tightening mineral export controls, elongating procurement timelines for cell manufacturers dependent on regional feedstock.
- Lead-acid recycling infrastructure:Established lead recycling networks in Southern Africa create switching costs for motorcycle OEMs evaluating lithium alternatives, preserving incumbent chemistry share.
- Import testing requirements:Nigeria's Standards Organization mandates automotive battery certification procedures that delay cross-border shipments and increase compliance overhead for foreign suppliers.
Strategic Opportunities
- Kenya's Rift Valley:Underpenetrated agricultural electrification zones present white space for solar-storage bundles targeting smallholder irrigation and cold-chain applications.
- Local assembly incentives:Egypt's Industrial Development Authority coordinates production incentives that condition market access, rewarding cell suppliers establishing domestic manufacturing footprints.
- Telecom-tower-as-anchor:Tower operators are expanding into energy-as-a-service models, creating new channel structures for battery vendors to bypass traditional distributor networks.
Industry Challenges
- IEC 61427 cycle-life validation:Desert-climate testing protocols extend product qualification timelines, compressing revenue realization windows for new market entrants.
- Grid-connection standards:South Africa's National Energy Regulator mandates battery inverter compliance procedures that fragment technical requirements across provincial implementation.
- Skill scarcity in thermal management:High-ambient-temperature battery system design expertise concentrates with established manufacturers, constraining local installer capability development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Solar and Motorcycle Battery Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium Ion, Nickel Cadmium, Gel Application: Residential, Commercial, Industrial, Automotive End User: OEMs, Retail Consumers, Installers, Distributors Technology: Solar Photovoltaic, Battery Storage, Hybrid Systems, Backup Power |
| Companies Covered | Panasonic, East Penn Manufacturing Co Inc., GS Yuasa International Ltd., System Sunlight SA, HBL Power Systems Ltd, Exide Technologies, Kokam Company, Azuri Technologies, Amara Raja Batteries Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Solar and Motorcycle Battery Market Shifts & Advancements
Lithium-ion cell technology is bifurcating competitive positioning across solar and motorcycle applications, while regulatory mandates and procurement model evolution reshape how batteries reach end-users in high-temperature operating environments.
Cell chemistry selection is bifurcating between solar deep-cycle and motorcycle starting applications. Lithium iron phosphate formulations dominate stationary solar deployments in Nigeria's northern states due to thermal stability and cycle depth tolerance. Motorcycle OEMs in Egypt and Nigeria retain lead-acid preferences for starting functions given established recycling economics and price accessibility at mass-market tiers. The technology divergence compresses lithium-ion penetration timelines in two-wheeler propulsion while accelerating displacement in stationary storage.
South Africa's National Energy Regulator enforces grid-connection standards mandating battery inverter compliance, reshaping product development priorities for storage system integrators. The regulation requires synchronized frequency response and anti-islanding protection that elevate hardware costs for residential solar-storage bundles. Installers in the Eastern Cape province are responding by consolidating procurement around pre-certified inverter-battery combinations, reducing vendor fragmentation in project execution.
Installer-led solar-storage bundles are displacing component-only sales in peri-urban settlements across Kenya and Nigeria. End-users prefer single-contract responsibility for system performance over managing separate module, inverter, and battery suppliers. The channel shift concentrates volume with vertically integrated installers capable of warranty bundling and after-sales service coverage. Kenya's Rift Valley agricultural zones exhibit the most pronounced preference consolidation, where irrigation reliability demands drive toward outcome-based supplier relationships.
Middle East and Africa Solar and Motorcycle Battery Market Segmentation
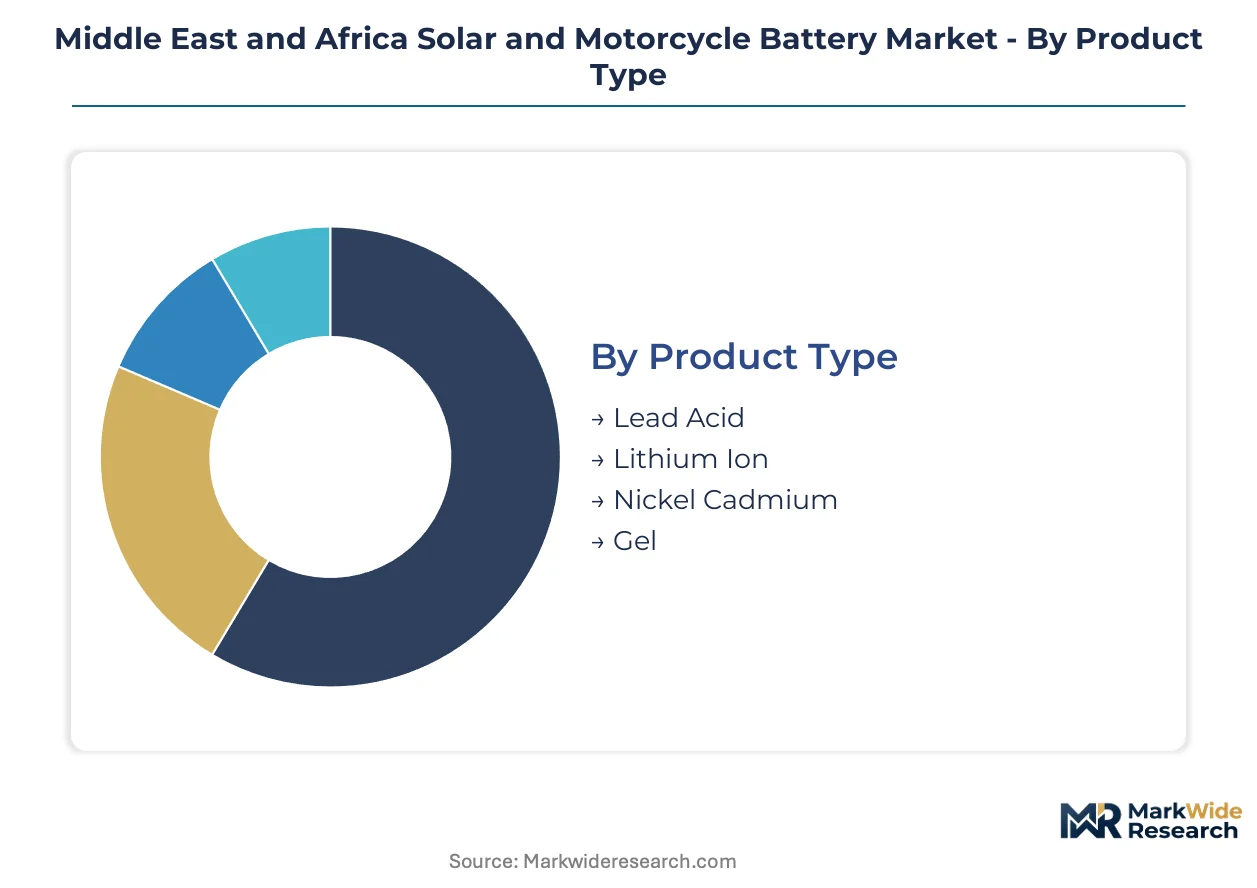
Segmentation in the Middle East and Africa Solar and Motorcycle Battery Market reveals how product chemistry, application requirements, and procurement channels intersect. Installers in Kenya's Rift Valley source differently than motorcycle OEMs in Egypt, while South Africa's utility-scale projects demand distinct qualification pathways from Nigeria's telecom tower operators.
Product Type:
Lead Acid and Lithium Ion dominate installer procurement in Nigeria's northern states and Kenya's agricultural zones, while Nickel Cadmium and Gel batteries serve specialized industrial applications through distributor networks in South Africa's Eastern Cape.
- Lead Acid:Flooded and AGM configurations deliver cold-cranking performance above 100A for motorcycle starting applications. Demand concentrates with assembly plants in Egypt and Nigeria where established lead recycling infrastructure preserves incumbent chemistry preferences against lithium alternatives.
- Lithium Ion:Lithium iron phosphate formulations tolerate 45°C ambient temperatures with 50-80% cycle depths for solar absorption systems. Procurement from South Africa's solar-storage hybrid developers is accelerating as cell price declines enable diesel displacement in peri-urban settlements.
- Nickel Cadmium:Industrial backup installations in mining and telecom sectors specify sintered plate construction for extreme temperature cycling.
- Gel:Deep-cycle configurations serve off-grid installations requiring maintenance-free operation in remote Northern Nigerian tower sites.
By volume, Lead Acid leads. By growth pace, Lithium Ion is ahead.
Application:
Cost tier differentiation separates premium-certified solar-storage bundles from mass-market motorcycle starting batteries, with installation channel density varying sharply across settlement types.
- Residential:Peri-urban solar-storage bundles in Kenya's Rift Valley and Nigeria's northern states combine photovoltaic modules with lithium-ion buffering. Installer-led single-contract responsibility is displacing component-only sales as irrigation reliability demands drive outcome-based supplier relationships.
- Commercial:Cold-chain and agricultural processing facilities in Kenya specify solar-storage hybrids for reliability-critical loads. South Africa's National Energy Regulator mandates battery inverter compliance that elevates hardware costs and consolidates procurement around pre-certified combinations.
- Industrial:Mining operations and manufacturing plants in South Africa's Eastern Cape procure deep-cycle configurations for load shifting and backup power.
- Automotive:Motorcycle OEM supply agreements in Egypt and Nigeria channel Lead Acid starting batteries through established distributor networks.
Automotive commands unit volume. Residential posts the steepest expansion trajectory.
End User:
Customer type determines whether batteries flow through certified installer networks, OEM direct procurement, or fragmented retail channels with varying warranty coverage capabilities.
- OEMs:Motorcycle manufacturers in Egypt and Nigeria negotiate multi-year supply agreements specifying cold-cranking performance and recycling economics. GS Yuasa and Exide Technologies anchor positions through captive lead recycling and assembly plant proximity.
- Installers:Vertically integrated solar-storage providers in Kenya and South Africa bundle module, inverter, and battery procurement under single-contract performance guarantees. Kenya's Rift Valley exhibits the most pronounced preference consolidation for outcome-based relationships.
- Retail Consumers:Individual motorcycle owners and smallholder farmers purchase replacement batteries through informal distributor networks with limited after-sales service coverage.
- Distributors:Southern African networks maintain Lead Acid inventory positions serving fragmented retail and commercial accounts across provincial markets.
Installers are gaining share fastest in solar applications. OEMs retain channel control in motorcycle starting.
Technology:
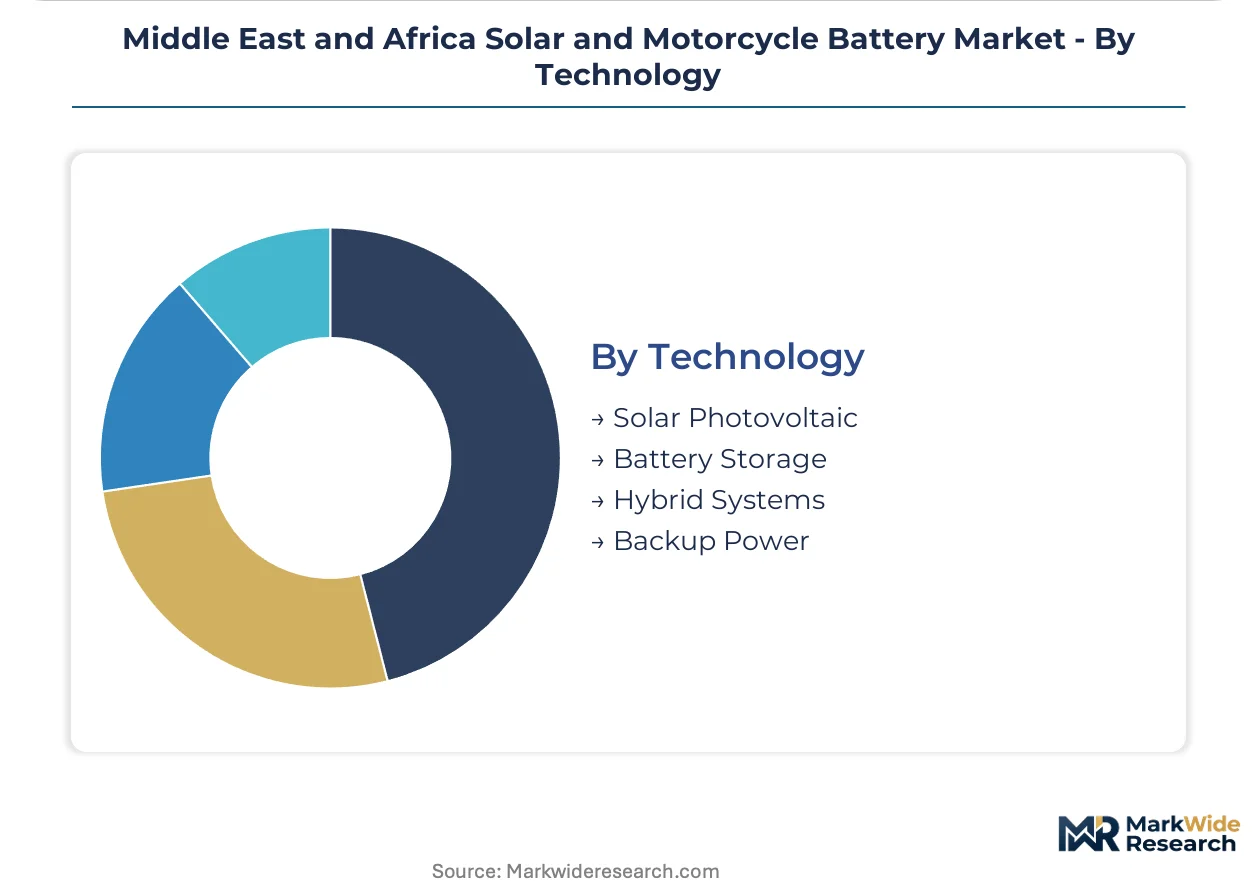
Supply concentration varies by system architecture, with integrated hybrid vendors capturing margin from pure component suppliers as procurement consolidates around pre-certified combinations.
- Solar Photovoltaic:Module-battery pairings in Nigeria's northern states and Kenya's Rift Valley buffer intermittent irradiance for off-grid installations. IEC 61427 certification requirements rotate procurement toward manufacturers with validated desert-climate cycle-life testing.
- Battery Storage:Standalone lithium-ion systems serve telecom tower operators in Nigeria and Kenya bundling solar-storage into rural infrastructure rollouts. Tower operators are expanding into energy-as-a-service models creating new channel structures bypassing traditional distributors.
- Hybrid Systems:Solar-diesel-battery configurations dominate South African commercial and industrial procurement under the updated Integrated Resource Plan.
- Backup Power:Diesel-dependent standalone systems persist in regions with weak grid infrastructure and limited solar irradiance reliability.
Hybrid Systems lead by project value. Battery Storage is climbing the fastest as tower operators scale energy-as-a-service deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Installer-led procurement concentrates in peri-urban solar-storage corridors, while motorcycle OEM supply chains anchor lead-acid demand across North African assembly zones. National utility mandates and rural electrification programs are redirecting capital toward certified battery configurations.
South Africa
Solar-storage hybrid developers in the Eastern Cape province are consolidating procurement around pre-certified inverter-battery combinations. The National Energy Regulator enforces grid-connection standards mandating battery inverter compliance with synchronized frequency response. Mining operations and manufacturing plants in the Eastern Cape drive deep-cycle demand for load shifting applications.
Nigeria
Telecom tower operators in northern states bundle solar-storage systems into rural infrastructure rollouts. The Standards Organization mandates import testing procedures for automotive batteries that delay cross-border shipments. Kano and Kaduna industrial corridors concentrate motorcycle assembly plants sourcing lead-acid starting batteries.
Kenya
Smallholder irrigation and cold-chain applications in the Rift Valley drive solar-storage bundle adoption through vertically integrated installers. The Rural Electrification Authority coordinates mini-grid programs that specify lithium-ion storage for agricultural zones. Nakuru and Eldoret agricultural hubs exhibit pronounced preference consolidation for outcome-based supplier relationships.
Egypt
Motorcycle OEM supply agreements channel lead-acid batteries through assembly plants in Cairo and Alexandria industrial zones. The Industrial Development Authority coordinates local assembly incentives conditioning market access for foreign cell suppliers. Suez Canal Economic Zone manufacturing clusters are attracting battery component suppliers seeking regional export positioning.
United Arab Emirates
Desert-climate solar deployments in Dubai and Abu Dhabi specify IEC 61427-certified batteries for thermal tolerance validation. MOHAP and local energy regulators enforce product safety standards that elevate technical barriers for unproven entrants. Mohammed bin Rashid Al Maktoum Solar Park procurement is concentrating volume with manufacturers holding validated cycle-life testing documentation.
Middle East and Africa Solar and Motorcycle Battery Market Competitive Landscape
Player mix skews toward diversified electrochemical manufacturers with established desert-climate qualification capabilities. The competitive set fragments across three tiers: integrated solar-storage system vendors, lead-acid specialists with captive recycling infrastructure, and lithium-ion cell suppliers qualifying for telecom tower applications. Panasonic anchors the premium tier through Osaka-based R&D pipelines, while Exide Technologies and GS Yuasa International Ltd. represent entrenched positions in motorcycle starting and stationary storage respectively. Dominant competitive moves include backward integration into lead recycling and geographic expansion through local assembly partnerships.
Within the diversified electrochemical tier, Panasonic, Exide Technologies, and GS Yuasa International Ltd. occupy positions shaped by distinct capability footprints. Panasonic exemplifies the premium-qualification archetype, leveraging desert-climate R&D assets for solar-storage certification. Exide Technologies anchors the lead-acid recycling-integrated position, sustaining distributor network control across Southern Africa. GS Yuasa International Ltd. represents the motorcycle OEM supply archetype, with assembly plant proximity in Egypt and Nigeria conditioning contract renewal rates. These three manufacturers illustrate how technical qualification, recycling economics, and OEM channel density stratify competitive positioning.
| Leading Market Players |
|---|
| Panasonic |
| East Penn Manufacturing Co Inc. |
| GS Yuasa International Ltd. |
| System Sunlight SA |
| HBL Power Systems Ltd |
| Exide Technologies |
| Kokam Company |
| Azuri Technologies |
| Amara Raja Batteries Ltd. |
| Others |
Supply & Pricing Matrix
Ninety-day lead times for lithium carbonate delivery from South American refiners concentrate pricing power with cell manufacturers holding forward-contract coverage, while spot-market exposure among smaller assemblers forces margin compression in Nigeria's solar-storage corridor.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange lithium carbonate pricing dominate procurement between South African hybrid developers and East Asian cell suppliers. Price differentiation separates IEC 61427-certified configurations from uncertified alternatives, with brand premiums attaching to desert-climate validation. Pricing pressure intensifies in Kenya's Rift Valley as installer consolidation squeezes component margins. Retail consumers in motorcycle replacement markets exhibit highest price sensitivity, while telecom tower operators prioritize reliability over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites feedstock security for Gulf-based petrochemical producers supplying electrolyte solvents to regional cell assemblers. Manufacturing concentrates in China, South Korea, and Japan for cathode active materials, while lithium feedstock draws from Chilean and Australian mining operations. Single-source vulnerability in separator membrane supply creates exposure for African battery packagers. Distribution runs through Cairo and Johannesburg logistics hubs serving installer networks and OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Falling lithium-ion cell costs and South Africa's Integrated Resource Plan revision constitute a dual inflection disrupting established lead-acid economics across solar-storage applications.
For Market Incumbents: Shield market position through captive lead recycling investments in Southern Africa and accelerated IEC 61427 certification timelines for lithium iron phosphate portfolios. Threat from vertically integrated Chinese cell suppliers with Egyptian assembly footholds demands preemptive channel control in Kenya's agricultural zones. Backward integration into lithium carbonate offtake agreements represents the critical defensive lever. For New Entrants and Emerging Players: IEC 61427 fast-track programs through UAE testing laboratories open procurement channels with Dubai's Mohammed bin Rashid Al Maktoum Solar Park operators. Kenya's Rift Valley agricultural electrification presents the most penetrable white space, with smallholder irrigation demand outpacing incumbent installer capacity. Energy-as-a-service partnerships with Nigerian telecom tower operators offer the strongest go-to-market angle bypassing fragmented distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming battery divisions lacking desert-climate qualification capabilities. Long-term viability centers on chemistry-agnostic platform strategies spanning solar deep-cycle and motorcycle starting applications. Monitor lithium export restriction announcements from African producing states as the critical inflection signal for procurement geography reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| Desert-Climate Certification Investment | IEC 61427 validation unlocks procurement with UAE utility-scale solar developers and Nigerian telecom operators. |
| Local Assembly Partnership in Egypt | Industrial Development Authority incentives condition market access for foreign cell suppliers seeking regional export positioning. |
| Captive Lead Recycling Expansion | Established Southern African recycling networks preserve motorcycle OEM supply relationships against lithium substitution pressure. |
| Energy-as-a-Service Channel Development | Tower operator direct contracting bypasses traditional distributor fragmentation in Nigerian and Kenyan rural infrastructure. |
| Lithium Carbonate Offtake Securement | Forward contracting with Chilean and Australian producers hedges raw material export restriction risk from African states. |
Research Methodology
A standing panel of solar EPC contractors, motorcycle OEM procurement managers, telecom tower operations directors, and lead recycling facility engineers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against customs records, national utility procurement disclosures, and Standards Organization of Nigeria import certification databases. Bottom-up installer shipment tracking and top-down national electrification program budgets were triangulated for volume estimation.
Consistency checks against IEA renewable energy deployment data and national regulatory filings validated projection outputs across the analysis window. Segmentation modeling incorporated chemistry type, application tier, end-user channel, and regional regulatory cluster dimensions. CAGRs were derived from installer pipeline visibility and OEM contract renewal schedules, with lithium price trajectory assumptions feeding cost-driven adoption elasticity parameters.
Underlying assumptions cover cell price decline continuity and grid-connection standard enforcement timelines, with deviation risk concentrated in raw material export policy shifts and currency volatility in Nigerian and Kenyan procurement corridors. Practitioners should keep alternative scenarios live as lithium-producing African state industrial policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Solid Electrolyte Market
Batteries
Vanadium Redox Batteries Market
Batteries
Mobile Battery Market
Batteries
Water-Based Zinc-Ion Battery Market
Batteries
Iron Salt Battery Market
Batteries
Southeast Asia Battery Market
Batteries
Zinc-Ion Battery Cells Market
Batteries
Nas Battery Market
Batteries
Middle East and Africa Rechargeable Battery Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
North Europe Battery Market
Batteries
Aluminum Based Battery Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
48 Volt Battery System Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market