
 Spain Fermentation Ingredients Market | 2026-2036
Spain Fermentation Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Fermentation Ingredients Market Outlook
Spain is narrowing its reliance on imported fermentation inputs through capacity expansions in Castilla y León and Aragón. Evonik Industries AG leverages its amino acid expertise to supply Spanish pharmaceutical formulators. BASF SE anchors regional distribution through its specialty enzyme portfolio. Chr. Hansen Holding A/S specializes in dairy culture applications that dominate Iberian cheese production.
Fermentation ingredients comprise viable microorganisms, enzymatic proteins, organic acids, and derived metabolites produced via submerged or solid-state bioprocessing under controlled pH, temperature, and dissolved oxygen parameters, serving as functional inputs for food preservation, drug synthesis, and biochemical manufacturing. Yeast and enzymes command the largest volume positions in Spanish food manufacturing, while organic acids extract premium pricing from pharmaceutical-grade contracts. Bacteria cultures are gaining fastest in plant-based dairy alternatives, though margin pools remain deepest in pharma-validated enzyme supply.
Spain's national pharmaceutical regulator enforces EU GMP Annex 1 standards that elevate compliance costs for fermentation ingredient suppliers to drug manufacturers. FSSAI-aligned import documentation and BIS-referenced quality benchmarks shape cross-border enzyme trade into Spanish food plants. Stakeholders must monitor how EU CSRD disclosure rules and evolving bioeconomy certification schemes will restructure procurement priorities for fermentation-derived inputs.
Market Dynamics
Spain's fermentation ingredients sector is restructuring around EU Green Deal bioeconomy mandates that redirect capital from petrochemical feedstocks toward microbial production platforms, compressing legacy supply timelines while elevating compliance thresholds for pharmaceutical-grade suppliers.
Growth Catalysts
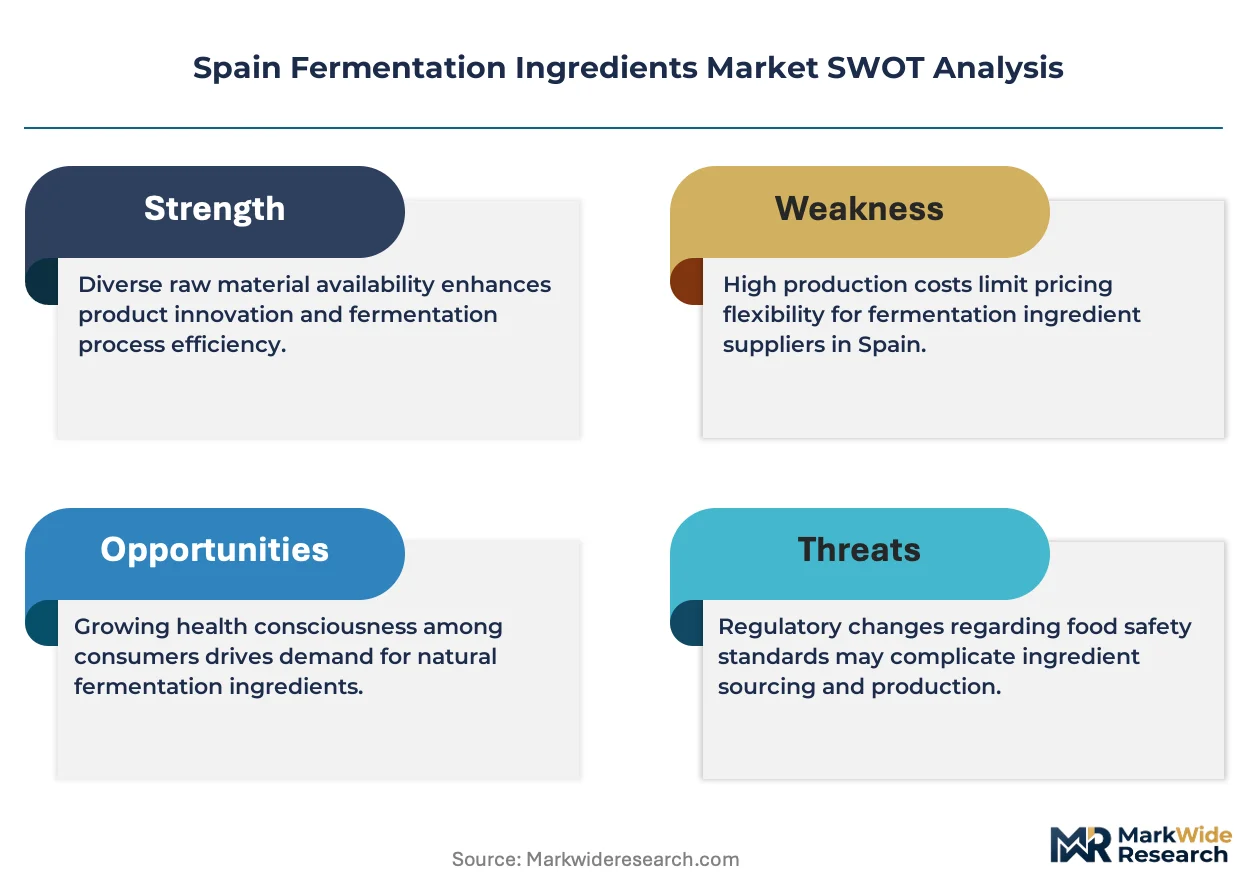
- EU Green Deal capital redirection:National bioeconomy strategies channel public and private investment into Castilla y León and Aragón fermentation capacity expansions, reducing import dependency for enzymatic inputs.
- Pharmaceutical validation requirements:Spanish drug manufacturers scale purchases of fermentation-derived active ingredients as EU GMP Annex 1 standards tighten substitution barriers for synthetic alternatives.
- Plant-based dairy culture demand:Catalonia's food processing corridor drives fastest volume expansion for bacteria cultures serving oat and almond milk alternatives.
Market Restraints
- Feedstock cost volatility:Molasses and corn steep liquor prices fluctuate with global agricultural commodity cycles, squeezing margin predictability for organic acid producers.
- Supplier concentration risk:Critical enzyme categories rely on concentrated German and Danish manufacturing bases, exposing Spanish formulators to single-source vulnerability.
- EU GMP Annex 1 compliance friction:Elevated documentation and facility validation requirements extend qualification timelines for new pharmaceutical-grade suppliers.
Strategic Opportunities
- Underpenetrated Aragón biotech corridor:Greenfield fermentation capacity in this autonomous community offers land and energy cost advantages versus saturated Catalonia and Madrid clusters.
- CSRD disclosure tailwinds:Corporate sustainability reporting mandates position fermentation-derived inputs as quantifiable Scope 3 reduction instruments for food and pharma buyers.
- Precision fermentation convergence:Integration of synthetic biology with traditional submerged bioprocessing enables novel metabolite categories beyond established amino acid and organic acid portfolios.
Industry Challenges
- Pharmaceutical-grade talent scarcity:Qualified fermentation scientists and process engineers command premium compensation in Madrid's competing pharma cluster, constraining facility staffing.
- Multi-year capex recovery timelines:Stainless steel bioreactor installations and downstream purification suites require extended depreciation periods amid accelerating technology obsolescence cycles.
- Cross-border certification complexity:FSSAI-aligned import documentation for Indian enzyme suppliers creates documentation bottlenecks at Spanish food manufacturing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Fermentation Ingredients Market |
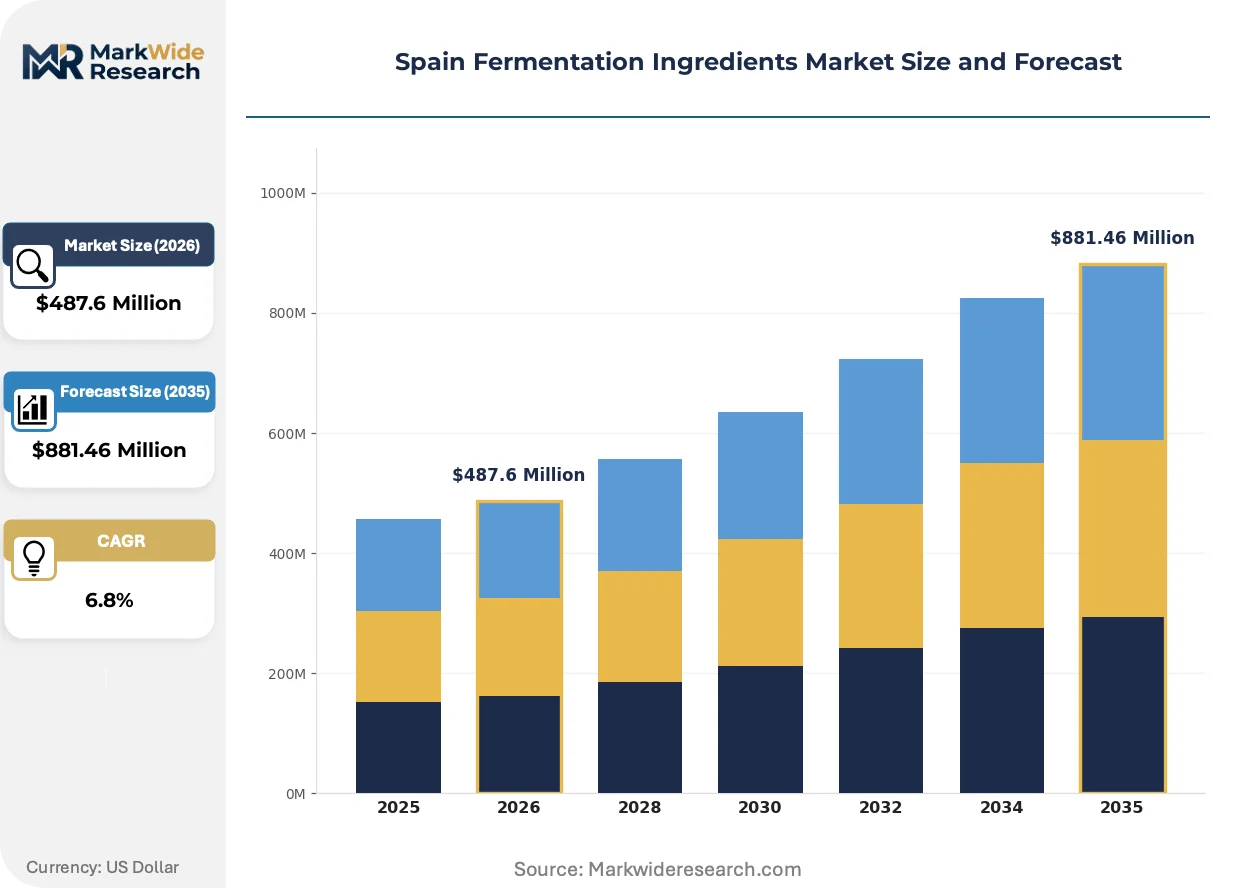
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast, Bacteria, Enzymes, Organic Acids Application: Beverages, Dairy Products, Bakery, Pharmaceuticals End User: Food Manufacturers, Beverage Producers, Pharma Companies, Home Brewers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Evonik Industries AG, Archer Daniels Midland Company, BASF SE, DSM Nutritional Products, Novozymes A/S, DuPont de Nemours Inc, Kerry Group plc, Chr. Hansen Holding A/S, Cargill Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Fermentation Ingredients Market Strategic Shifts
Continuous bioprocessing architectures and single-use fermentation systems are compressing batch cycle times while synthetic biology toolkits expand the metabolite addressable market beyond traditional fermentation outputs.
Single-use bioreactor technology is rendering obsolete stainless steel vessel dependence for mid-scale pharmaceutical ingredient production. Spanish contract manufacturers adopt disposable fermentation systems to reduce cross-contamination risk and accelerate product changeover. This shift compresses capital deployment timelines from five-year steel installations to eighteen-month operational readiness.
EU CSRD disclosure rules mandate granular supply chain emissions reporting for large enterprises. Food and pharmaceutical manufacturers now require fermentation ingredient suppliers to provide certified carbon intensity data. Spanish buyers prioritize domestic and near-shore microbial production to simplify Scope 3 accounting and reduce transportation-related disclosure complexity.
Buyer consolidation among Iberian dairy processors concentrates culture supply negotiations with fewer purchasing entities. Large cooperatives in Galicia and Castilla y León now demand multi-year volume commitments with price indexing mechanisms. Smaller culture suppliers face exclusion from approved vendor lists without demonstrated scale and financial stability credentials.
Spain Fermentation Ingredients Market Segmentation
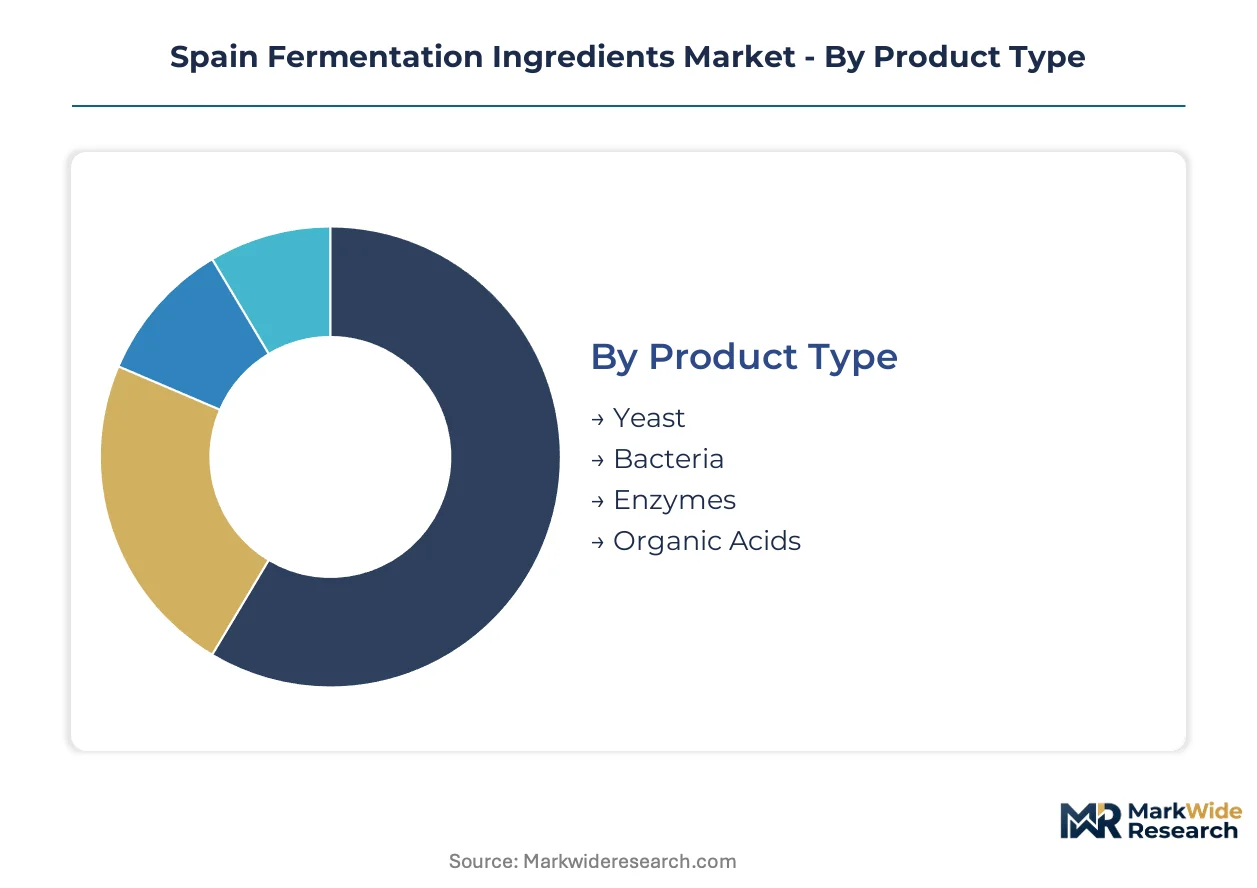
Fermentation ingredient purchasing cycles vary dramatically across Spain's food and pharmaceutical sectors. Dairy culture replenishment occurs weekly, while pharmaceutical enzyme validation spans quarters. Understanding these velocity differences enables suppliers to calibrate inventory and pricing strategies.
Product Type:
Cycle times stretch from days for commodity yeast to months for pharma-validated organic acids. Inventory turns correlate inversely with certification burden.
- Yeast:Saccharomyces cerevisiae and specialized brewing strains dominate Iberian bread and beer production. Catalonia's bakery cooperatives consume bulk volumes with weekly replenishment rhythms. Price sensitivity intensifies during wheat harvest volatility.
- Enzymes:Proteases, amylases, and lipases catalyze process efficiency in Spanish dairy and starch processing. Madrid's pharmaceutical formulators extract premium pricing for GMP-validated enzyme supply, though documentation extends procurement cycles.
- Bacteria:Lactic acid cultures for cheese and emerging plant-based dairy applications.
- Organic Acids:Citric, lactic, and gluconic acids for food preservation and active pharmaceutical ingredient synthesis.
Yeast anchors the volume base while bacteria gains share at the steepest rate.
Application:
Margin structures diverge sharply between commoditized food processing and regulated pharmaceutical manufacturing. Certification tiers create pricing stratification that application type largely determines.
- Pharmaceuticals:Fermentation-derived active ingredients and excipients face EU GMP Annex 1 compliance that elevates supplier qualification barriers. Spanish drug manufacturers in Madrid's cluster prioritize domestic sourcing to simplify regulatory audits.
- Dairy Products:Cheese cultures and yogurt starters command repeat purchase loyalty. Galicia's dairy cooperatives negotiate multi-year supply agreements with volume indexing.
- Beverages:Wine, beer, and cider fermentation inputs.
- Bakery:Leavening agents and dough conditioners for industrial bread production.
Dairy products generate the most predictable revenue streams whereas pharmaceuticals delivers the deepest margin pools.
End User:
Procurement sophistication separates industrial-scale buyers from fragmented artisanal purchasers. Contract structures, payment terms, and technical service expectations vary accordingly.
- Food Manufacturers:Industrial bakeries and processed food plants in Catalonia and Valencia purchase fermentation inputs through annual tenders with specification lock-ins.
- Pharma Companies:Madrid-based drug formulators demand batch documentation, stability data, and audit rights that smaller suppliers cannot satisfy.
- Beverage Producers:wineries, breweries, and cider houses.
- Home Brewers:hobbyist segment purchasing through retail channels.
Food manufacturers provide the broadest customer base while pharma companies concentrate purchasing power most intensely.
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements. Direct relationships dominate where formulation support matters; intermediaries persist where logistics efficiency prevails.
- Distributors:Regional chemical and ingredient distributors warehouse inventory across Castilla y León and Andalucía, offering just-in-time delivery to mid-sized food plants.
- Direct Sales:Pharmaceutical-grade enzyme and culture suppliers bypass intermediaries to control technical service and documentation chains.
- Online Retail:e-commerce platforms serving small-scale and artisanal buyers.
- Wholesalers:bulk commodity handlers for standard-grade fermentation inputs.
Distributors capture the widest geographic coverage while direct sales commands the highest value-added relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish fermentation ingredient supply concentrates in three autonomous communities that host distinct industrial ecosystems. Catalonia's food processing corridor, Madrid's pharmaceutical cluster, and Castilla y León's emerging biotech infrastructure each generate differentiated demand patterns for microbial inputs.
Catalonia
Dairy culture consumption dominates regional demand as Galician cheese cooperatives extend supply contracts into Barcelona's logistics hub. EU CSRD disclosure mandates accelerate procurement centralization among large food manufacturers. Girona's precision fermentation startups attract venture capital for alternative protein applications.
Madrid
Pharmaceutical-grade enzyme validation cycles stretch procurement timelines as drug formulators enforce EU GMP Annex 1 documentation standards. The national pharmaceutical regulator maintains inspection protocols that elevate facility qualification barriers. Alcobendas hosts contract manufacturing organizations adopting single-use bioreactor systems.
Castilla y León
Greenfield fermentation capacity expansions target molasses feedstock availability from regional sugar beet processing. National bioeconomy strategies channel public investment into microbial production platforms. Burgos anchors industrial biotechnology infrastructure development with land and energy cost advantages.
Aragón
Underpenetrated biotech corridor positioning attracts capital seeking alternatives to saturated coastal clusters. Zaragoza's logistics connectivity enables distribution reach into both Mediterranean and Atlantic markets. Regional government incentives support pilot-scale fermentation facility construction.
Andalusia
Wine and olive fermentation traditions sustain commodity yeast demand through seasonal purchasing cycles. Sevilla's food technology institutes collaborate with culture suppliers on indigenous strain development. Agricultural cooperatives negotiate volume-indexed supply agreements for harvest-period inputs.
Spain Fermentation Ingredients Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in a structure where multinational chemical conglomerates anchor supply while regional distributors fragment local access. Three archetypes dominate: diversified nutrition conglomerates with fermentation-derived portfolios, enzyme-focused biotechnology specialists, and dairy culture purveyors with Iberian manufacturing heritage. Competitive moves concentrate on capacity expansion in underpenetrated Spanish regions and strategic partnerships that secure feedstock supply chains.
Among Germany-based chemical conglomerates, Evonik Industries AG and BASF SE occupy positions as upstream platform suppliers, while Chr. Hansen Holding A/S exemplifies the culture-specialist archetype with concentrated dairy applications expertise.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Archer Daniels Midland Company |
| BASF SE |
| DSM Nutritional Products |
| Novozymes A/S |
| DuPont de Nemours Inc |
| Kerry Group plc |
| Chr. Hansen Holding A/S |
| Cargill Inc |
| Others |
Value Chain & Pricing Dynamics
Castilla y León's greenfield fermentation capacity expansions are compressing import-dependent pricing premiums as domestic molasses-fed production platforms achieve scale economies previously locked behind German and Danish supply chains.
Pricing Analysis
EU GMP Annex 1 dictates the pricing tier structure across pharmaceutical-grade enzyme supply, separating validated manufacturers from commodity producers. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, volume scale, and technical service bundling. Cost compression in standard-grade food enzymes is intensifying because Catalonia's dairy cooperatives consolidate purchasing through multi-year tenders. Artisanal bakeries exhibit highest price sensitivity, while Madrid's drug formulators accept premium positioning for audit-ready documentation packages.
Supply Chain Analysis
Molasses and corn steep liquor feedstock availability anchors upstream cost structures, drawing from Spanish sugar beet processing, Brazilian cane refineries, and Indian agricultural commodity markets. Critical enzyme categories rest on concentrated German and Danish manufacturing bases, creating single-source vulnerability for Spanish formulators. Distribution runs through regional chemical distributors in Castilla y León and Andalucía, with direct sales channels dominating pharmaceutical-grade relationships requiring technical service integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Iberian dairy cooperatives and Madrid pharmaceutical clusters, compressing supplier margins as procurement centralization accelerates under EU CSRD disclosure mandates.
For Market Incumbents: Build regulatory moats through EU GMP Annex 1 certification investments that emerging entrants cannot replicate within qualification timelines. Expand stainless steel and single-use bioreactor capacity in Aragón's underpenetrated corridor to capture land and energy cost advantages. Secure long-term molasses supply agreements with Castilla y León sugar processors before feedstock competition intensifies.
For New Entrants and Emerging Players: Establish a beachhead in plant-based dairy culture applications where bacteria strain demand outpaces established supplier capacity. Target Aragón's biotech corridor for pilot-scale facility construction, leveraging regional government incentives absent in saturated coastal clusters. Lead with precision fermentation capabilities for novel metabolite categories beyond traditional amino acid portfolios.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturing organizations adopting single-use bioreactor systems over capital-intensive stainless steel legacy operators. Long-term viability hinges on Scope 3 emissions accounting capabilities that satisfy CSRD-mandated supply chain disclosure. Watch for inflection when pharmaceutical-grade talent scarcity in Madrid's cluster forces facility location decisions toward lower-cost autonomous communities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive molasses access from Castilla y León sugar beet processors insulates margin volatility from global agricultural commodity cycles. |
| Single-Use Bioreactor Adoption | Disposable fermentation systems in Alcobendas contract manufacturing organizations compress capital deployment timelines from five years to eighteen months. |
| EU GMP Annex 1 Certification Investment | Validated facility qualification creates substitution barriers against synthetic alternatives in Madrid's pharmaceutical cluster procurement. |
| Precision Fermentation Platform Development | Synthetic biology integration in Girona startups expands metabolite addressable market beyond established organic acid portfolios. |
| CSRD-Aligned Carbon Intensity Certification | Certified emissions data positions fermentation-derived inputs as quantifiable Scope 3 reduction instruments for food and pharma buyers. |
Study Parameters
The analysis maps pharmaceutical-grade enzymes, dairy cultures, organic acids, and commodity yeast segments, each validated through fermentation scientists, pharmaceutical procurement managers, dairy cooperative supply directors, and regional distributor operations leads. Primary interviews with plant managers at Castilla y León biotech facilities and regulatory affairs specialists at Madrid drug formulators combined with secondary validation from EU GMP inspection databases, Spanish customs trade records, FSSAI import documentation filings, and bioeconomy strategy white papers. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Assumptions held fixed include EU Green Deal bioeconomy capital redirection continuity and CSRD disclosure mandate enforcement timelines; variables stress-tested encompass molasses price volatility bands and pharmaceutical-grade talent availability scenarios. Across the analysis window, product type, application tier, end-user scale, and autonomous community production cluster dimensions segmented the model. CAGRs derived from historical capacity expansion patterns and announced facility investments, with feedstock cost curves and regulatory qualification timelines as industry-specific forecast inputs.
Stress conditions across agricultural commodity price bands, EU GMP inspection frequency changes, and precision fermentation technology adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to bioeconomy policy continuity and cross-border certification harmonization progress. Cross-checking against EMA inspection outcome databases and Spanish bioeconomy public investment disbursement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Carotenoids Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
Fish Peptones Market
Ingredients
Stabilized Starch Market
Ingredients
Functional Flours Market
Ingredients
Textured Wheat Protein Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Europe Insoluble Dietary Fibers Market
Ingredients
Lime Seed Oils Market
Ingredients
North America Corn Starch Market
Ingredients
Europe Sodium Reduction Ingredient Market
Ingredients
Moringa Ingredients Market
Ingredients
Konjac Flour Market
Ingredients
Glucuronolactone Market
Ingredients
Asia-Pacific Yeast Market
Ingredients
North America Plant Protein Ingredients Market