
 White Top Testliner Market | 2026-2036
White Top Testliner Market Size, Share, and Industry Trends Forecast 2026-2036
White Top Testliner Market Analytics
REACH compliance is hardening the cost-of-entry calculus for new entrants into European white top testliner supply. International Paper leverages its integrated pulp-to-board footprint across Nordic mills to sustain margin resilience. Smurfit Kappa Group anchors its competitive position through recycled-fiber sourcing networks that span Iberian and Benelux collection systems. Mondi Group differentiates via specialty coating formulations that navigate food-contact certification requirements.
White top testliner denotes a recycled-paperboard grade featuring a bleached or clay-coated top ply laminated to a grey or brown testliner back, typically manufactured in weights from 250 GSM to 400 GSM through multi-ply Fourdrinier or cylinder machine forming. Its primary commercial purpose is to provide printable, structurally rigid surfaces for corrugated packaging where brand presentation and stacking strength must coexist. The coated product type commands the deepest margin pools due to barrier-property premiums in chilled-food applications, while uncoated grades dominate volume through cost-sensitive industrial shipping cases. Among end-use industries, food packaging leads absolute consumption as retailers specify white-top liners for shelf-ready produce trays and ready-meal cartons.
EMA food-contact frameworks, EU Green Deal recycled-content targets, and ISO 9001 quality management standards collectively shape product specifications and mill-level capital allocation across European production corridors. FDA regulations govern export-bound shipments destined for North American food distribution channels, adding dual-certification overhead for integrated suppliers. Stakeholders must monitor how pending revisions to F-Gas Regulation thermal standards affect energy-intensive drying processes before committing to capacity expansions.
Market Dynamics
Recycled-fiber sourcing networks are consolidating around Nordic and Benelux collection corridors as EU Green Deal mandates harden minimum recycled-content thresholds for food-contact board grades.
Growth Catalysts
- EMA food-contact certification expansion:Retailers across Germany and France now require EMA-compliant white top testliner for chilled ready-meal cartons, pulling coated-grade capacity toward barrier-property investments.
- Shelf-ready display specifications:Supermarket chains in the Netherlands and Belgium are mandating printable white-top surfaces for produce trays that withstand refrigerated distribution.
- Central European export corridor development:Corrugated converters in Poland and the Czech Republic are expanding white top testliner consumption to serve automotive and electronics export packaging demand.
Market Restraints
- Recycled-fiber input cost volatility:OCC (old corrugated container) prices fluctuate with municipal collection system disruptions across Iberian peninsula markets.
- REACH compliance cost escalation:ECHA substance restrictions on coating chemistries impose dual-certification overhead for mills serving both EU and export markets.
- Plastic substitution threat in chilled food:Mono-material polypropylene trays with printed labels are capturing share in premium ready-meal segments where moisture barrier demands exceed paperboard performance.
Strategic Opportunities
- Polish and Romanian converter expansion:Underpenetrated Central European markets present volume growth corridors as regional logistics hubs mature.
- F-Gas Regulation thermal efficiency incentives:Pending revisions to EU drying-process standards create first-mover advantage for mills investing in heat-recovery systems.
- Barrier coating-nanocellulose convergence:Emerging coating formulations integrating nanocellulose with conventional clay barriers open high-margin pharmaceutical and fresh-produce applications.
Industry Challenges
- Food-contact certification timeline compression:EMA and EFSA parallel review processes extend new product qualification cycles beyond eighteen months.
- Multi-ply forming technician scarcity:Cylinder machine operators with Fourdrinier hybrid experience are concentrated among retiring workforce cohorts in Nordic mill regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Top Testliner Market |
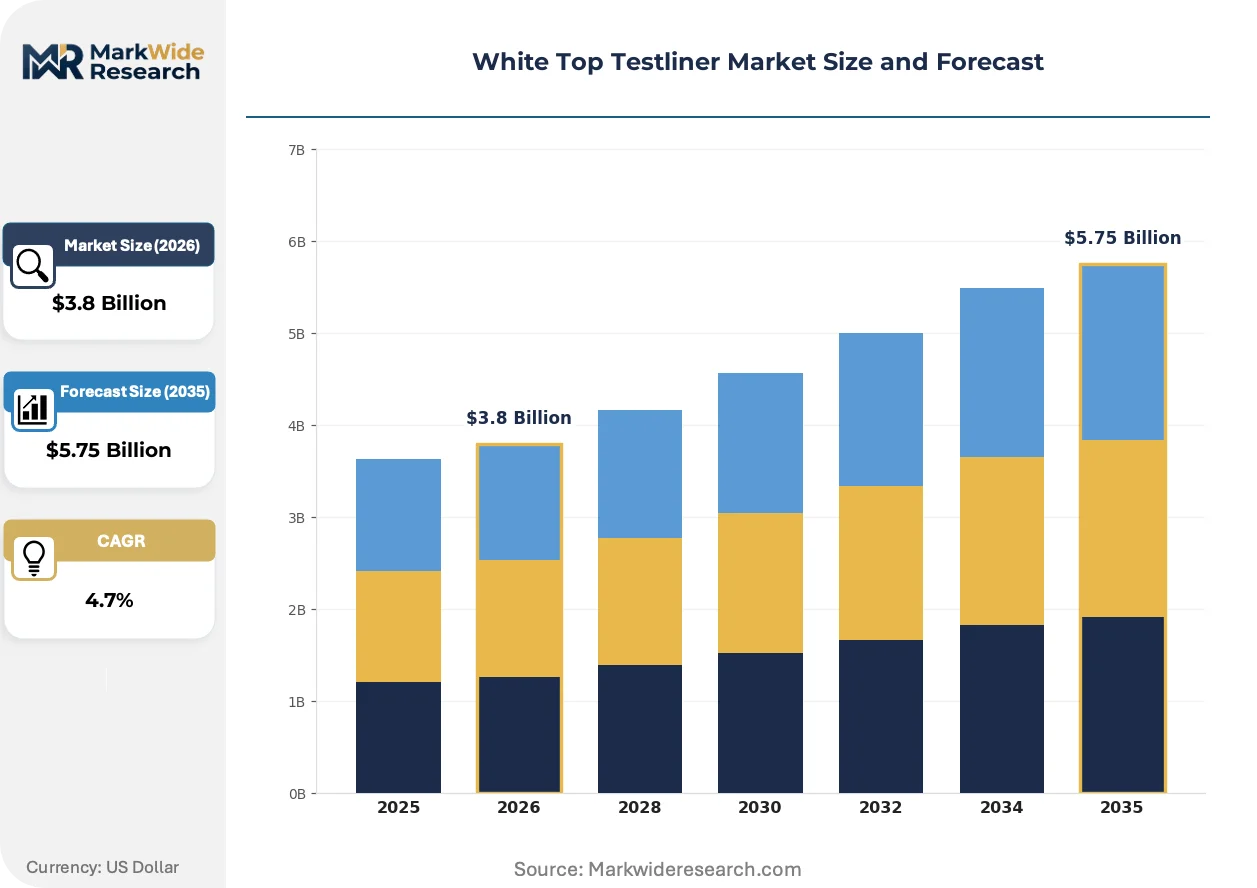
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated, Uncoated, Bleached, Non-Bleached End Use Industry: Food Packaging, Consumer Goods, Electronics, Pharmaceuticals Weight: 250 GSM, 300 GSM, 350 GSM, 400 GSM Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | International Paper, Polo Handels, Smurfit Kappa Group, Green Power Holding, PG Paper Company, DS Smith, Stora Enso, LEIPA Georg Leinfelder, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Top Testliner Market Evolving Landscape
Digital print compatibility and barrier-performance convergence are redefining white top testliner specifications as brand owners consolidate supplier bases around dual-capability mills.
Advanced clay-barrier coatings with controlled porosity are converging with high-speed inkjet print engines to enable short-run, variable-data packaging for regional food brands. German and French converters are retrofitting existing corrugators with UV-curable ink systems that demand modified surface energy on white-top plies. This convergence is compressing minimum order quantities from truckload to pallet-scale while fragmenting volume across more SKUs.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant chemistries from food-contact coatings by 2026. Mills dependent on fluoropolymer barriers must reformulate with bio-based alternatives or forfeit quick-service restaurant packaging contracts. The coated-grade segment faces the steepest compliance cliff as ECHA enforcement concentrates on imported board from non-EU origins.
Consolidated procurement by pan-European retail buying groups is displacing national converter relationships with centralized tender structures. Aldi and Lidl purchasing cooperatives now specify white top testliner across produce, bakery, and ready-meal categories through single-supplier frameworks. This concentration is most visible in Benelux and German retail corridors where three buying groups control sixty percent of coated-grade volume.
White Top Testliner Market Segmentation
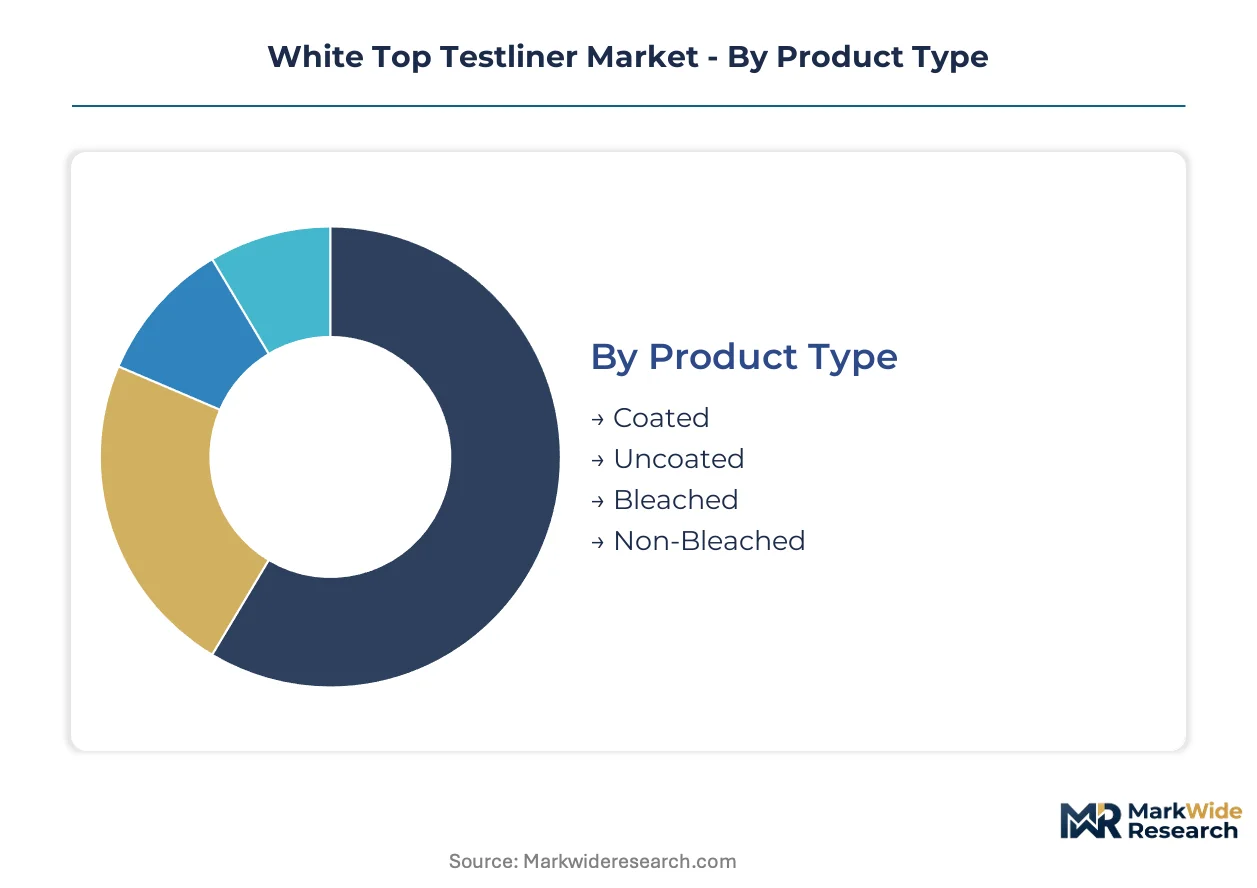
White top testliner specifications diverge sharply between commodity industrial grades and certified food-contact variants. Procurement patterns across Europe favor coated solutions for retail-facing applications while uncoated grades dominate bulk logistics. Understanding these segment boundaries clarifies where mills must deploy barrier-coating capital versus standard Fourdrinier capacity.
Product Type:
The volume-premium split in white top testliner runs through coating investments, with coated grades capturing margin pools from chilled-food barrier requirements while uncoated volumes serve cost-sensitive shipping cases.
- Coated:Clay or polymer-modified top surfaces deliver controlled porosity for moisture and grease resistance. German and French retailers now mandate these grades for ready-meal cartons distributed through refrigerated supply chains, pulling capacity toward EMA-compliant barrier investments.
- Uncoated:Standard white or grey top plies without surface modification offer printable surfaces at lower unit economics. Demand concentrates in Polish and Czech automotive export packaging where stacking strength matters more than barrier performance.
- Bleached:Hydrogen peroxide or elemental chlorine-free whitening of recycled fiber delivers superior brightness for premium brand presentation. Cosmetic and pharmaceutical secondary packaging in Benelux markets specifies these grades for shelf impact.
- Non-Bleached:Retains natural grey-brown fiber coloration from OCC pulping, minimizing chemical processing costs. Industrial shipping cases across Iberian peninsula logistics corridors favor this grade for non-retail applications.
Mature deployment sits with uncoated grades. Newer deployment is concentrated in coated solutions navigating REACH Annex XVII fluoropolymer restrictions.
End Use Industry:
Application-driven segmentation reveals where white top testliner displaces solid bleached board versus competing with kraftliner in heavy-duty cases.
- Food Packaging:Produce trays, ready-meal cartons, and bakery boxes require EMA-compliant surfaces with controlled migration properties. Aldi and Lidl buying groups across Germany and the Netherlands now specify white top testliner for shelf-ready produce categories, consolidating procurement around dual-certification mills.
- Consumer Goods:Personal care and household product cartons demand printable rigidity without food-contact certification overhead. French converters serving parapharmacy retail chains favor these specifications for mid-weight display packaging.
- Electronics:Anti-static and moisture-buffering properties for component shipping favor heavier GSM constructions. Czech and Polish export corridors serving German automotive electronics specify these grades for returnable packaging systems.
- Pharmaceuticals:Secondary packaging for OTC and prescription products requires batch-traceable fiber sourcing with ISO 9001 documentation. Swiss and German markets lead specification of nanocellulose-enhanced barriers for moisture-sensitive dosage forms.
Volume concentration remains with food packaging. Steepest expansion trajectory sits with pharmaceutical applications as nanocellulose coating formulations mature.
Weight:
GSM specifications align with corrugated board flute profiles and pallet-loading requirements across European distribution networks.
- 250 GSM:Lightweight construction for single-wall corrugated display boxes and shelf-ready trays. Belgian supermarket chains specify this weight for produce trays requiring manual handling efficiency.
- 300 GSM:Mid-range specification balancing printability with stacking performance. German bakery and confectionery converters favor this grade for retail-ready shipping cases.
- 350 GSM:Heavy-duty construction for double-wall corrugated export packaging. Polish automotive parts distributors specify this weight for Central European cross-border shipments.
- 400 GSM:Maximum rigidity for triple-wall applications and palletized industrial loads. Limited deployment in specialty machinery export packaging from Nordic production hubs.
Standard procurement clusters at 300 GSM. Emerging specification growth concentrates at 250 GSM as retailers lightweight packaging to meet EU Green Deal material reduction targets.
Distribution Channel:
Channel selection reflects order scale, certification complexity, and converter technical service requirements.
- Direct Sales:Mill-to-converter relationships for high-volume, specification-intensive orders. Major German and French corrugated producers maintain direct contracts with Nordic and Benelux mills for EMA-certified coated grades.
- Distributors:Regional inventory holding for mid-volume converters requiring technical support and smaller lot sizes. Iberian peninsula markets rely heavily on distributor networks given fragmented converter geography.
- Online Retail:Digital procurement platforms for standardized, uncertified grades with transparent pricing. Limited penetration in food-contact segments due to qualification documentation requirements.
- Wholesale:Bulk volume aggregation for industrial shipping case applications without certification overhead. Polish and Romanian markets show concentration here as regional logistics hubs mature.
Direct relationships dominate coated-grade procurement. Wholesale channels capture expanding share in uncoated industrial segments as Central European converter bases consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benelux logistics corridors concentrate coated-grade demand as EU Green Deal recycled-content mandates harden minimum thresholds for food-contact board grades.
Germany
Corrugated converters in Bavaria and North Rhine-Westphalia expand white top testliner orders for automotive and electronics export packaging. EMA food-contact certification requirements now govern chilled ready-meal carton specifications across German retail chains. The Rhine-Main logistics cluster anchors Central European distribution networks serving Polish and Czech manufacturing corridors.
France
Parapharmacy retail chains in Île-de-France specify mid-weight white top testliner for display packaging with printable rigidity. REACH Annex XVII restrictions on coating chemistries impose dual-certification overhead for mills serving both domestic and export markets. The Lyon-Auvergne industrial basin hosts converters retrofitting corrugators for UV-curable ink compatibility.
Netherlands
Supermarket cooperatives mandate shelf-ready produce trays with printable white-top surfaces for refrigerated distribution networks. EFSA parallel review processes extend new product qualification cycles beyond eighteen months for barrier-coated grades. The Rotterdam-Antwerp port corridor enables Nordic mill access to Benelux converter demand.
Poland
Underpenetrated converter bases in Silesia and Greater Poland expand consumption to serve regional logistics hub maturation. F-Gas Regulation thermal efficiency standards create first-mover advantage for mills investing in heat-recovery drying systems. Warsaw-area distributors aggregate bulk volume for industrial shipping case applications without certification overhead.
Spain
Iberian peninsula markets rely on distributor networks given fragmented converter geography across Catalonia and Madrid regions. OCC price volatility from municipal collection disruptions affects recycled-fiber input costs for domestic mills. Barcelona-area converters favor non-bleached grades for non-retail industrial applications.
White Top Testliner Market Competitive Landscape
Nordic producers anchor the integrated pulp-to-board tier; Benelux and Iberian specialists hold positions in recycled-fiber sourcing and coating formulation. The vendor base concentrates around mills with captive collection networks and multi-ply forming capabilities. Three archetypes define competitive positioning: integrated Nordic giants with energy-efficient drying assets, regional European champions with dense converter relationships, and specialty coating innovators navigating food-contact certification. Capacity expansion and barrier-technology licensing represent the dominant competitive moves as REACH compliance hardens cost-of-entry calculus.
Within the integrated-tier archetype, International Paper and Stora Enso occupy positions defined by Nordic mill footprints and captive pulp supply. Smurfit Kappa Group exemplifies the regional-champion model through recycled-fiber collection density across Iberian and Benelux corridors. Mondi Group represents the specialty-innovation vector via coating formulation capabilities that navigate EMA and FDA dual-certification requirements for food-contact applications.
| Leading Market Players |
|---|
| International Paper |
| Polo Handels |
| Smurfit Kappa Group |
| Green Power Holding |
| PG Paper Company |
| DS Smith |
| Stora Enso |
| LEIPA Georg Leinfelder |
| Mondi Group |
| Others |
Value Network & Pricing Analysis
Coated-grade certification ladders create tiered margin pools that separate EMA-compliant barrier formulations from commodity uncoated volumes, with pricing power concentrating in mills possessing dual-certification capabilities while supply chains fragment around Nordic collection density versus Iberian spot-market volatility.
Pricing Analysis
Short-lead-time premiums for EMA-certified coated grades now exceed standard contract pricing by meaningful spreads, while spot-market uncoated volumes trade at discounts reflecting OCC cost volatility. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden: EMA-FDA dual-certified barrier grades command top positioning, single-certified food-contact grades occupy mid-tier, and industrial uncoated specifications sit at economy levels. Price differentiation hinges on coating chemistry compliance costs and fiber sourcing traceability. Pricing pressure stems from REACH Annex XVII reformulation mandates hitting fluoropolymer-dependent mills. Industrial shipping-case buyers show highest price sensitivity; pharmaceutical and chilled-food segments absorb premiums for barrier performance.
Supply Chain Analysis
EU Green Deal recycled-content mandates are reshaping sourcing patterns toward captive collection networks in Germany, Sweden, and Finland. Raw material flows draw from Nordic OCC corridors, Benelux municipal collection systems, and Iberian post-consumer fiber pools. Supply chain risk centers on single-source vulnerability in coating chemical supply, particularly bio-based barrier alternatives replacing restricted fluoropolymers. Distribution runs through mill-direct relationships for certified grades, with regional distributors holding inventory for mid-volume converters in fragmented Iberian and Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: multi-ply forming technician scarcity and eighteen-month EMA qualification timelines prop pricing for qualified capacity.
For Market Incumbents: Extend coating formulation R&D into nanocellulose-barrier convergence to capture pharmaceutical margin pools before specialty competitors consolidate. Lock in long-term OCC supply contracts across Nordic and Benelux collection corridors to defend against fiber cost volatility. Prioritize heat-recovery drying investments ahead of F-Gas Regulation revisions to secure first-mover operational cost advantage. For New Entrants and Emerging Players: Launch via distributor partnerships in Polish and Romanian wholesale channels where certification overhead is lowest and converter consolidation creates volume aggregation opportunities. Target 250 GSM lightweight specifications for retail produce trays as EU Green Deal material reduction mandates accelerate specification shifts. Pursue private-label coating tolling arrangements with established mills to bypass capital-intensive forming assets. For Investors and Strategic Acquirers: Re-rating potential sits with specialty coating innovators possessing EMA-FDA dual-certification capabilities given pending fluoropolymer substitution demand inflection. Five-to-ten-year viability favors mills with backward integration into recycled-fiber collection and captive pulp supply. Monitor ECHA enforcement intensity against imported non-EU board as signal for domestic capacity utilization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating R&D Partnership | Nanocellulose convergence opens pharmaceutical and fresh-produce applications beyond commodity food packaging. |
| Heat-Recovery Drying Retrofit | F-Gas Regulation thermal standards create first-mover cost advantage for mills with upgraded energy assets. |
| Captive Fiber Collection Expansion | EU Green Deal recycled-content thresholds favor mills controlling Nordic and Benelux post-consumer supply corridors. |
| Dual-Certification Investment | EMA-FDA parallel qualification enables access to Aldi and Lidl pan-European buying group tenders. |
| Digital Print Surface Engineering | UV-curable ink compatibility captures short-run, variable-data packaging demand from regional food brands. |
Research Methodology
Trade association filings, ECHA substance restriction databases, and customs export records formed the secondary backbone for this analysis. Primary interviews with corrugated converter procurement directors, mill-level technical sales managers, and retail packaging specification leads validated supply-side capacity and demand-side qualification timelines. Bottom-up volume estimates from segment-level GSM specifications and top-down cross-checks against Nordic and Benelux production data were triangulated to anchor market sizing.
Historical trendline analysis across coated and uncoated grade trajectories informed projection frameworks over the analysis window. Segmentation modeling incorporated product type, end-use industry, weight specification, and distribution channel dimensions. CAGR derivation rested on capacity expansion pipelines, regulatory compliance cost curves, and substitution elasticity between white top testliner and competing substrates. Forecast inputs included EMA certification queue lengths and F-Gas Regulation implementation schedules.
OCC price volatility, REACH Annex XVII enforcement intensity, and plastic substitution acceleration in chilled-food segments are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding recycled-fiber availability and coating chemistry transition timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Pigment Market
Paper Products
Solid Bleached Board Market
Paper Products
Glassine Paper Market
Paper Products
Specialty Paper Market
Paper Products
Fluff Pulp Market
Paper Products
GCC Stone Paper Market
Paper Products
Chemical Pulp Market
Paper Products
North America Coated Paper Market
Paper Products
Functional and Barrier Coatings for Paper Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
North America Decor Paper Market
Paper Products
Global Paper Chemical Market
Paper Products
Americas Stone Paper Market
Paper Products
Inkjet Papers and Films Market
Paper Products
Liquid Paperboard Market
Paper Products
Woodfree Paper Market