
 Uncoated White Top Testliner Market | 2026-2036
Uncoated White Top Testliner Market Size, Share, and Industry Trends Forecast 2026-2036
Uncoated White Top Testliner Market Analytics
Finland's pulp-to-board capacity expansion is rewriting supply dynamics for uncoated white top testliner across Northern Europe. Stora Enso leverages its integrated forest-products chain to sustain cost-advantaged virgin fiber output. Mondi Group anchors cross-border supply through its Central European mill network. International Paper competes on containerboard scale while navigating divergent recycling standards between EU and export markets.
Uncoated white top testliner denotes a multi-ply containerboard grade with an unbleached or semi-bleached recycled fiber base and a white-printable top layer, typically manufactured through Fourdrinier or hybrid forming with dry-strength additives to achieve burst indices of 2.0–3.5 kPa·m²/g. The grade serves premium corrugated packaging where direct flexographic or offset lithographic printing replaces separate label application. Virgin testliner dominates structural packaging for electronics exports where fiber consistency ensures predictable die-cutting performance. Recycled testliner gains share in food and beverage applications as post-consumer fiber processing yields improve. High-strength grades command margin pools in palletized agricultural exports requiring edge-crush resistance above 7.5 kN/m.
The EU Packaging and Packaging Waste Regulation and Germany's Verpackungsgesetz enforce minimum recycled content thresholds that reshape fiber procurement for testliner producers. REACH compliance for surface sizing agents and FDA food-contact migration limits for uncoated grades govern market access in respective jurisdictions. Stakeholders must monitor fiber cost spreads between OCC collections and virgin pulp to calibrate grade-mix decisions ahead of regulatory tightening.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing fiber procurement timelines for testliner mills, forcing rapid recalibration of recycled-to-virgin fiber ratios across European supply chains.
Growth Catalysts
- E-commerce fulfillment surge:German corrugated packaging clusters absorb rising demand for direct-print shipping boxes, displacing labeled alternatives in food and beverage logistics.
- REACH-compliant dry-strength chemistry:Advances in surface sizing agents enable higher recycled fiber content without sacrificing printability thresholds required by premium brand owners.
- Rhine-Ruhr logistics density:Proximity to Benelux container ports and inland waterway networks reduces finished board transport costs for export-oriented converters.
Market Restraints
- OCC collection volatility:Post-consumer fiber availability fluctuates with municipal recycling program funding cycles, compressing margin predictability for recycled-grade producers.
- Fourdrinier asset concentration:Capacity for uncoated white top grades clusters in Nordic and Central European integrated mills, creating supply vulnerability during energy price spikes.
- Plastic corrugated substitution:Reusable polypropylene boxes gain share in closed-loop agricultural logistics, threatening edge-crush-resistant testliner volumes in palletized produce exports.
Strategic Opportunities
- Eastern European converter expansion:Underpenetrated Polish and Romanian corrugated markets offer white-field capacity deployment for mills with cross-border rail access.
- Food-contact certification premium:EFSA-compliant uncoated grades command pricing power in dairy and chilled ready-meal segments where migration limits restrict competitive supply.
- Hybrid forming technology convergence:Combination of gap-forming base layers with Fourdrinier white tops enables burst index customization without dedicated virgin fiber lines.
Industry Challenges
- Die-cutting precision engineering:Fiber variability in high-recycled-content grades demands advanced crush-cut tooling calibration, stretching technical talent pools in converter operations.
- CSRD reporting integration:Scope 3 emissions disclosure requirements for packaging supply chains force mill-to-converter data system interoperability investments ahead of 2025 compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uncoated White Top Testliner Market |
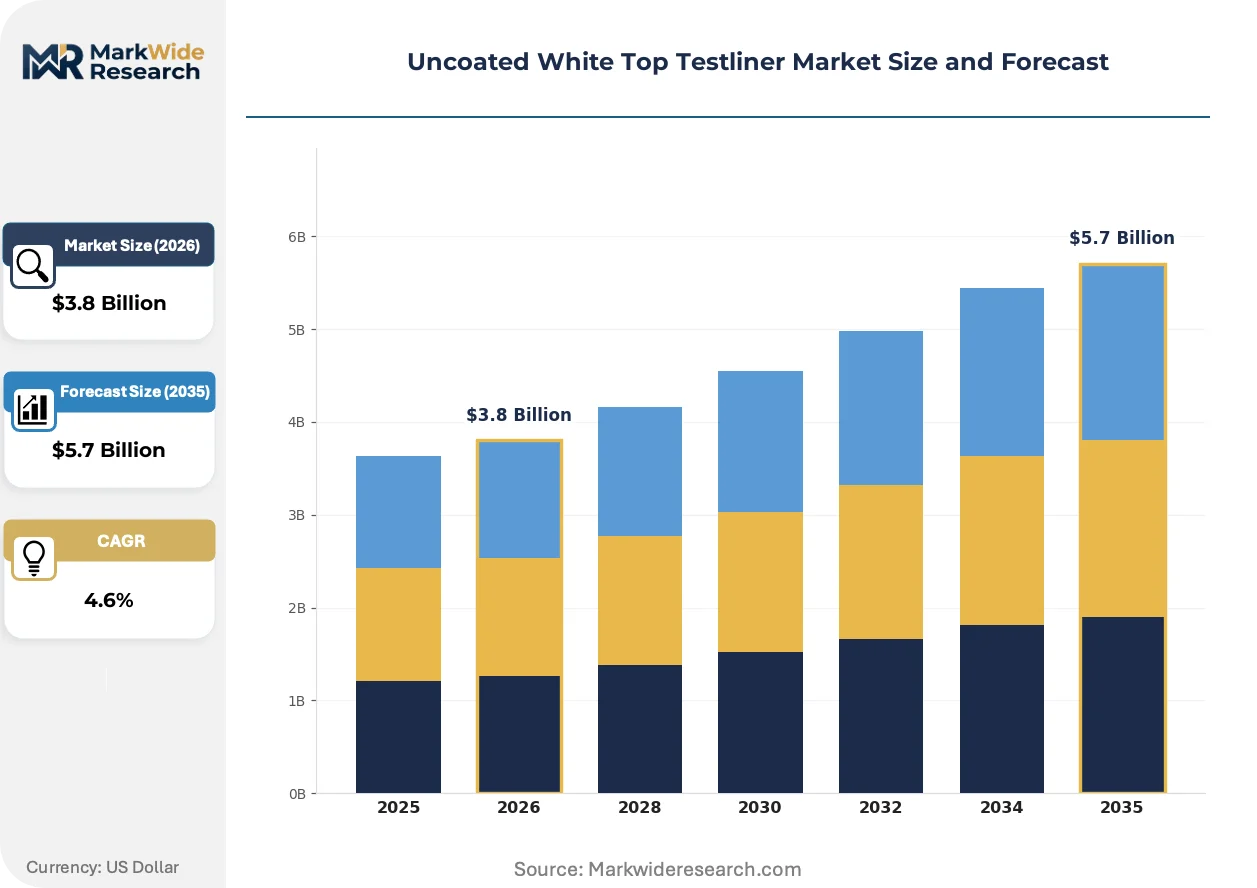
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recycled Testliner, Virgin Testliner, Coated Testliner, Uncoated Testliner Application: Packaging, Printing, Construction, Stationery End User: Food & Beverage, Consumer Goods, Electronics, Healthcare Grade: High Strength, Standard Grade, Lightweight, Recycled Grade |
| Companies Covered | International Paper, Polo Handels, Smurfit Kappa Group, Green Power Holding, PG Paper Company, DS Smith, Stora Enso, LEIPA Georg Leinfelder, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uncoated White Top Testliner Market Evolving Landscape
Digital print readiness specifications are rewriting grade development priorities, as brand owners eliminate pre-print inventory risk through short-run corrugated production.
Near-infrared spectroscopy for real-time fiber composition monitoring is virtualizing quality control protocols across testliner production lines. Premium electronics exporters in the Netherlands and Belgium adopt these traceability-assured grades for predictable die-cutting performance. The technology is virtualizing traditional lab-based testing workflows, compressing batch release cycles from hours to minutes.
EU Green Deal carbon border adjustment mechanisms reshape competitive positioning for virgin fiber imports from Nordic kraft pulp producers. German packaging converters face incremental compliance costs for non-EU sourced linerboard that erode cost advantages previously held by integrated overseas suppliers. Mills with certified renewable energy procurement gain preferential supplier status in retailer sustainability scorecards.
Brand-owner consolidation in European food retail is concentrating corrugated purchasing through centralized packaging engineering teams. Direct mill relationships displace traditional merchant distribution for volume accounts in the Benelux and northern France. This procurement compression is most visible in private-label beverage and dairy segments where specification standardization across retail banners reduces grade complexity requirements.
Uncoated White Top Testliner Market Segmentation
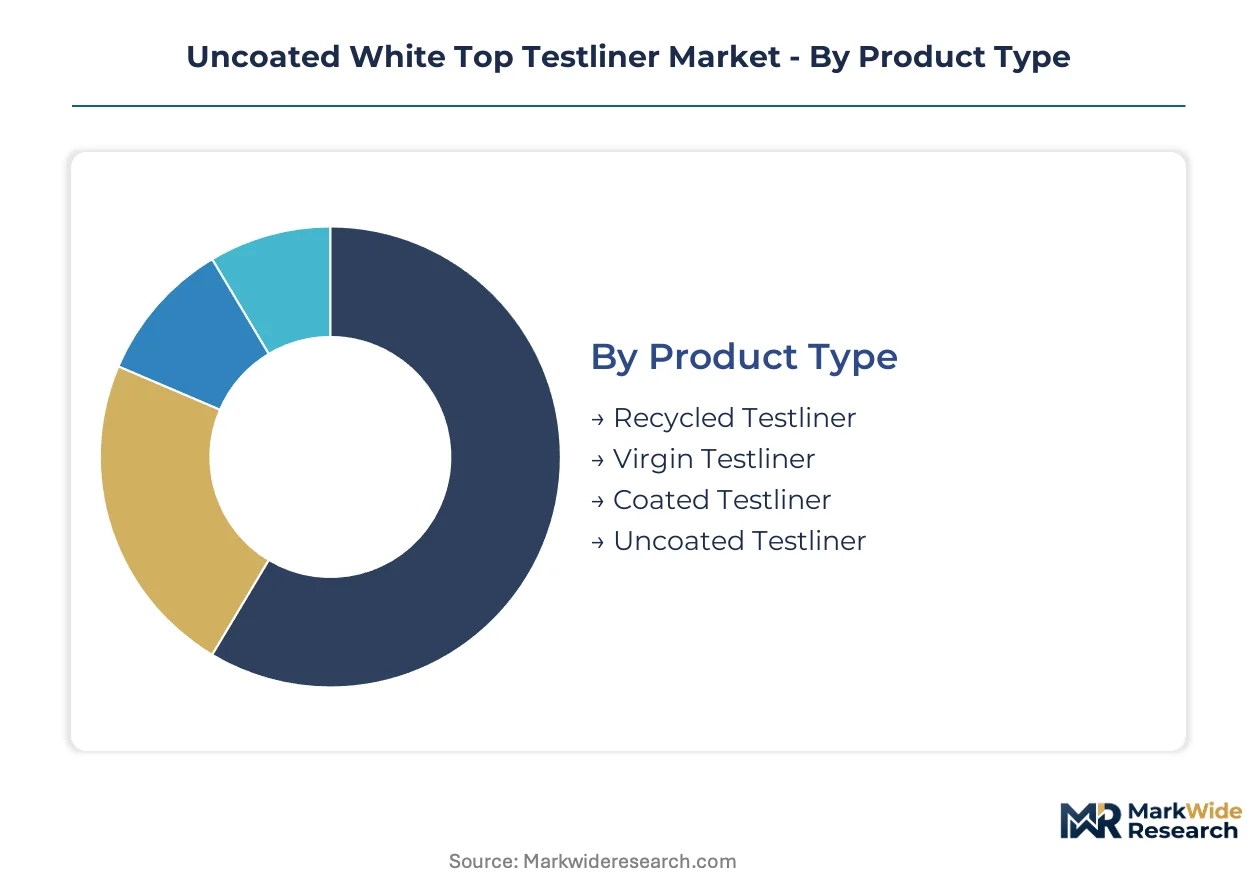
Uncoated white top testliner serves divergent performance requirements across containerboard applications. Grade selection balances burst strength, printability, and regulatory compliance against fiber cost structures. Procurement teams calibrate specifications to end-use durability thresholds and direct-print branding requirements.
Product Type:
Recycled fiber integration spans the full use-case spectrum from basic shipping containers to premium retail-ready packaging. Virgin fiber maintains structural integrity for precision die-cutting in electronics export applications.
- Recycled Testliner:Multi-ply board manufactured from 80-100% post-consumer recovered fiber with dry-strength additives compensating for shorter fiber length. German corrugated converters absorb the majority of European volume as Verpackungsgesetz mandates tighten recycled content floors.
- Virgin Testliner:Unbleached kraft pulp base delivers consistent fiber length distribution and predictable crush resistance. Finnish integrated mills supply premium grades to Benelux electronics exporters requiring edge-crush resistance above 7.5 kN/m for palletized sea freight.
- Coated Testliner:Surface clay or pigment coating enables high-resolution offset lithography for luxury consumer goods presentation packaging.
- Uncoated Testliner:Direct-print receptive surface without additional coating layers, preferred for flexographic short-run production and sustainability scoring.
The dominant share belongs to Recycled Testliner, while Virgin Testliner is closing the gap fastest through food-contact certification premiums.
Application:
Volume concentration tracks e-commerce fulfillment density and retail supply chain restructuring across Northern Europe.
- Packaging:Corrugated case manufacture for transit and shelf-ready applications consumes the majority of uncoated white top tonnage. Rhine-Ruhr logistics clusters anchor demand as direct-print shipping boxes displace pre-labeled alternatives in food and beverage logistics.
- Printing:Short-run digital print readiness specifications drive grade development for brand owners eliminating inventory risk. Dutch retail banner consolidation accelerates specification standardization across private-label segments.
- Construction:Temporary protective sheathing and concrete formwork applications favor lower-cost recycled grades with reduced printability requirements.
- Stationery:Premium folder and binder applications command small-volume specialty production with enhanced surface smoothness specifications.
Packaging commands the installed capacity base, though Printing is expanding most quickly through digital production adoption.
End User:
Regulatory migration limits and shelf-life requirements segment procurement priorities across consumer-facing industries.
- Food & Beverage:Dairy and chilled ready-meal segments drive EFSA-compliant uncoated grade premiums. Migration testing protocols restrict competitive supply for direct-contact applications.
- Consumer Goods:Cosmetics and personal care brand owners specify high-brightness white tops for shelf impact without secondary labeling.
- Electronics:Export-oriented manufacturers in the Netherlands and Belgium require predictable die-cutting performance from low-variability virgin fiber grades.
- Healthcare:Sterile barrier packaging and pharmaceutical logistics demand certified fiber traceability and controlled substance migration profiles.
Food & Beverage holds the volume anchor position, while Healthcare is climbing the fastest through traceability-assured grade premiums.
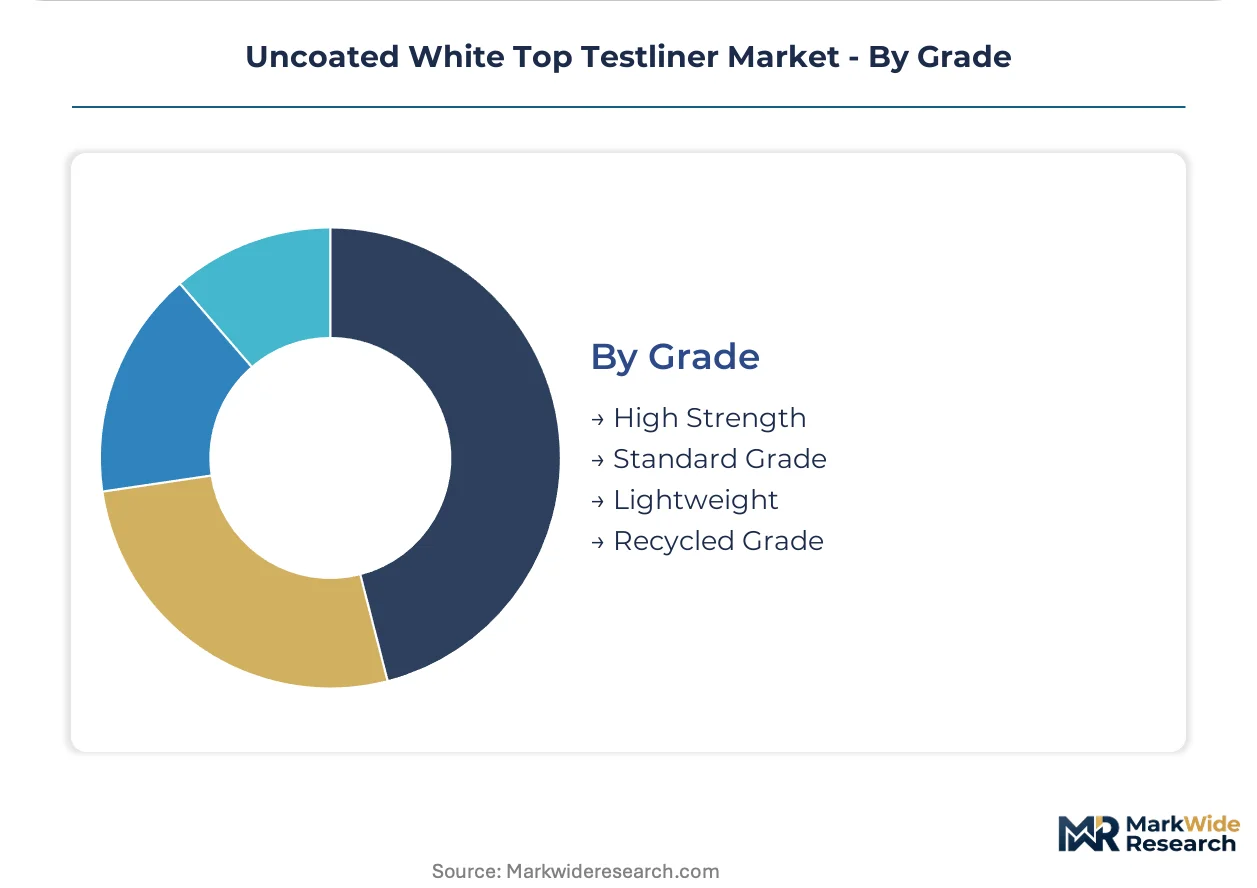
Grade:
Performance tiering aligns burst index specifications with palletized load requirements and printing resolution demands.
- High Strength:Burst indices of 3.0-3.5 kPa·m²/g and edge-crush resistance above 7.5 kN/m serve agricultural export palletization. Stora Enso's Nordic kraft integration secures cost-advantaged virgin fiber supply for this tier.
- Standard Grade:Balanced performance for general-purpose corrugated cases with burst indices of 2.5-3.0 kPa·m²/g. Mondi Group's Central European mill network optimizes cross-border delivery for this mid-tier volume.
- Lightweight:Reduced grammage specifications maintain stiffness through advanced dry-strength chemistry, lowering transport costs for e-commerce fulfillment.
- Recycled Grade:Maximum post-consumer fiber content within regulatory thresholds, subject to OCC collection availability and municipal program funding cycles.
Standard Grade maintains the production volume base, though High Strength is gaining share fastest through agricultural export palletization growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Verpackungsgesetz mandates from Germany's federal environment ministry establish the regulatory baseline for uncoated white top testliner procurement across Northern European supply chains. Mill capacity clusters in the Rhine-Ruhr corridor absorb the majority of regional volume as e-commerce fulfillment packaging specifications tighten.
Germany
Rhine-Ruhr logistics density drives converter demand for direct-print shipping boxes in food and beverage distribution. Verpackungsgesetz recycled content floors force rapid recalibration of fiber procurement toward post-consumer sources. Düsseldorf-Dortmund mill networks anchor supply for Benelux export corridors.
Netherlands
Rotterdam-Antwerp port throughput channels premium electronics exports requiring predictable die-cutting performance from virgin fiber grades. REACH compliance for surface sizing agents governs market access for food-contact applications. Eindhoven-Tilburg converter clusters specialize in short-run digital print readiness specifications.
Finland
Integrated forest-products chains sustain cost-advantaged kraft pulp output for high-strength agricultural export palletization. EU Green Deal carbon border adjustments reshape competitive positioning for virgin fiber shipments to Central European converters. Kotka-Rauma mill networks optimize Baltic Sea logistics for German and Polish demand.
Poland
Underpenetrated corrugated markets offer white-field capacity deployment for mills with cross-border rail access from Germany and Czechia. EFSA-compliant grade premiums attract dairy and chilled ready-meal packaging investment. Silesian manufacturing zones concentrate converter expansion near German border logistics.
Belgium
Benelux retail banner consolidation centralizes corrugated purchasing through packaging engineering teams in Brussels-Antwerp corridor. Migration testing protocols restrict competitive supply for direct-contact food applications. Ghent industrial zones host specialty converters serving premium cosmetics and personal care brand owners.
Uncoated White Top Testliner Market Competitive Landscape
Capability concentration sits with integrated Nordic forest-product groups; scale advantage sits with transatlantic containerboard specialists. The market structures around three tiers: virgin fiber-integrated producers commanding premium agricultural and electronics export grades; recycled-grade specialists optimizing Verpackungsgesetz compliance; and merchant distributors consolidating purchasing for mid-tier converters. Dominant competitive moves include hybrid forming technology licensing and backward integration into OCC collection networks.
Within the integrated-producer tier, Stora Enso and Mondi Group exemplify divergent geographic anchoring strategies. Smurfit Kappa Group occupies a position spanning merchant distribution and mill ownership. International Paper represents transatlantic scale deployment amid divergent EU and export market recycling standards. LEIPA Georg Leinfelder anchors specialized recycled-grade production within German regulatory compliance frameworks.
| Leading Market Players |
|---|
| International Paper |
| Polo Handels |
| Smurfit Kappa Group |
| Green Power Holding |
| PG Paper Company |
| DS Smith |
| Stora Enso |
| LEIPA Georg Leinfelder |
| Mondi Group |
| Others |
Value Network & Pricing Analysis
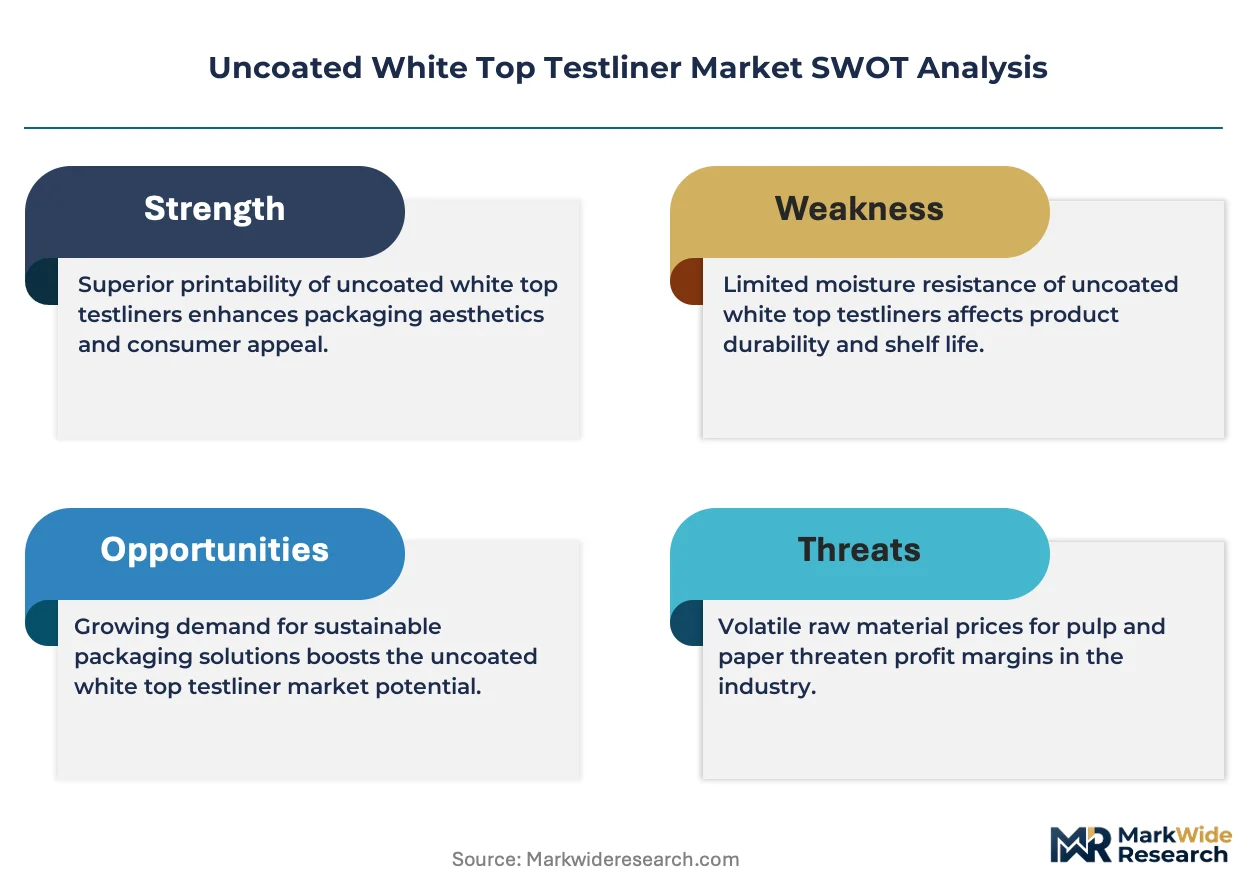
Undercapacity in Finland's kraft pulp integration is compressing margin pools for virgin fiber testliner while forcing German converters toward higher recycled-content grades. This utilization squeeze simultaneously elevates pricing power for Nordic integrated mills and accelerates cost-pass-through negotiations with Rhine-Ruhr packaging clusters.
Pricing Analysis
Price spreads between Finnish virgin fiber shipments and Central European recycled grades are widening as EU Green Deal carbon border adjustments layer compliance premiums onto Nordic imports. Three-tier pricing structure across EFSA-certified premium, Verpackungsgesetz-compliant standard, and economy recycled levels stratifies procurement tiers. Pricing pressure stems from OCC collection volatility compressing margin predictability for post-consumer fiber specialists. Small-format e-commerce converters exhibit highest price sensitivity, while electronics exporters absorbing premium virgin grades demonstrate lowest elasticity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard supply-chain finance instruments among German corrugated converters managing Verpackungsgesetz compliance costs. Geographic concentration centers on Finland, Germany, and Poland, with Finnish kraft integration anchoring virgin fiber supply and Polish rail corridors feeding underpenetrated Eastern European demand. Raw material dependencies rest on OCC collection networks, dry-strength chemical additives, and surface sizing agents. Single-source vulnerability concentrates in Nordic kraft pulp for high-strength agricultural grades. Distribution runs through integrated mill-direct relationships displacing traditional merchant channels for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as e-commerce fulfillment packaging displaces labeled alternatives across European food logistics. Digital print readiness specifications are accelerating grade development timelines and shortening converter procurement cycles.
For Market Incumbents: Harden defensibility through backward integration into OCC collection networks securing post-consumer fiber supply ahead of regulatory tightening. Deepen captive kraft pulp capacity in Finland to sustain cost advantages as carbon border adjustments erode import competitiveness. Plastic corrugated substitution in agricultural logistics and hybrid forming technology licensing by competitors constitute immediate threats requiring monitoring. For New Entrants and Emerging Players: Build out white-field converter capacity in Poland and Romania where corrugated penetration lags German benchmarks by substantial margins. Target EFSA-compliant uncoated grades for dairy and chilled ready-meal segments where migration testing protocols restrict incumbent supply. Lead with food-contact certification as the primary go-to-market wedge against established recycled-grade specialists. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated Nordic forest-product groups with captive pulp supply and long-term offtake agreements with Benelux electronics exporters. Five-to-ten year viability favors mills with hybrid forming technology licenses enabling burst index customization without dedicated virgin fiber lines. Acquisition targets should display cross-border rail access and EFSA certification infrastructure. Watch for OCC collection network consolidation as the inflection signal for margin compression in recycled-grade specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Collection | Verpackungsgesetz compliance secures post-consumer fiber supply for German mill networks. |
| Hybrid Forming Technology Licensing | Gap-forming base layers combined with Fourdrinier white tops enable grade customization without virgin fiber lines. |
| EFSA Food-Contact Certification Investment | Dairy and chilled ready-meal segments command pricing premiums where migration limits restrict supply. |
| Cross-Border Rail Capacity Expansion | Polish and Romanian corrugated markets absorb white-field deployment from German mill networks. |
| Digital Print Readiness Specification Development | Short-run production capabilities align with brand-owner inventory risk elimination strategies. |
Research Methodology
Desk research of trade association publications, customs filings, and mill capacity databases preceded structured interviews with corrugated plant managers, packaging procurement leads at food and beverage manufacturers, technical R&D directors at dry-strength chemical suppliers, and sustainability officers at retail banner headquarters. Secondary validation drew from EU Packaging and Packaging Waste Regulation documentation, EFSA migration limit guidelines, and SEC filings of publicly traded containerboard producers. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections across the analysis window.
Assumptions held fixed include Verpackungsgesetz recycled content floors, REACH compliance timelines for surface sizing agents, and EU Green Deal carbon border adjustment implementation schedules. Variables incorporated OCC collection rate trajectories, e-commerce fulfillment packaging penetration curves, and digital print adoption velocities across European retail banners. Segmentation dimensions modeled encompassed fiber source type, end-use application, performance grade tier, and regional production hub clustering. CAGRs derived from elasticity-adjusted demand curves calibrated to historical containerboard consumption patterns and pulp-to-board capacity expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by transatlantic containerboard specialists or rapid hybrid forming technology diffusion would shift outcomes. Macroeconomic contraction in German manufacturing, regulatory relaxation of recycled content mandates, or breakthrough advances in plastic corrugated durability would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Machine Systems Market
Paper Products
Paper Pigment Market
Paper Products
Wood-Based Panel Market
Paper Products
Paper Products Market
Paper Products
Paper and Board Technologies Market
Paper Products
Europe Decor Paper Market
Paper Products
North America Coated Paper Market
Paper Products
Billing Paper Market
Paper Products
Duplex Paper and Board Market
Paper Products
Printing and Writing Papers Market
Paper Products
Reprographic Paper Market
Paper Products
Aramid Paper Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Greaseproof Paper Sheets Market
Paper Products
Decor Paper Market
Paper Products
Paper Machinery Market