
 Solid Bleached Sulfate (SBS) Board Market | 2026-2036
Solid Bleached Sulfate (SBS) Board Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Bleached Sulfate (SBS) Board Market Analytics
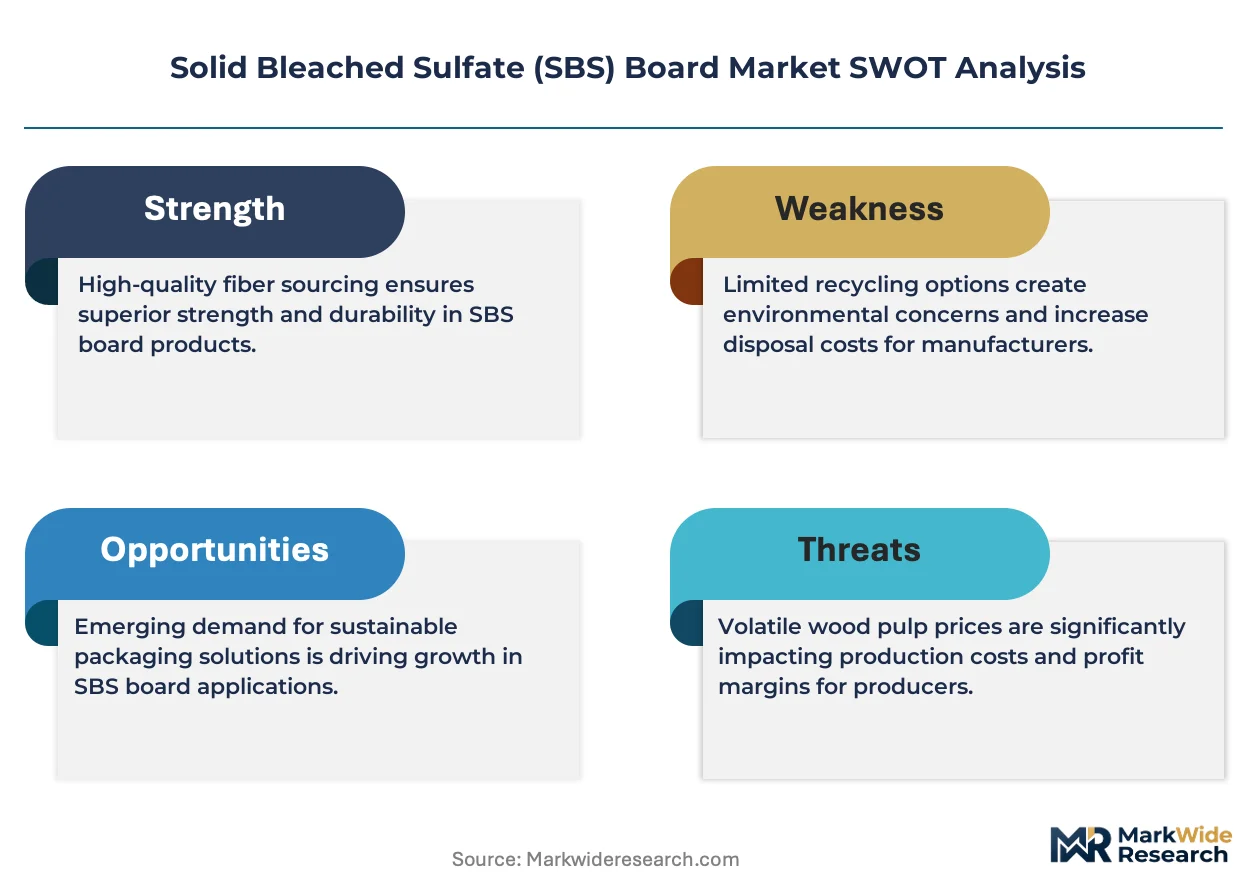
Buyer concentration in North American pharmaceutical packaging is pivoting toward a smaller pool of FDA-validated converters with dedicated SBS supply agreements. Graphic Packaging International leverages its integrated carton converting network to secure multi-year contracts with top drug manufacturers. Sappi sustains European pharmaceutical board leadership through its certified barrier-coating technology. Smurfit WestRock anchors Americas volume through its broad containerboard and specialty paper footprint.
Solid Bleached Sulfate board consists of fully bleached virgin wood fibers refined through chemical pulping, yielding a bright, hygienic surface with high stiffness-to-weight ratios between 200-400 gsm. Its primary purpose serves premium packaging where print fidelity, moisture resistance, and direct food contact compliance prove essential. Specialty Board commands the highest margin pools due to custom barrier properties and short-run flexibility, while Single-Wall dominates total volume in standard folding carton applications. Chemical Pulping underpins quality-grade supply despite higher energy intensity than mechanical alternatives.
FDA food-contact regulations and EPA effluent standards govern North American SBS manufacturing, with REACH and EU Packaging Waste Directive shaping European product specifications and recyclability claims. The EU Green Deal's carbon border adjustments are pressuring energy-intensive bleaching operations to decarbonize or relocate. Stakeholders must monitor how FDA packaging integrity rules and emerging state-level extended producer responsibility laws in the US reshape sourcing requirements and capital allocation priorities for virgin fiber board assets.
Market Dynamics
FDA child-resistant packaging standards are compressing the converter base, forcing pharmaceutical buyers toward vertically integrated suppliers with validated SBS supply chains and barrier-coating certifications.
Growth Catalysts
- REACH-compliant barrier coatings:European pharmaceutical exporters require certified SBS substrates to maintain EU market access, pulling premium board volumes toward certified European mills.
- Pharmaceutical blister packaging:Tightening FDA packaging integrity rules for pediatric safety are mandating stiffer, more printable substrates that SBS uniquely delivers.
- Chemical pulping efficiency gains:Energy consumption per ton is declining through process optimization, improving unit economics for virgin fiber board against recycled alternatives.
Market Restraints
- Softwood pulp cost volatility:SBS pricing tracks northern bleached softwood kraft pulp contracts, exposing converters to commodity swings without pass-through mechanisms.
- European energy intensity:EU carbon border adjustments threaten bleaching operations dependent on natural gas, compressing margins for non-decarbonized mills.
- Polyethylene terephthalate substitution:Clear PET blisters compete for pharmaceutical unit-dose applications where print fidelity matters less than visibility.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO-aligned packaging standards are converging with FDA requirements, creating demand for import-certified SBS among domestic converters.
- Biodegradable barrier coatings:Convergence of aqueous coatings and compostability certifications opens premium positioning against conventional polymer-laminated boards.
- Extended producer responsibility tailwinds:State-level EPR laws in the US are favoring recyclable virgin fiber substrates over multi-material laminates in brand owner specifications.
Industry Challenges
- FDA validation timelines:Converter qualification for pharmaceutical supply chains requires 18-24 month certification cycles that lock working capital and technical resources.
- Barrier coating integration:Migrating from conventional polyethylene extrusion to aqueous or biodegradable alternatives demands retooling of lamination lines and retraining of production crews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Bleached Sulfate (SBS) Board Market |
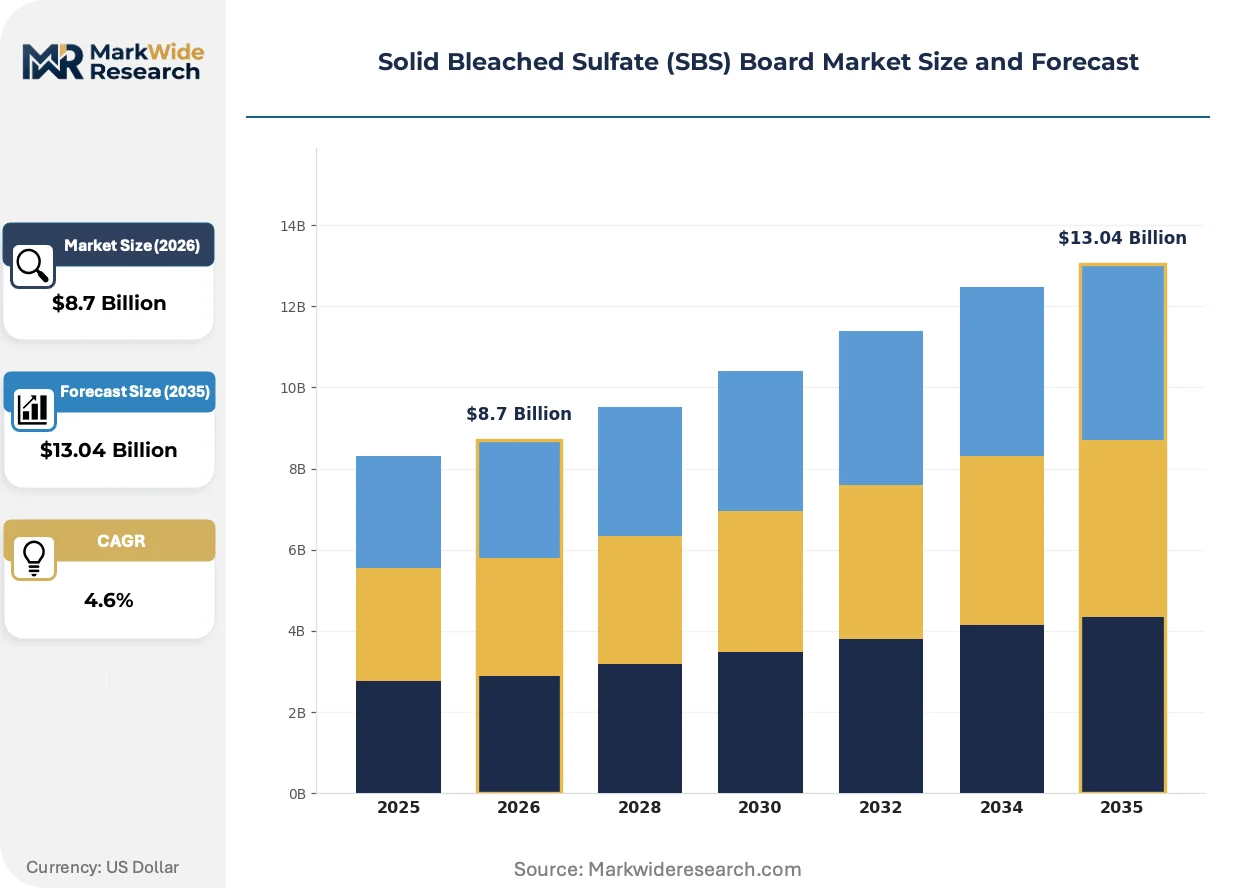
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Wall, Double-Wall, Triple-Wall, Specialty Board End Use: Packaging, Food Service, Consumer Goods, Pharmaceuticals Grade: High-Strength, Lightweight, Coated, Uncoated Manufacturing Process: Mechanical Pulping, Chemical Pulping, Recycled Fiber, Bleaching |
| Companies Covered | Graphic Packaging International, LLC, Sappi, Smurfit WestRock, Holmen Iggesund, Georgia-Pacific LLC, International Paper, Clearwater Paper Corporation, ITC Limited, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Bleached Sulfate (SBS) Board Market Evolving Landscape
Digital print compatibility and barrier performance are converging to redefine premium folding carton specifications, with sustainability certifications now gating access to pharmaceutical and food-contact supply chains.
Water-based barrier coatings are consolidating their position as the preferred alternative to polyethylene extrusion for moisture-sensitive pharmaceutical applications. Major drug manufacturers are specifying these substrates for new product launches to preempt EPR compliance costs. This consolidation is compressing demand for conventional polymer-laminated SBS in premium segments.
EU Green Deal carbon border adjustments are forcing bleaching operations to document Scope 1 and 2 emissions or face import penalties into the European single market. Mills without renewable energy contracts are relocating chemical pulping capacity to Nordic regions with biomass power access. Nordic producers are capturing contract renewals from European pharmaceutical converters seeking supply chain decarbonization.
Consolidated procurement among North American pharmaceutical giants is displacing fragmented spot purchasing with multi-year sole-source agreements. Tier-one drug manufacturers are mandating dedicated mill capacity and audit rights over coating operations. This concentration is most visible among FDA-validated converters serving the generic drug cluster in New Jersey and Pennsylvania.
Solid Bleached Sulfate (SBS) Board Market Segmentation
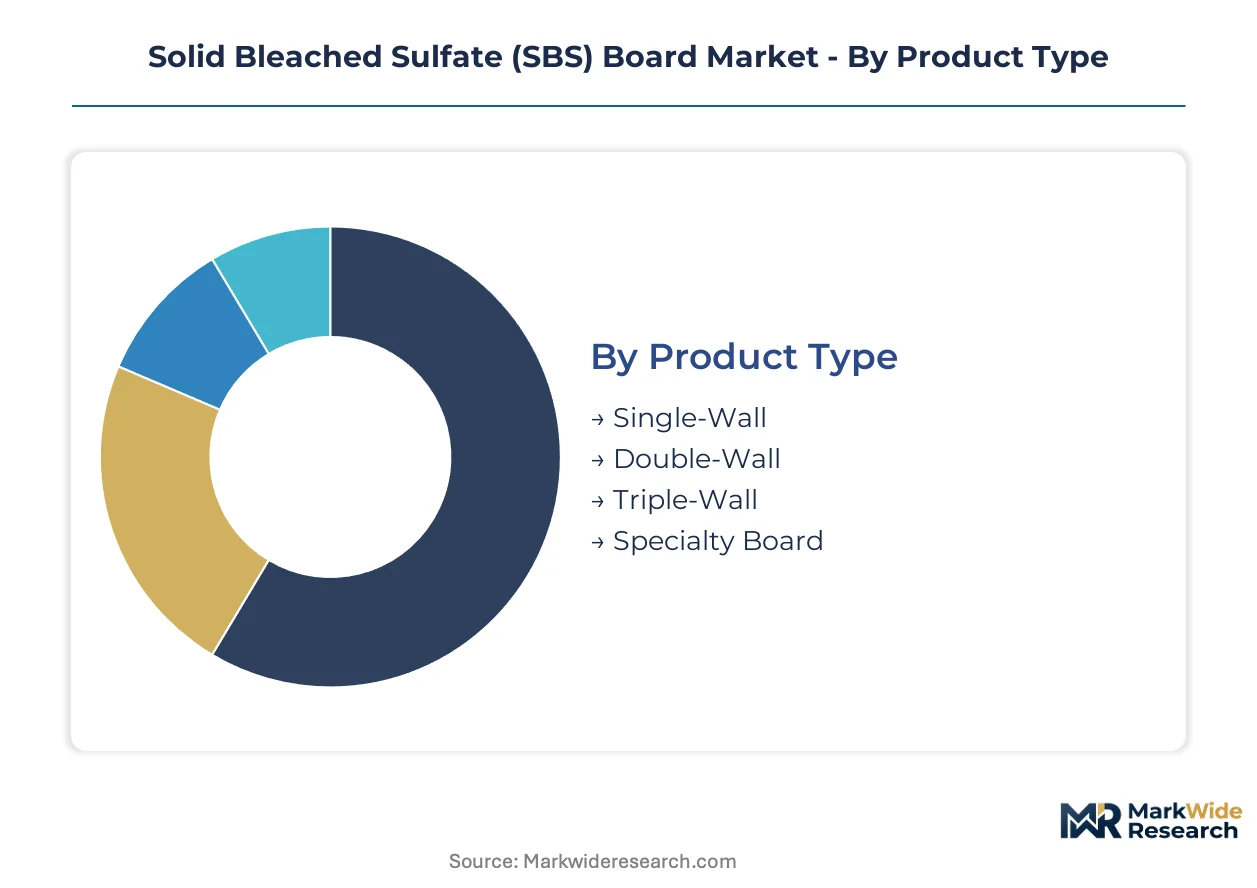
SBS board segmentation reflects divergent buyer priorities across pharmaceutical compliance, food-contact safety, and print performance requirements. Each dimension carries distinct margin structures and capital intensity profiles that reshape supplier positioning.
Product Type:
Buyers select wall configuration based on structural load requirements and converting equipment compatibility.
- Specialty Board:Custom-engineered substrates incorporate aqueous barrier coatings and tailored stiffness profiles for moisture-sensitive pharmaceutical applications. FDA-validated converters in New Jersey and Pennsylvania specify these grades for pediatric safety packaging where coating integrity undergoes 18-24 month qualification cycles.
- Single-Wall:Standard folding carton substrates dominate unit volume across food service and consumer goods. Mills in the US Southeast and Nordic regions supply this grade through high-speed production lines optimized for 200-350 gsm specifications.
- Double-Wall:Enhanced rigidity serves heavier consumer electronics and premium cosmetic packaging where dimensional stability during transport proves critical.
- Triple-Wall:Maximum structural grade addresses industrial applications and bulk pharmaceutical distribution requiring stacking strength beyond standard carton specifications.
Single-Wall leads on scale; Specialty Board leads on momentum.
End Use:
Application-driven specifications separate commodity board from certified pharmaceutical supply chains.
- Pharmaceuticals:Blister packaging and folding cartons for prescription drugs demand FDA-validated substrates with documented fiber sourcing and coating migration testing. Tightening child-resistant packaging standards are compressing demand toward mills with dedicated barrier-coating capabilities and audit-ready quality systems.
- Food Service:Direct-contact compliance for quick-service restaurant packaging and frozen food cartons requires specific bleaching chemistries and extractable limits under FDA food-contact regulations.
- Packaging:General industrial and e-commerce applications prioritize cost efficiency and printability over barrier performance, sourcing standard grades through spot markets and annual contracts.
- Consumer Goods:Premium cosmetics and electronics packaging balance structural requirements with high-fidelity print reproduction, often specifying coated grades with enhanced surface smoothness.
Packaging leads on scale; Pharmaceuticals climbs the fastest.
Grade:
Performance tier selection hinges on strength-to-weight ratios and surface treatment requirements.
- Coated:Clay or polymer surface treatments enable high-resolution lithographic and digital printing for premium pharmaceutical and cosmetic applications. European REACH compliance for coating chemistries is pulling export demand toward certified mills.
- High-Strength:Optimized fiber refining delivers superior stiffness at reduced basis weights, reducing shipping costs for pharmaceutical distributors.
- Lightweight:Reduced grammage specifications serve cost-sensitive food service applications where structural demands remain moderate.
- Uncoated:Raw bleached surfaces suit applications where absorbency or subsequent coating by converters is preferred.
Coated leads on scale; High-Strength gains share fastest.
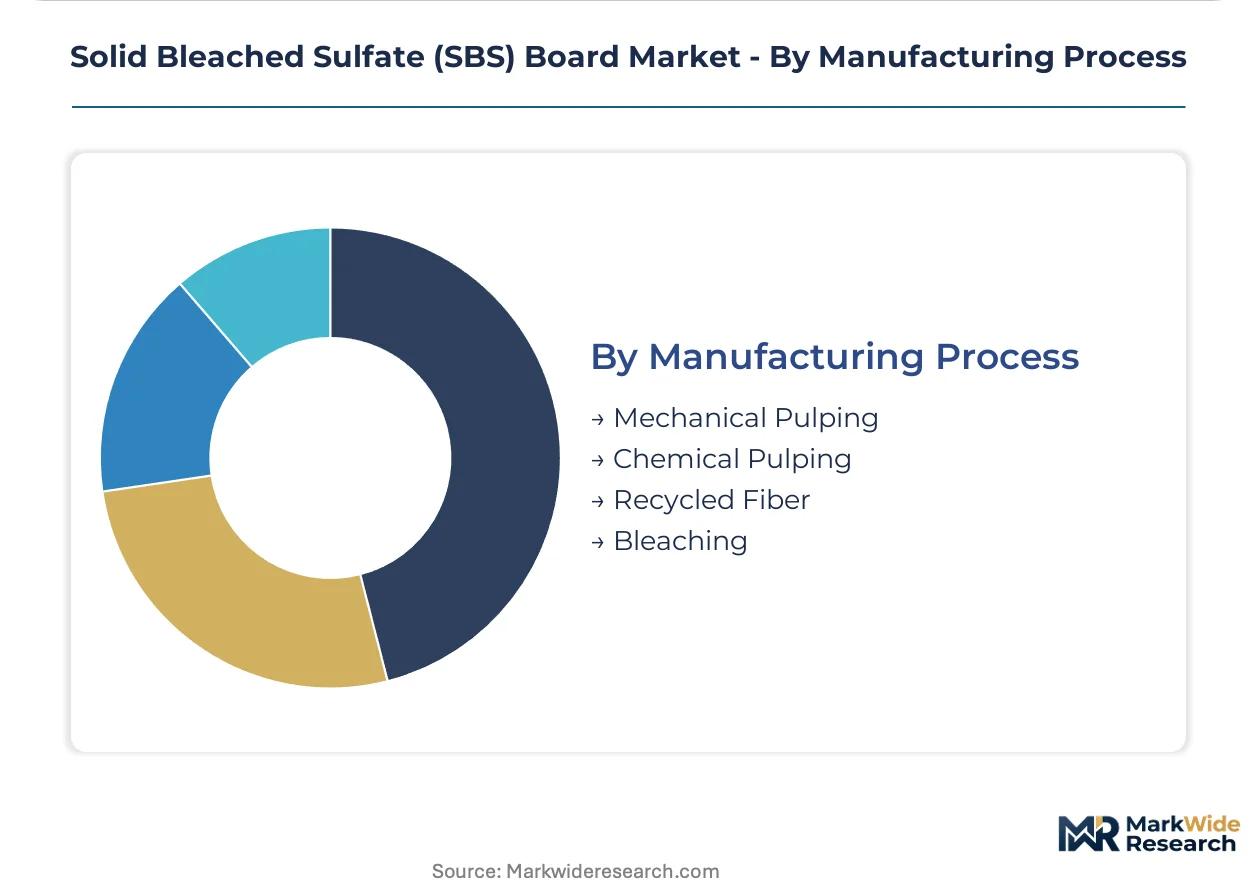
Manufacturing Process:
Pulping method determines fiber quality, energy intensity, and regulatory exposure.
- Chemical Pulping:Kraft process with full bleaching yields the bright, hygienic fibers essential for pharmaceutical and food-contact grades. EU carbon border adjustments are pressuring European mills to document Scope 1 and 2 emissions or relocate capacity to Nordic biomass-powered facilities.
- Bleaching:Elemental chlorine-free and totally chlorine-free sequences govern brightness levels and effluent profiles, with EPA standards shaping North American operations.
- Mechanical Pulping:Higher yield but lower strength restricts application to non-structural or recycled-content blends outside premium SBS specifications.
- Recycled Fiber:Post-consumer content faces limitations in pharmaceutical and direct food-contact applications due to fiber traceability and contamination risk requirements.
Chemical Pulping leads on scale; Bleaching faces steepest regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled converter workforces in New Jersey and Pennsylvania anchor pharmaceutical SBS demand, while Nordic pulp engineering talent sustains European supply quality. Chemical pulping expertise concentrates in specific mill clusters where energy access and regulatory compliance intersect.
United States
FDA-validated pharmaceutical converters in New Jersey and Pennsylvania drive specialty board demand for child-resistant packaging applications. EPA effluent standards under the Clean Water Act shape bleaching operations in the Southeast. Integrated mill-converter networks in the Mid-Atlantic secure multi-year supply agreements with generic drug manufacturers.
Germany
REACH-compliant barrier coating requirements pull premium SBS volumes toward certified European mills serving pharmaceutical exporters. EU Packaging Waste Directive recyclability mandates reshape converter specifications for folding cartons. Industrial packaging clusters in North Rhine-Westphalia specify high-strength grades for automotive component distribution.
India
CDSCO-aligned packaging standards converging with FDA requirements create import-certified SBS demand among domestic pharmaceutical converters. PLI scheme incentives for active pharmaceutical ingredients indirectly support packaging investment. Gujarat-based converters expand capacity to serve export-oriented generic drug manufacturers.
Sweden
EU Green Deal carbon border adjustments drive bleaching capacity relocation to Nordic regions with biomass power access. Biomass-powered chemical pulping operations document Scope 1 and 2 emissions for EU single market compliance. Mill clusters in northern Sweden capture contract renewals from European pharmaceutical converters seeking supply chain decarbonization.
China
Dual carbon goals and GB standards for food-contact paperboard reshape domestic SBS manufacturing investment patterns. NMPA pharmaceutical packaging regulations tighten substrate traceability requirements for domestic drug manufacturers. Yangtze River Delta converters expand coated board capacity for premium cosmetic and electronics packaging exports.
Solid Bleached Sulfate (SBS) Board Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. Consolidated procurement among North American pharmaceutical giants compresses the converter base toward vertically integrated suppliers with validated supply chains. Three archetypes dominate: integrated forest-products conglomerates with captive pulp supply, specialty paper pure-plays with barrier-coating certifications, and regional containerboard operators extending into premium grades. Capacity expansion and strategic partnerships represent the dominant competitive moves, as mills secure renewable energy contracts and converter relationships simultaneously.
Among North American integrated operators, Graphic Packaging International exemplifies the conglomerate archetype through its carton converting network, while Georgia-Pacific occupies a position within forest-products diversification. Sappi represents the specialty pure-play model with European pharmaceutical board leadership. These three anchors illustrate how geographic footprint and integration depth stratify competitive positioning across FDA-validated and REACH-compliant supply chains.
| Leading Market Players |
|---|
| Graphic Packaging International, LLC |
| Sappi |
| Smurfit WestRock |
| Holmen Iggesund |
| Georgia-Pacific LLC |
| International Paper |
| Clearwater Paper Corporation |
| ITC Limited |
| Stora Enso |
| Others |
Value Network & Pricing Analysis
Skilled chemical pulping engineers in the US Southeast and Nordic regions anchor production cost differentials that widen spreads between FDA-validated pharmaceutical grades and standard folding carton tiers. Labor scarcity at certified barrier-coating facilities compresses margins on specialty board while spot-market softness in food-service grades intensifies price competition among commodity mills.
Pricing Analysis
Coated SBS board commands premium positioning through bundled barrier-certification services that pharmaceutical converters lock in via multi-year sole-source agreements, while uncoated grades trade on transactional spot markets with minimal service attachment. Price differentiation rests on FDA validation status and renewable energy sourcing credentials, with Nordic biomass-powered mills capturing contract renewals at sustained premiums. Cost compression in standard Single-Wall grades is intensifying because Southeast US mills face natural gas price volatility without carbon-adjustment hedging. Generic drug manufacturers in New Jersey and Pennsylvania exhibit highest price sensitivity due to consolidated procurement mandates, while innovator pharmaceutical brands prioritize coating integrity over unit cost.
Supply Chain Analysis
Regional distribution centers in the US Mid-Atlantic and Nordic port clusters coordinate hub-and-spoke patterns that position inventory within 48-hour reach of FDA-validated converters. Manufacturing concentrates in the United States, Sweden, and Germany, with emerging capacity additions in India serving CDSCO-aligned export requirements. Chemical pulping operations draw from northern bleached softwood kraft pulp contracts, aqueous coating chemistries, and biomass power purchase agreements. Single-source vulnerability runs through Nordic biomass supply chains exposed to EU carbon border documentation requirements. Distribution runs through mill-direct arrangements with integrated converters and specialized pharmaceutical packaging distributors holding cold-chain certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SBS board market functions as a stable compounder where tightening FDA packaging integrity standards for pediatric safety create durable demand pull with limited substitution risk. Regulatory compliance investments by incumbent mills erect structural barriers that protect pricing power across pharmaceutical-grade segments.
For Market Incumbents: Deepen backward integration into certified barrier-coating operations to capture margin pools currently leaking to third-party laminators, while securing dedicated pulp supply agreements that hedge against northern bleached softwood kraft volatility. PET blister substitution in unit-dose applications and emerging aqueous coating specialists threaten premium positioning, making in-house coating capability the critical defensive lever.
For New Entrants and Emerging Players: Launch via toll-manufacturing partnerships with underutilized Nordic chemical pulping assets to bypass 18-24 month FDA validation cycles while accumulating batch records for independent certification. CDSCO-aligned pharmaceutical packaging in India represents the most penetrable geography, with Gujarat-based converters expanding capacity to serve export-oriented generic drug manufacturers seeking import-certified substrates.
For Investors and Strategic Acquirers: Integrated forest-products conglomerates with captive pulp supply and existing FDA-validated converter relationships are the most active acquirers in this space, targeting specialty paper pure-plays with barrier-coating certifications to fill portfolio gaps. Long-term viability hinges on decarbonized chemical pulping capacity with documented Scope 1 and 2 emissions for EU single market access. Watch for state-level extended producer responsibility law enactments in the US as the signal indicating accelerated brand-owner preference shifts toward recyclable virgin fiber substrates.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New chemical pulping lines in Nordic regions with biomass power access secure EU Green Deal compliance for pharmaceutical export contracts. |
| Backward Integration | Captive aqueous barrier-coating operations eliminate third-party laminator margins and accelerate FDA validation timelines. |
| Long-term Supply Agreement | Multi-year sole-source contracts with New Jersey and Pennsylvania generic drug manufacturers lock in volume against spot-market volatility. |
| Green Manufacturing Transition | Elemental chlorine-free bleaching sequences with renewable energy documentation satisfy EU carbon border adjustment requirements. |
| Joint Venture | Partnerships with Indian converters in Gujarat align CDSCO standards with FDA requirements for export-oriented pharmaceutical packaging. |
Research Methodology
Direct dialogue with mill operations managers, pharmaceutical packaging procurement directors, FDA regulatory consultants, and barrier-coating technology suppliers grounded qualitative findings in operational reality. Secondary validation drew from EPA effluent compliance filings, EU ETS emissions databases, FDA packaging integrity guidance documents, and Nordic biomass power purchase agreement disclosures. Bottom-up volume estimates from individual mill capacities and top-down demand segmentation from pharmaceutical production data were triangulated to constrain forecast variance.
Bottom-up modeling of chemical pulping capacity by mill and grade was cross-checked against top-down pharmaceutical packaging demand projections across the analysis window. Segmentation dimensions included wall configuration, end-use application, surface treatment grade, and pulping process energy intensity. CAGRs were derived from capacity utilization trends, regulatory compliance cost trajectories, and substitution elasticity estimates for PET blister alternatives. Forecast inputs incorporated EU carbon border adjustment implementation timing and state-level extended producer responsibility legislative momentum.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PET substitution in pediatric unit-dose applications or abrupt Nordic biomass supply disruptions. Projections reflect assumptions about FDA validation timeline stability and REACH coating chemistry continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Solar Paper Market
Paper Products
Solid Bleached Board Market
Paper Products
Global Molded Pulp Products Market
Paper Products
White Top Testliner Market
Paper Products
Reprographic Paper Market
Paper Products
Paper Based Laminates Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
Recovered Paper Market
Paper Products
Tissue Paper Market
Paper Products
Dissolving Pulp Market
Paper Products
Photographic Paper Market
Paper Products
Wood-Based Sheet Materials Market
Paper Products
Synthetic Paper Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Americas Stone Paper Market
Paper Products
Sawn Wood Market