
 Paper Doilies Market | 2026-2036
Paper Doilies Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Doilies Market Analytics
Indonesia is fragmenting as low-cost paper doily production disperses across Java-based mills and emerging Batam export zones. Maesindo Indonesia Ltd. leverages integrated pulp-to-lace manufacturing to control raw material costs for European private-label buyers. Garcia De Pou anchors Iberian distribution through dedicated hospitality supply chains. Monteverdi Srl specializes in artisanal embossed patterns that command premium positioning in Italian restaurant table settings.
Paper doilies are die-cut or lace-punched decorative mats, typically manufactured from bleached kraft pulp or greaseproof paper in weights ranging from 40 to 80 grams per square meter, designed to absorb moisture and prevent food contact with serving surfaces. Circular formats dominate commercial bakery and foodservice procurement due to standardized plate compatibility, while decorative variants capture margin pools in event planning and artisanal retail. Eco-friendly material grades now outpace conventional paper growth as EU and North American buyers enforce compostability mandates across hospitality supply contracts.
EU REACH and F-Gas Regulation frameworks govern chemical treatments in paper bleaching and coating processes, while FDA food-contact substance notifications shape US import acceptance criteria for greaseproof doily coatings. BIS certification requirements for imported paper goods influence Indian procurement patterns among hotel chains and catering operators. Stakeholders must monitor evolving compostability standards across multiple jurisdictions to avoid supply chain disqualification as buyer specifications tighten.
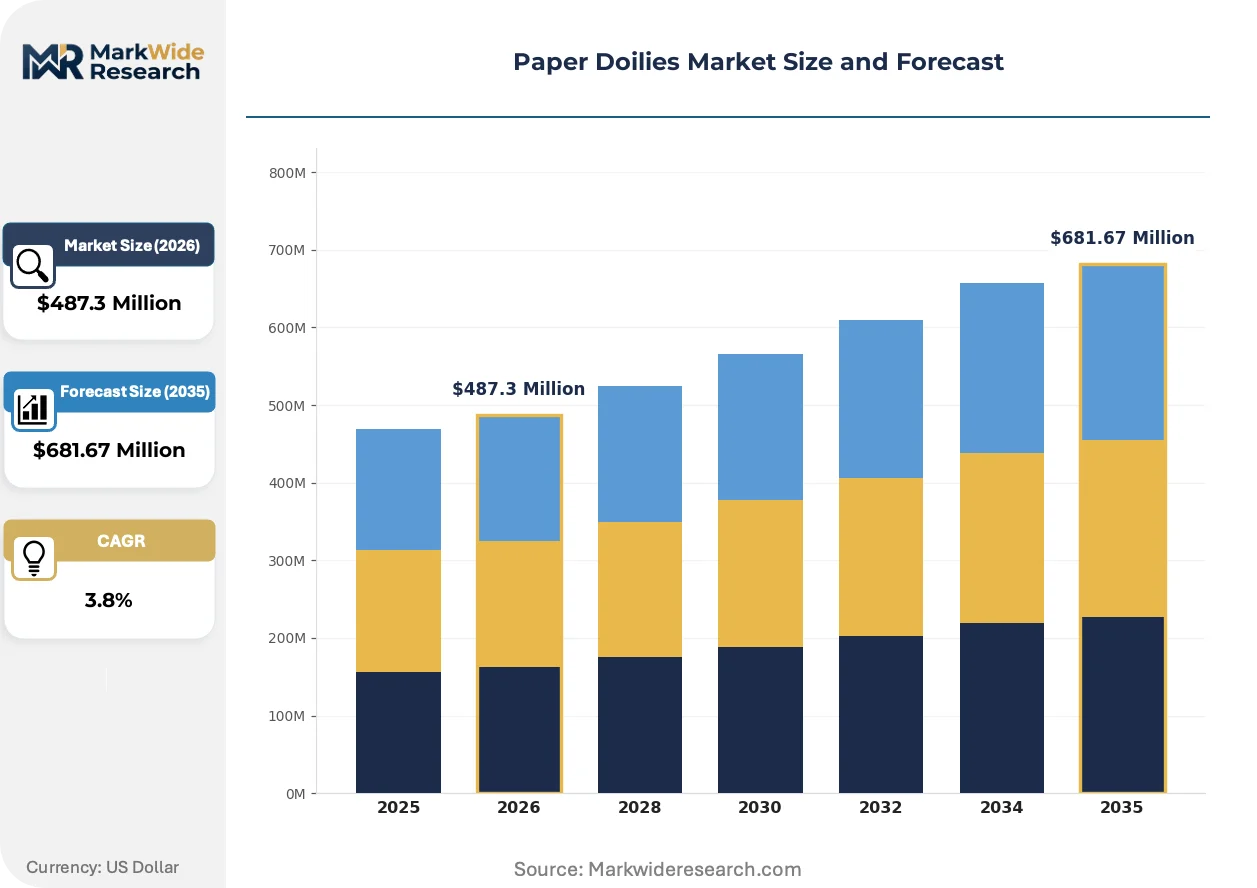
Market Dynamics
The EU Single-Use Plastics Directive is redirecting foodservice procurement toward paper substitutes, while Indonesian export mills consolidate pulp-to-lace manufacturing control over European private-label supply chains.
Growth Catalysts
- EU Single-Use Plastics Directive:The framework bans select plastic foodservice items, forcing bakery chains and catering operators across Germany, France, and Italy to specify compostable paper doilies for pastry displays and table settings.
- Greaseproof coating advancement:Food-grade fluorochemical-free barrier treatments now meet FDA food-contact substance notifications, enabling US import acceptance for high-moisture pastry applications previously served only by plastic liners.
- Japanese import demand:Tokyo and Osaka hospitality buyers specify artisanal embossed patterns for kaiseki and omakase presentations, creating premium export channels for specialized lace-punched formats.
Market Restraints
- Bleached kraft pulp volatility:Input costs fluctuate with Nordic pulp mill capacity and Indonesian acacia plantation harvest cycles, compressing margin pools for converters without backward integration into pulp sourcing.
- REACH chemical compliance:ECHA registration requirements for optical brighteners and sizing agents create documentation burdens that disqualify smaller Indonesian mills from EU certification.
- Silicone-coated parchment substitution:Heat-resistant bakery applications increasingly specify parchment liners over paper doilies for oven-to-table service, narrowing addressable market scope in commercial baking segments.
Strategic Opportunities
- Indian hotel chain procurement:BIS certification requirements for imported paper goods currently limit foreign supplier participation, creating first-mover advantage for mills achieving compliance ahead of domestic capacity expansion.
- Event planning channel innovation:Direct-to-planner e-commerce platforms bypass traditional hospitality distributors, enabling margin capture from wedding and corporate event coordinators seeking customized embossed branding.
- Compostability mandate alignment:EN 13432 and ASTM D6400 certification investments position suppliers for municipal procurement contracts in California, New York, and Washington state where food waste diversion laws accelerate compostable packaging adoption.
Industry Challenges
- Die-cut tooling capex intensity:Lace-punch pattern customization requires hardened steel cylinder investments exceeding $200,000 per design, constraining product line breadth for mid-scale converters.
- Multi-jurisdiction compostability certification:Divergent testing protocols across EU EN standards, US ASTM methods, and Australian AS 4736 create timeline delays averaging 14-18 months for unified global product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Doilies Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circular, Floral, Square, Decorative Material: Paper, Plastic, Eco-friendly, Biodegradable Application: Party Decor, Bakery, Arts & Crafts, Table Setting End User: Retailers, Wholesalers, Home Users, Restaurants |
| Companies Covered | Xiamen Lantianwei Imp. & Exp. Co., Ltd., Novacart Corporate, AVIS d.o.o., Mafcote Inc., Monteverdi Srl, Maesindo Indonesia Ltd., Gráficas Salaet, Graphic Management Specialty Products, Garcia De Pou, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Doilies Market Evolving Landscape
Water-based barrier coatings and digital die-cut pattern libraries are collapsing traditional manufacturing batch constraints, while procurement platforms consolidate specification authority among multi-national hospitality groups.
Fluorochemical-free greaseproof treatments are collapsing the performance gap between conventional paper doilies and plastic liners. North American bakery chains now specify these coatings for high-moisture pastry displays without sacrificing compostability credentials. The technology is collapsing minimum order quantity thresholds, enabling SKU proliferation for regional bakery formats.
REACH F-Gas Regulation frameworks now govern perfluorinated compound usage in paper sizing agents, forcing reformulation of legacy greaseproof treatments. ECHA enforcement actions against non-compliant imports have intensified third-party testing requirements at Rotterdam and Hamburg entry points. Italian and Spanish converters are responding by sourcing untreated base stock for in-house barrier application.
Buyer consolidation among multi-national hospitality groups is compressing supplier negotiation cycles and unbundling after-sales technical support. Procurement teams at major US and European hotel chains now mandate direct mill relationships, bypassing traditional paper distribution intermediaries. This pattern is most visible in contract catering segments where centralized purchasing dictates continental supply specifications.
Paper Doilies Market Segmentation
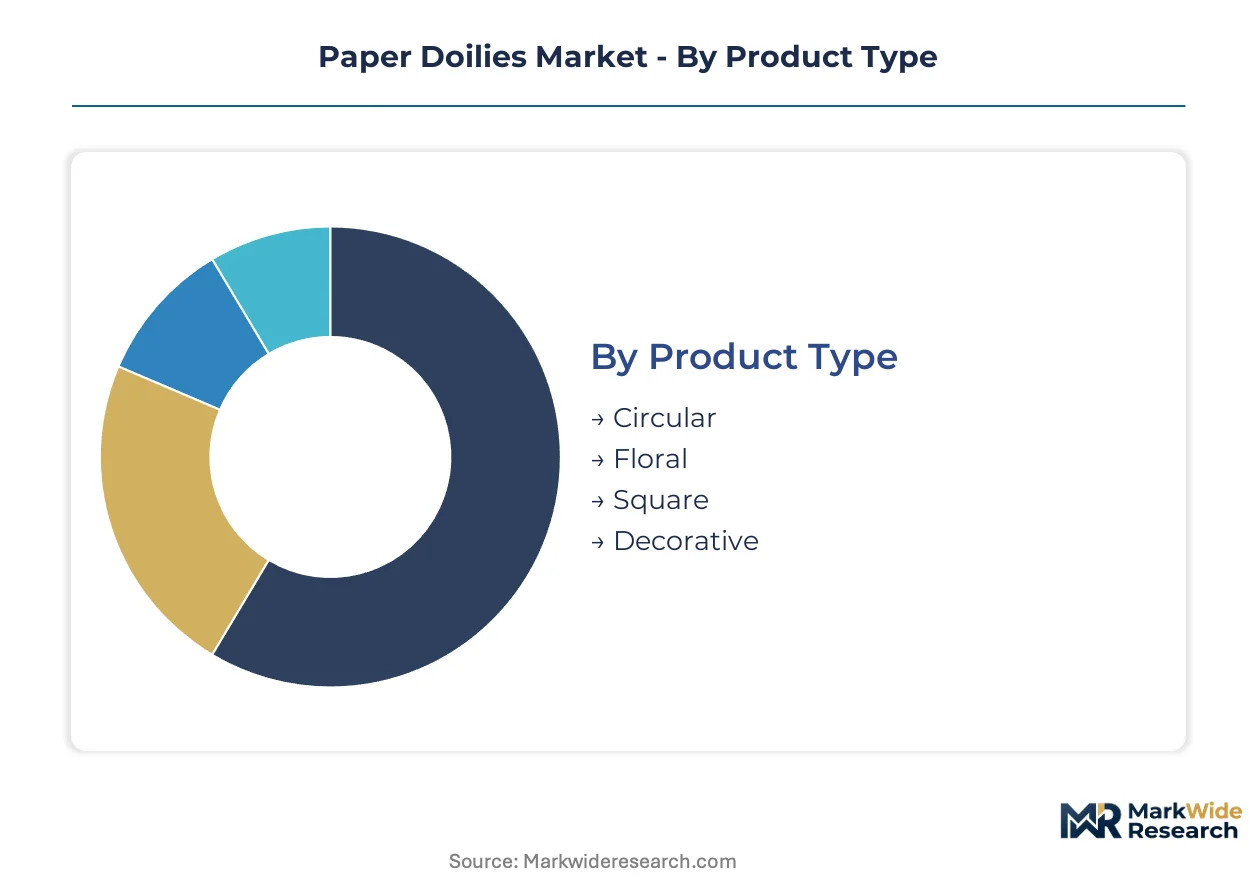
Paper doily procurement patterns diverge sharply across format specifications and buyer sophistication tiers. Segment-level profitability correlates with tooling amortization cycles and certification burden rather than raw material input costs alone.
Product Type:
Turnover velocity varies from standardized bakery procurement cycles to event-driven decorative spikes, with die-cut complexity determining replenishment frequency.
- Circular:Die-cut from bleached kraft pulp in diameters from 4 to 16 inches, circular formats absorb moisture across standardized plate footprints. North American bakery chains specify greaseproof coatings for pastry displays under FDA food-contact substance notifications, driving consistent replenishment schedules.
- Decorative:Artisanal lace-punched patterns command extended production lead times but capture premium positioning in Japanese kaiseki presentations and Italian restaurant table settings.
- Floral:Seasonal demand peaks align with wedding and spring event planning calendars in European hospitality markets.
- Square:Geometric formats serve rectangular serving platters in Iberian tapas establishments and Middle Eastern catering operations.
Circular formats anchor the volume base while decorative variants gain share at the steepest rate.
Material:
Cost stratification separates commodity pulp grades from certified compostable substrates that satisfy divergent regulatory thresholds.
- Eco-friendly:Unbleached kraft and bamboo pulp variants meeting EN 13432 compostability standards capture municipal procurement contracts in California and Washington state. EU Single-Use Plastics Directive enforcement accelerates specification shifts across German and French foodservice distributors.
- Paper:Conventional bleached kraft pulp at 40-80 GSM remains the baseline for high-volume bakery and foodservice applications.
- Biodegradable:Cellulose-based substrates with accelerated decomposition timelines serve Australian food waste diversion programs under AS 4736 certification requirements.
- Plastic:Polyethylene and polypropylene liners face declining hospitality procurement as REACH F-Gas Regulation restrictions tighten across European import channels.
Paper substrates dominate absolute volume while eco-friendly grades expand most quickly across contract catering segments.
Application:
Customer lifetime value spreads widest between impulse retail purchases and multi-year hospitality supply agreements with technical specification requirements.
- Bakery:Commercial baking operations specify fluorochemical-free greaseproof treatments for high-moisture pastry displays, with procurement centralized among multi-national chain purchasing departments.
- Table Setting:Italian and Spanish restaurants commission embossed patterns for premium positioning, with artisanal converters capturing margin pools through direct mill relationships.
- Party Decor:Event planning coordinators source customized branding through direct-to-planner e-commerce platforms, bypassing traditional hospitality distributors.
- Arts & Crafts:Educational and hobbyist channels demand lower GSM variants for scrapbooking and paper craft applications with minimal barrier performance requirements.
Bakery applications anchor the volume base while table setting specifications gain share at the steepest rate.
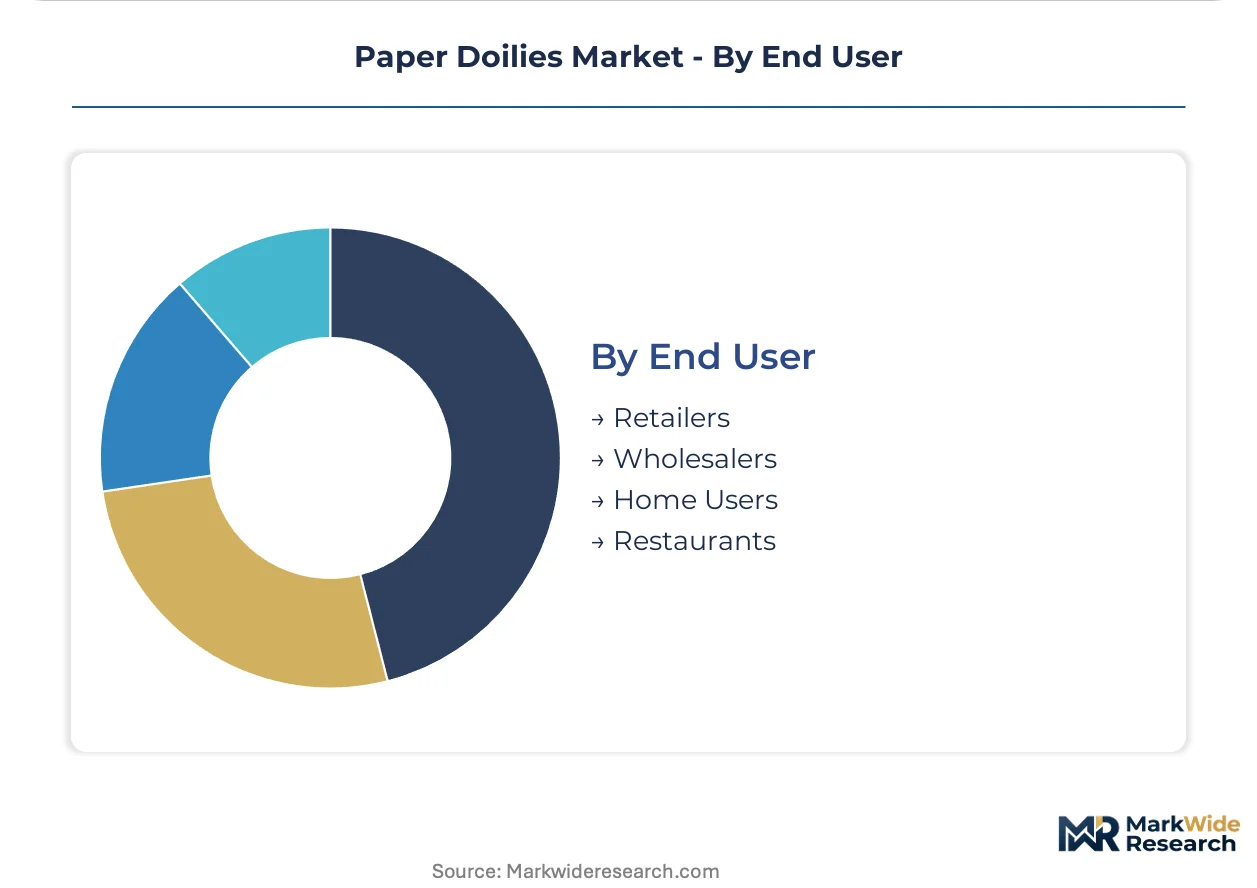
End User:
Procurement authority consolidation distinguishes centralized hospitality purchasing from fragmented household consumption patterns.
- Restaurants:Multi-national hotel chains mandate direct mill relationships and compostability certification, compressing supplier negotiation cycles across contract catering segments.
- Wholesalers:Iberian distribution networks anchored by Garcia De Pou consolidate specification authority for independent hospitality operators across Portugal and Spain.
- Retailers:Mass-market channels stock standardized circular formats for household table setting and casual entertaining occasions.
- Home Users:E-commerce platforms enable SKU proliferation for regional preferences, though individual order values remain below commercial procurement thresholds.
Restaurant procurement anchors the volume base while wholesaler consolidation gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH and F-Gas Regulation frameworks govern chemical treatments in paper doily manufacturing, while FDA food-contact substance notifications shape US import criteria for greaseproof coatings.
United States
North American bakery chains specify fluorochemical-free greaseproof doilies for pastry displays under FDA food-contact substance notifications. EPA enforcement of PFAS restrictions accelerates reformulation timelines for imported paper goods. Chicago and New York metro areas concentrate procurement authority among multi-national hospitality purchasing departments.
Germany
German foodservice distributors enforce EN 13432 compostability standards across contract catering segments. EU Single-Use Plastics Directive bans redirect procurement from plastic liners toward certified paper substitutes. The Rhine-Ruhr industrial corridor anchors conversion capacity for bleached kraft pulp imports from Nordic mills.
Indonesia
Export-oriented manufacturers serve European and Japanese hospitality buyers from Java-based integrated pulp-to-lace facilities. BIS certification requirements for Indian market entry drive compliance investments among Surabaya and Jakarta mill clusters. Batam export zones emerge as alternative production bases with proximity to Singapore logistics hubs.
Italy
Artisanal embossed patterns command premium positioning in restaurant table settings across Milan and Rome hospitality markets. ECHA registration requirements for optical brighteners disqualify smaller converters from EU-wide distribution. Tuscany and Emilia-Romagna host specialized lace-punch tooling workshops serving domestic and Japanese kaiseki presentation demand.
Japan
Tokyo and Osaka hospitality buyers specify specialized lace-punched formats for kaiseki and omakase presentations. METI guidelines on sustainable procurement accelerate compostable paper specification in luxury dining segments. The Kanto region concentrates import distribution channels for Indonesian and European supply sources.
Paper Doilies Market Competitive Landscape
Integrated pulp-to-lace manufacturers and specialized decorative converters split the market along cost-versus-premium vectors. Tiering reflects backward integration depth and pattern customization capability rather than scale alone. Two archetypes dominate: vertically integrated Southeast Asian mills controlling raw material costs, and European artisanal specialists capturing margin through design differentiation. Capacity expansion and direct mill relationship cultivation with multi-national hospitality chains represent the dominant competitive moves.
Among Indonesian integrated manufacturers, Maesindo Indonesia Ltd. exemplifies the pulp-captive archetype serving European private-label demand. Within European specialist tiers, Monteverdi Srl and Garcia De Pou occupy positions anchored in artisanal embossing and Iberian distribution consolidation respectively. Xiamen Lantianwei Imp. & Exp. Co., Ltd. represents the Chinese export-trading intermediary archetype facilitating cross-border procurement for mid-scale hospitality operators.
| Leading Market Players |
|---|
| Xiamen Lantianwei Imp. & Exp. Co., Ltd. |
| Novacart Corporate |
| AVIS d.o.o. |
| Mafcote Inc. |
| Monteverdi Srl |
| Maesindo Indonesia Ltd. |
| Gráficas Salaet |
| Graphic Management Specialty Products |
| Garcia De Pou |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp freight corridors govern landed cost spreads between Indonesian mill gates and European distribution hubs, compressing margin pools for converters lacking captive pulp supply while enabling three-tier pricing stratification across premium artisanal, standard foodservice, and economy private-label tiers.
Pricing Analysis
Price spreads between Java-based integrated mills and European artisanal converters reach multiples of base material costs. Pricing stratifies across premium embossed patterns, standard greaseproof grades, and economy uncoated variants. Cost compression in economy tiers intensifies as Nordic pulp mill capacity constraints elevate bleached kraft input costs. Mass-market bakery chains exhibit highest price sensitivity; Japanese kaiseki hospitality buyers show lowest sensitivity to pattern premiums.
Supply Chain Analysis
Tariff exposure between Indonesia and EU member states dominates supply chain risk calculus for private-label distributors. Manufacturing concentrates in Indonesia, Italy, and Germany. Raw material flows draw from Nordic pulp mills, Indonesian acacia plantations, and Chinese coating chemical suppliers. Single-source vulnerability persists in specialized lace-punch tooling workshops. Distribution runs through consolidated Iberian hospitality supply networks and direct mill relationships with multi-national hotel chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
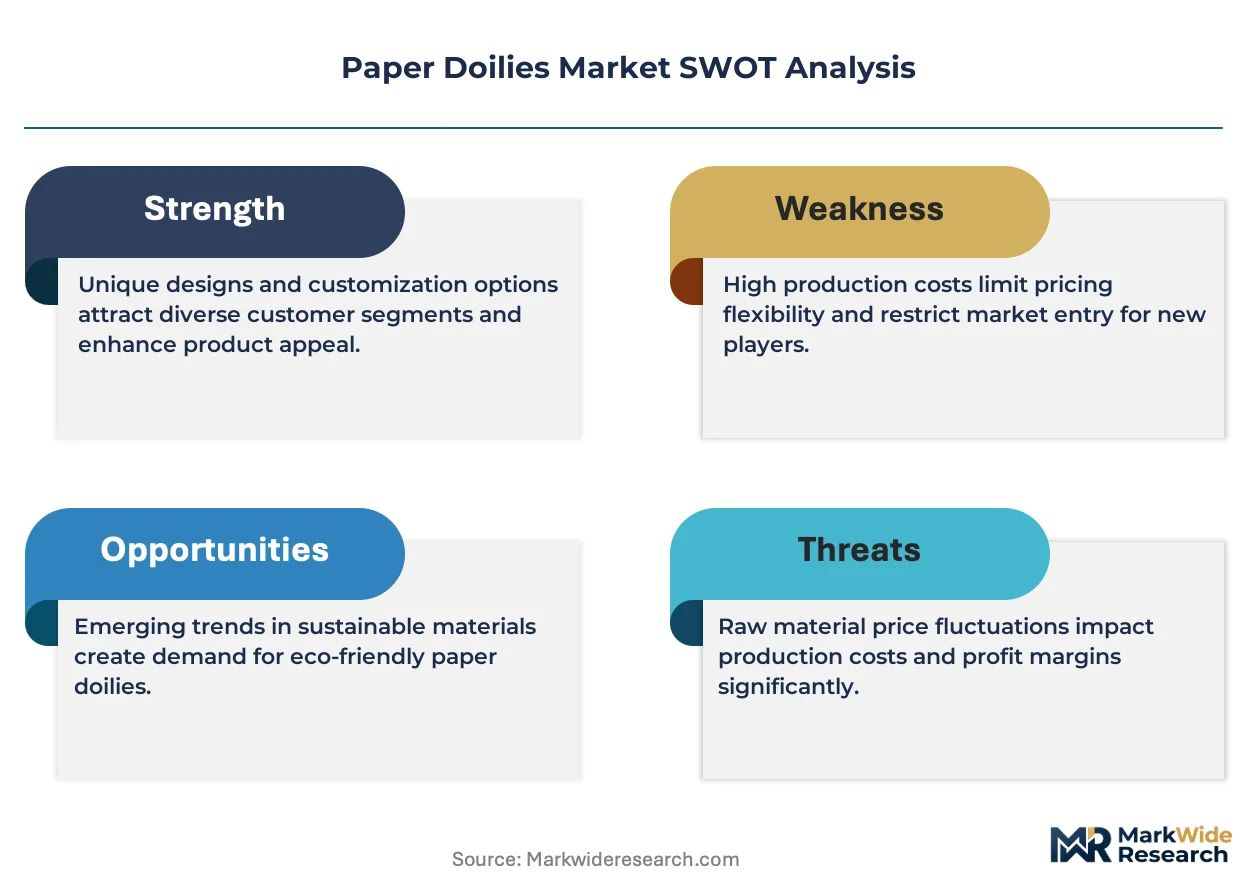
Analyst Recommendations
Technical specification support and compostability certification services expand faster than base product turnover, creating attach-rate opportunities for mills investing in compliance documentation and buyer education.
For Market Incumbents: Pre-empt silicone-coated parchment substitution in heat-resistant bakery segments by advancing fluorochemical-free barrier R&D. Secure EN 13432 and ASTM D6400 certifications ahead of municipal procurement mandate waves. Deepen backward integration into pulp sourcing to defend margin position against Nordic input cost volatility.
For New Entrants and Emerging Players: Establish a beachhead in Indian hotel chain procurement by achieving BIS certification ahead of domestic capacity expansion. Target event planning e-commerce channels with digital die-cut pattern libraries enabling customized embossed branding. Deploy direct-to-planner go-to-market models bypassing traditional hospitality distribution markups.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated pulp-to-lace manufacturers with pattern customization capability over pure trading intermediaries. Long-term viability hinges on compostability mandate alignment across multiple jurisdictions. Monitor ECHA enforcement intensity at Rotterdam and Hamburg entry points as inflection indicator for compliance-cost barrier elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Sourcing | Captive acacia plantation control insulates Maesindo Indonesia Ltd. from Nordic pulp price volatility. |
| Compostability Certification Investment | EN 13432 and ASTM D6400 credentials unlock California and New York municipal procurement contracts. |
| Direct Mill Relationship Cultivation | Bypassing Garcia De Pou distribution layers captures margin from multi-national hotel chain central purchasing. |
| Digital Die-Cut Pattern Library Development | Water-based barrier coating compatibility enables SKU proliferation for regional bakery format customization. |
| Specialized Lace-Punch Tooling Acquisition | Hardened steel cylinder control secures artisanal embossed pattern capability for Japanese kaiseki export channels. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with paper mill operations directors, hospitality procurement managers, and EU regulatory compliance officers; and secondary validation through customs trade databases, ECHA registration filings, FDA food-contact substance notifications, and Nordic pulp mill capacity reports. Bottom-up volume modeling triangulated against top-down category spending estimates.
Forecast inputs span product format circularity, material compostability tier, application moisture-barrier requirements, and end-user procurement centralization patterns across the projection horizon. Segment-level CAGRs derive from elasticity-adjusted demand curves incorporating EU Single-Use Plastics Directive enforcement timelines and Japanese import specification evolution.
Stress conditions across pulp input cost bands, REACH chemical compliance stringency, and parchment liner substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Global Cellulose Sponge Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Sanitary Paper Products Market
Paper Products
Global Kraft Paper Market
Paper Products
BPA Free Thermal Paper Market
Paper Products
Europe Paper Market
Paper Products
Bleached Softwood Kraft Pulp Market
Paper Products
Paper Pigment Market
Paper Products
Cheque Paper Market
Paper Products
Acrylic Paper Market
Paper Products
Pigmented Paper Market
Paper Products
Organic Tissue Paper Market
Paper Products
Synthetic Paper Market
Paper Products
Canada Honeycomb Paper Market
Paper Products
Global Wood Pulp Market
Paper Products
Recovered Paper Market