
 Paper Glass Market | 2026-2036
Paper Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Glass Market Analytics
EU Single-Use Plastics Directive enforcement is hardening the cost-of-entry calculus for conventional plastic cup manufacturers across Europe. Dart Container Corporation leverages its North American manufacturing scale to anchor supply contracts with national quick-service chains. Huhtamäki Oyj differentiates through fiber-molding expertise and coated-barrier technology leadership in cold-beverage applications. Graphic Packaging International competes by extending its integrated paperboard supply chain into converting operations.
Paper glass denotes a rigid, cylindrical beverage vessel formed from wood-fiber pulp, typically laminated with polyethylene or polylactic acid barriers to resist liquid penetration, with wall calipers ranging from 0.4 mm to 1.2 mm depending on thermal requirements. The product serves commercial and institutional food service as a disposable, single-use alternative to conventional glass or plastic drinkware. Biodegradable and compostable product types command premium positioning in European food service channels where municipal organics collection mandates create pull-through. Coated variants dominate volume in North American takeaway applications where extended shelf stability and hot-fill compatibility anchor procurement specifications. Food packaging and beverage applications concentrate margin pools, while events and parties segments exhibit higher price sensitivity and lower supplier switching costs.
FDA food-contact substance regulations govern barrier coating approvals in the United States, while EFSA and REACH frameworks in Europe restrict certain perfluorinated chemistries and mandate migration testing for hot-fill paper vessels. BIS certification requirements in India and GB standards in China impose additional compositional and hygiene benchmarks that shape export market access for multinational converters. Stakeholders must monitor evolving extended producer responsibility schemes and deposit-return pilots, as these mechanisms will determine whether paper glass achieves unit-economics parity with reusable alternatives in regulated channels.
Market Dynamics
The EU Single-Use Plastics Directive is hardening substitution economics across European food service channels, forcing converters to reconfigure coating chemistries and compostability certifications at scale.
Growth Catalysts
- EU Directive Enforcement:The Single-Use Plastics Directive bans select plastic vessels across member states, creating immediate displacement demand for fiber-based alternatives in quick-service and institutional channels.
- German Composting Infrastructure:Municipal organics collection mandates in Germany generate pull-through for certified compostable paper glass variants, anchoring premium positioning in European food service.
- Polyethylene Barrier Advances:Enhanced PE and PLA lamination technologies now deliver hot-fill compatibility above 85°C, expanding paper glass penetration into coffee and tea applications previously reserved for foam or plastic.
Market Restraints
- Pulp Input Volatility:Northern European softwood pulp prices fluctuate with energy costs and forestry harvest cycles, compressing converter margins during supply tightness.
- Coating Chemistry Constraints:EFSA and REACH restrictions on perfluorinated barriers limit conventional grease-resistant formulations, forcing costly reformulation cycles for European market access.
- Reusable Vessel Competition:Deposit-return schemes for stainless steel and glass alternatives in German and French food service channels threaten unit-economics parity for single-use fiber vessels.
Strategic Opportunities
- Indian State-Level Bans:Maharashtra's prohibition on plastic disposables creates immediate white space for paper glass converters with BIS certification and local converting partnerships.
- Cold-Beverage Barrier Convergence:Integration of bio-based PLA with conventional PE coatings enables premium positioning in juice and smoothie channels without full compostability infrastructure.
- Extended Producer Responsibility:Emerging EPR schemes in France and Italy will favor converters with verified end-of-life pathways, rewarding early certification investments.
Industry Challenges
- Migration Testing Bottlenecks:EFSA hot-fill migration protocols require 12-18 month certification timelines, delaying product launches for reformulated barrier chemistries.
- Composting Infrastructure Gaps:Industrial composting facility scarcity outside Germany and the Netherlands limits addressable market for certified compostable variants, forcing geographic cherry-picking.
- Coating Equipment Retrofit Costs:Conventional cup-forming lines require substantial capital outlay to handle next-generation bio-based barriers, straining mid-scale converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Glass Market |
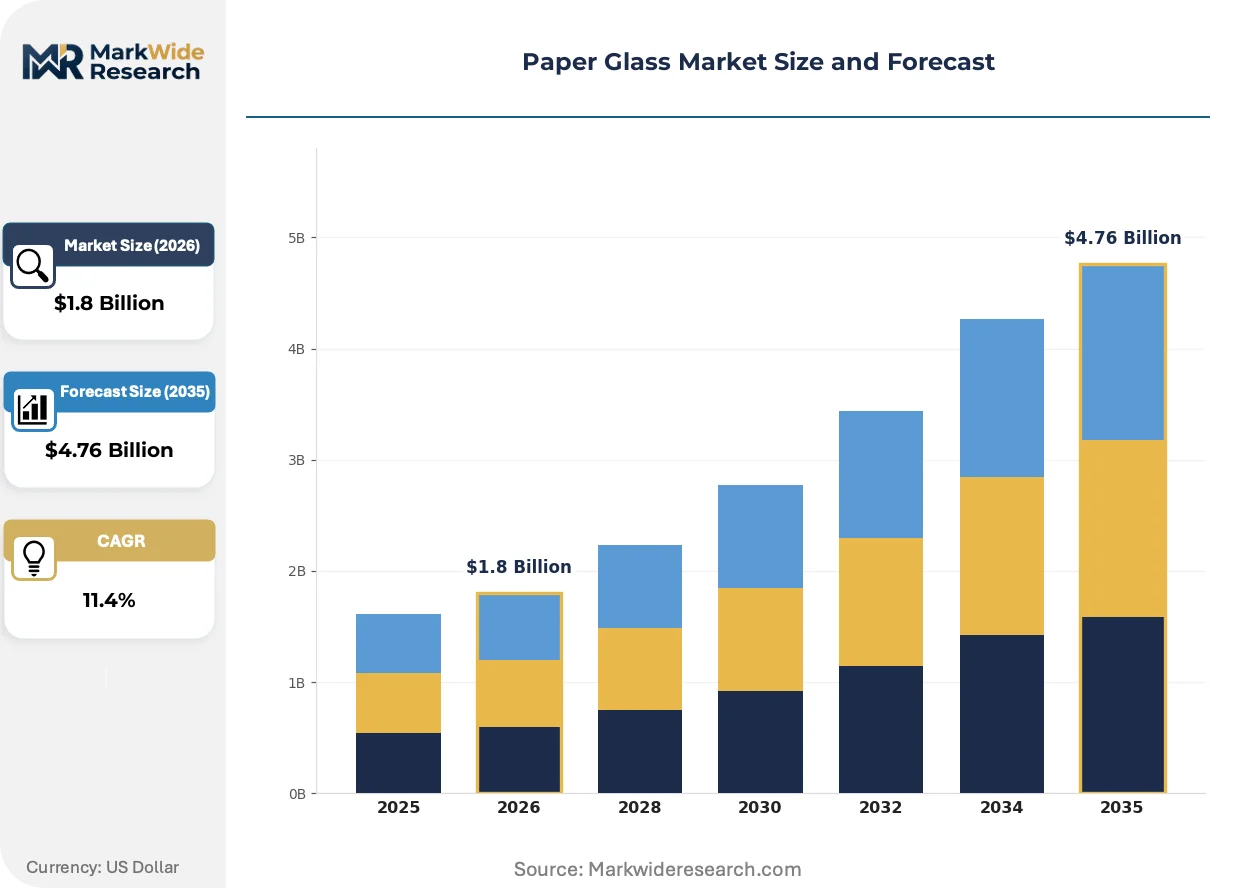
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
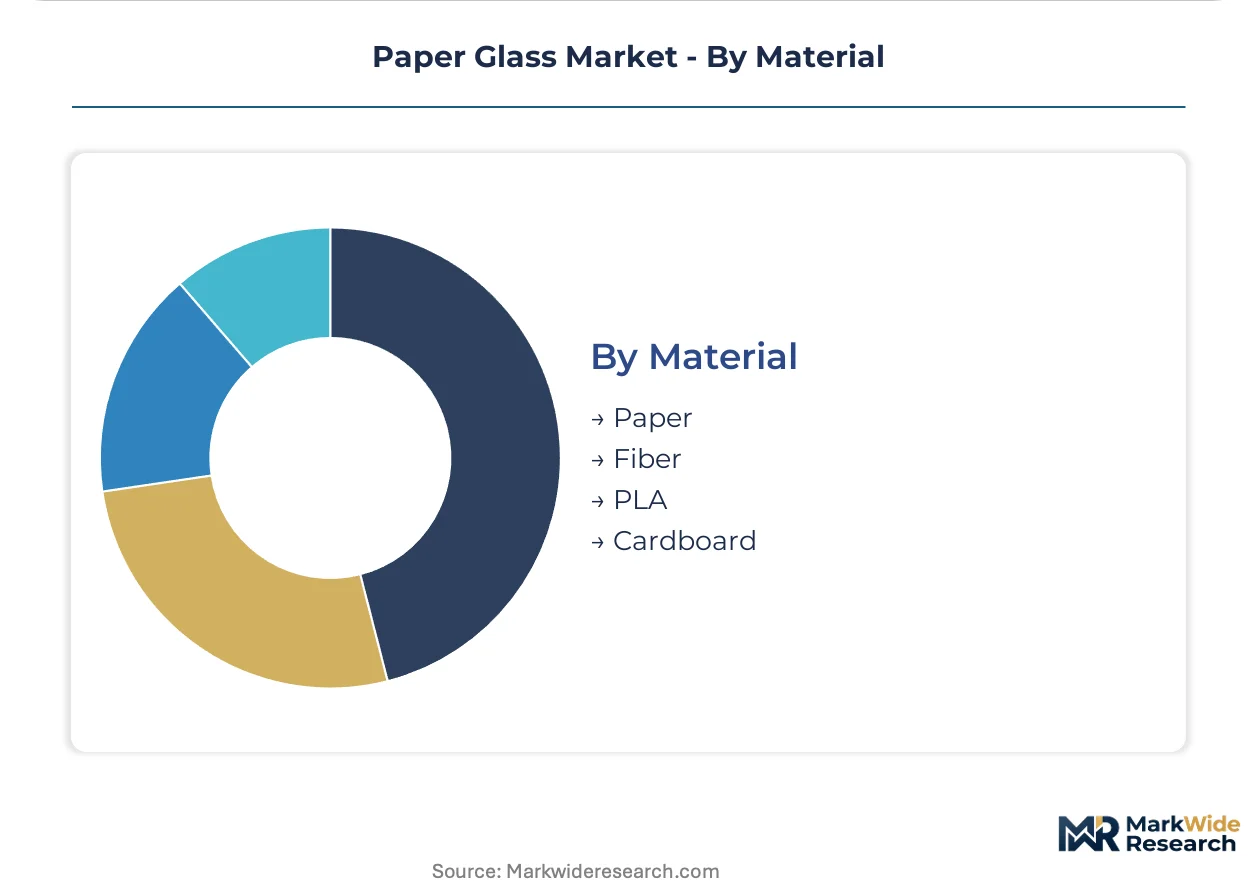
| Segmentation | Product Type: Biodegradable, Compostable, Recyclable, Coated End User: Food Service, Retail, Events, Catering Application: Beverages, Food Packaging, Takeaway, Parties Material: Paper, Fiber, PLA, Cardboard |
| Companies Covered | Dart Container Corporation, Graphic Packaging International, Georgia-Pacific Consumer Products, Huhtamäki Oyj, Pactiv Evergreen, International Paper, Bender Limited, Go-Pak Group, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Glass Market Evolving Landscape
Barrier coating chemistry and forming automation are converging to reshape competitive positioning, while regulatory fragmentation across jurisdictions forces parallel certification strategies.
High-speed fiber-molding lines with integrated barrier deposition are automating quality consistency and throughput rates for coated paper glass production. Quick-service chains in Germany and France are adopting these systems to secure supply volumes under tightening EPR timelines. The technology is automating labor cost structures and defect-rate compression that previously favored Asian converters.
REACH restrictions on perfluorinated substances are eliminating legacy grease-resistant chemistries from European food-contact applications. Converters must migrate to bio-based or mineral oil-free barrier systems, extending R&D cycles and supplier qualification periods. Cold-beverage applications with shorter contact times face lighter compliance burdens than hot-fill coffee vessels.
Buyer consolidation among national quick-service chains is compressing supplier switching cycles and unbundling after-sales technical support from base supply contracts. Chains now demand direct coating formulation transparency and end-of-life certification documentation. This pattern concentrates most intensely in German and French procurement desks with dedicated sustainability compliance functions.
Paper Glass Market Segmentation
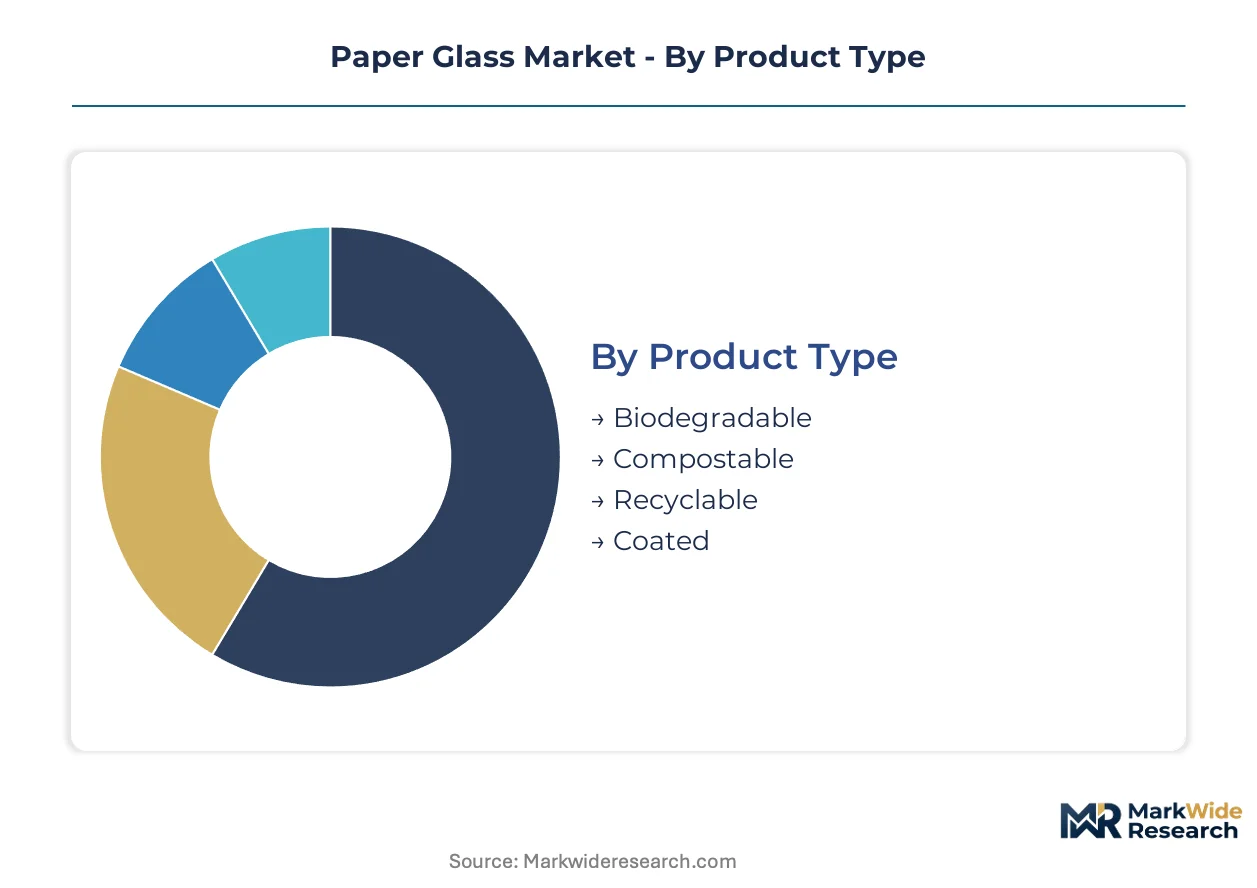
Paper glass procurement decisions pivot on disposal infrastructure availability, thermal performance requirements, and end-use channel specifications. Segmentation reveals how coating chemistry and material substrate choices map to distinct margin pools and regulatory compliance burdens across food service, retail, and institutional channels.
Product Type:
Buyers differentiate primarily by end-of-life pathway certification and the composting infrastructure available in their operating geographies.
- Coated:Polyethylene or polylactic acid laminated fiber vessels deliver hot-fill compatibility above 85°C, anchoring volume in North American quick-service takeaway channels where extended shelf stability governs procurement. Quick-service chains in the United States prioritize these variants for coffee and tea applications under FDA food-contact substance regulations.
- Compostable:Certified fiber-molded vessels with bio-based barriers command premium positioning in German and French food service channels where municipal organics collection mandates create pull-through. EFSA and REACH compliance requirements for hot-fill migration testing extend supplier qualification timelines.
- Biodegradable:Unlaminated or mineral-oil-free barrier formulations degrade in ambient environments without industrial composting infrastructure, serving events and outdoor catering segments in regions with limited waste processing capacity.
- Recyclable:Fiber-pulp vessels designed for standard paperboard recycling streams compete in retail and institutional channels where single-stream collection predominates, though polyethylene contamination limits actual recovery rates in many jurisdictions.
Coated variants lead volumes today; compostable alternatives are gaining share fastest in European channels with verified end-of-life infrastructure.
End User:
Channel concentration and contract scale determine supplier switching costs and technical service intensity across buyer categories.
- Food Service:National quick-service chains and institutional cafeterias drive specification-setting for barrier performance, thermal tolerance, and direct coating formulation transparency, with procurement desks in Germany and France maintaining dedicated sustainability compliance functions.
- Events:Outdoor festivals and temporary food service operations exhibit acute price sensitivity and minimal supplier loyalty, favoring lowest-unit-cost biodegradable variants regardless of certification status.
- Retail:Supermarket and convenience store channels prioritize shelf-stable inventory with extended dating, aligning with coated paper glass specifications and standardized case-pack configurations.
- Catering:Contract caterers serving corporate and institutional clients balance presentation quality against disposal logistics, often specifying compostable variants for client sustainability reporting requirements.
Food Service commands the largest revenue pool; Events shows the steepest price compression and highest supplier churn.
Application:
Temperature exposure duration and liquid contact time shape barrier chemistry selection and regulatory testing burdens.
- Beverages:Hot-fill coffee and tea applications demand polyethylene or advanced PLA barriers with migration-tested chemistries under EFSA protocols, compressing margins through extended certification timelines.
- Food Packaging:Dry and semi-moist food containment allows thinner wall calipers and lighter barrier specifications, reducing pulp input costs per unit.
- Takeaway:Transport durability and leak resistance anchor procurement criteria for delivery-aggregator partnerships, with quick-service chains specifying coated variants for extended holding periods.
- Parties:Single-use social gathering applications tolerate lower performance thresholds, enabling economy-tier biodegradable and uncoated fiber products.
Beverages anchors premium pricing; Takeaway is expanding most quickly through delivery-channel proliferation.
Material:
Substrate selection determines forming equipment compatibility, barrier adhesion properties, and end-of-life degradation pathways.
- Paper:Bleached kraft pulp forms the dominant substrate for coated and recyclable variants, with Northern European softwood supply concentration exposing converters to energy-cost-driven input volatility.
- Fiber:Molded fiber technologies enable complex rim and base geometries for beverage applications, integrating with high-speed barrier deposition systems automating quality consistency.
- PLA:Polylactic acid serves as both standalone substrate and coating modifier, delivering bio-based content claims for European EPR scheme compliance despite industrial composting infrastructure gaps outside Germany and the Netherlands.
- Cardboard:Heavier caliper paperboard substrates support rigid-wall food packaging applications with structural load requirements exceeding cylindrical beverage vessel specifications.
Paper dominates substrate volumes; PLA is climbing the fastest as converters reformulate for REACH perfluorinated substance restrictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale paper glass production originated in post-war Europe, where Swedish and Finnish pulp conglomerates pioneered fiber-molding technologies for disposable food service. German municipal composting infrastructure subsequently validated the end-of-life economics that now anchor premium positioning across the continent.
Germany
Quick-service chains and institutional cafeterias in Bavaria and North Rhine-Westphalia drive specification-setting for compostable variants. The EU Single-Use Plastics Directive enforcement through national transposition laws mandates fiber-based alternatives in federal food service procurement. Berlin-Brandenburg hosts converter clusters serving pan-European quick-service contracts with certified end-of-life documentation.
United States
National quick-service chains anchor volume demand for polyethylene-laminated hot-fill vessels across the Southeast and Midwest. FDA food-contact substance regulations govern barrier coating approvals, with migration testing protocols shaping supplier qualification timelines. Georgia-Pacific operates integrated pulp-to-converting capacity in the Southern timber belt.
India
Maharashtra's state-level prohibition on plastic disposables creates immediate displacement demand for BIS-certified paper glass in Mumbai-Pune food service corridors. The Bureau of Indian Standards imposes compositional and hygiene benchmarks that filter import competition. Gujarat's chemical processing clusters supply barrier coating intermediates to domestic converters.
France
Deposit-return pilots for reusable alternatives in Parisian food service channels pressure single-use fiber vessel economics. EFSA hot-fill migration protocols extend certification timelines for reformulated barrier chemistries. The Île-de-France region concentrates procurement desks with dedicated sustainability compliance functions demanding coating formulation transparency.
China
Export-oriented converting capacity in the Yangtze River Delta serves North American and European private-label contracts. GB standards impose additional compositional benchmarks shaping market access for multinational converters. Zhejiang and Jiangsu provinces host forming equipment manufacturers automating barrier deposition quality consistency.
Paper Glass Market Competitive Landscape
The competitive structure tilts toward integrated paperboard producers with captive pulp supply and barrier coating capabilities. Tier-one positions concentrate among North American and Nordic conglomerates with multi-continent converting footprints. Mid-scale specialists compete through regional certification depth and quick-service technical service intensity. Dominant competitive moves include backward integration into pulp supply and strategic partnerships with bio-based barrier technology licensors.
Among North American conglomerates, Dart Container Corporation and Pactiv Evergreen exemplify scale-driven archetypes with national quick-service supply contracts. Georgia-Pacific Consumer Products anchors a pulp-integrated position through captive softwood supply. Huhtamäki Oyj represents Nordic fiber-molding expertise with European compostability certification leadership. International Paper and Stora Enso occupy integrated paperboard-to-converting positions spanning industrial and food service channels.
| Leading Market Players |
|---|
| Dart Container Corporation |
| Graphic Packaging International |
| Georgia-Pacific Consumer Products |
| Huhtamäki Oyj |
| Pactiv Evergreen |
| International Paper |
| Bender Limited |
| Go-Pak Group |
| Stora Enso |
| Others |
Value Network & Pricing Analysis
High-speed fiber-molding automation with integrated barrier deposition is compressing unit economics while concentrating production among converters with capital scale to retrofit forming lines. This technological shift simultaneously raises fixed-cost barriers for mid-tier competitors and anchors pricing power among Nordic and North American pulp-integrated conglomerates serving quick-service chains.
Pricing Analysis
After-sales technical support unbundling from base supply contracts is reshaping how quick-service chains evaluate total cost of ownership. Three-tier pricing structure across premium, standard, and economy levels separates compostable-certified variants in German channels from polyethylene-laminated takeaway vessels in North American markets. Price differentiation hinges on EFSA migration certification timelines and volume-scale procurement commitments. Cost compression in standard-tier coated variants is intensifying because buyer consolidation among national chains squeezes converter margins. Events and outdoor catering segments exhibit acute price sensitivity, while institutional food service with dedicated sustainability compliance functions tolerates premium positioning.
Supply Chain Analysis
Direct-to-converter channels handle hyperscale demand from national quick-service chains, while distributor networks serve regional food service operators and event suppliers. Pulp supply concentrates in Sweden, Finland, and the United States, with Northern European softwood harvest cycles exposing converters to energy-cost-driven input volatility. Raw material dependencies center on bleached kraft pulp, polyethylene barrier resins, and polylactic acid biopolymers. Single-source vulnerability in coating chemistry supply chains intensifies as REACH restrictions force reformulation cycles. Distribution runs through integrated paperboard producers with captive converting capacity and specialized fiber-molding equipment manufacturers in Germany and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paper glass market functions as a stable compounder, with regulatory displacement of single-use plastics anchoring steady demand expansion across food service channels.
For Market Incumbents: To counter coating chemistry constraints under REACH and EFSA protocols, incumbents should deepen backward integration into pulp supply and accelerate bio-based barrier R&D partnerships. Captive softwood supply in Nordic operations insulates margin structures from input volatility. Certification investment in industrial compostability pathways secures premium positioning in German procurement channels. For New Entrants and Emerging Players: PLA-PE hybrid barrier technology offers entry traction into Indian state-level markets where BIS certification filters import competition. Maharashtra's plastic prohibition creates immediate white space for converters with local manufacturing partnerships. Cold-beverage applications with lighter migration testing burdens represent the most penetrable segment for qualification timeline compression. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale converters with regional certification depth but limited barrier technology licensing. The five-to-ten-year viability thesis rests on extended producer responsibility scheme proliferation favoring verified end-of-life pathways. Acquisition targets should demonstrate compostability certification infrastructure and quick-service technical service intensity. The signal to watch is deposit-return pilot expansion in French and German food service channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Georgia-Pacific's captive Southern timber belt operations demonstrate margin insulation from Northern European softwood price cycles. |
| Bio-Based Barrier R&D Partnership | Huhtamäki's PLA coating expertise anchors premium positioning in EFSA-compliant European food service channels. |
| Industrial Compostability Certification | Berlin-Brandenburg converter clusters leverage German municipal organics infrastructure for verified end-of-life documentation. |
| High-Speed Forming Line Automation | Quick-service chains in Bavaria adopt automated barrier deposition systems to secure supply volumes under tightening EPR timelines. |
| Regional Converting Partnership | Gujarat chemical clusters supply BIS-certified coating intermediates to domestic converters serving Maharashtra's plastic prohibition. |
Research Methodology
Direct dialogue with converter operations managers, quick-service chain procurement directors, barrier coating technology suppliers, and municipal waste processing officials grounded qualitative insights. Secondary validation drew from FDA food-contact substance filings, EFSA migration test protocols, BIS certification registries, and trade customs data for pulp and barrier resin flows. Bottom-up demand modeling triangulated against top-down market sizing across coating chemistry and end-use channel dimensions.
Bottom-up volume builds aggregated individual segment trajectories while top-down cross-checks anchored macroeconomic assumptions across the projection horizon. Segmentation dimensions modeled include product type certification tier, thermal performance specification, end-use channel concentration, and regional regulatory framework cluster. CAGRs derived from trend extrapolation of substitution rates, infrastructure deployment timelines, and buyer consolidation patterns. Forecast inputs incorporated EU Single-Use Plastics Directive enforcement schedules and Indian state-level ban proliferation curves.
The model holds under steady regulatory enforcement and composting infrastructure expansion; deviation in coating chemistry approval timelines or deposit-return scheme acceleration would shift volume trajectories. Forecasts reflect documented assumptions regarding barrier technology adoption rates and pulp input cost normalization. Periodic stress-testing of base assumptions is recommended given migration testing bottleneck variability and extended producer responsibility scheme design uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
North America Decor Paper Market
Paper Products
Billing Paper Market
Paper Products
Chemical Cellulose Market
Paper Products
Thermal Paper Market
Paper Products
Heat Transfer Paper Market
Paper Products
Semi Chemical Wood Pulp Market
Paper Products
Canada Honeycomb Paper Market
Paper Products
Overlay Paper Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
Liquid Paperboard Market
Paper Products
Global Paper Chemical Market
Paper Products
Glassine Paper Market
Paper Products
Reprographic Paper Market
Paper Products
High-Speed Production Inkjet Printer Paper Market
Paper Products
Global Electrical Insulation Paper Market