
 Base Paper Market | 2026-2036
Base Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Base Paper Market Outlook
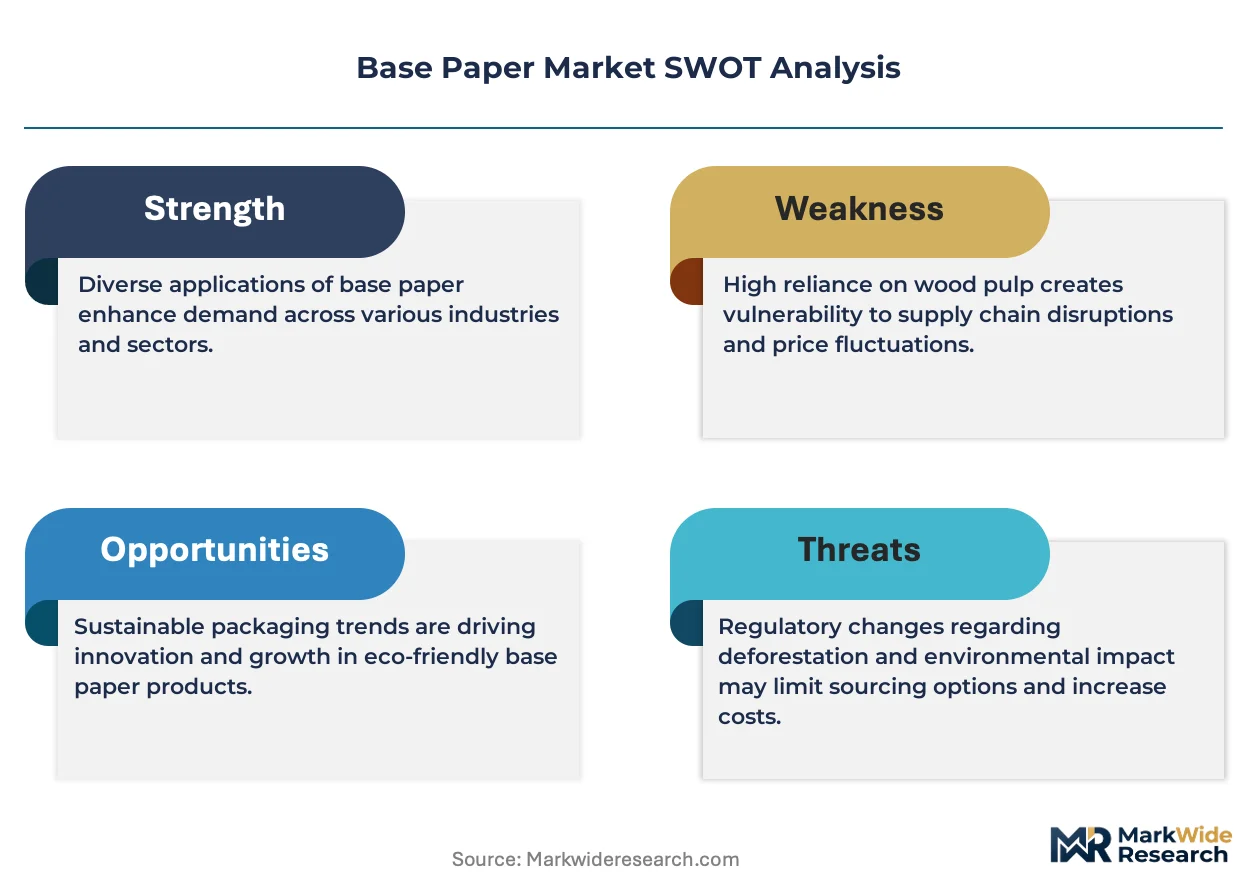
Digital printing integration is reshaping how base paper grades are specified, with shorter run lengths demanding faster ink-setting surfaces and tighter caliper tolerances. International Paper leverages its North American pulp network to sustain cost-advantaged kraft linerboard output. Stora Enso Oyj anchors Nordic softwood fiber supply for premium packaging grades across European consumer goods channels. Ahlstrom-Munksjö specializes in technical base papers where synthetic fiber blends command durable filtration and medical wrapping applications.
Base paper constitutes the unfinished substrate—typically 40–350 gsm in basis weight, composed of bleached or unbleached cellulose fibers with optional filler loading—subsequently converted into packaging, printing, or specialty formats through coating, calendering, or lamination processes. Uncoated paper dominates volume flows into office and educational stationery where opacity and printability standards remain consistent. Specialty paper captures expanding margin pools as industrial users specify thermal, greaseproof, and release liners for food service and adhesive applications. Coated paper retains structural importance in high-fidelity publishing despite secular pressure from digital media substitution.
EPA effluent guidelines constrain US mill discharge parameters, while REACH and the EU Green Deal mandate recyclability verification and carbon footprint disclosure across European value chains. India's BIS grading protocols for packaging paper enforce burst strength and ring crush specifications that filter subscale domestic producers from institutional procurement channels. Stakeholders must monitor how divergent regulatory stringency between OECD and emerging markets reshapes capital allocation toward integrated pulp-and-paper complexes versus merchant converters.
Market Dynamics
The EU Green Deal's recyclability mandates are compressing virgin fiber demand while redirecting capital toward recycled-content processing infrastructure across European packaging supply chains.
Growth Catalysts
- E-commerce corrugated specifications:Consumer goods manufacturers in Germany, India, and Brazil now specify higher basis weights for protective shipping substrates.
- REACH carbon disclosure:European value chains now require verified carbon footprint documentation, accelerating mill investment in emissions monitoring systems.
- Pharmaceutical barrier demand:Blister pack converters are specifying specialty base papers with oxygen and moisture resistance to replace plastic lamination layers.
Market Restraints
- Softwood pulp price volatility:Nordic and North American fiber supply disruptions transmit directly into kraft linerboard cost structures.
- Integrated mill concentration:Merchant converters face sourcing vulnerability as production consolidates around captive pulp-and-paper complexes.
- Digital media substitution:Coated publication grades confront accelerating demand erosion from screen-based content consumption.
Strategic Opportunities
- India BIS compliance gap:Domestic mills meeting burst strength and ring crush specifications can capture institutional procurement channels filtering subscale competitors.
- Synthetic fiber blending:Technical base papers incorporating durable fiber mixes address filtration and medical wrapping applications with premium pricing potential.
- Digital print surface engineering:Faster ink-setting substrates with tighter caliper tolerances capture shorter-run packaging workflows.
Industry Challenges
- Effluent compliance capex:EPA discharge parameter constraints require US mills to fund wastewater treatment upgrades without guaranteed fiber cost recovery.
- Cross-border certification latency:Divergent OECD versus emerging market regulatory stringency creates product qualification delays for multi-territory suppliers.
- Legacy calendering integration:Existing supercalender assets face write-down pressure as digital print grades demand alternative surface finish protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Base Paper Market |
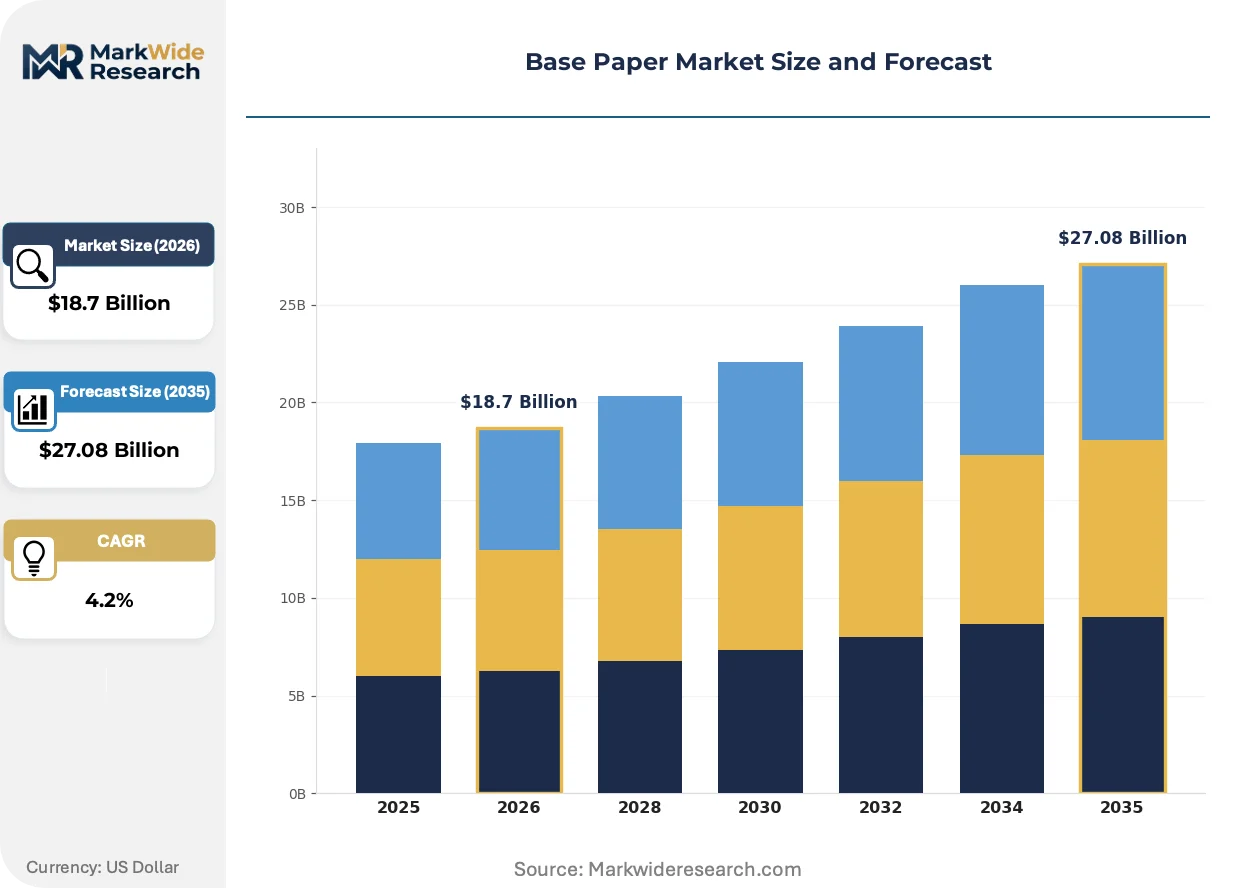
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Specialty Paper, Newsprint Application: Packaging, Printing, Publishing, Stationery End User: Consumer Goods, Publishing Houses, Educational Institutions, Industrial Users Distribution Channel: Direct Sales, Distributors, Online Platforms, Retailers |
| Companies Covered | International Paper, Stora Enso Oyj, Ahlstrom-Munksjö, Graphic Packaging, Pudumjee Paper Products, WestRock, Smurfit Kappa, Mondi, Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Base Paper Market Strategic Shifts
Base paper specification workflows are fragmenting as digital print adoption compresses run lengths and tightens tolerance requirements across packaging and publishing segments.
Barrier coating chemistries incorporating bio-based polymers and mineral additives are rendering obsolete conventional plastic-laminated structures in food service and pharmaceutical primary packaging. European and North American converters are qualifying these substrates for twelve- to eighteen-month shelf-life applications. The shift is compressing demand for multi-layer extrusion coating capacity while expanding coating weight precision requirements at the base paper mill.
EPA effluent guidelines are tightening dissolved solids and color discharge limits for US pulp and paper facilities. Mills in the Great Lakes and Southeast regions are retrofitting biological treatment systems to meet numeric effluent limitations. The regulatory pressure is diverting capital from capacity expansion into environmental compliance, tightening supply availability for unbleached kraft grades.
Brand owners in consumer packaged goods are consolidating supplier panels around vertically integrated producers with certified chain-of-custody documentation. German retailers and their packaging converters now require FSC or PEFC verification for corrugated shipping cases. The purchasing pattern is marginalizing merchant converters without backward fiber integration or third-party certification infrastructure.
Base Paper Market Segmentation
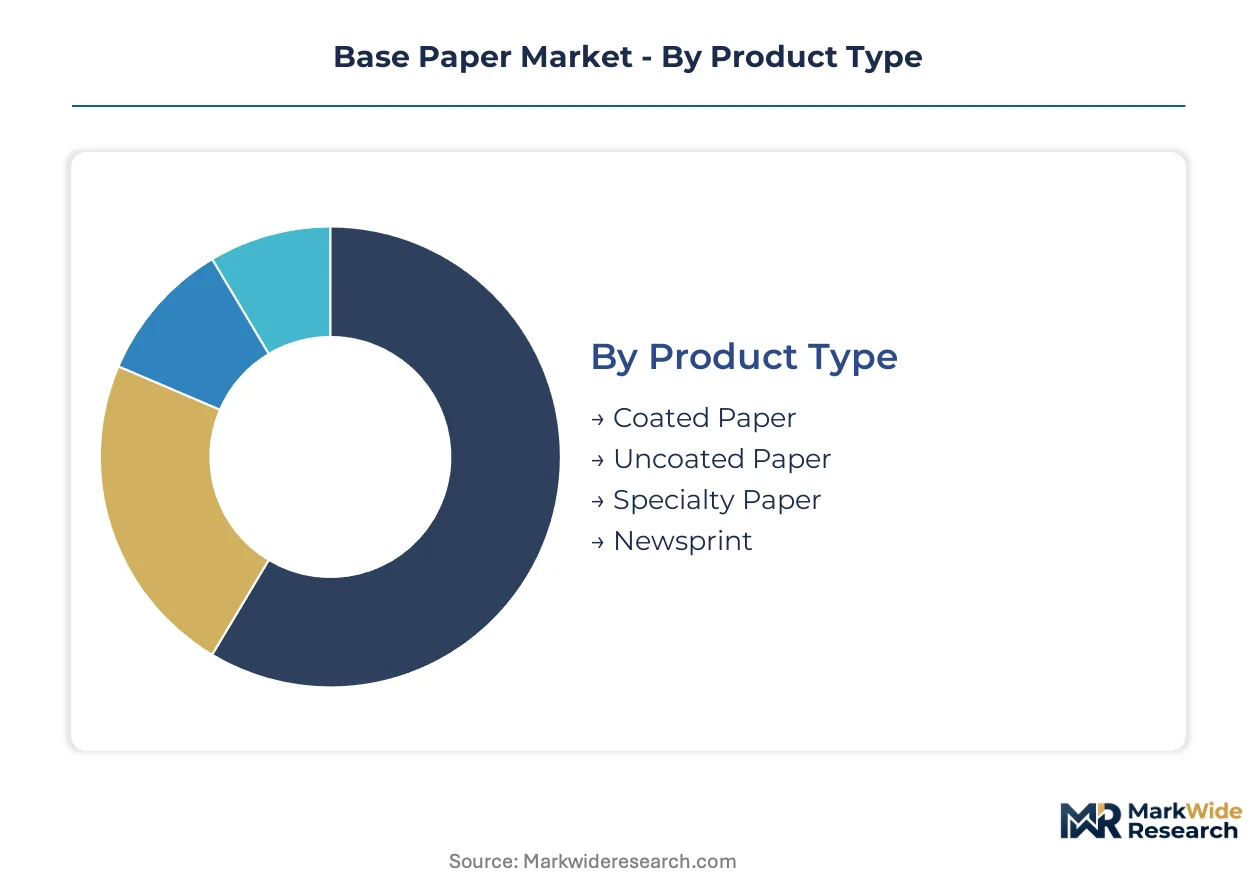
Base paper specifications fragment across end-use requirements, with packaging converters demanding rapid-turn grades while publishing channels impose longer qualification cycles. Understanding segment velocity and margin concentration guides capital allocation between commodity volume plays and specialty premium positions.
Product Type:
Cycle times vary dramatically: uncoated grades turn inventory weekly for office supply chains while specialty papers undergo six-month converter qualification protocols.
- Coated Paper:Clay or polymer-surfaced substrates engineered for high-fidelity halftone reproduction in annual reports and luxury catalogs. European publishing houses specify these grades despite secular volume pressure from digital media substitution.
- Specialty Paper:Functional substrates incorporating synthetic fiber blends, thermal coatings, or greaseproof barriers for pharmaceutical blister packs and food service liners. German and Indian pharmaceutical converters specify oxygen-resistant grades to displace plastic lamination layers.
- Uncoated Paper:Virgin or recycled fiber webs serving high-volume stationery and educational channels where opacity and ink absorption standards remain consistent. Institutional procurement in Brazil and India drives steady replenishment cycles.
- Newsprint:Mechanical pulp-based lightweight grades for daily newspaper production experiencing accelerating demand erosion from screen-based news consumption.
Uncoated paper anchors the volume base while specialty paper gains share at the steepest rate.
Application:
Cost tiers separate commodity packaging from premium publishing substrates, with corrugated liners commanding scale economics that coated freesheet cannot match.
- Packaging:Kraft linerboard and medium grades specified for e-commerce shipping cases, with German and Brazilian consumer goods manufacturers now requiring higher basis weights for protective performance. EU Green Deal recyclability mandates redirect virgin fiber demand toward recycled-content processing infrastructure.
- Printing:Commercial web and sheetfed grades for marketing collateral and direct mail, where digital print adoption compresses run lengths and tightens caliper tolerance requirements.
- Publishing:Book paper and magazine substrates confronting secular demand erosion as screen-based content consumption displaces physical formats.
- Stationery:Bond and writing grades for corporate and educational procurement channels where opacity specifications and ISO brightness standards filter subscale suppliers.
Packaging commands the revenue concentration while printing contracts most rapidly under digital substitution pressure.
End User:
Customer type determines specification intensity, with industrial users imposing technical barriers that consumer channels cannot replicate.
- Consumer Goods:Brand owners consolidating supplier panels around FSC-certified integrated producers for corrugated shipping cases, marginalizing merchant converters without chain-of-custody documentation.
- Industrial Users:Filtration, medical wrapping, and abrasive backing applications specifying synthetic fiber blends with premium pricing potential and extended qualification cycles.
- Publishing Houses:Magazine and book printers reducing page counts and shifting to lighter basis weights as advertising revenue migrates to digital platforms.
- Educational Institutions:Government procurement channels in India enforcing BIS burst strength and ring crush specifications that filter subscale domestic producers.
Consumer goods procurement anchors volume stability while industrial users deliver the steepest margin expansion.
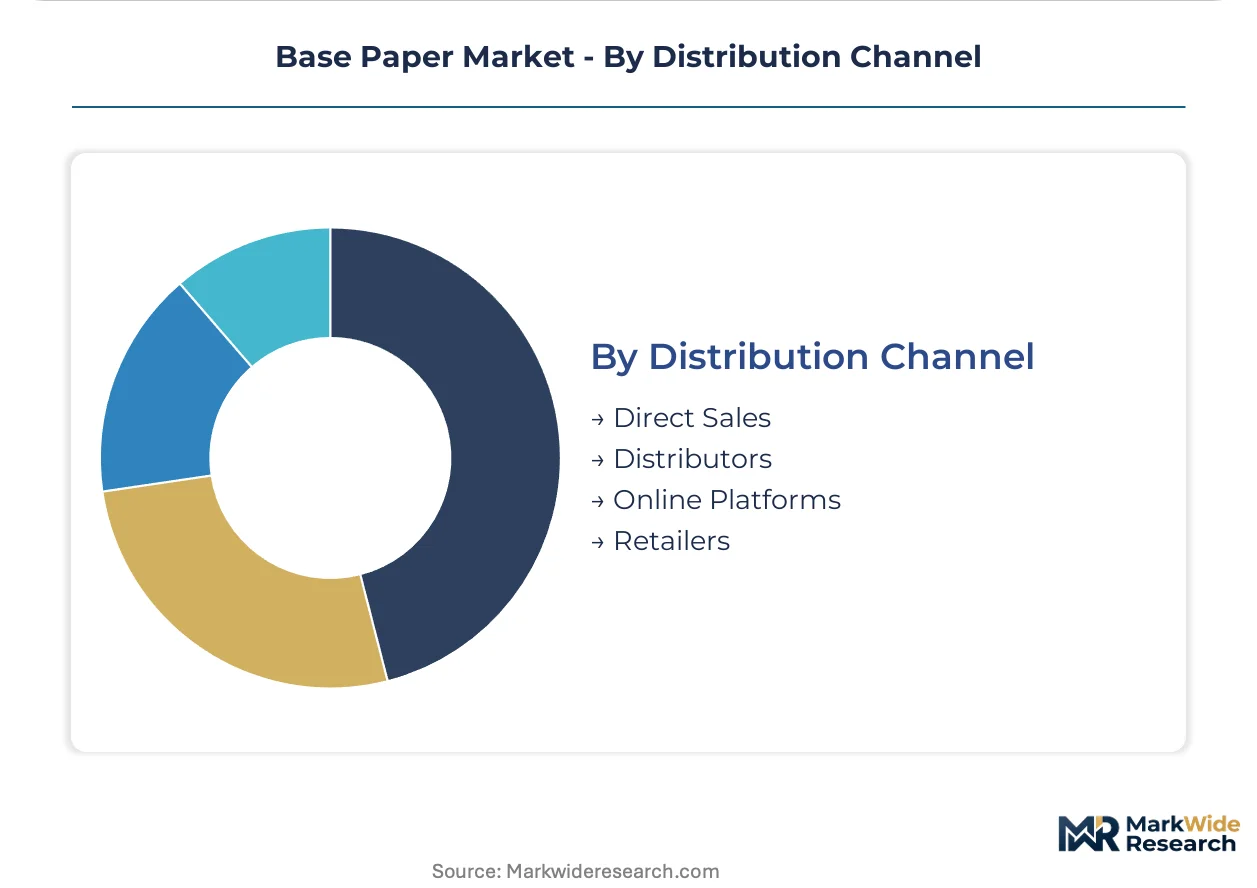
Distribution Channel:
Supply concentration favors direct mill relationships for high-volume packaging accounts, while fragmented stationery demand flows through layered intermediaries.
- Direct Sales:Mill-direct contracts with German retailers and Brazilian consumer goods manufacturers requiring certified chain-of-custody documentation and carbon footprint disclosure under REACH mandates.
- Distributors:Regional paper merchants stocking uncoated grades for educational and office supply channels, capturing smaller converters without volume scale for direct procurement.
- Online Platforms:E-procurement portals for standardized stationery specifications, compressing lead times but limiting technical consultation for specialty grade selection.
- Retailers:Big-box and specialty office supply chains moving commoditized copy paper and envelopes, with private label substitution pressuring branded supplier margins.
Direct sales anchor volume concentration while online platforms climb fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retailers and Brazilian consumer goods manufacturers anchor the highest-specification procurement channels, while Indian institutional buyers enforce rigorous domestic standards that filter subscale suppliers from corrugated and educational paper contracts.
United States
E-commerce fulfillment networks and pharmaceutical blister pack converters drive specialty kraft and barrier-grade demand. EPA effluent guidelines tighten dissolved solids discharge limits for mills in the Great Lakes and Southeast regions. Wisconsin and Georgia mill clusters retrofit biological treatment systems to meet numeric limitations, diverting capital from capacity expansion.
Germany
Corrugated shipping case specifications from consumer goods manufacturers now mandate higher basis weights for protective performance. EU Green Deal recyclability mandates and REACH carbon disclosure requirements redirect virgin fiber demand toward recycled-content processing infrastructure. The Rhine-Ruhr packaging corridor consolidates procurement around FSC-certified integrated producers with verified chain-of-custody documentation.
India
Institutional procurement for educational stationery and e-commerce corrugated substrates enforces BIS burst strength and ring crush specifications. The Bureau of Indian Standards grading protocols filter subscale domestic producers from government tender channels. Maharashtra and Gujarat mill complexes invest in quality control infrastructure to capture premium procurement segments.
Brazil
Consumer goods manufacturers specify elevated basis weights for protective e-commerce shipping cases. National environmental regulators enforce wastewater discharge parameters that constrain unbleached kraft expansion. São Paulo state packaging converters consolidate supplier relationships around integrated pulp-and-paper complexes with certified sustainability credentials.
Japan
Pharmaceutical blister pack converters specify oxygen-resistant specialty grades to displace plastic lamination layers. METI industrial standards govern synthetic fiber blend ratios for medical wrapping and filtration applications. The Kanto region technical paper cluster qualifies barrier coating chemistries for twelve- to eighteen-month shelf-life pharmaceutical applications.
Base Paper Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement segments. Integrated pulp-and-paper complexes dominate corrugated linerboard supply through captive fiber networks, while merchant converters face sourcing vulnerability without backward integration. Three archetypes define competitive positioning: North American scale-driven kraft producers, Nordic softwood-based premium packaging specialists, and technical base paper innovators blending synthetic fibers for filtration and medical applications. Capacity expansion and M&A consolidation represent the dominant competitive moves as mills seek fiber security and geographic coverage.
Among the scale-driven North American producers, International Paper exemplifies channel control through integrated pulp network leverage. Stora Enso Oyj anchors Nordic premium packaging positioning through softwood fiber supply security across European consumer goods channels. Ahlstrom-Munksjö occupies the technical specialization tier where synthetic fiber blends command durable filtration and medical wrapping applications with extended qualification cycles.
| Leading Market Players |
|---|
| International Paper |
| Stora Enso Oyj |
| Ahlstrom-Munksjö |
| Graphic Packaging |
| Pudumjee Paper Products |
| WestRock |
| Smurfit Kappa |
| Mondi |
| Oji Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Ruhr corridor's freight cost dynamics amplify pricing power for integrated German mills while compressing margins for merchant converters dependent on spot pulp purchases. Softwood fiber indexation in Nordic supply contracts transmits volatility directly into kraft linerboard quotations, forcing downstream differentiation between FSC-certified integrated producers and uncertified competitors.
Pricing Analysis
Cost-plus contracts indexed to NBSK pulp futures dominate European packaging paper transactions, with quarterly adjustments passing fiber volatility through to converters. Price differentiation rests on chain-of-custody certification tier and volume scale, with REACH carbon disclosure compliance commanding premium positioning. Pricing pressure stems from recycled-content grade oversupply as EU Green Deal mandates redirect capacity investment. Educational procurement channels in India exhibit highest price sensitivity, while pharmaceutical blister pack converters accept premium positioning for oxygen-resistant barrier grades.
Supply Chain Analysis
Tariff exposure between US and Canadian softwood lumber markets dominates raw material cost uncertainty for North American linerboard producers. Supply concentrates in Sweden, Finland, and the US Southeast, with Nordic mills drawing from managed boreal forest concessions and American producers sourcing from private timberland. The supply chain rests on chemical pulp, recycled fiber bales, and specialty coating chemistries as critical inputs. Distribution runs through mill-direct contracts for high-volume corrugated accounts and regional merchants for fragmented stationery demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into pulp supply and certified fiber sourcing represents the scarcest operational capability as merchant converters face exclusion from retailer procurement panels. Mills without captive softwood supply or FSC/PEFC infrastructure confront structural margin compression.
For Market Incumbents: Harden fiber security through long-term timber concession agreements or recycled-content processing infrastructure investments. Defend against plastic-laminate substitution in pharmaceutical packaging by accelerating barrier coating R&D. Prioritize REACH carbon disclosure compliance to maintain access to German retailer supplier panels.
For New Entrants and Emerging Players: Pursue the India BIS compliance gap where burst strength and ring crush specifications filter subscale domestic competitors from government educational procurement. Target Maharashtra and Gujarat mill complexes with quality control infrastructure investments. Position through technical specialization in synthetic fiber blends for filtration and medical wrapping applications.
For Investors and Strategic Acquirers: Technical base paper innovators with pharmaceutical converter relationships and extended qualification cycles present the most defensible acquisition profile. Long-term viability favors producers with backward fiber integration and barrier coating intellectual property. Monitor EU Green Deal recyclability mandate enforcement as the inflection signal for recycled-content grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive softwood fiber secures cost stability for kraft linerboard output against Nordic price volatility. |
| Barrier Coating R&D Investment | Bio-based polymer formulations displace plastic lamination in pharmaceutical blister pack applications. |
| FSC/PEFC Certification Program | Chain-of-custody documentation unlocks German retailer procurement panels marginalizing uncertified competitors. |
| Recycled-Content Processing Infrastructure | EU Green Deal compliance redirects virgin fiber demand toward qualified recycled-grade capacity. |
| Synthetic Fiber Blend Development | Durable fiber mixes command premium pricing in filtration and medical wrapping technical applications. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across mill operations, converter procurement, and end-use specification roles. Primary interviews with kraft linerboard plant managers, corrugated packaging procurement leads at consumer goods manufacturers, pharmaceutical blister pack converters, and educational stationery distributors were cross-validated against secondary sources including EPA effluent filings, EU ETS carbon disclosure databases, BIS grading protocols, and trade flow customs records. Bottom-up capacity assessments and top-down demand modeling were triangulated to establish volume and value estimates.
Calibration against historical price indices and capacity utilization rates anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application, end user, and distribution channel, with additional granularity on certification tier and fiber source. CAGRs were derived from regression analysis of demand drivers and supply elasticity parameters, incorporating e-commerce corrugated specifications, REACH carbon disclosure adoption curves, and pharmaceutical barrier grade qualification timelines as industry-specific inputs.
Sensitivities concentrate around softwood pulp price volatility, EU Green Deal enforcement timing, and India BIS specification revisions. Forecasts reflect documented assumptions on fiber cost pass-through rates and converter substitution elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Coated Wood Free Papers Market
Paper Products
Pigmented Paper Market
Paper Products
Global Wood Pulp Market
Paper Products
Global Molded Pulp Products Market
Paper Products
Chemical Cellulose Market
Paper Products
Europe Coated Paper Market
Paper Products
Compressed Fiberboard Market
Paper Products
Paper Doilies Market
Paper Products
North America Thermal Paper Market
Paper Products
Europe Thermal Paper Market
Paper Products
Paper Based Laminates Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Inlay Paper Market
Paper Products
Sanitary Paper Products Market
Paper Products
Solar Paper Market
Paper Products
Cheque Paper Market