
 Global Molded Pulp Products Market | 2026-2036
Global Molded Pulp Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molded Pulp Products Market Outlook
E-commerce fulfillment packaging is reconfiguring procurement patterns for protective inserts and shipper trays. Huhtamaki Oyj leverages its European thermoformed fiber footprint to supply quick-service chains with clamshells and bowls. Brødrene Hartmann A/S anchors egg packaging demand through automated molding lines serving European and Latin American retail. Sonoco Products Company extends its industrial protective expertise into electronics and appliance cushioning applications.
Molded pulp products are engineered from cellulose fibers—pulped paper, recycled paper, bagasse, or bamboo fiber—formed under heat and pressure into dimensionally stable trays, clamshells, and protective structures with specified caliper and edge-crush resistance. These products serve as primary and secondary packaging where cushioning, nesting, and compostability replace petroleum-based alternatives. Food Containers command the largest volume share as fresh-produce and ready-meal segments convert from plastic, while Industrial Packaging captures expanding margin pools from precision electronics and automotive component shipping. Bagasse-based material grades are gaining fastest in regions with surplus sugarcane processing residue.
The EU Packaging and Packaging Waste Regulation, the US EPA sustainable materials management hierarchy, and China's GB standards for restricted plastic articles are converging to ban or surcharge single-use plastics in foodservice and consumer goods channels. These frameworks elevate molded pulp to default status in categories previously dominated by expanded polystyrene and polyethylene terephthalate. Stakeholders must monitor how evolving compostability certification requirements and fiber sourcing traceability rules reshape supplier qualification criteria and capital allocation decisions.
Market Dynamics
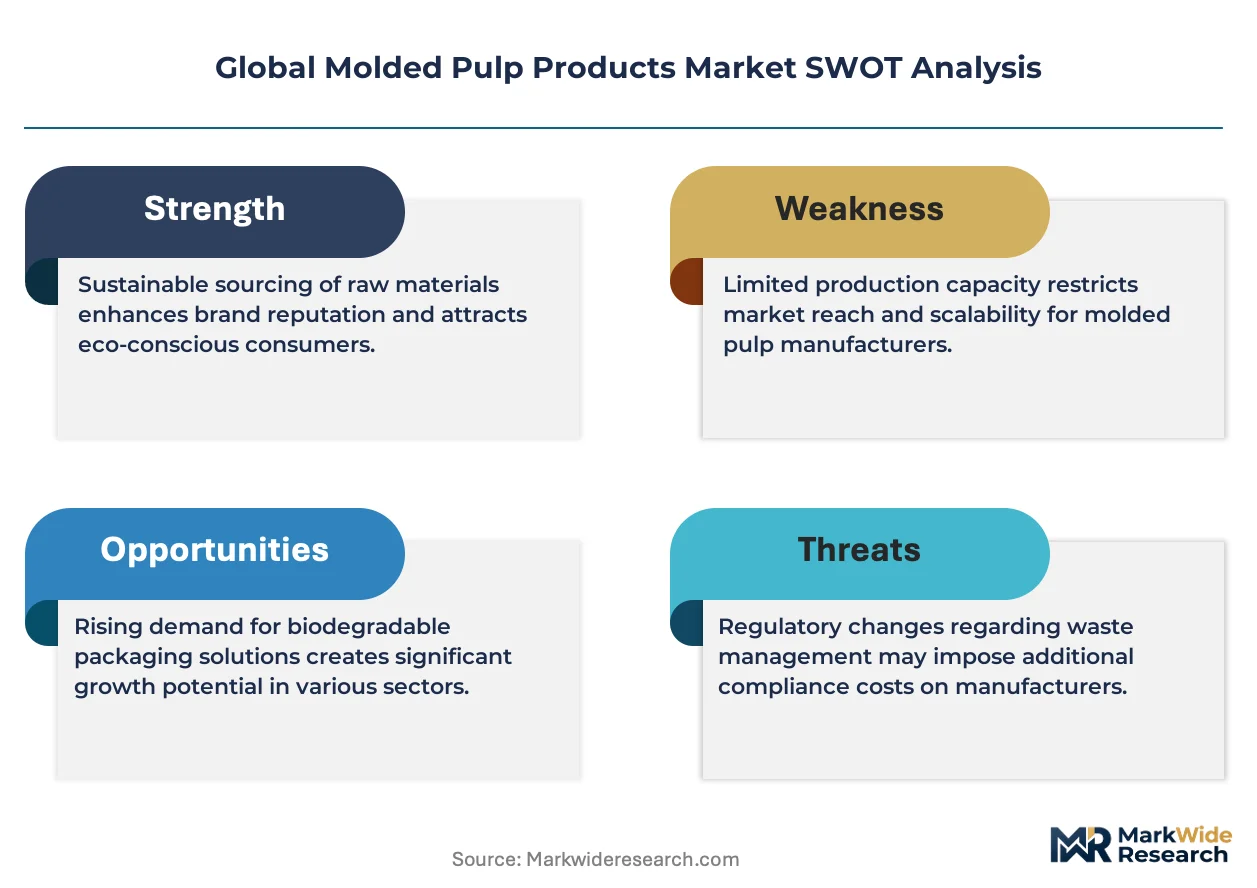
Extended producer responsibility frameworks are forcing foodservice operators and e-commerce platforms to abandon expanded polystyrene and polyethylene terephthalate packaging, redirecting procurement volumes toward fiber-based alternatives with certified compostability credentials.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability thresholds and plastic reduction targets are converting institutional catering and quick-service restaurant procurement toward molded pulp trays and clamshells.
- Bagasse fiber processing:Surplus sugarcane residue from Brazil and India is supplying low-cost raw material streams for food-grade molded pulp with enhanced moisture resistance.
- E-commerce fulfillment surge:Protective inserts and shipper trays for electronics and appliances are displacing petroleum-based cushioning across China, Germany, and the United States.
Market Restraints
- Pulp fiber cost volatility:Recycled paper and agricultural residue prices fluctuate with energy costs and harvest yields, compressing margin predictability for converters.
- Composting infrastructure gaps:Industrial composting facility scarcity in the United States and developing Asian markets limits end-of-life value realization for certified products.
- Barrier coating limitations:Grease and moisture resistance in uncoated fiber remains inferior to plastic alternatives for hot-food applications above 85 degrees Celsius.
Strategic Opportunities
- Precision electronics protective packaging:Anti-static molded pulp formulations are penetrating semiconductor and medical device shipping segments previously served by expanded polystyrene.
- India fresh-food delivery expansion:Swiggy and Zomato procurement specifications are mandating fiber-based meal containers, opening volume contracts for regional molded pulp suppliers.
- China GB standards enforcement:Municipal plastic restriction ordinances in Shanghai, Beijing, and Shenzhen are accelerating restaurant compliance transitions.
Industry Challenges
- Compostability certification timelines:TÜV Austria and BPI certification processes extend 12-18 months, delaying supplier qualification for urgent foodservice tenders.
- Automated molding line capex:Thermoformed fiber equipment for high-caliper industrial applications requires capital deployment that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molded Pulp Products Market |
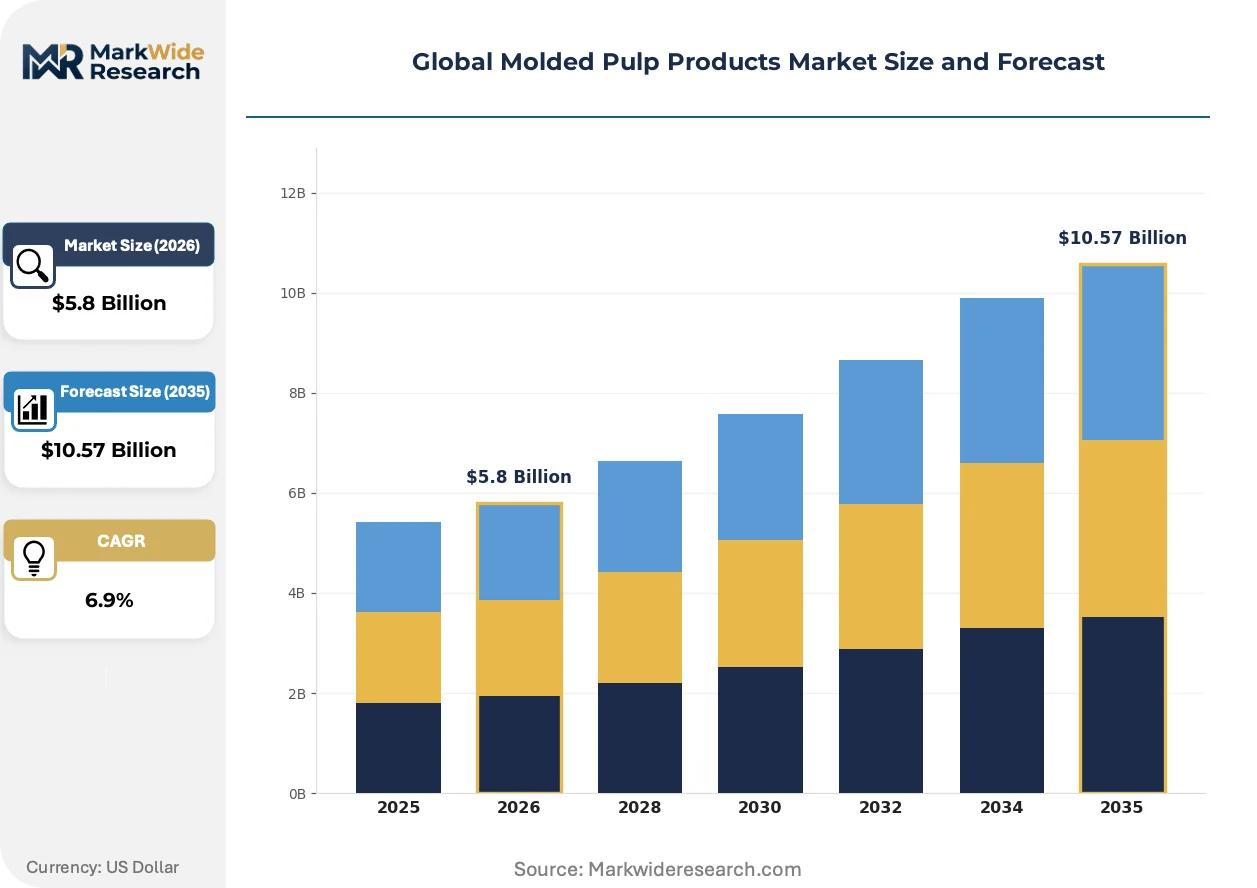
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.57 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Containers, Consumer Goods Packaging, Egg Cartons, Industrial Packaging Material Used: Pulped Paper, Recycled Paper, Bagasse, Bamboo Fiber End Use Industry: Food & Beverage, Electronics, Personal Care, Automotive Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Huhtamaki Oyj, Brødrene Hartmann A/S, Sonoco Products Company, UFP Technologies, Inc., Sabert Corporation, Genpak LLC, Henry Molded Products Inc., Stora Enso, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molded Pulp Products Market Strategic Shifts
Material science advances are merging agricultural waste streams with synthetic fiber blends to achieve performance parity with plastic barriers, while regulatory enforcement tightens disposal accountability across major economies.
Thermoformed fiber technology is hybridizing traditional wet-molded pulp with precision calendering and barrier coating deposition. Electronics manufacturers in Germany and South Korea are specifying these hybrid structures for precision component shipping. The technology is hybridizing protective performance expectations, compressing the addressable market for expanded polystyrene in industrial applications.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated grease barriers from food-contact fiber packaging. European converters are accelerating plant-based wax and clay coating development. Fresh-produce and ready-meal segments in France, Italy, and the Netherlands are absorbing reformulation costs and passing specifications through supply contracts.
Direct procurement relationships between quick-service chains and molded pulp converters are disintermediating traditional packaging distributors. McDonald's and Burger King sustainability mandates in the United Kingdom and Canada are establishing approved supplier lists with fiber-content minimums. Foodservice procurement teams in London, Toronto, and Sydney are consolidating volumes into multi-year agreements with qualifying converters.
Global Molded Pulp Products Market Segmentation
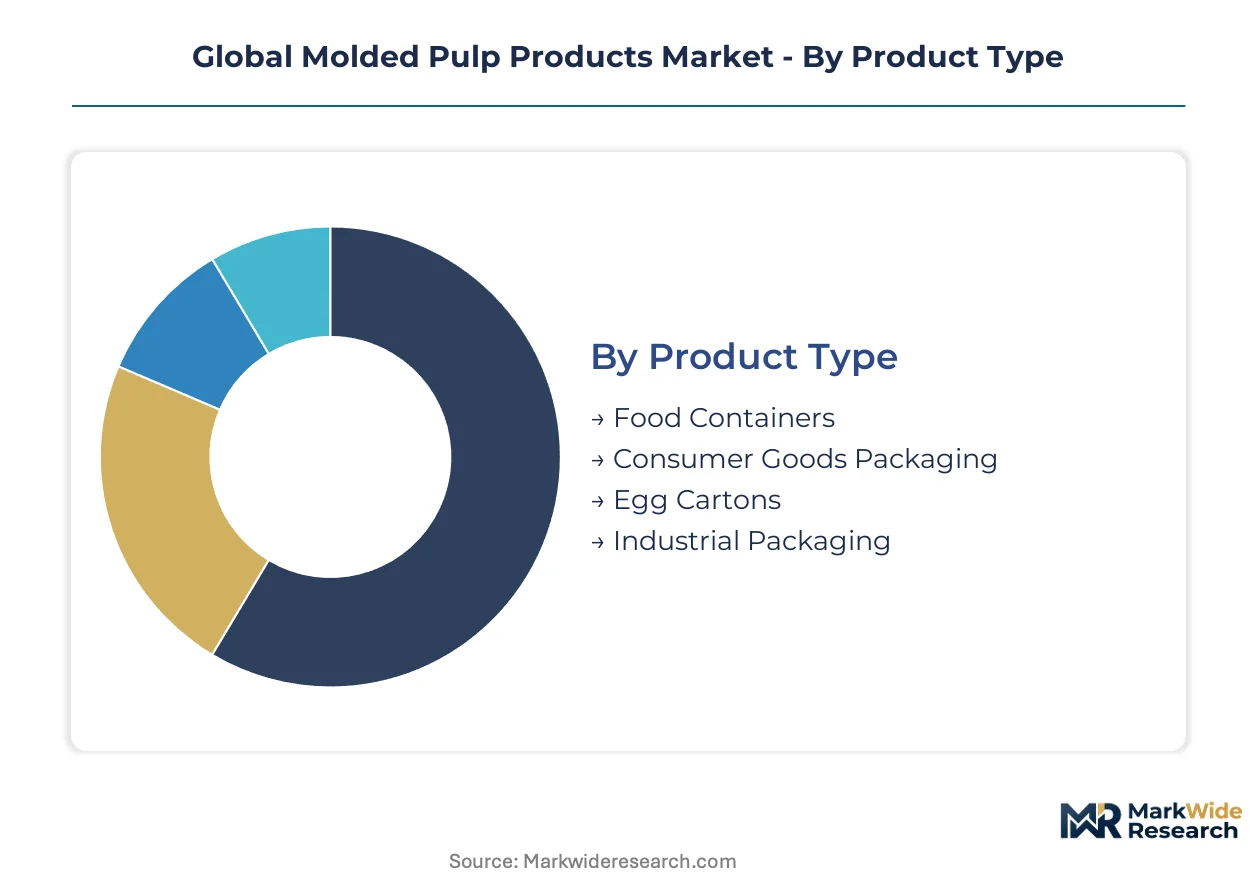
Molded pulp procurement cycles vary dramatically by application, with foodservice trays turning every 2-4 weeks versus industrial protective inserts renewing on 12-18 month contracts. Understanding these velocity differentials helps suppliers align capacity planning and working capital deployment across divergent demand rhythms.
Product Type:
Food Containers rotate through supply chains fastest due to single-use consumption patterns, while Industrial Packaging sits at the opposite extreme with multi-year protective specifications.
- Food Containers:Trays, clamshells, and bowls engineered from thermoformed fiber for fresh-produce and ready-meal segments. Quick-service chains in the United Kingdom and Canada are mandating minimum recycled fiber content thresholds in procurement tenders.
- Egg Cartons:Precision-molded cellulose structures with defined nesting geometry and compressive strength for fragile cargo. Automated molding lines serving European and Latin American retail anchor consistent volume demand through long-term supply agreements.
- Consumer Goods Packaging:Cosmetic and personal care inserts with smooth-finish surfaces.
- Industrial Packaging:High-caliper cushioning for electronics and automotive components.
Food Containers anchors the volume base while Industrial Packaging gains share at the steepest rate.
Material Used:
Cost tiers separate commodity agricultural residues from premium cultivated fibers, with price spreads widening during energy price spikes that affect pulping economics.
- Bagasse:Sugarcane processing residue pulped for food-grade moisture-resistant formulations. Surplus availability from Brazil and India is redirecting procurement toward this lowest-cost tier for quick-service applications.
- Recycled Paper:Post-consumer fiber streams with established collection infrastructure across Germany and Japan. E-commerce fulfillment specifications in these markets are absorbing volume despite quality variability constraints.
- Pulped Paper:Virgin cellulose with consistent fiber length and strength properties.
- Bamboo Fiber:Rapid-renewal cultivated source with premium positioning in personal care packaging.
Recycled Paper dominates current tonnage while Bagasse expands most quickly as sugarcane processing scales.
End Use Industry:
Customer concentration patterns diverge sharply, with Food & Beverage fragmenting across thousands of operators versus Electronics consolidating around major OEM procurement desks.
- Food & Beverage:Primary packaging for fresh produce, ready meals, and foodservice disposables. China's municipal plastic restrictions in Shanghai and Beijing are accelerating restaurant compliance transitions toward fiber-based alternatives.
- Electronics:Anti-static protective inserts and shipper trays for semiconductors and precision components. German and South Korean manufacturers are specifying hybrid thermoformed fiber structures that displace expanded polystyrene in high-value shipping.
- Personal Care:Cosmetic and skincare product cushioning and presentation packaging.
- Automotive:Component shipping trays and protective dunnage for supply chain logistics.
Food & Beverage holds the installed base while Electronics climbs the fastest on precision protective specifications.
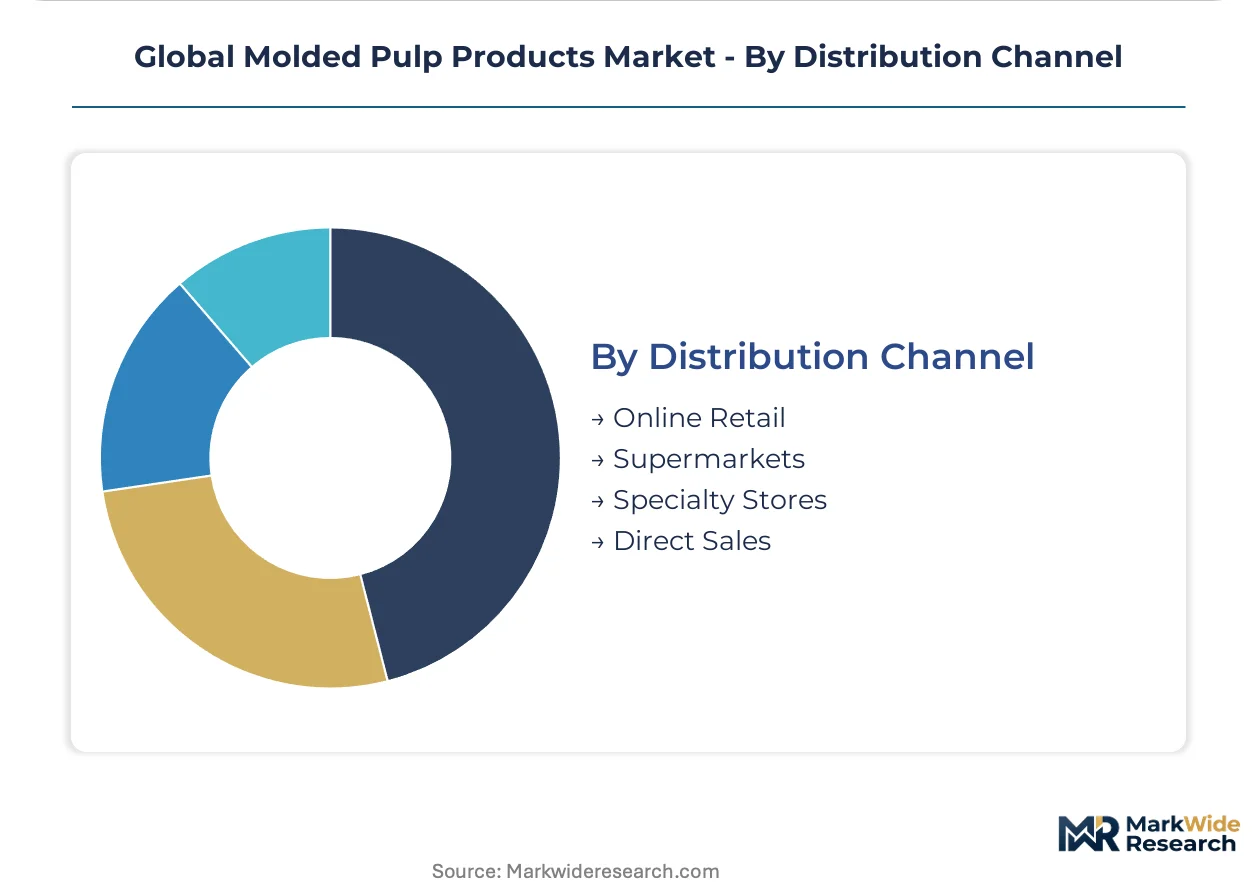
Distribution Channel:
Channel margin structures separate high-touch specification sales from low-touch replenishment, with Direct Sales capturing the deepest customer relationships.
- Direct Sales:Converter-to-brand procurement relationships disintermediating traditional distributors. McDonald's and Burger King sustainability mandates are establishing approved supplier lists with multi-year volume commitments.
- Online Retail:E-commerce platforms aggregating small-lot orders from independent foodservice operators. India's Swiggy and Zomato are mandating fiber-based specifications through their vendor qualification portals.
- Supermarkets:Retail private-label egg and produce packaging procurement.
- Specialty Stores:Premium and artisan food packaging with custom specifications.
Direct Sales commands the relationship depth while Online Retail scales most rapidly on platform aggregation effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's fiber packaging distribution, while China's high-speed rail network moves molded pulp from interior production zones to coastal export hubs.
China
E-commerce fulfillment apps Meituan and Ele.me drive tray consumption for fresh-food delivery across tier-one cities. GB standards for restricted plastic articles enforce municipal compliance in Shanghai, Beijing, and Shenzhen. Yangtze River Delta manufacturing clusters supply precision-molded protectors for electronics exports through Shanghai Port.
United States
Quick-service chains McDonald's and Burger King mandate fiber-content minimums in procurement contracts. EPA sustainable materials management hierarchy elevates compostable packaging in federal foodservice contracts. Midwest agricultural processing zones supply bagasse feedstock to converters serving Chicago and Detroit industrial corridors.
Germany
Automotive OEMs specify thermoformed fiber cushioning for component shipping to assembly plants. REACH restrictions on per- and polyfluoroalkyl substances eliminate fluorinated grease barriers from food-contact applications. Bavarian precision electronics manufacturers in Munich-Stuttgart corridor adopt anti-static molded pulp for semiconductor shipping.
India
Swiggy and Zomato procurement portals mandate fiber-based meal containers for restaurant partners. FSSAI food-contact safety standards govern molded pulp formulations for hot-food applications. Maharashtra and Gujarat sugar belt supplies bagasse residue to converters serving Mumbai-Pune industrial zone.
Brazil
São Paulo foodservice distributors convert tray procurement toward fiber alternatives for institutional catering. ANVISA food-contact regulations align with Mercosur standards for cellulose-based packaging. São Paulo state sugarcane processing clusters feed bagasse pulp mills serving Southeast Brazil manufacturing belt.
Global Molded Pulp Products Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying fiber formulations and molding equipment. The vendor base spans three tiers: multinational converters with thermoformed fiber platforms, regional specialists in agricultural residue processing, and equipment fabricators serving mid-tier entrants. Strategic moves concentrate on capacity expansion in bagasse-processing zones and direct procurement relationships disintermediating traditional distributors.
Among Nordic-European converters, Huhtamaki Oyj and Brødrene Hartmann A/S occupy positions exemplifying the integrated platform archetype, combining fiber sourcing networks with automated molding capabilities. Sonoco Products Company represents the industrial protective specialization vector, extending expertise into electronics cushioning applications. These three anchors illustrate how geographic clustering around raw material sources and end-user demand centers shapes competitive positioning.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Brødrene Hartmann A/S |
| Sonoco Products Company |
| UFP Technologies, Inc. |
| Sabert Corporation |
| Genpak LLC |
| Henry Molded Products Inc. |
| Stora Enso |
| Amcor plc |
| Others |
Value Chain & Pricing Dynamics
The Port of Rotterdam's container throughput cost dynamics compress margin predictability for European converters while amplifying price differentiation between bagasse-sourced economy grades and precision thermoformed fiber premiums. Supply concentration in Brazilian sugarcane processing zones and Yangtze River Delta manufacturing clusters feeds directly into tiered procurement negotiations across quick-service and industrial channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified compostable food-contact grades from commodity bagasse trays and virgin-pulp industrial protectors. Price differentiation hinges on TÜV Austria certification status and volume scale, with multi-year quick-service contracts commanding steepest discounts. Cost compression in economy tiers is intensifying because Indian and Brazilian agricultural residue oversupply is expanding converter capacity. Small-lot foodservice operators exhibit highest price sensitivity, while German automotive OEMs absorb premiums for anti-static precision specifications.
Supply Chain Analysis
Extended payment terms from multinational quick-service chains are squeezing working capital for mid-tier converters, forcing supply-chain finance facility adoption. Raw material sourcing draws from Brazilian bagasse residue, German recycled paper streams, and Indian sugarcane processing byproducts. Single-source vulnerability concentrates in Yangtze River Delta precision molding equipment, where German and South Korean fabricators dominate thermoformed fiber line supply. Distribution runs through direct procurement relationships disintermediating traditional packaging distributors, with platform aggregators capturing fragmented foodservice replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation's mandatory recyclability thresholds are accelerating molded pulp from alternative status to default specification across foodservice channels, compressing incumbent plastic converter timelines while opening white-space for fiber specialists.
For Market Incumbents: Harden supply security through backward integration into Brazilian and Indian bagasse pulping operations, locking in cost advantage against resin price volatility. Accelerate TÜV Austria and BPI certification timelines to defend qualification status against emerging Asian converters targeting European quick-service tenders. For New Entrants and Emerging Players: Build out regional molding capacity in Maharashtra and Gujarat to capture Swiggy and Zomato procurement mandates before pan-Indian platform consolidation hardens supplier lists. Target precision electronics protective packaging in South Korea and Germany, where anti-static specifications displace expanded polystyrene with limited incumbent fiber expertise. For Investors and Strategic Acquirers: Automated molding line operators with established quick-service approved-supplier status represent the most defensible acquisition profile across the packaging transition. Long-term viability centers on fiber traceability compliance and composting infrastructure buildout pace; monitor municipal composting facility permitting acceleration in the United States and Southeast Asia as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bagasse Pulping | Brazilian and Indian residue access secures lowest-cost raw material tier for foodservice volume contracts. |
| Thermoformed Fiber Capacity Expansion | Precision calendering lines serving German automotive OEMs capture industrial packaging margin pools. |
| Compostability Certification Investment | TÜV Austria and BPI credentials unlock quick-service procurement tenders with mandated sustainability thresholds. |
| Direct Procurement Relationship Development | McDonald's and Burger King approved-supplier status disintermediates distributor margins and locks volume. |
| Anti-Static Formulation R&D | Semiconductor shipping specifications in South Korea and Germany displace expanded polystyrene protectors. |
Study Parameters
A spread of perspectives from fiber procurement managers at quick-service chains, molding equipment engineers, composting facility operators, and regulatory affairs specialists at packaging converters converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EU Packaging and Packaging Waste Regulation implementation documents, EPA sustainable materials management guidance, China's GB standards filings, and customs trade data tracking bagasse pulp movements. Bottom-up capacity modeling across Brazilian, Indian, and Chinese production zones triangulated against top-down demand segmentation by end-use industry.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning product type, material grade, end-use industry, and distribution channel. CAGRs were derived from elasticity-adjusted volume projections incorporating pulp fiber cost volatility and regulatory enforcement pace assumptions. Forecast inputs included e-commerce fulfillment growth trajectories in China and fresh-food delivery platform procurement specifications in India.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed converters or accelerated EU plastic ban enforcement would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Machine Systems Market
Paper Products
Pharma Grade Paper Market
Paper Products
Global Paperboard Market
Paper Products
Drum Pulper Market
Paper Products
Overlay Paper Market
Paper Products
Thin Printing Paper Market
Paper Products
NCR Laser Paper Market
Paper Products
Heat Transfer Paper Market
Paper Products
Plywood Market
Paper Products
Europe Medium-Density Fiberboard Market
Paper Products
Medical Grade Paper Market
Paper Products
Global Cellulose Sponge Market
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
Coated Wood Free Papers Market
Paper Products
Europe Decor Paper Market
Paper Products
Household Paper Market