
 Necrobiosis Lipoidica Diabeticorum Market | 2026-2036
Necrobiosis Lipoidica Diabeticorum Market Size, Share, and Industry Trends Forecast 2026-2036
Necrobiosis Lipoidica Diabeticorum Market Foresight
Multi-source procurement of active pharmaceutical ingredients is broadening as manufacturers seek supply resilience for corticosteroid and immunosuppressant formulations. Pfizer leverages its biologics manufacturing infrastructure to serve specialty dermatology channels. Novartis anchors its position through dermatology-focused R&D pipelines. AbbVie differentiates via immunology expertise that extends into rare skin disease indications.
Necrobiosis Lipoidica Diabeticorum represents a chronic granulomatous dermatosis characterized by collagen degeneration with lipid deposition, primarily affecting the pretibial skin of diabetic patients and requiring long-term management to prevent ulceration. The condition demands therapies that modulate inflammatory cascades while preserving wound-healing capacity in compromised tissue. Treatment Type segmentation reveals systemic medications capturing expanding share as biologics demonstrate efficacy in refractory cases, while topical therapies retain volume leadership in early-stage disease management. Product Type dynamics show biologicals representing the fastest-growing margin pool despite corticosteroids maintaining the largest absolute prescription base.
FDA orphan drug designation pathways and EMA incentives for rare disease therapeutics are accelerating clinical development timelines for novel biologic interventions. Health Technology Assessment bodies in Germany and France are tightening reimbursement evidence requirements for dermatology biologics, reshaping market access strategies. Stakeholders must monitor evolving payer criteria for step-therapy protocols that determine sequencing between topical, systemic, and biologic treatment tiers.
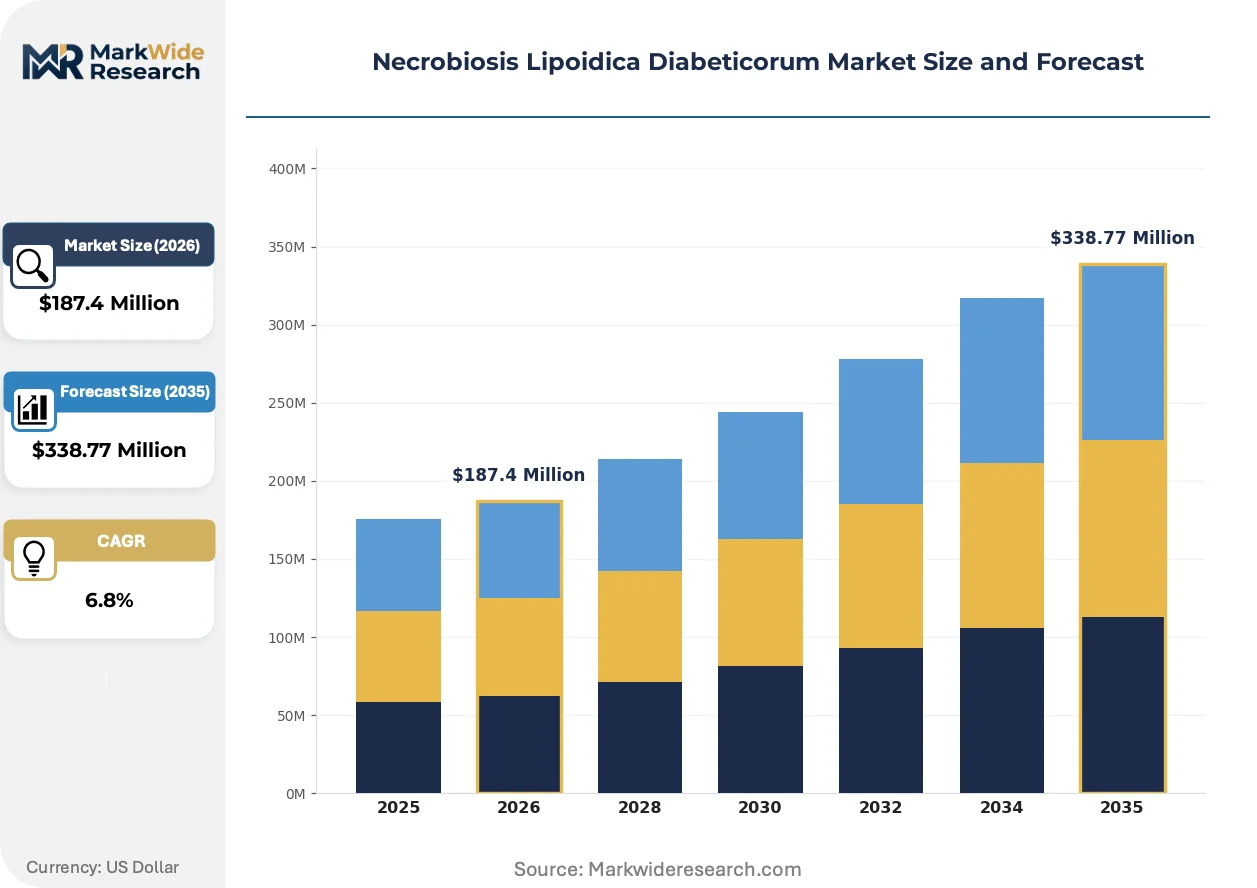
Market Dynamics
Biologic therapy pipelines are redirecting capital toward rare dermatologic indications as orphan drug incentives compress development timelines and reshape competitive entry patterns.
Growth Catalysts
- FDA Orphan Drug Designation:Accelerated approval pathways and tax credits for clinical trials are pulling venture capital into necrobiosis lipoidica therapeutic development, reducing sponsor risk exposure.
- Specialized Referral Networks:Germany's diabetes-dermatology integrated care pathways are concentrating patient volumes into academic medical centers, creating concentrated demand pools for novel therapies.
- TNF-alpha Inhibitor Repurposing:Off-label efficacy signals in refractory granulomatous dermatoses are expanding prescriber comfort with biologic intervention earlier in treatment sequences.
Market Restraints
- API Supply Concentration:Corticosteroid active pharmaceutical ingredient production clusters in India and China, exposing formulators to geopolitical trade friction and import inspection backlogs.
- Biologic Manufacturing Complexity:Cold-chain requirements and biosimilar competition are compressing margin structures for systemic therapies targeting small patient populations.
- Reimbursement Evidence Burden:Germany's IQWiG and France's HAS are tightening comparative effectiveness requirements for dermatology biologics, extending market access timelines.
Strategic Opportunities
- Telemedicine Triage Protocols:Remote dermatology platforms in the United States are capturing pretibial lesion photography for specialist routing, expanding addressable patient identification.
- JAK Inhibitor Topical Formulations:Transdermal delivery innovations are converging with immunology pipeline assets to create first-in-class localized biologic alternatives.
- EMA PRIME Scheme:Priority medicine eligibility for ulcerative complication prevention is accelerating regulatory dialogue for novel mechanism therapies.
Industry Challenges
- Dermatopathology Diagnostic Bottlenecks:Biopsy interpretation specialization gaps are delaying definitive diagnosis and treatment initiation in community settings.
- Multi-site Trial Recruitment:Rare disease prevalence requires sponsors to activate 15-20 investigative sites across dispersed geographies to achieve enrollment targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Necrobiosis Lipoidica Diabeticorum Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Dermatology Clinics, Diabetes Care Centers, General Practices, Specialty Research Institutions End User: Healthcare Providers, Patients, Researchers, Payers Treatment Type: Topical Therapies, Systemic Medications, Phototherapy, Surgery Product Type: Corticosteroids, Immunosuppressants, Growth Factors, Biologicals |
| Companies Covered | Johnson & Johnson Services Inc., Pfizer, Novartis AG, AbbVie Inc., Merck & Co., Inc., GlaxoSmithKline Plc, Bristol-Myers Squibb Company, Eli Lilly and Company, Regeneron Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Necrobiosis Lipoidica Diabeticorum Market Shifts & Advancements
Regulatory science advances and digital health integration are compressing the gap between mechanistic discovery and clinical deployment in rare dermatology.
Interleukin pathway modulation is integrating into necrobiosis lipoidica treatment algorithms through targeted biologic platforms that interrupt granulomatous inflammation cascades. Academic dermatology departments in the United States and Germany are adopting these agents for refractory cases following failure of first-line corticosteroid regimens. The technology is integrating prescriber education requirements and risk evaluation mitigation strategies into standard of care protocols, elevating treatment complexity.
EMA's PRIME designation pathway is compressing scientific advice timelines and enabling accelerated assessment for therapies addressing unmet needs in rare dermatologic conditions. Sponsors are restructuring clinical development programs to align with rolling review procedures and adaptive trial designs. European biotech developers targeting necrobiosis lipoidica are prioritizing this regulatory route to secure conditional marketing authorization ahead of full confirmatory data packages.
Step-therapy protocol enforcement by United States payers is restructuring prescribing sequences, requiring documentation of topical and systemic failure before biologic authorization. Dermatology practices are deploying registry data and prior authorization specialists to navigate these requirements. This behavioral shift is most pronounced in Medicare Advantage and commercial managed care plans where pharmacy benefit managers control formulary tier placement.
Necrobiosis Lipoidica Diabeticorum Market Segmentation
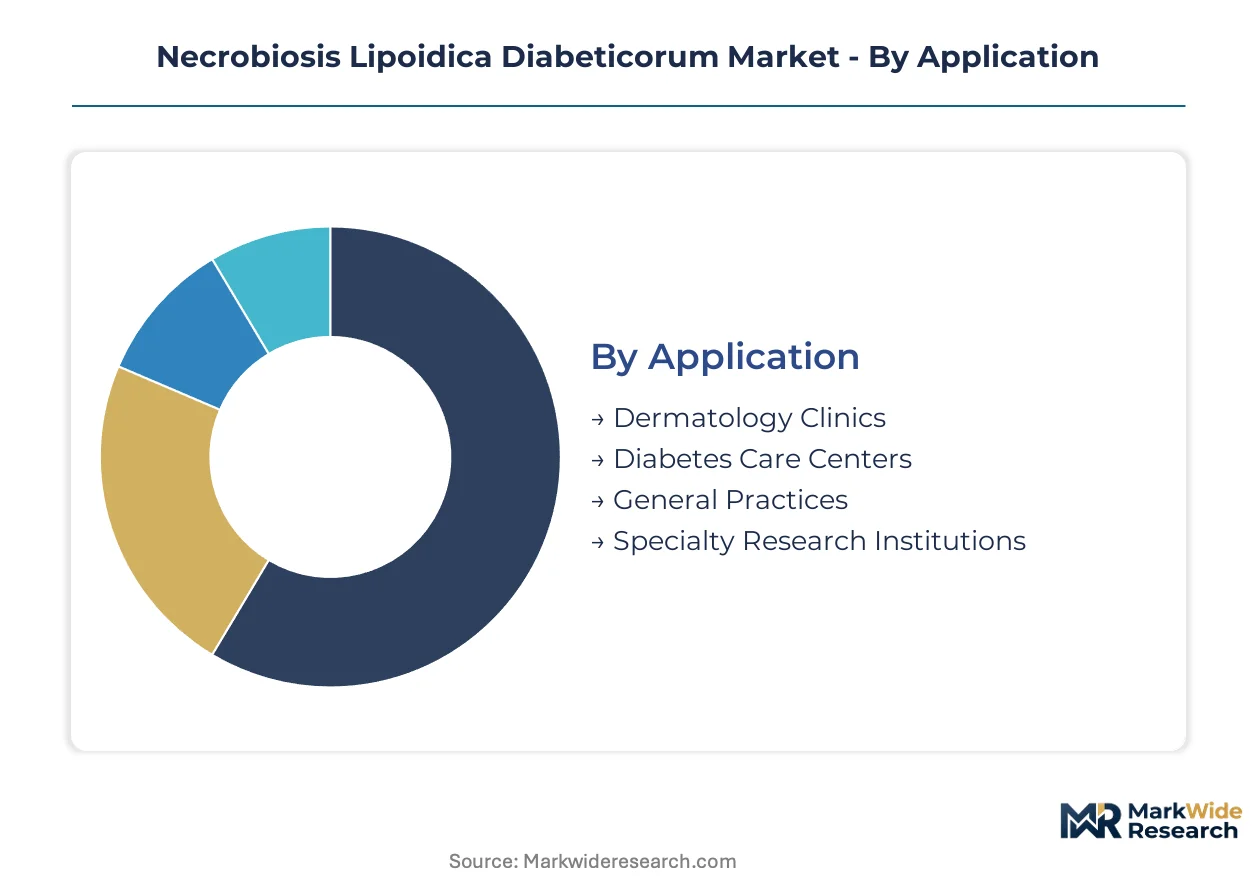
Treatment pathways for necrobiosis lipoidica diabeticorum diverge sharply by disease stage and ulceration risk, requiring precise segmentation to match therapeutic modality to tissue pathology. Prescriber behavior and reimbursement protocols further stratify demand across institutional settings and product categories.
Application:
Technology intensity and diagnostic capability define site selection for necrobiosis lipoidica management.
- Dermatology Clinics:Biopsy-confirmed diagnosis and advanced phototherapy infrastructure concentrate pretibial lesion management in specialized dermatology centers. Academic medical centers in the United States and Germany anchor referral networks for refractory cases requiring biologic therapy.
- Diabetes Care Centers:Integrated endocrinology-dermatology protocols enable early lesion detection during routine diabetic foot examinations. Germany's diabetes-dermatology integrated care pathways are concentrating patient volumes into these settings.
- General Practices:First-line corticosteroid initiation and wound monitoring occur in primary care settings with dermatology referral triggers for treatment failure.
- Specialty Research Institutions:Clinical trial enrollment and mechanistic studies on granulomatous inflammation cascade modulation.
Dermatology clinics lead on scale; diabetes care centers lead on momentum.
End User:
Decision-making authority and financial liability distribute unevenly across stakeholder groups.
- Healthcare Providers:Dermatologists and endocrinologists drive treatment selection through step-therapy protocol navigation and biologic prescribing authority. United States Medicare Advantage plans require extensive documentation from this group for biologic authorization.
- Patients:Ulceration risk and cosmetic concerns elevate treatment adherence priorities among diabetic populations with pretibial lesions. Telemedicine triage protocols in the United States are expanding patient-driven specialist access.
- Researchers:Academic investigators pursue interleukin pathway modulation and JAK inhibitor mechanisms through EMA PRIME-aligned clinical programs.
- Payers:Pharmacy benefit managers and national health technology assessment bodies control formulary tier placement and reimbursement timelines.
Healthcare providers lead on scale; payers lead on momentum.
Treatment Type:
Mechanism of action and tissue penetration depth determine sequencing through disease progression.
- Topical Therapies:High-potency corticosteroids and calcineurin inhibitors address early-stage plaques without systemic exposure. Community dermatology practices in the United States retain volume leadership for this modality.
- Systemic Medications:Immunosuppressants and antimalarials target refractory granulomatous inflammation with broader tissue distribution. TNF-alpha inhibitor repurposing is expanding prescriber comfort with earlier biologic intervention.
- Phototherapy:Narrowband UVB and PUVA protocols for patients with contraindications to systemic therapy.
- Surgery:Debridement and grafting for ulcerative complications unresponsive to medical management.
Topical therapies lead on scale; systemic medications lead on momentum.
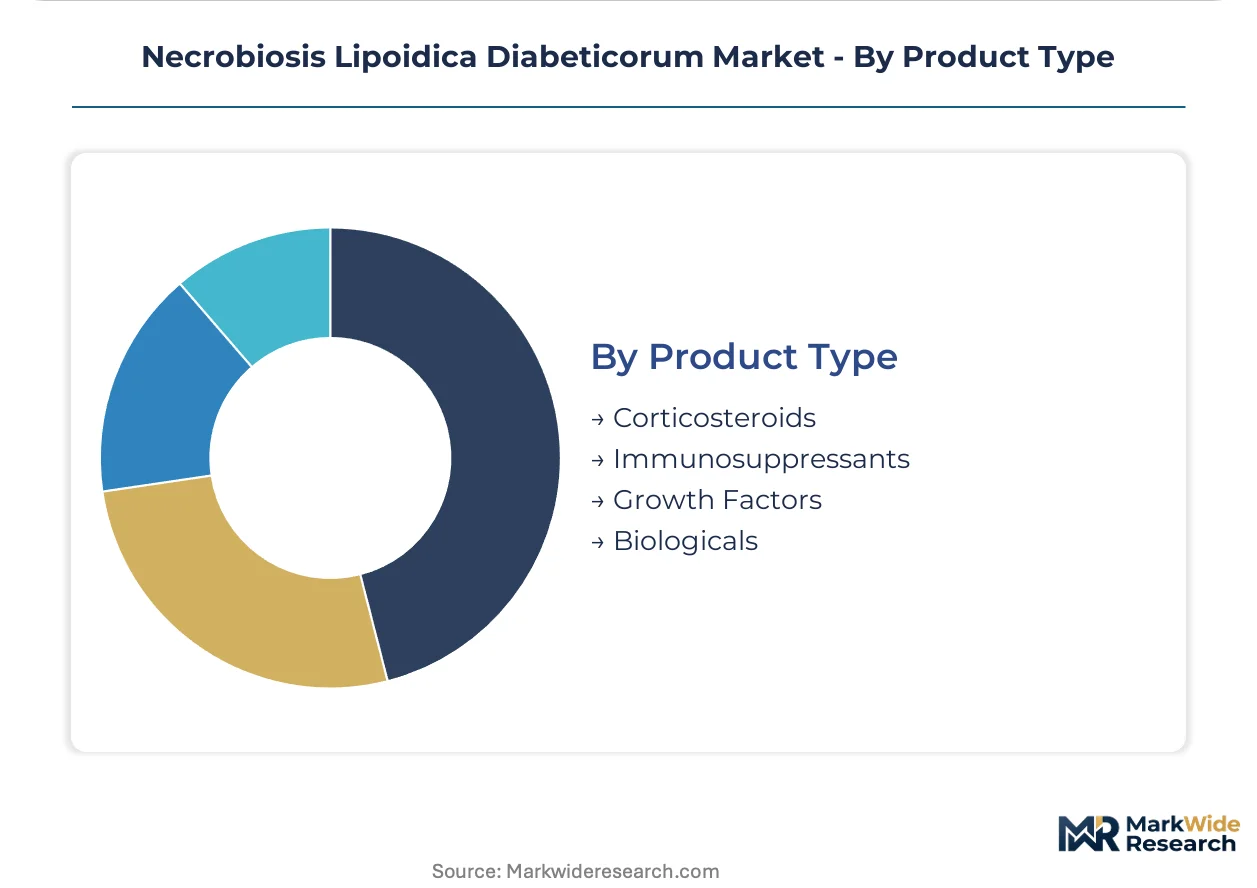
Product Type:
Manufacturing complexity and regulatory pathway differentiate margin structures across therapeutic classes.
- Corticosteroids:Synthetic glucocorticoid formulations dominate prescription volume through established safety profiles and generic availability. API production concentration in India and China exposes supply chains to import inspection backlogs.
- Biologicals:Monoclonal antibodies targeting interleukin and TNF-alpha pathways command premium pricing in refractory cases. Cold-chain requirements and biosimilar competition compress margin structures despite orphan drug incentives.
- Immunosuppressants:Systemic agents including methotrexate and mycophenolate mofetil for corticosteroid-sparing protocols.
- Growth Factors:Recombinant proteins and platelet-derived preparations for ulcerative wound healing acceleration.
Corticosteroids lead on scale; biologicals lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's diabetes-dermatology integrated care pathways concentrate patient volumes into academic medical centers with specialized referral networks. The United States anchors biologic therapy adoption through Medicare Advantage step-therapy protocols and telemedicine triage platforms. Regulatory incentives in both markets are accelerating clinical development timelines for novel mechanism therapies.
United States
Medicare Advantage plans and commercial pharmacy benefit managers enforce strict step-therapy documentation requirements for biologic authorization. FDA orphan drug designation pathways provide tax credits and accelerated approval mechanisms for rare dermatologic indications. Academic medical centers in Boston and New York anchor specialized referral networks for refractory necrobiosis lipoidica cases requiring interleukin pathway modulation.
Germany
IQWiG health technology assessments tighten comparative effectiveness evidence requirements for dermatology biologics, extending market access timelines. EMA PRIME designation eligibility accelerates scientific advice and rolling review procedures for priority medicines. Integrated diabetes-dermatology care pathways in North Rhine-Westphalia and Bavaria concentrate pretibial lesion management into university hospital networks with advanced phototherapy infrastructure.
France
HAS reimbursement evaluations demand robust cost-effectiveness data for systemic therapies targeting small patient populations. EMA orphan drug incentives attract French biotech developers toward necrobiosis lipoidica therapeutic programs with conditional marketing authorization potential. Paris-based academic dermatology departments lead mechanistic research on granulomatous inflammation cascade modulation through JAK inhibitor platforms.
United Kingdom
NICE technology appraisals structure access to high-cost biologics through managed entry agreements and real-world evidence collection requirements. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for rare disease therapeutics. London and Manchester dermatology centers participate in multi-site European trial networks for novel biologic interventions in refractory cases.
Switzerland
Swissmedic streamlined procedures for orphan medicines compress regulatory timelines for therapies addressing unmet needs in rare dermatoses. Federal reimbursement frameworks require demonstration of clinical benefit relative to existing corticosteroid and immunosuppressant standards. Basel and Zurich pharmaceutical clusters host biologics manufacturing infrastructure serving specialty dermatology channels across European markets.
Necrobiosis Lipoidica Diabeticorum Market Competitive Landscape
Global majors compete with regional champions across regulatory science capabilities and biologics manufacturing scale. Market structure tilts toward consolidated leadership among immunology-focused pharmaceutical conglomerates with dermatology R&D pipelines, while mid-tier specialists occupy niche formulation segments. Three archetypes dominate: diversified biopharmaceutical conglomerates with immunology platforms, dermatology-focused R&D specialists, and generic corticosteroid manufacturers with API supply control. Competitive dynamics center on M&A activity targeting interleukin pathway assets and strategic partnerships for transdermal delivery innovation.
Within the diversified biopharmaceutical tier, Pfizer leverages established biologics manufacturing infrastructure to serve specialty dermatology distribution channels. Novartis anchors its competitive position through dermatology-focused therapeutic development pipelines with European regulatory alignment. AbbVie occupies a distinctive position by extending immunology expertise into rare skin disease indications including granulomatous dermatoses. These three entities exemplify how scale, specialization, and therapeutic area focus create differentiated market access for systemic therapies targeting refractory necrobiosis lipoidica cases.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Pfizer |
| Novartis AG |
| AbbVie Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline Plc |
| Bristol-Myers Squibb Company |
| Eli Lilly and Company |
| Regeneron Pharmaceuticals Inc. |
| Others |
Supply & Pricing Matrix
Specialty pharmaceutical conglomerates with integrated immunology platforms anchor supply-side ownership patterns, translating captive biologics manufacturing into pricing discipline for systemic therapies targeting refractory necrobiosis lipoidica cases. Their control over cold-chain distribution networks and orphan drug exclusivity periods shapes margin structures across treatment tiers.
Pricing Analysis
Active pharmaceutical ingredient cost pass-through from corticosteroid and immunosuppressant formulations drives pricing stratification across premium biologics, standard systemic medications, and economy topical tiers. Price differentiation rests on FDA orphan drug exclusivity status and EMA PRIME designation tier, with German IQWiG assessments intensifying cost compression for non-differentiated systemic agents. Medicare Advantage pharmacy benefit managers exhibit highest price sensitivity through step-therapy enforcement, while academic medical centers demonstrate lowest sensitivity for refractory case biologics.
Supply Chain Analysis
Direct-to-specialty-pharmacy channels handle biologic cold-chain requirements, while wholesale distributors manage corticosteroid volume flows to community dermatology practices. API production concentrates in India and China for synthetic glucocorticoids, with Switzerland and Germany anchoring biologics fill-finish operations. Supply chains draw from corticosteroid raw materials, monoclonal antibody cell lines, and transdermal delivery polymers, exposing formulators to single-source vulnerability for TNF-alpha inhibitor precursor supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Necrobiosis lipoidica therapeutics represent a late-cycle quality story as diabetic population expansion and ulceration risk awareness shift demand toward premium biologic specifications with orphan drug protections.
For Market Incumbents: Acquire interleukin pathway modulation assets to fortify position against TNF-alpha inhibitor biosimilar erosion. Backward integration into corticosteroid API supply buffers against India-China import inspection backlogs. Prioritize EMA PRIME-aligned clinical programs to compress regulatory timelines ahead of generic systemic competition. For New Entrants and Emerging Players: JAK inhibitor topical formulation platforms offer technology-first entry into localized biologic alternatives with reduced systemic exposure. White-space concentration sits with United States telemedicine triage protocols enabling patient capture before specialist referral. Target diabetes care centers in Germany's integrated pathways through endocrinology-dermatology partnership structures. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier dermatology specialists with orphan drug pipeline exposure but limited commercial infrastructure. Five-to-ten year viability hinges on successful navigation of HAS and IQWiG reimbursement evidence requirements. Watch EMA conditional marketing authorization grants as inflection signals for premium asset re-rating.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA tax credits and accelerated approval compress development timelines for novel biologic mechanisms. |
| Integrated Care Pathway Partnership | Germany's diabetes-dermatology networks concentrate patient volumes into university hospital referral systems. |
| Transdermal Delivery Platform Investment | JAK inhibitor topical formulations create first-in-class localized alternatives to systemic biologics. |
| Reimbursement Strategy Development | IQWiG and HAS evidence packages determine market access timelines for premium therapeutics. |
| API Supply Diversification | Multi-source corticosteroid procurement mitigates India-China geopolitical trade friction exposure. |
Research Methodology
Bottom-up patient volume modeling reconciled against top-down prescription tracking forms the analytical core of this study. Primary interviews with dermatology department heads, endocrinology clinic directors, pharmacy benefit managers, and regulatory affairs specialists at EMA and FDA were validated against secondary sources including ClinicalTrials.gov entries, EMA orphan drug designation databases, formulary tier placement records, and health technology assessment publications from IQWiG and HAS.
Historical treatment sequence pattern analysis established baseline adoption curves for topical, systemic, and biologic therapy tiers across the projection horizon. Segmentation dimensions encompass treatment line position, product mechanism class, site of care setting, and regional regulatory cluster. CAGRs were derived from epidemiological prevalence projections cross-referenced with pricing elasticity assumptions and reimbursement policy scenario modeling, with ulceration complication rates and step-therapy protocol enforcement serving as key forecast inputs.
The model holds under stable orphan drug incentive frameworks and continued diabetes prevalence expansion; deviation in biosimilar entry timelines or payer prior authorization tightening would shift volume and value trajectories. Forecasts reflect documented assumptions regarding clinical trial success rates and regulatory approval probabilities. Periodic stress-testing of base assumptions against EMA PRIME scheme utilization and Medicare Advantage formulary evolution is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Rhabdomyosarcoma Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Hepatic Insufficiency/Liver Failure Market
Specialty Medicine
Diamond-Blackfan Anemia Syndrome Therapeutics Market
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
United States Sports Medicine Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Grand Mal Seizure Market
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Cholangiocarcinoma Market