
 Middle East and Africa Eco-Friendly Packaging Market | 2026-2036
Middle East and Africa Eco-Friendly Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Eco-Friendly Packaging Market Foresight
CE marking and ISO 14001 environmental management certification is bifurcating the competitive landscape between qualified suppliers and marginal entrants. Mondi Group leverages its integrated pulp-to-paper operations across Southern Africa to sustain cost advantages in recycled paperboard. Amcor Plc anchors its regional position through advanced barrier coating technologies that extend shelf life in hot-climate distribution. Napco National competes on localized production scale, with Saudi-based manufacturing controlling lead times for GCC food exporters.
Eco-friendly packaging comprises containers, wraps, and structural components manufactured from bioplastics, recycled fibers, or renewable feedstocks with specified biodegradability thresholds, designed to reduce environmental impact across collection, processing, and end-of-life phases. Recycled paper holds mature volume leadership due to established collection infrastructure, while bioplastics represent the fastest-expanding material category as petrochemical price volatility and composting facility investments alter total cost equations. Food and beverage applications dominate current offtake, though cosmetics brands are shifting toward plant-based inks and molded fiber formats to meet retailer sustainability scorecards.
South Africa's Department of Forestry, Fisheries and the Environment enforces extended producer responsibility regulations that obligate brand owners to fund collection and recycling systems, directly expanding demand for certified recyclable substrates. The UAE's Emirates Authority for Standardization and Metrology aligns Gulf technical regulations with EU REACH and F-Gas frameworks, raising compliance barriers for imported conventional plastics. Saudi Arabia's SFDA packaging material safety requirements intersect with SASO biodegradability labeling rules, creating dual-gatekeeping for market access. Stakeholders must monitor harmonization gaps between national standards and the African Continental Free Trade Area's emerging technical regulations to preempt certification misalignment.
Market Dynamics
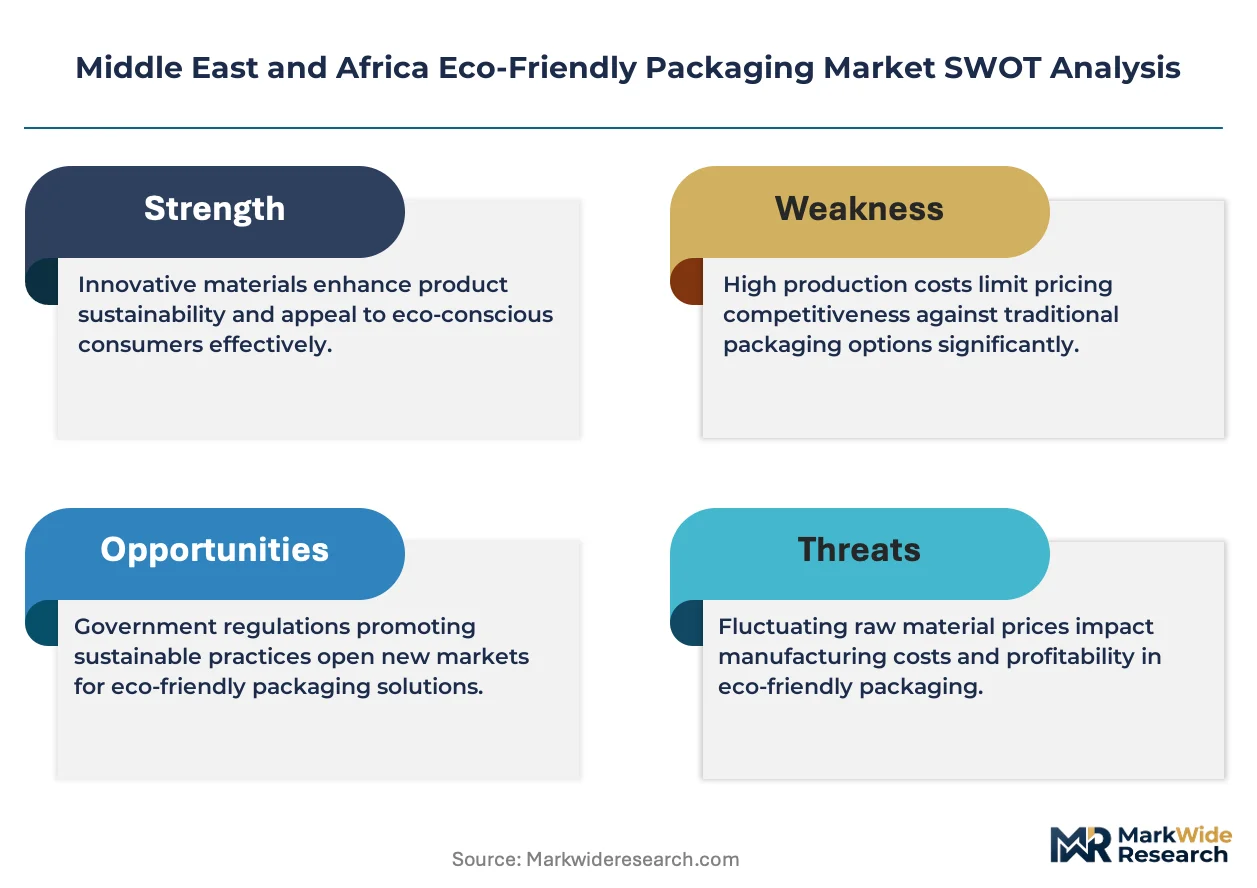
Extended producer responsibility frameworks across South Africa and Gulf Cooperation Council states are redirecting capital flows from virgin plastic infrastructure toward certified recyclable and biodegradable substrate production, compressing conventional packaging margins while elevating compliant suppliers.
Growth Catalysts
- Biodegradability mandates:Saudi Arabia's SFDA packaging material safety requirements intersect with SASO biodegradability labeling rules, creating dual-gatekeeping that accelerates demand for certified compostable food containers.
- Hot-climate distribution needs:Advanced barrier coating technologies that extend shelf life in arid conditions are pulling investment toward high-performance sustainable materials for beverage and dairy applications.
- Dubai procurement gravity:The emirate's packaging clusters function as the regional sourcing hub, concentrating buyer decision-making and standardizing sustainability specifications across GCC food exporters.
Market Restraints
- Composting infrastructure gaps:Industrial composting facility coverage remains sparse outside South Africa's Western Cape and UAE's industrial zones, limiting end-of-life viability for bioplastic packaging.
- Recycled fiber input volatility:Collection infrastructure inconsistencies across sub-Saharan African markets create supply uncertainty for paperboard manufacturers dependent on post-consumer waste streams.
- Petrochemical price anchoring:Conventional plastic resin costs in Saudi Arabia and UAE remain suppressed by regional feedstock advantages, compressing the total-cost gap with bioplastic alternatives.
Strategic Opportunities
- Nigeria's informal retail channel:Traditional open-air markets and neighborhood kiosks represent an underpenetrated vector for lightweight molded fiber containers replacing single-use plastic bags.
- Plant-based ink convergence:Cosmetics brands are integrating soy and algae-derived inks with molded fiber formats to meet retailer sustainability scorecards, opening premium positioning for integrated solution providers.
- AfCFTA technical alignment:The African Continental Free Trade Area's emerging packaging standards create a window for early movers to shape harmonized certification requirements across 54 member states.
Industry Challenges
- ISO 14001 auditor scarcity:Certified environmental management system implementation faces bottlenecks due to limited accredited third-party verification capacity across the Middle East and North Africa.
- Legacy equipment retrofit costs:Converting existing extrusion and thermoforming lines for bioplastic processing requires substantial capital outlay that mid-scale converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Eco-Friendly Packaging Market |
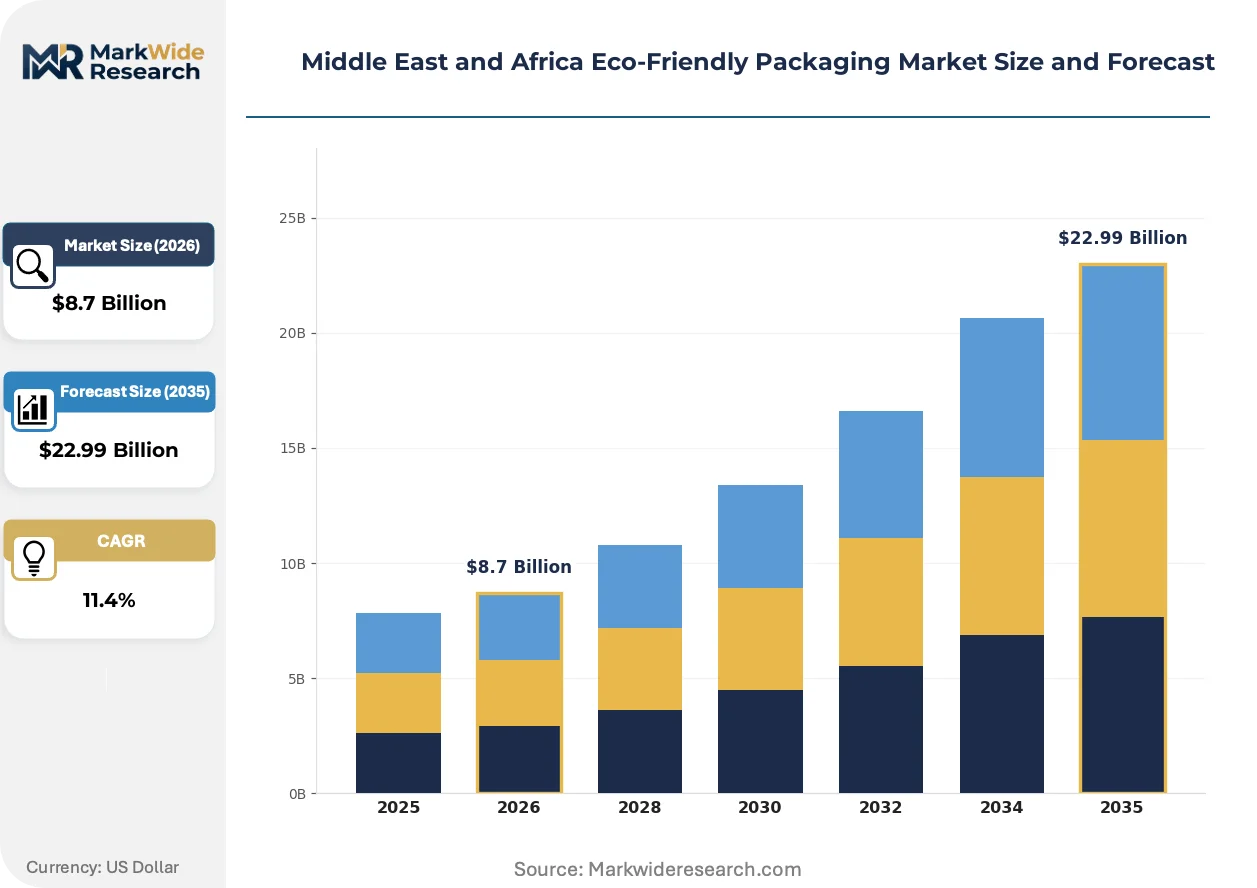
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Bioplastics, Recycled Paper, Glass, Plant-based Inks Product Type: Bags, Containers, Boxes, Wraps Application: Food & Beverage, Cosmetics, Consumer Goods, Electronics Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Mondi Group, Amcor Plc, Huhtamaki, Napco National, Sealed Air Corporation, Tetra Pak, ENPI Group, Hotpack Packaging Industries LLC, Silver Corner Packaging, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Eco-Friendly Packaging Market Shifts & Advancements
Active barrier technologies and substrate miniaturization are compressing material intensity per package while regulatory alignment with EU frameworks is elevating compliance complexity. Procurement patterns are consolidating around integrated pulp-to-converter operations that control traceability documentation.
Thin-wall molded fiber technology is miniaturizing structural components for electronics and cosmetics secondary packaging. Premium beauty brands in the UAE and Saudi Arabia are adopting these formats for unboxing experiences. The shift is miniaturizing shipping cube requirements and reducing dimensional weight charges for e-commerce fulfillment.
The UAE's Emirates Authority for Standardization and Metrology is aligning Gulf technical regulations with EU REACH and F-Gas frameworks. This convergence is raising import barriers for conventional plastic packaging from Asian manufacturing hubs. Food and beverage exporters targeting Dubai's re-export channels are reformulating specifications to meet the elevated compliance threshold.
Consolidated procurement through Dubai's packaging clusters is displacing fragmented national distributor networks. Major GCC retailers are mandating direct supplier relationships with certified converters to secure chain-of-custody documentation. The pattern is most visible in Saudi Arabia's hypermarket sector, where centralized buying desks now specify batch-level biodegradability certification.
Middle East and Africa Eco-Friendly Packaging Market Segmentation
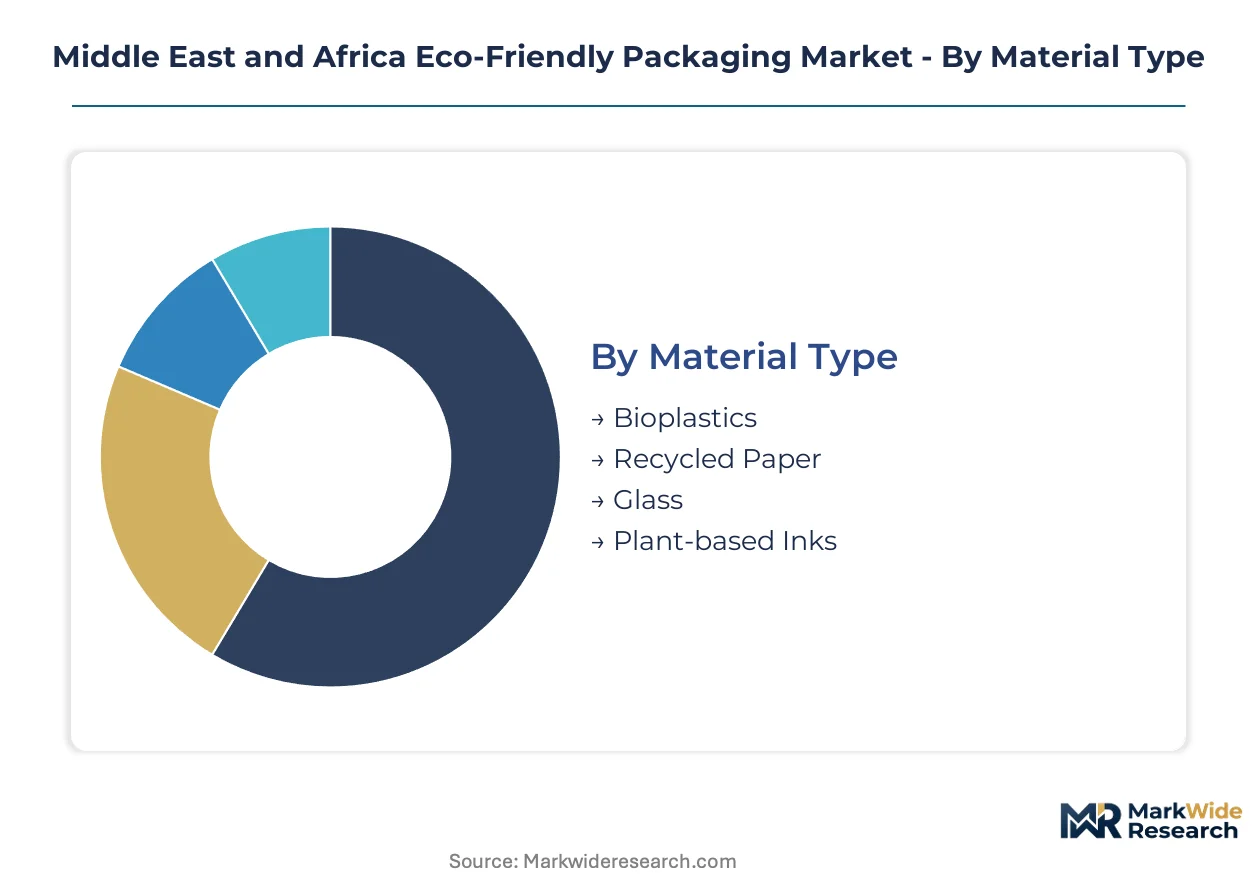
Segmentation in this market reveals divergent supply chain architectures. Export-oriented segments cluster around Dubai's procurement hubs, while domestic consumption patterns drive localized production investments across South Africa and Saudi Arabia.
Material Type:
Recycled paper dominates domestic production capacity across South Africa and Egypt, while bioplastics concentrate in UAE and Saudi import channels serving GCC food exporters.
- Bioplastics:Polylactic acid and polyhydroxyalkanoate formulations engineered for industrial composting conditions. Demand concentrates in UAE foodservice chains supplying Dubai's hospitality sector, where SASO biodegradability certification gates market access.
- Recycled Paper:Post-consumer fiber processed to ISO 14001 standards with specified contamination thresholds. South Africa's Western Cape collection infrastructure anchors regional supply, though sub-Saharan input volatility constrains expansion.
- Glass:Returnable bottle systems retain share in Lebanese and Egyptian beverage markets.
- Plant-based Inks:Soy and algae-derived formulations penetrate UAE cosmetics labeling requirements.
Recycled paper commands the established base. The steepest expansion runs through bioplastics.
Product Type:
Cost-tier differentiation separates commodity formats from performance-engineered solutions, with premium barrier-coated containers capturing margin in hot-climate distribution.
- Containers:Molded fiber and bioplastic vessels with active barrier coatings extending shelf life in arid conditions. Saudi dairy and beverage exporters specify these for Dubai re-export channels facing Emirates Authority for Standardization and Metrology compliance.
- Boxes:Corrugated formats with recycled content certification dominate South African agricultural export packaging.
- Bags:Lightweight molded fiber alternatives target Nigeria's informal retail channel replacing polyethylene.
- Wraps:Compostable films gain traction in UAE hypermarket private-label specifications.
Boxes anchor volume throughput. Containers are climbing the fastest.
Application:
Customer-type concentration shows food and beverage procurement consolidating through centralized GCC buying desks, while cosmetics specifications fragment across premium beauty brands.
- Food & Beverage:Biodegradable primary packaging for ambient and chilled distribution. Dubai's packaging clusters standardize sustainability specifications across Saudi and UAE hypermarket chains requiring batch-level certification.
- Cosmetics:Molded fiber secondary packaging with plant-based inks for unboxing experiences. UAE and Saudi premium brands adopt these formats to meet retailer sustainability scorecards.
- Consumer Goods:Recycled paperboard for household products faces price pressure from conventional plastics.
- Electronics:Thin-wall molded fiber miniaturizes shipping cube requirements for e-commerce fulfillment from South African distribution centers.
Food and beverage commands the established base. Cosmetics is gaining share fastest.
Distribution Channel:
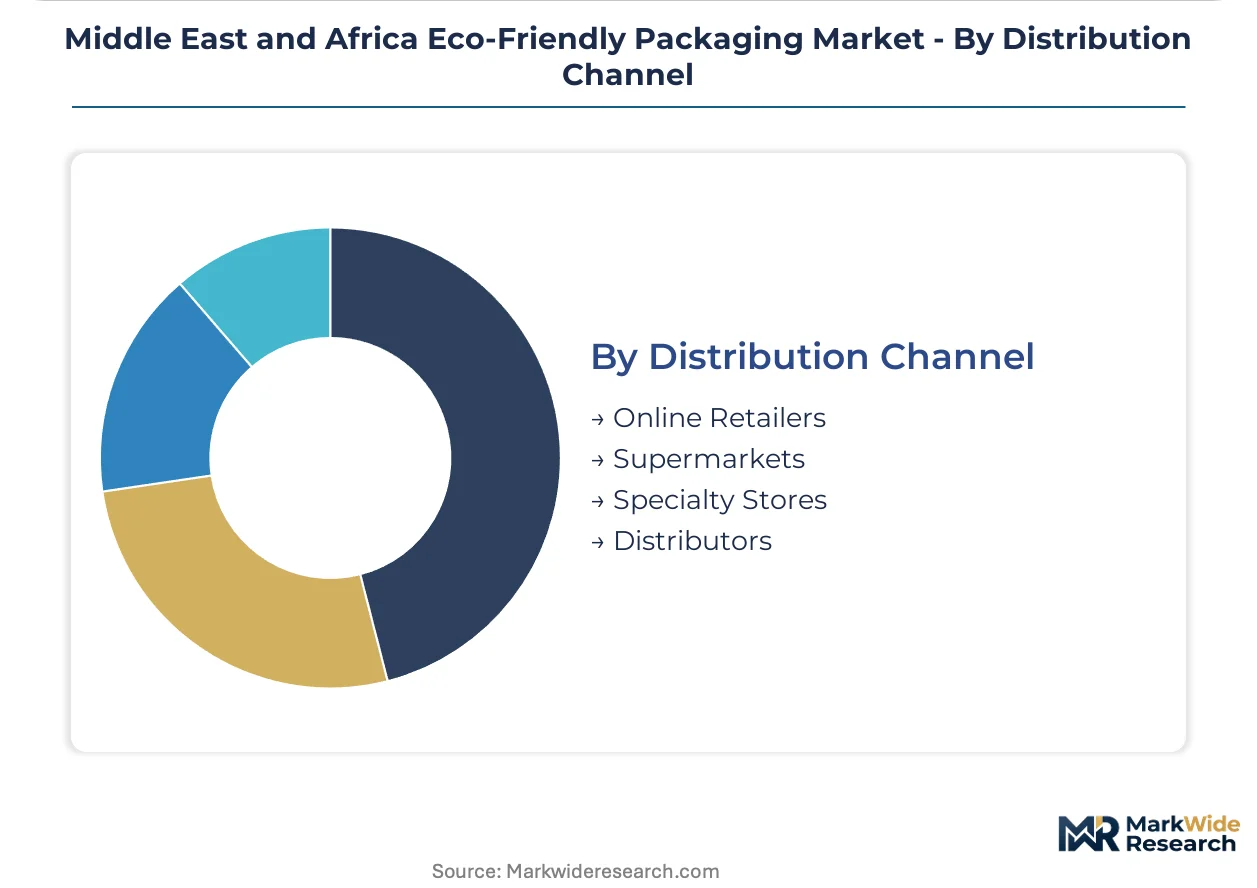
Supply concentration in Dubai's converter clusters is displacing fragmented national distributor networks across the GCC.
- Supermarkets:Centralized procurement desks in Saudi Arabia's hypermarket sector mandate direct supplier relationships with certified converters.
- Distributors:Legacy networks retain relevance in sub-Saharan markets lacking compliance infrastructure.
- Online Retailers:E-commerce platforms specify dimensional weight-optimized formats for last-mile delivery.
- Specialty Stores:Niche organic and premium retailers drive small-batch compostable packaging demand in South Africa's Western Cape.
Distributors anchor legacy volume. Supermarkets are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement desks at Saudi hypermarket chains and UAE hospitality groups concentrate buying power for certified sustainable packaging. Dubai's converter clusters standardize specifications across Gulf Cooperation Council food exporters. South African brand owners fund collection infrastructure under extended producer responsibility mandates.
United Arab Emirates
Dubai's packaging clusters serve as the regional sourcing hub for GCC food exporters requiring Emirates Authority for Standardization and Metrology compliance. The emirate's alignment with EU REACH and F-Gas frameworks raises technical barriers for imported conventional plastics. Jebel Ali industrial zones concentrate advanced barrier coating operations serving hot-climate beverage distribution.
Saudi Arabia
SFDA packaging material safety requirements intersect with SASO biodegradability labeling rules to create dual-gatekeeping for food container market access. Centralized procurement desks at hypermarket chains mandate direct supplier relationships with certified converters. Riyadh-based manufacturing anchors lead time advantages for dairy exporters targeting Dubai re-export channels.
South Africa
The Department of Forestry, Fisheries and the Environment enforces extended producer responsibility regulations that obligate brand owners to fund collection and recycling systems. Western Cape collection infrastructure anchors regional recycled fiber supply for paperboard manufacturers. Cape Town industrial zones concentrate ISO 14001-certified production serving agricultural export packaging.
Egypt
Returnable glass bottle systems retain structural share in beverage markets despite bioplastic expansion. National technical regulations for packaging safety create compliance entry barriers for imported substrates. Cairo-Alexandria corridor manufacturing serves domestic food processors with recycled content corrugated formats.
Nigeria
Traditional open-air markets and neighborhood kiosks represent underpenetrated demand for lightweight molded fiber containers replacing single-use polyethylene bags. Absence of industrial composting infrastructure outside Lagos and Abuja limits bioplastic end-of-life viability. Lagos-based distributors retain relevance in compliance-scarce retail channels.
Middle East and Africa Eco-Friendly Packaging Market Competitive Landscape
Player mix skews toward integrated pulp-to-paper operators and specialized barrier technology developers. Market structure shows moderate consolidation around Dubai procurement gravity with fragmented sub-Saharan supply. Three archetypes dominate: integrated fiber processors controlling traceability documentation, barrier coating specialists serving hot-climate distribution, and localized converters optimizing GCC lead times. Competitive moves concentrate on backward integration into recycled fiber collection and strategic partnerships with hospitality procurement desks.
Among integrated paperboard producers, Mondi Group and Amcor Plc occupy positions exemplifying scale-driven fiber control and advanced coating capabilities respectively. Napco National represents the localized production archetype with Saudi-based manufacturing. These three anchors illustrate how geographic positioning relative to Dubai procurement clusters and Riyadh regulatory gates determines competitive access rather than technology differentiation alone.
| Leading Market Players |
|---|
| Mondi Group |
| Amcor Plc |
| Huhtamaki |
| Napco National |
| Sealed Air Corporation |
| Tetra Pak |
| ENPI Group |
| Hotpack Packaging Industries LLC |
| Silver Corner Packaging |
| Others |
Supply & Pricing Matrix
SASO biodegradability labeling rules gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified converters while elevating compliant producers to premium tiers. Buyers face tiered cost structures where certification investment translates directly into procurement access across Saudi Arabia's hypermarket centralized buying desks.
Pricing Analysis
Cost-plus contracts with recycled fiber indexation dominate long-term agreements between South African paperboard mills and GCC food exporters. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified integrated producers from regional converters lacking chain-of-custody documentation. Pricing pressure stems from petrochemical price anchoring in Saudi Arabia and UAE, where regional feedstock advantages suppress conventional plastic resin costs. Small-scale Nigerian distributors exhibit highest price sensitivity, while Dubai-based hospitality procurement desks prioritize certification compliance over unit cost.
Supply Chain Analysis
Inventory cycles stretch 6-8 weeks for bioplastic resin deliveries from European compounders to UAE converters, compressing lead-time flexibility for just-in-time Dubai re-export channels. Supply concentrates in South Africa's Western Cape recycled fiber collection infrastructure, UAE's Jebel Ali industrial zones for barrier coating operations, and Saudi Arabia's Riyadh-based dairy packaging manufacturing. Raw material dependencies center on post-consumer waste streams, polylactic acid resin imports, and soy-derived ink formulations. Single-source vulnerability runs through European bioplastic resin suppliers given sparse regional compounding capacity. Distribution runs through Dubai's packaging clusters displacing fragmented national distributor networks across the GCC.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Dubai's packaging clusters and Saudi hypermarket centralized procurement desks, fragmenting supplier negotiating leverage across fragmented sub-Saharan converter bases.
For Market Incumbents: Compound certification advantages by backward integration into Western Cape recycled fiber collection and UAE composting facility partnerships. Barrier coating technology leadership at Amcor Plc and Mondi Group faces substitution threat from emerging PHA resin formulations with superior hot-climate performance. Prioritize SASO pre-certification of production batches to defend access at Saudi hypermarket buying desks. For New Entrants and Emerging Players: Post-consumer waste collection infrastructure gaps in Nigeria's informal retail channel represent the most penetrable white-space target. Lightweight molded fiber containers for open-air markets bypass industrial composting dependency that limits bioplastic viability. Go-to-market angle: direct distributor partnerships in Lagos bypassing compliance-scarce legacy networks. For Investors and Strategic Acquirers: AfCFTA technical alignment reshapes the acquisition landscape by elevating ISO 14001-certified producers with multi-country regulatory navigation capabilities. Long-term viability favors integrated pulp-to-converter operations controlling traceability documentation across the analysis window. Target acquisition archetype: mid-scale UAE barrier coating specialists with established Dubai cluster positioning. Signal to watch: harmonization gaps between national standards and AfCFTA emerging technical regulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | Western Cape fiber control secures post-consumer waste supply for Mondi Group's recycled paperboard expansion. |
| Barrier Coating Technology Licensing | Amcor Plc's hot-climate shelf-life extension patents differentiate UAE beverage export packaging specifications. |
| SASO Pre-Certification Investment | Napco National's Saudi-based manufacturing accelerates lead times for SFDA-compliant food container batches. |
| Composting Facility Joint Venture | UAE industrial zone partnerships address end-of-life infrastructure gaps constraining bioplastic adoption. |
| Plant-Based Ink Formulation Partnership | Soy and algae-derived cosmetics labeling meets retailer sustainability scorecards for premium Saudi beauty brands. |
Research Methodology
Desk research of customs trade databases, SASO technical regulation filings, and Emirates Authority for Standardization and Metrology compliance directories preceded structured interviews with Dubai packaging cluster procurement managers, Saudi hypermarket category buyers, South African paperboard plant managers, and Nigerian distributor network operators. Bottom-up volume estimates triangulated against top-down regulatory mandate impact assessments.
Variance decomposition across material type, product format, application segment, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling against regulatory compliance cost curves. Industry-specific forecast inputs incorporated extended producer responsibility fee structures and composting facility capex pipelines.
Underlying assumptions cover sustained petrochemical feedstock cost advantages in GCC states and AfCFTA harmonization progress, with deviation risk concentrated in bioplastic resin import tariff shifts and industrial composting infrastructure buildout delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
North America Eco-Friendly Packaging Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Asia-Pacific Sustainable Packaging Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Global Paper Straw Market
Sustainable Packaging
Europe Eco-Friendly Packaging Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
GCC Green Packaging Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Compostable Tableware Market