
 Pulses Market | 2026-2036
Pulses Market Size, Share, and Industry Trends Forecast 2026-2036
Pulses Market Intelligence
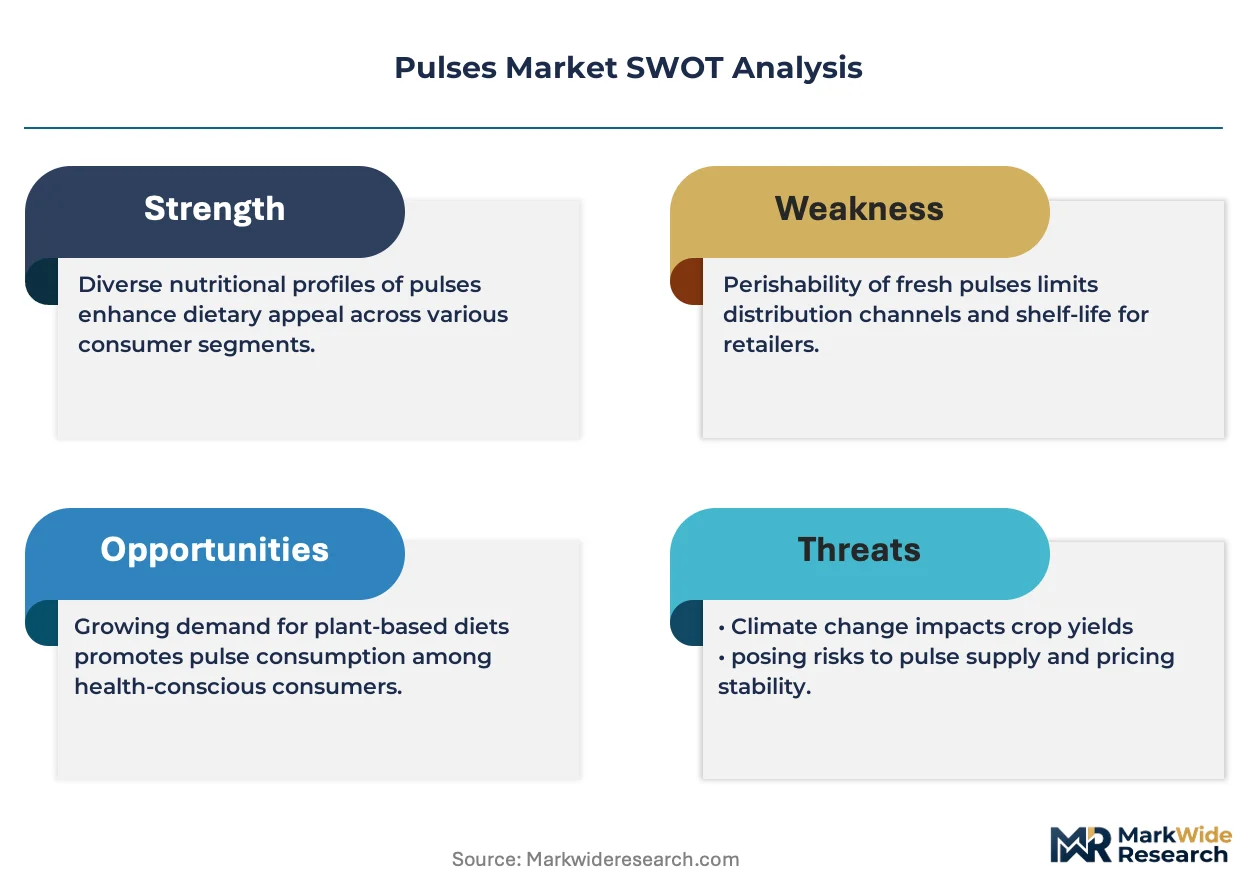
A shift from single-source to multi-source procurement is hardening across the pulses value chain. Cargill leverages its global origination network to secure diverse supply streams across multiple growing regions. AGT Food and Ingredients anchors North American processing capacity with vertically integrated cleaning and splitting facilities. Roquette Frères specializes in pea protein extraction, commanding premium positioning within the ingredient sector.
Pulses comprise dried seeds of leguminous crops—lentils, chickpeas, peas, and beans—typically containing 20-25% protein by dry weight and requiring nitrogen-fixing cultivation that reduces synthetic fertilizer dependence. Their primary commercial purpose spans direct food consumption, milled flour production, and protein isolate extraction for alternative meat formulations. Chickpeas lead volume within product type segments due to sustained Mediterranean and South Asian dietary integration, while pea-derived isolates capture the fastest expansion as dairy and meat analogues gain shelf space. Food industry end users concentrate margin pools through long-term supply agreements, whereas animal feed applications operate on thinner spreads tied to commodity grain pricing.
FDA food safety standards govern pulse imports into the United States, enforcing mycotoxin limits and labeling requirements that determine market access eligibility. EU Green Deal agricultural targets and EFSA novel food assessments shape European demand for sustainably sourced pulse ingredients. India's FSSAI fortification mandates and PLI scheme incentives for food processing infrastructure direct domestic investment flows. Stakeholders must monitor how carbon border adjustment mechanisms and evolving protein content certification standards reshape competitive sourcing decisions.
Market Dynamics
Plant-based protein adoption is restructuring procurement patterns across the pulses value chain, forcing processors to secure long-term supply agreements with origination networks spanning multiple hemispheres.
Growth Catalysts
- EU Green Deal agricultural targets:Sustainability mandates in the European Union are redirecting crop subsidies toward nitrogen-fixing cultivation, expanding contract farming for pulse ingredients.
- Pea protein extraction technology:Wet-fractionation advances are lowering isolate production costs, enabling alternative meat formulators to substitute soy and dairy proteins at scale.
- India:Government-backed food security programs and PLI scheme incentives for processing infrastructure are accelerating domestic consumption and value-added manufacturing capacity.
Market Restraints
- Input cost volatility:Synthetic fertilizer price swings and irrigation energy costs expose non-vertically integrated growers to margin compression during drought cycles.
- Supply concentration risk:Black Sea region origination dominance for certain lentil varieties creates single-point vulnerability to trade route disruptions.
- FDA mycotoxin limits:Strict aflatoxin and ochratoxin thresholds for US pulse imports disqualify substantial harvest volumes from emerging suppliers, constraining eligible origin zones.
Strategic Opportunities
- Underpenetrated African processing:Ethiopia and Tanzania possess expanding cultivation bases with minimal domestic splitting and fractionation infrastructure, offering first-mover positioning for integrated operators.
- Carbon border adjustment mechanisms:Upcoming EU carbon tariffs on imported agricultural goods will favor low-emission pulse proteins against carbon-intensive animal feed alternatives.
- Direct-to-manufacturer digital platforms:Blockchain-traceable procurement marketplaces are collapsing traditional broker layers, allowing food manufacturers to contract directly with certified grower cooperatives.
Industry Challenges
- Specialized agronomy talent scarcity:Pulse-specific crop rotation expertise and biological nitrogen fixation management skills lag behind row-crop farming knowledge pools.
- Fractionation capex intensity:Commercial-scale pea protein isolate facilities require substantial capital deployment for wet-processing equipment and wastewater treatment systems.
- Novel food authorization timelines:EFSA assessments for emerging pulse-derived ingredients extend commercialization cycles, delaying revenue recognition for innovative fractionation outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulses Market |
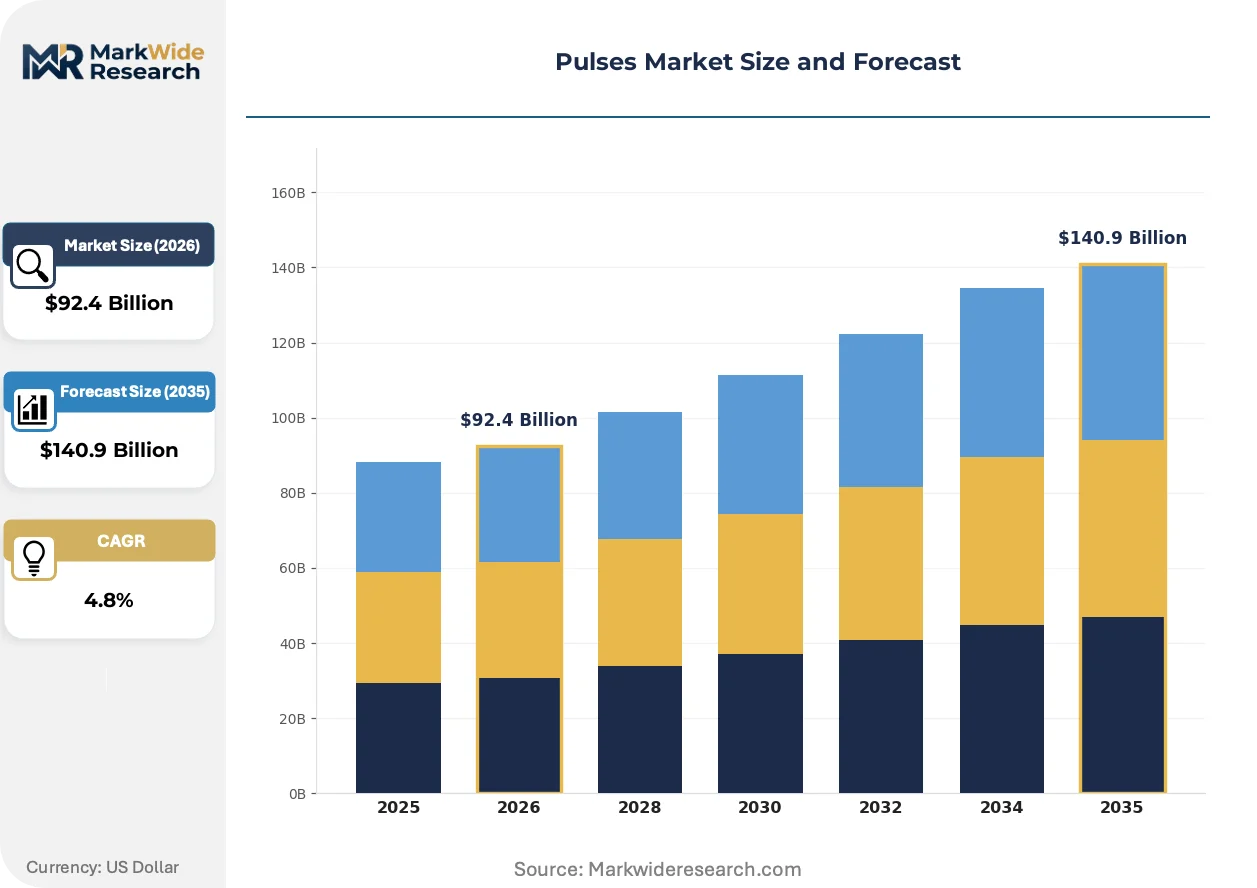
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $140.9 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lentils, Chickpeas, Peas, Beans End User: Food Industry, Animal Feed, Nutraceuticals, Organic Farming Distribution Channel: Supermarkets, Online Retail, Wholesale, Direct Sales Packaging Type: Bags, Bulk Containers, Cans, Vacuum Sealed |
| Companies Covered | Ingredion, Emsland Group, Cargill, Puris, The Scoular Company, Archer Daniels Midland (ADM), AGT Food and Ingredients, Axiom Foods, Roquette Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulses Market Strategic Shifts & Innovations
Processing technology and traceability systems are converging to compress supply chain layers, altering how ingredient buyers source and validate pulse-derived inputs.
Dry-fractionation equipment paired with near-infrared spectroscopy is decentralizing protein concentration validation away from centralized laboratories. Mid-sized processors in Canada and Australia are adopting portable quality-assessment units to certify batches at collection points. This capability is compressing the time between harvest and contract settlement, reducing working capital requirements for regional aggregators.
REACH chemical safety registrations and evolving EU Green Deal farm-to-fork metrics are tightening residue monitoring for imported pulse ingredients. European food manufacturers now require comprehensive pesticide and heavy metal documentation before contract execution. Pulse exporters to the EU are responding by investing in third-party certified storage and transport infrastructure to maintain market access eligibility.
Long-term offtake agreements are displacing spot-market purchasing among alternative protein startups and established food conglomerates. Buyers are locking in multi-year supply contracts with named-origin clauses to secure volume certainty and ESG credentialing. This contracting pattern is most pronounced in North American and European markets where sustainability disclosure requirements pressure supply chain transparency.
Pulses Market Segmentation
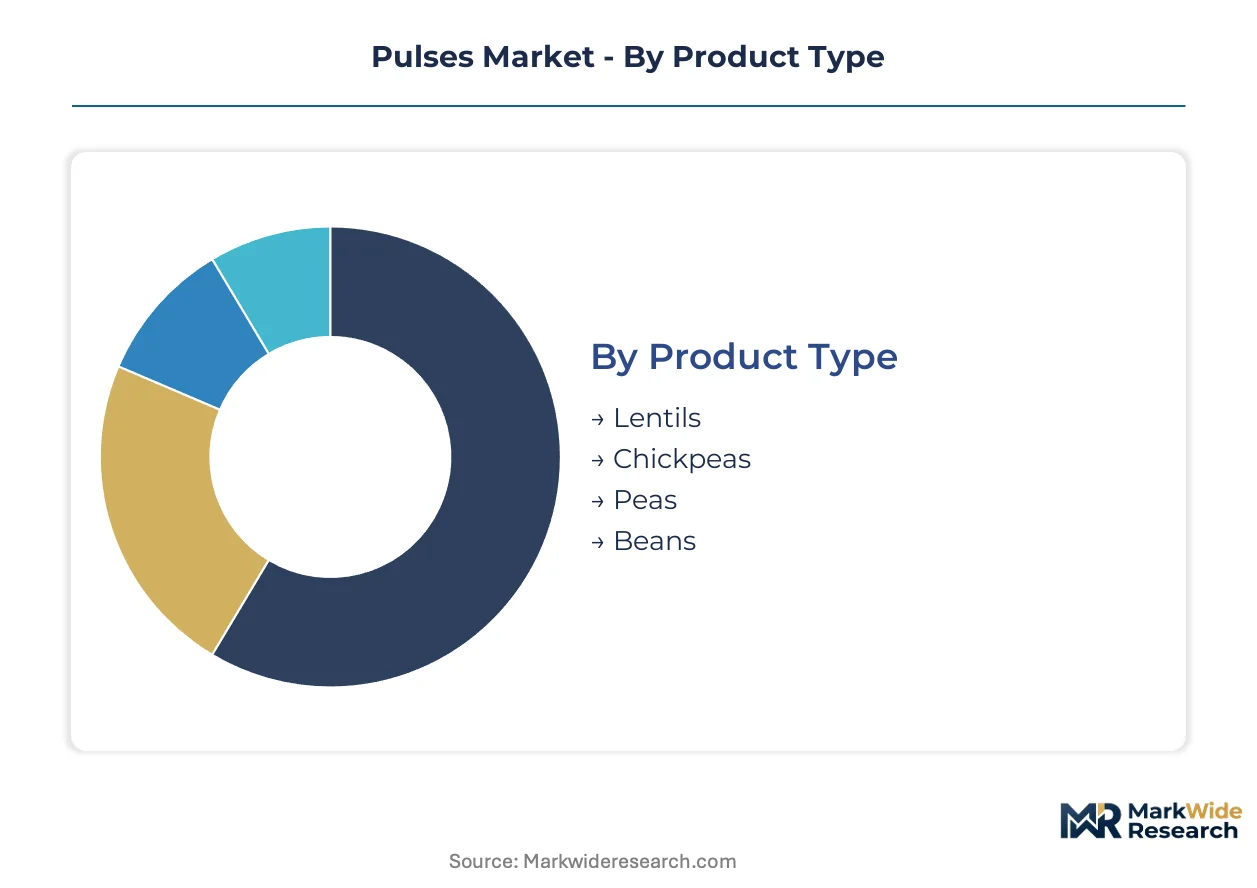
Pulse processors configure equipment lines around specific seed morphology and protein recovery targets. Segmentation discipline separates commodity bulk flows from premium ingredient streams, determining margin capture and capital allocation priorities.
Product Type:
Capital intensity varies sharply across processing configurations, with protein isolate extraction demanding wet-fractionation infrastructure that exceeds dry-cleaning and splitting facilities by an order of magnitude.
- Chickpeas:Larger seed size and higher starch content relative to other pulses necessitate specialized dehulling and splitting machinery. Mediterranean and South Asian food manufacturers absorb the dominant volume for hummus production and flour milling, though protein isolate extraction from chickpeas lags pea fractionation in commercial scale.
- Peas:Yellow and green pea varieties contain protein concentrations optimized for wet-fractionation into isolates and concentrates. North American and European alternative meat formulators are locking in long-term offtake agreements for pea-derived ingredients as dairy and meat analogues displace soy formulations.
- Lentils:Red and green varieties require precision color-sorting technology to meet export grade standards. Indian dal processors and Canadian exporters dominate trade flows, with minimal value-added fractionation relative to pea and chickpea streams.
- Beans:Kidney, black, and navy bean varieties serve predominantly whole-seed and canned applications with lower processing intensity. Central American and Brazilian origin zones supply North American canneries under seasonal contracting patterns.
Chickpeas absorb the bulk of installed splitting and dehulling capacity; pea-derived isolates are expanding most quickly.
End User:
Margin structure diverges sharply between formulated food applications and commodity feed channels, with protein isolate contracts commanding premium pricing over whole-seed bulk sales.
- Food Industry:Bakeries, snack manufacturers, and alternative protein formulators drive specification-grade demand for milled flours, protein concentrates, and texturized ingredients. EU Green Deal sustainability disclosure requirements are pressuring food conglomerates toward certified-origin pulse sourcing with comprehensive carbon accounting.
- Nutraceuticals:Protein isolates and fiber extracts target sports nutrition and clinical dietary applications with stringent purity standards. EFSA novel food assessments govern ingredient authorization timelines for emerging pulse-derived bioactives.
- Animal Feed:Pulse byproducts and lower-grade whole seeds compete with oilseed meals on protein content and price. Pricing ties directly to soybean meal futures, compressing processor margins during commodity volatility cycles.
- Organic Farming:Whole seed demand for cover crop and green manure applications operates outside food-grade certification requirements. Premium pricing reflects organic cultivation compliance rather than processing value-add.
Food industry offtake anchors revenue stability; nutraceutical applications are gaining share fastest.
Distribution Channel:
Channel selection determines working capital intensity and traceability compliance burden, with direct sales to manufacturers collapsing traditional broker layers.
- Wholesale:Aggregators and commodity traders handle bulk volumes from origin to processor, absorbing price risk and quality variability. Black Sea and Canadian prairie origination zones flow predominantly through this channel.
- Direct Sales:Long-term supply agreements between processors and food manufacturers specify origin, protein content, and sustainability credentials. Blockchain-traceable platforms are accelerating direct contracting by certified grower cooperatives.
- Supermarkets:Packaged whole seeds and canned pulse products reach consumers through retail grocery networks. Private-label expansion is compressing branded shelf space in North American and European markets.
- Online Retail:Specialty and organic pulse products target health-conscious consumers through direct-to-subscription models. Indian e-grocery platforms are expanding packaged pulse delivery to tier-2 and tier-3 cities.
Wholesale channels handle volume concentration; direct sales are climbing the fastest.
Packaging Type:
Packaging configuration signals value tier and shelf-life requirements, with vacuum and canning infrastructure representing distinct capital deployment decisions.
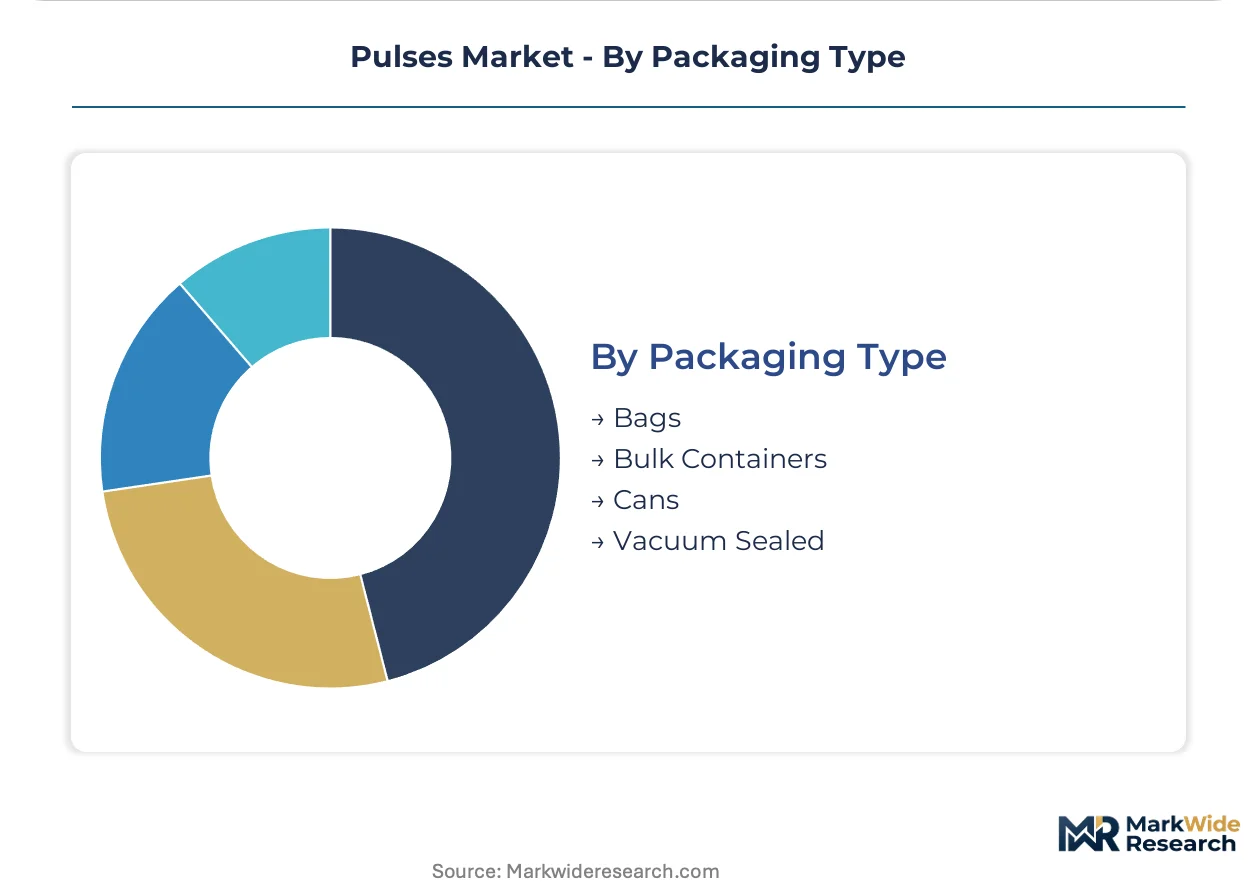
- Bulk Containers:Flexible intermediate bulk containers and rail hopper cars move commodity-grade whole seeds from origin to processing facilities. Canadian and Australian export terminals specialize in bulk handling infrastructure for containerized ocean freight.
- Vacuum Sealed:Modified atmosphere packaging extends shelf life for premium whole seeds and protein ingredients requiring oxidation protection. European organic pulse distributors specify vacuum protocols to maintain certification integrity.
- Bags:Woven polypropylene and paper sacks serve retail and foodservice whole-seed distribution. Indian domestic markets rely heavily on 25-50kg bag formats for institutional procurement.
- Cans:Retort processing for ready-to-eat beans requires specialized canning lines with thermal treatment validation. North American canneries concentrate in Minnesota and North Dakota near pea and navy bean cultivation zones.
Bulk containers absorb the dominant logistics volume; vacuum-sealed formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the dominant demand share through government-backed food security programs and expanding domestic processing capacity. Supply origination networks span Saskatchewan prairie farms, Black Sea cultivation belts, and Australian grain corridors.
United States
Alternative meat formulators in Minneapolis and Chicago drive pea protein isolate demand through long-term offtake agreements. FDA mycotoxin limits enforce strict aflatoxin thresholds on imported lentils and chickpeas. North Dakota and Montana host concentrated splitting and dehulling infrastructure serving domestic canneries.
Canada
Saskatchewan prairie farms supply the dominant export volume of lentils and peas to Indian dal processors and European ingredient buyers. Canadian Grain Commission grading standards determine international contract eligibility. Winnipeg and Regina anchor North American pulse trading and quality certification infrastructure.
India
FSSAI fortification mandates and PLI scheme incentives accelerate domestic value-added processing capacity expansion. Government procurement through MSP operations concentrates lentil and chickpea consumption in food security distribution networks. Indore and Jalgaon house India's largest dal milling and splitting clusters.
Australia
Winter pulse cultivation in New South Wales and Victoria supplies premium-grade chickpeas to South Asian and Middle Eastern markets. Biosecurity export protocols govern phytosanitary certification for international shipment. Port Adelaide and Melbourne terminals specialize in containerized bulk handling for Asian destination markets.
Germany
EU Green Deal farm-to-fork targets redirect crop subsidies toward nitrogen-fixing cultivation systems. EFSA novel food assessments govern authorization timelines for emerging pulse-derived ingredients. Hamburg and Bremen port infrastructure handles Black Sea and North American pulse import flows for Central European processing.
Pulses Market Key Industry Players
Long-term supply agreement contracting dominates the current landscape as alternative protein formulators lock in multi-year offtake commitments. The vendor base organizes around three strategic archetypes: global trading houses with origination networks, regional processors with splitting infrastructure, and specialized fractionators targeting ingredient markets. Competitive positioning hinges on securing named-origin supply streams and achieving carbon accounting transparency for EU sustainability disclosure requirements.
Among North American processors, AGT Food and Ingredients and The Scoular Company exemplify the regional infrastructure archetype with vertically integrated cleaning and splitting capabilities. Roquette Frères occupies the specialized fractionation tier, commanding premium positioning within pea protein isolate extraction. Cargill represents the global trading house model, leveraging hemispheric origination networks to secure diverse supply streams across multiple growing regions.
| Leading Market Players |
|---|
| Ingredion |
| Emsland Group |
| Cargill |
| Puris |
| The Scoular Company |
| Archer Daniels Midland (ADM) |
| AGT Food and Ingredients |
| Axiom Foods |
| Roquette Frères |
| Others |
Cost & Logistics Intelligence
Backward integration into origination networks anchors pricing power for pulse processors, allowing Roquette Frères and AGT Food and Ingredients to lock in named-origin supply streams that command premium positioning against spot-market competitors. This upstream control buffers margin compression during drought cycles while securing ESG credentialing required by EU Green Deal disclosure mandates.
Pricing Analysis
Certification bundling separates contract-grade pulse ingredients from commodity bulk sales, with EFSA novel food authorization and carbon accounting documentation included in premium tier quotes. Three-tier pricing structure across premium, standard, and economy levels tracks protein concentration thresholds and organic cultivation compliance. Price differentiation hinges on wet-fractionation capability and blockchain traceability infrastructure. Cost compression in standard-grade whole seeds is intensifying because Black Sea supply concentration exposes buyers to trade route volatility. Animal feed processors exhibit highest price sensitivity due to soybean meal futures linkage, while alternative meat formulators accept premium spreads for isolate supply security.
Supply Chain Analysis
Direct-to-manufacturer channels handle specification-grade isolate demand from North American and European alternative protein formulators, collapsing traditional broker layers through blockchain-traceable platforms. Supply concentrates in Saskatchewan prairie farms, Black Sea cultivation belts, and Australian grain corridors for lentil and pea origination. Raw material flows draw from nitrogen-fixing cultivation systems, synthetic fertilizer inputs, and irrigation energy infrastructure. Single-source vulnerability in Black Sea lentil varieties creates disruption exposure to trade route blockades. Distribution runs through Winnipeg and Regina trading hubs for Canadian export flows, Hamburg and Bremen for European import processing, and Indore and Jalgaon for Indian domestic dal milling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pulse market positioning is becoming a vertical-integration race, with fractionation capex deployment and captive origination networks serving as the decisive levers separating premium ingredient suppliers from commodity traders.
For Market Incumbents: Anchor margin defense through wet-fractionation capacity additions in Saskatchewan and Manitoba, securing captive supply against Roquette Frères' pea protein dominance. Lock in multi-year offtake agreements with named-origin clauses before carbon border adjustment mechanisms reshape EU import economics. Invest in third-party certified storage infrastructure to maintain REACH compliance eligibility for European market access. For New Entrants and Emerging Players: Enter via underpenetrated African processing infrastructure in Ethiopia and Tanzania, where expanding cultivation bases lack domestic splitting and fractionation capacity. Target East African origination zones with mobile dry-fractionation units paired with near-infrared spectroscopy validation. Pursue direct contracting with certified grower cooperatives through digital procurement platforms, bypassing established wholesale aggregators. For Investors and Strategic Acquirers: Exit pathways concentrate in specialized fractionation assets with EFSA novel food dossiers and locked-in alternative meat offtake agreements. Long-term viability favors processors with demonstrated carbon accounting transparency and multi-hemisphere origination diversification. Watch for EU carbon tariff implementation timelines as inflection indicators for low-emission pulse protein valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination Networks | Cargill leverages hemispheric farm partnerships to secure named-origin supply streams against Black Sea concentration risk. |
| Wet-Fractionation Capacity Expansion | Roquette Frères commands premium isolate positioning through proprietary extraction technology serving alternative meat formulators. |
| Blockchain-Traceable Procurement Platforms | Direct manufacturer-grower contracting collapses broker layers while satisfying EU Green Deal sustainability disclosure requirements. |
| EFSA Novel Food Dossier Investment | Authorization timelines for emerging pulse-derived ingredients determine commercialization cycles and revenue recognition schedules. |
| Third-Party Certified Storage Infrastructure | REACH residue compliance and organic certification integrity depend on validated transport and warehousing protocols. |
Research Approach
Multi-period observation of pea protein isolate contract volumes, EU Green Deal subsidy redirection patterns, and Indian PLI scheme infrastructure deployment anchored the trend analysis, supplemented by interviews with pulse processing plant managers, procurement leads at alternative protein formulators, distribution channel partners in Canadian prairie trading hubs, and technical R&D directors at fractionation equipment suppliers. Secondary validation drew from Canadian Grain Commission grading standards, FSSAI fortification mandate filings, EFSA novel food assessment databases, and customs trade flow records. Bottom-up facility capacity modeling and top-down demand segmentation triangulation ensured cross-verification.
Segment-weighting across product type, end user, distribution channel, and packaging format dimensions shaped the analytical framework over the projection horizon. CAGRs were derived through trend extrapolation of plant-based protein adoption rates and nitrogen-fixing cultivation subsidy trajectories. Modeled inputs included FDA mycotoxin threshold enforcement patterns, synthetic fertilizer price volatility cycles, and carbon border adjustment mechanism implementation progress.
Revisions become necessary when EU carbon tariff schedules accelerate, Black Sea trade routes experience sustained disruption, or wet-fractionation technology costs shift materially. Forecasts reflect documented assumptions regarding pea protein substitution rates for soy and dairy formulations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Basmati Rice Market
Grains
GMO Corn Market
Grains
Gluten Feed Market
Grains
Dried Spent Grain Market
Grains
Corn Silage Market
Grains
Non-Basmati Rice Market
Grains
Spelt Wheat Market
Grains
Argentina Maize Market
Grains
Rye Market
Grains
Oat Flour Market
Grains
United States Maize Market
Grains
Grain Augers Market
Grains
Rice Flour Market
Grains
Heritage Grain Market
Grains
Uganda Grains Market
Grains
Organic Cereals Market