
 Colombia Grains Market | 2026-2036
Colombia Grains Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Grains Market Outlook
Multi-source grain procurement is realigning how Colombian millers and feed compounders manage supply risk. RIOPAILA AGRICOLA S A anchors its position through backward integration into seed development and commercial farming across the Cauca Valley. The Grupo Daabon differentiates via organic certification and sustainable cultivation protocols that command premium offtake from European buyers. Agropecuaria Aliar S.A. competes on geographic breadth, operating collection networks that extend into previously isolated Cordillera municipalities.
Colombia grains comprise cereal crops cultivated for human consumption, animal nutrition, and industrial processing, with moisture content, protein grade, and mycotoxin thresholds determining commercial suitability and end-use allocation. Dry milling dominates processing infrastructure, though wet milling capacity expands to serve starch and ethanol derivatives. Corn leads product type volume due to its centrality in poultry and swine feed formulations, while rice maintains structural importance through price stabilization mechanisms and consumer subsidy programs. Barley occupies a niche position serving craft brewing and malt import substitution, with margin pools concentrated in certified seed and specialty varieties.
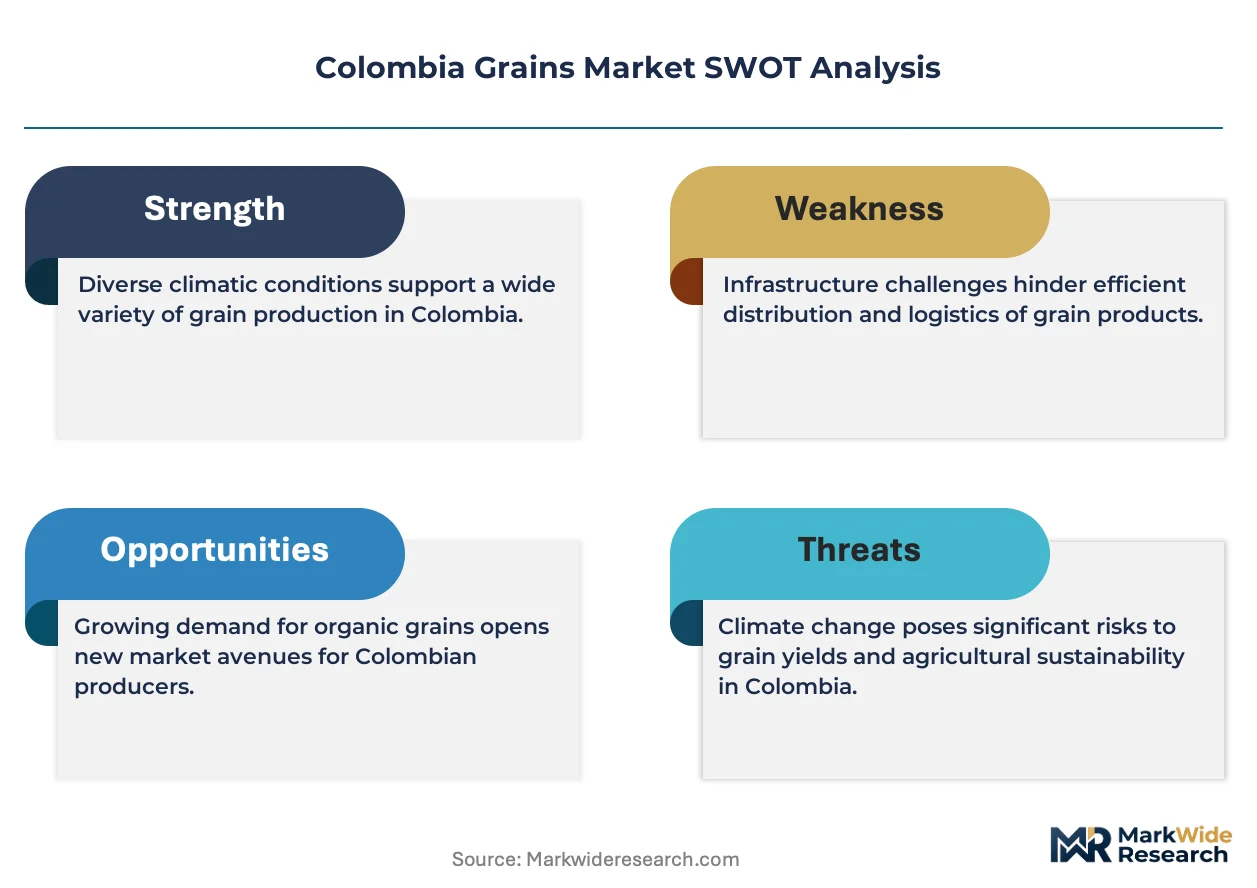
INVIMA enforces maximum residue limits and sanitary registration for grain-derived food products, while the Ministry of Agriculture and Rural Development administers phytosanitary protocols through ICA that govern seed certification and transboundary pest control. The national biofuel blending mandate, overseen by the Mining and Energy Planning Unit, structurally diverts corn toward ethanol production during surplus harvests. Stakeholders must monitor how climate volatility in the Magdalena River basin reshapes planting calendars and whether decentralized storage investments can reduce post-harvest losses that currently erode farmer margins.
Market Dynamics
Mechanized harvesting investment is displacing traditional smallholder production across Colombia's Altillanura plains, concentrating grain supply among capital-intensive commercial operators while ICA phytosanitary protocols raise compliance barriers for marginal producers.
Growth Catalysts
- Biofuel blending mandate:The Mining and Energy Planning Unit's ethanol diversion policy structurally absorbs corn surpluses during peak harvests, stabilizing processor offtake and incentivizing acreage expansion.
- Orinoquía livestock expansion:Animal feed processors in this eastern region are scaling compound feed operations, creating sustained pull for yellow corn and soybean meal imports.
- INVIMA residue protocols:Tightening maximum residue limits for grain-derived foods are accelerating certified seed adoption and traceability system investments among commercial farms.
Market Restraints
- Post-harvest loss concentration:Decentralized storage infrastructure gaps in Magdalena River basin municipalities erode farmer margins by 15-20% through moisture damage and pest infestation.
- Import dependency for soybean meal:Domestic oilseed crushing capacity constraints force feed compounders to source protein inputs from Argentine and Brazilian traders, exposing cost structures to currency volatility.
- Climate calendar compression:El Niño-Southern Oscillation disruptions are narrowing reliable planting windows in Córdoba and Sucre departments, increasing yield variance for rain-fed corn.
Strategic Opportunities
- Altillanura irrigation deficit:Pivot irrigation installation in Casanare and Meta provinces could double corn yields on currently rain-dependent hectares, attracting equipment financing from rural development funds.
- Organic certification premium:European buyer demand for pesticide-free grains creates margin pools for producers achieving EU organic equivalence through ICA-accredited certifiers.
- Wet milling capacity expansion:Starch and ethanol derivative processing investments in Valle del Cauca offer corn growers alternative outlets beyond dry milling and feed channels.
Industry Challenges
- Agronomic technician scarcity:Precision agriculture deployment in commercial operations outpaces trained personnel supply from Colombian agricultural universities, constraining technology adoption rates.
- ICA certification timelines:Seed variety registration and phytosanitary clearance delays of 18-24 months slow genetic improvement cycles for climate-adaptive corn hybrids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Grains Market |
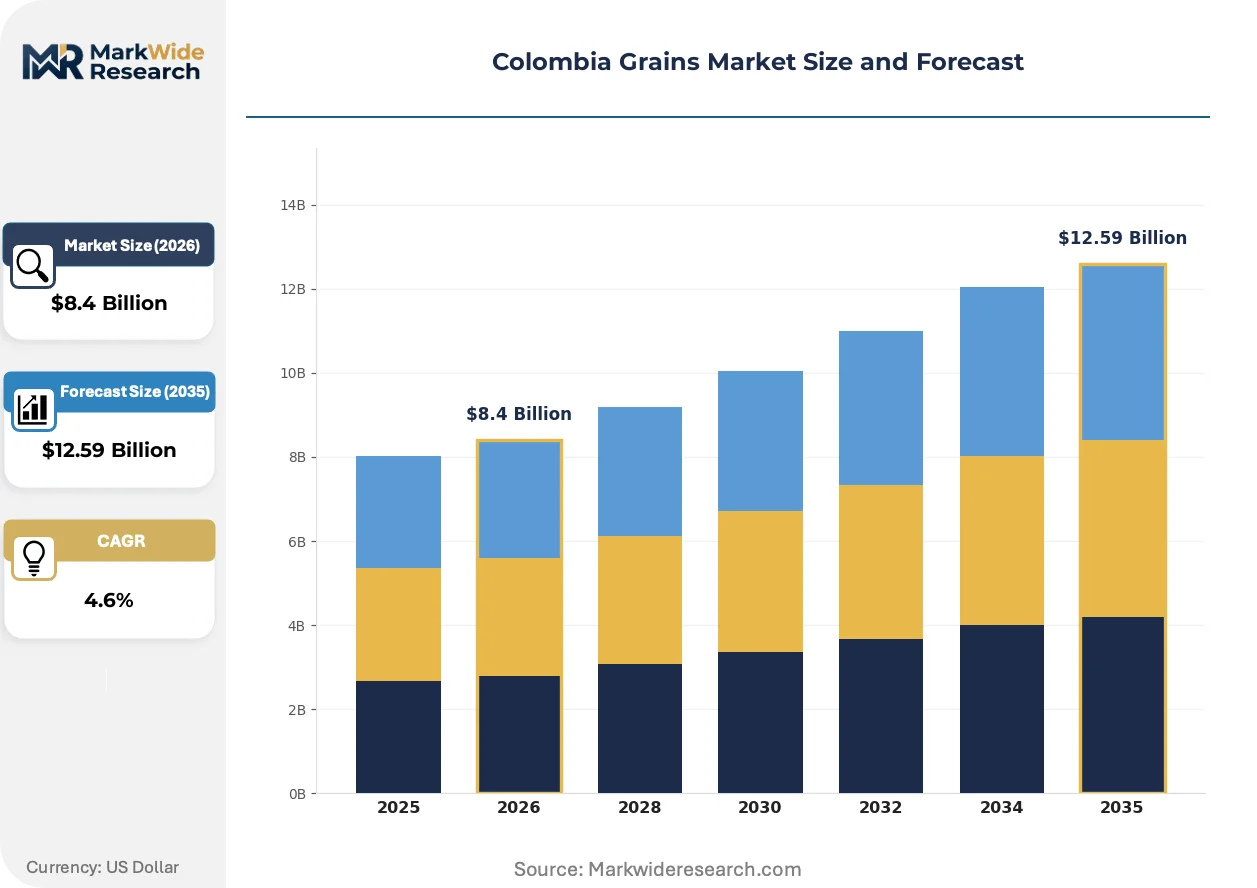
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat, Corn, Rice, Barley End Use Industry: Baking, Animal Feed, Food Processing, Export Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales Processing Method: Dry Milling, Wet Milling, Roller Milling, Others |
| Companies Covered | Agricol SA, Agropecuaria Aliar S.A., AGROPECUARIA SANTAMARIA S A, RIOPAILA AGRICOLA S A, SEMILLAS VALLE SA, Guaicaramo S.A.S, SAPUGA S A, SAENZ FETY SAS, The Grupo Daabon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Grains Market Strategic Shifts
Digital agriculture platforms and mechanization services are compressing the technology gap between Colombia's commercial grain belt and traditional farming regions. Three developments are restructuring competitive access and operational economics.
Telematics-enabled fleet management is modularizing equipment utilization across the Altillanura. Large-scale operators are deploying shared-service harvesting cooperatives that pool combine harvesters across multiple farms during narrow weather windows. This asset-light approach is reducing capital intensity barriers for mid-scale entrants while concentrating maintenance expertise among specialized service providers.
ICA's accelerated phytosanitary certification pathway for climate-resilient seed varieties is compressing variety approval timelines from 36 to 24 months for drought-tolerant corn hybrids. Commercial breeders are prioritizing stacked-trait submissions that combine herbicide tolerance with water-use efficiency markers. Feed processors in Cundinamarca and Boyacá are adjusting procurement specifications to favor certified hybrid origin over open-pollinated varieties.
Compound feed buyers are consolidating procurement authority at the regional level, displacing decentralized mill-level purchasing. Integrated poultry operators in Santander and Norte de Santander are centralizing grain sourcing through dedicated supply chain functions that negotiate directly with Cauca Valley commercial farms. This concentration is marginalizing traditional intermediary assemblers in historically fragmented Cordillera municipalities.
Colombia Grains Market Segmentation
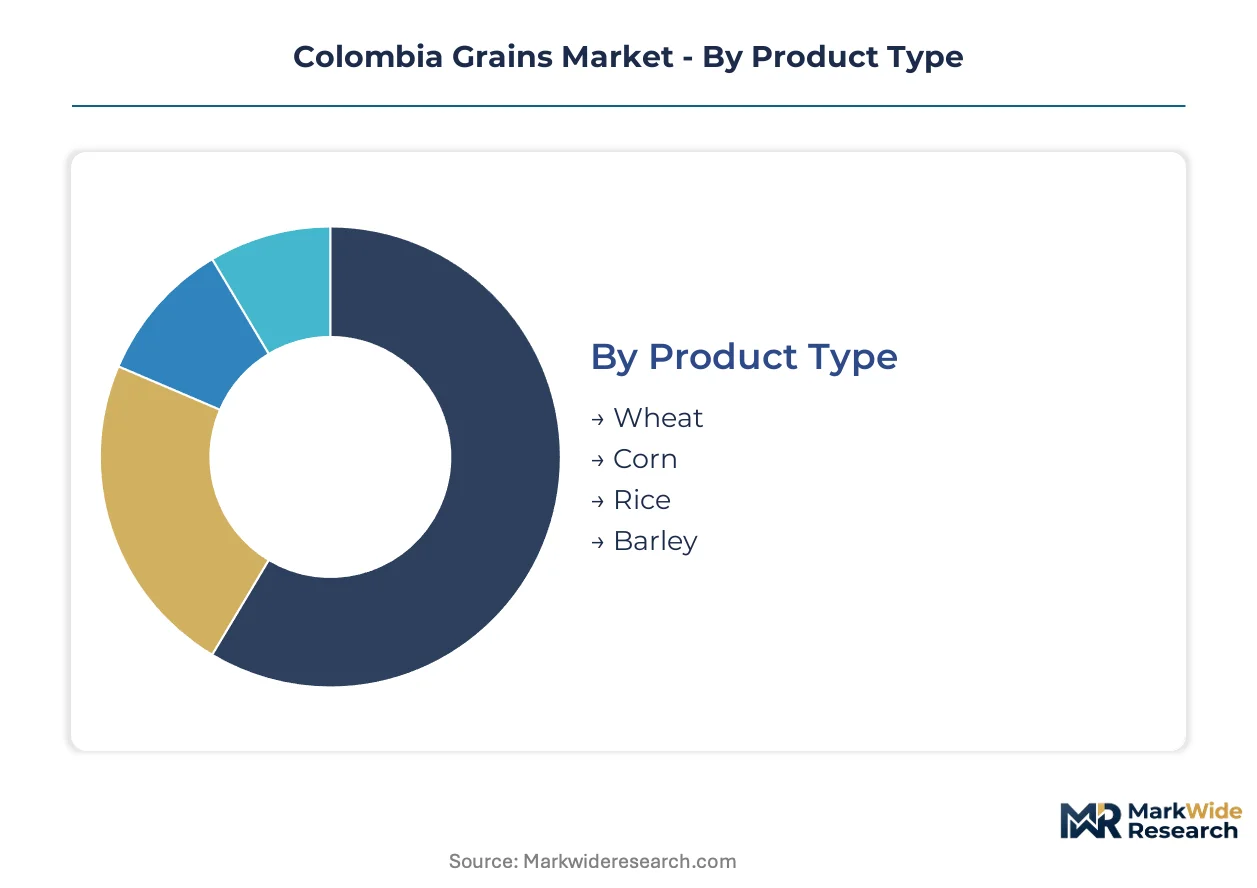
Grain segmentation in Colombia determines which regulatory pathways apply—INVIMA food safety registration for human-consumption channels, ICA phytosanitary clearance for seed propagation, and Mining and Energy Planning Unit compliance for biofuel-diverted volumes. Buyers and processors navigate distinct specification tiers, residue thresholds, and traceability requirements based on end-use classification.
Product Type:
Certification burden varies sharply across grain categories, with INVIMA residue protocols and ICA seed registration creating tiered compliance costs that favor commercial operators over smallholders.
- Corn:Yellow corn dominates poultry and swine feed formulations with protein grades of 8-9% and moisture thresholds capped at 14%. Demand concentrates in the Orinoquía region where integrated livestock operators in Casanare and Meta provinces source directly from Altillanura commercial farms, though the national biofuel blending mandate periodically diverts surpluses toward ethanol processors in Valle del Cauca.
- Rice:Paddy and milled varieties operate under price stabilization mechanisms administered through consumer subsidy programs, with INVIMA-enforced aflatoxin limits below 10 ppb determining commercial suitability. Procurement authority clusters in the Tolima and Huila departments where millers maintain backward integration into irrigation-dependent cultivation.
- Wheat:Hard and soft red varieties serve baking and industrial processing channels with gluten content specifications of 12-14% for bread flour applications. Colombian wheat production remains structurally limited, forcing millers to rely on North American and Argentine imports subject to ICA phytosanitary inspection at Barranquilla and Cartagena ports.
- Barley:Malting-grade two-row varieties with protein below 11.5% supply craft brewing substitution for imported malt, with certified seed production concentrated in Cundinamarca's high-altitude municipalities where cooler temperatures preserve enzymatic activity.
Corn sits at the top of the volume ranking, with barley climbing the fastest as craft brewing capacity expands in Bogotá and Medellín metropolitan areas.
End Use Industry:
Application-driven segmentation determines margin structure, with export-facing channels commanding premium certification investments while domestic food processing operates on standardized grades.
- Animal Feed:Compound feed processors in the Orinoquía and Caribbean regions formulate rations with 55-65% corn content for poultry and swine operations, sourcing protein supplementation through Brazilian and Argentine soybean meal imports due to domestic crushing capacity constraints.
- Food Processing:Dry milling operations in Valle del Cauca and Tolima produce flour, grits, and snack ingredients under INVIMA sanitary registration, with mycotoxin screening and metal detection forming mandatory process controls.
- Baking:Industrial bakeries and artisanal panaderías in major urban centers specify wheat flour with falling number values above 250 seconds, with price volatility managed through government strategic reserve releases.
- Export:Organic-certified grains achieving EU equivalence through ICA-accredited certifiers access premium European markets, with phytosanitary certificates issued by ICA's Plant Health Division required for every shipment.
Animal Feed captures the largest volume share, with Export channels gaining share fastest as European buyers deepen sourcing relationships with certified organic producers in Cauca Valley.
Distribution Channel:
Channel selection reflects buyer scale and geographic isolation, with traditional intermediary networks persisting in Cordillera municipalities while integrated operators bypass wholesale layers entirely.
- Wholesale:Regional assemblers in Córdoba and Sucre departments aggregate smallholder production for mill delivery, though post-harvest losses of 15-20% erode farmer margins through moisture damage and pest infestation in decentralized storage.
- Direct Sales:Large-scale Altillanura operators negotiate supply agreements directly with feed compounders and processors, eliminating intermediary markups while satisfying traceability requirements through farm-level documentation systems.
- Retail:Bagged grain sales through agricultural supply stores serve small livestock producers and backyard poultry operations, with 50kg packaging standard for corn and sorghum varieties.
- E-commerce:Digital platforms connecting farmers with urban feed buyers remain nascent, constrained by logistics infrastructure gaps and preference for physical grain inspection before purchase commitment.
Wholesale retains volume leadership, with Direct Sales expanding most quickly as regional procurement centralization displaces traditional assembler networks.
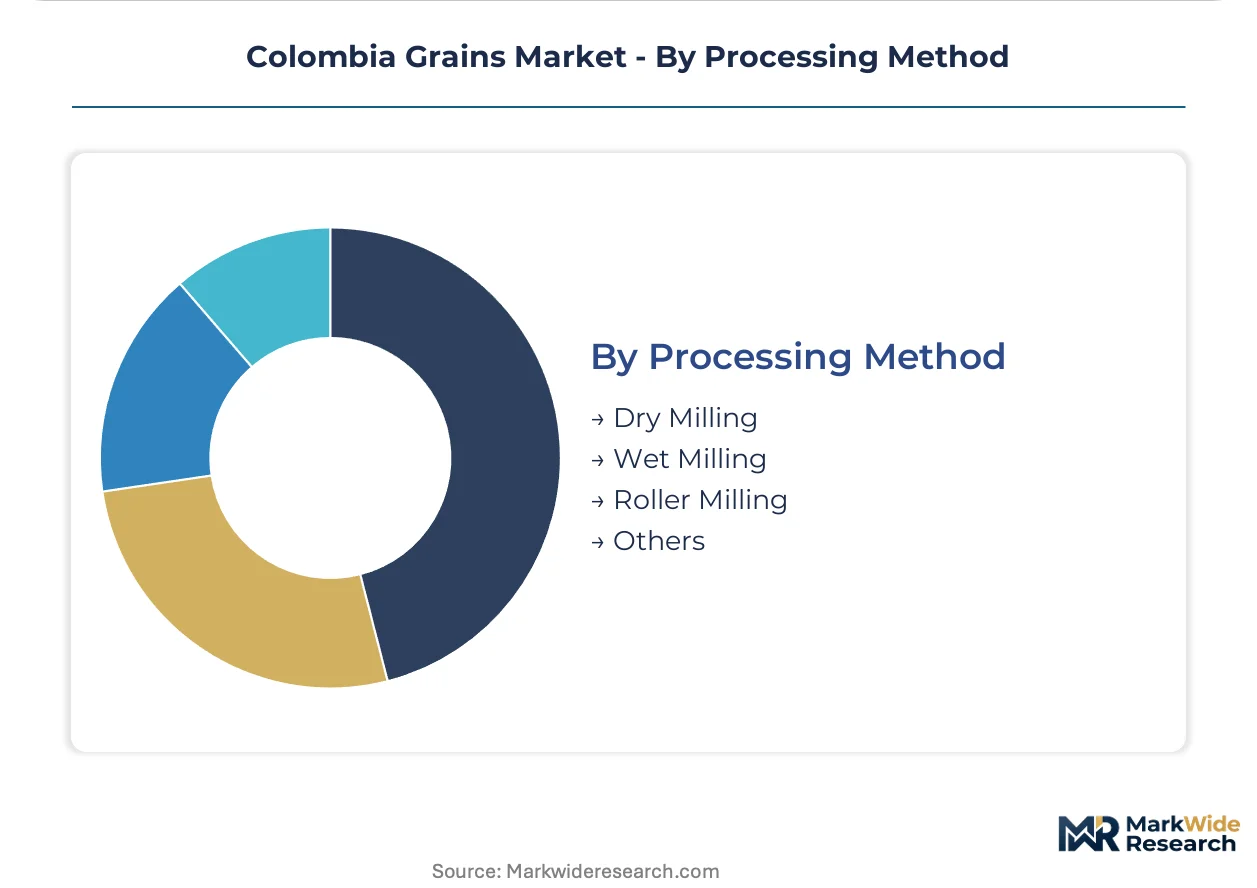
Processing Method:
Capital intensity and product margin stratify processing infrastructure, with wet milling investments concentrated near ethanol demand centers while dry milling maintains geographic dispersion.
- Dry Milling:Hammer and roller mills produce flour, meal, and grits across departmental capitals, with equipment scale ranging from 10-tonne daily village operations to 500-tonne industrial facilities in Palmira and Ibagué.
- Wet Milling:Starch and ethanol derivative processing in Valle del Cauca separates corn into germ, fiber, gluten, and starch fractions, with steeping and fermentation stages requiring substantial water and energy inputs.
- Roller Milling:Precision reduction systems for wheat and rice achieve consistent particle size distribution for baking and brewing applications, with pneumatic conveying and automated sifting replacing older stone mill infrastructure.
- Others:Nixtamalization for arepa production and traditional chicha fermentation represent artisanal processing preserving cultural practice, though volumes remain marginal to commercial grain flows.
Dry Milling dominates installed capacity, with Wet Milling showing steepest expansion trajectory as biofuel policy diverts corn toward ethanol channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ICA phytosanitary compliance costs are driving production consolidation toward capital-intensive zones where mechanized operators absorb certification burdens that marginal smallholders cannot sustain.
Altillanura Plains
Commercial corn and soybean operations in Casanare and Meta provinces attract feed processor procurement from Orinoquía livestock integrators. The Ministry of Agriculture's rural development incentives channel credit toward pivot irrigation installation on previously rain-dependent hectares. Palmira-based equipment distributors are scaling telematics-enabled harvesting cooperatives that pool combine fleets across multiple farms during compressed weather windows.
Cauca Valley
Wet milling capacity for starch and ethanol derivatives concentrates in Valle del Cauca, absorbing corn surpluses diverted by the Mining and Energy Planning Unit's biofuel blending mandate. INVIMA residue protocols enforce maximum limits on grain-derived food products processed through Palmira and Ibagué dry milling facilities. RIOPAILA AGRICOLA S A anchors regional supply through backward integration into seed development and commercial farming.
Cordillera Municipalities
Traditional smallholder production persists in isolated Cundinamarca and Boyacá highland zones where topography constrains mechanization. Agropecuaria Aliar S.A. operates collection networks extending into these municipalities, consolidating fragmented output for mill delivery. Post-harvest losses of 15-20% erode farmer margins through moisture damage in decentralized storage lacking climate control infrastructure.
Caribbean Lowlands
Rice cultivation clusters in Tolima and Huila departments where millers maintain backward integration into irrigation-dependent paddy production. Price stabilization mechanisms and consumer subsidy programs buffer growers from import competition. INVIMA-enforced aflatoxin limits below 10 ppb determine commercial suitability for milled varieties entering domestic food channels.
Magdalena River Basin
Climate volatility in Córdoba and Sucre departments compresses reliable planting windows for rain-fed corn, increasing yield variance. El Niño-Southern Oscillation disruptions narrow the sowing period, forcing rapid field preparation and germination. Regional assemblers aggregate smallholder production for mill delivery, though decentralized storage infrastructure gaps perpetuate pest infestation losses.
Colombia Grains Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue organic certification and specialty variety differentiation. The market structures around three archetypes: integrated agroindustrial conglomerates with captive seed development, geographic-specialist assemblers operating collection networks in fragmented zones, and sustainability-focused operators commanding premium offtake through certified protocols. Competitive dynamics center on backward integration into upstream cultivation and regional procurement centralization that displaces traditional intermediary layers.
Among integrated operators, RIOPAILA AGRICOLA S A exemplifies the agroindustrial archetype through Cauca Valley commercial farming and seed development. Agropecuaria Aliar S.A. occupies the geographic breadth position, extending collection infrastructure into Cordillera municipalities where competitors lack presence. The Grupo Daabon represents the sustainability-focused tier, leveraging organic certification to access European buyer premiums through ICA-accredited equivalence protocols.
| Leading Market Players |
|---|
| Agricol SA |
| Agropecuaria Aliar S.A. |
| AGROPECUARIA SANTAMARIA S A |
| RIOPAILA AGRICOLA S A |
| SEMILLAS VALLE SA |
| Guaicaramo S.A.S |
| SAPUGA S A |
| SAENZ FETY SAS |
| The Grupo Daabon |
| Others |
Value Chain & Pricing Dynamics
Backward integration into seed development and commercial farming anchors supply position and pricing power for Colombia's largest grain operators, concentrating procurement leverage among Cauca Valley conglomerates while marginal smallholders absorb cost compression from ICA phytosanitary compliance.
Pricing Analysis
Direct-to-processor contracting eliminates distributor margin layers that previously absorbed 8-12% markup in traditional assembler networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with organic-certified grains commanding differential premiums from European buyers. Cost compression in standard-grade corn is intensifying because feed compounders centralize procurement authority and squeeze intermediary margins. Small livestock producers and backyard poultry operations demonstrate highest price sensitivity through bagged retail channel preference, while integrated poultry operators show lowest sensitivity due to captive supply agreements.
Supply Chain Analysis
Single-source vulnerability sits with Argentine and Brazilian soybean meal suppliers that feed compounders draw from due to domestic crushing capacity constraints. Geographic supply concentration clusters in Colombia's Altillanura plains and Cauca Valley, with secondary nodes in Tolima and Huila departments. Raw material dependencies center on certified hybrid corn seed, pivot irrigation equipment, and imported protein meal inputs. Supply chain risk hinges on currency volatility exposure for dollar-denominated soybean meal imports. Distribution runs through direct sales agreements between Altillanura commercial farms and Orinoquía feed processors, displacing wholesale assembler layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's grains market functions as a geographic-arbitrage play where Altillanura irrigation infrastructure investments exploit yield differentials against rain-dependent Cordillera municipalities constrained by INVIMA residue protocol compliance costs.
For Market Incumbents: Acquire pivot irrigation installation assets and telematics-enabled harvesting cooperatives to consolidate Altillanura acreage expansion. Defensive positioning requires accelerating ICA-accredited organic certification programs to capture European buyer premiums before sustainability-focused competitors scale. Threat substitution from Brazilian grain traders intensifies margin pressure at Atlantic port delivery points, making captive supply control through backward integration into seed development the critical defensive lever. For New Entrants and Emerging Players: Digital agriculture platforms serving mid-scale Altillanura operators represent the most penetrable white-space target, compressing technology adoption gaps through equipment-sharing cooperatives. Cordillera municipalities offer secondary entry through collection network infrastructure that Agropecuaria Aliar S.A. has proven viable. Go-to-market execution should anchor on precision agriculture deployment partnerships with Palmira-based equipment distributors, bypassing capital intensity barriers through asset-light service models. For Investors and Strategic Acquirers: Roll-up economics work for geographic-specialist assemblers operating collection networks in fragmented Cordillera zones because ICA phytosanitary compliance barriers prevent smallholder consolidation without intermediary infrastructure. Long-term viability favors operators achieving scale sufficient to absorb certification and traceability system investments. Acquisition targets should demonstrate established relationships with ICA for accelerated seed variety registration. The inflection signal to monitor is central bank currency policy affecting soybean meal import cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Pivot Irrigation Installation | Altillanura yield doubling attracts Ministry of Agriculture rural development credit allocation. |
| ICA Organic Certification Pathway | EU equivalence protocols unlock premium European offtake for Cauca Valley producers. |
| Wet Milling Capacity Expansion | Valle del Cauca ethanol processing diversifies corn outlets beyond feed channels. |
| Telematics Harvesting Cooperative | Shared-service combine pools reduce capital intensity for mid-scale Altillanura entrants. |
| Regional Procurement Centralization | Orinoquía feed processor consolidation displaces traditional Cordillera assembler networks. |
Study Parameters
Coverage spans Colombia's five grain-producing regions, with primary inputs from each including compound feed procurement directors, ICA phytosanitary certification officers, Altillanura commercial farm operators, and Cauca Valley wet milling facility managers. Secondary validation draws from Ministry of Agriculture rural development filings, INVIMA residue limit enforcement records, Mining and Energy Planning Unit biofuel diversion statistics, and ICA seed registration databases. Bottom-up acreage and yield estimates triangulate against top-down processor offtake volumes.
Segmentation granularity models product type, end-use industry, distribution channel, and processing method dimensions at the departmental level across the projection horizon. CAGRs derive from trend extrapolation of mechanization investment flows, livestock integration patterns, and biofuel policy absorption capacity. Industry-specific forecast inputs incorporate El Niño-Southern Oscillation cycle impacts on planting window reliability and European organic import demand trajectories.
The model holds under stable ICA certification timelines and Ministry of Agriculture credit continuity; deviation in currency volatility magnitude or biofuel blending mandate suspension would shift volume and value trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Heritage Grain Market
Grains
Barley Grass Market
Grains
Spain Rice Market
Grains
Grain Bins Market
Grains
Africa Wheat Flour Market
Grains
Global Wheat Market
Grains
Tunisia Grain Market
Grains
Organic Rice Flour Market
Grains
Global Rice Market
Grains
Grain Storage Silos Market
Grains
Mexico Rice Market
Grains
Grain Silos Market
Grains
Europe Wheat Protein Market
Grains
Red Rice Market
Grains
IQF Rice Market
Grains
Argentina Grains Market