
 Multi-Touch Equipment Market | 2026-2036
Multi-Touch Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Touch Equipment Market Analysis
China is rewriting capacity dynamics for multi-touch equipment as Shenzhen and Dongguan expand OLED-on-glass foundry output for next-generation displays. Samsung Electronics leverages captive semiconductor fabrication to secure in-house controller chip supply for premium touch panels. Apple sustains design-to-manufacturing discipline through tight supplier qualification protocols across its Asian assembly network. Microsoft Corporation anchors enterprise demand via Surface Hub interactive whiteboard deployments in North American corporate campuses.
Multi-touch equipment encompasses display-integrated sensing systems that detect simultaneous contact points through capacitive, infrared, or optical sensing layers, typically supporting ten or more concurrent touch inputs with response latencies under ten milliseconds for commercial and industrial human-machine interfaces. The technology serves retail kiosks, surgical navigation suites, and collaborative workspaces where gesture-based interaction replaces mechanical controls. Capacitive technology dominates premium smartphone and tablet segments due to optical clarity and durability, while infrared sensing retains cost advantages for large-format interactive whiteboards in education budgets. Touchscreen product types capture the largest installed base, though digital signage with embedded multi-touch represents the fastest-expanding margin pool as advertisers shift from passive to interactive street-level engagement.
FCC equipment authorization rules govern electromagnetic emissions for multi-touch devices sold in the United States, while the EU Green Deal's ecodesign requirements push manufacturers toward mercury-free backlighting and recyclable sensor substrates. China's GB standards for electromagnetic compatibility and Japan's METI energy efficiency labeling both shape product certification roadmaps for cross-border equipment shipments. Stakeholders must monitor how the EU AI Act's risk classification framework applies to touch-enabled biometric kiosks, as compliance obligations could redraw competitive boundaries between integrated system vendors and component suppliers.
Market Dynamics
Capacitive controller chip supply concentration in South Korean and Taiwanese foundries is forcing display integrators to redesign sourcing strategies around captive semiconductor capacity and long-term supply agreements.
Growth Catalysts
- EU Medical Device Regulation:Healthcare facilities across Germany, France, and Italy are expanding interactive diagnostic display deployments, creating certified demand for surgical-grade multi-touch panels with sub-ten-millisecond latency.
- OLED-on-glass foundry expansion:Shenzhen and Dongguan manufacturing clusters are scaling next-generation display output, reducing sensor substrate costs for premium touchscreen segments.
- Infrared sensing cost structure:Education budgets in North American school districts favor large-format interactive whiteboards using infrared technology over capacitive alternatives for collaborative learning spaces.
Market Restraints
- Indium tin oxide price volatility:Capacitive touchscreen manufacturing faces input cost pressure from rare earth supply chain disruptions concentrated in Chinese processing facilities.
- Controller chip foundry concentration:Advanced semiconductor fabrication for touch ICs remains captive to Samsung Electronics and TSMC capacity allocation decisions.
- Mercury-free backlighting mandate:EU Green Deal ecodesign requirements impose transition costs on manufacturers still dependent on legacy cold cathode fluorescent lamp assemblies.
Strategic Opportunities
- Street-level interactive advertising:Digital signage with embedded multi-touch represents underpenetrated inventory as out-of-home media owners retrofit passive displays for gesture-based engagement.
- EU AI Act compliance services:Touch-enabled biometric kiosks face emerging risk classification obligations, creating white space for system integrators offering certified privacy-by-design architectures.
- Automotive interior convergence:Haptic feedback integration with curved multi-touch surfaces is displacing mechanical switchgear in electric vehicle cockpit designs.
Industry Challenges
- FCC equipment authorization timelines:Electromagnetic emissions certification for multi-touch devices sold in the United States creates launch delays for products with novel sensor geometries.
- Legacy system integration friction:Industrial human-machine interface retrofits require protocol translation layers to connect modern capacitive panels with existing programmable logic controller networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Touch Equipment Market |
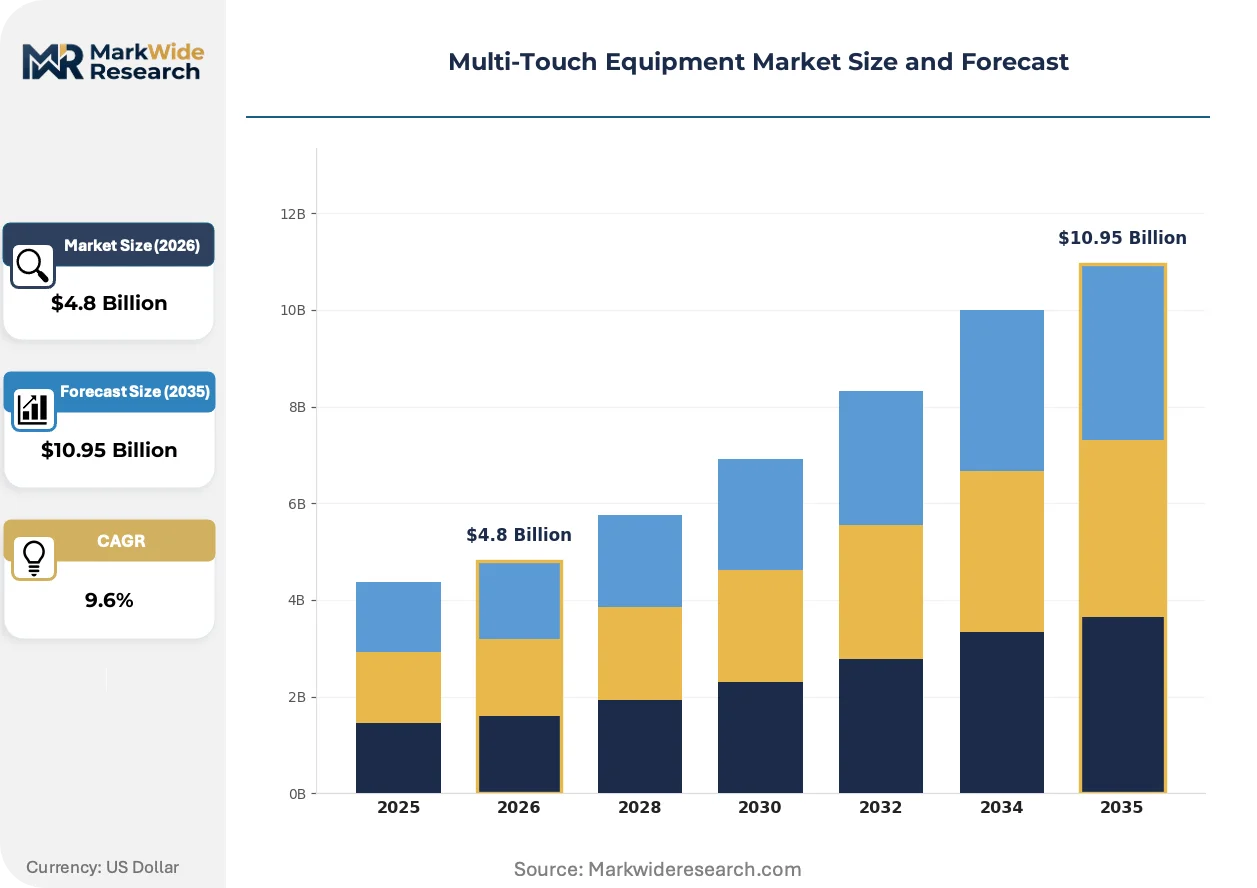
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.95 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreens, Interactive Whiteboards, Kiosks, Digital Signage Technology: Infrared, Capacitive, Resistive, Optical End User: Healthcare, Education, Retail, Entertainment Installation: Wall-mounted, Tabletop, Standalone, Integrated |
| Companies Covered | Samsung Electronics, Apple, Microsoft Corporation, 3M Company, FlatFrog Laboratories, Panasonic Corporation, Fujitsu Limited, A D Metro, Touch Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Touch Equipment Market Emerging Trajectories
Gesture recognition algorithms and haptic feedback layers are converging with display-integrated sensing to transform how operators interact with industrial and commercial interfaces.
Optical bonding technology is eliminating air gaps between cover glass and liquid crystal display panels to improve optical clarity and durability in high-ambient-light environments. Automotive manufacturers and surgical suite designers are specifying bonded stacks for curved and edge-to-edge form factors. This process is virtualizing the traditional mechanical gasket assembly step, compressing module thickness while improving ingress protection ratings.
China's GB standards for electromagnetic compatibility are tightening test protocols for multi-touch equipment shipped across borders, forcing redesigns of controller board shielding and cable routing. Manufacturers targeting both domestic Chinese sales and export markets must maintain dual certification tracks. Medical device segments face the steepest compliance burden as GB requirements diverge from IEC baselines for patient-contact equipment.
After-sales service contracts are unbundling from hardware procurement as enterprise buyers negotiate separate agreements for touchscreen calibration, sensor replacement, and firmware updates. Systems integrators serving North American corporate campuses are responding with tiered support offerings. This shift is most visible in Surface Hub deployments where IT departments prefer operational expenditure treatment over capital-intensive refresh cycles.
Multi-Touch Equipment Market Segmentation
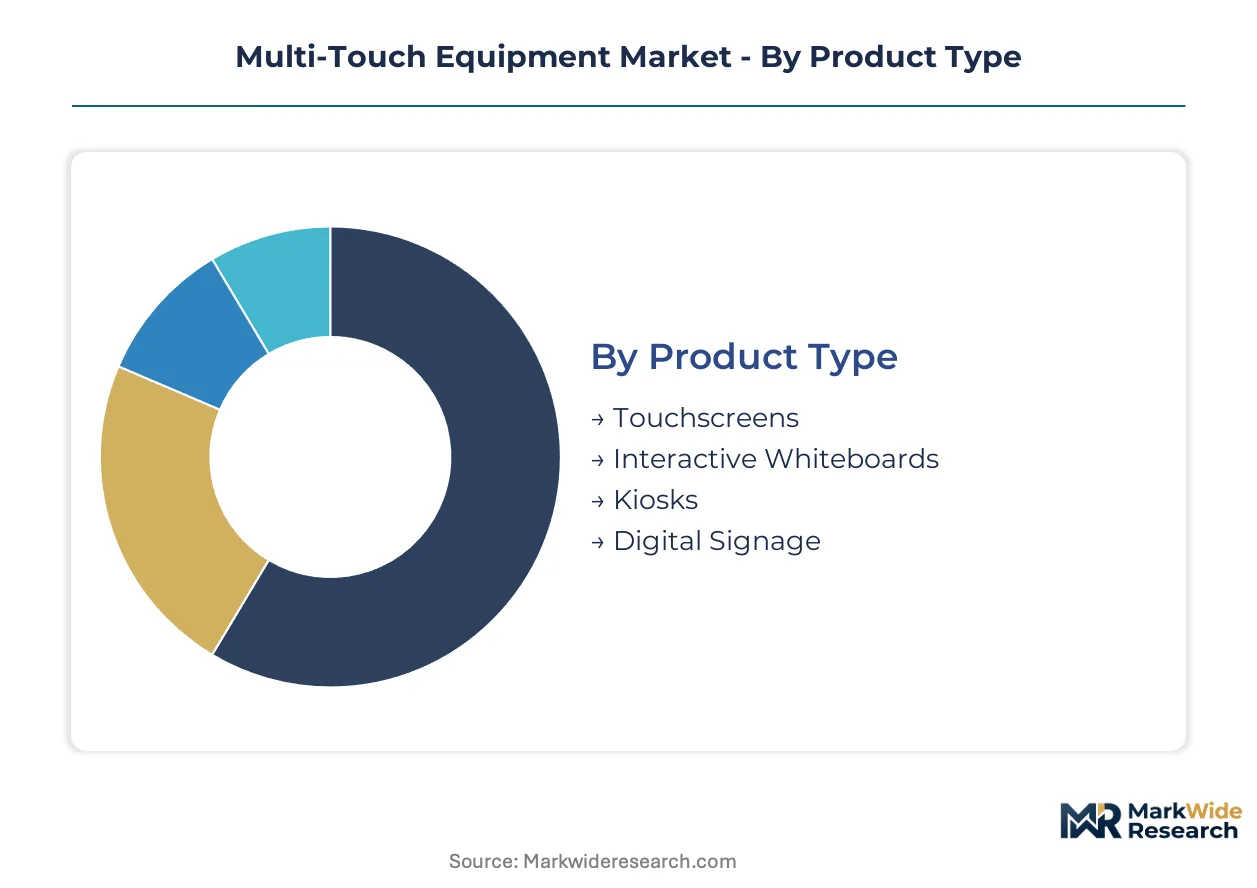
Multi-touch equipment segmentation reveals how technical specifications, deployment contexts, and user environments create distinct procurement criteria across commercial and industrial buyers. Understanding these divides helps suppliers align controller chip sourcing, calibration protocols, and after-sales service models with segment-specific performance requirements.
Product Type:
End-use environments span surgical suites requiring sub-ten-millisecond latency, classroom collaboration spaces, and street-level advertising inventory demanding weatherproofing.
- Touchscreens:Display-integrated capacitive or infrared sensing layers support ten or more concurrent inputs with optical clarity prioritized in premium smartphone and tablet manufacturing. Demand concentrates in South Korean electronics clusters where Samsung Electronics leverages captive semiconductor fabrication for controller chip supply.
- Interactive Whiteboards:Large-format infrared sensing dominates education budgets in North American school districts, offering cost advantages over capacitive alternatives for collaborative learning deployments. Microsoft Corporation anchors enterprise demand via Surface Hub installations across corporate campuses with unbundled after-sales service contracts.
- Kiosks:Self-service terminals with embedded multi-touch serve retail and healthcare check-in workflows, facing emerging EU AI Act risk classification obligations for biometric-enabled deployments.
- Digital Signage:Interactive street-level displays represent expanding inventory as out-of-home media owners retrofit passive screens for gesture-based engagement.
Established volume favors touchscreens; emerging adoption favors digital signage.
Technology:
Cost tiers separate premium optical clarity from budget infrared implementations, with controller chip foundry access determining supply security.
- Capacitive:Indium tin oxide sensing layers deliver durability and optical clarity for smartphone and tablet segments, though rare earth supply chain disruptions in Chinese processing facilities create input cost pressure. Foundry concentration in Samsung Electronics and TSMC forces display integrators toward long-term supply agreements.
- Infrared:LED emitter-receiver arrays around display bezels enable cost-effective large-format implementations, dominating education budgets for interactive whiteboards where collaborative learning spaces prioritize scale over pixel density.
- Resistive:Pressure-sensitive membrane stacks suit industrial gloves and stylus inputs, retaining niche demand in factory floor human-machine interfaces.
- Optical:Camera-based sensing enables arbitrary surface interaction, gaining traction in automotive cockpit designs where curved form factors displace mechanical switchgear.
Capacitive technology commands premium positioning; optical sensing gains share fastest in automotive convergence applications.
End User:
Customer type dictates certification requirements, from EU Medical Device Regulation compliance to education procurement cycles and retail footfall analytics.
- Healthcare:Surgical navigation suites and diagnostic displays require certified panels with sub-ten-millisecond latency under EU Medical Device Regulation frameworks, with German facilities expanding deployments.
- Education:North American school district budgets favor infrared-based interactive whiteboards for collaborative learning, with procurement cycles tied to fiscal year appropriations.
- Retail:Self-service kiosks and interactive storefront displays drive demand for weatherproof capacitive stacks with gesture recognition algorithms.
- Entertainment:Museums, theme parks, and gaming venues specify durable optical bonding for high-ambient-light environments with haptic feedback integration.
Healthcare commands certification premiums; retail offers volume scale through kiosk standardization.
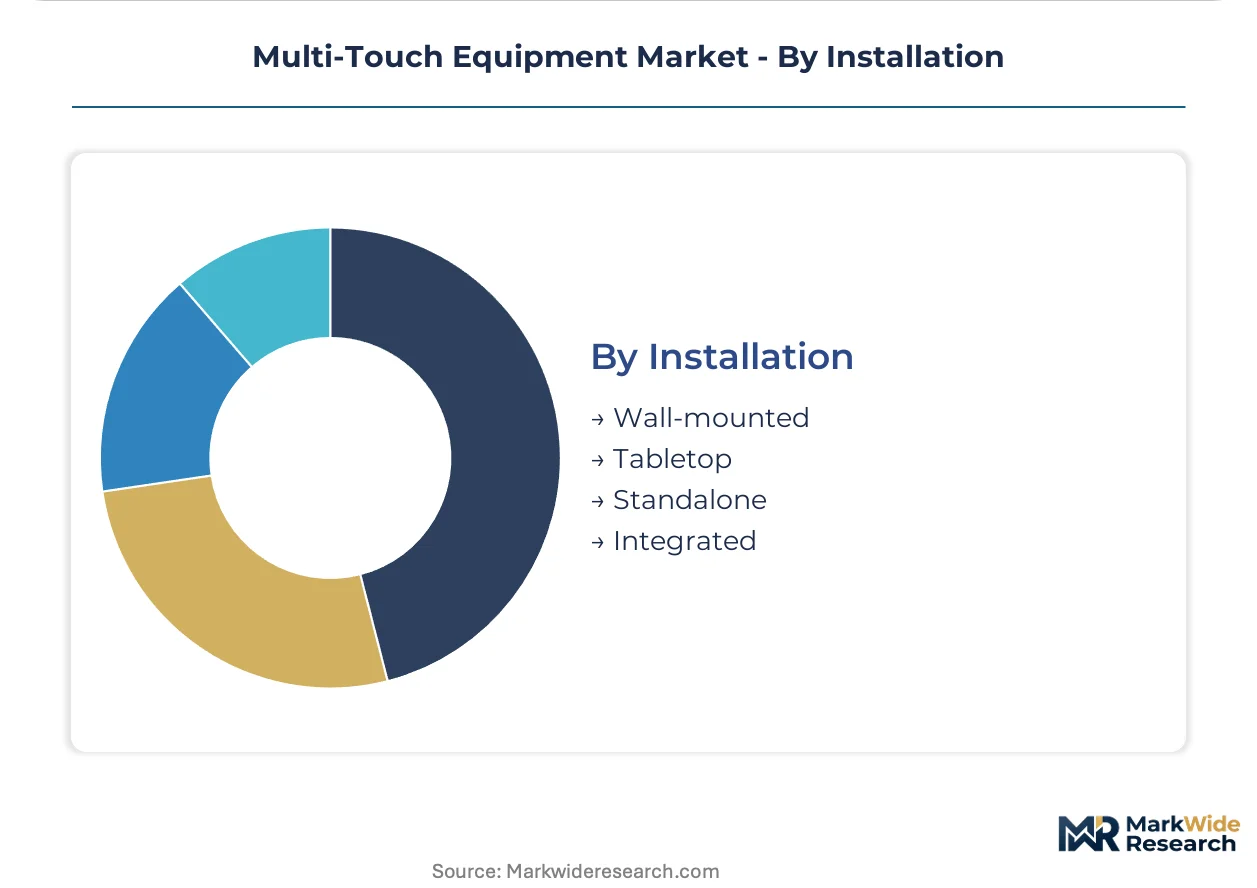
Installation:
Physical deployment mode determines structural requirements, cable routing complexity, and integration with existing building systems.
- Wall-mounted:Fixed installations dominate classroom and corporate meeting room deployments, requiring VESA-compatible bracketing and concealed power delivery.
- Tabletop:Horizontal surfaces enable collaborative workstations and dining applications, demanding spill-resistant sealing and edge-to-edge glass specifications.
- Standalone:Floor-mounted kiosks and wayfinding terminals require stability engineering and accessibility compliance for public space deployments.
- Integrated:Built-to-surface implementations in automotive cockpits and surgical suites demand optical bonding for curved form factors with ingress protection ratings.
Wall-mounted configurations retain largest installed base; integrated implementations show steepest expansion trajectory in automotive and medical device convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shenzhen anchors Asia-Pacific multi-touch equipment flows, handling display module exports that feed assembly networks across three continents. This maritime infrastructure underwrites China's dominance in capacitive sensor substrate manufacturing.
United States
Corporate campus deployments of interactive whiteboards drive enterprise demand, with IT departments favoring operational expenditure models over capital-intensive refresh cycles. FCC equipment authorization rules govern electromagnetic emissions certification, creating launch delays for novel sensor geometries. Surface Hub installations concentrate in North American metropolitan corridors where collaborative workspace retrofits accelerate.
Germany
Healthcare facilities expand surgical-grade multi-touch panel deployments under EU Medical Device Regulation frameworks requiring sub-ten-millisecond latency certification. The EU Green Deal's ecodesign requirements push manufacturers toward mercury-free backlighting assemblies. Bavarian medical technology clusters coordinate with Baden-Württemberg display integrators to meet stringent patient-contact equipment standards.
China
Shenzhen and Dongguan manufacturing clusters scale OLED-on-glass foundry output for next-generation display modules, reducing sensor substrate costs for premium touchscreen segments. GB standards for electromagnetic compatibility tighten test protocols for cross-border shipments. Pearl River Delta electronics assemblers maintain dual certification tracks for domestic sales and export markets.
South Korea
Electronics manufacturing clusters concentrate capacitive touchscreen demand, with captive semiconductor fabrication securing in-house controller chip supply for premium touch panels. METI energy efficiency labeling shapes product certification roadmaps for Japanese-bound equipment shipments. Seoul Capital Area display integrators negotiate long-term supply agreements with Samsung Electronics foundry capacity.
Japan
Automotive cockpit designs specify curved multi-touch surfaces with haptic feedback integration, displacing mechanical switchgear in electric vehicle interiors. METI energy efficiency labeling drives compliance investment for equipment targeting domestic and export markets. Nagoya-based automotive suppliers coordinate with Kanto region display specialists on bonded stack specifications for edge-to-edge form factors.
Multi-Touch Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in controller chip and sensor substrate supply. The vendor base stratifies across three tiers: captive electronics conglomerates with semiconductor fabrication assets, independent display integrators sourcing from merchant foundries, and niche specialists in infrared or optical sensing modalities. Competitive moves concentrate on securing foundry allocation through long-term supply agreements and optical bonding process investments for curved form factors.
Among Korean and American electronics conglomerates, Samsung Electronics and Apple occupy positions anchored by captive semiconductor supply and tight supplier qualification protocols respectively. Microsoft Corporation exemplifies the enterprise platform integrator archetype, anchoring demand through interactive whiteboard deployments with unbundled after-sales service structures. These three represent distinct competitive vectors: upstream component security, design-to-manufacturing discipline, and enterprise service model innovation.
| Leading Market Players |
|---|
| Samsung Electronics |
| Apple |
| Microsoft Corporation |
| 3M Company |
| FlatFrog Laboratories |
| Panasonic Corporation |
| Fujitsu Limited |
| A D Metro |
| Touch Innovations |
| Others |
Supply Flow & Price Mechanics
Indium tin oxide price volatility in Chinese processing facilities compresses margin spreads across premium capacitive tiers while forcing display integrators toward long-term offtake agreements that reshape procurement geography. This input cost pressure simultaneously widens the premium-to-economy price gap and accelerates sourcing diversification into South Korean and Taiwanese foundry networks.
Pricing Analysis
Volume-discount tiering structures separate surgical-grade certified panels from education-budget infrared implementations, with EU Medical Device Regulation compliance adding certification premiums to healthcare deployments. Price differentiation tracks controller chip foundry access and optical bonding process investments, with Samsung Electronics captive supply commanding premiums over merchant-sourced alternatives. Cost compression in large-format education segments intensifies as North American school districts consolidate procurement through cooperative purchasing agreements. Retail kiosk buyers exhibit highest price sensitivity, while automotive cockpit integrators prioritize haptic feedback performance over unit economics.
Supply Chain Analysis
Contract-manufacturing concentration centers on Shenzhen and Dongguan electronics clusters for display module assembly, with Samsung Electronics and TSMC holding captive capacity for advanced controller chip fabrication. Raw material dependencies include indium tin oxide sensing layers, OLED-on-glass substrates, and mercury-free backlighting assemblies. Single-source vulnerability in South Korean semiconductor foundries threatens supply security for premium touch panel segments. Distribution runs through direct OEM relationships for automotive and medical device verticals, while education and retail channels leverage systems integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
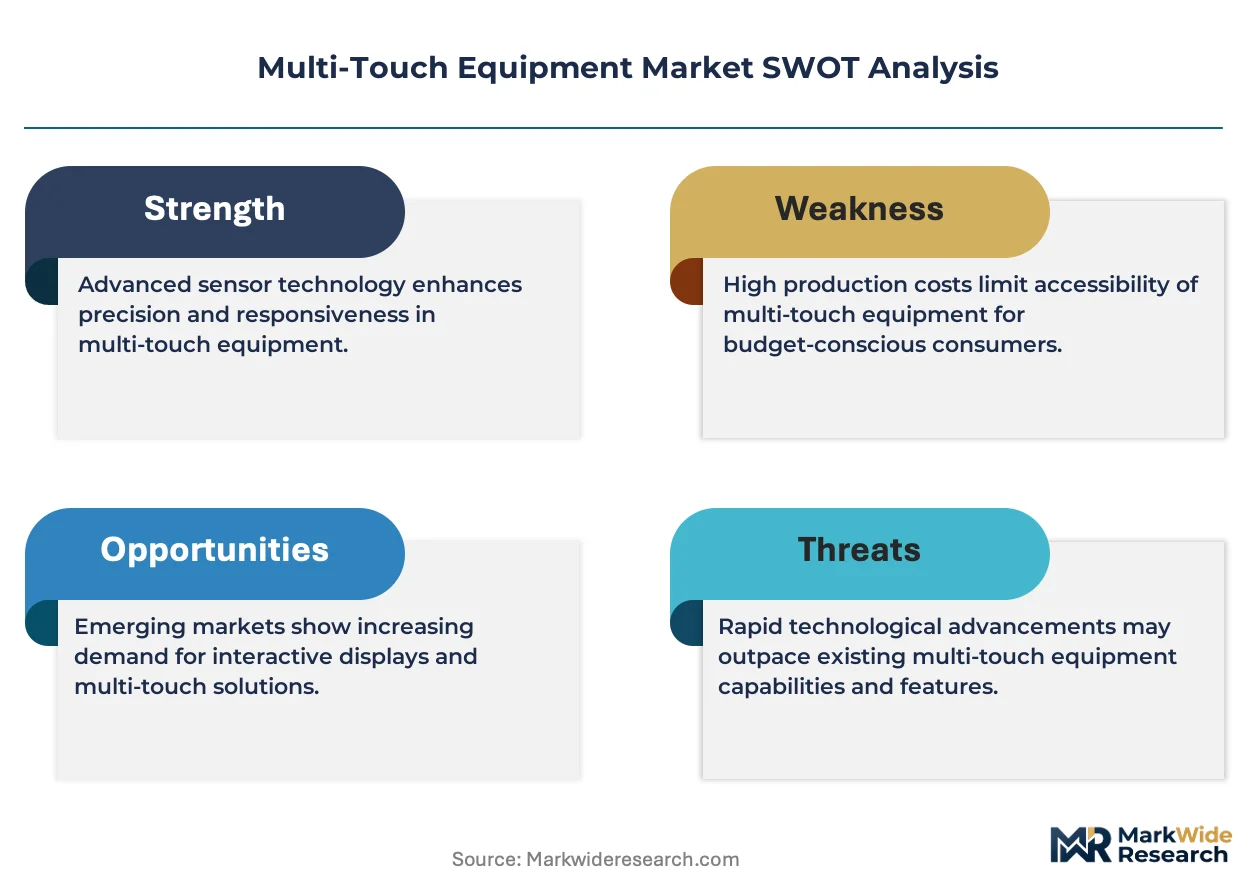
Voice-based and gesture-only interfaces threaten to bypass touch-dependent hardware in automotive and smart home applications, requiring incumbents to defend through embedded haptic differentiation and certification moats.
For Market Incumbents: Harden supply security through backward integration into controller chip design or exclusive foundry allocation agreements with Samsung Electronics and TSMC. Deepen optical bonding process investments for curved automotive form factors to create technical switching costs against voice-interface substitutes. Prioritize EU AI Act compliance certification for biometric-enabled kiosk deployments before regulatory deadlines reshape competitive access. For New Entrants and Emerging Players: Establish a beachhead in street-level interactive advertising digital signage, where out-of-home media owners retrofit passive inventory and procurement cycles remain fragmented. Target North American school district cooperative purchasing networks with cost-optimized infrared whiteboard alternatives to Microsoft Surface Hub dominance. Lead with unbundled after-sales service contracts that convert capital expenditure procurement to operational expenditure relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors component specialists with captive foundry relationships or optical bonding IP. Long-term viability over the next decade hinges on automotive interior convergence and surgical-grade certification expansion. Acquisition targets should display dual-use capability across medical device and automotive verticals. Monitor indium tin oxide price spreads and EU Green Deal ecodesign enforcement timelines as inflection indicators for margin compression and regulatory-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Foundry Supply Agreement | Secures controller chip allocation from Samsung Electronics and TSMC against capacity constraints. |
| Optical Bonding Process Investment | Enables curved form factor production for automotive cockpit and surgical display specifications. |
| EU AI Act Compliance Certification | Opens biometric kiosk deployments under emerging risk classification frameworks. |
| Unbundled After-Sales Service Launch | Converts Surface Hub-style enterprise procurement from capital to operational expenditure treatment. |
| Indium Tin Oxide Sourcing Diversification | Reduces exposure to Chinese rare earth processing disruptions through alternative substrate development. |
Methodological Framework
Initial hypotheses were tested against primary input from display integration engineers, semiconductor procurement leads, hospital biomedical equipment managers, and automotive Tier 1 supplier program directors, then refined through secondary validation against SEC filings from Samsung Electronics and Microsoft Corporation, EU Medical Device Regulation guidance documents, FCC equipment authorization databases, and Pearl River Delta customs export records. Bottom-up demand estimates from end-user procurement cycles were triangulated with top-down supply capacity assessments across OLED-on-glass foundry networks.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling volume and value outputs through technology segmentation by capacitive, infrared, resistive, and optical modalities, product type across touchscreens, interactive whiteboards, kiosks, and digital signage, and end-user verticals spanning healthcare, education, retail, and automotive applications. CAGRs were derived from fitted growth curves calibrated against historical foundry capacity expansion rates and EU regulatory compliance investment cycles. Industry-specific forecast inputs included EU Green Deal ecodesign transition timelines and indium tin oxide price trajectory assumptions.
Stress conditions across indium tin oxide supply disruptions, EU AI Act enforcement intensity, and automotive platform standardization rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about foundry capacity allocation decisions and regulatory implementation pacing. Quarterly review of controller chip lead times, EU MDR certification approval velocities, and automotive OEM curved display sourcing announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
UV-Based Nanoimprint Lithography (UV-NIL) System Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Semiconductor Wafer Process Control Equipment Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Semiconductor Bonding Equipment Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Tape on Reel Feeder Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market