
 Electric Vehicle AC Charging Pile Market | 2026-2036
Electric Vehicle AC Charging Pile Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle AC Charging Pile Market Insights
EU Green Deal compliance is pivoting the cost-of-entry calculus for AC charging pile manufacturers selling into Europe. ChargePoint leverages its software-integrated hardware stack to sustain pricing power across the residential and fleet boundary. Siemens anchors German engineering credibility while competing on three-phase AC systems for commercial complexes.
An electric vehicle AC charging pile converts alternating current from the grid into vehicle-compatible power through onboard rectification, typically delivering 3.7 kW to 22 kW depending on single-phase or three-phase configuration. Wall-mounted chargers dominate residential installations where space constraints and cost sensitivity shape procurement, while smart charging technology captures expanding margin pools as utilities introduce time-of-use rate structures. Fleet operators represent the fastest-growing customer type, driven by overnight depot charging economics that favor lower-capital AC hardware over DC alternatives.
EMA device standards, CE marking requirements, and EU AI Act provisions for grid-connected infrastructure collectively shape product design and market access timelines for AC charging equipment in Europe. China's SAMR enforces GB standards that constrain import compatibility, forcing parallel certification strategies for multinational suppliers. Stakeholders must monitor how utility demand-response programs recalibrate the revenue model from hardware sales toward energy-management services.
Market Dynamics
Fleet electrification timelines are compressing procurement cycles for depot-grade AC hardware, forcing manufacturers to reconcile three-phase power architectures with legacy single-phase residential infrastructure.
Growth Catalysts
- EU Green Deal mandates:Germany's municipal bundling of streetlight retrofits with curbside AC infrastructure creates anchor demand for interoperable hardware.
- Time-of-use rate structures:Utilities across France, Italy, and Spain are introducing dynamic pricing that rewards smart-charging-capable AC piles with preferential grid access.
- Onboard rectification advances:Silicon carbide power electronics in newer vehicle inverters extend AC charging efficiency curves, preserving hardware margins at 22 kW output levels.
Market Restraints
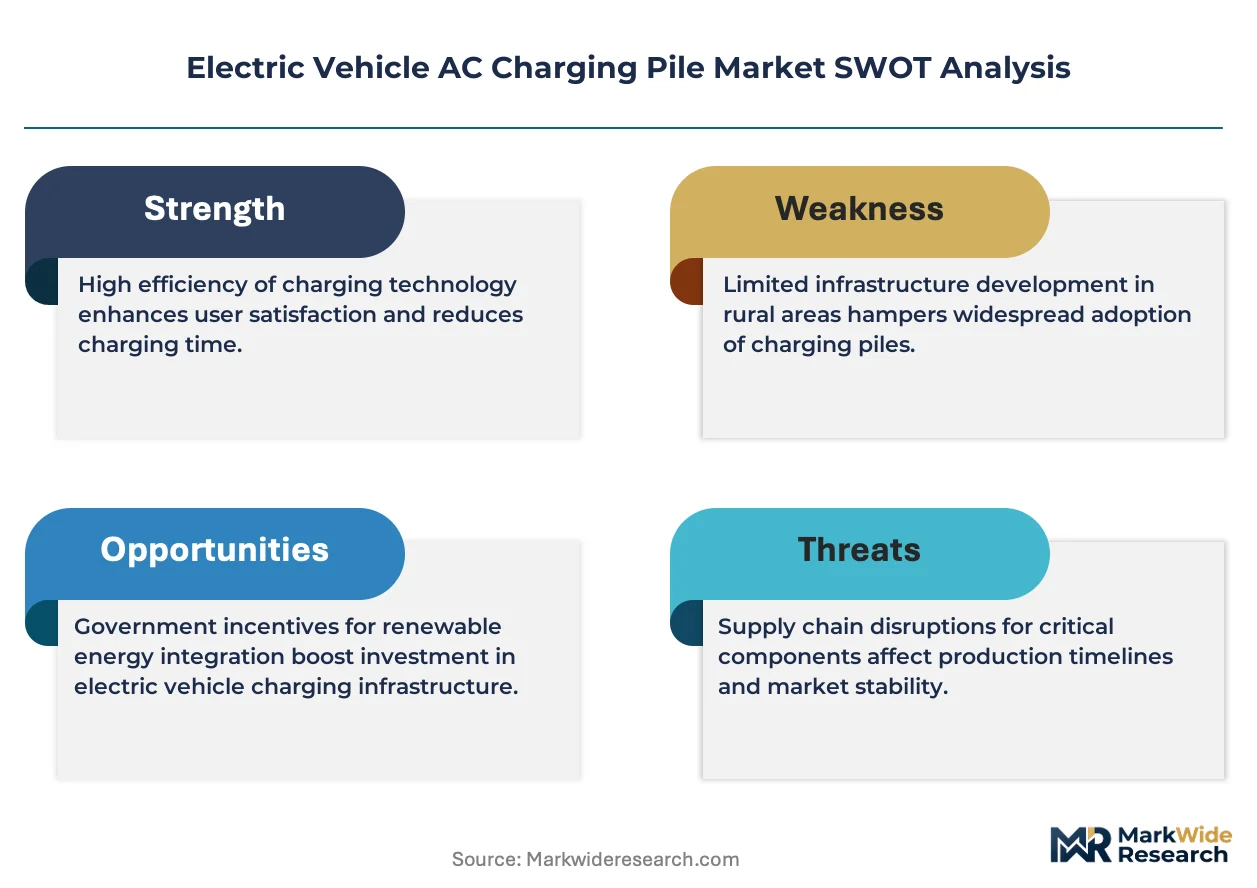
- Copper conductor volatility:Three-phase cable assemblies constitute 18-24% of bill-of-materials costs, exposing manufacturers to LME price swings without pass-through mechanisms.
- GB/T certification fragmentation:China's SAMR enforces parallel testing protocols that add 8-14 months to product launch timelines for multinational suppliers.
- DC fast-charging substitution:Fleet operators with 200+ vehicle deployments increasingly bypass AC depot infrastructure for 150 kW DC hardware despite higher capital outlay.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives for power electronics create localization pathways for AC pile assembly at 40% lower landed cost.
- Vehicle-to-grid convergence:Bidirectional AC charging protocols (ISO 15118-20) enable fleet operators to monetize battery assets as distributed storage resources.
- Retail channel disintermediation:Direct-to-installer platforms in the United Kingdom are collapsing traditional electrical wholesaler markups by 12-18 percentage points.
Industry Challenges
- Embedded systems cybersecurity certification:EU AI Act provisions for grid-connected infrastructure require functional safety audits that strain mid-tier engineering teams.
- Legacy electrical panel compatibility:Residential installations in older German and French housing stock face service upgrade costs that stall purchase decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle AC Charging Pile Market |
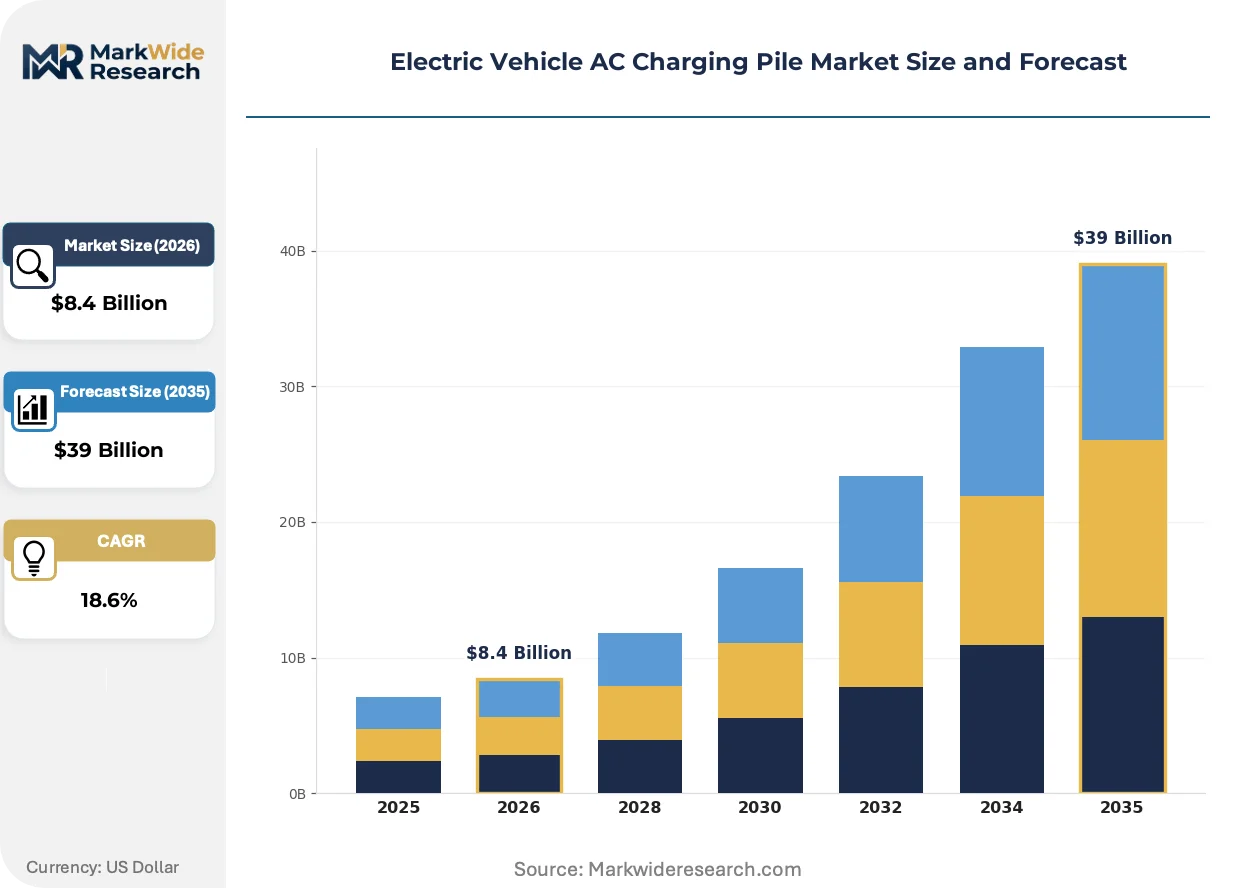
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-mounted Chargers, Pedestal Chargers, Mobile Chargers, Portable Chargers Charging Technology: Single-phase AC, Three-phase AC, Smart Charging, Wireless Charging Application Sector: Private Vehicle Charging, Fleet Charging, Commercial Complexes, Public Parking Facilities Customer Type: Individual Users, Fleet Operators, Commercial Property Owners, Municipal Authorities |
| Companies Covered | ABB, ChargePoint, Schneider Electric, Eaton, Siemens, Webasto, EVBox, Wallbox, Blink Charging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle AC Charging Pile Market Trends and Innovations
Smart-grid interoperability is rewriting the value architecture of AC charging hardware, shifting competitive advantage from power electronics toward software-defined energy management and predictive maintenance capabilities.
Vehicle-to-load (V2L) bidirectional charging is decentralizing the traditional grid-to-vehicle power flow model. Residential customers in Japan and South Korea are adopting V2L-capable AC piles as backup power sources during grid instability. This capability is compressing the addressable market for standalone home battery systems.
EU AI Act algorithmic transparency requirements are mandating explainable decision logic for grid-connected charging controllers. Manufacturers must now document machine-learning models that optimize charge timing against utility rates. Commercial fleet deployments in the Netherlands and Denmark face the steepest compliance burdens due to aggregated load profiling.
Installer-led specification authority is displacing end-user brand preference in residential procurement. Electrical contractors in California and Texas increasingly bundle AC pile selection with panel upgrade services, capturing margin through hardware-software integration rather than unit sales. This channel consolidation favors suppliers with certified training programs and field service networks.
Electric Vehicle AC Charging Pile Market Segmentation
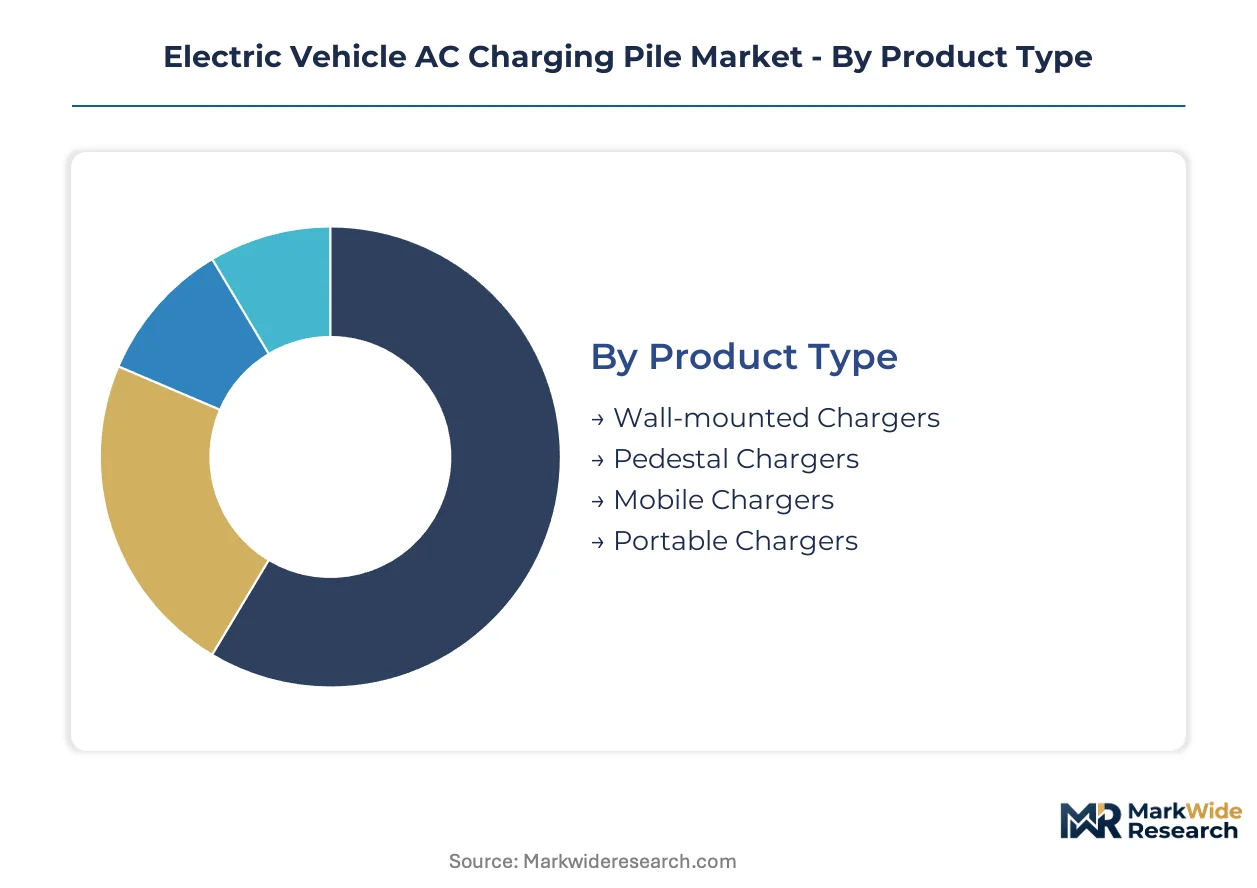
AC charging pile procurement varies sharply across installation contexts, power requirements, and buyer sophistication. Segment boundaries increasingly blur as fleet operators adopt residential-grade hardware and smart capabilities penetrate cost-sensitive channels.
Product Type:
The customization-vs-standardization spectrum stretches from hardwired fixed installations to plug-and-play portable units, with enclosure durability and mounting complexity driving manufacturing variance.
- Wall-mounted Chargers:Enclosed units affixed to residential garages or commercial building exteriors, typically delivering 3.7-11 kW through single-phase connections. German municipalities bundle these with streetlight retrofits in Rhine-Ruhr corridor curbside deployments, exploiting existing electrical infrastructure to minimize trenching costs.
- Pedestal Chargers:Freestanding posts housing dual-output configurations for public parking facilities and workplace campuses. Demand concentrates in French commercial complexes where property managers prioritize vandal-resistant steel enclosures over unit cost.
- Mobile Chargers:Detachable cable-and-connector assemblies with temporary mounting brackets for fleet depots requiring flexible bay reconfiguration.
- Portable Chargers:Compact emergency units stored in vehicle cargo compartments, drawing standard household outlets at reduced amperage.
Leading the category by volume: Wall-mounted Chargers. Growing fastest: Pedestal Chargers.
Charging Technology:
Power electronics sophistication separates commodity hardware from margin-rich intelligent systems, with silicon carbide components and bidirectional protocols commanding pricing premiums.
- Single-phase AC:230V residential connections delivering 3.7-7.4 kW through onboard vehicle rectification. Legacy housing stock in older French and German districts faces service upgrade barriers that stall purchase decisions despite hardware availability.
- Three-phase AC:400V industrial connections enabling 11-22 kW output for commercial and fleet depot applications. Fleet operators across North America scale these installations as total cost of ownership advantages sharpen against DC alternatives.
- Smart Charging:Grid-communicating controllers optimizing charge timing against utility time-of-use rates. Netherlands and Denmark fleet deployments face EU AI Act compliance burdens for algorithmic transparency in aggregated load profiling.
- Wireless Charging:Inductive pad systems eliminating connector wear, currently constrained by efficiency losses and GB/T certification fragmentation in China.
Volume leadership: Three-phase AC. Steepest expansion trajectory: Smart Charging.
Application Sector:
End-use concentration determines hardware specification authority, with installer bundling displacing direct consumer choice in residential channels while fleet procurement centralizes around total cost metrics.
- Private Vehicle Charging:Overnight residential and workplace installations dominated by wall-mounted single-phase units. California and Texas electrical contractors increasingly capture specification authority through panel upgrade bundling.
- Fleet Charging:Depot-based overnight infrastructure for logistics and municipal vehicle pools. Operators with 200+ vehicle deployments increasingly bypass AC for 150 kW DC hardware despite capital cost premiums.
- Commercial Complexes:Retail and office parking amenities prioritizing dual-output pedestal configurations with occupancy-based load management.
- Public Parking Facilities:Curbside and municipal garage installations requiring payment integration and vandal-resistant enclosures.
Leading by deployment count: Private Vehicle Charging. Expanding most quickly: Fleet Charging.
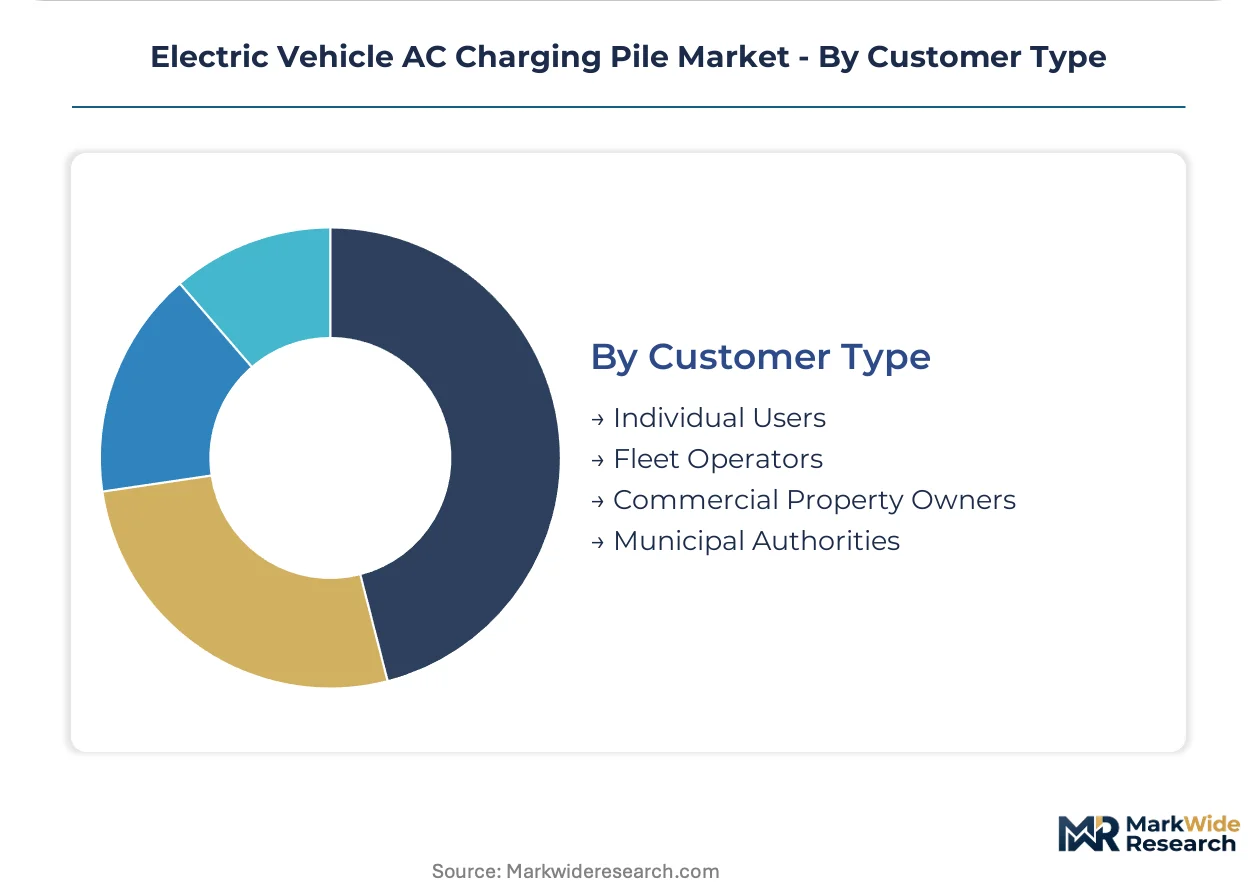
Customer Type:
Procurement sophistication spans individual price sensitivity through institutional lifecycle costing, with channel strategy and service bundling requirements diverging sharply across buyer categories.
- Individual Users:Residential consumers selecting hardware through electrical contractor recommendations or direct-to-installer platforms in the United Kingdom that collapse traditional wholesaler markups.
- Fleet Operators:Logistics companies and municipal vehicle pools negotiating volume procurement with depot installation and predictive maintenance services. India's PLI scheme for auto components creates localization pathways for AC pile assembly at reduced landed cost.
- Commercial Property Owners:Retail and office landlords treating charging amenities as tenant retention tools rather than profit centers.
- Municipal Authorities:City governments bundling streetlight retrofits with curbside infrastructure in Germany's Rhine-Ruhr metropolitan corridor.
Volume concentration: Individual Users. Fastest-growing demand: Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet depot installations concentrate procurement authority in Germany's industrial corridor, while China's GB/T certification mandates reshape supply timelines for multinational suppliers. Municipal bundling strategies in the Rhine-Ruhr region and California's contractor-led specification channels illustrate diverging demand formation patterns.
United States
Electrical contractors in California and Texas increasingly bundle AC pile selection with residential panel upgrades, capturing specification authority through hardware-software integration services. NHTSA interoperability guidelines shape product design requirements for grid-connected infrastructure. Fleet operators across the Midwest scale three-phase depot installations as total cost of ownership advantages sharpen against DC alternatives.
Germany
Municipal authorities in the Rhine-Ruhr metropolitan corridor bundle streetlight retrofits with curbside AC infrastructure, exploiting existing electrical infrastructure to minimize trenching costs. EU Green Deal mandates and CE marking requirements tighten product certification timelines for equipment suppliers. Siemens anchors engineering credibility while competing on three-phase systems for commercial complexes in Baden-Württemberg.
China
SAMR enforces GB standards that constrain import compatibility, forcing parallel certification strategies that add 8-14 months to product launch timelines for multinational suppliers. Dual carbon goals accelerate municipal procurement of smart-grid-interoperable charging infrastructure. Yangtze River Delta manufacturing clusters concentrate power electronics assembly for domestic and export markets.
India
PLI scheme incentives for auto components create localization pathways for AC pile assembly at 40% lower landed cost, attracting fleet operator procurement committees. CEA grid connectivity standards shape product design requirements for utility-integrated installations. Maharashtra and Gujarat industrial corridors concentrate emerging domestic manufacturing capacity.
Netherlands
Commercial fleet deployments face EU AI Act compliance burdens for algorithmic transparency in aggregated load profiling and smart-charging optimization systems. Dynamic time-of-use rate structures from utilities reward grid-communicating controllers with preferential access. Randstad urban clusters drive demand for vandal-resistant public parking infrastructure.
Electric Vehicle AC Charging Pile Market Competitive Landscape
European producers anchor the premium-tier engineering segment; Chinese fabricators hold volume manufacturing positions. The vendor base separates into consolidated multinational electrical conglomerates, specialized EV charging pure-plays, and emerging regional assemblers. Three archetypes dominate: software-integrated hardware stacks, three-phase power system specialists, and contractor-channel-optimized residential units. Geographic expansion and strategic partnerships constitute the dominant competitive moves as suppliers navigate divergent certification regimes.
Among diversified electrical conglomerates, ABB and Schneider Electric occupy positions exemplifying the integrated power systems archetype, leveraging established industrial distribution channels. Siemens represents the German engineering credibility tier, while ChargePoint anchors the software-integrated hardware category. Webasto and EVBox sit within the specialized charging infrastructure segment, with Wallbox and Blink Charging representing contractor-channel-focused residential specialists. Eaton exemplifies the industrial electrical equipment crossover archetype, applying legacy power distribution expertise to EV applications.
| Leading Market Players |
|---|
| ABB |
| ChargePoint |
| Schneider Electric |
| Eaton |
| Siemens |
| Webasto |
| EVBox |
| Wallbox |
| Blink Charging |
| Others |
Pricing and Supply Chain Analysis
Power electronics engineering talent concentration in Germany's Baden-Württemberg region feeds directly into pricing-tier spreads, with labor-cost differentials between European design centers and Yangtze River Delta assembly operations creating three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Volume-vs-margin split separates commodity wall-mounted single-phase units from software-integrated smart charging systems. Price differentiation rests on CE marking tier and after-sales service bundling, with EU AI Act compliance adding certification premiums. Cost compression in standard-tier hardware is intensifying because copper conductor volatility erodes bill-of-materials stability. Fleet operators exhibit lowest price sensitivity due to lifecycle costing frameworks, while individual residential buyers in older French housing stock stall purchases over service upgrade costs.
Supply Chain Analysis
Single-source vulnerability sits with silicon carbide substrate suppliers concentrated in Japan and the United States. Power electronics assembly draws from China's Yangtze River Delta, Germany's industrial corridor, and emerging Maharashtra-Gujarat clusters in India. Raw material dependencies span copper conductors, rare-earth magnets, and semiconductor-grade silicon. Tariff exposure on Chinese-manufactured controllers threatens margin stability. Distribution runs through electrical contractor networks in California and Texas, direct-to-installer platforms in the United Kingdom, and municipal procurement channels in Germany's Rhine-Ruhr corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Vehicle AC Charging Pile Market functions as a cost-of-compliance story where EU AI Act algorithmic transparency requirements create a barrier-to-entry moat for compliant players capable of documenting machine-learning decision logic.
For Market Incumbents: Anchor engineering credibility through GB/T certification investment for China market access despite SAMR-mandated timeline extensions. Defend against DC fast-charging substitution threat by bundling predictive maintenance services with three-phase depot installations. Prioritize backward integration into power electronics assembly via India's PLI scheme incentives. For New Entrants and Emerging Players: Begin with India's domestic manufacturing incentives as the most penetrable geography, exploiting 40% landed cost advantages for fleet operator procurement committees. Target contractor-channel optimization in the United Kingdom where direct-to-installer platforms collapse traditional wholesaler markups. Pursue vehicle-to-grid bidirectional protocol certification as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Re-rating potential sits with software-integrated hardware specialists given utility demand-response program expansion as catalyst. Long-term viability favors suppliers with certified training programs and field service networks capable of capturing installer-led specification authority. Monitor fleet operator bypass behavior toward 150 kW DC hardware as inflection signal for AC addressable market compression.| Strategic Initiative | Industry Significance |
|---|---|
| GB/T Certification Investment | SAMR compliance unlocks China's dual carbon goals procurement pipeline. |
| Smart Charging Platform Integration | EU AI Act transparency requirements favor explainable algorithm architectures. |
| India PLI Localization | Domestic assembly incentives reduce landed cost for fleet operator volume contracts. |
| Installer Channel Partnership | Electrical contractor bundling captures specification authority in California and Texas. |
| Bidirectional Charging Development | ISO 15118-20 protocols enable fleet battery monetization as distributed storage. |
Research Methodology
Document review covered utility demand-response program filings, CEA grid connectivity standards, and SAMR certification protocols, complemented by interviews with fleet procurement directors, electrical contractor specification leads, power electronics engineering managers, and municipal infrastructure planners. Secondary validation drew from EIA charging infrastructure databases, IEA electrification reports, FERC interconnection filings, and customs trade data for copper conductor and semiconductor imports. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Installed base forecasts and revenue projections reflect analytical framework spanning product type, charging technology, application sector, and customer type segmentation dimensions. CAGRs were derived from logistic diffusion curves fitted to fleet electrification timelines and residential adoption patterns. Key inputs included utility time-of-use rate structure rollouts, onboard rectification efficiency advances, and GB/T certification timeline impacts on multinational supplier market entry.
Underlying measurement precision varies by segment; fleet charging deployments carry tighter precision than residential individual user estimates due to centralized procurement visibility. Forecasts reflect assumptions around copper price stability, regulatory compliance timeline adherence, and DC hardware substitution thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
United Kingdom Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
North America Electric Vehicle Charging Station Market
Electric Vehicle Charging
Solar Charging Station Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
Belgium Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Infrastructure Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
Electric Vehicle Charger Operations and Maintenance Services Market
Electric Vehicle Charging
EV Solar Charging Wallbox Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
Bidirectional Charging Units Market
Electric Vehicle Charging
Asia-Pacific Airport Electric Vehicle Charging Station Market