
 EV DC Chargers Market | 2026-2036
EV DC Chargers Market Size, Share, and Industry Trends Forecast 2026-2036
EV DC Chargers Market Insights
Ultra-fast 350 kW and 500 kW charging specifications is redrawing competitive boundaries in the EV DC charger landscape. Tesla leverages its proprietary connector ecosystem and captive vehicle base to dominate premium corridor deployments. ABB sustains technology leadership through high-voltage power electronics R&D and manufacturing scale across European and Asian production hubs. ChargePoint anchors its position through software-integrated hardware platforms that control network interoperability and fleet management services.
EV DC chargers are high-power electrical systems that convert alternating current from grid infrastructure into direct current suitable for battery electric vehicles, typically operating at power ratings from 50 kW to 500 kW with conversion efficiencies exceeding 95 percent. These systems serve the primary commercial purpose of reducing charging dwell times to 15-30 minutes for passenger and commercial electric vehicles. Ultra-fast chargers occupy the fastest-expanding margin pool as automakers design 800-volt architectures requiring 350 kW and above. CCS connectors lead in European and North American public infrastructure due to regulatory standardization, while fleet operators represent a structurally underserved end-user segment with concentrated procurement volumes and dedicated depot charging requirements.
The EU Green Deal and F-Gas Regulation shape product design mandates for cooling systems and energy efficiency in European deployments, while the US NHTSA and EPA influence vehicle-side charging standards that cascade into infrastructure requirements. China's GB standards and MIIT directives govern connector protocols and grid interconnection rules for domestic manufacturers. Stakeholders must monitor divergence between regional connector standards and power rating roadmaps as they make capital allocation decisions across multi-jurisdictional charging networks.
Market Dynamics
Ultra-fast charging architectures above 350 kW are compressing dwell times and forcing infrastructure providers to upgrade transformer capacity and cooling systems ahead of vehicle deployment curves.
Growth Catalysts
- EU Green Deal infrastructure mandates:Binding targets for charging point density along trans-European transport corridors are unlocking public funding pools for network operators in Germany, France, and the Netherlands.
- Fleet electrification programs:Logistics operators with centralized depot operations in China's Pearl River Delta are procuring 150-350 kW systems in volume contracts that amortize hardware costs across ten-year asset lifecycles.
- 800-volt vehicle architectures:Battery electric platforms from Hyundai, Porsche, and Kia are normalizing acceptance of 350 kW+ charge rates, expanding addressable market for next-generation dispenser hardware.
Market Restraints
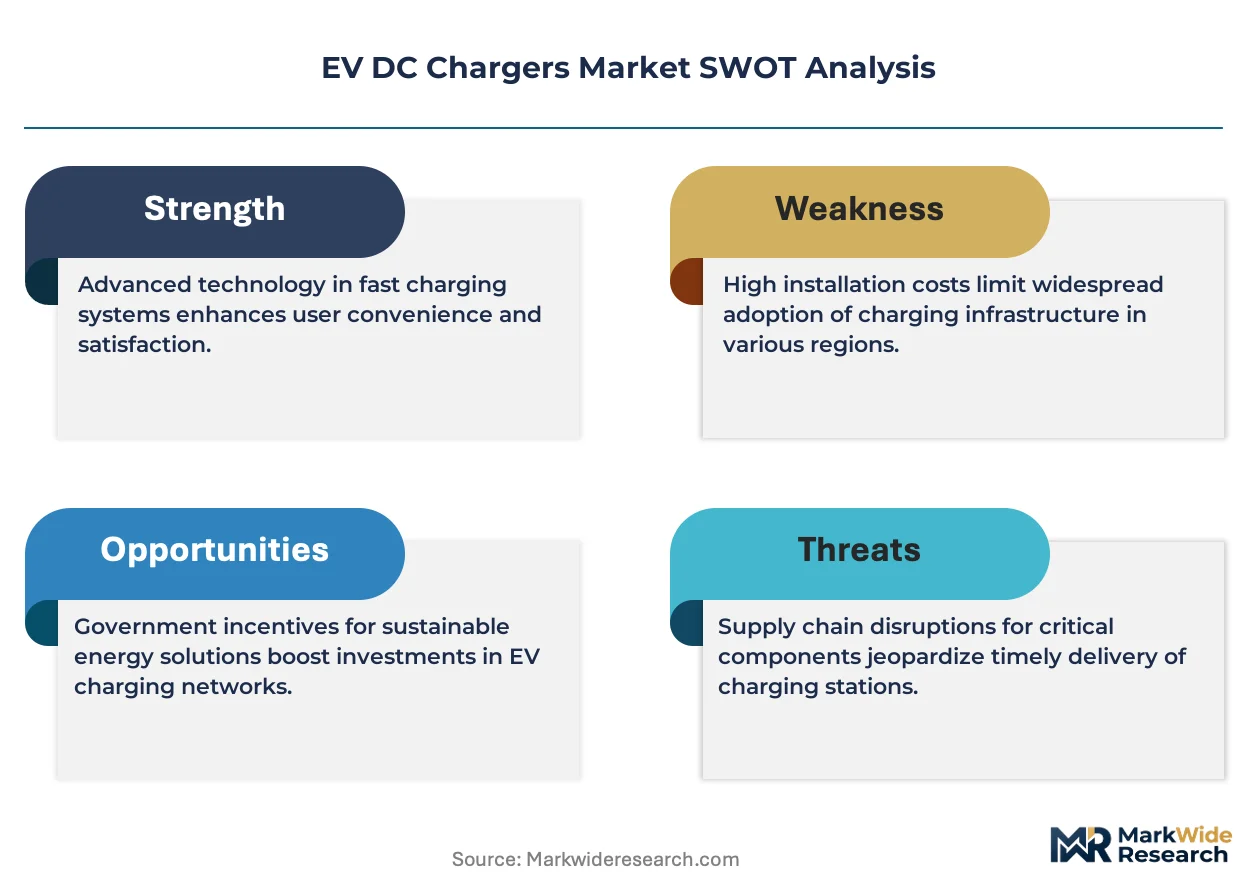
- Copper and silicon carbide supply concentration:Power semiconductor fabrication for high-frequency conversion modules depends on Taiwanese and German foundry capacity, creating input bottlenecks during demand surges.
- Grid interconnection queues:Utility approval timelines for multi-megawatt substation upgrades in the United States stretch 18-36 months, delaying revenue commencement for corridor charging investments.
- Connector standard fragmentation:Divergence between CCS, NACS, and GB/T protocols forces hardware manufacturers to maintain redundant inventory and certification pathways across export markets.
Strategic Opportunities
- India's PLI scheme for auto component manufacturing:Domestic production-linked incentives for power electronics and battery systems are attracting charger assembly investments to serve South Asian demand.
- Battery-integrated charging stations:Co-location of stationary storage with dispensers is enabling grid services revenue streams and demand charge arbitrage for operators in markets with volatile wholesale electricity pricing.
- Workplace and retail destination charging:Commercial real estate developers in the United Kingdom are bundling 50-150 kW units into lease agreements as tenant amenity differentiators.
Industry Challenges
- Power electronics engineering talent scarcity:Specialized design capabilities for high-voltage conversion and thermal management concentrate among a limited pool of experienced practitioners in Germany and Japan.
- Multi-jurisdictional certification timelines:UL, CE, and CCC mark acquisition for a single hardware platform requires 14-22 months of testing documentation and factory audits.
- Legacy distribution network integration:Rural charging deployments in Australia and Canada must accommodate weak grid infrastructure that necessitates on-site generation or battery buffering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV DC Chargers Market |
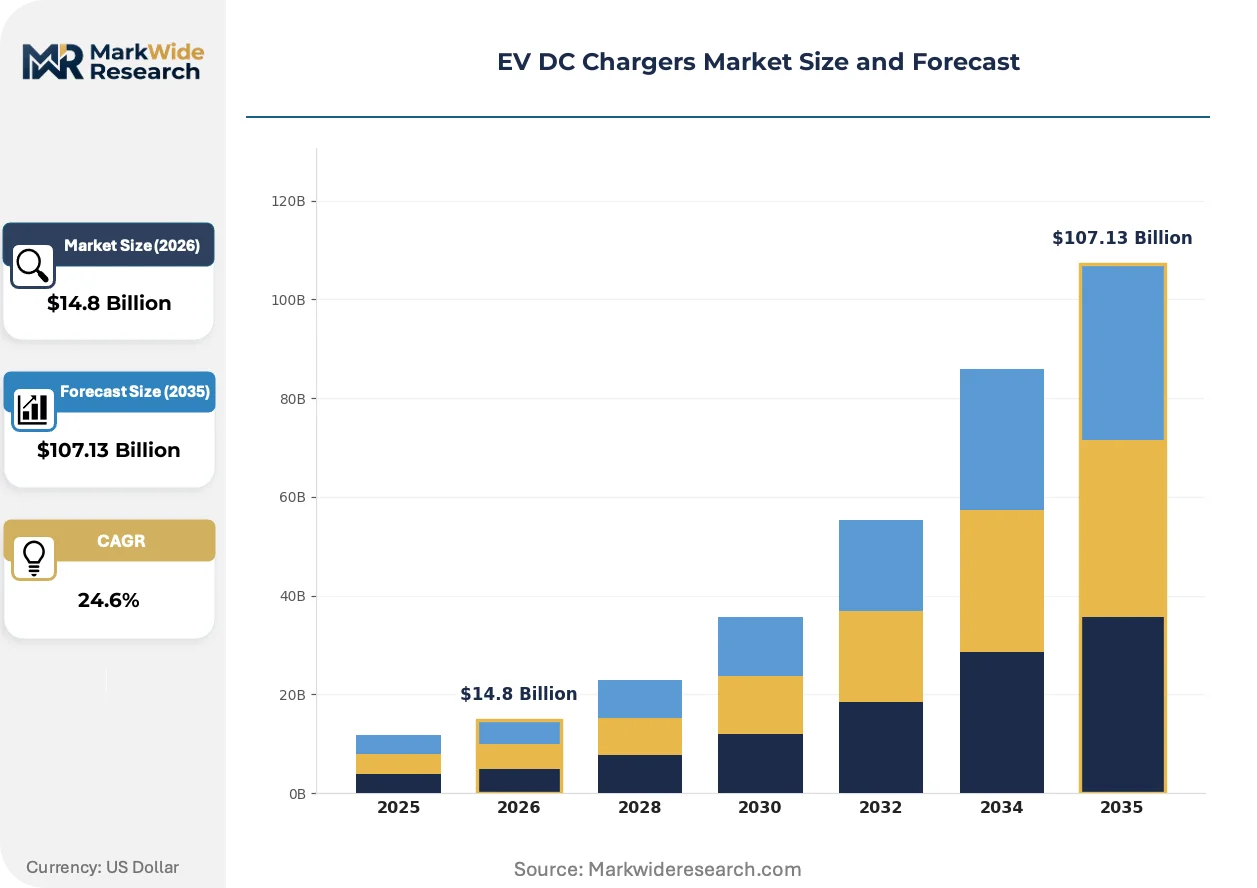
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $107.13 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charger Type: Fast Chargers, Rapid Chargers, Ultra-Fast Chargers, Level 3 Chargers Connector Type: CCS, CHAdeMO, Tesla Supercharger, GB/T Power Rating: 50 kW, 150 kW, 350 kW, 500 kW End User: Public Charging Stations, Fleet Operators, Commercial Establishments, Residential Complexes |
| Companies Covered | Tesla, ChargePoint, ABB, EVgo, Electrify America, EVBox, Blink Charging, Eaton, Delta Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV DC Chargers Market Trends and Innovations
Hardware commoditization is pushing competitive differentiation toward software-defined power management and dynamic load balancing across multi-dispenser sites.
Liquid-cooled cable assemblies rated for 500 kW continuous output are displacing air-cooled conductor systems in premium corridor applications. European highway operators in Norway and the Netherlands are specifying these systems for new tender awards. The technology is compressing physical footprint requirements and enabling longer cable reach without thermal derating.
The EU F-Gas Regulation phase-down schedules are accelerating adoption of CO2-based cooling circuits in power conversion modules. Equipment manufacturers must redesign thermal architectures to maintain efficiency above 95 percent while eliminating hydrofluorocarbon refrigerants. German and French certification bodies are prioritizing inspection protocols for these transitional product generations.
Site hosts are consolidating vendor relationships around integrated hardware-software-service bundles that unbundle traditional capital equipment sales. Fleet operators in California and Texas are negotiating availability-guaranteed contracts where payment ties to uptime metrics rather than unit procurement. This model is most visible among logistics customers with dedicated depot charging requirements and internal sustainability reporting obligations.
EV DC Chargers Market Segmentation
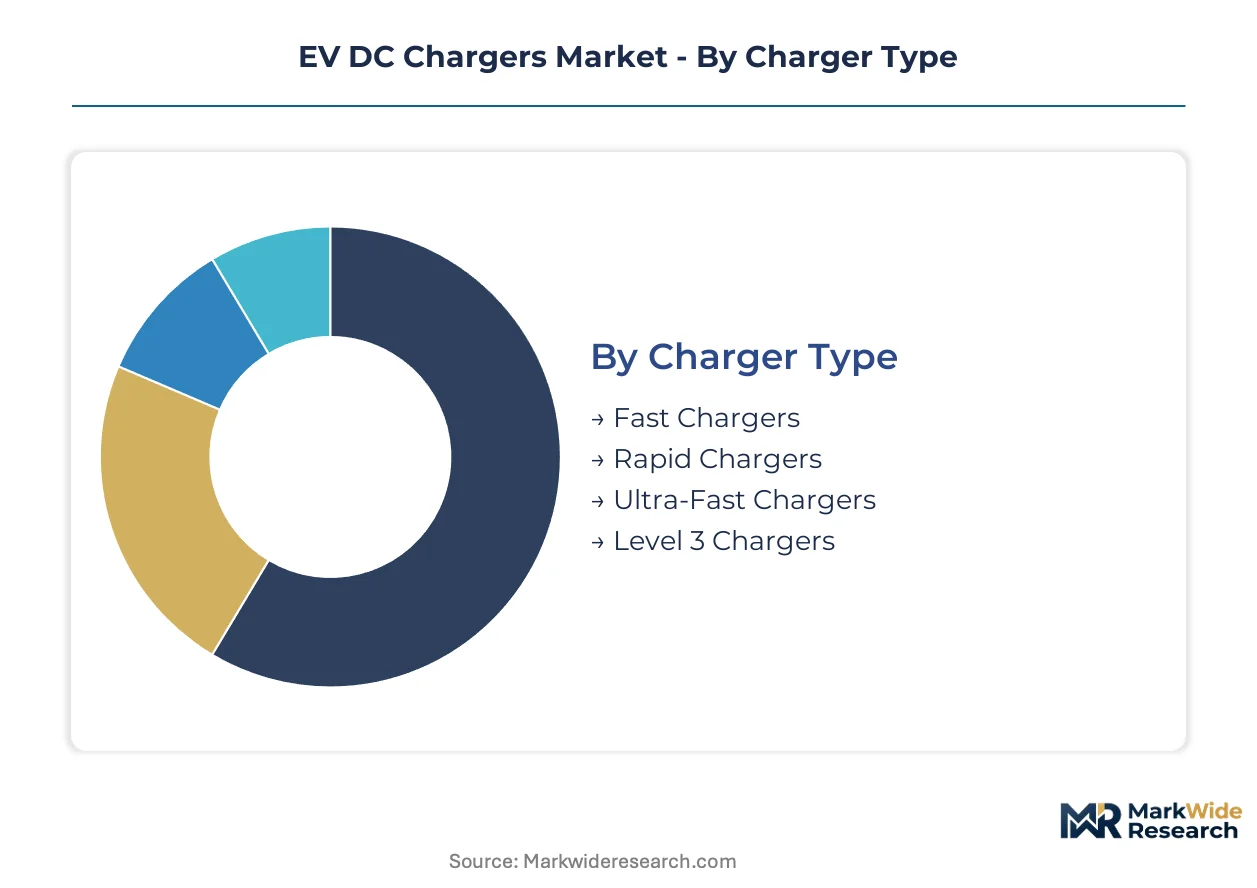
Segmentation in the EV DC charger market reveals divergent procurement patterns across power classes and installation contexts. Charger specifications, connector protocols, and end-use deployment models each create distinct margin structures and competitive dynamics that shape vendor positioning.
Charger Type:
Channel mix varies sharply across charger categories, with highway corridor operators favoring ultra-fast units while fleet depots concentrate procurement in fast and rapid classes.
- Ultra-Fast Chargers:Systems rated above 350 kW employ liquid-cooled cable assemblies and silicon carbide power modules to sustain continuous output. Demand clusters along Germany's autobahn network and California's Interstate 5 corridor as 800-volt vehicle platforms normalize acceptance of sub-20-minute charging sessions.
- Rapid Chargers:Units in the 150-350 kW range balance capital efficiency with dwell-time reduction for mixed-use sites. China's Pearl River Delta logistics operators specify these systems for depot installations where overnight fleet turnover demands moderate power density without full ultra-fast infrastructure costs.
- Fast Chargers:50-150 kW systems serve workplace and retail destination charging where vehicle dwell times exceed 45 minutes.
- Level 3 Chargers:This designation encompasses all DC fast charging hardware above 50 kW in North American regulatory frameworks.
By volume, rapid chargers lead procurement tallies. By growth pace, ultra-fast systems are climbing the fastest as automakers expand 800-volt architecture deployment.
Connector Type:
Cost tier stratification separates premium proprietary ecosystems from standardized open-access hardware, with implications for vendor lock-in and network interoperability.
- CCS:The Combined Charging System integrates AC and DC pins within a single inlet, dominating European and North American public infrastructure due to EU regulatory standardization and US NHTSA guidance. German highway operators mandate CCS compatibility for tender eligibility, creating volume concentration among suppliers with established certification pathways.
- Tesla Supercharger:Proprietary connector and network architecture leverages captive vehicle base to optimize hardware-software integration. The connector's recent opening to third-party vehicles through adapter protocols is expanding addressable market while preserving Tesla's software control over charging sessions.
- CHAdeMO:Japanese-developed standard retains installed base among earlier Nissan and Mitsubishi electric vehicle models.
- GB/T:China's national standard governs all domestic DC charging infrastructure under MIIT directives, with connector geometry and communication protocols distinct from Western equivalents.
CCS connectors command the largest installed base across open networks. GB/T maintains steepest expansion trajectory within China's protected domestic market.
Power Rating:
Application context determines power selection, with commercial vehicle duty cycles and passenger car highway transit imposing divergent technical requirements on grid interconnection and thermal management.
- 350 kW:This threshold marks the transition to true ultra-fast charging, enabling 10-80 percent battery replenishment in approximately 15 minutes for 800-volt architectures. Hyundai, Porsche, and Kia vehicle platforms normalize acceptance of these charge rates, expanding hardware addressable market beyond premium passenger segments into commercial fleet specifications.
- 500 kW:Emerging specification targets heavy-duty commercial vehicles and future battery-electric trucks with megawatt-hour-scale packs. Norwegian highway operators pilot these systems for corridor freight electrification, though grid interconnection requirements limit deployment to substation-proximate sites.
- 50 kW:Entry-level DC fast charging serves secondary road networks and captive fleet depots with predictable dwell schedules.
- 150 kW:Mid-tier rating dominates mixed-use public installations where vehicle mix spans multiple battery capacities and voltage classes.
150 kW hardware leads current procurement volume across diversified site hosts. 350 kW systems are gaining share fastest as vehicle-side voltage architecture upgrades accelerate.
End User:
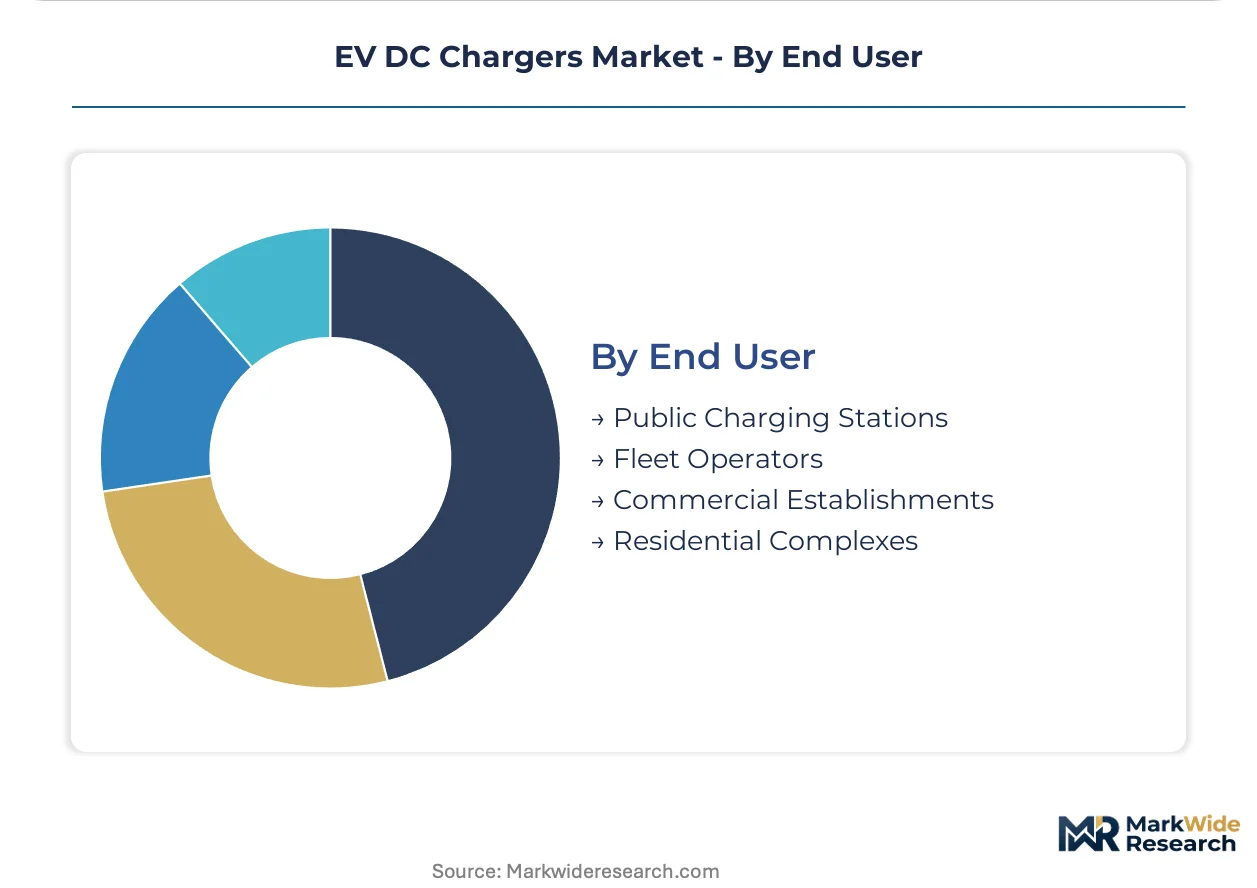
Customer type shapes contract structure, with fleet operators negotiating availability-guaranteed service agreements while public station operators prioritize throughput optimization.
- Fleet Operators:Centralized depot operations with dedicated land and predictable vehicle schedules amortize hardware costs across ten-year asset lifecycles. California and Texas logistics customers procure 150-350 kW systems in volume contracts with uptime-linked payment terms rather than capital equipment purchases.
- Public Charging Stations:Highway corridor and urban fast-charging sites maximize revenue per port through dynamic pricing and multi-dispenser load balancing. UK motorway service area operators bundle charging with retail amenities to capture dwell-time spending.
- Commercial Establishments:Workplace and retail hosts deploy 50-150 kW units as tenant or customer amenities with lower utilization requirements than dedicated charging businesses.
- Residential Complexes:Multi-unit dwellings represent emerging installation context where shared DC infrastructure supplements individual AC charging assignments.
Public charging stations lead by installed port count. Fleet operator procurement is expanding most quickly as logistics electrification programs scale across North America and Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German charger manufacturers export corridor-grade hardware to Netherlands highway operators and French fleet depots, establishing a Rhine-centered trade flow that supplies Western European electrification programs.
United States
California logistics operators and Texas fleet depots drive procurement of 150-350 kW depot systems under availability-guaranteed contracts. NHTSA vehicle-side charging standards cascade into infrastructure requirements that shape dispenser specifications. The Interstate 5 corridor hosts concentrated ultra-fast deployment as 800-volt vehicle penetration climbs.
Germany
Autobahn network operators and Rhine-Ruhr industrial logistics customers specify CCS-compatible ultra-fast hardware for tender eligibility. EU Green Deal binding targets for charging point density unlock public funding pools for corridor investments. Bavarian power electronics specialists supply silicon carbide conversion modules to domestic and export markets.
China
Pearl River Delta logistics operators procure rapid chargers in volume contracts amortizing hardware across ten-year asset lifecycles. MIIT GB standards govern connector protocols and grid interconnection rules for domestic manufacturers. Coastal manufacturing corridors concentrate assembly capacity serving protected domestic demand.
Netherlands
Highway corridor operators specify liquid-cooled 500 kW systems for freight electrification pilot programs. EU F-Gas Regulation phase-down schedules accelerate CO2-based cooling circuit adoption in power conversion modules. Randstad logistics hubs integrate depot charging with multimodal freight terminals.
Norway
Arctic highway freight routes pilot 500 kW systems for heavy-duty commercial vehicle electrification. National ICE phase-out mandates accelerate infrastructure deployment ahead of vehicle availability curves. Substation-proximate sites host concentrated ultra-fast deployment due to grid interconnection constraints.
EV DC Chargers Market Competitive Landscape
Listed leaders compete with private specialists across hardware-software integration depth, creating a tiered structure where scale advantages concentrate among vertically integrated platform operators while regional specialists capture fleet depot niches. Three archetypes dominate: proprietary ecosystem builders leveraging captive vehicle bases, open-network platform operators bundling hardware with network management software, and industrial power electronics specialists supplying conversion modules and thermal systems. Competitive moves center on strategic partnerships between automotive OEMs and infrastructure operators, plus geographic expansion through regulatory certification stacking.
Within the proprietary ecosystem tier, Tesla anchors closed-loop integration between vehicle hardware and corridor charging assets. ABB and Delta Electronics occupy positions among power electronics specialists supplying high-voltage conversion and thermal management systems to network operators and automotive integrators.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| EVgo |
| Electrify America |
| EVBox |
| Blink Charging |
| Eaton |
| Delta Electronics |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide foundry utilization rates in Taiwan and Germany establish minimum efficient scale thresholds that compress margins for sub-scale assemblers while anchoring price floors for high-power conversion modules. This concentration forces procurement officers at European highway operators and Chinese fleet depots into long-term offtake commitments that lock in component costs across ten-year infrastructure amortization schedules.
Pricing Analysis
Prior-generation 50 kW air-cooled hardware trades at commodity margins while current-generation 150-350 kW liquid-cooled systems command premium positioning, and next-generation 500 kW specifications are resetting price ceilings for corridor deployments. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled ultra-fast dispensers from air-cooled rapid units and entry-level fast chargers. Cost compression in the standard tier is intensifying because Chinese manufacturers are scaling GB/T-compatible assembly lines for domestic volume contracts. Fleet operators with availability-guaranteed service agreements exhibit lowest price sensitivity, while independent public station operators maximizing throughput per port face acute margin pressure.
Supply Chain Analysis
Taiwan Strait shipping lanes carry concentrated silicon carbide wafer shipments that underpin power semiconductor fabrication for high-frequency conversion modules. Manufacturing gravity centers on Taiwan, Germany, and China for power electronics, with copper cable assemblies drawing from Chilean and Indonesian smelter output. Single-source vulnerability concentrates in Taiwanese foundry capacity for 1200V MOSFET devices. Distribution runs through integrated hardware-software-service bundles where fleet operators negotiate uptime-linked payment terms rather than unit procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV DC charger market constitutes a high-growth infrastructure disruption where 800-volt vehicle architectures and EU Green Deal corridor mandates are compressing technology replacement cycles. Stakeholders must position against accelerated obsolescence of sub-350 kW hardware.
For Market Incumbents: Fortify silicon carbide supply security through captive foundry partnerships or long-term wafer offtake agreements with Taiwanese and German semiconductor fabricators. Deepen backward integration into liquid-cooled cable assembly production to defend margin position against Chinese cost competitors. Prioritize CE and UL certification stacking for 500 kW product generations ahead of Norwegian and Dutch highway tender windows.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for power electronics manufacturing to serve South Asian demand with domestic cost structures. Target fleet depot operators in Texas and California with availability-guaranteed service contracts rather than capital equipment sales. Pursue software-defined power management platforms as the primary go-to-market angle, bundling dynamic load balancing with hardware procurement.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors power electronics specialists with certified 350 kW+ product pipelines and established utility interconnection relationships. Long-term viability hinges on silicon carbide supply security and multi-jurisdictional certification capabilities. Monitor NHTSA vehicle-side charging standard revisions as the critical inflection signal for infrastructure requirement cascades.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Locks in Taiwanese foundry capacity for 1200V MOSFET modules ahead of demand surges. |
| Liquid-Cooled Cable Assembly Scale-Up | Enables 500 kW continuous output certification for Norwegian highway freight pilots. |
| Multi-Jurisdictional Certification Stacking | Accelerates UL, CE, and CCC mark acquisition for single hardware platform deployment. |
| Battery-Integrated Station Deployment | Captures grid services revenue through demand charge arbitrage in volatile wholesale markets. |
| Software-Defined Power Management Launch | Differentiates commoditized hardware through dynamic load balancing across multi-dispenser sites. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors, highway corridor operators, power electronics R&D leads, and utility interconnection planners. Secondary validation drew from NHTSA vehicle standard filings, EU Green Deal infrastructure mandate documentation, MIIT GB standard publications, and silicon carbide supply chain trade data. Bottom-up unit deployment tallies triangulated against top-down infrastructure investment forecasts across the analysis window.
Across the projection horizon, the analytical framework modeled charger type, connector protocol, power rating tier, and end-user deployment context as core segmentation dimensions. CAGRs were derived from vehicle adoption curve penetration rates and infrastructure density targets mandated by EU and national regulators. Forecast inputs incorporated 800-volt architecture deployment timelines from Hyundai, Porsche, and Kia platform roadmaps alongside F-Gas Regulation cooling system phase-down schedules.
Underlying assumptions cover sustained EU Green Deal funding availability and Taiwanese semiconductor foundry capacity expansion, with deviation risk concentrated in grid interconnection queue delays and copper price volatility. Practitioners should keep alternative scenarios live as NHTSA vehicle-side charging standard revisions and Chinese GB standard export compatibility positions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
PV BESS EV Charging Systems Market
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Global Electric Vehicle Charging As a Service Market
Electric Vehicle Charging
Global Automotive Charging System Market
Electric Vehicle Charging
Electric Vehicle Fast and Rapid Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
United States Electric Vehicle Charging Systems and Equipment Market
Electric Vehicle Charging
Public EV Charger Market
Electric Vehicle Charging
Engineered Polymers in Electric Charging Infrastructure Market
Electric Vehicle Charging
Belgium Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Pantograph Charger Market