
 Asia-Pacific Portable EV Charger Market | 2026-2036
Asia-Pacific Portable EV Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Portable EV Charger Market Insights
China's dual carbon goals is shifting procurement priorities across the EV charging ecosystem. Guangzhou Electway Technology Co., Ltd leverages its southern China manufacturing base to dominate portable fast-charger production for domestic fleet operators. Shenzhen SETEC Power Co., Ltd. anchors its position through R&D intensity in high-frequency power conversion. Okaya Power Pvt. Ltd. competes across India's price-sensitive residential segment with localized assembly operations.
A portable EV charger is a mobile power electronics device, typically rated between 3 kW and 22 kW, that converts grid alternating current to direct current suitable for electric vehicle battery replenishment without fixed infrastructure installation. The unit integrates power factor correction circuitry, thermal management systems, and either tethered or detachable connector cables to enable charging at diverse locations lacking dedicated wall-mounted equipment. Smart charger configurations command margin premiums through embedded connectivity and load-balancing algorithms, while 7 kW power ratings capture the largest addressable volume across residential and light-commercial applications. Fleet operator demand for 22 kW portable units is expanding fastest as logistics providers seek flexible depot charging without civil works investment.
China's MIIT enforces GB standards for electromagnetic compatibility and electrical safety that determine product certification requirements for domestic portable charger sales. India's BIS mandates ISI marking under compulsory registration for power electronics above specified voltage thresholds, while Australia's TGA-equivalent electrical safety regulator oversees state-level equipment approvals. Stakeholders must monitor evolving interoperability protocols between vehicle onboard chargers and portable supply equipment as OEMs tighten handshake requirements.
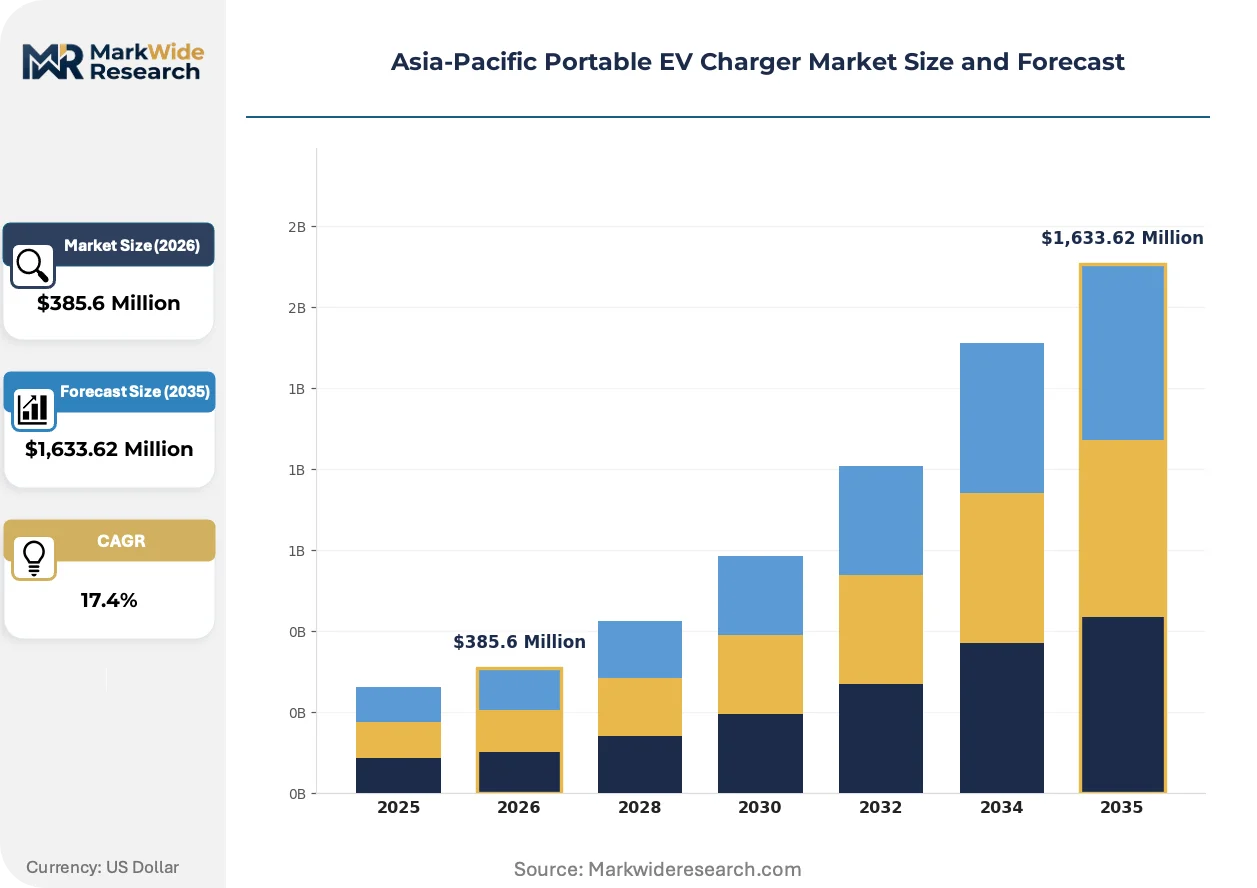
Market Dynamics
Residential parking constraints across China's tier-one cities are compressing demand toward compact, plug-and-play charging architectures that bypass fixed civil infrastructure requirements entirely.
Growth Catalysts
- China's dual carbon goals:National emissions targets are redirecting fleet procurement budgets toward flexible depot charging solutions that eliminate concrete pad installation timelines.
- India's PLI scheme:Production-linked incentives for automotive manufacturing are attracting component suppliers to establish localized assembly operations for price-sensitive residential segments.
- High-frequency power conversion:Advances in silicon carbide switching topologies are shrinking thermal management footprints and enabling 22 kW output from handheld form factors.
Market Restraints
- Copper and rare-earth magnet costs:Input price volatility in magnet wire and ferrite cores is compressing gross margins for manufacturers without backward integration into raw material sourcing.
- Guangdong supplier concentration:Overreliance on Pearl River Delta electronics clusters creates single-point vulnerability to regional power rationing or logistics disruptions.
- GB standard certification timelines:MIIT electromagnetic compatibility testing protocols extend product launch windows by four to six months versus unregulated export markets.
Strategic Opportunities
- Vietnam's manufacturing migration:Labor cost arbitrage and emerging electronics industrial zones are drawing assembly capacity away from saturated Chinese coastal provinces.
- Load-balancing algorithm integration:Embedded connectivity modules that synchronize with time-of-use electricity tariffs are commanding hardware margin premiums in Australia's deregulated retail markets.
- Japan's apartment dweller segment:METI building energy codes that restrict fixed installation in rental properties are creating pull-through demand for detachable connector systems.
Industry Challenges
- Power electronics engineering talent:Scarce domestic expertise in high-frequency magnetics design is forcing reliance on expatriate technical leadership or licensed foreign IP.
- Vehicle-to-charger handshake standardization:OEM-proprietary communication protocols are fragmenting interoperability testing requirements and inflating SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Portable EV Charger Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,633.62 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Charger, Public Charger, Fast Charger, Smart Charger Installation: Wall-mounted, Portable, Built-in, Standalone Power Rating: 3 kW, 7 kW, 11 kW, 22 kW End User: Residential, Commercial, Fleet Operators, Charging Stations |
| Companies Covered | Evteq Mobility Private Limited, Heliox Energy, Guangzhou Electway Technology Co., Ltd, Okaya Power Pvt. Ltd., AG Electrical Technology Co., Ltd, Shenzhen SETEC Power Co., Ltd., JTM Power Limited, Power Sonic Corporation, Wonder New Energy Technology, Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Portable EV Charger Market Trends and Innovations
Silicon carbide semiconductor adoption is compressing thermal management volumes while software-defined power control is enabling dynamic tariff optimization. These converging vectors are reshaping product architecture and procurement criteria simultaneously.
Gallium nitride switching devices are replacing silicon IGBTs in 7 kW residential units, cutting heat sink mass by sixty percent while maintaining conversion efficiency above ninety-six percent. Fleet operators in Australia's logistics corridors are piloting these compact units for opportunistic depot charging. The technology is modularizing supply chains by decoupling thermal design from power stage engineering.
China's MIIT is tightening GB/T 18487 electromagnetic compatibility thresholds for portable supply equipment, mandating conducted emissions testing across expanded frequency bands. Domestic manufacturers are absorbing six-figure certification costs per SKU while export-oriented competitors face exclusion from state procurement tenders. Tier-one suppliers are responding by vertically integrating test laboratory capabilities to compress validation cycles.
Apartment dwellers in Shanghai and Shenzhen are rejecting fixed-installation contractor quotes in favor of detachable cable systems that preserve lease-end mobility. E-commerce platforms are displacing electrical wholesale channels for residential purchases, with live-stream commerce now capturing substantial transaction volume among first-time EV owners. This behavioral pivot is most pronounced among urban millennials in China's eastern coastal megacities where residential turnover exceeds fifteen percent annually.
Asia-Pacific Portable EV Charger Market Segmentation
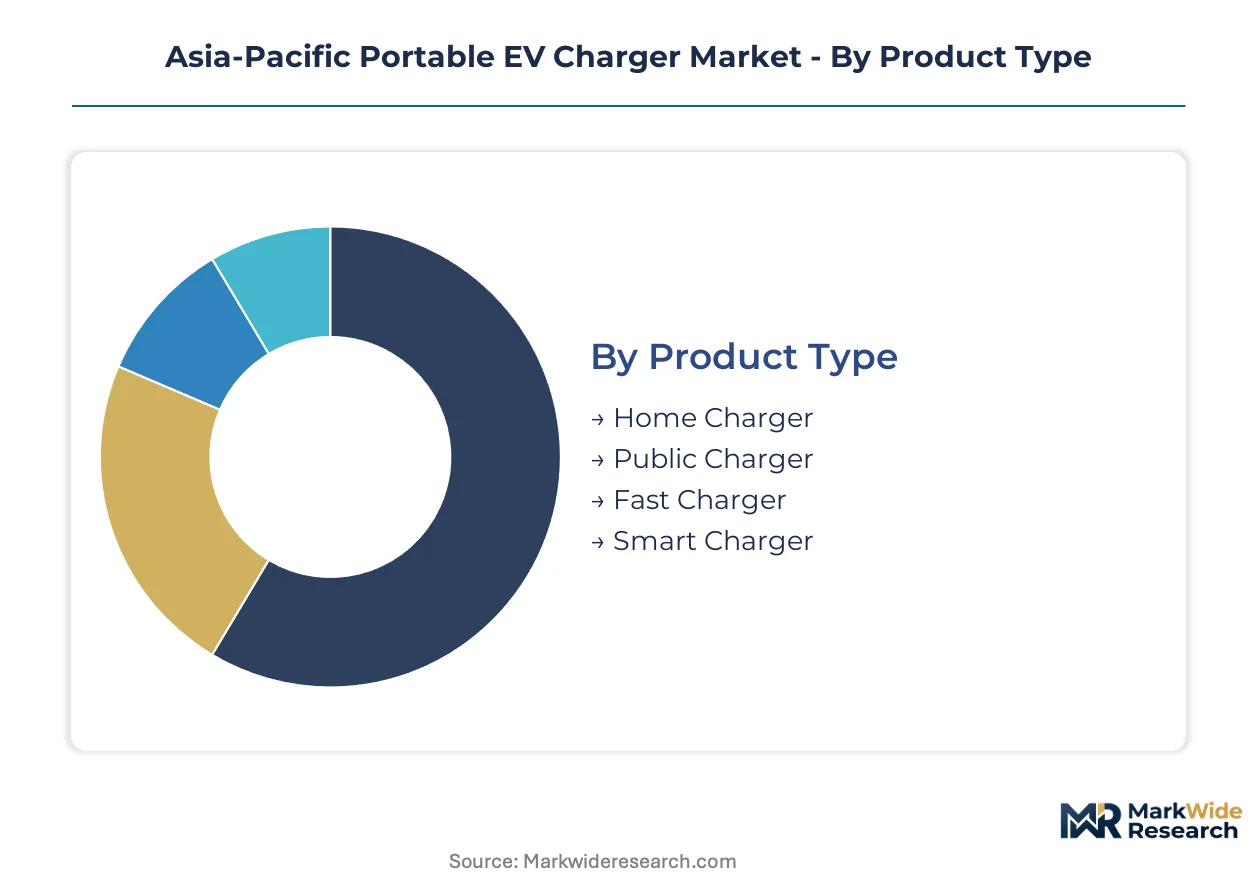
Portable EV charger procurement across the Asia-Pacific region fragments along power ratings, installation constraints, and end-user operational profiles. Certification requirements from MIIT, BIS, and Australia's state-level electrical safety regulators create divergent compliance burdens across these dimensions. Understanding segment-specific regulatory exposure enables suppliers to prioritize SKU development and geographic deployment sequencing.
Product Type:
MIIT GB standards and BIS compulsory registration schemes impose varying electromagnetic compatibility and electrical safety testing timelines across portable charger configurations. Smart chargers face the most stringent connectivity protocol validation, while basic home chargers navigate streamlined certification pathways.
- Home Charger:Compact units rated 3-7 kW with tethered cables dominate residential sales through Chinese e-commerce platforms. Apartment dwellers in Shanghai and Shenzhen favor these for lease-end mobility, bypassing fixed-installation contractor costs entirely.
- Fast Charger:Silicon carbide-enabled 22 kW handheld units are compressing thermal footprints while serving logistics depots in Australia's interstate corridors. Fleet operators pilot these for opportunistic charging without concrete pad investments.
- Public Charger:Weather-hardened enclosures with detachable cable systems target municipal procurement tenders in Japan's urban centers. METI building energy codes restrict fixed installation in rental properties, amplifying detachable connector demand.
- Smart Charger:Embedded connectivity modules synchronize with time-of-use tariffs in Australia's deregulated retail markets. Load-balancing algorithms command hardware margin premiums while extending GB standard certification cycles.
Leading the category by volume: Home Charger. Growing fastest: Fast Charger.
Installation:
Installation architecture determines civil works requirements, mobility preservation, and deployment speed across residential and commercial contexts. Portable and wall-mounted configurations split the market along ownership tenure and parking security variables.
- Portable:Plug-and-play units requiring zero fixed infrastructure capture China's tier-one city demand where residential parking constraints prohibit permanent equipment. Live-stream commerce channels displace electrical wholesalers for millennial first-time EV owners.
- Wall-mounted:Fixed brackets with detachable cable options serve Japan's apartment rental market under METI energy codes. These preserve tenant mobility while satisfying landlord liability concerns.
- Built-in:Vehicle-integrated charging hardware bypasses external supply equipment entirely, though this segment sits outside core portable charger definition boundaries.
- Standalone:Self-supporting pedestal units with integrated cable management target commercial parking operators in India's price-sensitive segments. Localized assembly under PLI scheme incentives compresses landed costs.
Volume concentration: Portable. Steepest expansion trajectory: Wall-mounted.
Power Rating:
Power output tiers align with battery capacity, dwell time economics, and grid connection capacity across residential, commercial, and fleet applications. Higher ratings demand more sophisticated thermal management and heavier copper magnet wire content.
- 7 kW:Single-phase residential workhorses balance overnight charging duration against standard household circuit limits. Gallium nitride switching devices are replacing silicon IGBTs, cutting heat sink mass by sixty percent while maintaining conversion efficiency above ninety-six percent.
- 22 kW:Three-phase output enables rapid depot turnaround for logistics fleets without civil works investment. Australia's logistics corridors see concentrated pilot deployment as operators test opportunistic charging models.
- 3 kW:Entry-level units serve India's price-sensitive residential segment with localized assembly operations. BIS ISI marking requirements extend product launch windows versus unregulated export markets.
- 11 kW:Mid-tier commercial specification bridges residential convenience and fleet throughput requirements. This rating encounters fragmented OEM handshake protocol compatibility.
Revenue concentration: 7 kW. Gaining share fastest: 22 kW.
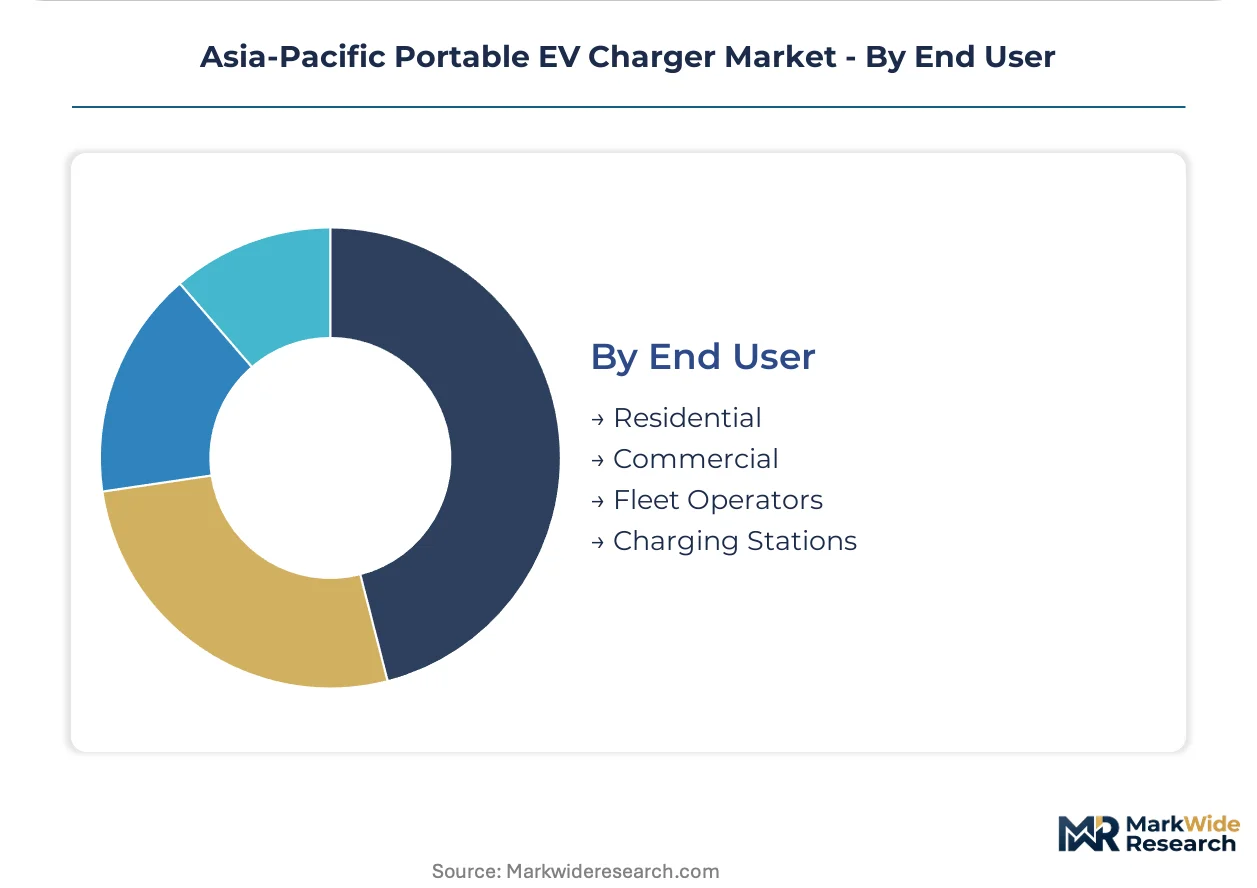
End User:
End-user procurement patterns diverge sharply across ownership structure, utilization intensity, and electricity tariff exposure. Residential buyers prioritize upfront cost and mobility, while fleet operators optimize for throughput and total cost of ownership.
- Residential:Urban apartment dwellers across Chinese megacities drive compact plug-and-play unit adoption. Annual residential turnover exceeding fifteen percent in eastern coastal cities reinforces detachable cable preferences.
- Fleet Operators:Logistics providers in Australia's interstate corridors pilot 22 kW portable units for depot flexibility. These buyers absorb hardware premiums to eliminate concrete pad installation timelines.
- Commercial:Workplace and retail parking operators in Japan's dense urban centers deploy under METI building energy code constraints. Procurement emphasizes reliability certifications and warranty terms.
- Charging Stations:Dedicated public charging infrastructure providers source higher-power standalone units with integrated payment systems. This segment faces the longest GB standard electromagnetic compatibility validation cycles.
Addressable volume leader: Residential. Climbing the fastest: Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta electronics corridor dominates portable EV charger manufacturing, with Shenzhen and Guangzhou anchoring production capacity for domestic and export markets. This concentration shapes procurement patterns across the broader Asia-Pacific region.
China
Urban apartment dwellers in Shanghai and Shenzhen compress demand toward compact plug-and-play units that bypass fixed civil infrastructure. MIIT enforces GB/T 18487 electromagnetic compatibility standards that extend certification timelines by four to six months. Guangzhou Electway Technology Co., Ltd leverages its southern China manufacturing base to serve domestic fleet operators with localized fast-charger production.
India
Price-sensitive residential buyers in Delhi-NCR and Maharashtra drive adoption of entry-level 3 kW units with tethered cables. BIS mandates ISI marking under compulsory registration for power electronics above specified voltage thresholds. Okaya Power Pvt. Ltd operates localized assembly facilities to compress landed costs for budget-conscious consumers.
Japan
Apartment renters in Tokyo and Osaka reject fixed-installation options under METI building energy codes that restrict permanent equipment in rental properties. METI regulations create pull-through demand for detachable connector systems that preserve tenant mobility. Kanto region manufacturers specialize in weather-hardened enclosures for municipal procurement tenders.
Australia
Logistics fleet operators along interstate corridors pilot 22 kW portable units for opportunistic depot charging without concrete pad investments. State-level electrical safety regulators oversee equipment approvals that vary across jurisdictions. Victoria and New South Wales concentrate demand where deregulated retail markets enable time-of-use tariff optimization through smart charger connectivity.
South Korea
Seoul Capital Area residential complexes face parking constraints similar to Chinese tier-one cities, amplifying interest in mobile charging architectures. MFDS-equivalent electrical safety protocols govern product certification for domestic sales. Busan-Ulsan industrial zones host component suppliers serving the broader regional assembly ecosystem.
Asia-Pacific Portable EV Charger Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and thermal management sophistication. The vendor base organizes into three tiers: vertically integrated electronics conglomerates, specialized power conversion houses, and regional assembly operations serving price-sensitive segments. Strategic moves concentrate on backward integration into magnet wire sourcing and captive test laboratory capabilities to compress MIIT validation cycles.
Among China-based fabricators, Guangzhou Electway Technology Co., Ltd and Shenzhen SETEC Power Co., Ltd occupy positions within the integrated manufacturer archetype. Evteq Mobility Private Limited represents the India-focused regional specialist tier. Okaya Power Pvt. Ltd exemplifies the price-competitive assembler segment leveraging PLI scheme incentives. These anchors illustrate how geographic origin and company structure map to distinct margin and certification exposure profiles.
| Leading Market Players |
|---|
| Evteq Mobility Private Limited |
| Heliox Energy |
| Guangzhou Electway Technology Co., Ltd |
| Okaya Power Pvt. Ltd. |
| AG Electrical Technology Co., Ltd |
| Shenzhen SETEC Power Co., Ltd. |
| JTM Power Limited |
| Power Sonic Corporation |
| Wonder New Energy Technology, Ltd |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride switching adoption in 7 kW residential units is compressing heat sink mass by sixty percent while simultaneously concentrating power stage engineering talent in Shenzhen and Guangzhou, creating dual cost and supply advantages for Pearl River Delta manufacturers serving price-sensitive Indian buyers and premium Australian fleet operators.
Pricing Analysis
Throughput-based pricing anchors procurement decisions for 22 kW fast chargers in Australia's logistics corridors, where fleet operators absorb hardware premiums to eliminate concrete pad installation timelines. Three-tier pricing structure across premium, standard, and economy levels separates GB-certified smart chargers with embedded connectivity from basic tethered units and entry-level 3 kW assemblies. Cost compression in India's residential tier intensifies because Okaya Power's localized assembly under PLI scheme incentives compresses landed costs for budget-conscious Delhi-NCR buyers. Fleet operators exhibit least price sensitivity, while Indian apartment dwellers in Maharashtra drive hardest bargain negotiations.
Supply Chain Analysis
Power electronics engineering talent scarcity in Vietnam's emerging industrial zones is constraining manufacturing migration despite labor cost arbitrage, forcing continued reliance on China's Pearl River Delta clusters. Magnet wire draws from Chinese copper smelters, silicon carbide substrates source from Japanese and American wafer suppliers, and gallium nitride devices hinge on South Korean foundry capacity. Single-source vulnerability to Guangdong power rationing threatens quarterly production schedules. Distribution runs through Chinese e-commerce platforms displacing electrical wholesalers for millennial first-time EV owners in Shanghai and Shenzhen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide semiconductor displacement of silicon IGBTs is restructuring product architecture and procurement criteria simultaneously, rewarding suppliers who compress thermal management volumes while maintaining conversion efficiency above ninety-six percent.
For Market Incumbents: To counter gallium nitride-enabled compact entrants from Vietnam's emerging electronics zones, Guangzhou Electway and Shenzhen SETEC must deepen backward integration into magnet wire sourcing and establish captive test laboratory capabilities to compress MIIT GB/T 18487 validation cycles. Certification investment represents the critical defensive lever against four-to-six-month product launch delays. For New Entrants and Emerging Players: India's PLI scheme for automotive manufacturing opens a window for regional assembly specialists to capture price-sensitive residential demand in Delhi-NCR and Maharashtra with localized 3 kW tethered cable production. Japan's METI building energy codes restricting fixed installation in Tokyo and Osaka rental properties present the most penetrable white-space for detachable connector systems. Direct-to-consumer live-stream commerce channels offer the lowest customer acquisition cost for millennial first-time EV owners. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated power conversion houses given silicon carbide switching topology R&D intensity and GB standard certification moats. Long-term viability through the technology transition window favors suppliers with in-house high-frequency magnetics design capability rather than licensed foreign IP dependence. Watch for MIIT electromagnetic compatibility threshold tightening as the inflection signal indicating consolidation pressure on export-oriented competitors lacking domestic test infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Wire Sourcing | Captive copper supply insulates Guangdong manufacturers from commodity volatility compressing gross margins. |
| Captive Test Laboratory Establishment | In-house GB/T 18487 validation compresses MIIT certification timelines by four to six months versus third-party dependency. |
| Silicon Carbide Power Stage R&D Investment | High-frequency switching topologies enable 22 kW output from handheld form factors for Australian fleet pilots. |
| Localized Assembly Under PLI Incentives | Indian component suppliers establish price-competitive 3 kW production for Maharashtra's budget-conscious residential buyers. |
| Live-Stream Commerce Channel Development | E-commerce platforms displace electrical wholesalers for Shanghai and Shenzhen millennial first-time EV owners. |
Research Methodology
Independent corroboration across MIIT certification databases, BIS compulsory registration filings, and Australian state-level electrical safety approvals underwrites the qualitative findings. Primary interviews with power electronics engineering directors, fleet procurement managers at Australian logistics operators, and category buyers at Chinese e-commerce platforms combined with secondary validation from customs trade data, SEC 10-K disclosures by listed component suppliers, and IEA electric vehicle deployment statistics. Bottom-up unit shipment estimates and top-down market value reconstruction triangulate to consistent magnitude.
Comparable-period anchoring to historical GB standard adoption curves and PLI scheme implementation phases structured the projection horizon. The analytical framework models power rating tiers, installation architecture preferences, end-user operational profiles, and regional regulatory cluster exposure. CAGRs derive from segment-specific volume trajectories weighted by average selling price evolution. Silicon carbide semiconductor penetration rates and gallium nitride device cost curves feed directly into fast charger segment forecasts.
The model assumes a particular technology adoption path; alternative pathways for solid-state power conversion would alter the outlook. Forecasts reflect underlying assumptions regarding MIIT electromagnetic compatibility enforcement intensity and India's PLI scheme extension decisions. Material deviation in copper and rare-earth magnet input costs or Guangdong regional power stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
PV BESS EV Charging Systems Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
Electric Vehicle Fast and Rapid Charger Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Europe Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Connector Market
Electric Vehicle Charging
Pantograph Charger Market
Electric Vehicle Charging
Asia-Pacific Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market